
 Air-Dried Food Market | 2026-2036
Air-Dried Food Market Size, Share, and Industry Trends Forecast 2026-2036
Air-Dried Food Market Analysis
Backpacking enthusiasts and emergency-preparedness buyers is collapsing the historical dominance of conventional grocery shoppers in air-dried food procurement. Van Drunen Farms leverages its vertically integrated fruit and vegetable supply chain to dominate bulk ingredient sales to downstream processors. Nestle S.A. sustains global brand recognition across retail and institutional channels with shelf-stable meal platforms. Saraf Foods Pvt. Ltd. anchors South Asian export volumes through specialized herb and spice drying capabilities.
Air-dried food refers to products dehydrated through controlled ambient or low-temperature airflow, typically retaining 5-10% residual moisture while preserving cellular structure and rehydration capacity superior to freeze-dried alternatives. The process operates at 50-80°C depending on substrate sensitivity, serving commercial food manufacturers and outdoor recreation markets that prioritize weight reduction and extended ambient shelf stability. Fruits command the largest volume share within product type segments, though meats generate disproportionate margin contribution from premium jerky and protein snack applications. Pouch packaging is displacing rigid containers across retail and HoReCa channels due to logistics efficiency and portion-control alignment with single-serve consumption trends.
FDA food safety modernization rules and USDA organic certification requirements govern product standards and market access for North American suppliers, while EFSA residue limits and EU Green Deal agricultural sustainability targets shape European formulation and sourcing decisions. Compliance with REACH chemical safety protocols and evolving CSRD supply-chain disclosure obligations adds compliance layers for brands sourcing across multiple jurisdictions. Stakeholders must monitor divergence between regional clean-label definitions and packaging waste directives when configuring product portfolios for cross-border expansion.
Market Dynamics
Backpacking and emergency-preparedness buyer segments are compressing lead times and forcing SKU proliferation across lightweight meal portfolios, while EFSA residue tightening under the EU Farm to Fork Strategy reconfigures supplier qualification protocols.
Growth Catalysts
- EFSA Residue Limits:The EU's tightening clean-label mandates are disqualifying conventional preservative-dependent processors and opening shelf space for ambient-dried alternatives with minimal additive load.
- Outdoor Recreation Equipment Procurement:Specialty retailers in Germany and Austria are expanding dedicated air-dried meal sections to capture alpine trekking and van-life customer segments.
- Strategic Stockpiling Behavior:Civil defense and household emergency preparedness programs across Northern Europe are incorporating lightweight dehydrated rations into official recommendation frameworks.
Market Restraints
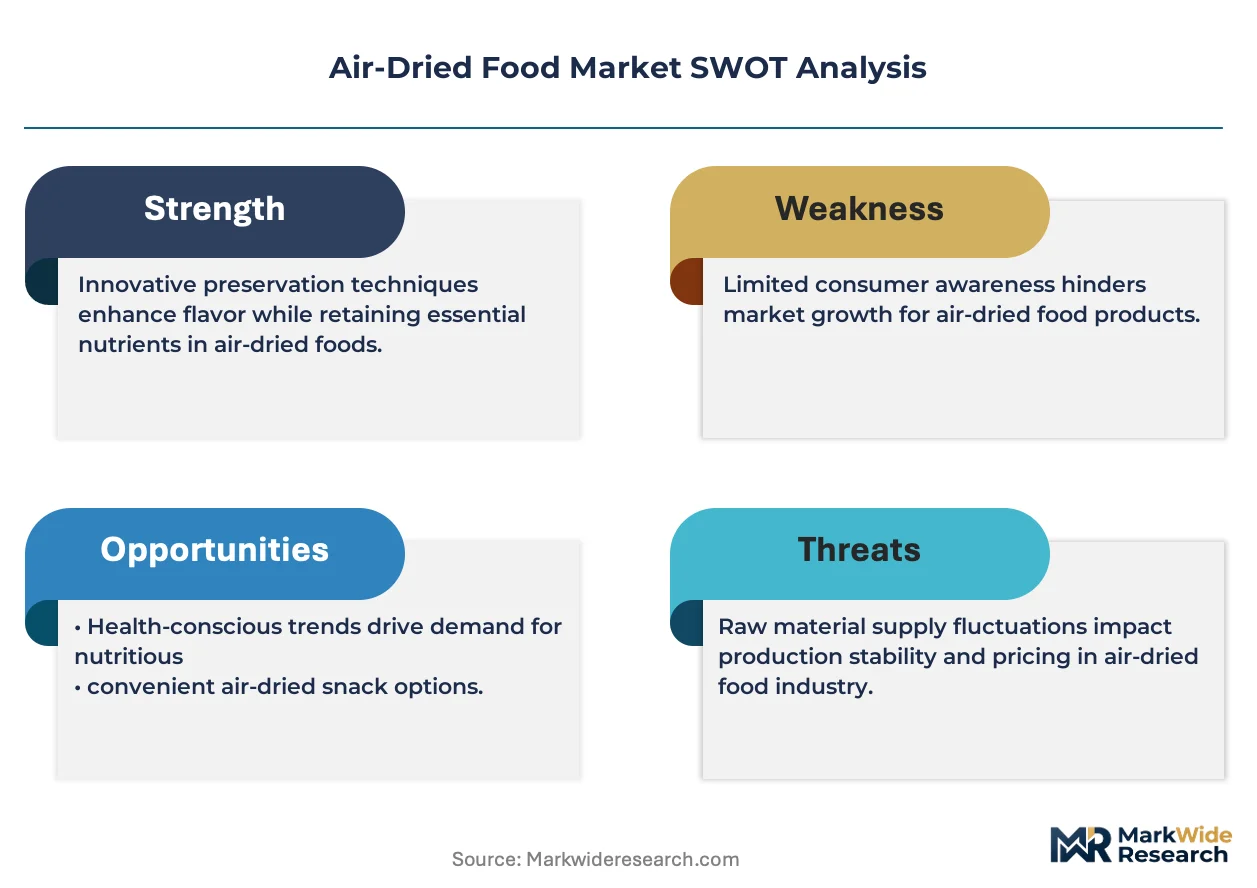
- Energy Input Cost Volatility:Natural gas and electricity price swings in EU processing hubs directly compress margins on thermal-dependent drying operations.
- Raw Material Concentration:Premium fruit and vegetable sourcing clusters in specific Mediterranean growing regions create weather and logistics vulnerability.
- Freeze-Dried Substitution:Higher-end outdoor consumers increasingly accept the weight penalty of freeze-dried meals for superior texture and faster rehydration.
Strategic Opportunities
- CSRD Supply-Chain Disclosure:Early compliance with EU corporate sustainability reporting requirements opens institutional and foodservice procurement channels.
- Pet Nutrition Crossover:Human-grade air-dried meat formats are penetrating premium pet food segments with minimal formulation adjustment.
- Direct-to-Consumer Subscription:Specialized meal-plan services for thru-hikers and digital nomads bypass traditional outdoor retail markup structures.
Industry Challenges
- Multi-Jurisdiction Certification Timelines:Simultaneous USDA organic, EU organic, and BSI PAS 96 compliance creates 12-18 month product launch delays.
- Legacy Drying Asset Retrofit:Conventional hot-air tunnel systems require substantial capital injection to achieve EFSA-aligned temperature control and traceability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Air-Dried Food Market |
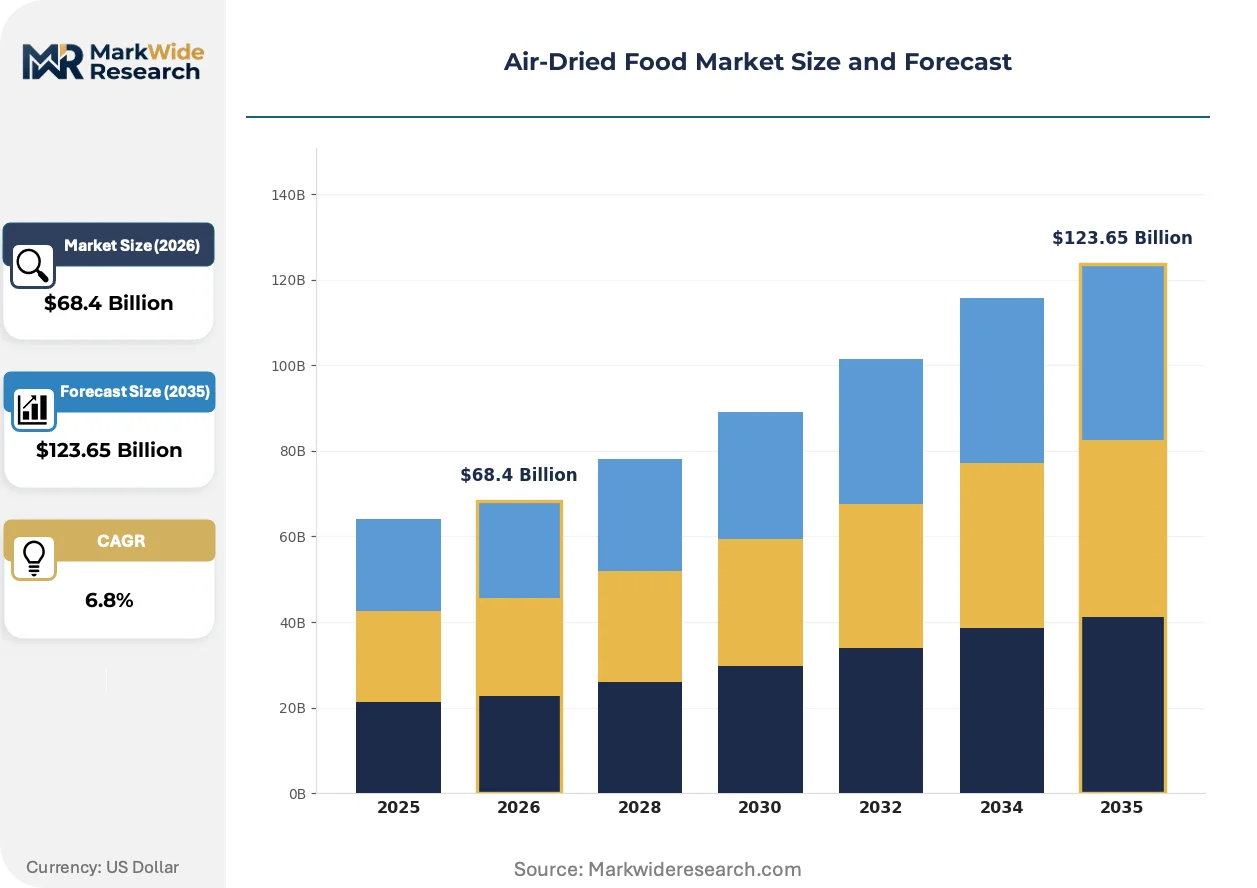
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetables, Fruits, Herbs, Meats End User: Food Processing, Retail, HoReCa, Households Packaging Type: Bags, Pouches, Jars, Bulk Packaging Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Distributors |
| Companies Covered | Van Drunen Farms, Dehydrates Inc., Nestle S.A., Berrifine A/S, Conagra Brands, Unilever PLC, Saraf Foods Pvt. Ltd., A La Frubense, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Air-Dried Food Market Emerging Trajectories
Controlled low-temperature airflow engineering is narrowing the quality gap with freeze-dried alternatives while preserving the cost and energy advantages that define air-dried positioning.
Hybrid solar-thermal drying infrastructure is displacing conventional fossil-fuel-dependent batch systems across Mediterranean and Australian processing facilities. Mid-scale cooperatives in Spain and Portugal are adopting photovoltaic-assisted dehydration to meet EU Green Deal carbon intensity benchmarks. This technology is displacing gas-fired tunnel dryers in the premium fruit segment and capturing price premiums from carbon-conscious German retailers.
REACH chemical safety protocols are forcing reformulation of cleaning agents and equipment coatings used in food-contact drying environments. Processors must now document full substance inventory and substitution plans for per- and polyfluoroalkyl substances previously standard in non-stick conveyor systems. The meat and dairy air-dried segments face the steepest compliance costs, with several Dutch facilities completing multi-year equipment replacement cycles.
Expedition catering procurement now favors modular pouch formats over rigid containers for weight and waste-volume calculations on extended backcountry itineraries. Alpine guiding services and polar logistics operators are specifying single-serve flexible packaging in tender documents. This specification shift is most visible in Norway, Switzerland, and New Zealand, where commercial outdoor recreation carries substantial economic weight.
Air-Dried Food Market Segmentation
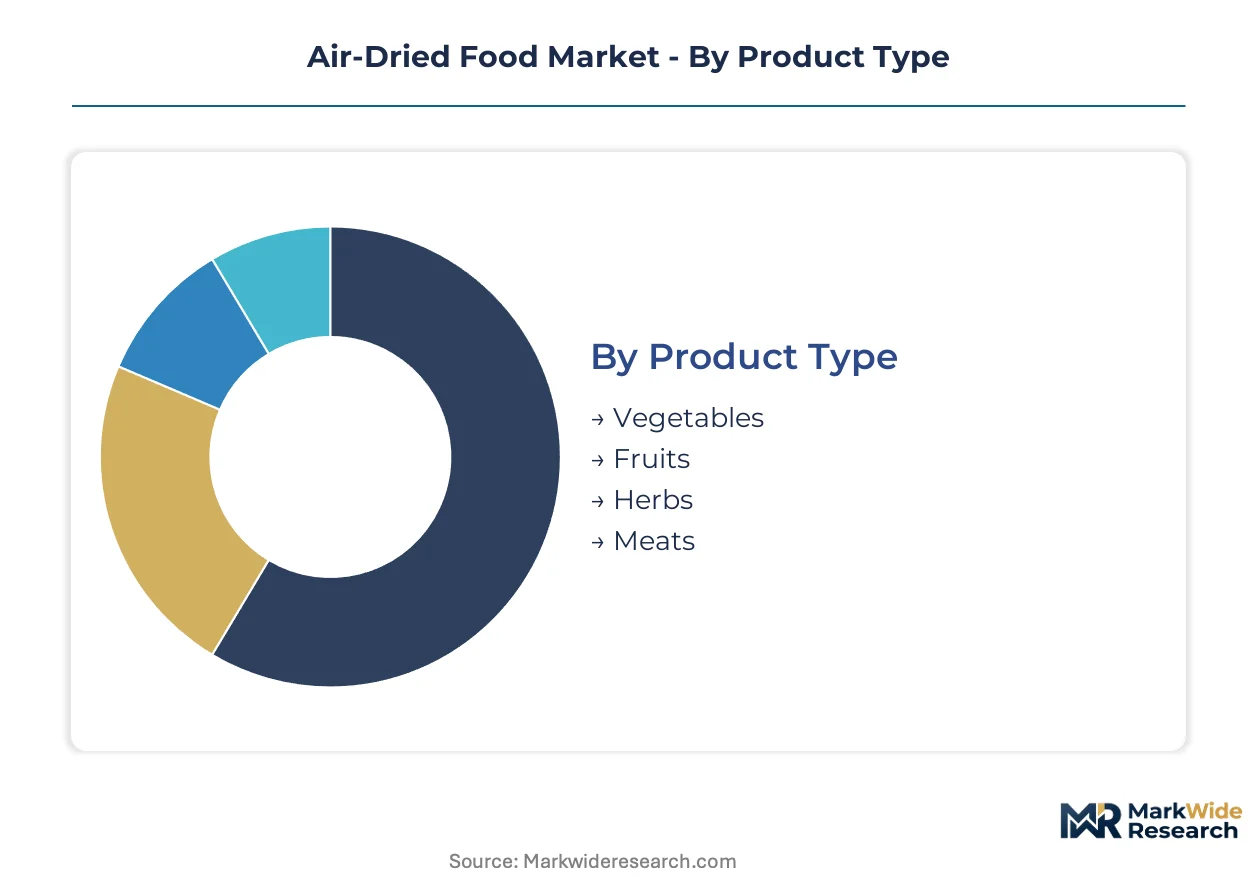
Segmentation in air-dried foods reveals how margin capture diverges sharply between commodity bulk ingredients and branded consumer formats. Technical drying specifications and packaging choices determine which suppliers access premium outdoor recreation and emergency preparedness channels.
Product Type:
Margin pools concentrate in protein segments where moisture control complexity and shelf stability command formulation premiums, while fruit and vegetable categories compete on scale and sourcing proximity.
- Meats:Jerky and air-dried protein strips retain cellular structure through controlled 60-80°C airflow cycles, preserving myofibrillar texture superior to freeze-dried alternatives. Demand concentrates in German and Austrian alpine trekking segments where weight-to-protein ratios justify premium positioning. EFSA residue tightening under Farm to Fork Strategy is disqualifying conventional preservative-heavy processors and opening shelf space for clean-label meat formats.
- Fruits:Apples, berries, and tropical varieties dominate commercial volume through Mediterranean and Australian processing clusters, with residual moisture specifications of 5-10% enabling extended ambient stability without refrigeration. German outdoor retailers and Dutch emergency preparedness distributors are expanding dedicated air-dried fruit sections to capture van-life and strategic stockpiling customer segments. Hybrid solar-thermal infrastructure is displacing gas-fired tunnel dryers across Spanish and Portuguese cooperatives.
- Vegetables:Tomato, pepper, and leafy green formats serve soup and sauce reconstitution applications with faster rehydration kinetics than freeze-dried equivalents.
- Herbs:Basil, oregano, and specialty botanicals anchor South Asian export volumes through controlled low-temperature dehydration preserving volatile oil compounds.
Meats holds installed capacity. Fruits is rotating up the share rankings.
End User:
Application-driven purchasing patterns split between formulation-scale procurement by downstream manufacturers and direct consumption by outdoor recreation and preparedness buyers.
- Households:Emergency preparedness programs across Northern Europe and alpine recreational consumers in Germany, Austria, and Switzerland drive lightweight meal pouch procurement for home storage and backcountry use. Strategic stockpiling behavior is compressing lead times and forcing SKU proliferation across single-serve formats.
- HoReCa:Expedition catering procurement favors modular pouch formats over rigid containers for weight and waste-volume calculations on extended backcountry itineraries, with alpine guiding services in Norway and Switzerland specifying flexible packaging in tender documents.
- Food Processing:Bulk ingredient acquisition by soup, sauce, and ready-meal manufacturers prioritizes rehydration coefficient consistency and lot-level traceability.
- Retail:Specialty outdoor stores and conventional supermarkets diverge on packaging format and portion size specifications.
Households is climbing the fastest. HoReCa holds established procurement frameworks.
Packaging Type:
Logistics efficiency and portion control requirements are reshaping format selection across retail and institutional channels.
- Pouches:Flexible single-serve and multi-serve formats displace rigid containers due to weight reduction, compressed waste volume, and alignment with thru-hiker and digital nomad consumption patterns. Norwegian polar logistics operators and New Zealand commercial guiding services now specify pouch formats in equipment procurement tenders.
- Bulk Packaging:Food manufacturers and institutional kitchens acquire air-dried ingredients in industrial totes and drums for formulation-scale reconstitution.
- Bags:Stand-up and flat formats serve mid-volume retail and foodservice applications with intermediate barrier properties.
- Jars:Rigid glass containers retain niche positioning in premium gift and specialty retail segments where visual product display commands shelf placement.
Pouches is expanding most quickly. Bulk Packaging maintains contract manufacturing relationships.
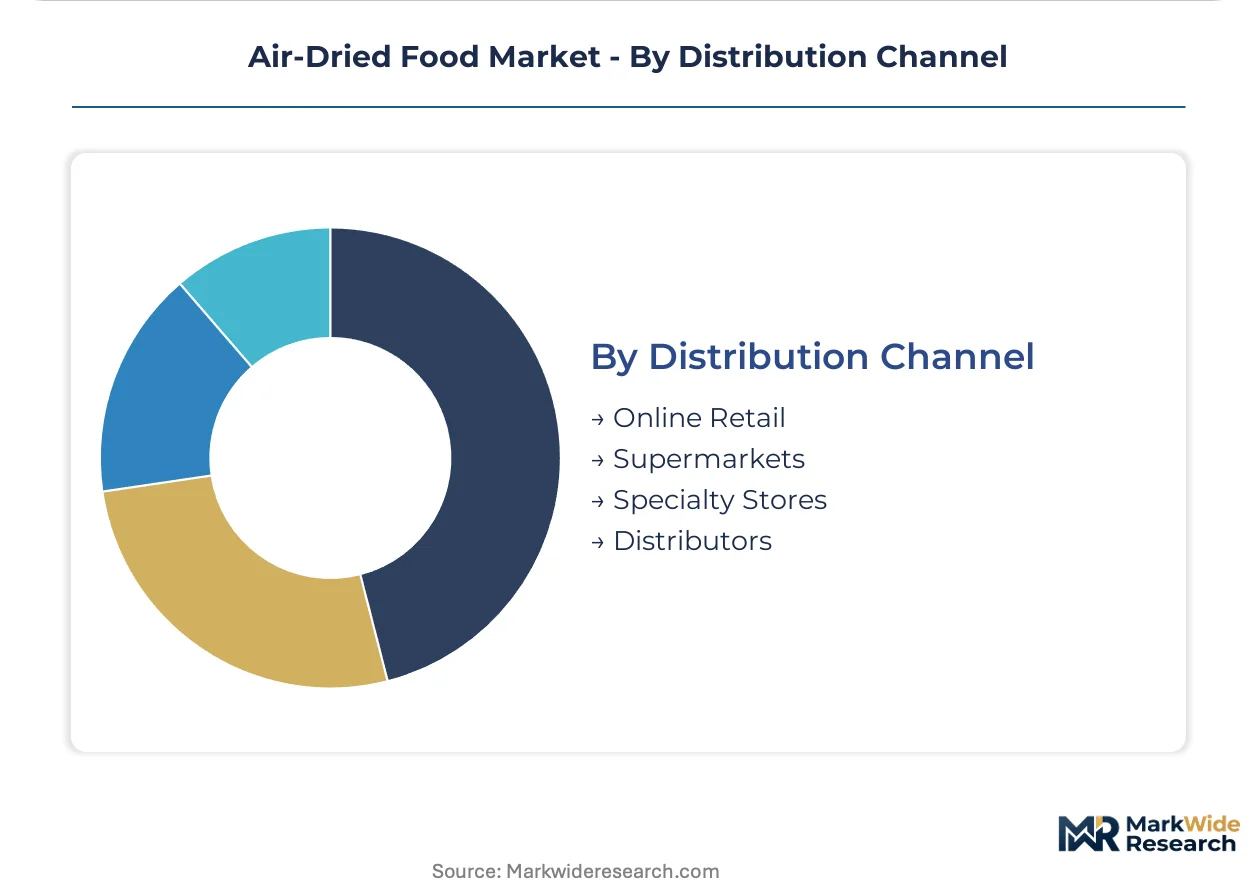
Distribution Channel:
Channel selection determines margin retention and customer data access for specialized air-dried meal portfolios.
- Specialty Stores:Dedicated outdoor recreation retailers in Germany and Austria curate alpine trekking and van-life assortments with trained staff consultation and equipment bundling. These channels capture price premiums through technical specification expertise and trip-planning service integration.
- Online Retail:Direct-to-consumer subscription services for thru-hikers and emergency preparedness buyers bypass traditional retail markup structures, enabling customized meal-plan configurations and recurring revenue models.
- Supermarkets:Conventional grocery placement requires price competitiveness and mass-market packaging formats.
- Distributors:Regional and national foodservice distributors aggregate institutional and HoReCa procurement volumes.
Specialty Stores holds technical credibility. Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's cold-chain and dry-bulk logistics infrastructure underwrites Northern Europe's dominance in air-dried food import and redistribution. German alpine retail networks and Dutch emergency preparedness distributors leverage this hub for just-in-time inventory positioning.
Germany
Outdoor recreation equipment procurement from Munich and Innsbruck-based specialty retailers drives lightweight meal pouch demand for alpine trekking and van-life segments. EFSA residue limits under the EU Farm to Fork Strategy disqualify conventional preservative-heavy processors from shelf placement. Bavarian processing cooperatives retrofit solar-thermal drying infrastructure to meet EU Green Deal carbon intensity benchmarks.
United States
Backpacking and strategic stockpiling buyer segments compress lead times across single-serve format portfolios. FDA food safety modernization rules and USDA organic certification requirements govern product standards and market access. California's Central Valley fruit processing clusters adopt photovoltaic-assisted dehydration to offset natural gas price volatility.
Netherlands
Civil defense emergency preparedness programs incorporate lightweight dehydrated rations into official recommendation frameworks. REACH chemical safety protocols force reformulation of cleaning agents in food-contact drying environments. Rotterdam-Antwerp logistics corridors concentrate bulk ingredient redistribution to downstream European manufacturers.
Spain
Mediterranean fruit and vegetable sourcing clusters supply premium air-dried ingredient volumes to German retailers. Hybrid solar-thermal drying infrastructure displaces gas-fired tunnel dryers across Andalusian and Valencian cooperatives. Barcelona-based processors document CSRD supply-chain disclosure compliance to access institutional procurement channels.
Australia
Expedition catering procurement from polar logistics operators and New Zealand commercial guiding services specifies modular pouch formats for weight and waste-volume calculations. TGA food standards align with international shelf-stability benchmarks. Queensland and New South Wales processing facilities retrofit conventional hot-air tunnel systems for temperature control and traceability alignment.
Air-Dried Food Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and sourcing control dimensions. The market exhibits tiered consolidation with multinational packaged food corporations occupying branded retail channels while regional cooperatives and private specialists dominate bulk ingredient supply. Three archetypes define competitive positioning: vertically integrated agricultural processors, brand-aggregating multinationals, and specialized drying technology operators. Capacity expansion and strategic partnerships represent the dominant competitive moves as players secure Mediterranean and Australian raw material clusters.
Within the agricultural processor archetype, Van Drunen Farms exemplifies North American vertical integration from field to bulk ingredient, while Saraf Foods Pvt. Ltd. occupies a parallel position in South Asian herb and spice drying. Nestle S.A. represents the brand-aggregating multinational tier with shelf-stable meal platform recognition across retail and institutional channels. These three anchors illustrate how geographic sourcing specialization and downstream brand access create defensible positioning against commodity price volatility.
| Leading Market Players |
|---|
| Van Drunen Farms |
| Dehydrates Inc. |
| Nestle S.A. |
| Berrifine A/S |
| Conagra Brands |
| Unilever PLC |
| Saraf Foods Pvt. Ltd. |
| A La Frubense |
| Kerry Group |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times on Mediterranean fruit concentrates concentrate pricing power with Spanish and Portuguese cooperatives possessing hybrid solar-thermal capacity, while German retailers leverage just-in-time inventory positioning through Rotterdam-Antwerp corridors to compress supplier margins on commodity vegetable formats.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates clean-label organic SKUs commanding alpine trekking premiums from conventional preservative-dependent formats facing EFSA disqualification pressure. Price differentiation rests on EU organic certification tier and volume scale, with institutional procurement contracts anchoring standard-tier stability. Cost compression in economy-tier fruit segments is intensifying because Dutch emergency preparedness distributors are consolidating supplier panels. Household emergency stockpilers exhibit highest price sensitivity; expedition catering procurement through Norwegian polar logistics operators shows lowest.
Supply Chain Analysis
Just-in-time inventory preferences among German outdoor specialty retailers clash with strategic stockpiling behavior across Northern European civil defense programs, creating demand forecasting complexity. Supply concentrates in Spain, Portugal, and Australia, with Mediterranean fruit clusters and Queensland processing facilities feeding downstream redistribution. Raw material dependencies center on natural gas for thermal drying operations, photovoltaic infrastructure for carbon compliance, and flexible packaging films. Single-source vulnerability runs through Andalusian tomato concentrate processors. Distribution runs through Rotterdam-Antwerp logistics corridors aggregating bulk ingredient flows to downstream European manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Direct-to-consumer subscription services for thru-hikers and digital nomads represent a service-attach opportunity expanding faster than branded retail hardware, with recurring meal-plan configurations capturing customer lifetime value beyond one-time pouch purchases.
For Market Incumbents: Shield clean-label positioning by accelerating USDA organic and EU organic certification coverage before EFSA residue tightening disqualifies conventional processors. Prioritize backward integration into Mediterranean fruit sourcing clusters to secure supply continuity against weather volatility threatening Spanish and Portuguese cooperatives.
For New Entrants and Emerging Players: EU organic certification fast-tracks open shelf space in German alpine retail networks where technical specification expertise commands price premiums. White-space targets include premium pet nutrition crossover applications and photovoltaic-assisted drying infrastructure serving carbon-conscious Dutch distributors. Penetrate through direct-to-consumer subscription models bypassing traditional outdoor retail markup structures.
For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaged food corporations divesting non-core air-dried ingredient divisions to focus on branded retail platforms. Long-term viability over a multi-year horizon hinges on CSRD supply-chain disclosure compliance opening institutional procurement channels. Watch hybrid solar-thermal retrofit penetration rates across Mediterranean processing facilities as inflection indicator for cost-competitive positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Solar-Thermal Retrofit | Spanish cooperatives adopting photovoltaic-assisted dehydration capture carbon premiums from German retailers. |
| CSRD Supply-Chain Disclosure | Early compliance opens institutional procurement channels through Rotterdam-Antwerp logistics corridors. |
| Direct-to-Consumer Subscription Launch | Thru-hiker meal-plan services bypass traditional outdoor retail markup structures entirely. |
| Clean-Label Certification Investment | USDA organic and EU organic tiers separate premium positioning from EFSA-disqualified conventional formats. |
| Pet Nutrition Crossover Extension | Human-grade air-dried meat formats penetrate premium pet food segments with minimal reformulation. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of EFSA residue limit documentation, EU Green Deal agricultural sustainability targets, and customs records through Rotterdam-Antwerp corridors. Interviews with outdoor recreation equipment procurement managers, Mediterranean cooperative processing directors, Dutch civil defense emergency preparedness coordinators, and German specialty retail category buyers combined with FDA food safety modernization filings and SEC 10-K disclosures from listed packaged food corporations. Bottom-up volume modeling and top-down value triangulation validated segment-level outputs.
Segmentation dimensions modeled span product type, end user archetype, packaging format, and distribution channel across the projection horizon. CAGRs were derived from demand elasticity analysis against EFSA regulatory trajectory and outdoor recreation participation trends. Forecast inputs incorporated photovoltaic-assisted drying capacity expansion timelines and REACH chemical safety protocol compliance costs affecting meat and dairy segments.
Decision-makers should treat outputs as directional under assumptions of continued EU Farm to Fork Strategy implementation and stable natural gas pricing for thermal-dependent operations; material deviation would warrant model refresh. Revision becomes warranted when hybrid solar-thermal retrofit adoption crosses thresholds disrupting Spanish and Portuguese cooperative cost structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
Cookie Pucks Market
Packaged Foods
Canned Fruits Market
Packaged Foods
Canned Food Market
Packaged Foods
High-End Instant Noodles Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Iraq Dried Pasta Market
Packaged Foods
Packaged Zhug Market
Packaged Foods
North America Pasta and Noodles Market
Packaged Foods
Carbon Labeled Packaged Meal Market
Packaged Foods
Ready to Use Fillings Market
Packaged Foods
Protein Packed Foods Market
Packaged Foods
Canned Mushroom Market
Packaged Foods
Condensed Canned Soups Market
Packaged Foods
Convenience Food Market
Packaged Foods
Brio Bowls Market
Packaged Foods
Instant Soup Market