
 North America Packaged Salad Market | 2026-2036
North America Packaged Salad Market Size, Share, and Industry Trends Forecast 2026-2036
North America Packaged Salad Market Intelligence
The fragmentation of the buyer landscape, shifting from large supermarkets to meal kit companies and online retailers, is recalibrating the market's competitive structure. Taylor Fresh Foods leverages its processing scale to serve high-volume channels. Meanwhile, Gotham Greens Holdings, LLC specializes in controlled-environment agriculture for premium urban markets. Dole Food Company, Inc. sustains its position through powerful brand recognition and an extensive distribution network.
North America's packaged salad market encompasses ready-to-eat vegetable mixes that are pre-washed, cut, and sealed for consumer convenience. These products often utilize Modified Atmosphere Packaging, which adjusts internal gas levels to slow spoilage and extend shelf life for retail and food service. The organic product type continues to gain share from conventional offerings, commanding a price premium and appealing to health-conscious consumers. In packaging, rigid clamshells dominate for delicate greens, while flexible pouches provide a cost-effective option for heartier mixes.
The U.S. Food and Drug Administration (FDA) enforces the Food Safety Modernization Act (FSMA), mandating stringent preventive controls for produce safety from farm to fork. In parallel, Health Canada's Safe Food for Canadians Regulations (SFCR) impose strict traceability and licensing requirements on producers and importers. Navigating these complex food safety rules while managing volatile agricultural supply chains remains the central strategic challenge for all operators.
Market Dynamics
The central structural force shaping the North America packaged salad market is the fragmentation of the buyer landscape. A definitive shift in consumer purchasing from large-format supermarkets to direct-to-consumer meal kit companies and online grocery platforms is recalibrating distribution models.
Growth Catalysts
- Convenience-Driven Lifestyles:Demand from time-constrained consumers, particularly within urban centers in the United States and Canada, for quick and healthy meal solutions continues to propel the market forward.
- Packaging Technology:Advances in Modified Atmosphere Packaging (MAP) are critical, extending the shelf life of perishable greens and enabling broader distribution networks while reducing food waste for retailers.
- Organic Product Demand:A sustained consumer shift toward organic and non-GMO products, driven by health and wellness concerns, allows producers to capture price premiums and differentiate offerings.
Market Restraints
- Input Cost Volatility:Producers face significant margin pressure from the unpredictable costs of agricultural inputs, including leafy greens, which are subject to weather events, water availability, and pest-related crop failures.
- Regulatory Compliance Burden:Adherence to stringent food safety regulations, such as the FDA's Food Safety Modernization Act and Health Canada's SFCR, requires substantial investment in traceability and preventive controls.
- High Perishability:Despite packaging innovations, the inherently short shelf life of fresh-cut produce results in high spoilage rates throughout the supply chain, creating inventory management challenges and financial losses.
Strategic Opportunities
- Channel Expansion:There is an opportunity to develop products specifically for institutional food service channels, such as corporate cafeterias, hospitals, and universities, which represent an underpenetrated segment.
- Product Line Extension:Creating salad kits that cater to specific dietary trends, including plant-based, keto, or globally inspired flavor profiles, can attract new consumer demographics and command higher price points.
- Geographic Infill:Operators can target expansion in mid-sized cities and suburban areas across the U.S. and Canada that currently have limited access to the diverse premium offerings found in major metropolitan markets.
Industry Challenges
- Food Safety Management:The operational challenge of preventing and managing potential contamination events and subsequent product recalls remains a primary concern, posing significant risk to brand reputation and consumer trust.
- Cold Chain Complexity:Maintaining precise temperature control across a fragmented logistics network, especially for last-mile delivery to consumers via e-commerce and meal kits, is a constant operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Packaged Salad Market |
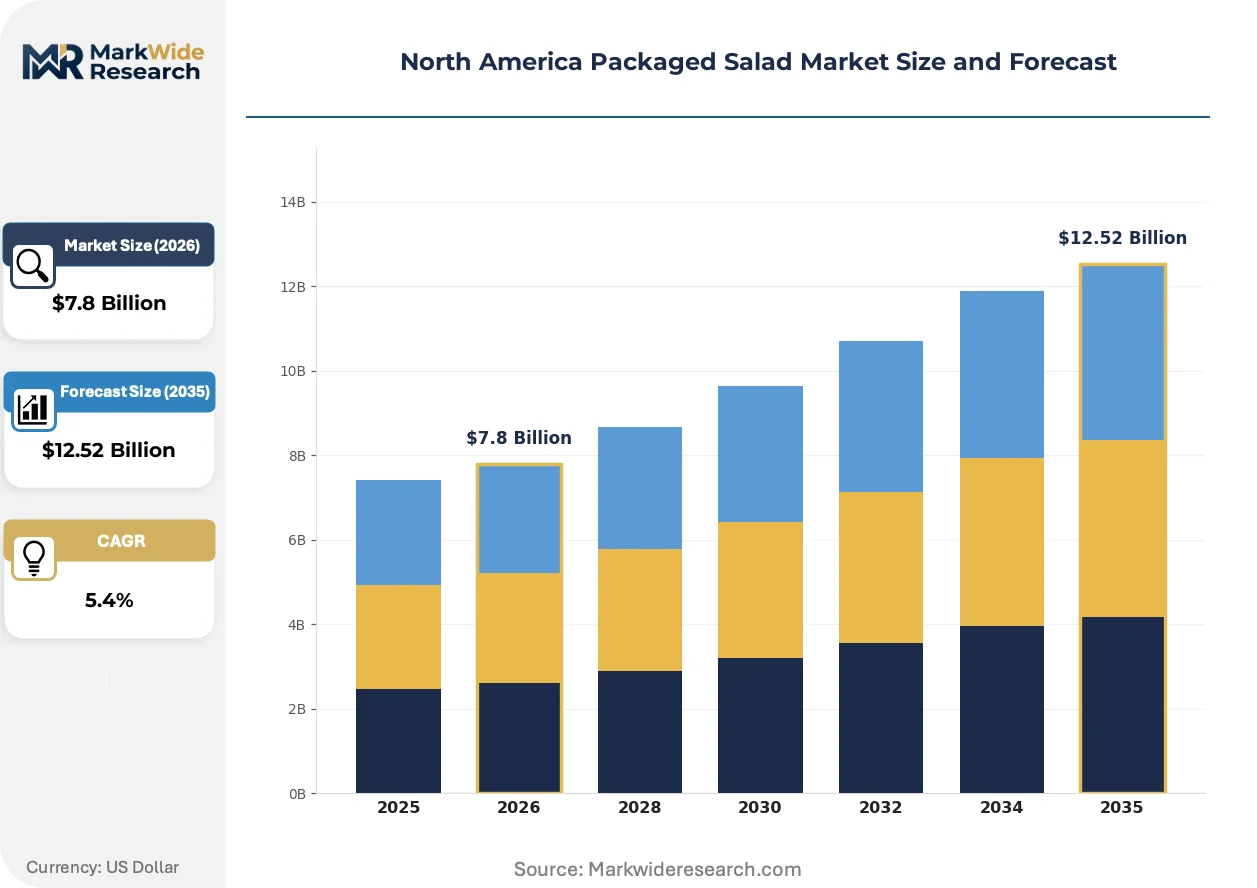
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $12.52 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic, Conventional, Regional Specialties, Pre-packaged End User: Retail Consumers, Food Service Providers, Meal Kit Companies, Caterers Packaging Type: Flexible Pouches, Rigid Containers, Clamshells, Modified Atmosphere Packaging Distribution Channel: Supermarkets, Online Retail, Convenience Stores, Wholesale Distributors |
| Companies Covered | Taylor Fresh Foods, Mann Packing Co., Inc., Dole Food Company, Inc., Misionero, Gotham Greens Holdings, LLC, Earthbound Farm, BrightFarms, Inc., Eat Smart, Fresh Express, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Packaged Salad Market Strategic Shifts & Innovations
The market's evolution is being defined by a convergence of agricultural technology, stricter food safety protocols, and consumer demand for greater sustainability. These forces are compelling producers to innovate in both cultivation methods and final product presentation.
Controlled-Environment Agriculture
Controlled-environment agriculture (CEA), including vertical farming and advanced greenhouses, provides a stable, localized supply of leafy greens independent of climate. Premium food service providers and urban retailers are adopting CEA produce for its consistency and quality. In high-value segments, produce from CEA facilities is overtaking field-grown alternatives due to its year-round availability and reduced need for pesticides.
Evolving Food Safety Mandates
The U.S. FDA's Food Safety Modernization Act (FSMA), particularly its Produce Safety Rule, imposes rigorous science-based standards for growing, harvesting, and packing fresh produce. This regulation increases the operational burden and compliance costs for growers across North America. The organic produce segment is most impacted, as suppliers must integrate these federal requirements with their existing organic certification protocols.
Sustainable Packaging Shift
A notable behavioral shift shows consumers actively preferring brands that use environmentally responsible packaging. This trend is disrupting the long-standing dominance of virgin PET clamshells, with alternatives like flexible pouches made from post-consumer recycled content or compostable biomaterials gaining favor. This purchasing preference is most visible among consumers in major metropolitan markets throughout the United States and Canada.
North America Packaged Salad Market Segmentation
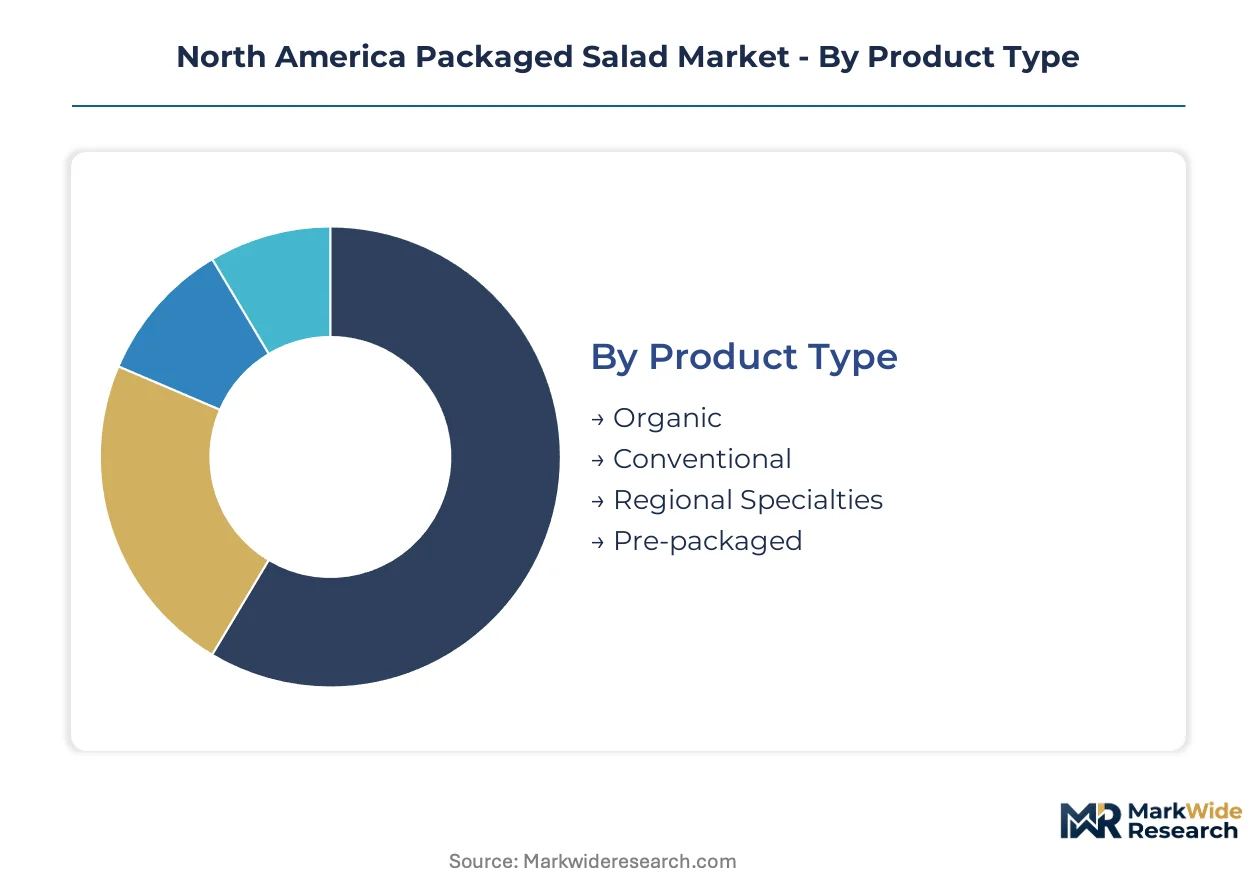
The North America packaged salad market is segmented across several critical dimensions, each reflecting distinct consumer preferences, operational requirements, and competitive landscapes. Understanding these segmentations is essential for strategic positioning and identifying areas for growth within this dynamic sector.
Product Type:
The product type segmentation highlights varying regulatory and certification burdens across offerings.
- Organic:These products require USDA Organic or Canada Organic Regime certification, adhering to strict production and processing standards. Demand concentrates in urban centers, driven by health-conscious consumers willing to pay a price premium.
- Conventional:These products represent the foundational volume of the market, produced without specific organic certifications. Retail consumer demand remains high due to affordability and widespread availability across North America.
- Regional Specialties:These include unique salad mixes featuring specific local ingredients or flavor profiles. Demand often concentrates in specific geographic sub-regions, catering to local culinary preferences.
- Pre-packaged:This broad category includes any vegetable mix that is pre-washed, cut, and sealed for immediate consumption. Convenience-driven lifestyles across the United States and Canada sustain widespread demand.
Conventional sits at the top of the volume ranking, with Organic climbing the fastest.
End User:
End-user segments reflect distinct purchasing behaviors and volume requirements.
- Retail Consumers:This segment comprises individuals purchasing packaged salads directly from supermarkets or online platforms for home consumption. Demand is driven by convenience and health trends among busy households in metropolitan areas.
- Meal Kit Companies:These businesses integrate packaged salads as components within their subscription-based meal delivery services. Their procurement patterns are reshaping competitive positioning for high-volume, consistent supply.
- Food Service Providers:This segment includes restaurants, corporate cafeterias, and institutional kitchens utilizing packaged salads for prepared meals. Operational efficiency and consistent quality are critical purchasing criteria for these operators.
- Caterers:Caterers purchase packaged salads for events and bulk meal preparation, prioritizing ease of use and consistent product presentation. Their demand is often seasonal and event-driven, requiring flexible supply.
Retail Consumers represent the largest segment, while Meal Kit Companies are rapidly expanding their share.
Packaging Type:
Packaging types differentiate based on material cost, product protection, and shelf-life extension capabilities.
- Clamshells:These rigid, often clear, containers dominate for delicate leafy greens, offering superior physical protection and visual appeal. Consumer preference in major metropolitan markets supports their continued use despite sustainability concerns.
- Modified Atmosphere Packaging:This technology actively modifies the internal gas composition to slow respiration and extend the shelf life of perishable salads. Its use is critical for broader distribution networks and reducing food waste for retailers.
- Flexible Pouches:These lightweight, cost-effective options are gaining traction for heartier salad mixes and value-oriented offerings. Consumer demand for sustainable packaging drives innovation in this segment.
- Rigid Containers:This category includes various plastic or sometimes fiber-based tubs and bowls, providing robust protection and often serving as ready-to-eat vessels. They are common in both retail and food service applications.
Clamshells maintain a strong market presence, with Modified Atmosphere Packaging enabling wider market reach.
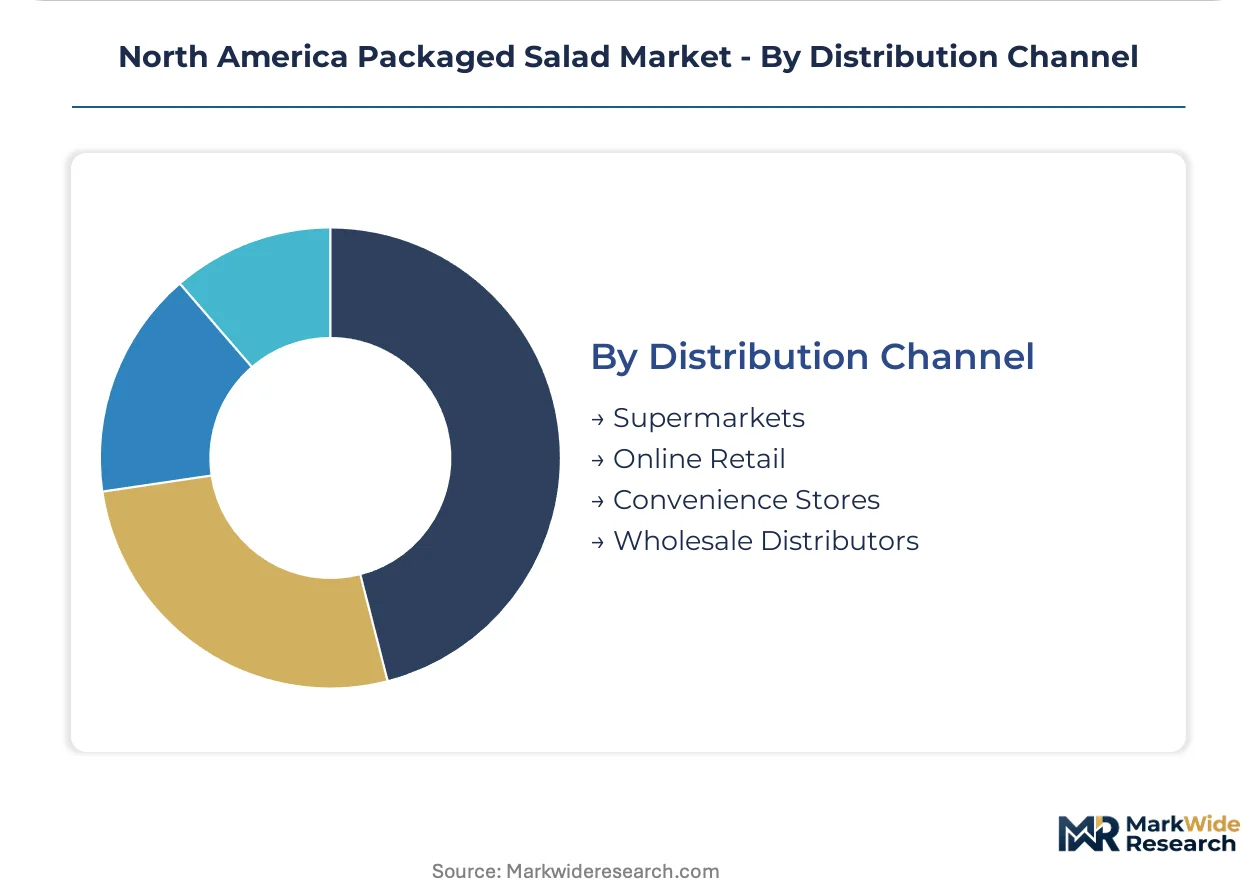
Distribution Channel:
Distribution channels vary significantly in their reach, logistical complexity, and direct consumer engagement.
- Supermarkets:These large-format retail stores remain the primary channel for packaged salad purchases across North America. Their extensive cold chain infrastructure supports high-volume sales of diverse product lines.
- Online Retail:E-commerce platforms and grocery delivery services are experiencing significant expansion, offering home delivery convenience to consumers. This channel requires sophisticated last-mile cold chain management.
- Convenience Stores:These smaller retail formats provide quick access to packaged salads for immediate consumption, particularly in urban areas. Product selection is often limited to popular, high-turnover items.
- Wholesale Distributors:These intermediaries supply packaged salads to food service providers, caterers, and smaller independent retailers. They manage bulk logistics and ensure consistent supply to various business clients.
Supermarkets continue to drive the largest volume, while Online Retail is experiencing the most rapid expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While demand for packaged salads across the United States is driven by health-conscious urban consumers, Canada exhibits a similar preference for convenience and organic offerings. Both nations demonstrate strong market growth, supported by evolving consumer lifestyles.
United States
Demand for ready-to-eat salads in the United States is propelled by time-constrained consumers and meal kit service expansion. The U.S. Food and Drug Administration (FDA) enforces the Food Safety Modernization Act (FSMA), mandating rigorous preventive controls. Major metropolitan areas like Los Angeles and Chicago concentrate demand, where diverse product lines thrive.
Canada
Canadian consumers prioritize convenient, healthy meal solutions, driving sustained growth in the packaged salad sector. Health Canada's Safe Food for Canadians Regulations (SFCR) impose strict traceability and licensing requirements on producers. Toronto and Vancouver represent key urban markets where organic and premium offerings see strong uptake.
Mexico
Mexican demand for packaged salads primarily stems from an expanding middle class seeking healthier, convenient food options. The country's health authorities regulate food safety standards for fresh produce, aligning with international guidelines. Mexico City and Guadalajara are emerging consumption hubs, with increasing availability of pre-washed vegetable mixes.
California
California's market for packaged salads is shaped by a strong health and wellness culture and significant agricultural production capabilities. The California Department of Food and Agriculture (CDFA) implements state-specific regulations for produce handling and safety. The Central Valley supplies a substantial portion of the nation's leafy greens, supporting processing.
New York City Metro
Consumers in the New York City metropolitan area exhibit high demand for premium and organic packaged salads, reflecting urban lifestyle trends. New York State's Department of Agriculture and Markets oversees food safety and labeling requirements for retail produce. Brooklyn and Manhattan feature a high concentration of specialized retailers and meal kit providers.
North America Packaged Salad Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists within the North America packaged salad market. The competitive structure features a mix of large-scale processors, niche providers, and vertically integrated growers. Archetypes include high-volume conventional producers, controlled-environment agriculture specialists targeting premium segments, and established brand leaders leveraging extensive distribution. Companies engage in strategic partnerships and pursue geographic expansion to enhance market reach.
Within the high-volume conventional processing tier, Taylor Fresh Foods represents a major player, leveraging its extensive scale for broad market penetration. Dole Food Company, Inc. exemplifies an established brand leader, maintaining strong market presence through powerful brand recognition and an extensive distribution network. Gotham Greens Holdings, LLC occupies a position as a specialist in controlled-environment agriculture, targeting premium urban markets with its differentiated produce. These entities collectively demonstrate the varied approaches to market leadership across different segments.
| Leading Market Players |
|---|
| Taylor Fresh Foods |
| Mann Packing Co., Inc. |
| Dole Food Company, Inc. |
| Misionero |
| Gotham Greens Holdings, LLC |
| Earthbound Farm |
| BrightFarms, Inc. |
| Eat Smart |
| Fresh Express, Incorporated |
| Others |
Cost & Logistics Intelligence
Agricultural labor concentration in California's Central Valley creates distinct cost structures. These regional labor-cost differentials influence the pricing tiers for conventional versus organic packaged salads across North America.
Pricing Analysis
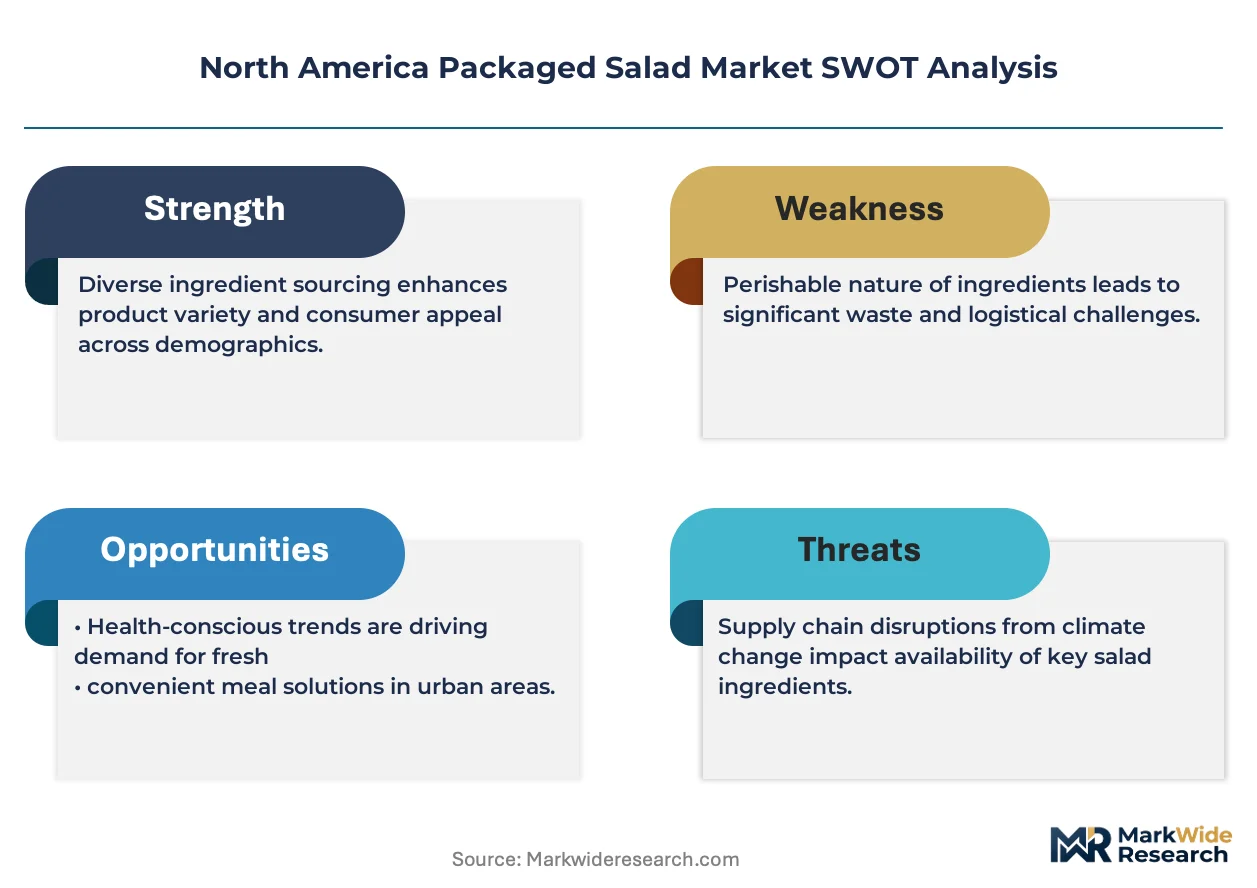
Capacity additions in controlled-environment agriculture facilities are reshaping price floors for premium packaged salads. The dominant pricing model is per-unit transactional, with contract-based long-term off-take agreements for food service. Organic certification level and geographic delivery cost drive price differentiation, particularly for fresh, perishable goods. Pricing pressure stems from input cost volatility for leafy greens, impacting conventional offerings most significantly, while retail consumers are most price-sensitive compared to meal kit companies.
Supply Chain Analysis
Leafy green supply rests on agricultural production in the United States, particularly California, and Mexico. The supply chain relies on consistent availability of fresh produce, packaging materials, and cold chain logistics. A key structural risk is commodity price volatility for leafy greens, driven by weather events and water availability. Downstream distribution primarily runs through large-format supermarkets and increasingly through online retail platforms, requiring sophisticated cold chain management.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America packaged salad market functions as a geographic-arbitrage play, leveraging labor cost differentials between U.S. and Mexican agricultural production. Regulatory compliance costs also vary significantly between Health Canada's SFCR and the FDA's FSMA, influencing operational strategies.
For Market Incumbents:Deploy advanced Modified Atmosphere Packaging research to counteract the high perishability of fresh produce, a persistent margin pressure point. Consolidate agricultural sourcing through long-term contracts to mitigate input cost volatility. Invest in robust traceability systems to manage the increasing regulatory burden from the FDA's Food Safety Modernization Act. This also helps defend against brand reputation damage from potential contamination events.
For New Entrants and Emerging Players:Direct-to-consumer online platforms offer a compelling entry point for niche packaged salad offerings. Target mid-sized cities and suburban areas in Canada with limited premium options, focusing on locally sourced ingredients for a strong go-to-market angle. The most penetrable segment remains health-conscious consumers seeking organic and plant-based salad kits. Develop product line extensions catering to specific dietary trends like keto or globally inspired flavors.
For Investors and Strategic Acquirers:Large food conglomerates are the most active acquirers in this space, seeking to diversify their fresh produce portfolios. The market demonstrates long-term viability over the next five to ten years due to sustained consumer demand for convenience and health. Target acquisition archetypes include controlled-environment agriculture specialists with established urban distribution networks or regional organic producers. A key signal to watch is the increasing market share of online retail and meal kit companies, indicating shifts in consumer purchasing habits.
| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Environment Agriculture Investment | Secures stable, localized leafy green supply for urban markets, reducing reliance on volatile field-grown produce. |
| Sustainable Packaging Innovation | Addresses consumer demand for environmentally responsible packaging alternatives, enhancing brand appeal in metropolitan areas. |
| Meal Kit Channel Partnership | Expands distribution into a rapidly growing segment, catering to convenience-driven consumers and consistent volume needs. |
| Enhanced Cold Chain Logistics | Reduces spoilage rates and extends product shelf life, critical for broader distribution across North America. |
| Food Safety Technology Integration | Strengthens compliance with FDA FSMA and Health Canada SFCR, safeguarding consumer trust and brand reputation. |
Research Approach
Bottom-up retail consumer demand modeling reconciled against top-down agricultural supply tracking forms the analytical core of this study. The approach combines primary interviews with industry stakeholders and secondary validation. Key roles engaged include produce buyers at supermarkets, meal kit company procurement heads, food service managers, and agricultural producers. Secondary data sources encompass government agricultural reports, industry association publications, and company financial filings.
An input-output matrix frames the forecast framework, projecting market evolution across the analysis window. Segmentation dimensions modeled include product type (organic/conventional), end-user, packaging type, and distribution channel, alongside regional demand patterns. Compound Annual Growth Rates were derived from historical market trends and projected future demand. Key forecast inputs include consumer spending on convenience foods and agricultural yield projections for leafy greens.
The model assumes a particular Modified Atmosphere Packaging technology adoption path; alternative pathways for packaging innovation would alter the outlook. Forecasts reflect assumptions regarding consumer preferences and regulatory stability, with geopolitical events impacting agricultural trade or water availability as specific risk factors. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Packaged Foods
North America Breakfast Cereals Market
Packaged Foods
Europe Free from Food Market
Packaged Foods
Asia-Pacific Ready-To-Eat Food Market
Packaged Foods
Rice Noodles Market
Packaged Foods
Sugar Bags Market
Packaged Foods
Low Calorie Noodles Market
Packaged Foods
Instant Noodles Market
Packaged Foods
Chewing Gum Market
Packaged Foods
Canned Goods Market
Packaged Foods
Fat Free Pasta Market
Packaged Foods
Instant Beverage Premix Market
Packaged Foods
Freekeh Market
Packaged Foods
Dried Honey Market
Packaged Foods
Pre-Packaged Sandwich Market
Packaged Foods
Breakfast Food Market
Packaged Foods
Ready-To-Eat Food Market