
 Asia-Pacific Organic Tea Market | 2026-2036
Asia-Pacific Organic Tea Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Organic Tea Market Outlook
Blockchain-enabled traceability is reconfiguring supply chain transparency across organic tea value chains. Tata Group leverages its integrated plantation-to-retail network to sustain quality verification at origin. Organic India anchors its competitive position through Ayurvedic herbal blends that differentiate the brand in wellness-oriented channels. Unilever competes through scale advantages in bottled ready-to-drink formats across mass-market retail.
Organic tea comprises Camellia sinensis leaves and herbal infusions cultivated without synthetic pesticides or chemical fertilizers, processed under certified organic protocols with maximum residue limits enforced at processing stages. The primary commercial purpose centers on delivering antioxidant-rich beverages to health-conscious consumers seeking verified clean-label alternatives. Green tea occupies the dominant volume position among product types due to established functional positioning in East Asian markets, while herbal tea registers the fastest structural expansion as caffeine-free formulations attract wellness center procurement. Loose leaf packaging commands premium margin pools in specialty stores, whereas tea bags dominate household penetration through supermarket channels.
India's FSSAI enforces organic certification compliance for domestic sale and export clearance, while China's SAMR administers GB standards for pesticide residue thresholds in agricultural products. Japan's JAS organic mark shapes import access requirements for foreign suppliers targeting METI-regulated distribution networks. Australia's TGA influences therapeutic claims governance when organic tea products carry functional health assertions. Stakeholders must monitor evolving divergence between national certification standards as harmonization failures threaten cross-border supply chain efficiency.
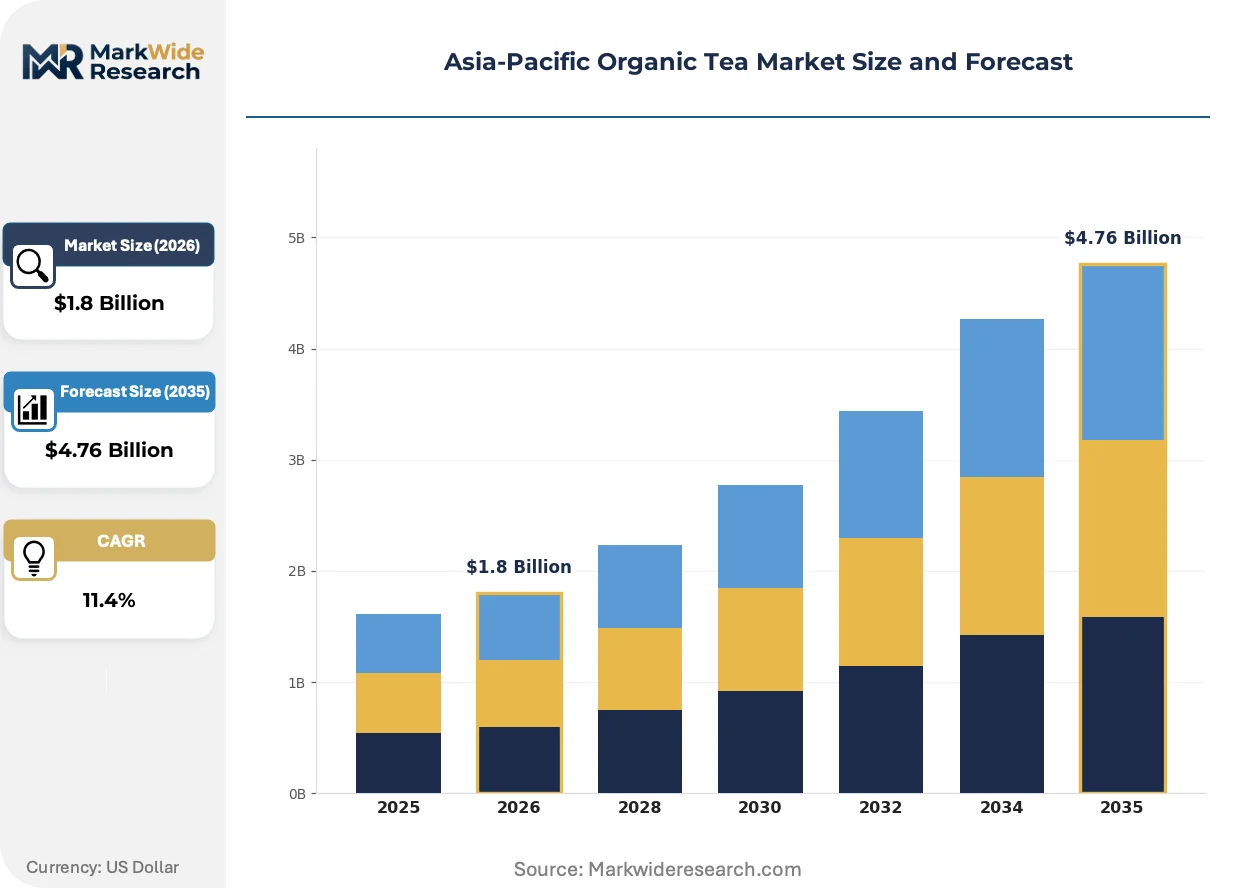
Market Dynamics
Blockchain-enabled traceability is reconfiguring supply chain transparency across organic tea value chains, compressing verification timelines from plantation to retail shelf while reshaping competitive positioning among certification-dependent suppliers.
Growth Catalysts
- India's FSSAI residue-free mandates:Tightening compliance requirements for exporters are accelerating quality investments at origin, filtering substandard suppliers from cross-border trade channels.
- Wellness center procurement expansion:Southeast Asian spa and holistic health chains are expanding certified organic infusion volumes, creating dedicated B2B demand streams with multi-year contract structures.
- Blockchain verification protocols:Distributed ledger systems are reducing documentation fraud in organic claims, enabling premium pricing realization for verified clean-label products.
Market Restraints
- Input cost volatility:Organic fertilizer and biocontrol input prices fluctuate with monsoon-dependent biomass availability, compressing margin predictability for smallholder-dependent supply bases.
- Certification timeline friction:China's SAMR GB standard conversion periods and Japan's JAS mark renewal cycles create 18-24 month compliance windows that freeze export capacity during transition phases.
- Substitute beverage encroachment:Functional bottled waters and adaptogenic coffee formulations are capturing wellness-oriented consumers seeking convenience without steeping rituals.
Strategic Opportunities
- Underpenetrated tier-two China expansion:Specialty retail shelf space for premium loose-leaf formats remains concentrated in tier-one cities, leaving tier-two urban clusters accessible for format-tailored entrants.
- Ayurvedic herbal blend convergence:Traditional medicine system positioning is hybridizing with modern wellness retail, opening pharmacy and clinic distribution channels previously closed to conventional tea.
- Australia's TGA therapeutic claims pathway:Functional health assertion governance is creating a regulatory tailwind for antioxidant-rich products with documented polyphenol content.
Industry Challenges
- Soil microbiome certification expertise scarcity:Transitioning conventional plantations requires agronomists trained in organic soil biology, a skill concentration limited to India's Kerala and Sri Lanka's central highlands.
- Multi-standard compliance complexity:Simultaneous FSSAI, JAS, and private EU-equivalent certification maintenance demands dedicated regulatory affairs capacity that fragments management attention.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Organic Tea Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Tea, Black Tea, Herbal Tea, Oolong Tea Packaging Type: Loose Leaf, Tea Bags, Bottled, Sachets Distribution Channel: Supermarkets, Specialty Stores, Online Retail, Health Stores End User: Households, Cafes, Restaurants, Wellness Centers |
| Companies Covered | Unilever, Tata Group, Organic India, The Hain Celestial Group, Madura Tea Estates, Assamica Agro, Golden Moon Tea, Orgse Tea, Ceylon Organics, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Organic Tea Market Strategic Shifts
Technology convergence and regulatory fragmentation are simultaneously compressing verification cycles and expanding format possibilities across the Asia-Pacific organic tea value chain.
Near-infrared spectroscopy is hybridizing with blockchain verification to create real-time pesticide residue detection at processing facilities. Large-scale plantation operators in Assam and Yunnan are deploying these integrated systems to preempt certification audit failures. The structural consequence is a bifurcation between technology-capable integrated producers and smallholder-dependent aggregators facing exclusion from premium retail channels.
Japan's METI is tightening JAS organic mark enforcement for imported agricultural products, requiring foreign suppliers to demonstrate equivalence with domestic cultivation standards. Industrial consequence includes accelerated investment in Japanese-market-dedicated processing lines by major Indian and Chinese exporters. The specialty loose-leaf segment is responding by establishing captive Japanese distribution subsidiaries to manage compliance directly.
Wellness-oriented consumers are rotating procurement toward direct-to-origin subscription models that bypass traditional wholesale and retail intermediaries. Australia's urban centers and China's tier-one cities are witnessing the fastest channel disintermediation, with digital-native brands capturing recurring revenue through harvest-timed delivery commitments. This behavioral shift is compressing working capital cycles for origin processors while demanding new logistics partnerships for temperature-controlled small-parcel fulfillment.
Asia-Pacific Organic Tea Market Segmentation
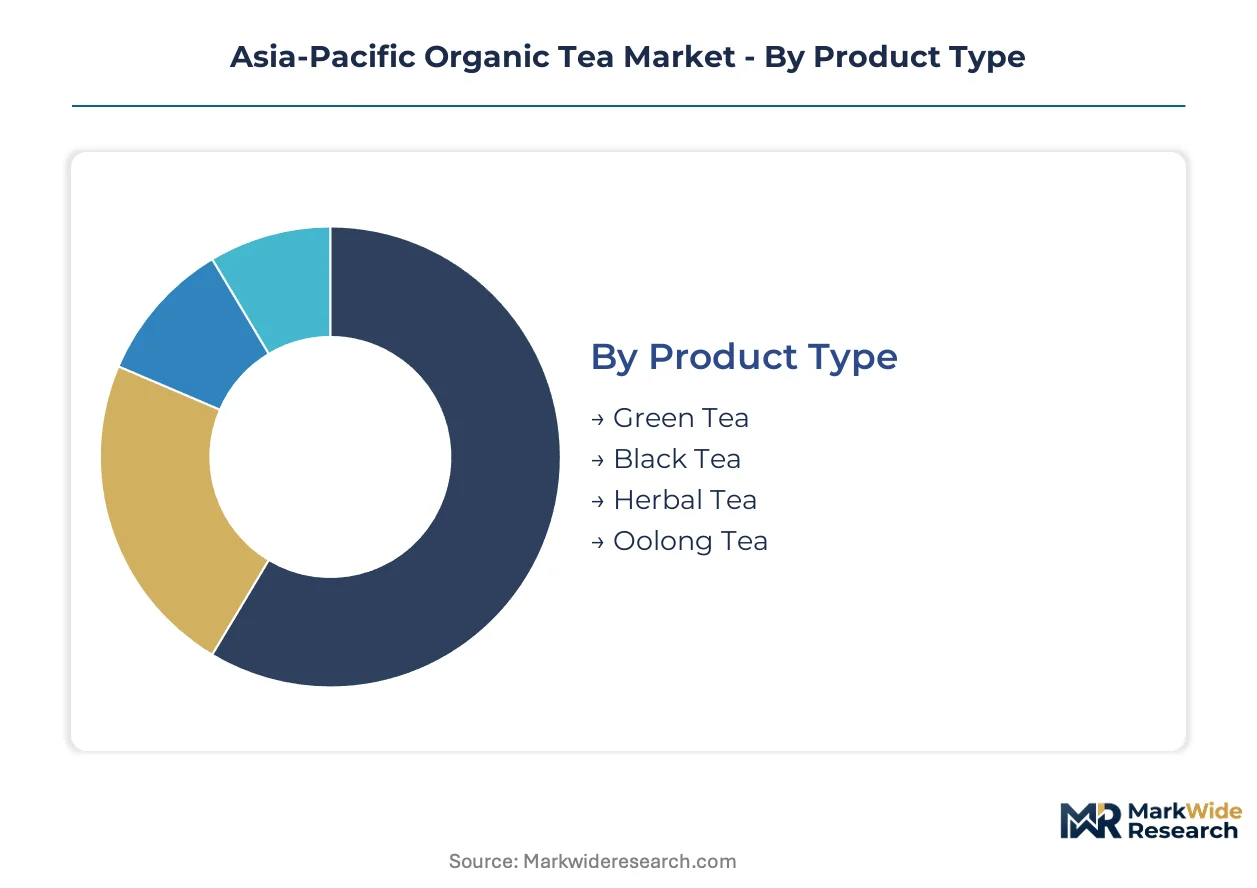
Asia-Pacific organic tea demand fragments across four structural dimensions. Product type and packaging format determine margin capture, while distribution channel and end-user concentration shape procurement scale. Each category carries distinct regulatory and logistics requirements.
Product Type:
Volume concentration and functional positioning split demand across Camellia sinensis varieties and herbal alternatives.
- Green Tea:Unoxidized leaves retain maximum catechin content for antioxidant positioning. China's tier-one cities and Japan's metropolitan corridors concentrate procurement, with FSSAI residue mandates filtering export-grade supply from Indian origins.
- Herbal Tea:Caffeine-free infusions from chamomile, rooibos, and Ayurvedic botanicals target wellness center channels. Southeast Asian spa chains are expanding multi-year contracts for certified organic variants, bypassing conventional retail markup structures.
- Black Tea:Fully oxidized leaves dominate traditional consumption patterns across South Asia, with Assam and Darjeeling origins commanding origin-premium positioning in specialty retail.
- Oolong Tea:Semi-oxidized processing creates flavor complexity for connoisseur segments, with Fujian province origins dominating procurement through Taiwan and Hong Kong distribution nodes.
Green tea commands the established base. The steepest expansion runs through herbal tea.
Packaging Type:
Format selection directly determines shelf placement, margin structure, and temperature-controlled logistics requirements.
- Loose Leaf:Whole-leaf presentation commands premium positioning in specialty retail and direct-to-origin subscription channels. China's tier-two cities present underpenetrated expansion terrain for format-tailored entrants with harvest-timed fulfillment capabilities.
- Tea Bags:Standardized sachets dominate household penetration through supermarket channels, with Unilever-scale operators leveraging volume advantages in mass-market retail.
- Bottled:Ready-to-drink formats capture convenience-oriented consumption in Australia's urban centers and Japan's vending machine networks, requiring aseptic processing investments.
- Sachets:Single-serve pouches align with hotel and airline hospitality procurement, with hygiene-sealed packaging meeting institutional food safety protocols.
Tea bags anchor volume throughput. Loose leaf generates the highest margin realization per kilogram.
Distribution Channel:
Channel selection determines certification visibility, consumer education depth, and working capital cycle length.
- Supermarkets:Mass retail placement demands JAS, FSSAI, or private EU-equivalent certification maintenance, with shelf space allocation favoring established brand recognition.
- Specialty Stores:Curated retail environments in Shanghai, Tokyo, and Sydney enable origin storytelling and brewing education, supporting 40-60% price premiums over supermarket equivalents.
- Online Retail:Direct-to-consumer platforms are compressing wholesale intermediation, with blockchain-enabled traceability claims converting digital-native consumers in Australia's urban centers.
- Health Stores:Pharmacy and clinic-adjacent retail channels are opening to Ayurvedic-positioned blends, with TGA therapeutic claims governance creating regulatory tailwinds in Australian markets.
Supermarkets maintain the widest household reach. Online retail is gaining share fastest through subscription monetization.
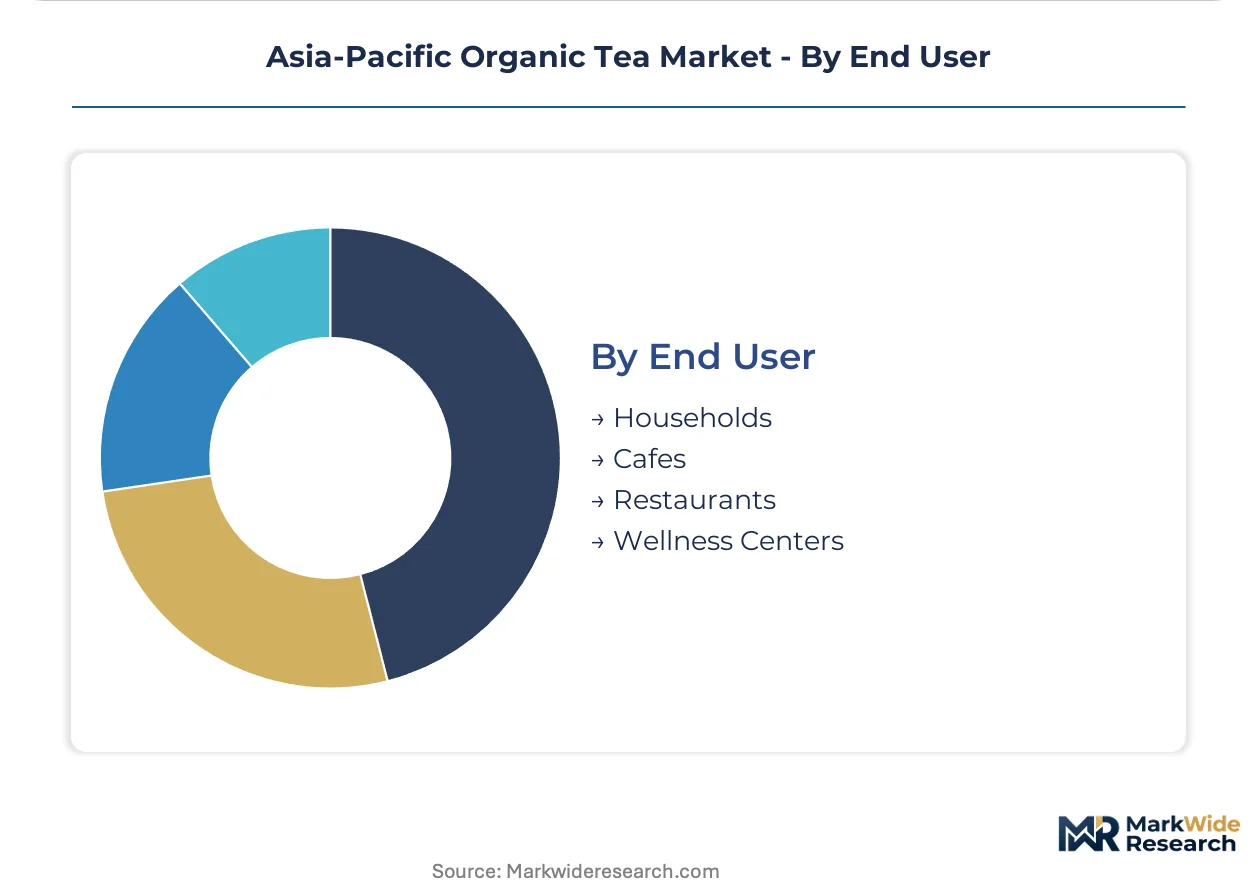
End User:
Procurement scale and contract structure vary sharply across consumption contexts.
- Households:Individual consumption drives repeat purchase loyalty, with flavor variety and convenience format determining brand switching behavior.
- Cafes:Third-wave coffee culture spillover is elevating single-origin tea service, with Melbourne and Bangkok independent operators sourcing direct from Yunnan and Assam processors.
- Restaurants:Fine dining tea pairing menus are expanding in Singapore and Hong Kong, requiring sommelier-trained staff and temperature-precision brewing equipment.
- Wellness Centers:Holistic health chains across Thailand, Indonesia, and Vietnam are expanding certified organic infusion volumes, creating dedicated B2B demand with 12-36 month contract structures.
Households represent the deepest installed base. Wellness centers are climbing the fastest as spa chain consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India exports certified organic Assam and Darjeeling grades through Kolkata and Cochin ports to Japanese buyers under JAS equivalence protocols, while Chinese Fujian and Yunnan processors supply premium oolong and pu-erh through Hong Kong re-export nodes to Southeast Asian wellness chains.
China
Green tea procurement concentrates in Shanghai and Beijing specialty retail, where SAMR's GB 2763 pesticide residue standards filter export-grade supply. Tier-two cities Hangzhou and Chengdu present underpenetrated terrain for loose-leaf format entrants with harvest-timed fulfillment capabilities. Fujian province processors dominate oolong supply through Taiwan distribution nodes.
India
FSSAI residue-free mandates accelerate quality investments at Assam and Darjeeling origins, filtering substandard suppliers from cross-border channels. Kerala's organic plantation clusters supply Ayurvedic-positioned herbal blends to wellness centers across Thailand and Vietnam. Cochin port infrastructure handles certified organic export clearance to METI-regulated Japanese distribution networks.
Japan
METI tightens JAS organic mark enforcement for imported agricultural products, requiring Indian and Chinese suppliers to demonstrate cultivation standard equivalence. Tokyo and Osaka metropolitan corridors concentrate green tea procurement with maximum catechin content positioning. Major exporters establish captive Japanese distribution subsidiaries to manage compliance directly.
Australia
TGA therapeutic claims governance creates regulatory tailwinds for antioxidant-rich products with documented polyphenol content in Sydney and Melbourne urban centers. Direct-to-origin subscription models compress wholesale intermediation through blockchain-enabled traceability claims. Temperature-controlled logistics partnerships support small-parcel fulfillment to digital-native consumers.
Vietnam
Wellness center procurement expansion across Ho Chi Minh City and Hanoi creates dedicated B2B demand streams with multi-year contract structures for caffeine-free herbal infusions. Thai and Indonesian spa chains source certified organic volumes through regional distribution hubs. Local processors face certification timeline friction with JAS and EU-equivalent standard maintenance.
Asia-Pacific Organic Tea Market Competitive Environment
Channel-controlling players compete with product-specialist players across tiered market strata. Scale-driven multinational operators leverage supermarket shelf space allocation and bottled ready-to-drink format penetration, while plantation-integrated domestic groups sustain origin-verified quality positioning. Three archetypes dominate: integrated plantation-to-retail networks, Ayurvedic herbal blend specialists, and mass-market convenience format scale players. Competitive moves concentrate on backward integration into captive organic cultivation and direct-to-consumer subscription channel establishment.
Within the integrated network tier, Tata Group exemplifies plantation-controlled supply chain architecture, while Organic India anchors the Ayurvedic-positioned specialist archetype through traditional medicine system convergence with modern wellness retail. Unilever occupies the scale-driven mass-market position, leveraging volume advantages in standardized format penetration across supermarket channels. These three represent divergent strategic vectors rather than direct segment overlap.
| Leading Market Players |
|---|
| Unilever |
| Tata Group |
| Organic India |
| The Hain Celestial Group |
| Madura Tea Estates |
| Assamica Agro |
| Golden Moon Tea |
| Orgse Tea |
| Ceylon Organics |
| Others |
Value Chain & Pricing Dynamics
Assam's plantation belt anchors regional supply capacity, with Kolkata and Cochin port infrastructure determining export clearance velocity and downstream pricing power across Japanese and Southeast Asian buyer networks. Organic certification maintenance costs and monsoon-dependent biomass availability for biocontrol inputs compress margin predictability for smallholder-dependent aggregators.
Pricing Analysis
Near-infrared spectroscopy deployment separates technology-capable integrated producers from conventional processors, creating a pricing gap between verified clean-label supply and unverified alternatives. Three-tier pricing structure across JAS-certified premium, FSSAI-compliant standard, and uncertified economy levels reflects certification grade and brand premium differentiation. Cost compression in economy tiers is intensifying because substitute beverage encroachment from functional waters and adaptogenic coffee captures convenience-oriented consumers. Wellness center procurement represents the least price-sensitive segment due to multi-year contract structures, while household supermarket channels exhibit highest sensitivity to per-unit packaging costs.
Supply Chain Analysis
Organic fertilizer and biocontrol feedstock availability hinges on monsoon patterns across India's Kerala and Sri Lanka's central highlands, where soil microbiome expertise concentrates. Raw material dependencies center on certified organic biomass inputs, JAS-equivalent processing line investments, and temperature-controlled logistics partnerships for small-parcel fulfillment. Single-source vulnerability runs through Japan-market-dedicated processing lines that freeze export capacity during 18-24 month compliance transition phases. Distribution runs through Hong Kong re-export nodes for Chinese oolong and pu-erh, captive Japanese distribution subsidiaries for major Indian exporters, and direct-to-origin subscription platforms compressing wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific organic tea sits in early-cycle expansion as wellness center procurement accelerates certified organic infusion volumes through multi-year B2B contracts across Southeast Asian spa chain consolidation.
For Market Incumbents: Harden quality verification infrastructure through backward integration into captive organic cultivation in Assam and Darjeeling origins, filtering substandard suppliers before FSSAI residue mandates tighten further. Anchor shelf space allocation in China's tier-two cities through harvest-timed fulfillment capabilities that match specialty retail education depth with supermarket convenience. Certification investment in simultaneous FSSAI, JAS, and EU-equivalent maintenance defends against regulatory fragmentation threatening cross-border supply chain efficiency. For New Entrants and Emerging Players: China's tier-two urban clusters Hangzhou and Chengdu present accessible white-space for loose-leaf format entrants with Ayurvedic herbal blend positioning hybridizing traditional medicine systems with modern wellness retail. Direct-to-origin subscription models in Australia's urban centers bypass wholesale markups through blockchain-enabled traceability claims converting digital-native consumers. Pharmacy and clinic distribution channels previously closed to conventional tea open through TGA therapeutic claims governance for antioxidant-rich products with documented polyphenol content. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated plantation-to-retail networks with near-infrared spectroscopy and blockchain verification capabilities that preempt certification audit failures. Long-term viability across the analysis window rests on soil microbiome certification expertise scarcity limiting transition capacity for conventional plantations. Acquisition target archetype: plantation-integrated domestic groups with captive Japanese distribution subsidiaries managing METI-regulated compliance directly. The signal to watch is JAS mark enforcement tightening that accelerates investment in Japanese-market-dedicated processing lines by major exporters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Organic Cultivation | Tata Group's plantation-controlled architecture sustains origin-verified quality positioning against certification-dependent competitors. |
| Blockchain-Enabled Traceability Deployment | Real-time pesticide residue detection at Assam and Yunnan processing facilities preempts FSSAI and JAS audit failures. |
| Ayurvedic Herbal Blend Convergence | Organic India's traditional medicine system positioning opens pharmacy and clinic channels previously closed to conventional tea. |
| Direct-to-Consumer Subscription Launch | Digital-native brands in Sydney and Melbourne compress working capital cycles through harvest-timed delivery commitments. |
| Captive Japanese Distribution Subsidiary | Specialty loose-leaf segment establishment manages METI-regulated JAS compliance directly without Hong Kong re-export intermediation. |
Study Parameters
Desk research of customs export records, FSSAI certification registries, and METI import compliance filings preceded structured interviews with plantation operations managers, specialty retail category buyers, wellness center procurement directors, and logistics providers handling temperature-controlled small-parcel fulfillment. Primary fieldwork across Assam, Fujian, and Kerala plantation clusters combined with secondary validation from SAMR GB standard documentation and TGA therapeutic claims guidance. Bottom-up volume modeling across product type, packaging format, and distribution channel segments triangulated against top-down trade flow analysis.
Assumptions held fixed include continued FSSAI residue mandate tightening, JAS mark enforcement trajectory, and wellness center contract structure prevalence; variables tested include monsoon-dependent biomass price volatility and substitute beverage encroachment rates. Segmentation dimensions modeled encompass product type, packaging format, distribution channel, and end-user concentration with regional regulatory cluster overlays. CAGRs derived from trend extrapolation of certification-driven premium realization and channel shift velocities, with organic fertilizer input cost trajectories and blockchain verification adoption curves as industry-specific forecast inputs across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive moves by technology-capable integrated producers or rapid regulatory harmonization between FSSAI, JAS, and EU-equivalent standards would shift outcomes beyond modeled ranges. Cross-checking against customs export volume data and wellness center contract announcement tracking is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tea
Asia-Pacific Ready to Drink Tea Market
Tea
Herbal Tea Market
Tea
Global Catechin Market
Tea
North America Tea Market
Tea
RTD Tea Market
Tea
Green Tea Bag Market
Tea
Floral Tea Market
Tea
Matcha Products Market
Tea
Tea Concentrate Market
Tea
Spray-Dried Tea Products Market
Tea
White Tea Market
Tea
Mate Tea Market
Tea
US Ready to Drink Tea Market
Tea
Instant Tea Market
Tea
Smart Tea Maker Market
Tea
Middle East Ready to Drink Tea Market