
 Multiflex Tubes Market | 2026-2036
Multiflex Tubes Market Size, Share, and Industry Trends Forecast 2026-2036
Multiflex Tubes Market Foresight
Multi-layer coextrusion technology is reconfiguring how tube manufacturers balance barrier performance with material efficiency. Amcor leverages its global film and laminate expertise to anchor supply relationships with pharmaceutical packagers. Berry Global sustains manufacturing scale across multiple polymer platforms, competing on throughput in high-volume healthcare segments. Hoffmann Neopac specializes in small-diameter precision tubes, differentiating through decorated aluminum-plastic laminates for cosmetic and medical applications.
Multiflex tubes are engineered conduits manufactured from single or coextruded polymers such as polyethylene, nylon, or rubber, designed to transport fluids, gases, or protect wiring across dynamic motion cycles. Wall thickness, burst pressure ratings, and chemical compatibility determine suitability for medical infusion sets, automotive fuel lines, or industrial hydraulic systems. Multi-layer tubes command premium positioning due to oxygen barrier and drug compatibility requirements in healthcare, while heat-resistant tubes gain traction in automotive under-hood applications where engine bay temperatures exceed standard polymer thresholds. Polyethylene dominates material volume for cost-sensitive fluid transfer, though nylon penetrates where abrasion resistance and dimensional stability prove critical.
FDA enforces biocompatibility and extractables testing for tubes contacting pharmaceuticals or bodily fluids, while REACH and RoHS constrain phthalate and heavy metal content in European-sold products. ISO 10993 provides the toxicological evaluation framework that medical device manufacturers reference when qualifying tube suppliers for Class II and III device registrations. Stakeholders must monitor evolving EU MDR documentation requirements and automotive OEM migration toward electrified thermal management architectures, as these forces will recalibrate material specifications and certification burdens across the value chain.
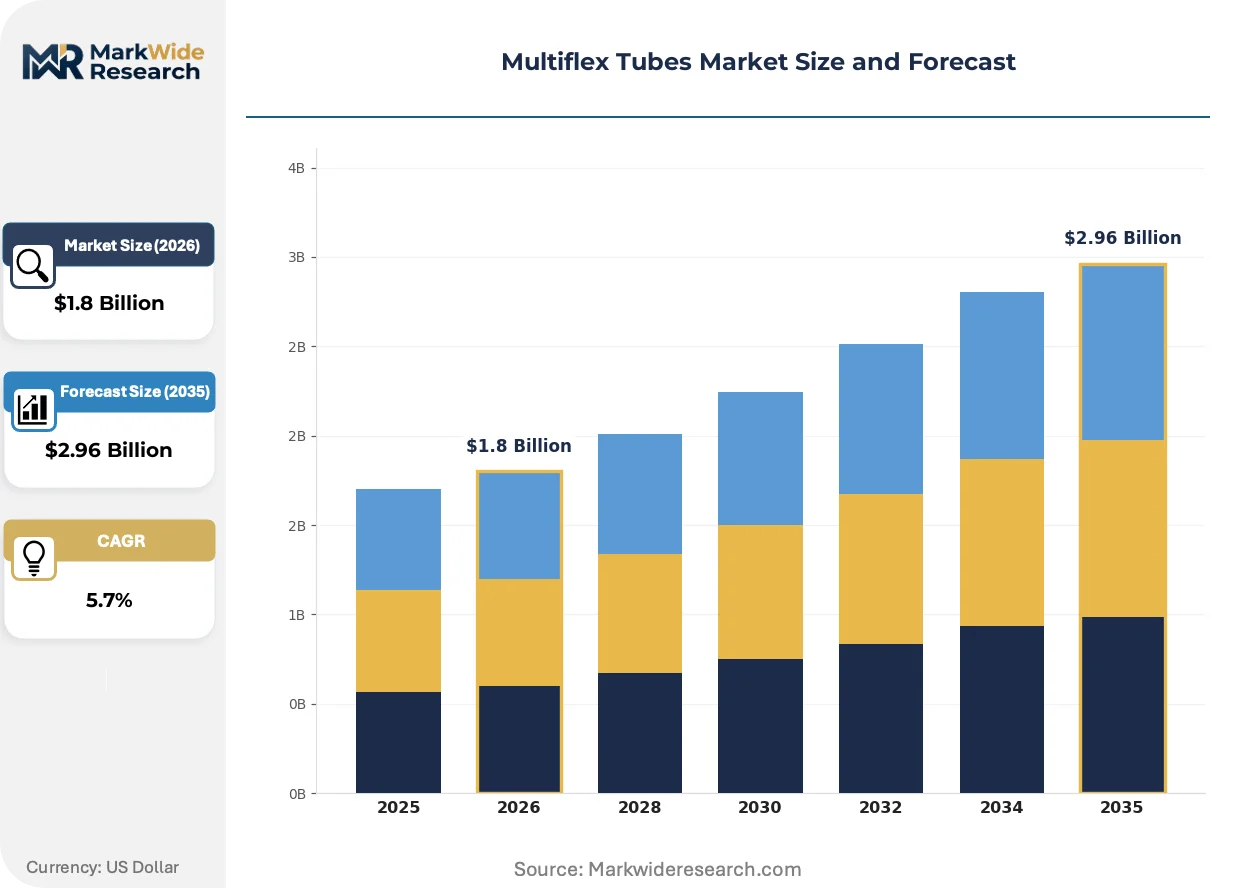
Market Dynamics
Multi-layer coextrusion technology is compressing material costs while tightening barrier specifications, forcing tube manufacturers to reconfigure production lines around oxygen transmission rate targets and pharmaceutical compatibility matrices.
Growth Catalysts
- EU MDR Documentation Burden:Medical device manufacturers are qualifying secondary tube suppliers to diversify regulatory risk, expanding addressable vendor pools for ISO 10993-certified producers.
- Automotive Thermal Management:Electrified powertrains are routing coolant through flexible conduits in battery packs and inverters, replacing rigid piping with abrasion-resistant nylon multiflex architectures.
- Germany's Precision Corridor:Co-location of automotive OEMs and medical device clusters in Baden-Württemberg and Bavaria creates dense supplier ecosystems with shared polymer compounding infrastructure.
Market Restraints
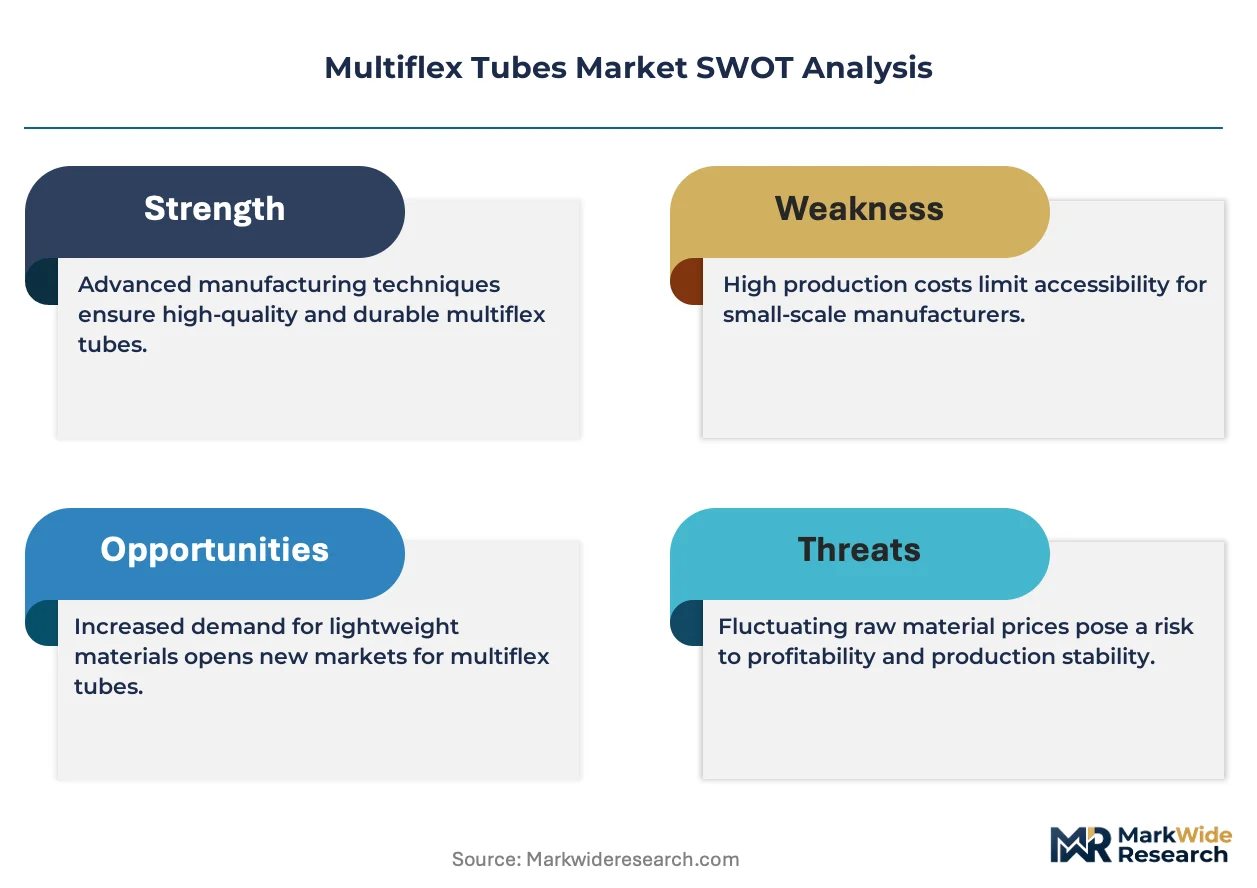
- Specialty Polymer Concentration:Medical-grade nylon 12 and barrier resins source from a narrow base of European and Japanese compounders, exposing converters to allocation risk during feedstock disruptions.
- REACH Phthalate Constraints:ECHA restrictions on plasticizers in healthcare and cosmetic applications force reformulation cycles that extend qualification timelines by 12-18 months.
- Metal Substitution Threat:Stainless steel corrugated tubing retains share in high-pressure hydraulic segments where polymer burst ratings cannot match fatigue resistance specifications.
Strategic Opportunities
- India's Medical Device PLI:Production-linked incentives for domestic catheter and infusion set manufacturing are attracting tube extruders to establish compounding and finishing operations near CDSCO-registered device parks.
- Closed-Loop Recycling Mandates:EU Green Deal packaging regulations are creating first-mover advantage for converters with validated post-industrial polyethylene regrind streams in cosmetic tube applications.
- Drug-Device Convergence:Prefilled syringe and wearable injector platforms are integrating sensor-ready tubing with embedded conductive traces, merging fluid handling with electronic functionality.
Industry Challenges
- Multi-Layer Bonding Expertise:Coextrusion die design and interlayer adhesion chemistry require specialized process engineers whose training pipelines lag equipment installation cycles.
- ISO 10993-18 Extractables Testing:Toxicological evaluation of polymer additives and processing aids extends supplier qualification timelines, compressing window for new product introduction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Multiflex Tubes Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Tubes, Rigid Tubes, Multi-Layer Tubes, Heat-Resistant Tubes Material: Polyethylene, PVC, Nylon, Rubber Application: Fluid Transfer, Medical Devices, Industrial Applications, Automotive End User: Healthcare, Automotive Industry, Construction, Food & Beverage |
| Companies Covered | Amcor, Huhtamaki, Essel Propack, Albéa, Montebello Packaging, Berry Global, EPL Limited, Hoffmann Neopac, Tubopac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Multiflex Tubes Market Shifts & Advancements
Material science and regulatory documentation are converging to redefine competitive advantage, with barrier performance and biocompatibility certification becoming inseparable from commercial viability.
Polymer-metal hybrid tubing is hybridizing barrier protection with mechanical durability in automotive fuel vapor recovery lines. Tier 1 suppliers are adopting five-layer coextruded structures with ethylene vinyl alcohol cores and aluminum foil wraps to meet evaporative emission standards. This architecture is compressing demand for monolithic rubber hoses in under-hood applications.
REACH SVHC candidate list expansion is forcing compounders to retire legacy plasticizers and heat stabilizers ahead of sunset dates. Medical tube converters are rebuilding supplier qualification dossiers around phthalate-free alternatives, with the most affected segments being neonatal and pediatric infusion sets where ECHA scrutiny is most intense.
Consolidated procurement by pharmaceutical packagers is displacing fragmented buying across regional converters. Amcor and Berry Global are capturing multi-year supply agreements with integrated barrier specifications, while smaller decorators face margin compression in cosmetic segments where Hoffmann Neopac's aluminum-laminate niche retains pricing power.
Multiflex Tubes Market Segmentation
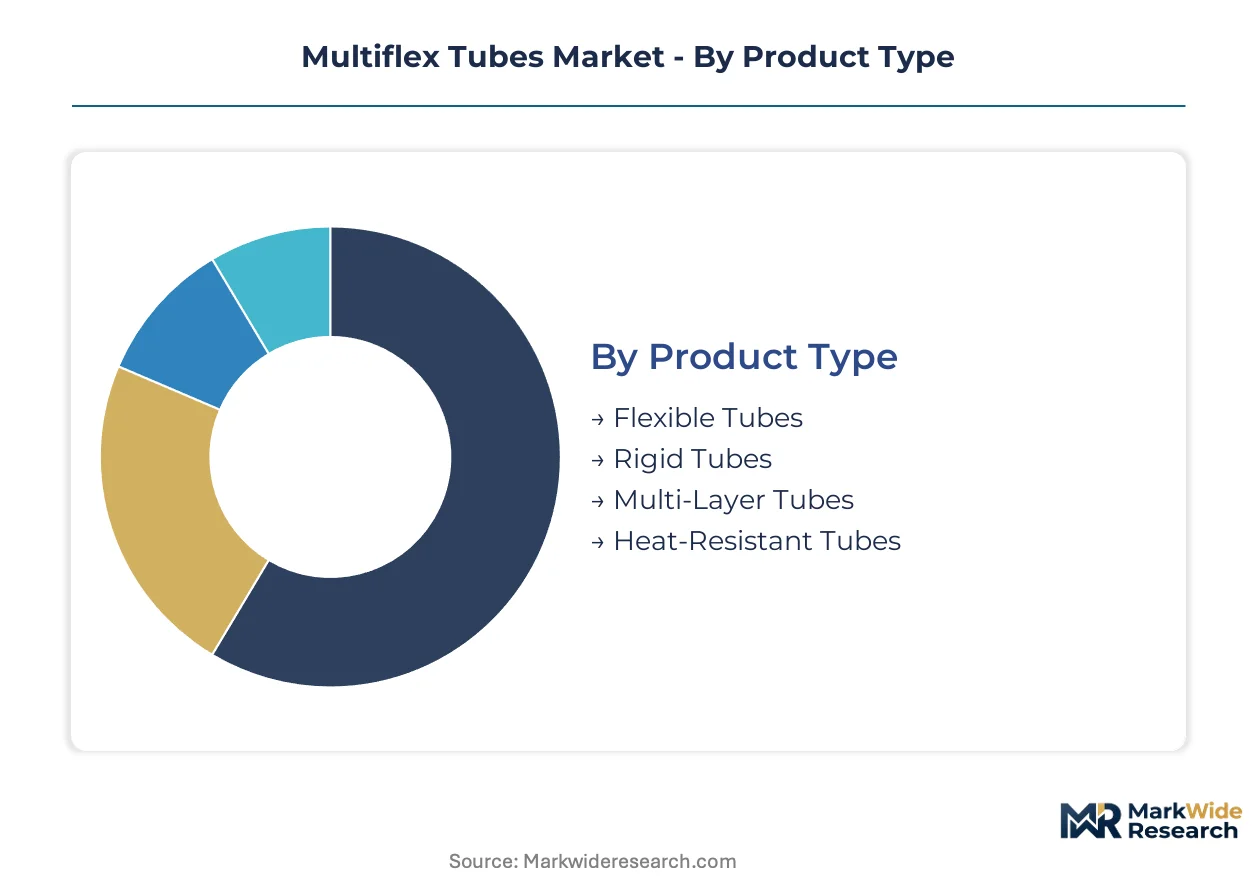
Multiflex tube specifications diverge sharply across end-use environments, with medical-grade barrier requirements and automotive thermal tolerances creating incompatible procurement pools. Manufacturers must maintain distinct compounding lines, certification dossiers, and customer qualification protocols for each segment cluster.
Product Type:
After-sales service intensity varies dramatically by product architecture, with multi-layer tubes requiring technical troubleshooting for delamination failures while rigid tubes demand minimal field support.
- Multi-Layer Tubes:Coextruded architectures with ethylene vinyl alcohol or aluminum foil cores deliver oxygen transmission barriers below 0.1 cc/m²/day for pharmaceutical packaging. Demand concentrates in Germany's precision manufacturing corridor where medical device and automotive clusters share polymer compounding infrastructure but impose divergent certification matrices.
- Heat-Resistant Tubes:Nylon 12 and fluoropolymer formulations withstand continuous exposure to 150°C engine bay temperatures in electrified vehicle thermal management systems. Automotive OEMs in Baden-Württemberg specify these for battery pack coolant routing where abrasion resistance and dimensional stability under thermal cycling prove critical.
- Flexible Tubes:Single-layer polyethylene constructions dominate cost-sensitive fluid transfer applications with burst pressure ratings typically below 10 bar.
- Rigid Tubes:High-density polyethylene and polypropylene profiles serve structural conduit applications where bend radius constraints are acceptable.
By volume, flexible tubes lead. By growth pace, multi-layer tubes are expanding most quickly.
Material:
Cost tier stratification separates commodity polyethylene from engineering-grade alternatives, with price multiples of 3-5x between base and specialty polymers.
- Polyethylene:Linear low-density and high-density grades command material volume leadership through cost positioning below €2/kg for standard extrusion grades. Healthcare fluid transfer and cosmetic packaging absorb the majority of output, though REACH-compliant phthalate-free formulations are compressing margins for European converters.
- Nylon:Nylon 11 and 12 variants deliver abrasion resistance and chemical compatibility for automotive fuel lines and pneumatic systems. Japanese and European compounders control specialty resin supply, exposing tube manufacturers to allocation risk during feedstock disruptions.
- PVC:Plasticized formulations retain share in medical drainage and general-purpose tubing despite regulatory pressure from ECHA SVHC candidate list expansions.
- Rubber:EPDM and nitrile constructions serve high-flexure hydraulic applications where polymer fatigue resistance falls short of specifications.
Polyethylene dominates tonnage. Nylon is climbing the fastest on electrification-driven thermal management demand.
Application:
Customer type fragmentation separates specification-heavy medical device buyers from price-driven industrial procurement.
- Medical Devices:Infusion sets, catheters, and drug delivery systems require ISO 10993 biocompatibility certification and extractables testing per FDA and EMA guidelines. Prefilled syringe and wearable injector platforms are integrating sensor-ready tubing with embedded conductive traces, merging fluid handling with electronic functionality.
- Automotive:Electrified powertrains route coolant through flexible conduits in battery packs and inverters, replacing rigid piping with abrasion-resistant architectures. Tier 1 suppliers specify five-layer coextruded structures with EVOH cores to meet evaporative emission standards.
- Fluid Transfer:General-purpose liquid and gas conveyance in industrial and consumer applications.
- Industrial Applications:Hydraulic and pneumatic systems requiring pressure ratings above 20 bar.
Fluid transfer leads in unit volume. Medical devices show the steepest expansion trajectory on drug-device convergence trends.
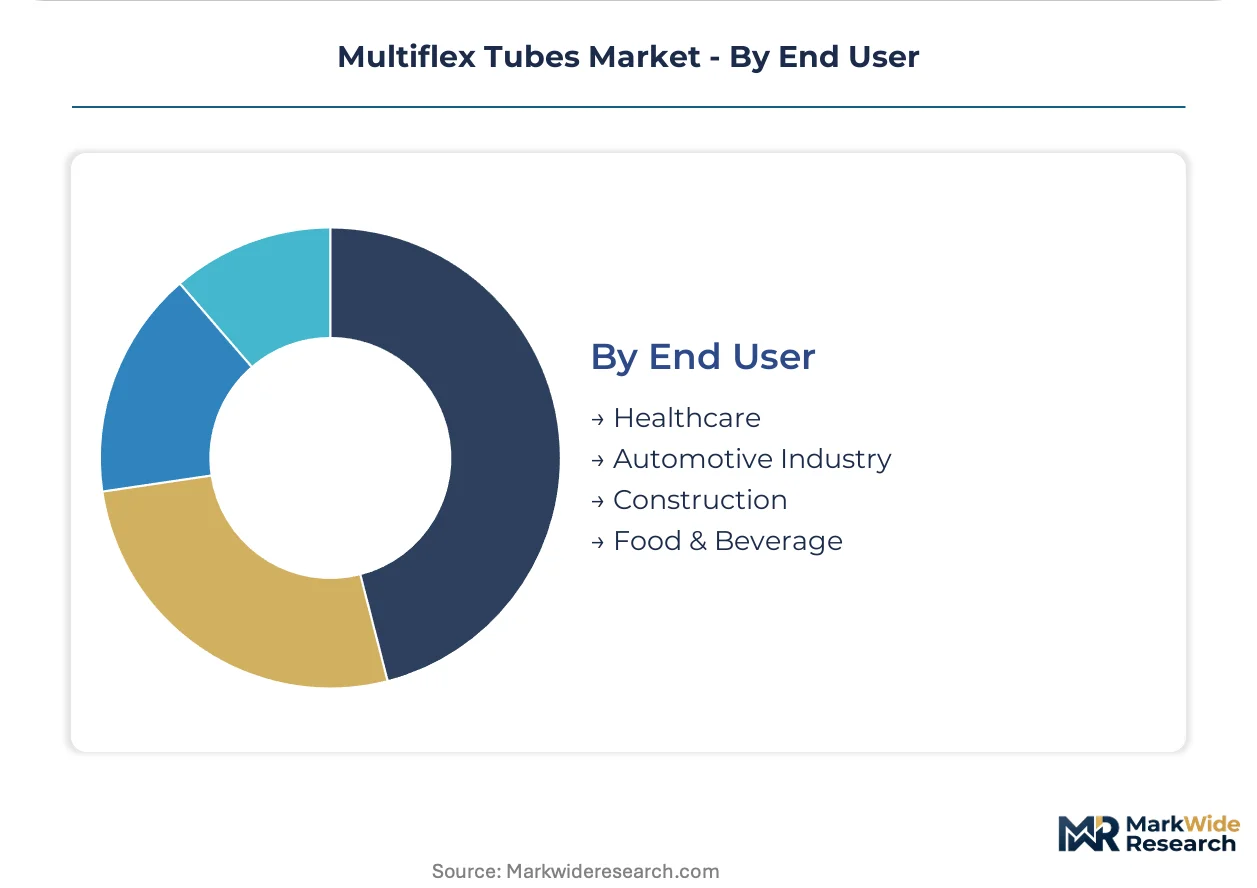
End User:
Supply concentration in Germany's automotive-medical cluster creates geographic lock-in for qualified suppliers.
- Healthcare:Hospitals, clinics, and home care settings drive demand for sterile, single-use tubing with documented biocompatibility. EU MDR documentation requirements are forcing manufacturers to qualify secondary suppliers, expanding vendor pools for ISO 10993-certified producers.
- Automotive Industry:OEMs and Tier 1 suppliers specify thermal management and fuel system tubing with PPAP submission requirements. Production-linked incentives in India are attracting tube extruders to establish operations near CDSCO-registered device parks.
- Construction:Plumbing and HVAC applications utilizing cross-linked polyethylene and barrier pipe.
- Food & Beverage:Beverage dispensing and processing equipment requiring FDA and EFSA compliance for food contact.
Healthcare generates premium pricing. Automotive is gaining share fastest on electrification capex cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-manufactured multiflex tubes to medical device and automotive buyers across Western Europe and North America, anchoring a trade corridor that channels high-barrier coextruded products into regulated healthcare markets.
Germany
Automotive electrification and medical device manufacturing drive demand for nylon 12 and EVOH-barrier tubes in Baden-Württemberg and Bavaria. ECHA REACH compliance mandates phthalate-free formulations, forcing compounders to rebuild supplier dossiers. Stuttgart's automotive cluster and Freiburg's medical technology corridor share polymer compounding infrastructure but impose divergent certification matrices.
United States
FDA biocompatibility requirements for Class II and III devices expand vendor qualification pools for ISO 10993-certified producers. The IRA's domestic manufacturing incentives attract tube extruders to establish operations near pharmaceutical packaging hubs. Minnesota's medical device corridor and Michigan's automotive belt generate concentrated demand for barrier and heat-resistant architectures.
India
CDSCO-registered device parks under the PLI scheme attract tube converters to establish compounding and finishing operations near catheter and infusion set manufacturers. Domestic production of medical-grade polymers remains limited, exposing converters to import dependency for specialty nylons. Maharashtra's Pune-Ahmednagar belt and Karnataka's Bengaluru cluster host emerging extrusion capacity.
Japan
PMDA's stringent extractables testing protocols extend supplier qualification timelines for medical tube applications. Automotive OEMs specify fluoropolymer and high-temperature nylon formulations for hybrid vehicle thermal management. The Nagoya automotive corridor and Osaka medical device cluster sustain demand for precision small-diameter tubing.
China
NMPA's biocompatibility documentation requirements for imported medical devices create compliance barriers for foreign tube suppliers. Domestic compounders scale production of medical-grade polyethylene and barrier resins to substitute European and Japanese imports. The Yangtze River Delta and Pearl River Delta concentrate extrusion capacity for export-oriented pharmaceutical packaging.
Multiflex Tubes Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a tiered structure where scale-driven converters face margin pressure from decorated-laminate specialists. The vendor base separates into three archetypes: global packaging conglomerates with multi-polymer platforms, precision-focused decorators serving cosmetic and medical niches, and regional extruders competing on throughput in commodity fluid transfer. Dominant competitive moves include backward integration into compounding operations and geographic expansion toward CDSCO-registered device parks in India.
Among global packaging conglomerates, Amcor and Berry Global occupy positions defined by film and laminate expertise that anchors pharmaceutical supply relationships. Hoffmann Neopac exemplifies the precision-specialist archetype, with its decorated aluminum-plastic laminates retaining pricing power in cosmetic and small-diameter medical segments where technical differentiation outweighs scale economies. These three companies represent the competitive spectrum from high-volume healthcare throughput to niche barrier-decorated applications.
| Leading Market Players |
|---|
| Amcor |
| Huhtamaki |
| Essel Propack |
| Albéa |
| Montebello Packaging |
| Berry Global |
| EPL Limited |
| Hoffmann Neopac |
| Tubopac |
| Others |
Supply & Pricing Matrix
Baden-Württemberg's precision manufacturing corridor concentrates multi-layer coextrusion capacity for pharmaceutical barrier tubes, giving qualified converters pricing power over medical device buyers facing EU MDR documentation deadlines. Stuttgart's automotive cluster and Freiburg's medical technology corridor share polymer compounding infrastructure but impose divergent certification matrices that fragment procurement pools and sustain premium tiers.
Pricing Analysis
Prior-generation monolithic polyethylene tubes trade at commodity margins below €2 per kilogram, while current-generation five-layer EVOH-barrier architectures command three-to-five multiples for oxygen transmission specifications below 0.1 cc per square meter daily. Three-tier pricing structure across premium, standard, and economy levels separates ISO 10993-certified medical grades from industrial fluid transfer and cosmetic packaging tiers. Cost compression in standard polyethylene segments is intensifying because REACH phthalate reformulation cycles extend qualification timelines without commensurate price recovery. Healthcare procurement committees exhibit lowest price sensitivity due to biocompatibility certification requirements, while industrial fluid transfer buyers drive spot-market negotiations.
Supply Chain Analysis
Specialty nylon 12 and barrier resin feedstocks draw from European and Japanese compounders, exposing tube manufacturers to allocation risk during petrochemical disruptions. Medical-grade polymer supply concentrates in Germany, Belgium, and Japan, with domestic compounding scaling in China to substitute import dependency. Raw material dependencies center on ethylene vinyl alcohol copolymers, aluminum foil laminates, and phthalate-free plasticizer systems. Single-source vulnerability persists for EVOH resin grades qualified to pharmaceutical extractables protocols. Distribution runs through direct supply agreements with pharmaceutical packagers and Tier 1 automotive suppliers, bypassing fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multiflex tubes sit in early-cycle expansion as electrified vehicle thermal management and drug-device convergence create specification-intensive demand pockets that resist commoditization. Penetration remains shallow in India's CDSCO-registered device parks and wearable injector platforms.
For Market Incumbents: Insulate qualification moats by deepening backward integration into medical-grade compounding operations near Stuttgart and Freiburg clusters. Prioritize ISO 10993-18 extractables testing infrastructure to compress supplier onboarding timelines for pharmaceutical packagers consolidating procurement. Defend against metal substitution threats in high-pressure hydraulic segments by advancing polymer-metal hybrid architectures with fatigue-resistant specifications. For New Entrants and Emerging Players: Establish a beachhead in India's Production-Linked Incentive medical device parks, where domestic tube extrusion capacity lags catheter and infusion set manufacturing growth. Target cosmetic packaging segments with decorated aluminum-laminate niches where Hoffmann Neopac's technical differentiation sustains pricing power above commodity converters. Pursue closed-loop recycling validation for post-industrial polyethylene regrind streams to capture EU Green Deal packaging compliance premiums. For Investors and Strategic Acquirers: Long-term, this sits as a specialty materials consolidation play because regulatory documentation burdens and multi-layer bonding expertise create asymmetric returns for qualified producers versus commodity extruders. Acquisition candidates include precision-focused decorators with validated barrier-decorate capabilities and regional extruders with captive compounding in polymer hub geographies. Monitor CDSCO registration velocity in Maharashtra and Karnataka as inflection indicator for India's domestic manufacturing shift.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Medical-Grade Compounding | Captures REACH-compliant phthalate-free formulation margins and compresses qualification timelines for EU MDR submissions. |
| Capacity Expansion in CDSCO-Registered Device Parks | Positions converters near India's catheter and infusion set manufacturing clusters under PLI incentive coverage. |
| Multi-Layer Coextrusion Technology Licensing | Transfers oxygen barrier expertise to regional extruders seeking pharmaceutical packaging qualification. |
| Closed-Loop Recycling Validation Program | Secures first-mover advantage under EU Green Deal packaging regulations for cosmetic tube applications. |
| Sensor-Ready Tubing Development Partnership | Integrates conductive trace embedding capabilities for wearable injector and prefilled syringe platforms. |
Research Methodology
Initial hypotheses were tested against primary input from tube extrusion plant managers, pharmaceutical packaging procurement leads, Tier 1 automotive supplier engineers, and medical device regulatory affairs directors, and refined through secondary validation against ECHA REACH substance registrations, FDA 510(k) device filings, CDSCO medical device park registrations, and European polymer trade association capacity reports. Bottom-up segment sizing triangulated with top-down macroeconomic elasticity checks across healthcare expenditure and automotive electrification capex cycles.
Demand-supply balance modeling anchored volume projections across the analysis window, with segmentation by product architecture, material grade tier, end-use application intensity, and regional regulatory cluster. CAGRs derived from elasticity-adjusted adoption curves for electrified vehicle thermal management and drug-device convergence platforms. Industry-specific forecast inputs incorporated OEM battery pack coolant routing specifications and EMA extractables testing protocol evolution.
Sensitivities concentrate around ECHA SVHC candidate list expansion timelines, specialty polymer allocation disruptions, and NMPA biocompatibility documentation barriers for imported medical devices. Cross-checking against IHS Markit vehicle production databases and hospital procurement system tubing spend patterns is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Metal Pipe Market
Pipes and Tubes
Global Polyethylene Pipes and Fittings Market
Pipes and Tubes
ESR Tubes Market
Pipes and Tubes
Global CPVC Pipes and Fittings Market
Pipes and Tubes
UAE PVC Pipes Market
Pipes and Tubes
PVDF Pipes Market
Pipes and Tubes
Cold Drawn Seamless (CDS) Steel Pipes Market
Pipes and Tubes
FRP Pipe Market
Pipes and Tubes
GRP Pipe Market
Pipes and Tubes
Global Cured-In-Place Pipe Market
Pipes and Tubes
Steel Pipe Market
Pipes and Tubes
North America Hydraulic Fluid Connectors Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
Global Titanium Tube Market
Pipes and Tubes
Pneumatic Fittings Market
Pipes and Tubes
HPLC Fused Silica Tube Market