
 India PVC Pipes Market | 2026-2036
India PVC Pipes Market Size, Share, and Industry Trends Forecast 2026-2036
India PVC Pipes Market Insights
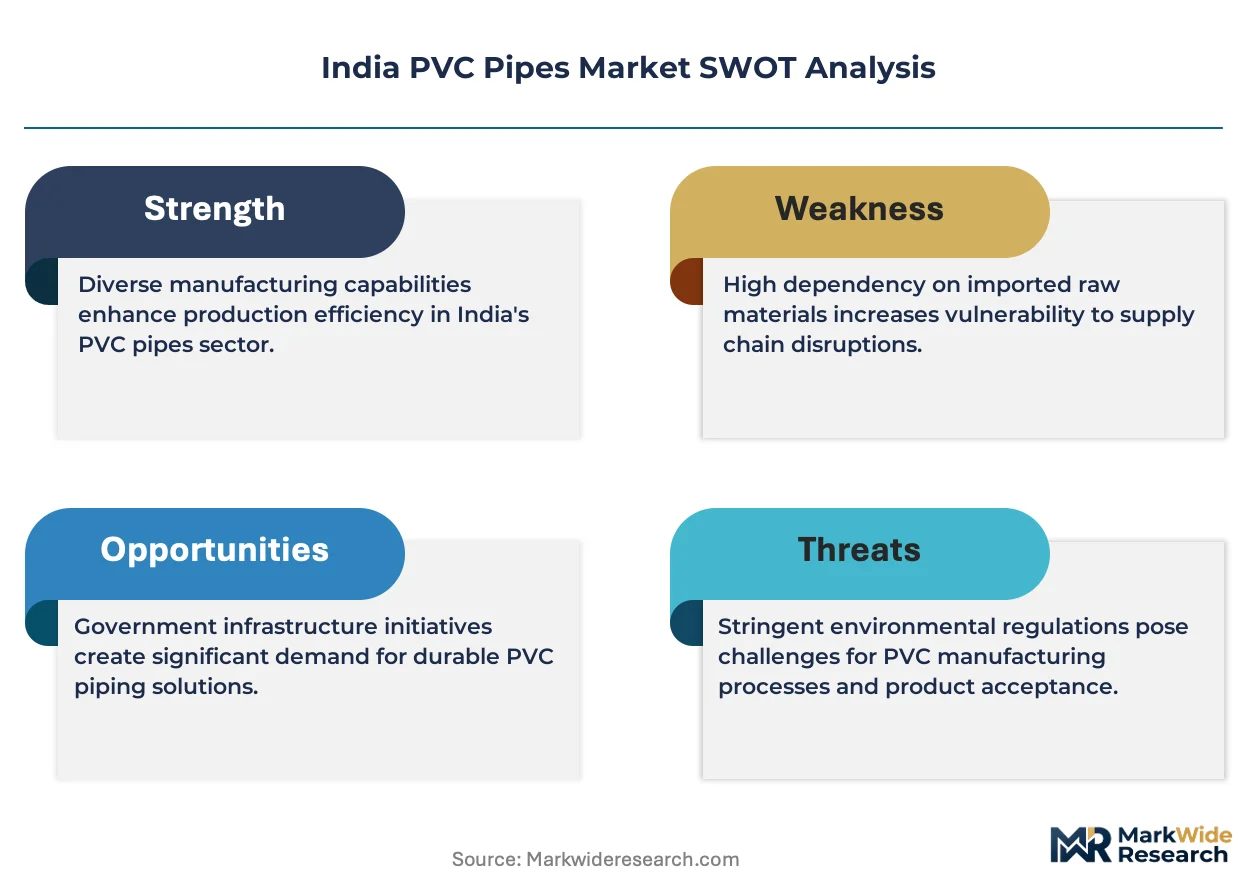
Project finance tied to Jal Jeevan Mission and AMRUT 2.0 outlays is reconfiguring competitive entry barriers, allowing mid-scale manufacturers to bid for multi-year municipal contracts previously reserved for large balance-sheet players. Finolex Industries leverages its captive resin capacity and western India manufacturing footprint to sustain margin resilience across volatile feedstock cycles. Supreme Industries anchors its position through deep distribution in southern and western states, while Astral Pipes differentiates via specialty plumbing solutions targeting urban residential complexes.
India PVC pipes are thermoplastic conduits manufactured from polyvinyl chloride resin blended with stabilizers and plasticizers, extruded to precise dimensional tolerances for pressure and non-pressure fluid conveyance. Their corrosion resistance, light weight, and jointing flexibility make them indispensable for agricultural irrigation, potable water distribution, and building drainage systems. Schedule 40 pipes dominate volume due to cost efficiency in gravity-flow applications, while Schedule 80 commands premium positioning in industrial pressure systems where mechanical strength is non-negotiable. The agricultural application segment retains structural heft from canal lining and drip mainline deployments, though plumbing applications exhibit faster trajectory shifts as housing-for-all schemes accelerate urban fitting demand.
BIS standards for potable water contact materials, CEA guidelines for hydro project penstocks, and state-level irrigation department procurement specifications collectively shape product certification requirements and market access conditions. Jal Jeevan Mission technical audits and BIS mark enforcement are progressively disqualifying uncertified extruders from government contract eligibility. Stakeholders must monitor feedstock import duty adjustments and state-level urban infrastructure budget allocations as decisive variables for capacity planning and regional market prioritization.
Market Dynamics
Jal Jeevan Mission disbursement velocity and BIS certification enforcement are compressing supplier qualification timelines, forcing extruders to front-load compliance investments before tender eligibility windows close.
Growth Catalysts
- Jal Jeevan Mission rural water schemes:Municipal distribution network tenders are accelerating PVC pipe procurement across gram panchayat jurisdictions, with Maharashtra and Gujarat irrigation departments issuing multi-year supply contracts.
- BIS IS 4985 potable water certification:Mandatory marking requirements for lead-free resin formulations are filtering uncertified extruders from government eligibility pools, concentrating volume among compliant manufacturers.
- Drip irrigation mainline deployment:Canal lining projects in Tamil Nadu and Karnataka are specifying large-diameter pressure-rated PVC over traditional concrete channels for seepage control and installation speed.
Market Restraints
- VCM feedstock import dependency:Domestic ethylene dichloride capacity constraints force resin producers to source vinyl chloride monomer from Middle Eastern suppliers, exposing margins to freight rate volatility and rupee-dollar fluctuations.
- Western India manufacturing concentration:Gujarat and Maharashtra host over sixty percent of extrusion capacity, creating regional supply vulnerability during monsoon logistics disruptions and state-level lockdowns.
- High-density polyethylene substitution in pressurized agricultural lines:HDPE's superior fatigue resistance under cyclic pressure loading is displacing PVC in deep borewell submersible pump discharge applications.
Strategic Opportunities
- AMRUT 2.0 urban water distribution retrofits:Smart city infrastructure outlays in tier-2 municipalities are specifying IoT-enabled flow monitoring integration with PVC network installations.
- North-eastern state pipeline connectivity gaps:Assam and Manipur irrigation departments lack established supplier relationships, creating first-mover advantages for extruders willing to establish regional warehousing.
- PLI scheme for specialty chemicals:Domestic VCM and stabilizer additive production incentives are enabling backward integration into resin compounding for pipe-grade formulations.
Industry Challenges
- Multi-grade extrusion die changeover complexity:Schedule 40 to Schedule 80 production switches require eight-hour line reconfigurations, constraining batch flexibility for small-diameter custom orders.
- BIS laboratory testing queue bottlenecks:Potable water-grade certification timelines have extended to fourteen weeks at NABL-accredited facilities, delaying tender submission deadlines for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India PVC Pipes Market |
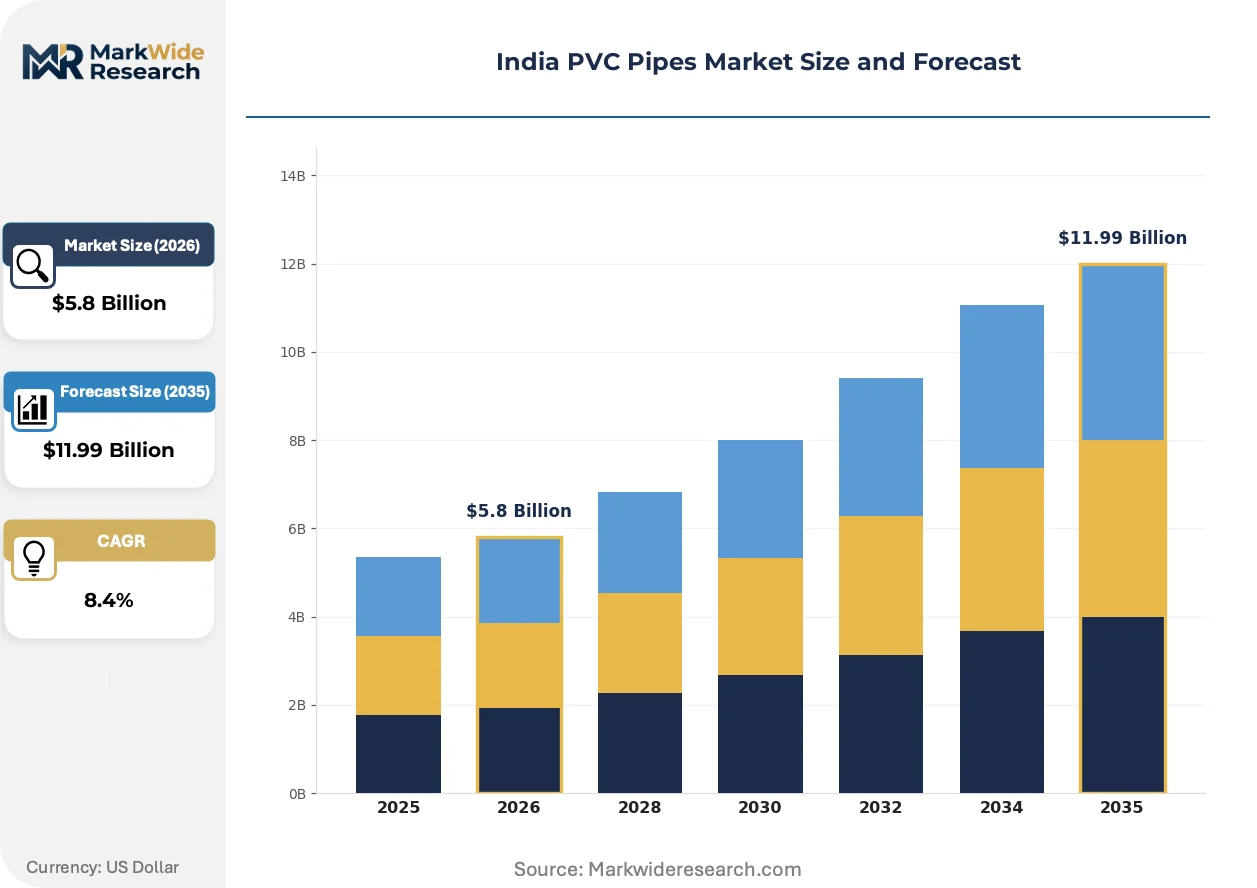
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.99 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Schedule 40, Schedule 80, SDR 21, SDR 26 Application: Agricultural, Industrial, Plumbing, Construction Form: Rigid, Flexible, Composite, Coated End User: Retailers, Wholesalers, Contractors, Manufacturers |
| Companies Covered | Ashirvad Pipes, Ajay Pipes, Supreme Industries, Jain Irrigation, Dutron Group, Finolex Industries, Prince Pipes, Ori-Plast, Astral Pipes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India PVC Pipes Market Trends and Innovations
Extrusion technology, regulatory compliance architecture, and procurement digitization are converging to reshape competitive advantage in Indian PVC pipe supply.
Impact-modified PVC-M compound formulations are collapsing the performance gap between standard PVC and ductile iron in municipal pressure applications. Jal Jeevan Mission contractors in Madhya Pradesh and Rajasthan are specifying PVC-M for distribution mains previously reserved for metal pipes. This substitution is collapsing premium pricing power for ductile iron foundries while compressing PVC supplier margin structures toward commodity levels.
BIS IS 17406 standards for lead-free stabilizer systems entered mandatory enforcement in January 2024, prohibiting calcium-lead formulations in potable water contact surfaces. Extruders lacking organotin or calcium-zinc stabilizer transition capabilities face disqualification from Jal Jeevan Mission and AMRUT tender pools. Southern and western state public health engineering departments are rejecting pre-2024 inventory, accelerating working capital strain for non-compliant manufacturers.
Municipal procurement portals are consolidating supplier discovery and reverse auction execution through centralized e-tendering platforms. State water supply boards in Gujarat and Tamil Nadu have migrated eighty percent of PVC pipe purchasing to digital channels, compressing distributor commission structures and privileging direct manufacturer relationships. Tier-1 extruders with dedicated government sales teams are capturing disproportionate share of these streamlined award processes.
India PVC Pipes Market Segmentation
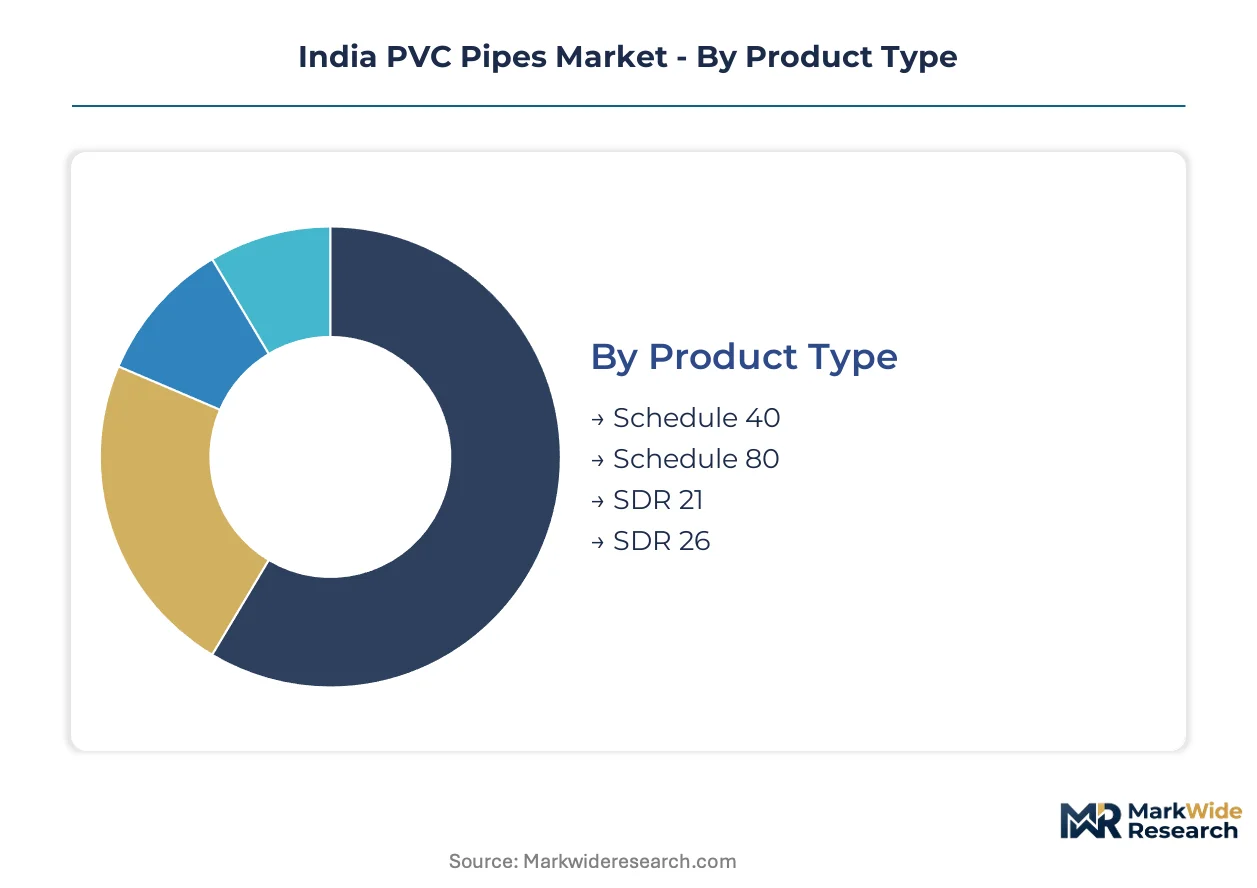
Segmentation in the India PVC pipes market reveals how procurement specifications, installation environments, and buyer power structures fragment demand across distinct technical and commercial categories. Each dimension carries implications for extrusion capacity planning, certification requirements, and channel strategy.
Product Type:
Mature pressure-rated specifications dominate government tender volumes while emerging dimensional standards gain traction in specialized drainage applications.
- Schedule 40:Thinner-walled extrusions optimized for gravity-flow and low-pressure conveyance, formulated with standard PVC-U compounds. Maharashtra and Gujarat gram panchayat contracts under Jal Jeevan Mission specify Schedule 40 for distribution laterals where operating pressures remain below 45 psi.
- Schedule 80:Heavy-wall construction with thicker cross-sections delivering elevated mechanical strength and pressure tolerance. Industrial effluent handling systems in Tamil Nadu chemical clusters mandate Schedule 80 for pump discharge headers where surge pressures exceed standard ratings.
- SDR 21:Standard dimension ratio extrusions balancing wall thickness against internal diameter for intermediate pressure agricultural mains.
- SDR 26:Thinner-wall profile optimized for non-pressure drainage and sewer applications in urban infrastructure retrofits.
Schedule 40 handles the majority of throughput; Schedule 80 is the fastest mover on share as industrial specification upgrades accelerate.
Application:
Cost tier stratification separates commodity agricultural procurement from premium plumbing and industrial specifications demanding enhanced compound formulations.
- Agricultural:Canal lining, drip irrigation mainlines, and borewell discharge systems constitute the volume foundation. Karnataka and Andhra Pradesh irrigation departments specify large-diameter pressure-rated PVC for seepage control in surface water distribution networks.
- Plumbing:Potable water distribution and building drainage systems within residential and commercial structures. AMRUT 2.0 urban retrofit outlays in tier-2 municipalities are specifying lead-free formulations for internal building supply lines.
- Industrial:Chemical processing effluent handling and manufacturing facility process water systems.
- Construction:Temporary dewatering, concrete curing supply, and site drainage during project execution phases.
Agricultural procurement commands the largest absolute volume; plumbing applications are expanding most quickly as housing-for-all schemes drive urban fitting demand.
Form:
Volume concentration favors rigid extrusions while margin differentiation accrues to specialty formulations requiring modified compound engineering.
- Rigid:Standard PVC-U extrusions with fixed dimensional stability for buried and exposed pressure applications. Municipal distribution networks across Rajasthan and Madhya Pradesh specify rigid PVC-M formulations for distribution mains.
- Flexible:Plasticized compounds enabling coiled transport and field bending for drainage and temporary conveyance.
- Composite:Multi-layer constructions incorporating reinforcement or barrier properties for specialized industrial service.
- Coated:Surface-treated extrusions with UV stabilization or abrasion resistance for exposed installations.
Rigid formulations carry the bulk of installed base; flexible products are gaining share fastest in temporary construction and repair applications.
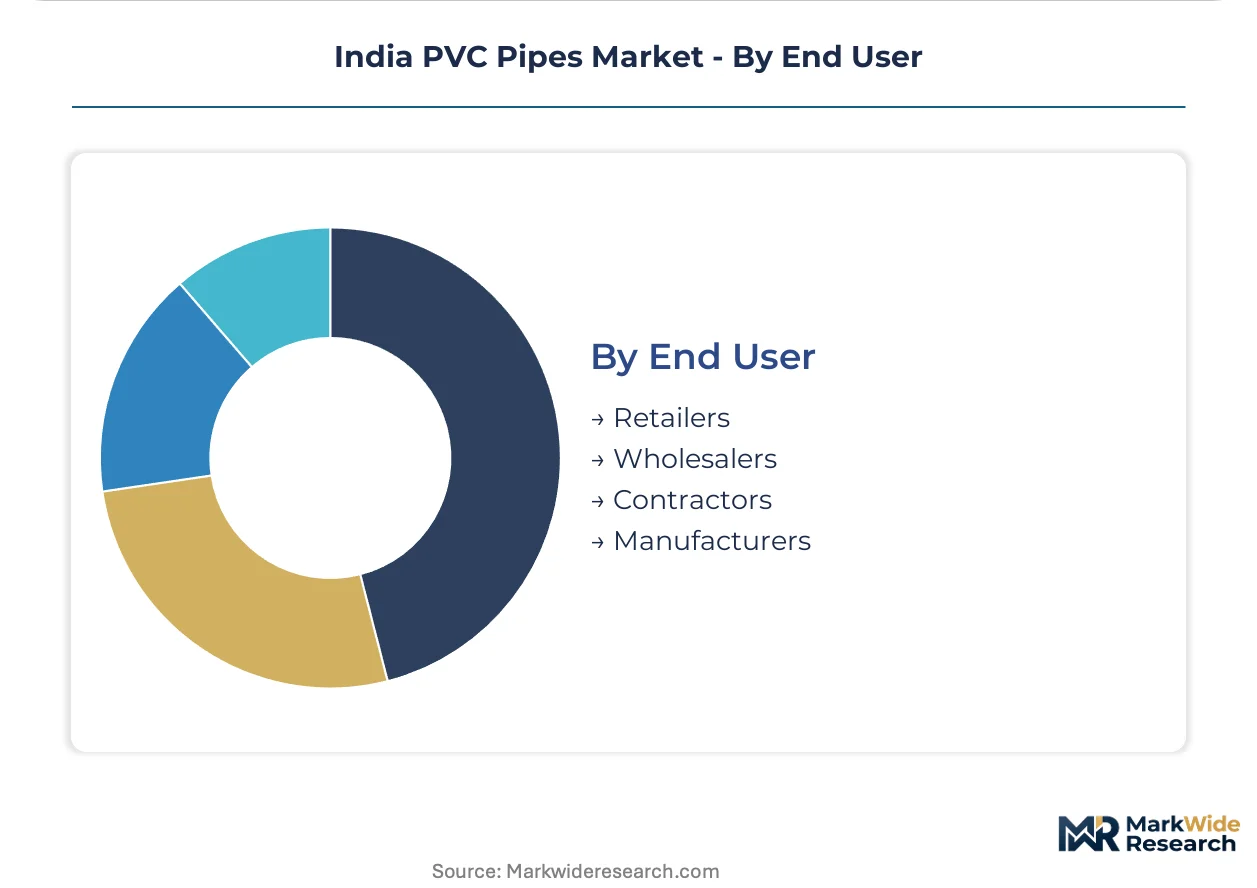
End User:
Customer type determines pricing leverage, with direct contractor relationships commanding premium terms over wholesale distribution channels.
- Contractors:Project-executing entities bidding Jal Jeevan Mission and state irrigation tenders. Direct manufacturer relationships are displacing distributor intermediaries as Gujarat and Tamil Nadu water boards migrate procurement to centralized e-tendering portals.
- Wholesalers:Regional inventory holders serving secondary distributors and smaller contractors.
- Retailers:Point-of-sale outlets for plumbing fittings and small-diameter repair stock.
- Manufacturers:Downstream processors fabricating custom assemblies or integrated system components.
Contractor direct procurement represents the dominant volume channel; wholesaler relationships are climbing the fastest as mid-scale extruders establish regional warehousing in underpenetrated north-eastern states.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jal Jeevan Mission disbursements and AMRUT 2.0 allocations are redistributing procurement volume across state-level water boards, with western and southern states consolidating supplier relationships while eastern and north-eastern jurisdictions open fresh tender windows.
Maharashtra
Gram panchayat water supply schemes under Jal Jeevan Mission drive Schedule 40 procurement for distribution laterals. BIS certification enforcement through the state public health engineering department disqualifies non-compliant extruders from municipal eligibility pools. The Nashik-Ahmednagar industrial corridor hosts dense extrusion capacity serving Marathwada irrigation department tenders.
Gujarat
Canal lining projects in the Narmada command area specify large-diameter pressure-rated PVC for seepage control. State water supply board migration to centralized e-tendering portals compresses distributor commissions and privileges direct manufacturer contracting. The Vadodara-Ankleshwar belt concentrates resin compounding and extrusion operations within a 150-kilometer radius.
Tamil Nadu
Drip irrigation mainline deployment in the Cauvery delta region accelerates SDR 21 specification for agricultural pressure mains. CEA guidelines for hydro project penstocks intersect with state irrigation procurement standards for industrial-grade formulations. The Coimbatore-Tiruppur cluster anchors southern distribution networks serving Karnataka and Andhra Pradesh spillover demand.
Karnataka
Micro-irrigation subsidy schemes through the state horticulture department specify PVC over HDPE for surface water distribution efficiency. BIS IS 4985 lead-free mandates filter pre-2024 inventory from government tender eligibility. The Bengaluru urban agglomeration drives plumbing-grade demand through AMRUT 2.0 retrofit outlays in tier-2 municipalities.
Assam
North-eastern pipeline connectivity gaps create first-mover advantages for extruders establishing regional warehousing outside western manufacturing concentration. State irrigation department procurement specifications remain less stringent than BIS-mandated standards elsewhere, opening transitional market access. The Guwahati corridor lacks established supplier relationships, attracting mid-scale manufacturers from Maharashtra and Gujarat.
India PVC Pipes Market Competitive Landscape
On the supply side, the industry is consolidating around three strategic archetypes: integrated resin-to-pipe manufacturers with captive feedstock security, pure-play extruders with deep distribution in specific state clusters, and specialty plumbing solution providers targeting urban residential specifications. Competitive moves center on backward integration into resin compounding and direct contractor relationship cultivation through dedicated government sales teams.
Among western India-integrated manufacturers, Finolex Industries and Supreme Industries exemplify the resin-captive archetype, while Astral Pipes occupies a position within the specialty plumbing tier. These three entities anchor distinctive competitive vectors: feedstock cost control, multi-state distribution density, and specification-grade product differentiation respectively.
| Leading Market Players |
|---|
| Ashirvad Pipes |
| Ajay Pipes |
| Supreme Industries |
| Jain Irrigation |
| Dutron Group |
| Finolex Industries |
| Prince Pipes |
| Ori-Plast |
| Astral Pipes |
| Others |
Pricing and Supply Chain Analysis
The Mumbai-JNPT freight corridor cost dynamics amplify western India supply concentration while forcing downstream price differentiation between BIS-certified and uncertified extruders. Resin import exposure through this corridor creates margin volatility that concentrates pricing power among captive compounders.
Pricing Analysis
Certification level (BIS IS 4985 lead-free grade) creates the primary spread between qualified and disqualified suppliers in Jal Jeevan Mission tenders. Contract-based long-term offtake dominates municipal procurement, with volume scale and geographic delivery cost as secondary differentiation drivers. Cost compression in Schedule 40 commodity grades is intensifying because HDPE substitution pressure in agricultural lines. Gram panchayat contractors show highest price sensitivity; industrial chemical processors demonstrate lowest.
Supply Chain Analysis
Extended payment terms from state water supply boards strain working capital for non-integrated extruders. Raw material sourcing draws from Saudi Arabian VCM suppliers, domestic ethylene dichloride producers, and Korean stabilizer additive manufacturers. Single-source vulnerability sits with Middle Eastern vinyl chloride monomer dependency. Distribution runs through direct manufacturer-contractor relationships displacing traditional wholesaler networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
E-tendering platform consolidation across state water boards creates platform-economics inflection, rewarding extruders with dedicated government sales teams and API-enabled procurement integration.
For Market Incumbents: Insulate margin position through captive resin compounding capacity and BIS laboratory accreditation ownership. HDPE fatigue resistance in deep borewell applications threatens agricultural PVC volume; backward integration into VCM production via PLI scheme incentives anchors feedstock cost control.
For New Entrants and Emerging Players: Pursue Assam and Manipur warehousing establishment ahead of irrigation department specification tightening. North-eastern pipeline connectivity gaps offer lowest competitive density. Direct contractor relationship cultivation through Jal Jeevan Mission technical audit preparation provides viable go-to-market angle.
For Investors and Strategic Acquirers: Regional extruders with dormant BIS certification pathways present acquisition target archetype for portfolio consolidation. Long-term viability frames around potable water infrastructure replacement cycles and irrigation modernization mandates. Watch Jal Jeevan Mission disbursement velocity as inflection indicator for contract backlog visibility.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive VCM supply via PLI scheme incentives reduces Middle Eastern import dependency for Gujarat extruders. |
| BIS Laboratory Accreditation Investment | In-house IS 4985 testing capability collapses fourteen-week external queue delays for tender eligibility. |
| North-Eastern Regional Warehousing | Assam and Manipur first-mover positioning captures irrigation department procurement before specification tightening. |
| IoT-Enabled Flow Monitoring Integration | AMRUT 2.0 smart city specifications privilege PVC suppliers with sensor partnership capabilities. |
| Organotin Stabilizer Transition | Lead-free formulation compliance filters pre-2024 inventory from Jal Jeevan Mission eligibility pools. |
Research Methodology
Operator-level perspectives from extrusion plant managers, state irrigation department procurement officers, BIS certification auditors, and Jal Jeevan Mission contractors anchored the qualitative base. Secondary validation drew from DGFT import records, BIS notification archives, state water supply board e-tendering disclosures, and CEA hydro project guidelines. Bottom-up capacity modeling and top-down disbursement tracking enabled triangulation across estimation approaches.
Scenario-bracketing framed volume projections across the analysis window, with segmentation dimensions spanning product type (Schedule 40/80/SDR variants), application (agricultural/plumbing/industrial), and end-user channel (contractor direct/wholesaler/retailer). CAGRs derived from tender award velocity correlation with budget allocation trajectories. Feedstock import duty adjustments and monsoon logistics disruption frequency served as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in rupee-dollar exchange rates, crude oil price volatility, or state-level infrastructure budget prioritization would shift the trajectory. Forecasts reflect documented assumptions around BIS enforcement continuity and Jal Jeevan Mission disbursement schedules. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
Gathering Pipeline Market
Pipes and Tubes
Gas Fittings and Components Market
Pipes and Tubes
Duplex Stainless Steel Pipe Market
Pipes and Tubes
Pipe and Tube Cutters Market
Pipes and Tubes
Global Flexible Pipes Market
Pipes and Tubes
Kuwait PVC Pipes Market
Pipes and Tubes
Stainless Steel Tank Container Market
Pipes and Tubes
Perfusion Tubing Systems Market
Pipes and Tubes
Americas Steel Pipes Market
Pipes and Tubes
Multibore Tubes Market
Pipes and Tubes
OCTG Pipe Market
Pipes and Tubes
Tapping Sleeves Market
Pipes and Tubes
Hot Dip Galvanized Steel Pipe Market
Pipes and Tubes
Carbon Steel Pipe Fittings Market
Pipes and Tubes
Europe Line Pipe Market
Pipes and Tubes
Piping System and Piping Spools Market