
 Thermoplastic Edge Bands Market | 2026-2036
Thermoplastic Edge Bands Market Size, Share, and Industry Trends Forecast 2026-2036
Thermoplastic Edge Bands Market Insights
Residential furniture manufacturing is consolidating its share of thermoplastic edge band consumption as commercial interiors soften. Surteco Group SE leverages its European coating technology base to anchor supply relationships with major panel producers. Fritz EGGER sustains vertical integration from particleboard through finished edge solutions, competing on specification breadth across Central European markets. REHAU Group dominates technical polymer formulation, extending its automotive PVC expertise into decorative furniture edges.
Thermoplastic edge bands are polymer-based strip materials, typically 0.4–3.0 mm in thickness, applied to exposed substrate edges through hot-melt adhesive bonding or laser fusion to provide moisture protection and aesthetic finish. Extrusion and co-extrusion processes predominate, with ABS edges gaining specification share over PVC in premium furniture segments due to superior heat resistance and recyclability credentials. The application dimension shows furniture and cabinets commanding the largest volume pools, while flooring edges represent a faster-growing niche driven by luxury vinyl tile expansion. Rigid edges retain scale in mass-market cabinetry, though flexible edges are capturing share in curved-component and custom kitchen applications where thermoforming compatibility matters.
EMA standards for indoor air quality, REACH substance restrictions on phthalate plasticizers, and CE marking requirements for construction products collectively elevate compliance costs while favoring suppliers with certified material traceability. Germany's KBA-influenced automotive supply discipline has cross-pollinated furniture sector quality expectations, tightening tolerance specifications for edge band thickness consistency. Stakeholders must monitor polymer feedstock volatility and evolving EU Green Deal carbon accounting rules that will recalibrate sourcing decisions across the value chain.
Market Dynamics
REACH substance restrictions on phthalate plasticizers are forcing rapid material reformulation across European furniture supply chains, compressing specification windows for PVC edge band producers while elevating certified ABS alternatives.
Growth Catalysts
- EU Green Deal carbon accounting:Furniture manufacturers in Germany's Baden-Württemberg cluster now prioritize low-carbon edge solutions to meet Scope 3 reporting requirements, pulling suppliers toward certified recyclable ABS grades.
- Laser fusion bonding technology:Custom kitchen producers across Poland's Lower Silesia belt are retrofitting production lines for seamless edge application, eliminating visible glue lines and reducing adhesive inventory costs.
- Luxury vinyl tile flooring expansion:Flooring manufacturers specify rigid thermoplastic edge bands for LVT transitions, creating incremental volume pools beyond traditional furniture applications.
Market Restraints
- Polymer feedstock volatility:Acrylonitrile and butadiene price swings compress margin predictability for ABS edge band extruders, particularly smaller compounders without long-term supply contracts.
- Phthalate restriction compliance costs:REACH Annex XVII limitations on plasticizer chemistry force reformulation of legacy PVC recipes, extending R&D timelines and recertification expenses.
- Technical thickness tolerance requirements:Germany's KBA-influenced automotive quality discipline has migrated into furniture sector specifications, disqualifying producers unable to maintain sub-0.05mm variance.
Strategic Opportunities
- Underpenetrated curved-component fabrication:Flexible thermoplastic edges compatible with 3D thermoforming remain undersupplied in Central European custom furniture, where Italian design houses currently import premium solutions.
- Low-VOC adhesive innovation:Hot-melt adhesive producers developing bio-based formulations can capture specification share as EMA indoor air quality standards tighten across residential furniture.
- Co-extrusion technology convergence:Multi-layer edge construction combining rigid cores with decorative surfaces enables premium pricing in high-end cabinetry while reducing material costs.
Industry Challenges
- Specialized extrusion technician scarcity:European labor markets lack sufficient operators trained in co-extrusion die calibration and color-matching for wood-grain decorative layers.
- CE marking certification timelines:Construction product regulation compliance for flooring edge applications extends market entry cycles by 8-14 months for new product lines.
- Legacy adhesive system incompatibility:Furniture manufacturers running solvent-based bonding equipment face capital-intensive line conversions to accommodate laser or reactive hot-melt processes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thermoplastic Edge Bands Market |
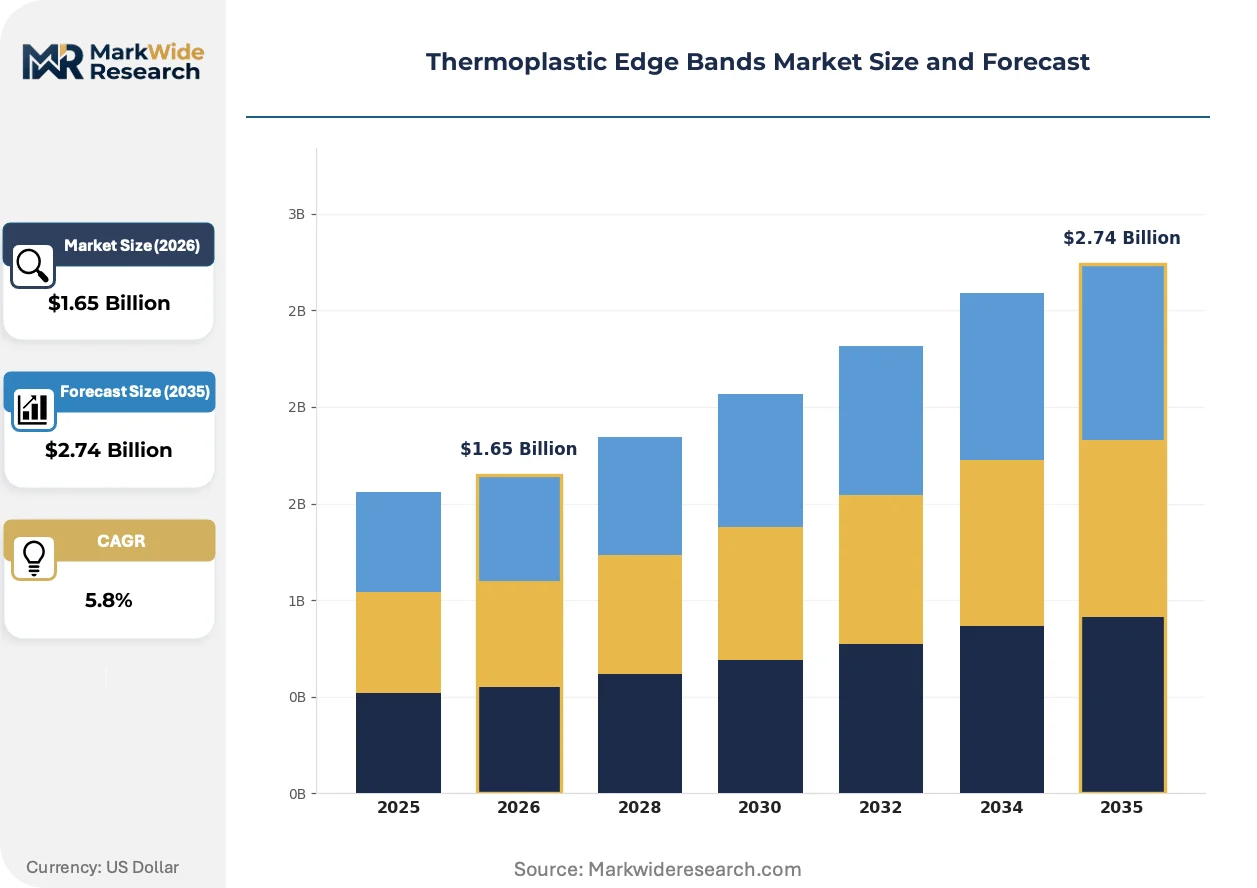
| Market Size in 2026 | $1.65 Billion |
| Market Size in 2035 | $2.74 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Edges, Flexible Edges, PVC Edges, ABS Edges Application: Furniture, Cabinets, Fixtures, Flooring Technology: Injection Molding, Extrusion, Thermoforming, Lamination End User: Manufacturers, Retailers, Distributors, Contractors |
| Companies Covered | Surteco Group SE, Fritz EGGER, REHAU Group, Teknaform Inc., MKT, Tece Dekor A.S., Scanwolf, Dongguan Huali, Zhejiang Wellscom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thermoplastic Edge Bands Market Trends and Innovations
Material science advances and bonding process automation are compressing traditional specification hierarchies while regulatory pressure on indoor air quality accelerates chemistry transitions across European supply chains.
Laser-activated edge bands with functional polymer layers are absorbing specification share from conventional glue-applied alternatives in German kitchen manufacturing. Premium cabinet producers in Stuttgart and Pforzheim are converting bonding stations to laser fusion systems at rates exceeding equipment supplier forecasts. This technology is absorbing the technical premium previously commanded by PUR adhesive applications while eliminating curing time bottlenecks.
REACH authorization procedures for plasticizer alternatives are extending reformulation timelines for PVC compounders serving mass-market furniture segments. ECHA's 2024 candidate list updates have forced inventory write-downs among distributors holding legacy phthalate-containing stock. Polish panel producers are responding fastest, consolidating purchase orders with suppliers holding valid SCIP database registrations.
Specification authority is migrating from furniture OEMs to panel producers with captive edge band coating capabilities. Surteco Group SE and similar integrated suppliers now set material standards that downstream manufacturers follow, compressing independent edge band distributors in Czech and Austrian markets. This concentration is most visible in Baden-Württemberg, where particleboard-integrated edge solutions command preference premiums over standalone band purchases.
Thermoplastic Edge Bands Market Segmentation
Edge band specification divides sharply between commodity mass-market supply and precision-engineered premium grades. Procurement patterns in Germany's furniture clusters reveal how technical requirements cascade through each segment tier.
Product Type:
Volume concentrates in rigid formulations for flat-panel cabinetry, while premium specification tilts toward flexible and ABS alternatives.
- Flexible Edges:Thermoplastic polymers formulated for 3D thermoforming compatibility enable curved-component fabrication in custom kitchen manufacturing. Polish producers in Lower Silesia are retrofitting lines to capture specification share previously served by Italian imports.
- ABS Edges:Acrylonitrile-butadiene-styrene compounds deliver superior heat resistance and post-consumer recyclability credentials. Germany's Baden-Württemberg furniture cluster now mandates ABS for premium cabinetry lines subject to EU Green Deal carbon accounting.
- Rigid Edges:Standard PVC and polypropylene formulations dominate mass-market particleboard finishing.
- PVC Edges:Legacy phthalate-plasticized recipes face REACH Annex XVII reformulation pressure.
Mature deployment sits with Rigid Edges. Newer deployment is concentrated in ABS Edges.
Application:
Specification authority migrates from finished furniture OEMs toward panel producers with captive coating capabilities.
- Furniture:Residential case goods and seating frames consume the largest volume pools, with German manufacturers consolidating purchase orders around suppliers holding valid SCIP database registrations.
- Cabinets:Kitchen and bath cabinetry drive precision tolerance requirements, with Stuttgart producers converting bonding stations to laser fusion systems.
- Fixtures:Commercial interior installations specify edge bands for display and storage systems.
- Flooring:Luxury vinyl tile transitions represent the application expanding most quickly, with rigid edge bands specified for plank perimeter finishing.
Established specification sits with Furniture. Accelerating specification sits with Flooring.
Technology:
Process selection determines surface finish quality and production throughput economics.
- Extrusion:Continuous profile production dominates volume manufacturing, enabling thickness consistency within sub-0.05mm variance demanded by KBA-influenced quality standards.
- Co-extrusion:Multi-layer construction combines rigid cores with decorative surfaces for premium pricing in high-end cabinetry.
- Injection Molding:Discontinuous production for complex profile geometries.
- Thermoforming:Post-extrusion shaping for curved-edge applications.
- Lamination:Decorative layer bonding for wood-grain aesthetic replication.
Scale concentration sits with Extrusion. Capability investment concentrates in Co-extrusion.
End User:
Procurement decision rights fragment across value chain positions with divergent technical priorities.
- Manufacturers:Furniture and panel producers hold dominant specification authority, with integrated suppliers like Surteco Group SE setting material standards that downstream producers follow.
- Distributors:Inventory holders face working capital pressure from ECHA candidate list updates forcing legacy stock write-downs.
- Retailers:Big-box and specialty channels specify finished goods with certified edge compliance.
- Contractors:Installation specialists source edge solutions for retrofit and repair applications.
Specification control sits with Manufacturers. Inventory risk concentrates in Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Baden-Württemberg's furniture manufacturing tax incentives and Poland's Special Economic Zones for woodworking have concentrated thermoplastic edge band demand in Central European industrial corridors.
Germany
KBA-influenced automotive quality standards now govern furniture sector tolerance specifications for edge band thickness consistency. REACH Annex XVII phthalate restrictions force rapid PVC reformulation across Baden-Württemberg's particleboard-integrated supply chains. Stuttgart and Pforzheim kitchen manufacturers are converting bonding stations to laser fusion systems faster than equipment supplier forecasts anticipated.
Poland
Lower Silesia's woodworking belt drives specification adoption for ABS edges in custom cabinetry as Italian design import substitution accelerates. ECHA's 2024 candidate list updates triggered inventory write-downs among distributors holding legacy phthalate-containing stock. Polish panel producers now consolidate purchase orders exclusively with suppliers holding valid SCIP database registrations.
Italy
Design-driven furniture OEMs in Lombardy and Veneto sustain import demand for premium flexible edges compatible with 3D thermoforming applications. CE marking requirements for construction product regulation extend market entry timelines for flooring edge applications by 8-14 months. The Brianza furniture district maintains specification authority over decorative layer aesthetics despite panel producer consolidation elsewhere.
France
Auvergne-Rhône-Alpes industrial policy supports co-extrusion technology investment for multi-layer edge construction combining rigid cores with decorative surfaces. EMA indoor air quality standards tighten specification windows for low-VOC adhesive compatibility in residential furniture. Île-de-France distribution networks face working capital pressure from regulatory-driven inventory obsolescence cycles.
China
Yangtze River Delta flooring manufacturers specify rigid thermoplastic edge bands for luxury vinyl tile transition applications at rates exceeding furniture sector growth. GB standards for indoor environmental quality and MIIT industrial upgrading guidelines elevate material traceability requirements. Dongguan-based extruders supply thickness-tolerant grades to European importers seeking cost-competitive alternatives to domestic production.
Thermoplastic Edge Bands Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated panel producers capturing specification authority from standalone edge band distributors. The vendor base organizes around three strategic archetypes: polymer compounders with captive extrusion capabilities, decorative surface specialists with coating technology advantages, and diversified materials conglomerates leveraging cross-sector polymer expertise. Capacity expansion and strategic partnerships dominate competitive moves, while M&A activity concentrates among mid-tier compounders seeking SCIP database compliance and certified material traceability.
Among European-integrated suppliers, Surteco Group SE and Fritz EGGER exemplify the shift toward captive edge solutions that compress independent distributor margins. REHAU Group anchors the technical polymer formulation tier, extending automotive-derived PVC expertise into decorative furniture applications. These three companies occupy positions that downstream manufacturers increasingly reference as specification benchmarks rather than purchasing from standalone band suppliers.
| Leading Market Players |
|---|
| Surteco Group SE |
| Fritz EGGER |
| REHAU Group |
| Teknaform Inc. |
| MKT |
| Tece Dekor A.S. |
| Scanwolf |
| Dongguan Huali |
| Zhejiang Wellscom |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap compounders in Germany's Baden-Württemberg region anchor supply discipline through generational capital stability, enabling patient pricing strategies that resist cyclical feedstock volatility while maintaining specification premiums for KBA-influenced tolerance grades.
Pricing Analysis
Short lead-time premiums command substantial markups as Polish custom kitchen manufacturers retrofit for laser fusion bonding ahead of equipment supplier capacity. Pricing stratifies across premium ABS grades with SCIP database registration, standard reformulated PVC meeting REACH Annex XVII, and economy polypropylene for mass-market particleboard. Cost compression in legacy phthalate-plasticized PVC is intensifying because ECHA candidate list updates force inventory write-downs. Big-box retailers exhibit highest price sensitivity, while integrated panel producers with captive coating capabilities absorb specification premiums.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Germany's particleboard-integrated suppliers, while independent distributors serve fragmented custom furniture workshops across Czech and Austrian markets. Manufacturing concentrates in Germany, Poland, and China, with Dongguan-based extruders feeding European importers seeking cost-competitive thickness-tolerant grades. Feedstock draws from acrylonitrile and butadiene supply chains anchored in petrochemical complexes. Single-source vulnerability sits with specialized co-extrusion die technicians trained in wood-grain color-matching. Distribution runs through panel producer procurement departments that now set material standards downstream.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Laser fusion bonding technology is displacing conventional hot-melt adhesive application across European kitchen manufacturing, compressing specification windows for legacy equipment suppliers and recalibrating procurement priorities toward seamless edge compatibility.
For Market Incumbents: Cement specification authority by deepening captive coating capabilities and securing exclusive supply relationships with Baden-Württemberg's particleboard-integrated producers. Prioritize SCIP database registration investment ahead of distributor consolidation, as Polish panel producers now mandate valid registrations for purchase order eligibility. Laser fusion retrofit demand presents capacity expansion opportunity in Lower Silesia. For New Entrants and Emerging Players: Custom furniture workshops in Central Europe's curved-component fabrication segment remain underserved by domestic flexible edge suppliers, creating entry path previously dominated by Italian imports. Target co-extrusion technology licensing partnerships with Auvergne-Rhône-Alpes equipment specialists to bypass technician scarcity constraints. Lead with low-VOC adhesive compatibility certification to capture EMA indoor air quality tightening. For Investors and Strategic Acquirers: ECHA's candidate list update velocity is the leading indicator that material traceability infrastructure will separate acquirable assets from stranded inventory risk. Five-to-ten-year viability favors compounders with certified ABS grades and backward integration into decorative surface coating. Watch for laser fusion equipment supplier order backlogs as demand confirmation signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Decorative Coating | Surteco Group SE's captive technology base anchors specification authority that downstream manufacturers follow. |
| Laser Fusion Production Line Retrofit | Stuttgart kitchen manufacturers convert bonding stations faster than equipment supplier forecasts anticipated. |
| SCIP Database Registration Investment | Polish panel producers consolidate purchase orders exclusively with suppliers holding valid registrations. |
| Co-extrusion Technology Licensing | Auvergne-Rhône-Alpes industrial policy supports multi-layer construction for premium cabinetry pricing. |
| Low-VOC Adhesive Formulation Partnership | EMA indoor air quality standards tighten specification windows for residential furniture certification. |
Research Methodology
Multi-period observation of polymer feedstock price volatility, REACH regulatory amendment timelines, and laser fusion equipment installation rates anchored the trend analysis, supplemented by interviews with extrusion plant managers, procurement leads at German panel producers, distribution channel partners in Czech markets, and technical R&D directors at adhesive suppliers. Secondary validation drew from ECHA candidate list publications, EU Green Deal implementation guidance, customs trade data for thermoplastic edge band imports, and SEC filings of publicly traded coating technology providers. Bottom-up volume modeling triangulated against top-down furniture production forecasts.
Segment-weighting applied product type, application, and technology dimensions across the projection horizon, with flexible edge and ABS grade trajectories modeled separately from rigid PVC mass-market decline. CAGRs derived from elasticity-adjusted demand curves incorporating specification migration patterns. Forecast inputs included KBA-influenced tolerance requirement adoption curves and SCIP database registration penetration rates among European compounders.
Revisions become necessary when ECHA accelerates phthalate restriction timelines, laser fusion equipment capacity constraints ease faster than modeled, or EU Green Deal carbon accounting rules recalibrate Scope 3 reporting thresholds. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Polybenzoxazine Resins Market
Polymers & Resins
US Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market
Polymers & Resins
Canada Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Global Medium Molecular Weight Polyisobutylene Market
Polymers & Resins
Amorphous Polyethylene Terephthalate (APET) Market
Polymers & Resins
India Polymer Emulsion Market
Polymers & Resins
Global HBPA Epoxy Resin Market
Polymers & Resins
Global Polymer Stabilizer Market
Polymers & Resins
Bio Based Resin Market
Polymers & Resins
Starch Polymer Market
Polymers & Resins
Polyamide 12 Market
Polymers & Resins
Polyglycerol Polyricinoleate Market
Polymers & Resins
Green Polyols Market
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
Polybutylene Succinate (PBS) Market