
 Compressed Air Pipe Market | 2026-2036
Compressed Air Pipe Market Size, Share, and Industry Trends Forecast 2026-2036
Compressed Air Pipe Market Insights
The capital-intensity divergence between integrated system providers and component suppliers is unwinding competitive dynamics across the compressed air pipe landscape. Atlas Copco (Airnet) leverages its captive compressor installed base to anchor bundled piping retrofit contracts in European manufacturing hubs. Parker Hannifin (Transair) differentiates through push-fit aluminum systems that sustain premium positioning in food-safe and cleanroom environments. Prevost competes on quick-connect modularity, extending its footprint in automotive maintenance bays where reconfiguration speed commands pricing power.
Compressed air pipes are pressure-rated conduits, typically fabricated from aluminum, stainless steel, or engineered composites, designed to transport compressed air at operating pressures commonly ranging from 90 to 150 psi across industrial distribution networks. Their primary purpose is to deliver consistent, leak-minimized airflow from compressor stations to pneumatic tools, automation actuators, and process equipment while minimizing pressure drop and energy waste. Aluminum pipes now lead product type momentum due to their corrosion immunity and lighter install burden, whereas steel pipes occupy mature replacement cycles in heavy machinery environments where mechanical robustness outweighs efficiency gains. Push-fit and quick-connect technologies are capturing the fastest growth by slashing installation labor and enabling future line reconfigurations without cutting or welding.
OSHA standards governing workplace compressed air exposure limits, coupled with FDA food-contact surface requirements and EU machinery directives mandating pressure equipment safety, collectively elevate material certification and traceability burdens for pipe suppliers. REACH compliance across European supply chains further restricts certain coating chemistries, pushing manufacturers toward bare aluminum and nickel-plated alternatives. Stakeholders must monitor how evolving energy-efficiency labeling regimes and carbon-border adjustments reshape material selection criteria and supplier qualification timelines.
Market Dynamics
Aluminum pipe systems are decomposing the legacy steel-installed base across European manufacturing, driven by Industrie 4.0 retrofit mandates that penalize energy losses from corrosion-induced pressure drops. This material transition is compressing replacement cycles and rewiring supplier-customer relationships around lifecycle efficiency guarantees rather than upfront capital cost.
Growth Catalysts
- REACH compliance deadlines:European coating chemistry restrictions are accelerating bare aluminum and nickel-plated pipe adoption as factories preempt regulatory non-compliance in compressed air distribution networks.
- Automotive OEM paint shop expansion:New assembly line investments in Germany and Spain are specifying modular aluminum piping with integrated leak detection to meet compressed air quality standards for robotic spraying operations.
- Push-fit connection technology:Mechanical joining systems are slashing installation labor hours by eliminating welding certification requirements, enabling faster line reconfigurations in contract manufacturing environments.
Market Restraints
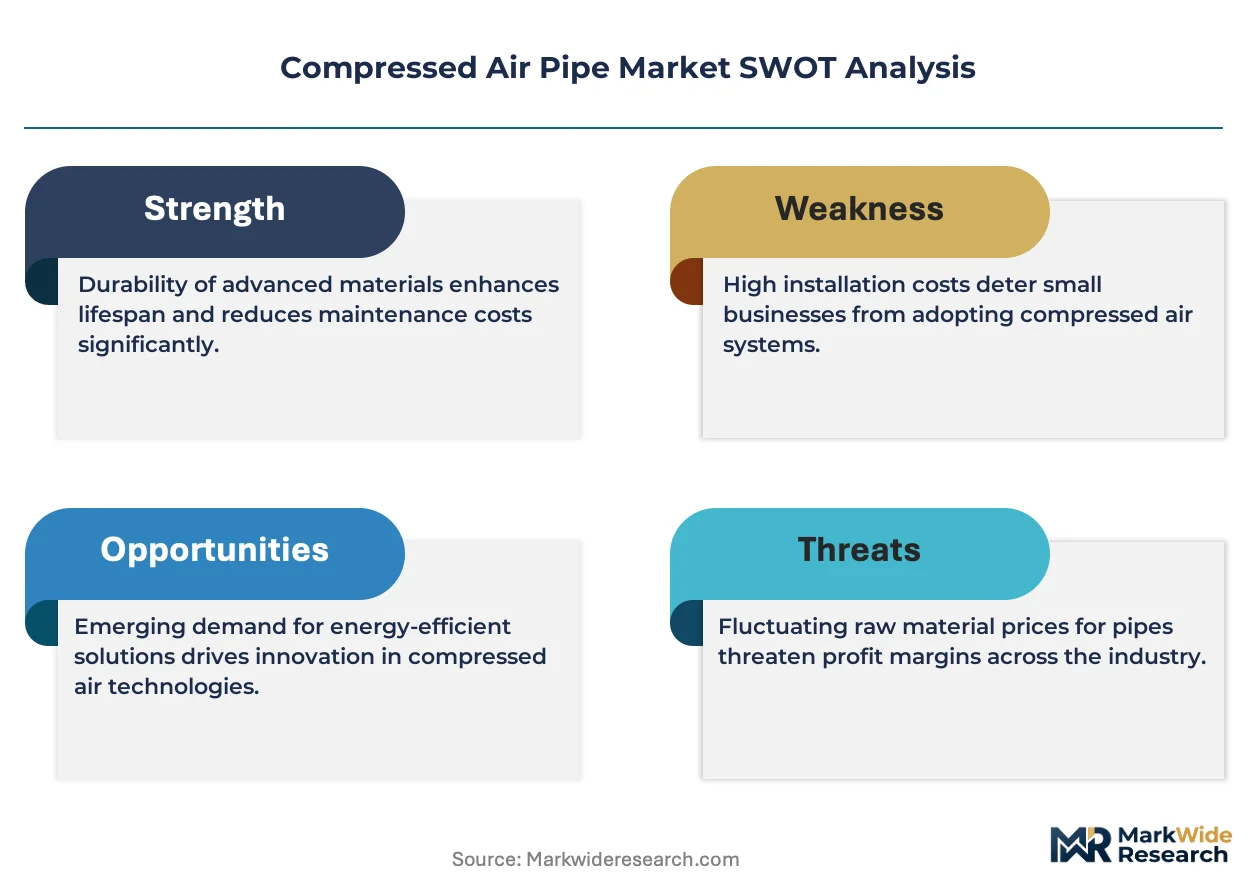
- Primary aluminum price volatility:LME aluminum fluctuations are compressing margins for pipe fabricators unable to pass through material cost swings to long-term infrastructure contracts.
- Welding skill scarcity:Legacy steel system maintenance depends on certified pressure welders whose training pipelines have constricted across Central European industrial regions.
- Stainless steel substitution in corrosive environments:Chemical processing and coastal facilities continue specifying 316L stainless for salt-fog resistance, capping aluminum penetration in high-chloride applications.
Strategic Opportunities
- Polish and Czech manufacturing corridors:Greenfield automotive component plants in these markets lack installed compressed air infrastructure, creating first-mover positioning for modular system providers.
- EU carbon border adjustment mechanism:Embodied carbon tracking in imported steel pipes is creating preference windows for domestically produced aluminum with verified low-carbon smelting credentials.
- IIoT sensor integration:Pressure and flow monitoring hardware embedded at pipe joints is converging with predictive maintenance platforms, opening recurring revenue streams beyond hardware supply.
Industry Challenges
- Pressure Equipment Directive certification timelines:Module H full quality assurance approvals for new aluminum alloy grades are stretching 14-18 months, delaying product launches.
- Legacy steel-to-aluminum interface engineering:Mixed-material retrofits require bespoke flange adapters and galvanic isolation solutions that complicate project execution and warranty liability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Compressed Air Pipe Market |
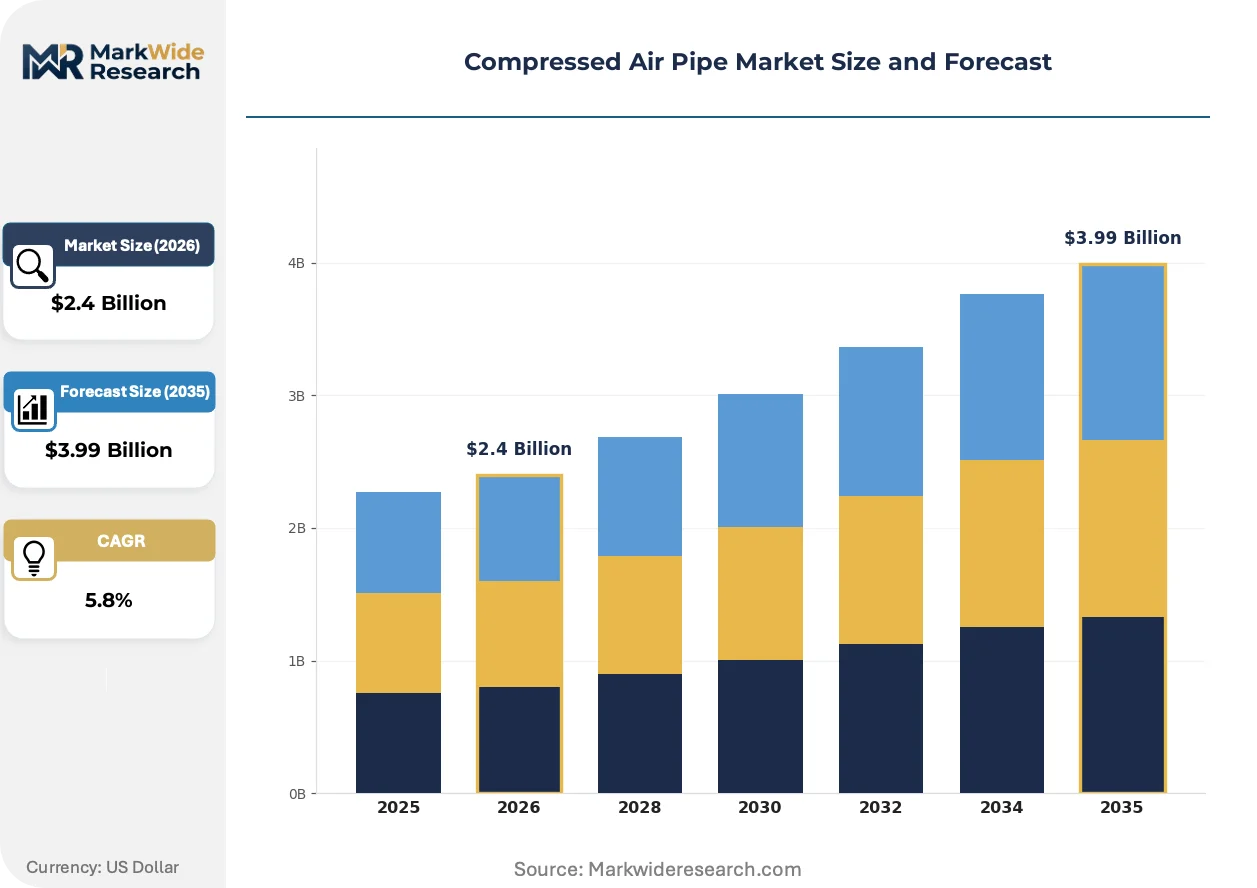
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Pipes, Aluminum Pipes, Copper Tubes, PVC Pipes, Composite Pipes Technology: Threaded, Welded, Flanged, Push-Fit, Clamped, Quick Connect Application: Manufacturing Plants, Food Processing, Chemical Processing, Pharmaceuticals, Textile Production, Electronics Assembly End User Industry: Automotive OEMs, Aerospace Units, Construction Firms, Heavy Machinery Makers, Packaging Companies |
| Companies Covered | John Guest U.S.A., Inc., Atlas Copco (Airnet), Teseo Srl, Unipipe Solutions, Prevost, Masterflex Group, Parker Hannifin (Transair), RapidAir Products, Waircom MBS Corporation Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Compressed Air Pipe Market Trends and Innovations
Compressed air distribution is undergoing a structural shift from passive conduit infrastructure to active energy management systems. Three interconnected developments are redefining how industrial buyers specify, install, and monetize piping networks.
Smart pipe systems with embedded pressure and temperature sensing are decomposing the traditional separation between mechanical distribution and process control. Automotive tier-one suppliers in Stuttgart and Wolfsburg are specifying these instrumented lines for real-time leak detection. The technology is compressing maintenance response times from scheduled inspections to automated alerts, rewiring supplier value propositions around uptime guarantees.
OSHA's updated workplace compressed air exposure limits are tightening material traceability requirements for pipes in food-contact and pharmaceutical cleanroom environments. FDA-aligned facilities must now document alloy composition and surface finish certification across entire distribution networks. Food-safe processors in Wisconsin and Pennsylvania are responding by mandating mill-test reports for every pipe section, elevating documentation burdens for distributors.
Buyer purchasing patterns are fragmenting from centralized engineering-procurement-construction contracts toward direct relationships between plant maintenance teams and specialized piping subcontractors. This disintermediation is compressing distributor margins while rewarding technical specialists who can deliver rapid line reconfigurations. The shift is most pronounced in German automotive supplier parks where just-in-sequence production demands frequent compressed air layout changes.
Compressed Air Pipe Market Segmentation
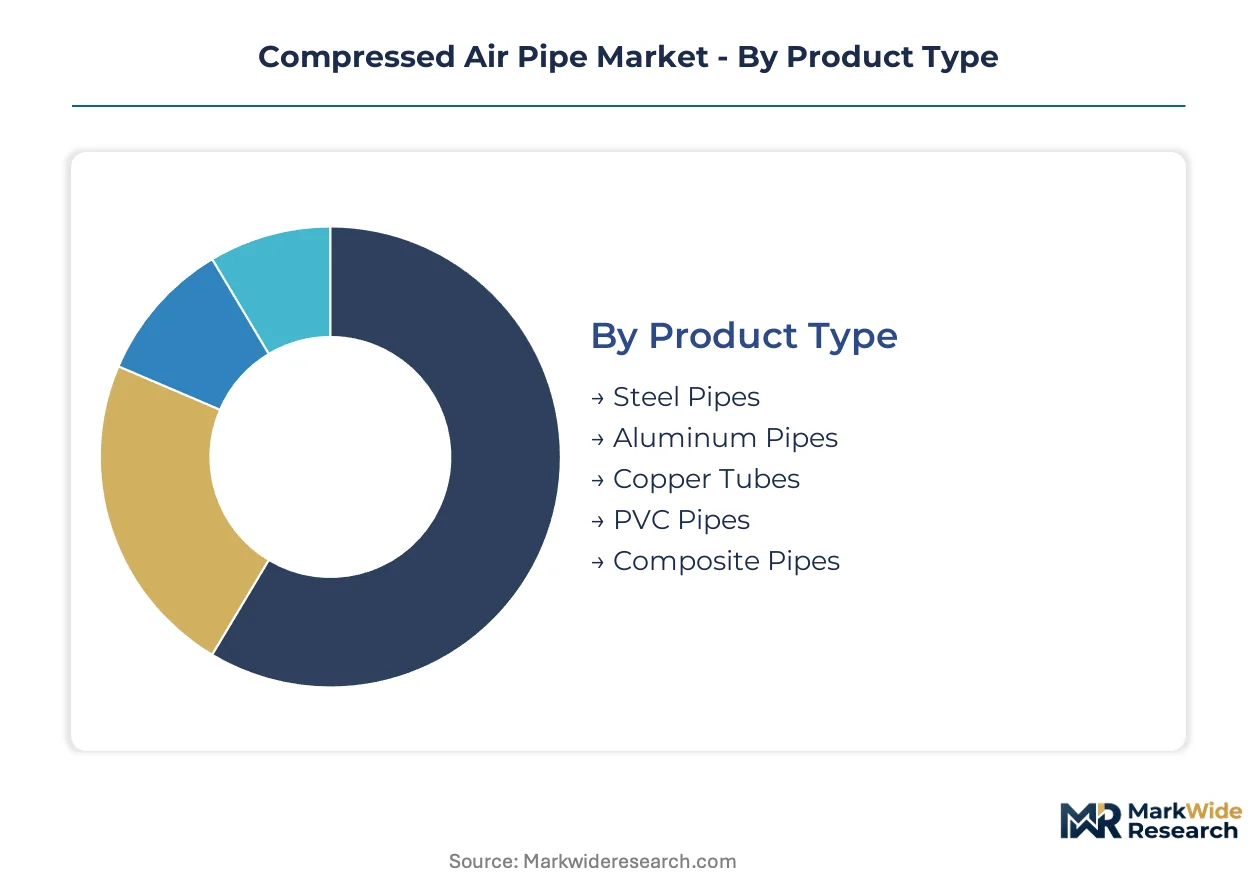
Compressed air pipe segmentation reveals how material selection and joining technology determine channel economics. Distribution patterns diverge sharply between legacy infrastructure retrofits and greenfield modular installations.
Product Type:
Channel flows split between distributor-heavy steel replacement cycles and direct-contract aluminum system rollouts. Steel pipes move through industrial supply houses serving maintenance departments, while aluminum networks bypass distributors for engineered system contracts.
- Steel Pipes:Fabricated from carbon steel or galvanized alloys with wall thicknesses rated for 150-200 psi operating pressures. German heavy machinery makers in the Ruhr region specify these for mechanical durability in high-vibration forging environments where corrosion management is secondary to structural integrity.
- Aluminum Pipes:Extruded 6063-T5 or 6060-T6 alloys with anodized surfaces delivering corrosion immunity and 40% weight reduction versus steel. Automotive OEM paint shops in Stuttgart and Wolfsburg mandate these for leak-resistant modular networks that cut energy losses from pressure drop.
- Copper Tubes:Seamless drawn copper for instrument air and laboratory applications requiring thermal conductivity and bacterial resistance.
- PVC Pipes:Schedule 80 thermoplastic for light-duty shop air in woodworking and non-critical pneumatic tool feeds.
- Composite Pipes:Reinforced polymer-metallic hybrids targeting mobile compressor skids and temporary construction air distribution.
Steel pipes dominate installed base. Aluminum pipes are where expansion concentrates.
Technology:
Installation labor cost tiers separate legacy welded systems from mechanical joining methods. Certified welder scarcity is pushing specification committees toward push-fit alternatives that eliminate hot-work permits and inspection delays.
- Threaded:Tapered NPT or BSPT connections requiring pipe sealant and torque-controlled assembly. Mature replacement demand in US Midwest manufacturing plants with existing threaded infrastructure.
- Welded:TIG or MIG fusion joining for high-pressure stainless steel networks in chemical processing. Scarcity of ASME Section IX certified welders in Czech industrial corridors is extending project timelines and inflating contract pricing.
- Flanged:Bolted ring-joint assemblies for large-diameter mains and isolation valve integration.
- Push-Fit:O-ring sealed mechanical couplings enabling tool-free assembly. Food processing facilities in Wisconsin specify Parker Transair systems for rapid line reconfiguration without production shutdowns.
- Clamped:Grooved-end mechanical couplings for seismic-resistant installations in Pacific Coast jurisdictions.
- Quick Connect:Modular drop-line fittings supporting frequent tool repositioning in automotive maintenance bays and contract manufacturing cells.
Welded systems anchor high-pressure chemical infrastructure. Push-fit methods are climbing the fastest in food-safe and cleanroom specifications.
Application:
Air quality grades and contamination risk stratify end-use specifications. Oil-free compressor integration requirements in food and pharmaceutical segments command premium material certification and documentation burdens.
- Manufacturing Plants:General-purpose pneumatic power for tooling, clamping, and automation actuators. Polish automotive component plants specify modular aluminum for flexible line reconfiguration.
- Food Processing:Oil-free air distribution with FDA-compliant surface finishes. USDA-inspected meatpacking facilities in Pennsylvania mandate mill-test reports and alloy traceability for every pipe section.
- Chemical Processing:Corrosion-resistant 316L stainless networks for chlorine and acid environments. Coastal facilities specify these for salt-fog resistance that aluminum cannot match.
- Pharmaceuticals:ISO 8573-1 Class 0 compressed air for sterile manufacturing. EU GMP Annex 1 compliance drives specification toward electropolished stainless with full material certification.
- Textile Production:Humidity-controlled air jets for weaving and spinning operations.
- Electronics Assembly:Desiccant-dried air for SMT pick-and-place equipment and cleanroom pneumatic controls.
Manufacturing plants represent volume concentration. Food processing and pharmaceuticals are where margin expansion concentrates.
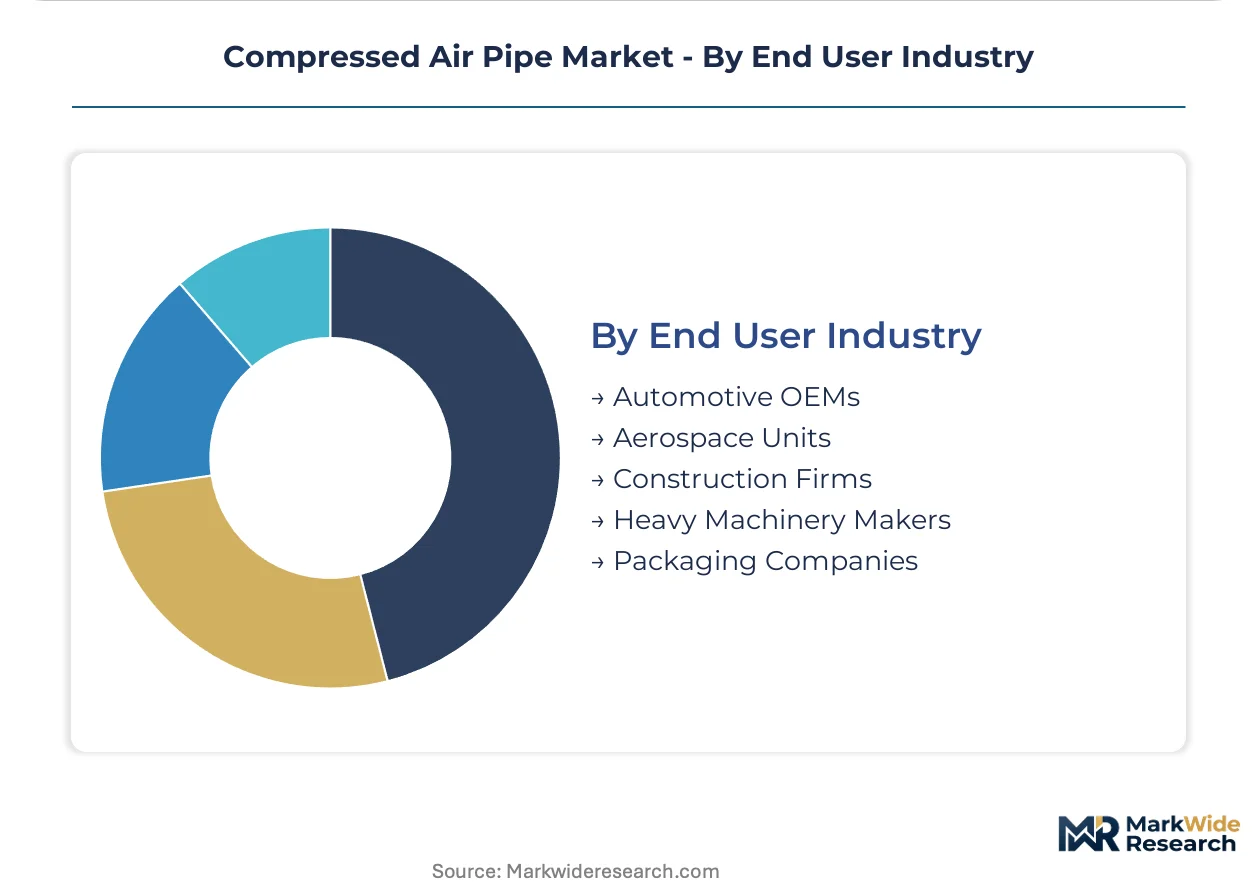
End User Industry:
Capital expenditure cycles and compressed air quality requirements fragment procurement patterns. Automotive OEMs bundle piping with compressor fleet renewals, while construction firms rent temporary distribution skids.
- Automotive OEMs:High-volume robotic spraying and assembly line pneumatic networks. BMW Group Leipzig and Mercedes-Benz Sindelfingen specify instrumented aluminum piping with integrated leak detection for paint shop quality compliance.
- Aerospace Units:Precision-machined titanium and composite components requiring oil-free air for contamination-sensitive finishing operations.
- Construction Firms:Mobile compressor-fed distribution for pneumatic tools and shotcrete application.
- Heavy Machinery Makers:High-pressure forging and casting pneumatic controls. Caterpillar and Komatsu facilities in Illinois and Japan specify thick-wall steel for mechanical shock resistance.
- Packaging Companies:Conveyor actuation and forming pneumatic systems with moderate pressure requirements.
Automotive OEMs anchor engineered system revenue. Heavy machinery sustains steel pipe replacement demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Poland and the Czech Republic display acute price sensitivity on greenfield installations, while German automotive OEMs absorb premium aluminum system costs for energy-efficiency guarantees. This elasticity divergence fragments supplier pricing power across European manufacturing corridors.
Germany
Industrie 4.0 retrofit programs mandate leak-resistant modular piping networks in automotive paint shops. REACH compliance deadlines accelerate bare aluminum adoption as factories preempt coating chemistry restrictions. Stuttgart and Wolfsburg clusters specify instrumented aluminum systems with integrated leak detection for robotic spraying operations.
Poland
Greenfield automotive component plants lack installed compressed air infrastructure, creating first-mover positioning opportunities. EU carbon border adjustment mechanisms favor domestically sourced aluminum with verified low-carbon smelting credentials. Manufacturing corridors near Wrocław and Poznań attract modular system providers seeking volume expansion.
United States
OSHA workplace compressed air exposure limits tighten material traceability requirements in food-contact environments. FDA-aligned facilities mandate mill-test reports documenting alloy composition across entire distribution networks. Wisconsin and Pennsylvania meatpacking processors drive specification toward certified surface finishes.
Spain
New assembly line investments specify modular aluminum piping to meet compressed air quality standards for robotic operations. ECHA coating chemistry restrictions push manufacturers toward nickel-plated alternatives. Automotive supplier parks in Barcelona and Valencia prioritize rapid line reconfiguration capabilities.
Czech Republic
Scarcity of ASME Section IX certified welders extends project timelines for legacy steel maintenance. Greenfield manufacturing investments bypass distributor channels for direct engineered system contracts. Automotive corridors near Brno and Ostrava concentrate demand for push-fit aluminum networks.
Compressed Air Pipe Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive compressor manufacturers leveraging installed bases to anchor bundled retrofit contracts. Component fabricators compete on modularity and installation speed, while regional distributors face margin compression from disintermediation. Three archetypes dominate: integrated system providers bundling hardware with efficiency guarantees, aluminum specialists pushing corrosion-resistant extrusions, and quick-connect fitting innovators targeting maintenance bay reconfiguration. Consolidation pressure concentrates through strategic partnerships between compressor OEMs and piping fabricators, plus geographic expansion into underpiped Central European manufacturing corridors.
Within the integrated system tier, Atlas Copco (Airnet) and Parker Hannifin (Transair) exemplify divergent competitive positioning. Atlas Copco anchors bundled piping retrofit contracts through its captive compressor installed base across European manufacturing hubs. Parker Hannifin occupies premium positioning in food-safe and cleanroom environments through push-fit aluminum systems that sustain technical differentiation. Prevost represents the quick-connect modularity archetype, with its footprint extending into automotive maintenance bays where reconfiguration speed commands pricing power. These three patterns illustrate how technology specialization and channel control determine margin capture across market segments.
| Leading Market Players |
|---|
| John Guest U.S.A., Inc. |
| Atlas Copco (Airnet) |
| Teseo Srl |
| Unipipe Solutions |
| Prevost |
| Masterflex Group |
| Parker Hannifin (Transair) |
| RapidAir Products |
| Waircom MBS Corporation Inc. |
| Others |
Pricing and Supply Chain Analysis
Aluminum's displacement of legacy steel in European factory retrofits simultaneously redraws sourcing maps around low-carbon smelting credentials and compresses pricing power toward lifecycle efficiency guarantees rather than capital cost competition. This substitution dynamic concentrates margin capture with integrated system providers while fragmenting component suppliers across divergent material certification tiers.
Pricing Analysis
Service contracts and predictive maintenance subscriptions now drive lifetime value capture beyond hardware margins. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and installation speed, with food-safe and cleanroom specifications commanding substantial premiums over general manufacturing tiers. Cost compression in standard-grade aluminum piping is intensifying because Polish and Czech greenfield buyers wield acute price leverage against undifferentiated distributors. Automotive OEMs in Stuttgart and Wolfsburg clusters display lowest price sensitivity, absorbing premium positioning for instrumented systems with integrated leak detection and energy-efficiency warranties.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes and Red Sea routing disruptions are elevating inbound logistics costs for nickel-plated fittings and specialized O-ring compounds. Primary aluminum supply concentrates in China, Russia, and the Gulf states, with European fabricators increasingly sourcing from domestic smelters with verified low-carbon credentials to satisfy EU carbon border adjustment documentation. The supply chain rests on bauxite refining capacity, extrusion-grade alloy availability, and REACH-compliant surface treatment chemistries. Single-source vulnerability in certified nickel plating for food-contact applications threatens delivery timelines for FDA-aligned facilities. Distribution runs through direct engineered system contracts for aluminum modular networks, while legacy steel replacement cycles persist through industrial supply houses serving maintenance departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The compressed air pipe market functions as a service-attach opportunity where IIoT sensor integration and predictive maintenance platforms expand recurring revenue faster than commodity hardware sales. This shift rewards suppliers who can bundle uptime guarantees with physical infrastructure.
For Market Incumbents: Consolidate position by deepening backward integration into low-carbon aluminum extrusion capacity in Poland and the Czech Republic, securing supply advantages as EU carbon border adjustments tighten. Anchor bundled retrofit contracts through captive compressor installed bases while investing in Pressure Equipment Directive certification pipelines to compress 14-18 month approval timelines for new alloy grades. Defend against quick-connect modularity specialists by embedding proprietary sensor hardware at pipe joints to create switching costs.
For New Entrants and Emerging Players: Differentiate on rapid line reconfiguration speed for automotive supplier parks in Barcelona, Valencia, and Brno where just-in-sequence production demands frequent compressed air layout changes. Target greenfield Polish automotive component plants near Wrocław and Poznań that lack installed infrastructure and display openness to first-mover modular system providers. Pursue direct relationships with plant maintenance teams rather than competing through distributor channels facing margin compression from disintermediation.
For Investors and Strategic Acquirers: The market sits at a material transition phase that favors aluminum specialists with established low-carbon supply chains and certified food-safe product lines. Over the medium-term horizon, viability accrues to providers who can bridge hardware supply with recurring software-enabled maintenance revenue. Acquisition targets should display embedded sensor integration capabilities and established OEM relationships in German automotive clusters. Monitor EU carbon border adjustment implementation timelines as the critical inflection signal for domestic aluminum sourcing premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Low-Carbon Aluminum Smelting | Secures supply advantages under EU carbon border adjustment mechanisms for Polish and Czech manufacturing corridors. |
| IIoT Sensor Integration at Pipe Joints | Opens predictive maintenance subscriptions beyond hardware margins for Stuttgart and Wolfsburg automotive OEMs. |
| Pressure Equipment Directive Certification Investment | Compresses 14-18 month approval timelines that currently delay new alloy grade launches. |
| Direct Maintenance Team Channel Development | Bypasses distributor margin compression from disintermediation in German automotive supplier parks. |
| Quick-Connect Modularity Patent Expansion | Extends footprint in automotive maintenance bays where reconfiguration speed commands pricing power. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant engineers, maintenance directors at automotive OEMs, OEM procurement teams specifying compressed air infrastructure, and aftermarket service heads managing legacy steel system retrofits. Secondary validation drew from SEC 10-K filings of integrated equipment providers, customs and trade data tracking aluminum pipe imports, EU ECHA regulatory databases documenting REACH compliance timelines, and automotive production databases tracking paint shop investments. Bottom-up sizing of installed base replacement cycles and top-down cross-checks against capital expenditure disclosures were triangulated to anchor volume estimates.
Across the projection horizon, the analytical framework modeled demand through four segmentation dimensions: material type capturing aluminum versus steel substitution dynamics, joining technology tracking push-fit adoption velocity, application stratifying food-safe and pharmaceutical cleanroom requirements, and end-user industry isolating automotive OEM bundling patterns from heavy machinery replacement cycles. CAGRs were derived from regression analysis of historical capital expenditure correlations with manufacturing output indices, adjusted for regulatory acceleration effects from EU carbon border adjustments and OSHA exposure limit updates. Industry-specific forecast inputs included Industrie 4.0 retrofit program commitments and certified welder scarcity indices across Central European industrial regions.
Material uncertainties — primary aluminum price volatility on the LME, REACH compliance deadline accelerations, and ASME Section IX welder training pipeline constraints — sit outside the modeled envelope and could compress or extend replacement cycle timing. Forecasts reflect documented assumptions about regulatory implementation schedules and carbon border adjustment scope definitions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pipes and Tubes
PVDF Pipes Market
Pipes and Tubes
Steel Pipes and Tubes Market
Pipes and Tubes
GCC PVC Pipes Market
Pipes and Tubes
Pneumatic Fittings Market
Pipes and Tubes
Pipe and Tube Cutters Market
Pipes and Tubes
Pipeline Processing and Pipeline Services Market
Pipes and Tubes
Pipe Market
Pipes and Tubes
ESR Tubes Market
Pipes and Tubes
Weld Overlay Process Clad Pipes Market
Pipes and Tubes
Global Cured-In-Place Pipe Market
Pipes and Tubes
Global CPVC Pipes and Fittings Market
Pipes and Tubes
Coiled Tubing Manufacturing Market
Pipes and Tubes
OCTG Pipe Market
Pipes and Tubes
Fttx Pipes Market
Pipes and Tubes
Steel Roll-On Tube Market
Pipes and Tubes
Aluminium Tubes for OPC Drum Market