
 Powdered Soft Drinks Market | 2026-2036
Powdered Soft Drinks Market Size, Share, and Industry Trends Forecast 2026-2036
Powdered Soft Drinks Market Outlook
E-commerce and direct-to-pantry subscription channels is rewriting how powdered soft drinks reach households. Nestlé S.A. leverages its Nesquik and Milo distribution infrastructure to dominate pantry-stocking occasions in emerging markets. PepsiCo Inc. sustains a competitive edge through Gatorade powder's grip on athletic and institutional channels. Unilever PLC anchors its position with Lipton iced tea mixes that occupy shelf space across multiple retail tiers.
Powdered soft drinks are dry, free-flowing concentrates composed of flavoring agents, sweeteners, acidulants, and functional additives that reconstitute with water to produce beverages; formulations typically achieve shelf stability through low moisture content below five percent and controlled particle size distribution. The primary commercial purpose is to deliver flavor, hydration, or functional benefits at reduced shipping weight and extended ambient storage compared to liquid alternatives. Fruit flavors command the largest volume share as they satisfy broad household palatability requirements across age demographics. Functional mixes represent the fastest-expanding margin pool as consumers seek added electrolytes, vitamins, or botanical extracts in single-serve formats. Sachet packaging concentrates demand in price-sensitive markets where unit affordability overrides bulk purchase incentives.
FDA nutrition labeling requirements and the EU's added-sugar disclosure frameworks are forcing reformulation across major export portfolios, while India's FSSAI fortification guidelines create compliance complexity for functional mix entrants. The USDA school nutrition standards further constrain permissible sugar levels in products targeting institutional channels in the United States. Stakeholders must monitor evolving front-of-pack labeling mandates and decide whether to develop region-specific formulations or pursue harmonized global recipes that satisfy the strictest jurisdiction.
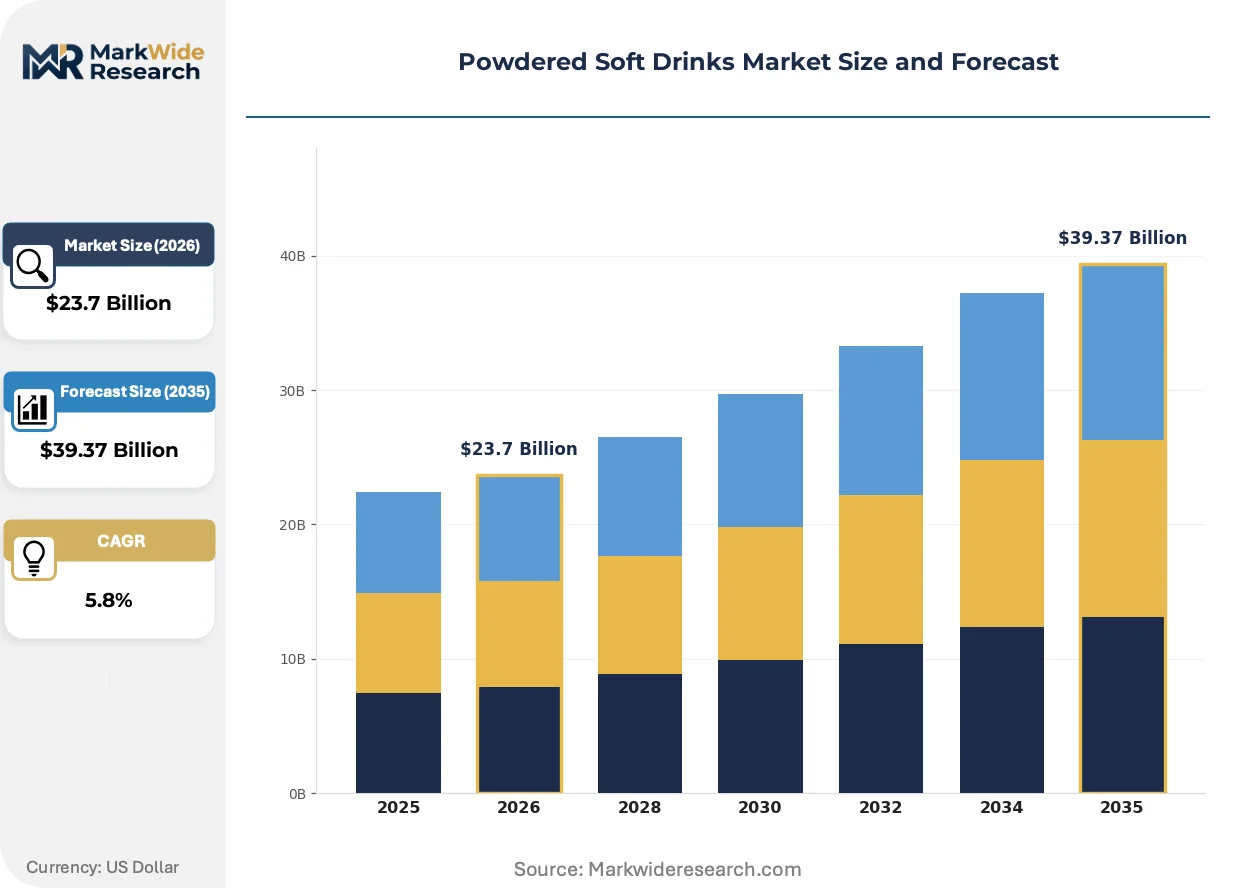
Market Dynamics
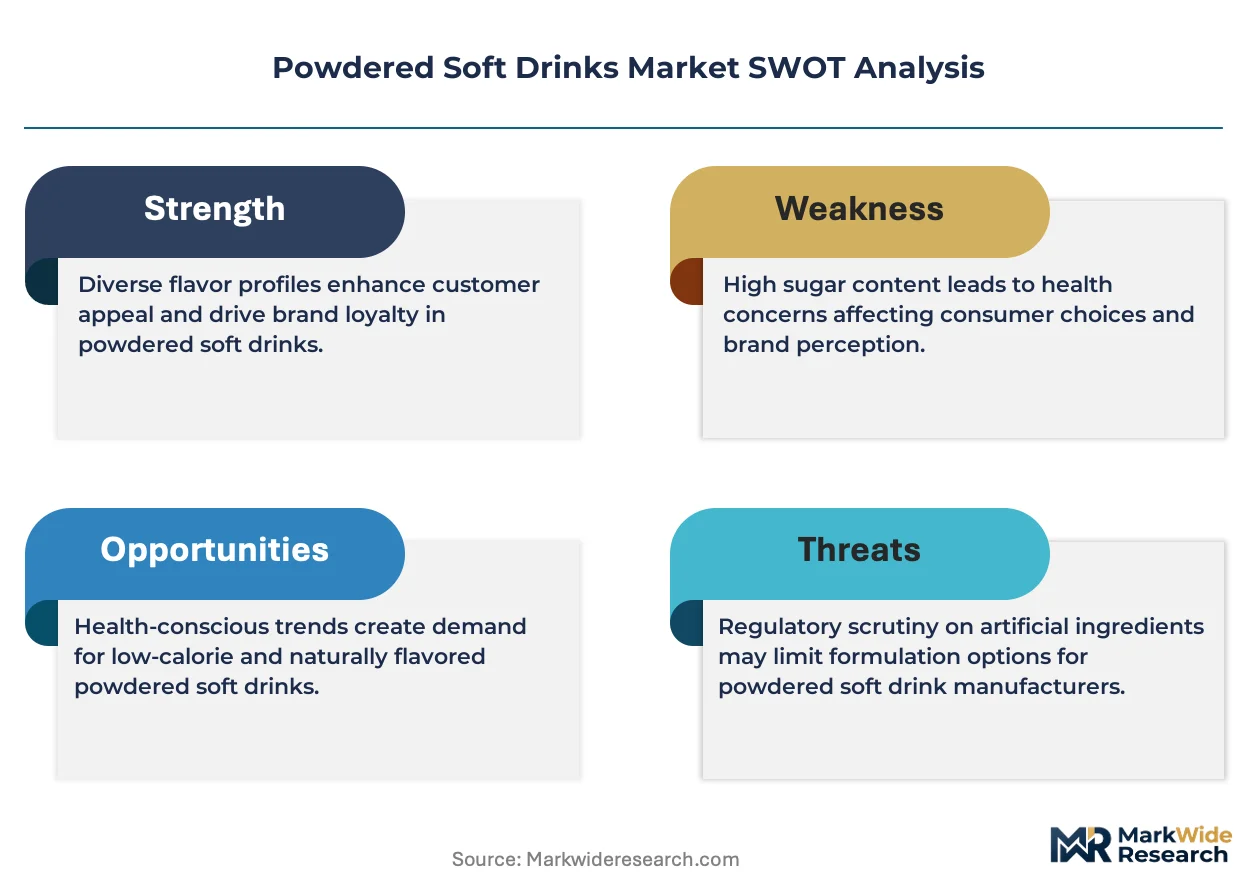
Sugar-reduction mandates from FDA and EU regulators are compressing formulation margins while simultaneously opening premium positioning for functional alternatives. Manufacturers must navigate divergent compliance frameworks or absorb reformulation costs that favor scaled producers with regional recipe flexibility.
Growth Catalysts
- Ambient Storage Economics:Powdered formats eliminate cold-chain dependencies, unlocking distribution into India's rural hinterlands and Southeast Asian archipelagos where refrigeration penetration remains limited. Sachet unit economics align with daily-wage purchasing patterns.
- FSSAI Fortification Guidelines:India's micronutrient mandates for commercial beverages create compliant demand for vitamin-fortified mixes in institutional feeding programs and school nutrition schemes.
- Electrolyte Functionalization:Athletic and occupational hydration segments are pulling single-serve electrolyte powders into convenience retail, displacing bottled sports drinks in gym and construction-site channels.
Market Restraints
- Input Cost Volatility:Crystalline fructose and citric acid prices fluctuate with Brazilian sugar harvests and Chinese citric acid export quotas, squeezing margin predictability for fixed-price contract customers.
- Regulatory Friction:EU added-sugar disclosure requirements and FDA nutrition label updates impose parallel but non-identical reformulation burdens, fragmenting global recipe standardization.
- Ready-to-Drink Substitution:PET-bottled and aseptic-carton beverages in chilled retail are capturing premium household occasions where convenience overrides price sensitivity.
Strategic Opportunities
- Direct-to-Pantry Subscriptions:E-commerce platforms are building recurring revenue streams through personalized flavor curation and auto-replenishment algorithms that bypass traditional retail slotting fees.
- Botanical Functional Convergence:Adaptogen and nootropic ingredient combinations are creating new occasion-based consumption in workplace and wellness segments previously unserved by conventional soft drinks.
- PLI Scheme Alignment:India's production-linked incentive schemes for food processing infrastructure reduce capital intensity for domestic manufacturing scale-up, favoring localized supply over import dependency.
Industry Challenges
- Formulation Talent Scarcity:Food technologists with dual expertise in spray-drying engineering and regulatory compliance across FDA, EFSA, and FSSAI frameworks command premium compensation and limited availability.
- Legacy Equipment Integration:Retrofitting existing dry-mix lines for precision micro-dosing of heat-sensitive vitamins and probiotics requires capital outlays that strain mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powdered Soft Drinks Market |
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $39.37 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fruit Flavors, Herbal Blends, Functional Mixes, Energy Boosters End User: Households, Cafes, Restaurants, Vending Machines Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale Packaging Type: Bulk Packs, Sachets, Pouches, Tubs |
| Companies Covered | Nestlé S.A., The Coca-Cola Company, PepsiCo Inc., Mondelez International Inc., Kraft Heinz Company, Unilever PLC, Keurig Dr Pepper Inc., Cargill Incorporated, Tate & Lyle, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powdered Soft Drinks Market Strategic Shifts
Cold-water instant dissolution technologies and precision micro-encapsulation are collapsing the sensory gap between reconstituted and ready-to-drink products. These advances are redrawing competitive boundaries between powder manufacturers and liquid bottlers.
Spray-dried natural flavor encapsulation using modified starch matrices is rendering obsolete heat-degraded citrus oils that previously required artificial top-noting. Premium household buyers in Japan and South Korea are adopting these clean-label formulations at accelerated rates. The technology is compressing the acceptable ingredient list for mass-market positioning.
EU F-Gas Regulation phase-down schedules are pressuring manufacturers to eliminate hydrofluorocarbon-based cooling in production environments, accelerating investment in ambient-process alternatives. Industrial spray-drying operations face retrofit timelines aligned with 2030 reduction targets. Functional mix producers with existing ambient capabilities are capturing contract manufacturing share from refrigerated-process competitors.
Pantry-stocking behavior has shifted toward bulk-purchase planning triggered by inflation-driven price awareness. Brazilian and Indonesian households are consolidating beverage purchases into monthly cycles through wholesale club and e-commerce bundling. This pattern favors larger-format canisters over single-serve sachets in middle-income urban segments.
Powdered Soft Drinks Market Segmentation
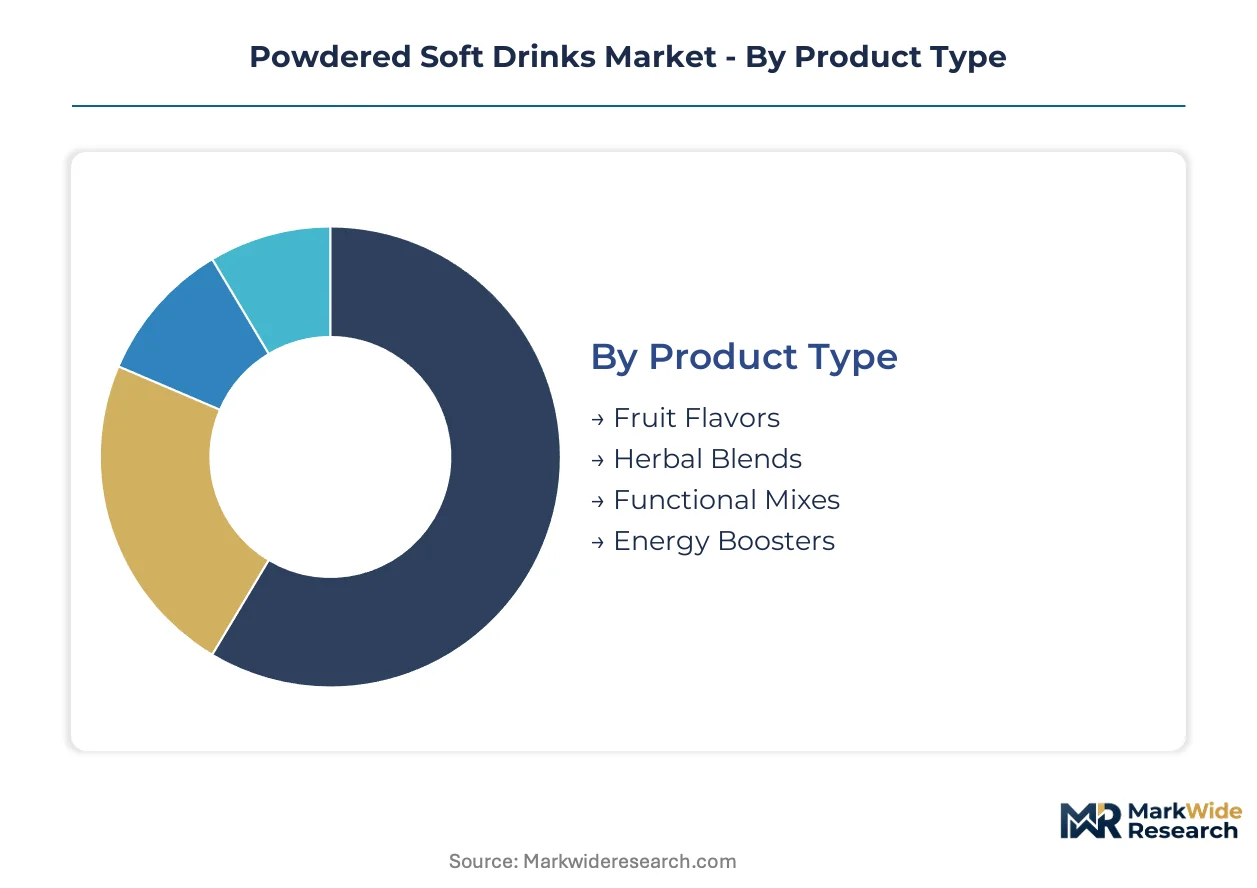
Segmentation in powdered soft drinks reveals how formulation chemistry, occasion-based consumption, and supply chain economics create distinct competitive arenas. Each dimension carries different margin profiles and regulatory exposure.
Product Type:
Cost tier stratification separates mass-market refreshment from premium functional positioning across the formulation spectrum.
- Fruit Flavors:Citrus and berry concentrates rely on spray-dried natural extracts and acidulant balance for shelf-stable palatability. Demand concentrates in Brazilian and Indonesian households where monthly bulk purchasing dominates inflation-adjusted budgeting.
- Functional Mixes:Electrolyte, vitamin, and botanical formulations incorporate heat-sensitive micro-encapsulation for bioactive preservation. Athletic channels in Japan and South Korea are pulling these into convenience retail, displacing bottled alternatives.
- Herbal Blends:Chamomile, hibiscus, and rooibos extracts target wellness occasions with caffeine-free positioning.
- Energy Boosters:Caffeine and taurine combinations serve occupational hydration in construction and logistics sectors across India.
Fruit flavors command the established base. The steepest expansion runs through functional mixes.
End User:
Application context determines formulation specifications, from sugar-reduction mandates in institutional channels to convenience priorities in automated retail.
- Households:Pantry-stocking consumers prioritize canister economics and multi-flavor variety packs for family consumption. Sachet affordability drives penetration in Indian rural markets where daily-wage purchasing patterns prevail.
- Cafes:Quick-service beverage programs favor bulk tubs for syrup-cost reduction and simplified inventory management. Southeast Asian cafe chains are expanding powdered programs to eliminate cold-chain logistics.
- Restaurants:Full-service operators demand consistent batch-to-batch dissolution performance for fountain applications.
- Vending Machines:Automated retail requires instant-dissolve formulations with minimal agitation and ambient storage compatibility.
Households anchor volume concentration. The fastest share gains are emerging through cafe channel conversion.
Distribution Channel:
Customer type and purchase frequency reshape margin capture across physical and digital touchpoints.
- Supermarkets:Shelf-space competition favors established brands with slotting fee capacity and promotional calendar alignment. Brazilian wholesale clubs are consolidating monthly beverage purchases into bundled canister formats.
- Online Retail:Direct-to-pantry subscriptions leverage auto-replenishment algorithms and flavor curation to bypass traditional retail gatekeepers. Indonesian e-commerce platforms are building recurring revenue through bulk bundling.
- Convenience Stores:Impulse-oriented single-serve sachets serve immediate consumption needs in urban transit corridors.
- Wholesale:Institutional buyers negotiate fixed-price contracts with volume commitments for foodservice and hospitality sectors.
Supermarkets retain the volume base. The most rapid channel expansion is occurring through online retail subscription models.
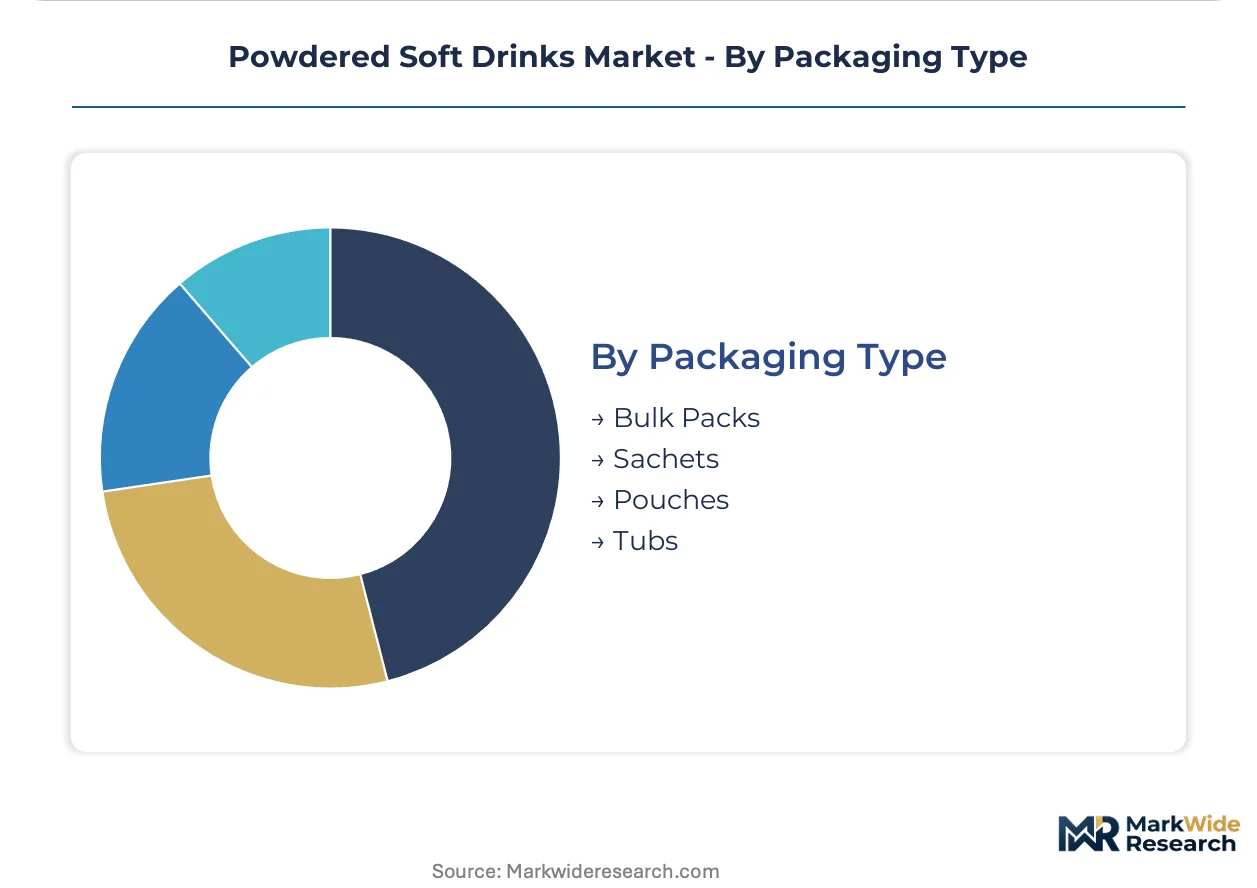
Packaging Type:
Volume scale and unit economics segment demand between individual convenience and household efficiency.
- Sachets:Single-serve foil laminates deliver unit affordability for price-sensitive markets. Daily-wage consumers across India and Southeast Asia favor these for controlled per-occasion spending.
- Bulk Packs:Multi-kilogram institutional formats serve cafe and restaurant fountain systems with minimal per-serving packaging cost.
- Pouches:Flexible stand-up bags bridge household and small commercial use with resealability features.
- Tubs:Rigid canisters with moisture-barrier closures protect hygroscopic formulations in humid climates for pantry storage.
Sachets dominate unit volume. The strongest growth trajectory is shifting toward bulk packs as middle-income households consolidate purchasing cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Singapore anchors Southeast Asian distribution networks for powdered soft drink ingredients, while India's Dedicated Freight Corridors enable cost-competitive inland movement of bulk formulations from coastal processing zones.
United States
Household pantry consolidation and athletic channel demand drive consumption. FDA nutrition labeling updates mandate added-sugar disclosure on front-of-pack formats. Chicago and Dallas-Fort Worth warehouse clusters host major distribution centers for direct-to-pantry subscription fulfillment.
India
Rural sachet affordability and urban bulk purchasing create dual-track demand patterns. FSSAI fortification guidelines for micronutrient-enhanced beverages reshape institutional procurement specifications. The Mumbai-Pune industrial corridor concentrates spray-drying capacity for domestic and export markets.
Brazil
Monthly wholesale club purchasing and inflation-driven price awareness favor larger canister formats. ANVISA labeling requirements align with Mercosur harmonization standards for cross-border trade. São Paulo state hosts the densest concentration of flavor encapsulation facilities serving Latin American markets.
Germany
EU F-Gas Regulation phase-down schedules accelerate ambient-process manufacturing investment. EFSA novel food evaluations create compliance pathways for botanical functional ingredients. The Cologne-Düsseldorf-Ruhr industrial triangle maintains specialized dry-mix contract manufacturing infrastructure.
Japan
Premium clean-label adoption and workplace wellness occasions expand functional mix penetration. METI sustainability guidelines pressure packaging lightweighting and carbon footprint reduction. The Kansai corridor around Osaka retains technical leadership in spray-dried natural flavor encapsulation systems.
Powdered Soft Drinks Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in ingredient and equipment supply. The market structure consolidates around multinational food conglomerates with established beverage distribution infrastructure, while mid-tier regional formulators occupy niche functional segments. Three archetypes dominate: diversified packaged goods platforms with pantry-stocking reach, athletic-focused functional specialists with institutional channel access, and private-label contract manufacturers serving retail brand programs. Competitive moves concentrate on portfolio diversification into sugar-reduced and fortified formulations, plus geographic expansion through localized production under India's PLI schemes.
Among Swiss-diversified food platforms, Nestlé S.A. occupies a position exemplifying pantry-stocking infrastructure leverage in emerging markets. PepsiCo Inc. and Unilever PLC represent contrasting archetypes—the former anchoring athletic and institutional channel presence, the latter spanning multiple retail tiers through tea-focused formulations. These three entities collectively illustrate how scale, channel specialization, and brand architecture determine competitive positioning within the powdered soft drinks segment.
| Leading Market Players |
|---|
| Nestlé S.A. |
| The Coca-Cola Company |
| PepsiCo Inc. |
| Mondelez International Inc. |
| Kraft Heinz Company |
| Unilever PLC |
| Keurig Dr Pepper Inc. |
| Cargill Incorporated |
| Tate & Lyle |
| Others |
Value Chain & Pricing Dynamics
Crystalline fructose price volatility tied to Brazilian sugar harvest cycles compresses margin predictability across both premium functional tiers and economy sachet segments, forcing manufacturers to either absorb input swings through hedging instruments or pass through costs via quarterly contract renegotiations with institutional buyers. This commodity exposure shapes a supply chain that clusters spray-drying capacity near coastal processing zones in India and Southeast Asia to minimize inland logistics exposure.
Pricing Analysis
Volume-discount tiering structures separate premium functional mixes with micro-encapsulated bioactives from standard fruit-flavored formulations and economy sachets for price-sensitive rural markets. Price differentiation rests on fortification certification levels under FSSAI guidelines and cold-chain elimination economics rather than brand premium alone. Cost compression in the economy tier is intensifying because Indian daily-wage consumers consolidate purchases into monthly cycles, eroding per-unit margins. Foodservice institutional buyers exhibit lowest price sensitivity due to syrup-cost reduction calculus, while rural sachet purchasers demonstrate highest elasticity.
Supply Chain Analysis
Tariff exposure between China and major import markets for citric acid concentrates dominates supply chain risk planning for formulation houses dependent on acidulant balance stability. Manufacturing gravity draws from India, Brazil, and Germany for spray-drying infrastructure, flavor encapsulation, and regulatory-compliant processing respectively. Raw material dependencies center on Brazilian crystalline fructose, Chinese citric acid export quotas, and modified starch matrices for natural flavor preservation. Single-source vulnerability in acidulant supply creates procurement contingency requirements. Distribution runs through Port of Singapore anchoring for Southeast Asian archipelago coverage, with India's Dedicated Freight Corridors enabling inland bulk movement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powdered soft drink incumbents face sustained substitution pressure from aseptic-carton and PET-bottled ready-to-drink beverages capturing premium household occasions where convenience overrides price sensitivity. Defense requires building moats that liquid alternatives cannot replicate.
For Market Incumbents: Build regulatory compliance moats through dual certification under FDA nutrition labeling and FSSAI fortification guidelines to lock institutional channel access against emerging regional formulators. Deepen backward integration into spray-drying capacity within India's PLI scheme zones to capture cost advantages over import-dependent competitors. Channel control through direct-to-pantry subscription algorithms creates switching costs that bottled alternatives cannot match. For New Entrants and Emerging Players: Southeast Asian cafe chain conversion from syrup systems presents the most penetrable white-space target, with quick-service beverage programs seeking cold-chain elimination and inventory simplification. Functional mix segments in Japanese workplace wellness channels offer premium positioning with lower slotting fee barriers than mass retail. Go-to-market execution should anchor in contract manufacturing partnerships with existing spray-dry facilities rather than greenfield capacity investment. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down schedules reshaping ambient-process manufacturing investment reshape the acquisition landscape toward targets with existing non-refrigerated production capabilities. Long-term viability frames around 5-10 year windows favor contract manufacturers serving private-label retail programs and functional specialists with botanical ingredient pipelines. Acquisition target archetype: mid-tier regional formulators with FSSAI-compliant portfolios and established cafe channel relationships. Monitor front-of-pack sugar disclosure mandate enforcement timelines as inflection indicator for reformulation demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Spray-Drying Capacity | Captures PLI scheme benefits in India while reducing citric acid tariff exposure. |
| Direct-to-Pantry Subscription Launch | Bypasses supermarket slotting fees through auto-replenishment algorithm deployment. |
| Botanical Functional Line Extension | Targets Japanese workplace wellness occasions with adaptogen and nootropic positioning. |
| FSSAI Fortification Certification Investment | Unlocks institutional procurement under micronutrient mandate compliance. |
| Southeast Asian Cafe Channel Partnership | Converts syrup-based beverage programs to powdered formats eliminating cold-chain logistics. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of customs trade data, FSSAI fortification compliance filings, and Nielsen retail audit records covering powdered beverage categories. Primary interviews engaged formulation technologists, cafe chain procurement directors, and spray-drying equipment specialists across India, Brazil, and Germany. Secondary validation incorporated SEC 10-K segment disclosures, EU F-Gas Regulation implementation timelines, and Brazilian ANVISA labeling harmonization standards. Bottom-up demand modeling triangulated against top-down category value assessments.
Forecast inputs considered product type segmentation across fruit flavors, functional mixes, and energy boosters alongside end-user splits between household pantry-stocking and institutional foodservice channels. Packaging format differentiation by sachet, bulk pack, and canister economics shaped volume-to-value conversion assumptions. CAGRs derived from trend extrapolation of ambient storage adoption rates, sugar-reduction mandate compliance costs, and e-commerce penetration curves across the projection horizon. Industry-specific inputs included spray-drying capacity utilization rates and crystalline fructose futures pricing patterns.
Practitioners should monitor Brazilian sugar harvest forecasts, Chinese citric acid export quota announcements, and FSSAI fortification guideline amendments for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beverages
Probiotic Beverage Market
Beverages
Asia-Pacific Spring Water Market
Beverages
Water Bottle Market
Beverages
Apple Juice Market
Beverages
Breakfast Drink Market
Beverages
Superfood Infused Beverages Market
Beverages
Asia-Pacific Yerba Mate Market
Beverages
Italy Bottled Water Market
Beverages
India Soy Beverages Market
Beverages
United States Beverage Contract Bottling and Filling Market
Beverages
Asia-Pacific Juices Market
Beverages
Apple Cider Vinegar Market
Beverages
Saudi Arabia Retail Bubble Tea Kits Market
Beverages
GCC Sports and Energy Drinks Market
Beverages
Asia-Pacific Vinegar Market
Beverages
Hot Cocoa Mix Market