
 Spain Power Market | 2026-2036
Spain Power Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Power Market Outlook
Spanish renewable generation capacity is broadening across the Iberian Peninsula as developers accelerate onshore wind and photovoltaic deployments. Iberdrola anchors its position through integrated project development and transmission access rights. Acciona Energía leverages its engineering heritage to compete in utility-scale solar tenders. EDP Renováveis specializes in wind portfolio optimization across northern and central provinces.
Spain power encompasses electricity generation, transmission, distribution, and trading across voltage levels from low-voltage residential supply to high-voltage industrial interconnections, with thermal efficiency ratings and grid frequency stabilization as core technical parameters. The renewable segment leads capacity additions driven by competitive auction pricing and land availability, while solar technology within the technology dimension captures the fastest growth trajectory due to declining module costs and high irradiance in southern regions. Conventional thermal generation retains structural importance for grid balancing and peak demand coverage despite declining baseload economics.
Spain's power sector operates under the Ministry for the Ecological Transition, the National Markets and Competition Commission, and EU-wide frameworks including the EU Green Deal and REPowerEU, which mandate renewable targets and carbon border adjustments that reshape investment priorities. The EU Emissions Trading System and national climate legislation enforce decarbonization timelines that constrain new fossil fuel capacity while accelerating permitting for clean energy projects. Stakeholders must monitor regulatory revisions to network tariff structures and storage procurement mandates as these instruments determine project returns and market entry feasibility.
Market Dynamics
Spain's power sector is undergoing a fundamental restructuring as the Ministry for the Ecological Transition accelerates renewable auction schedules and grid access reforms, forcing incumbent thermal operators to reposition around flexibility services rather than baseload generation.
Growth Catalysts
- REPowerEU mandates:The EU Green Deal's renewable targets are compressing permitting timelines for solar and wind projects in Castilla-La Mancha and Aragón, unlocking land-intensive capacity additions.
- Industrial electrification:Steel, cement, and chemical manufacturers are expanding long-term power purchase agreements to meet Scope 2 emissions commitments under CSRD disclosure rules.
- Grid modernization investments:Transmission upgrades along the Cantabrian corridor and Pyrenean interconnections are resolving congestion bottlenecks that previously constrained northern wind exports.
Market Restraints
- Polysilicon and rare earth supply concentration:Spain's solar and wind supply chains remain exposed to processing bottlenecks in China, creating input cost volatility for domestic developers.
- Interconnection capacity limits:The French and Portuguese border transmission corridors operate near technical ceilings, capping export revenue potential for Iberian renewable generators during peak production hours.
- EU ETS carbon price trajectory:Escalating emissions allowance costs are eroding residual load economics for combined-cycle gas turbines without sufficient capacity remuneration mechanisms.
Strategic Opportunities
- Andalusian floating solar:Reservoir-based photovoltaic installations on Guadalquivir basin water bodies offer land-constrained capacity expansion with reduced evaporation losses.
- Green hydrogen offtake integration:The national hydrogen roadmap is creating anchor demand for curtailed renewable generation, enabling merchant solar and wind projects without subsidy dependence.
- Behind-the-meter storage aggregation:Industrial battery deployments across Basque Country automotive plants are opening virtual power plant revenue streams through CNMC-regulated ancillary service markets.
Industry Challenges
- Grid code compliance timelines:New inverter requirements for fault ride-through and synthetic inertia are forcing retrofit capex on operational wind farms commissioned under earlier technical specifications.
- Specialized technician scarcity:High-voltage substation commissioning and offshore cable installation expertise concentrates among aging workforce cohorts, constraining deployment velocity for floating wind pre-commercial arrays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Power Market |
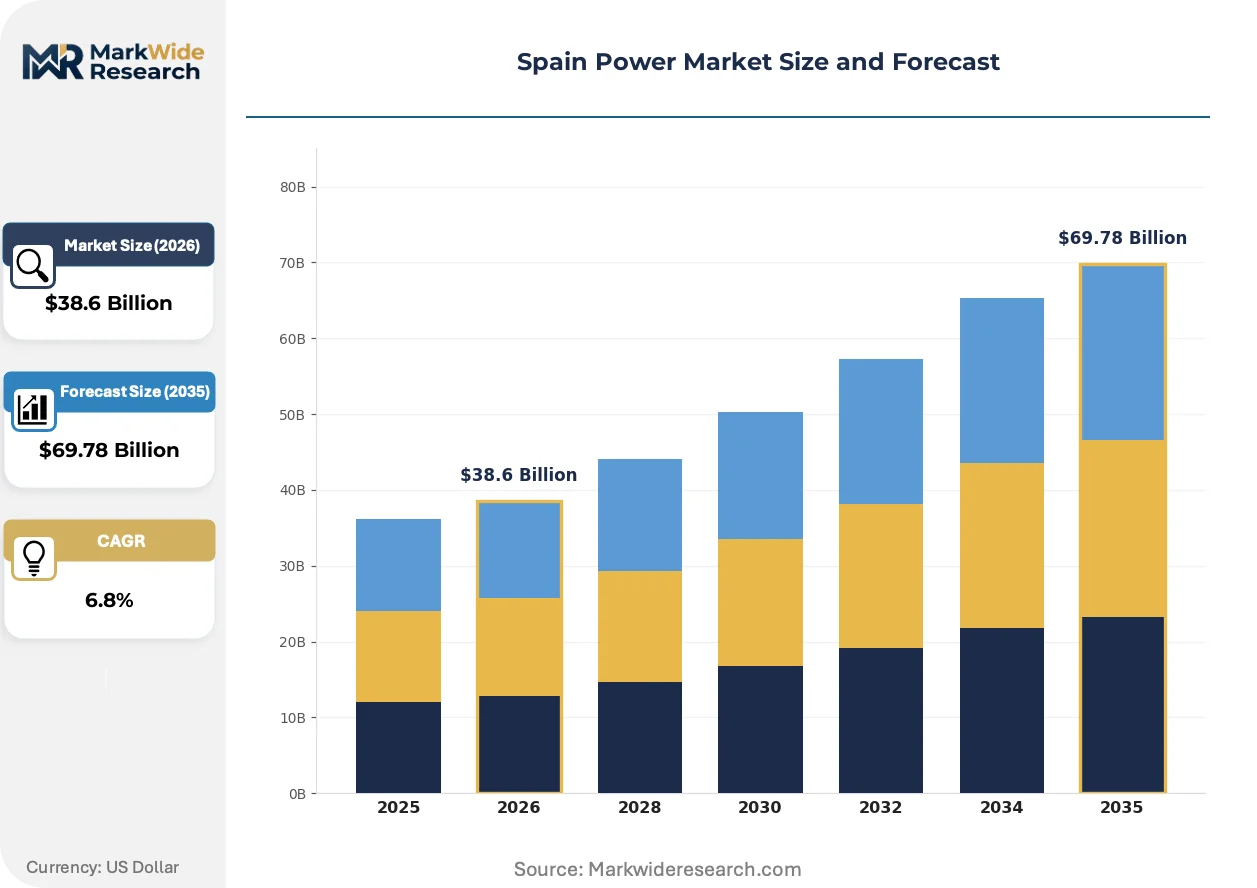
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $69.78 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Renewable, Conventional, Nuclear, Thermal Technology: Wind, Solar, Hydro, Geothermal End User: Residential, Commercial, Industrial, Agricultural Installation: Onshore, Offshore, Distributed, Centralized |
| Companies Covered | EDP Renováveis, Acciona Energía, Iberdrola, Matrix Renewables, Enagás, Endesa, Red Eléctrica Corporación, Solaria Energía y Medio Ambiente, Naturgy Energy Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Power Market Strategic Shifts
Technology convergence and regulatory compression are reshaping competitive positioning across Spain's generation stack, with hardware standardization and digital dispatch optimization emerging as decisive differentiators.
Centralized inverter architectures with integrated power electronics are consolidating market share in utility-scale solar deployments. Iberian developers favor 300kW+ string solutions over distributed alternatives for 500MW+ projects in Extremadura. This consolidation is compressing balance-of-system costs and squeezing mid-tier EPC margins.
EU Green Deal implementation through Spain's National Integrated Energy and Climate Plan is mandating storage co-location requirements in renewable auctions. Developers must now bundle battery capacity with solar or wind bids to qualify for grid access priority. Northern provinces with high wind penetration are responding with lithium-ion configurations sized for two-to-four-hour discharge duration.
Corporate buyers are restructuring electricity sourcing around 24/7 carbon-free matching rather than annual renewable energy certificate aggregation. Data center operators in Madrid and Barcelona are driving this shift, demanding hourly production verification through blockchain-tracked guarantees of origin. This behavioral pivot is most visible among technology sector tenants with Science Based Targets initiative commitments.
Spain Power Market Segmentation
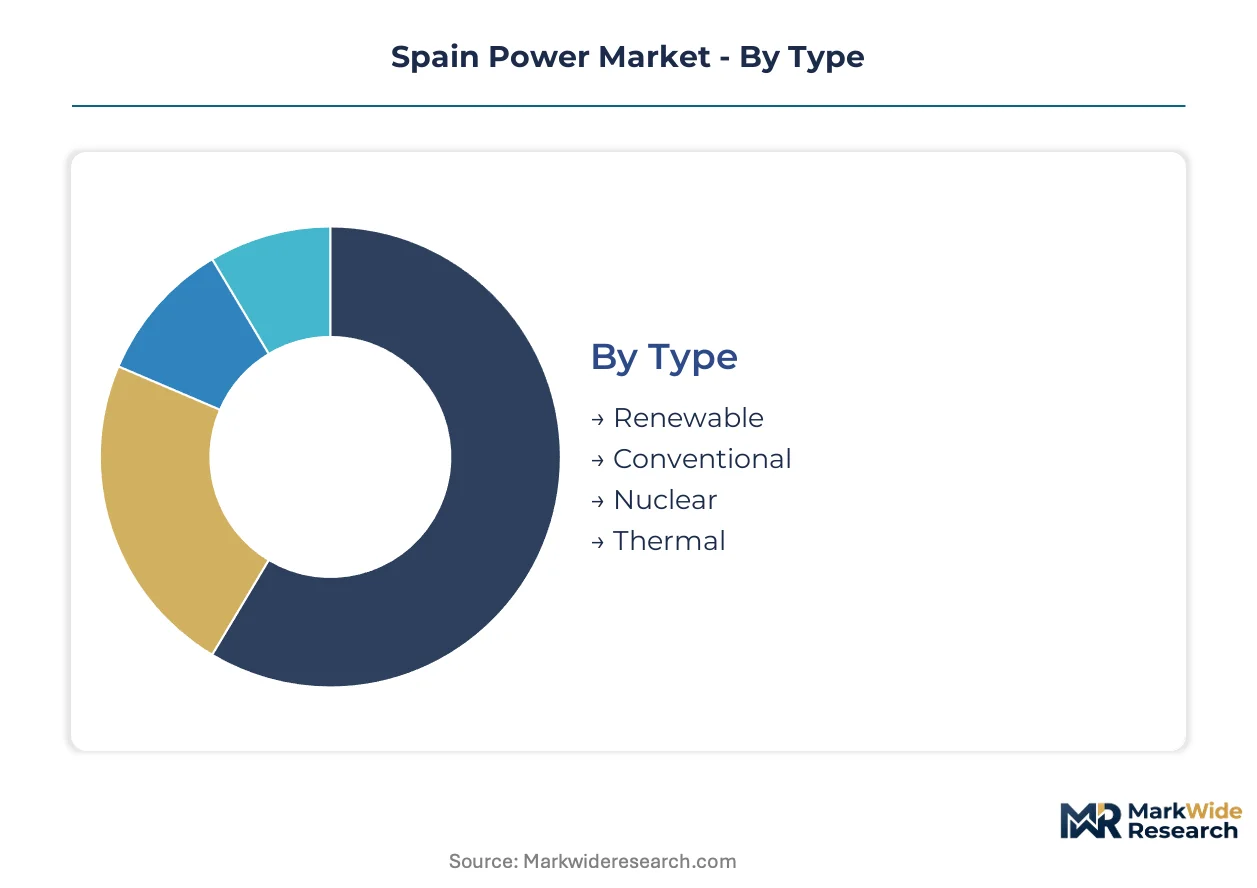
Power procurement patterns in Spain diverge sharply across voltage tiers and consumption profiles, with industrial offtakers driving capacity additions through corporate PPAs while residential segments remain price-sensitive to regulated tariff fluctuations. Understanding these segment boundaries clarifies where grid access rights, storage co-location mandates, and green hydrogen integration create divergent investment returns.
Type:
Industrial buyers prioritize dispatch reliability and carbon intensity disclosure compliance when selecting generation categories for long-term contracting.
- Renewable:Wind and solar assets dominate new capacity auctions under Spain's National Integrated Energy and Climate Plan, with developers bundling battery storage to meet grid access priority requirements. Demand concentrates among data center operators in Madrid and Barcelona seeking 24/7 carbon-free matching for Science Based Targets initiative commitments.
- Conventional:Combined-cycle gas turbines provide ramping flexibility for residual load balancing, though EU ETS carbon price escalation erodes baseload economics without capacity remuneration mechanisms. Cement and steel manufacturers in the Basque Country rely on this dispatchable backup for production continuity during renewable droughts.
- Nuclear:The Almaraz and Trillo facilities supply firm baseload with minimal carbon intensity, constrained by fixed retirement timelines under national decarbonization legislation.
- Thermal:Residual coal and fuel oil generation faces accelerated phase-out under EU Green Deal mandates, relegated to extreme peak demand coverage and grid emergency reserves.
Volume sits with Conventional; growth tilts toward Renewable.
Technology:
Module cost curves and land availability determine technology selection for utility-scale developers bidding into regional auction mechanisms.
- Wind:Onshore turbines in Castilla y León and Aragón benefit from high capacity factors and streamlined environmental permitting, while offshore pre-commercial arrays in the Canary Islands confront specialized technician scarcity for high-voltage cable installation.
- Solar:Photovoltaic deployments capture the steepest expansion trajectory as centralized inverter architectures above 300kW compress balance-of-system costs for 500MW+ projects in Extremadura. Guadalquivir basin floating solar offers land-constrained capacity with evaporation reduction co-benefits.
- Hydro:Pumped storage facilities in the Pyrenees provide synchronous inertia for frequency stabilization, with limited greenfield expansion potential due to protected river basin designations.
- Geothermal:Direct-use applications in volcanic zones of the Canary Islands serve district heating networks, though electricity generation remains marginal due to resource temperature limitations.
Capacity concentrates in Wind; deployment velocity favors Solar.
End User:
Consumption scale and metering infrastructure determine access to wholesale market pricing and behind-the-meter storage aggregation opportunities.
- Residential:Low-voltage supply with limited demand response capability, exposed to regulated tariff volatility under CNMC price-setting mechanisms.
- Commercial:Mid-scale consumers in retail and hospitality sectors pursue solar self-consumption with surplus feed-in to reduce grid dependence.
- Industrial:High-voltage connections enable direct market participation and long-term PPA negotiation for Scope 2 emissions reduction under CSRD disclosure rules.
- Agricultural:Irrigation pumping loads in Andalusia and Murcia align consumption with solar production profiles, reducing peak demand charges.
Revenue pools center on Industrial; participation rates climb fastest in Agricultural.
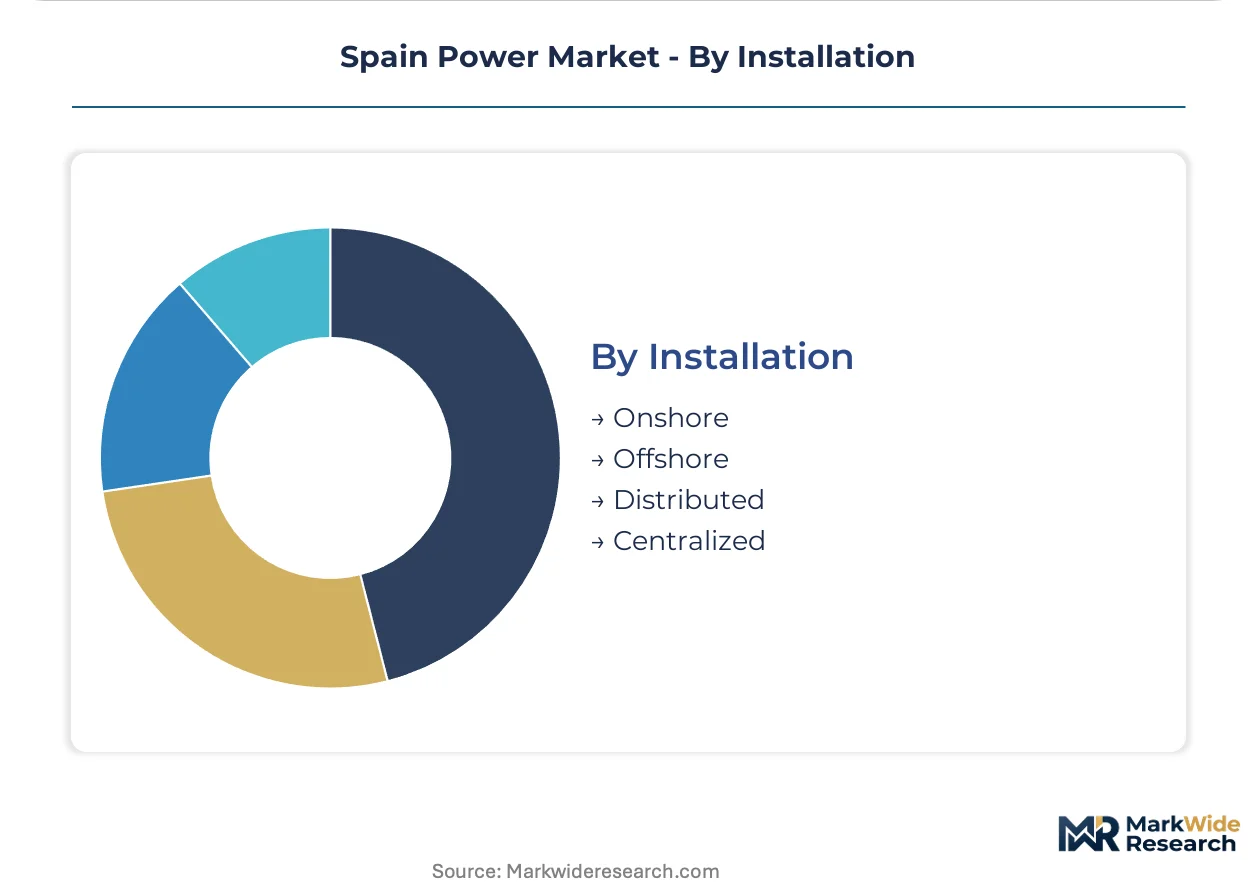
Installation:
Grid connection voltage level and land use constraints shape developer capital allocation between distributed and utility-scale project configurations.
- Onshore:Terrestrial wind and solar farms in Castilla-La Mancha leverage existing transmission corridors with available grid capacity.
- Offshore:Floating wind pre-commercial projects in the Cantabrian Sea face extended permitting timelines and specialized vessel requirements for foundation installation.
- Distributed:Rooftop solar and industrial battery deployments create virtual power plant revenue streams through CNMC-regulated ancillary service markets.
- Centralized:Utility-scale arrays require transmission upgrade co-investment to resolve congestion bottlenecks along the Cantabrian corridor.
Investment flows favor Centralized; regulatory support is strengthening for Distributed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Lignite deposits in Castilla y León and hard coal seams in Asturias historically anchored Spain's thermal generation geography, though renewable clusters now dominate capital allocation across the Iberian Peninsula.
Madrid
Data center operators in Alcobendas and San Sebastián de los Reyes are driving 24/7 carbon-free electricity procurement under CSRD disclosure rules. The Ministry for the Ecological Transition coordinates national auction schedules from the capital. Grid operator Red Eléctrica Corporación manages transmission planning for renewable exports toward the French border.
Catalonia
Chemical manufacturers in Tarragona's petrochemical complex are expanding long-term power purchase agreements to meet Scope 2 emissions commitments. The Catalan Institute for Energy implements regional building efficiency codes that accelerate industrial electrification. Port infrastructure in Barcelona supports floating wind component staging for pre-commercial Cantabrian Sea arrays.
Basque Country
Automotive plants in Vitoria-Gasteiz and Bilbao are deploying behind-the-meter battery storage for virtual power plant participation in CNMC-regulated ancillary service markets. The Basque Energy Agency promotes hydrogen valley development around the Port of Bilbao. High-voltage substation commissioning expertise concentrates among aging workforce cohorts, constraining deployment velocity.
Andalusia
Irrigation pumping loads in the Guadalquivir basin align consumption with solar production profiles, reducing peak demand charges for agricultural cooperatives. The Andalusian Energy Agency streamlines permitting for reservoir-based floating photovoltaic installations. Seville and Málaga host engineering consultancies specializing in concentrated solar power retrofit engineering.
Valencia
Ceramic tile manufacturers in Castellón are securing renewable supply contracts to maintain export competitiveness under EU carbon border adjustment mechanisms. The Valencian Institute for Business Competitiveness subsidizes industrial self-consumption installations. Port facilities in Sagunto handle photovoltaic module imports for Extremadura utility-scale projects.
Spain Power Market Competitive Environment
Global majors compete with regional champions across grid access rights and renewable auction participation. The Spanish power sector exhibits tiered consolidation, with integrated utilities controlling transmission corridors while specialized developers capture marginal solar and wind sites. Two strategic archetypes dominate: vertically integrated generation-to-grid operators and project-specific independent power producers. Competitive intensity centers on M&A activity for operational asset portfolios and strategic partnerships for storage co-location mandates.
Among Iberian-based integrated utilities, Iberdrola, Endesa, and Naturgy Energy Group exemplify distinct strategic positioning. Iberdrola occupies a position as the archetypal transmission-access integrator. Endesa represents the incumbent thermal operator repositioning around flexibility services. Naturgy Energy Group sits within the gas-to-power transition specialist tier, anchoring hydrogen roadmap implementation through existing infrastructure repurposing.
| Leading Market Players |
|---|
| EDP Renováveis |
| Acciona Energía |
| Iberdrola |
| Matrix Renewables |
| Enagás |
| Endesa |
| Red Eléctrica Corporación |
| Solaria Energía y Medio Ambiente |
| Naturgy Energy Group |
| Others |
Value Chain & Pricing Dynamics
Centralized inverter architectures above 300kW are compressing balance-of-system costs for 500MW+ solar projects in Extremadura while simultaneously concentrating procurement leverage among tier-one EPCs with direct manufacturer relationships. This hardware standardization is redrawing margin allocation between component suppliers and project developers.
Pricing Analysis
Long-term power purchase agreements bundle grid access priority rights with firming services from co-located battery storage, unbundling merchant risk from construction execution. Pricing stratifies across premium, standard, and economy tiers based on offtaker credit quality and contract duration. Cost compression in utility-scale solar is intensifying because module oversupply from Chinese manufacturers is transmitting downstream. Industrial buyers with CSRD disclosure obligations show lowest price sensitivity; agricultural cooperatives in Andalusia exhibit highest.
Supply Chain Analysis
End-of-life turbine refurbishment and solar panel remanufacturing flows remain underdeveloped, creating stranded asset risk for early-vintage renewable installations. Polysilicon processing concentrates in China, South Korea, and Germany; rare earth magnet supply for direct-drive wind turbines rests on Chinese separation facilities. Lithium-ion cell supply draws from South Korean and Japanese producers with limited European manufacturing scale. Single-source vulnerability in high-voltage cable insulation compounds deployment delays for floating wind pre-commercial arrays. Distribution runs through Red Eléctrica Corporación's transmission network with regional substation access as the chokepoint.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's power market operates as a supply-constrained environment where grid access rights—rather than generation capacity—prop pricing premiums for deliverable projects.
For Market Incumbents: Lock in transmission corridor control through strategic partnerships with Red Eléctrica Corporación for priority interconnection queue positioning. Defend against merchant solar entrants by accelerating storage co-location investments in high-wind-penetration provinces. Grid code compliance retrofits on operational wind farms represent a margin pressure point requiring proactive inverter upgrade programs. For New Entrants and Emerging Players: Engineering consultancies with concentrated solar power retrofit expertise offer partnership pathways into Andalusian project development. Floating solar on Guadalquivir basin reservoirs presents the most penetrable white-space opportunity with streamlined permitting from the Andalusian Energy Agency. Target behind-the-meter storage aggregation for Basque Country automotive plants as the anchor go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in operational asset portfolio sales to infrastructure funds seeking contracted cash flow visibility. Long-term viability hinges on regulatory stability across EU ETS carbon price trajectories and capacity remuneration mechanism design. Acquisition target archetype: utility-scale solar developers with secured grid access rights in Extremadura. Monitor CNMC storage procurement mandate announcements as the inflection indicator for battery co-location economics.| Strategic Initiative | Industry Significance |
|---|---|
| Grid Access Priority Securement | Red Eléctrica Corporación interconnection queue positioning determines project viability timelines. |
| Storage Co-location Bundling | CNMC auction rules mandate battery capacity for renewable bid qualification. |
| Corporate PPA Origination | Data center operators in Madrid drive 24/7 carbon-free matching demand under CSRD. |
| Floating Solar Development | Guadalquivir basin installations evade land constraints while reducing reservoir evaporation losses. |
| Green Hydrogen Integration | National hydrogen roadmap creates anchor offtake for curtailed renewable generation. |
Study Parameters
Grid operator filings, EU auction mechanism documentation, and corporate sustainability disclosure databases formed the secondary backbone for capacity addition tracking and regulatory timeline assessment. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators validated deployment velocity assumptions and grid access bottleneck severity. Bottom-up project pipeline aggregation triangulated against top-down National Integrated Energy and Climate Plan target reconciliation.
Historical capacity installation trendlines and auction clearing price trajectories anchored the projection framework across the analysis window. Segmentation modeling incorporated generation technology, project scale tier, end-user voltage level, and regional grid congestion status. CAGRs were derived from capacity-weighted average deployment velocities and technology-specific cost curve expectations. Forecast inputs included polysilicon price volatility scenarios and interconnection queue processing rate assumptions.
Caveats apply where EU ETS carbon price spikes or REPowerEU regulatory revisions could materially shift the outlook for thermal asset valuations and renewable auction participation economics. Forecasts reflect documented assumptions around permitting timeline compression and transmission upgrade completion schedules. Practitioners should monitor CNMC storage mandate enforcement intensity and French border interconnection capacity expansion announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Egypt Uninterruptible Power Supply (UPS) Market
Power
North America Micro CHP Market
Power
Single-Phase Microinverter Market
Power
Italy Power EPC Market
Power
Global UPS Market
Power
Vietnam Power Market
Power
Recloser Control Market
Power
Canada Thermal Power Market
Power
Germany Solar Inverter Market
Power
Telecom Power Rental Market
Power
Modular PSA Nitrogen Generator Market
Power
Harmonic Filter Market
Power
Electric Power Sports Market
Power
Colombia Power Market
Power
Canada Power Market
Power
Asia-Pacific Alternating Current (AC) Drive Market