
 Solar Plants Controllers Market | 2026-2036
Solar Plants Controllers Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Plants Controllers Market Insights
The EU Green Deal is restructuring the cost-of-entry calculus for solar plant controllers across European markets, forcing manufacturers to redesign products for stricter carbon-footprint and recyclability benchmarks. Schneider Electric leverages its integrated energy management portfolio to anchor utility-scale controller deployments across multiple continents. SMA Solar Technology AG sustains technology leadership through deep specialization in MPPT algorithms and grid-forming inverter controls. Victron Energy B.V. differentiates in off-grid and hybrid system segments where communication protocol flexibility commands premium positioning.
Solar plants controllers are electronic systems that regulate photovoltaic array operation through maximum power point tracking, voltage conversion, and real-time telemetry with response latencies typically under 100 milliseconds. Their primary purpose is to maximize energy harvest while ensuring grid-code compliance and protecting battery storage assets from overcharge or thermal runaway. Centralized controllers dominate utility-scale deployments where single-point optimization reduces balance-of-system costs, while distributed controllers are gaining traction in commercial installations requiring granular panel-level visibility. MPPT technology anchors the highest-margin controller variants due to its direct impact on energy yield, whereas communication protocols represent the fastest-evolving segment as IEC 61850 and SunSpec standards converge.
The EU Green Deal and CE marking frameworks shape product standards and market access for controller vendors serving European utilities, while India's BIS certification and PLI scheme for solar manufacturing create localized procurement incentives. China's GB standards and MIIT efficiency mandates dictate minimum conversion thresholds for controllers deployed in domestic utility projects. Stakeholders must monitor regulatory divergence between efficiency benchmarking methodologies as this determines which controller architectures qualify for subsidized installation programs.
Market Dynamics
Grid-forming inverter controls are compressing response latencies below 50 milliseconds, forcing legacy centralized architectures into rapid redesign cycles to maintain utility procurement eligibility.
Growth Catalysts
- EU Green Deal carbon-footprint benchmarks:Manufacturers redesign controller enclosures and power electronics for stricter recyclability mandates, opening premium positioning for compliant vendors in German and Spanish utility tenders.
- India's PLI scheme for solar manufacturing:Domestic controller production incentives accelerate localized supply chains for utility-scale projects in Rajasthan and Gujarat states.
- MPPT algorithm advancement:Deep learning-based maximum power point tracking improves energy harvest by dynamically adjusting to partial shading patterns in commercial rooftop installations.
Market Restraints
- IGBT and silicon carbide wafer concentration:Controller power module supply chains cluster in East Asian foundries, exposing European and North American assemblers to input volatility.
- CE marking technical file complexity:Extended conformity assessment timelines for grid-forming variants delay product launches by six to nine months.
- String inverter substitution:Modular string architectures with integrated MPPT displace centralized controller demand in sub-5MW commercial segments.
Strategic Opportunities
- Agricultural solar-plus-storage in India:Unpenetrated irrigation pump electrification programs create demand for hybrid controllers managing PV, grid, and battery inputs simultaneously.
- Dual carbon goals enforcement in China:Provincial MIIT mandates for domestic project efficiency thresholds favor advanced MPPT controllers in Inner Mongolia and Xinjiang utility deployments.
- IEC 61850 and SunSpec protocol convergence:Unified communication standards reduce engineering integration costs for distributed energy resource management platforms.
Industry Challenges
- Embedded firmware security certification:IEC 62443 cybersecurity compliance for grid-connected controllers requires specialized engineering talent scarce in European automation hubs.
- Legacy SCADA integration friction:Retrofitting 2015-era plant control networks with modern grid-forming interfaces demands custom protocol gateways.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Plants Controllers Market |
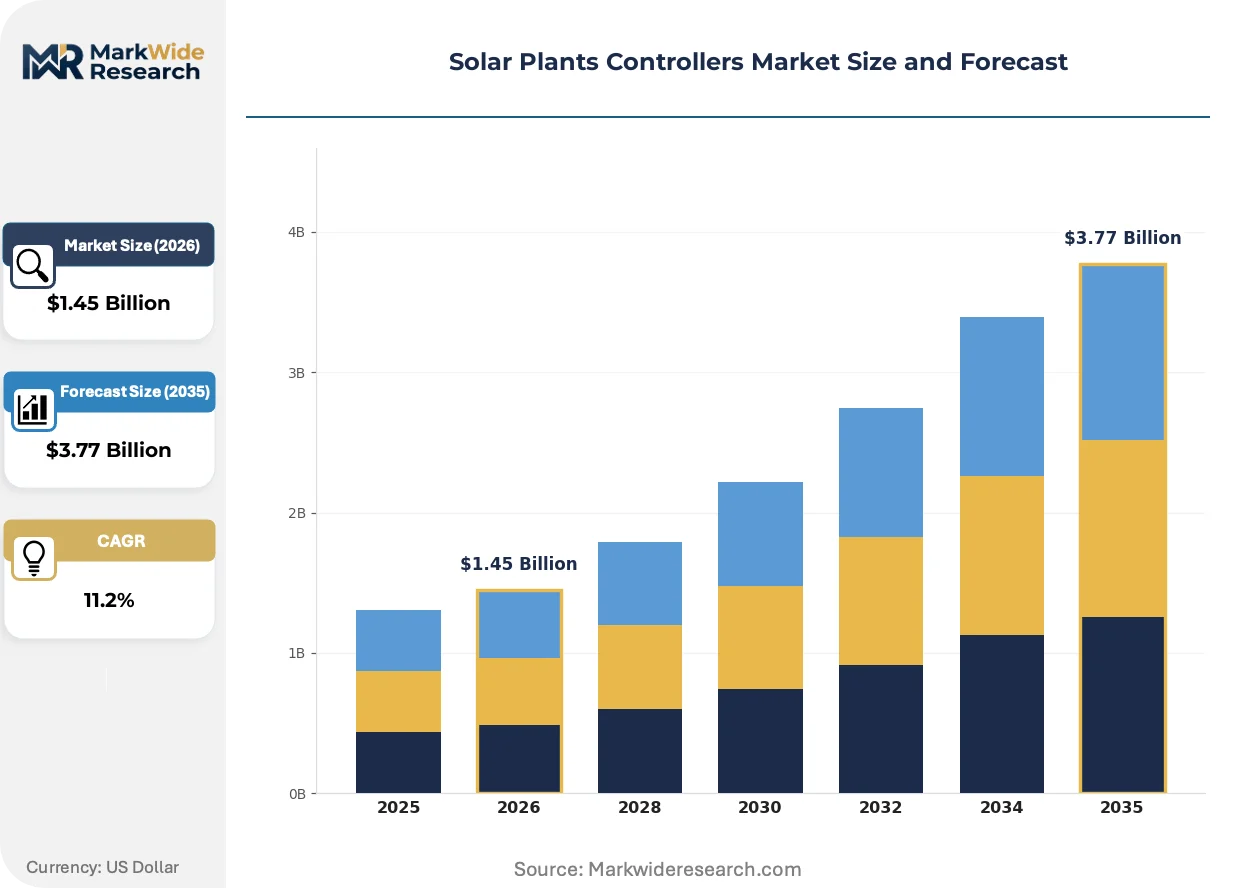
| Market Size in 2026 | $1.45 Billion |
| Market Size in 2035 | $3.77 Billion |
| CAGR (2026 – 2036) | 11.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Control Type: Centralized Controllers, Distributed Controllers, Supervisory Control, Remote Monitoring Systems Technology: PID Control, MPPT Technology, Inverter Technology, Communication Protocols End User: Utility-Scale Projects, Commercial Installations, Residential Systems, Independent Power Producers Installation Method: Ground-Mounted Systems, Roof-Mounted Systems, Floating Systems, Hybrid Solutions |
| Companies Covered | SUNGROW, Morningstar Corporation, Schneider Electric, BEIJING EPSOLAR TECHNOLOGY CO. LTD, Victron Energy B.V., Wenzhou Xihe Electric Co.,LTD., Phocos, SMA Solar Technology AG, SolarEdge, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Plants Controllers Market Trends and Innovations
Silicon carbide power semiconductors and edge-computing telemetry are compressing controller form factors while expanding real-time optimization capabilities across utility and commercial segments.
Grid-forming inverter control firmware is electrifying utility-scale plant architectures by enabling synthetic inertia provision and black-start capability without synchronous condensers. Developers in Australia and Chile are procuring these variants for weak-grid remote installations. This capability compression is displacing traditional centralized plant controllers in new-build tenders.
REACH substance restrictions and RoHS recast directives are forcing solder alloy and capacitor dielectric substitutions in European-bound controller production. Manufacturers serving German utilities must reformulate thermal interface materials to eliminate restricted phthalates. The industrial consequence cascades through Southeast Asian contract assembly networks.
Asset owner engineering teams are unbundling controller procurement from EPC contracts to direct manufacturer relationships. This disintermediation compresses margin capture for system integrators while expanding technical support obligations for controller vendors. The pattern is most visible in Indian and Brazilian utility-scale procurement cycles.
Solar Plants Controllers Market Segmentation
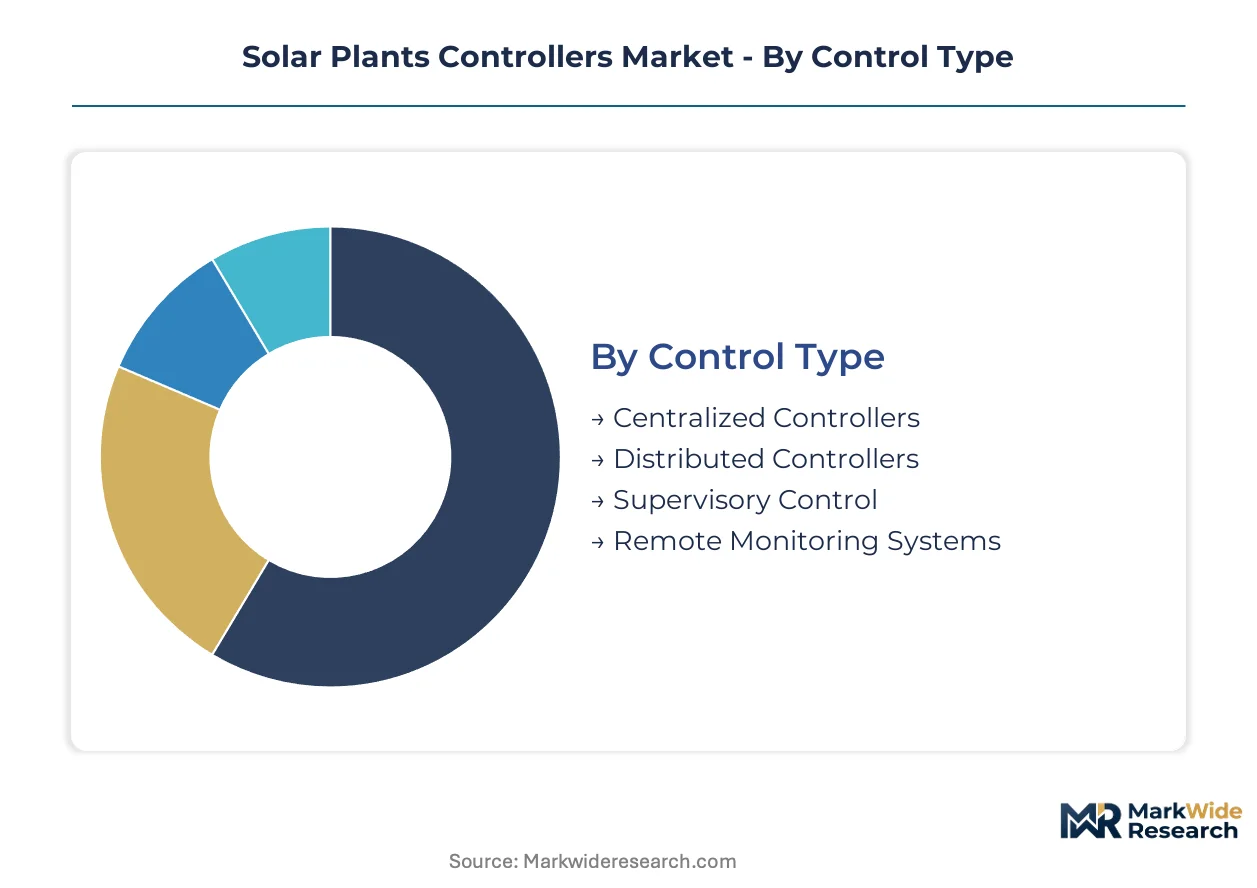
Controller architecture choices directly determine balance-of-system costs and grid compliance pathways for solar developers. Procurement patterns diverge sharply between utility-scale tenders favoring centralized optimization and commercial segments demanding granular visibility.
Control Type:
Supply concentration in centralized controller manufacturing clusters around German and Chinese automation hubs, while distributed architectures draw from broader electronics contract manufacturing networks.
- Centralized Controllers:Single-point optimization systems aggregate array-wide telemetry through high-capacity processing units rated for 100MW+ plant configurations. Utility-scale developers in Rajasthan and Gujarat specify these variants to minimize cabling infrastructure and reduce commissioning complexity.
- Distributed Controllers:Panel-level or string-level units embed MPPT and communication capabilities at multiple network nodes. Commercial rooftop installers in Germany and Spain procure these for granular fault isolation and per-module performance analytics in partially shaded environments.
- Supervisory Control:Plant-wide orchestration layers coordinate inverter fleets and energy storage dispatch.
- Remote Monitoring Systems:Cloud-connected telemetry platforms enable off-site diagnostics and predictive maintenance scheduling.
Centralized controllers absorb the bulk of installed capacity; distributed controllers are expanding most quickly.
Technology:
Cost tiers separate legacy analog control methods from digital architectures commanding premium positioning in efficiency-critical tenders.
- MPPT Technology:Maximum power point tracking algorithms dynamically adjust electrical operating points to extract peak energy from photovoltaic arrays under variable irradiance. Advanced variants employing deep learning pattern recognition are penetrating commercial installations in India where partial shading from adjacent structures degrades fixed-tilt harvest.
- Inverter Technology:Grid-forming and grid-following control firmware enables synthetic inertia provision and black-start capability without synchronous condensers. Australian and Chilean developers specify these for weak-grid remote installations where traditional rotating machinery is unavailable.
- Communication Protocols:IEC 61850 and SunSpec standard implementations reduce integration engineering for distributed energy resource management.
- PID Control:Proportional-integral-derivative feedback loops regulate voltage and current in simpler, cost-constrained applications.
MPPT technology commands the highest margin premiums; inverter technology is climbing the fastest as grid-forming requirements proliferate.
End User:
Volume concentration tilts toward utility procurement cycles with extended tender timelines, while residential and commercial segments generate higher unit margins through fragmented distribution.
- Utility-Scale Projects:Centralized procurement by state-owned utilities and independent power producers specifies controllers with 25-year operational lifespans and comprehensive warranty coverage. Developers in Inner Mongolia and Xinjiang deploy advanced variants to meet MIIT efficiency mandates under China's dual carbon goals enforcement.
- Commercial Installations:Distributed generation assets under 5MW capacity require flexible controller architectures accommodating mixed rooftop geometries and evolving tenant load profiles. Spanish and Italian installers favor modular string controllers with integrated monitoring to minimize balance-of-system labor.
- Residential Systems:Single-phase or small three-phase controllers prioritize plug-and-play commissioning and mobile app connectivity.
- Independent Power Producers:Merchant solar developers optimize controller selection for merchant price exposure and ancillary service revenue capture.
Utility-scale projects absorb the bulk of installed capacity; commercial installations are gaining share fastest.
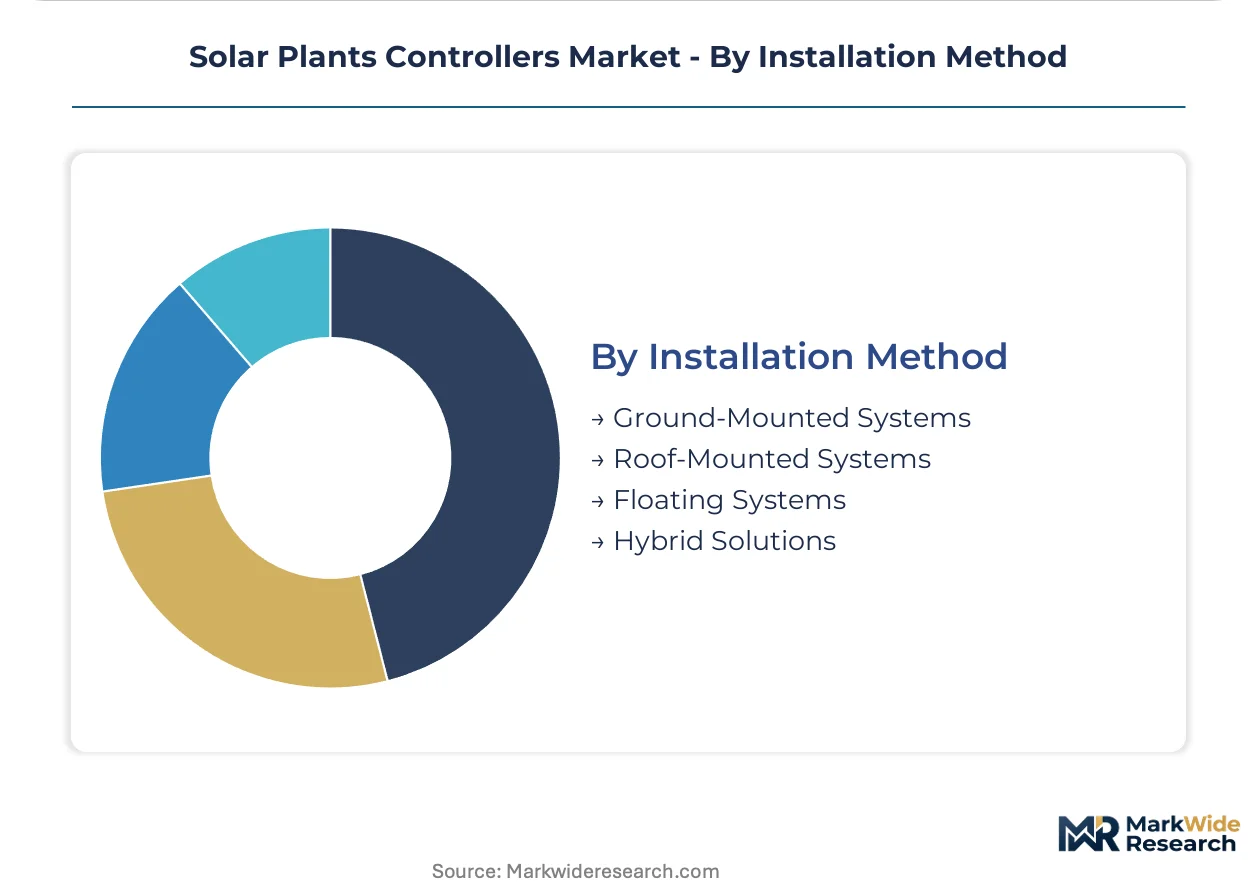
Installation Method:
Application-specific environmental stressors dictate controller enclosure ratings and thermal management requirements across mounting configurations.
- Ground-Mounted Systems:Large-area fixed-tilt or tracking installations expose controllers to dust, temperature cycling, and direct solar loading. Desert deployments in Rajasthan and Arizona specify IP65-rated enclosures with active thermal management to sustain conversion efficiency across 50°C ambient excursions.
- Floating Systems:Photovoltaic arrays on reservoirs and coastal lagoons demand corrosion-resistant controller housings and moisture-sealed cable entry points. Japanese and South Korean developers are expanding procurement for these variants as land constraints intensify.
- Roof-Mounted Systems:Commercial and residential rooftop controllers prioritize compact form factors and rapid shutdown compliance.
- Hybrid Solutions:Agrivoltaic and building-integrated configurations require specialized mounting adaptation and agricultural dust protection.
Ground-mounted systems absorb the bulk of installed capacity; floating systems are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's solar parks and special economic zones concentrate controller procurement through Rajasthan and Gujarat state tenders. Utility-scale developers in these corridors specify centralized architectures to meet CEA grid-code mandates.
China
Provincial MIIT efficiency mandates under dual carbon goals enforcement favor advanced MPPT controllers in Inner Mongolia and Xinjiang utility corridors. GB standards dictate minimum conversion thresholds for domestic project qualification. Manufacturers cluster in Yangtze River Delta automation hubs to serve state-owned utility procurement cycles.
Germany
EU Green Deal carbon-footprint benchmarks force enclosure redesigns for stricter recyclability compliance in German utility tenders. CE marking technical files extend conformity timelines for grid-forming variants. Industrial automation suppliers concentrate in Bavaria and North Rhine-Westphalia to anchor European controller production.
India
PLI scheme incentives accelerate localized controller supply chains for Rajasthan and Gujarat solar parks. BIS certification requirements filter import eligibility for utility-scale tenders. State nodal agencies in Maharashtra and Karnataka specify hybrid controllers for agricultural solar-plus-storage irrigation programs.
United States
IRA production tax credits reshape domestic controller assembly economics for utility-scale developers in Texas and California. FERC Order 2222 compliance drives grid-forming procurement for distributed resource aggregation. Southwest desert installations specify IP65-rated thermal management for 50°C ambient operation.
Australia
Weak-grid remote installations in Queensland and Western Australia specify synthetic inertia-capable controllers without synchronous condenser backup. AEMO reliability standards compress response latency requirements below 50 milliseconds. Mining sector off-grid microgrids anchor premium positioning for Victron Energy B.V. hybrid system variants.
Solar Plants Controllers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered procurement channels. The vendor base stratifies between integrated energy management portfolios and deep MPPT algorithm specialists. Three archetypes dominate: diversified industrial conglomerates with cross-sector energy platforms, solar-pure-play technology specialists with inverter heritage, and off-grid/hybrid system boutiques with protocol flexibility advantages. Competitive moves center on strategic partnerships for grid-forming firmware licensing and geographic expansion through localized certification compliance.
Among diversified industrial conglomerates, Schneider Electric anchors multi-continent utility-scale deployments through integrated energy management portfolios. SMA Solar Technology AG exemplifies the solar-pure-play specialist archetype with deep algorithm heritage. Victron Energy B.V. occupies the hybrid system boutique tier where communication protocol flexibility commands premium positioning in off-grid segments.
| Leading Market Players |
|---|
| SUNGROW |
| Morningstar Corporation |
| Schneider Electric |
| BEIJING EPSOLAR TECHNOLOGY CO. LTD |
| Victron Energy B.V. |
| Wenzhou Xihe Electric Co.,LTD. |
| Phocos |
| SMA Solar Technology AG |
| SolarEdge |
| Others |
Pricing and Supply Chain Analysis
Silicon carbide wafer spot indices cascading from East Asian foundries compress controller power module pricing tiers, forcing European and North American assemblers to absorb input volatility or pass through cost escalations to utility-scale developers in Germany and Rajasthan.
Pricing Analysis
Short lead-time premiums of four to six weeks command fifteen to twenty percent markups over standard twelve-week delivery cycles in utility procurement tenders. Three-tier pricing structure across IEC 61850-certified premium variants, CE-marked standard units, and economy-grade PID controllers stratifies the market. Cost compression in the economy tier is intensifying because string inverter substitution erodes centralized controller demand in sub-5MW commercial segments. Agricultural solar-plus-storage developers in India exhibit highest price sensitivity, while Australian mining sector off-grid microgrids absorb premium positioning with minimal negotiation leverage.
Supply Chain Analysis
Freight cost escalation from Yangtze River Delta automation hubs to European assembly networks adds seven to twelve percent landed cost burden for German utility-bound controller shipments. Manufacturing gravity centers on China, Germany, and Vietnam, with controller power modules drawing from Taiwanese silicon carbide foundries and Japanese IGBT packaging facilities. Single-source vulnerability concentrates in East Asian wafer supply, exposing downstream assemblers to geopolitical logistics chokepoints. Distribution runs through EPC contractor channels in utility-scale segments and direct manufacturer relationships in commercial rooftop installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
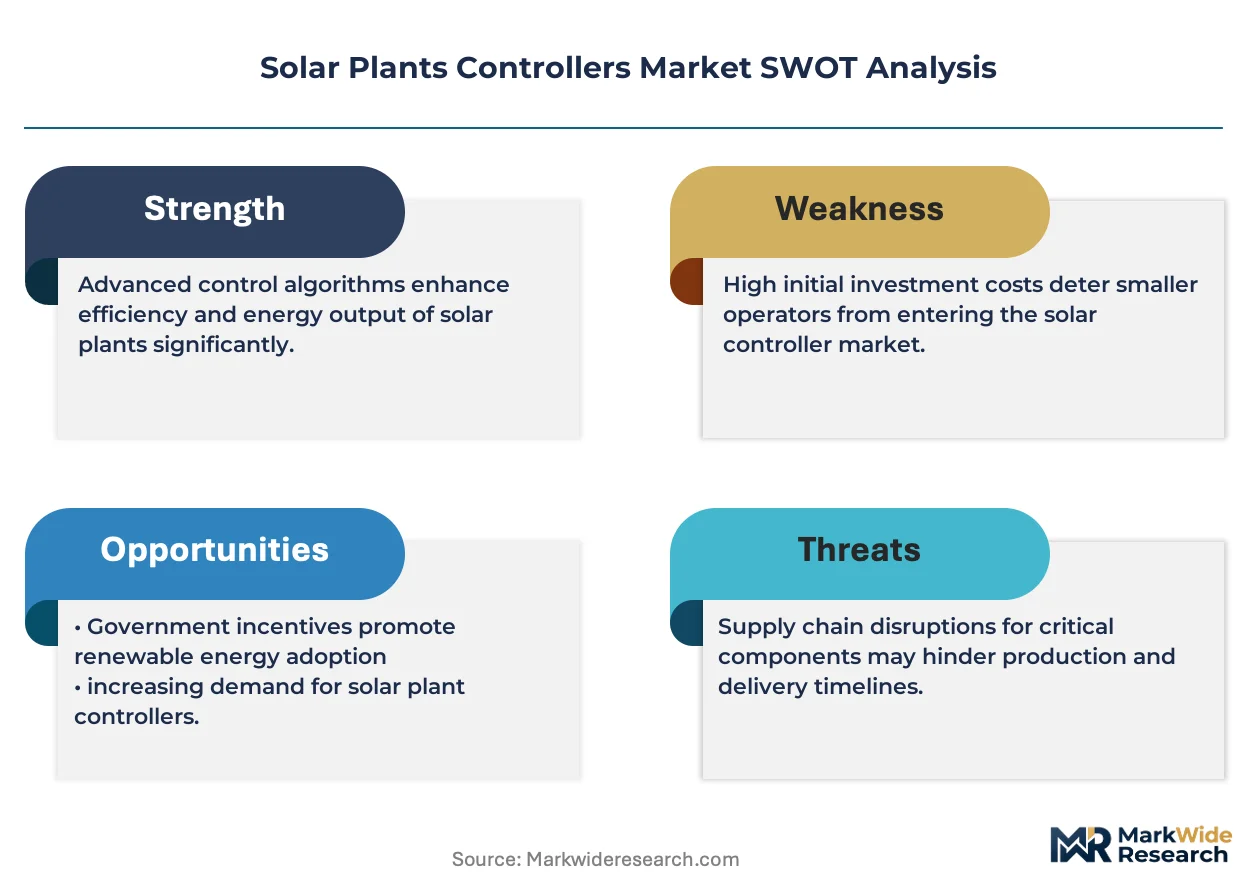
Consolidation pressure is accelerating as CE marking technical file complexity for grid-forming variants extends conformity timelines by six to nine months, forcing capital-constrained specialists into acquisition or exit.
For Market Incumbents: To counter string inverter substitution in commercial segments below 5MW, Schneider Electric and SMA Solar Technology AG should deepen backward integration into silicon carbide power module sourcing through captive supply agreements with Taiwanese foundries. Certification investment in IEC 62443 cybersecurity compliance creates defensive moats against firmware security talent scarcity in European automation hubs. For New Entrants and Emerging Players: EPC contractors in Indian agricultural solar-plus-storage programs represent the most accessible channel partnership for hybrid controller specialists lacking utility-scale track records. White-space targets concentrate in unpenetrated irrigation pump electrification corridors across Maharashtra and Karnataka states, where simultaneous PV-grid-battery management commands premium positioning absent from established vendor portfolios. For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically integrated mid-cap specialists with captive GB standards certification in China's Yangtze River Delta automation corridor. Long-term viability across the projection horizon hinges on grid-forming firmware licensing revenue streams rather than hardware margin capture alone. The inflection signal to monitor is FERC Order 2222 compliance acceleration in Texas and California distributed resource aggregation markets.| Strategic Initiative | Industry Significance |
|---|---|
| Grid-Forming Firmware Licensing | Synthetic inertia capability unlocks Australian and Chilean weak-grid remote installations without synchronous condenser backup. |
| Silicon Carbide Backward Integration | Captive wafer supply from Taiwanese foundries insulates European assemblers from East Asian input volatility. |
| CE Marking Fast-Track Certification | Compressed conformity timelines for grid-forming variants restore eligibility in German and Spanish utility tenders. |
| Hybrid Controller Platform Launch | Simultaneous PV-grid-battery management captures agricultural solar-plus-storage demand in Indian irrigation programs. |
| IEC 61850 Protocol Convergence | Unified SunSpec standard implementation reduces engineering integration costs for distributed energy resource platforms. |
Research Methodology
Document review covered FERC filings, IEA renewable energy reports, MIIT efficiency mandate disclosures, and CEA grid-code specifications, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across China, India, Germany, and Australia. Primary fieldwork with controller firmware engineers and procurement leads at state-owned utilities validated secondary data on MPPT algorithm advancement and grid-forming inverter control adoption trajectories. Bottom-up installation database construction triangulated against top-down regulatory mandate analysis.
Historical capacity deployment patterns cross-referenced against panel input from project finance institutions and equipment procurement specialists shaped the analytical framework. Segmentation dimensions modeled include control type architecture, MPPT versus inverter technology tiers, utility-scale versus commercial end-use categories, and ground-mounted versus floating installation methods. CAGRs derived from compound growth trajectory fitting across the projection horizon, with industry-specific inputs incorporating IRA production tax credit elasticity and EU Green Deal carbon-footprint benchmark compliance costs.
Caveats apply where silicon carbide wafer supply disruptions, CE marking timeline extensions, or FERC Order 2222 implementation delays could materially shift the outlook. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Power
Modular PSA Nitrogen Generator Market
Power
Power Capacitors Market
Power
Distribution Feeder Protection System Market
Power
Asia-Pacific Power Market
Power
Gabon Power Market
Power
Nigeria Power Market
Power
Steam Turbine MRO Market
Power
Egypt Uninterruptible Power Supply (UPS) Market
Power
Recloser Control Market
Power
Spain Power Market
Power
Global Ancillary Services Power Market
Power
Global Advanced Marine Power Supply Market
Power
Residential Micro Inverter Market
Power
Malaysia Power EPC Market
Power
Controllable Shunt Reactor for UHV Market
Power
Middle East and Africa Combined Heat & Power Market