
 Global Emulsion Polymer Market | 2026-2036
Global Emulsion Polymer Market Size, Share, and Industry Trends Forecast 2026-2036
Global Emulsion Polymer Market Foresight
Automotive subcomponent makers are unwinding legacy solvent-based procurement patterns and shifting volume toward waterborne systems. BASF SE leverages its acrylic technology leadership to serve tier-one paint formulators across Europe and Asia. Dow Inc. anchors North American supply through integrated ethylene feedstock positions and captive VAE resin capacity.
Emulsion polymers are aqueous dispersions of synthetic resin particles, typically 0.1 to 5 microns in diameter, stabilized by surfactant systems and produced through free-radical addition polymerization in water. These materials function as film-forming binders, imparting adhesion, flexibility, and durability to coatings, adhesives, and nonwoven substrates. Acrylic formulations command premium positioning in exterior architectural coatings where weathering resistance and color retention define specification value. Vinyl acetate ethylene maintains volume dominance in interior paints and construction adhesives due to cost efficiency and broad substrate compatibility. Styrene butadiene competes aggressively in paper coating and carpet backing where stiffness and binding strength take priority over exterior durability.
EPA VOC regulations and REACH substance restrictions are forcing reformulation across architectural coatings and industrial maintenance applications. ECHA hazard classifications for residual monomers are tightening purity specifications and elevating analytical compliance costs for EU-bound shipments. FDA indirect food-contact rules govern paper-coating grades destined for packaging end uses in the United States. Stakeholders must monitor evolving per- and polyfluoroalkyl substance restrictions, as these intersect with stain-resistant coating segments where emulsion polymers serve as backbone chemistries.
Market Dynamics
Waterborne coating mandates from EPA and REACH are forcing solvent-based formulators to rebuild supply chains around emulsion polymer feedstocks, compressing reformulation timelines and redrawing procurement relationships across architectural and industrial segments.
Growth Catalysts
- REACH substance restrictions:Low-VOC architectural coating mandates in Germany and France are pulling volume from alkyd systems into acrylic emulsion platforms.
- Construction adhesives:Vinyl acetate ethylene resins capture volume in China and India where infrastructure spending accelerates interior finish installation.
- Automotive waterborne transition:Tier-one paint shops in Japan and South Korea unwind solvent-based procurement for exterior vehicle coatings.
Market Restraints
- Ethylene feedstock volatility:VAE resin margins compress when naphtha-cracker output fluctuates across integrated petrochemical complexes.
- Residual monomer purification:ECHA hazard classifications for trace styrene and butadiene elevate analytical compliance costs for EU-bound shipments.
- Stiffness-performance tradeoff:Styrene butadiene emulsions face displacement in exterior architectural applications where acrylic weathering resistance dominates specification value.
Strategic Opportunities
- India infrastructure buildout:National highway and urban housing programs concentrate demand for construction-grade VAE and acrylic binders.
- Food-contact paper coatings:FDA indirect additive rules create specification entry points for styrene butadiene grades in US packaging converters.
- Bio-based acrylic feedstocks:Fermentation-derived acrylic acid pathways converge with conventional petrochemical routes to serve premium sustainability claims.
Industry Challenges
- Surfactant formulation expertise:Colloidal stability engineering for high-solids emulsions runs short of trained polymer chemists across formulator technical centers.
- Legacy coating line retrofit:Solvent-based spray booths and drying ovens require capital-intensive reconfiguration to handle waterborne viscosity and flash profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Emulsion Polymer Market |
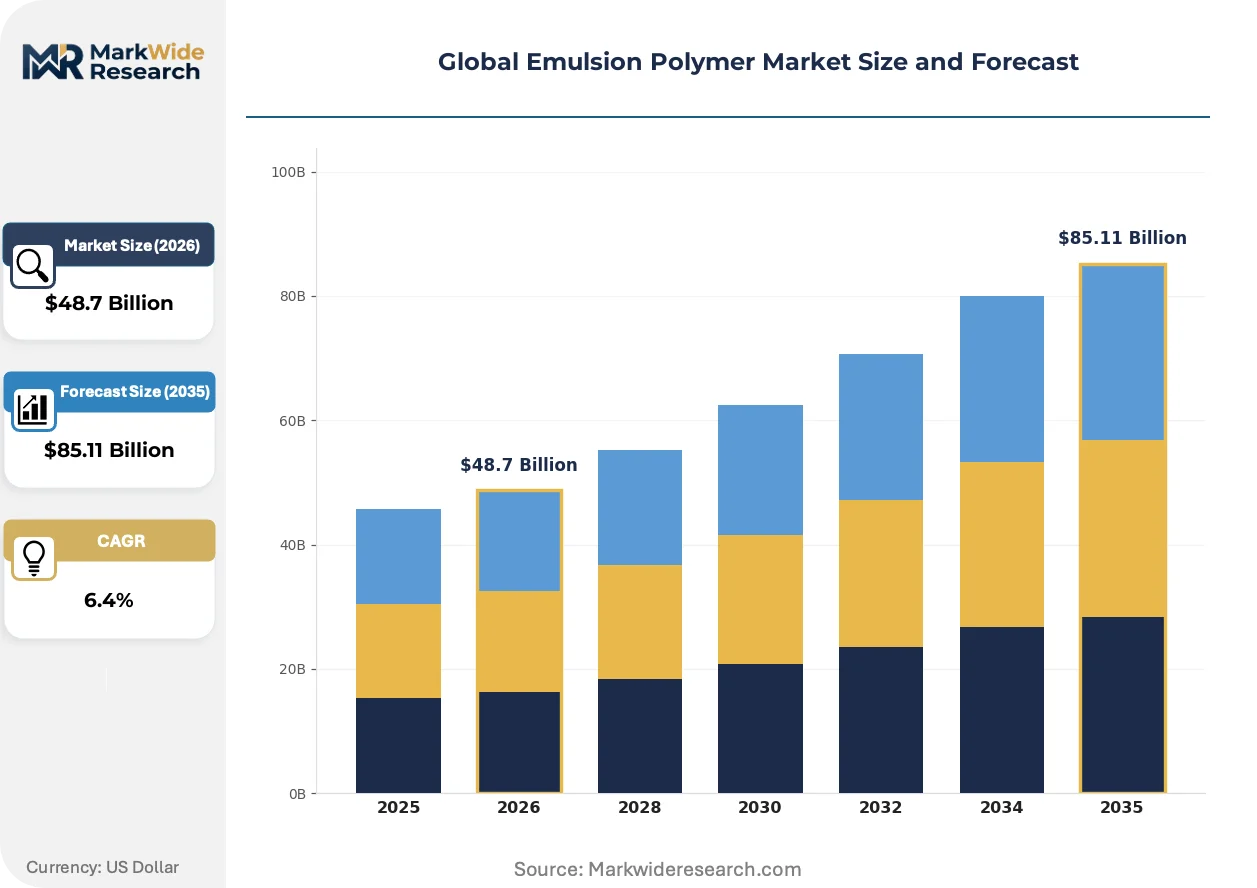
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $85.11 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Styrene Butadiene, Vinyl Acetate Ethylene, Acrylic, Chlorinated, Polyvinyl Chloride Application: Paints & Coatings, Adhesives, Textile Finishing, Paper Coating, Construction Materials, Leather Processing End User: Building Contractors, Textile Manufacturers, Packaging Producers, Footwear Makers, Automotive Subcomponent Makers Packaging Type: Drums, Carboys, Bulk Containers, Intermediate Bulk Containers, Pails |
| Companies Covered | Wacker Chemie AG, Celanese Corporation, BASF SE, DIC Corporation, JSR Corporation, Dow Inc., Synthomer plc, Trinseo S.A., Arkema S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Emulsion Polymer Market Shifts & Advancements
Hybrid emulsion polymer architectures are redrawing performance boundaries between acrylic, VAE, and styrene butadiene chemistries, enabling formulators to target specification gaps that single-resin systems cannot address.
Core-shell particle morphology is fragmenting traditional resin category boundaries. This technology embeds hard styrene-rich phases within soft acrylic or butadiene-rich matrices to deliver blocking resistance and flexibility simultaneously. Exterior wood coating formulators in Scandinavia and the Pacific Northwest are specifying these hybrids for deck and siding applications. The structural consequence is compressing premium pricing power for pure acrylic grades in mid-tier architectural segments.
EPA VOC regulations are tightening residual solvent limits in architectural and industrial maintenance coatings. Formulators must validate compliance through third-party certification to maintain product listings with major retail and specification channels. Small and mid-size coating producers in the US Southeast face disproportionate analytical burden as they lack in-house chromatography capacity.
Specification-driven procurement is consolidating buyer power among large architectural coating brands and national retail private-label programs. Regional formulators lose shelf placement unless they qualify for master specifications from Home Depot, Lowe's, or Sherwin-Williams. This concentration is most visible in US residential repaint and new construction segments where distributor consolidation has reduced independent channel alternatives.
Global Emulsion Polymer Market Segmentation
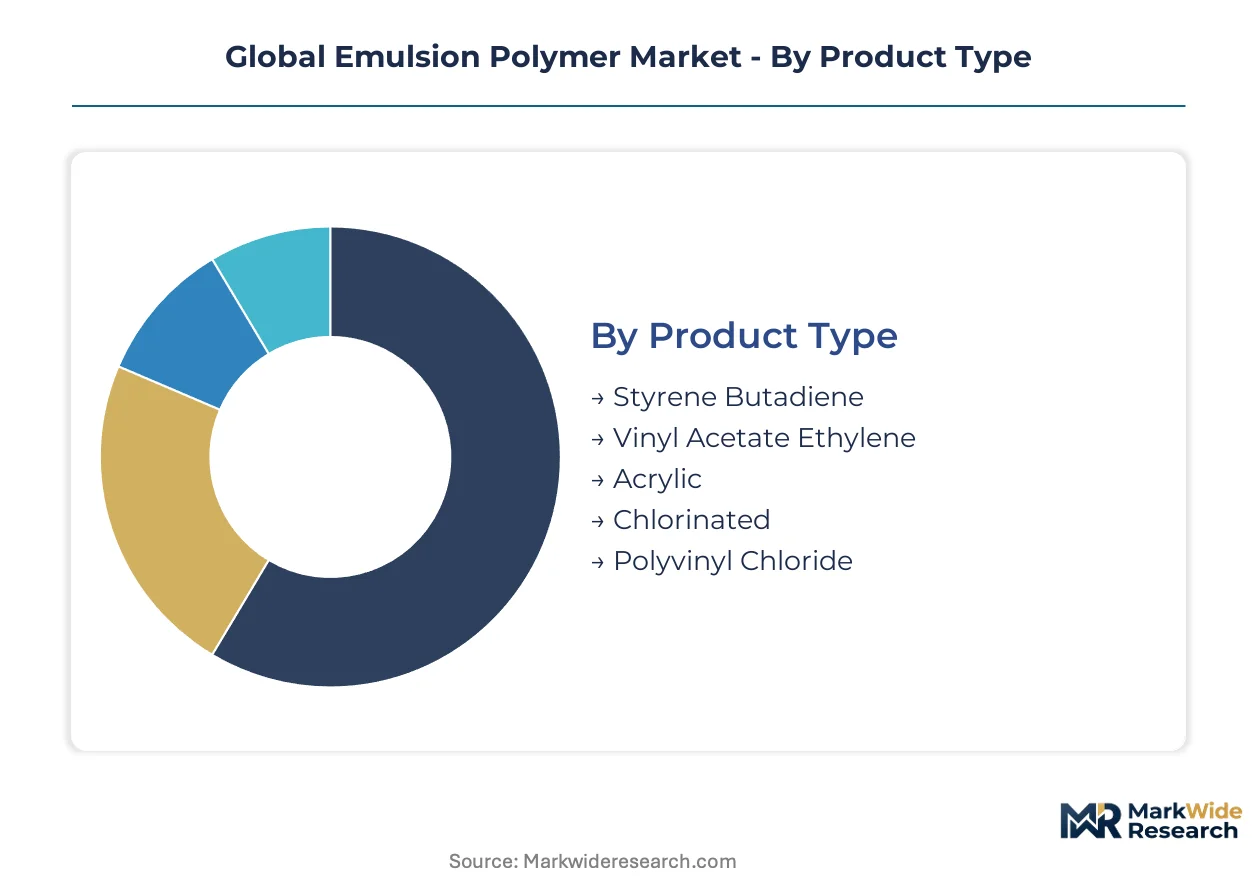
Emulsion polymer segmentation tracks divergent regulatory pathways across chemistries and end-uses. Product type determines VOC compliance burden under EPA and REACH rules, while application segments face distinct purity specifications for food-contact, architectural, and industrial uses.
Product Type:
REACH substance restrictions and EPA VOC limits create tiered compliance costs that reshape procurement economics across resin categories.
- Acrylic:These copolymers of methyl methacrylate and butyl acrylate deliver superior UV resistance and color retention for exterior architectural coatings. Demand concentrates in Germany and France where REACH low-VOC mandates displace alkyd systems from premium facade applications. ECHA hazard classifications for residual monomers elevate analytical compliance costs for EU-bound shipments of architectural grades.
- Vinyl Acetate Ethylene:Flexible copolymers combining vinyl acetate with ethylene segments dominate interior construction adhesives and economy architectural paints. Volume concentrates in China and India where infrastructure spending accelerates interior finish installation, though naphtha-cracker feedstock volatility compresses margins across integrated petrochemical complexes.
- Styrene Butadiene:Carboxylated latexes serve paper coating and carpet backing where stiffness and binding strength outweigh exterior durability requirements. FDA indirect food-contact rules govern packaging grades destined for US converters.
- Chlorinated:Modified polyethylene dispersions provide chemical resistance for industrial maintenance and marine protective coatings.
- Polyvinyl Chloride:Rigid homopolymer and copolymer emulsions bind construction materials including flooring and synthetic leather substrates.
Established volume favors Vinyl Acetate Ethylene; emerging adoption favors Acrylic.
Application:
Application segments diverge sharply in specification maturity and margin structure across architectural, industrial, and specialty end-uses.
- Paints & Coatings:Architectural and industrial maintenance formulations represent the specification anchor for emulsion polymer demand. EPA VOC regulations tighten residual solvent limits and force third-party certification for retail channel access, concentrating procurement power among Home Depot, Lowe's, and Sherwin-Williams master specifications.
- Adhesives:Construction-grade VAE and acrylic systems capture volume in China and India where national highway and urban housing programs concentrate demand for interior finish installation.
- Textile Finishing:Soft-hand acrylic and styrene butadiene binders modify fabric hand and dimensional stability for apparel and technical textiles.
- Paper Coating:Styrene butadiene latexes provide gloss and printability for magazine and packaging papers under FDA indirect additive rules.
- Construction Materials:Cement modification, waterproofing membranes, and flooring adhesives consume VAE and acrylic dispersions.
- Leather Processing:Acrylic and polyurethane-acrylic hybrids finish synthetic and natural leather for footwear and automotive upholstery.
Paints & Coatings commands the dominant value share; Adhesives gains share fastest on infrastructure buildout.
End User:
End-user concentration reflects divergent specification power and procurement sophistication across construction, automotive, and consumer goods supply chains.
- Building Contractors:Residential and commercial construction firms specify emulsion polymers for architectural coatings, tile adhesives, and waterproofing systems. Demand concentrates in China, India, and Germany where infrastructure spending and building code enforcement create specification pull for low-VOC formulations.
- Automotive Subcomponent Makers:Tier-one paint shops in Japan and South Korea unwind solvent-based procurement for exterior vehicle coatings, accelerating waterborne system adoption.
- Textile Manufacturers:Fabric finishers apply acrylic and styrene butadiene binders for technical and apparel applications.
- Packaging Producers:Paper converters specify styrene butadiene grades for food-contact coatings under FDA indirect additive rules.
- Footwear Makers:Synthetic leather and finishing applications consume acrylic and polyurethane-acrylic hybrid emulsions.
Building Contractors anchor volume concentration; Automotive Subcomponent Makers drive the steepest specification upgrade trajectory.
Packaging Type:
Packaging configuration tracks shipment scale, shelf stability requirements, and customer handling infrastructure across the value chain.
- Bulk Containers:Railcar and tank truck deliveries serve large architectural coating plants and adhesive compounders with captive storage and handling systems.
- Intermediate Bulk Containers:Tote tanks bridge bulk and smaller-scale requirements for mid-size formulators lacking rail access.
- Drums:Standard 55-gallon steel and plastic drums serve regional coating producers and specialty adhesive manufacturers.
- Pails:Five-gallon containers target small-batch formulators and maintenance repair operations.
- Carboys:Glass and plastic carboys deliver laboratory and sampling quantities for product development and quality validation.
Bulk Containers dominate tonnage movement; Intermediate Bulk Containers capture the fastest expansion among mid-scale formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Main-Danube waterway network positions Germany as the logistical backbone for European emulsion polymer distribution, connecting Bavarian production clusters to North Sea ports and inland industrial consumers.
Germany
REACH low-VOC mandates and facade renovation programs drive specification upgrades in architectural coatings. ECHA hazard classifications for residual monomers tighten purity requirements for EU-bound shipments. The BASF Ludwigshafen complex anchors acrylic emulsion supply for premium exterior applications across Western Europe.
China
National highway expansion and urban housing programs concentrate demand for construction-grade VAE binders. MIIT industrial standards for low-emission building materials accelerate waterborne adhesive adoption. The Yangtze River Delta manufacturing corridor hosts integrated petrochemical complexes supplying vinyl acetate monomer feedstock.
United States
EPA VOC regulations force reformulation across architectural and industrial maintenance segments. The Home Depot and Lowe's master specification programs consolidate procurement power among large coating brands. The Gulf Coast petrochemical corridor provides captive ethylene feedstock for VAE resin production.
India
Smart Cities Mission and Bharatmala highway programs expand infrastructure spending for construction adhesives. BIS certification requirements for low-VOC interior paints pull volume from solvent-based systems. The Gujarat chemical belt hosts expanding emulsion polymer capacity serving domestic and export markets.
Japan
Tier-one automotive paint shops unwind solvent-based procurement for exterior vehicle coatings. METI carbon neutrality roadmaps accelerate waterborne system transitions in manufacturing. The Nagoya-Toyota industrial corridor concentrates demand for high-performance acrylic binders in automotive applications.
Global Emulsion Polymer Market Competitive Landscape
Listed leaders compete with private specialists across integrated petrochemical and specialty chemical dimensions. The market structure consolidates around three to five global resin suppliers with captive monomer positions, while regional formulators and application-specific compounders fragment the downstream value chain. Strategic archetypes include integrated petrochemical majors, specialty acrylic technology leaders, and construction-focused VAE volume players. Capacity expansion in Asia-Pacific and strategic partnerships for bio-based feedstock pathways represent dominant competitive moves.
Among German-based chemical conglomerates, Wacker Chemie AG and BASF SE exemplify integrated technology leadership spanning silicones and acrylic emulsions. Dow Inc. anchors North American supply through Gulf Coast ethylene integration. Japanese specialists DIC Corporation and JSR Corporation occupy positions in automotive and electronics-grade polymer formulations.
| Leading Market Players |
|---|
| Wacker Chemie AG |
| Celanese Corporation |
| BASF SE |
| DIC Corporation |
| JSR Corporation |
| Dow Inc. |
| Synthomer plc |
| Trinseo S.A. |
| Arkema S.A. |
| Others |
Supply & Pricing Matrix
Waterborne acrylic substitution for solvent-based alkyds simultaneously redraws supply geography toward German and Chinese production clusters and compresses pricing power for legacy resin grades. This feedstock transition elevates analytical compliance costs for EU-bound shipments while concentrating procurement leverage among large architectural coating brands.
Pricing Analysis
Volume-discount tiering structures separate premium REACH-certified grades from standard architectural formulations and economy interior VAE binders. Price differentiation hinges on residual monomer purity certification and railcar-scale delivery commitments. Pricing pressure stems from naphtha-cracker feedstock volatility compressing VAE resin margins. Small regional formulators exhibit highest price sensitivity due to limited chromatography capacity, while tier-one automotive paint shops prioritize specification compliance over unit cost.
Supply Chain Analysis
Inventory lead times stretch across integrated petrochemical complexes when ethylene cracker output fluctuates, forcing coating plants to carry higher safety stock of acrylic and VAE dispersions. Supply concentrates in Germany, China, and the United States where captive monomer production anchors resin manufacturing. Raw material dependencies encompass vinyl acetate monomer, acrylic acid, and styrene-butadiene feedstocks. Tariff exposure on EU-bound shipments elevates compliance burden for US Gulf Coast producers. Distribution runs through railcar and tank truck bulk deliveries to large formulators, with intermediate bulk containers bridging mid-scale coating plants lacking rail access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as construction material demand accelerates from infrastructure spending cycles in China, India, and Germany. Building contractor procurement patterns normalize following pandemic-era volatility.
For Market Incumbents: Secure backward integration into captive ethylene feedstock positions to defend margin compression from naphtha-cracker volatility. Expand high-solids emulsion capacity in the Yangtze River Delta to capture China infrastructure demand. ECHA hazard classification tightening for residual monomers threatens non-compliant producers; analytical certification investment separates sustainable premium positioning from displacement risk. For New Entrants and Emerging Players: Technical service gaps in surfactant formulation expertise for high-solids emulsions offer white-space entry points where incumbents under-serve mid-size coating producers. Target India's Gujarat chemical belt where BIS certification requirements for low-VOC interior paints pull volume from solvent-based systems. Pursue toll-manufacturing partnerships with existing petrochemical complexes to bypass capital-intensive cracker investments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed construction-grade VAE specialists lacking REACH-compliant acrylic technology. Five-to-ten year viability favors integrated players with dual petrochemical and specialty resin capabilities. Monitor MIIT industrial standard enforcement in China as inflection signal for waterborne adhesive adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Feedstock | Gulf Coast petrochemical complexes anchor VAE resin cost positions against naphtha volatility. |
| REACH Certification Investment | ECHA residual monomer standards elevate analytical compliance barriers for EU architectural coatings. |
| High-Solids Emulsion Capacity Expansion | Yangtze River Delta manufacturing corridor captures China infrastructure adhesive demand. |
| Technical Service Partnership Program | Surfactant formulation expertise scarcity constrains mid-size coating producer high-solids adoption. |
| Bio-Based Acrylic Feedstock Development | Fermentation-derived pathways converge with petrochemical routes for premium sustainability positioning. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across architectural coating formulators, automotive tier-one paint shops, construction adhesive compounders, and paper coating converters. Primary fieldwork encompassed plant managers at integrated petrochemical complexes, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors. Secondary validation drew from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and EPA regulatory dockets. Bottom-up segment sizing triangulated against top-down macroeconomic drivers.
Across the analysis window, volume and value outputs reflect segmented modeling by chemistry type, end-use application, packaging configuration, and regional production hub. CAGRs were derived from regression-based trend extrapolation calibrated to historical capacity utilization and feedstock cost trajectories. Forecast inputs incorporated construction spending indices, automotive production schedules, and regulatory implementation timelines for VOC compliance mandates.
Forecasts assume regulatory continuity in EPA, REACH, and BIS regimes; material policy shifts would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Middle-East and Africa Thermoplastics Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
Middle East and Africa Poly Vinyl Chloride (PVC) Market
Polymers & Resins
Polymer Seals Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Polyether Amine Market
Polymers & Resins
Styrene-Butadiene-Styrene Block Copolymer Market
Polymers & Resins
Acrylic Polymer Emulsion Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
BPA-Free Epoxy Resins Market
Polymers & Resins
Canada Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Granular Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
Global Polymer Chameleons Market
Polymers & Resins
Bio-Based PU Market
Polymers & Resins
North America Polymer Emulsion Market
Polymers & Resins
Bio-Polybutadiene Market