
 Polyacrylate Market | 2026-2036
Polyacrylate Market Size, Share, and Industry Trends Forecast 2026-2036
Polyacrylate Market Outlook
The capital-intensity divergence between integrated petrochemical giants and specialty additive producers is collapsing as mid-scale competitors invest in backward polymerization capacity. BASF SE leverages its Ludwigshafen Verbund structure to sustain captive acrylic acid supply for polyacrylate derivatives. Nippon Shokubai anchors its position through proprietary high-purity ester technology developed at its Himeji research complex. Arkema competes via its Sartomer photopolymer-grade portfolio, differentiating on UV-curable oligomer performance.
Polyacrylate denotes a family of synthetic polymers derived from acrylic acid esters, typically synthesized through free-radical emulsion or solution polymerization to achieve molecular weights ranging from thousands to millions of Daltons, serving functions as thickeners, binders, superabsorbents, and rheology modifiers across industrial and consumer formulations. Emulsion polyacrylates dominate volume flows in architectural coatings where water-borne systems displace solvent alternatives under environmental mandates. Gel-grade superabsorbent polymers command premium positions in hygiene applications despite mature demand curves in developed economies. Solution polyacrylates retain specialized footholds in pressure-sensitive adhesives where precise solids content and viscosity control justify higher unit economics.
REACH registration requirements and EPA Toxic Substances Control Act notifications shape product entry pathways, forcing reformulation of residual monomer profiles and crosslinker chemistries. ECHA substance evaluation protocols and FDA indirect food contact clearances create divergent compliance cost structures across regional supply bases. Stakeholders must monitor regulatory pre-registration timelines and bio-based acrylic acid pilot scale-up announcements to anticipate feedstock cost inflections.
Market Dynamics
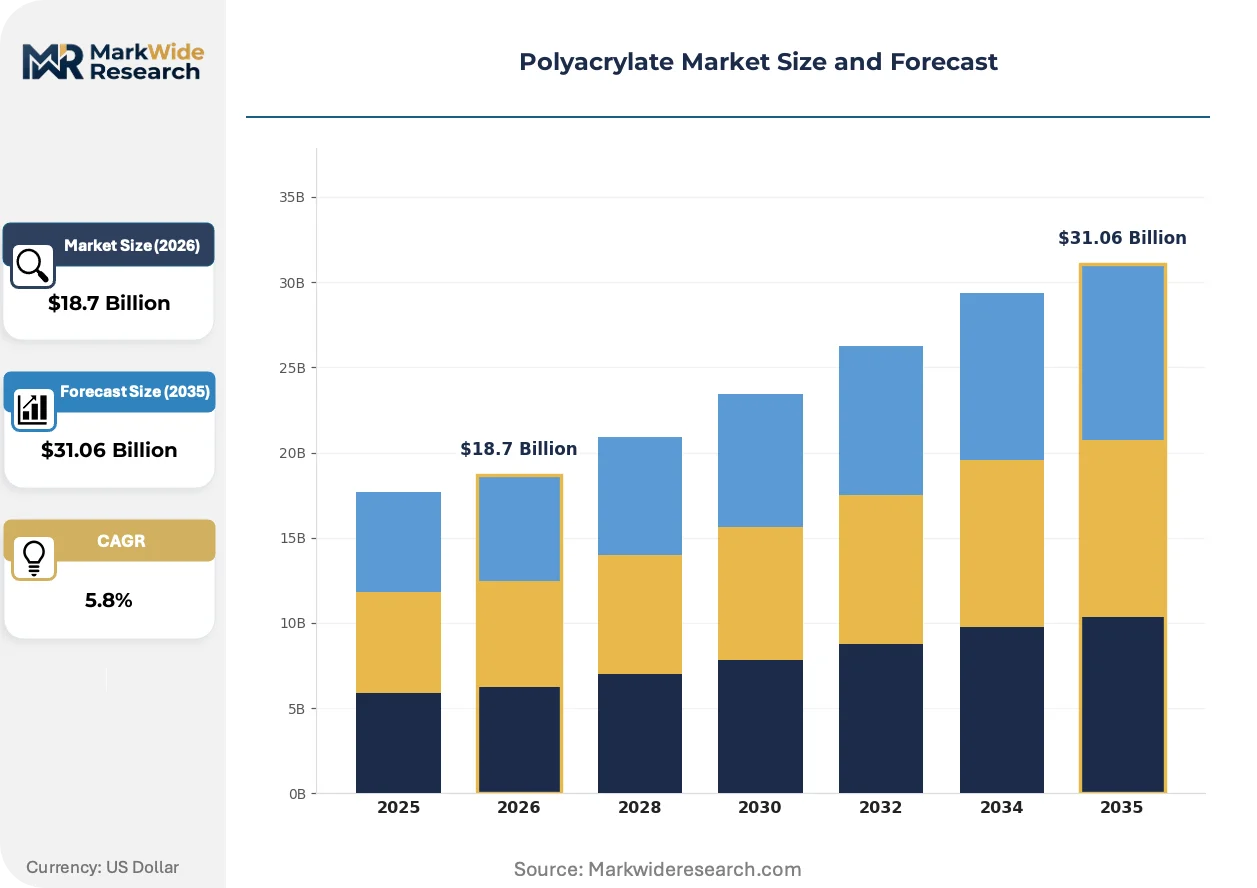
Water-borne coating mandates across automotive OEMs are compressing solvent-based acrylic demand while emulsion-grade capacity races to close the supply gap. REACH VOC limits and EPA TSCA notifications now determine which polymer architectures survive commercialization.
Growth Catalysts
- REACH VOC Limits:European automotive OEMs accelerate water-borne coating adoption, forcing reformulation of solvent-based systems and expanding emulsion polyacrylate pull-through.
- Hygiene Superabsorbent Demand:Gel-grade SAP consumption in adult incontinence products sustains premium pricing despite demographic saturation in developed economies.
- China Emulsion Capacity:Domestic polymerization investments reduce import dependency for architectural coating binders serving the country's construction sector.
Market Restraints
- Acrylic Acid Feedstock Volatility:Propylene oxide and acrylonitrile price swings transmit directly to polyacrylate unit economics, compressing margin predictability for non-integrated producers.
- German Supply Concentration:Ludwigshafen and Marl production clusters create single-point vulnerability for European derivative supply chains.
- Residual Monomer Thresholds:FDA indirect food contact clearances and ECHA substance evaluation protocols extend certification timelines by 18-24 months.
Strategic Opportunities
- India Construction Chemicals:Underpenetrated waterproofing and tile adhesive markets offer volume expansion as BIS standards formalize polymer-modified cement specifications.
- UV-Curable Oligomer Convergence:Photopolymer-grade polyacrylates intersect with digital printing growth in packaging and electronics fabrication.
- EU Green Deal Bio-Feedstock:Bio-based acrylic acid pilot scale-up creates first-mover positioning for renewable-attributed polymer certificates.
Industry Challenges
- Emulsion Polymerization Talent Gap:Free-radical kinetics expertise and particle size control specialization command wage premiums as experienced technologists retire.
- Crosslinker Chemistry Reconfiguration:N-methylolacrylamide replacement timelines compress as formaldehyde-free mandates tighten across hygiene and coating applications.
- Legacy Solvent System Integration:Coating manufacturers face capital-intensive line conversion to accommodate higher-solids water-borne formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyacrylate Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion, Solution, Dispersion, Gel Application: Agriculture, Coatings, Adhesives, Personal Care End User: Construction, Automotive, Textiles, Pharmaceuticals Packaging Type: Drums, Bags, Containers, Sachets |
| Companies Covered | Evonik Industries AG, Kao Corporation, BASF SE, Nippon Shokubai, Lucite International, Arkema, LG Chem, Sanyo Chemical, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyacrylate Market Strategic Shifts
Acrylic polymer architectures are fragmenting along performance-grade lines as regulatory thresholds harden and end-use specifications diverge. Three developmental vectors now dominate competitive investment priorities.
Core-shell emulsion technology with hard-soft phase separation is supplanting conventional homogeneous latex in premium architectural coatings. German and Chinese OEMs specify these structures for scrub resistance and block resistance in high-traffic interior applications. The shift compresses commodity emulsion margins while rewarding proprietary seed-and-feed polymerization expertise.
REACH authorization requirements for residual monomer content are forcing reformulation of conventional crosslinker packages. ECHA substance evaluation protocols now target NMA and other formaldehyde-releasing chemistries, compelling suppliers to validate glyoxal or aziridine alternatives. Coating and adhesive formulators in France and Italy face the steepest compliance cost escalations.
Specification-driven procurement now dominates large coating manufacturer relationships with polyacrylate suppliers. Volume commitments tie to certified low-VOC and low-odor performance tiers rather than commodity resin pricing. This behavioral shift is most visible in US architectural coating channels where EPA TSCA Section 5 pre-manufacture notifications create vendor qualification barriers.
Polyacrylate Market Segmentation
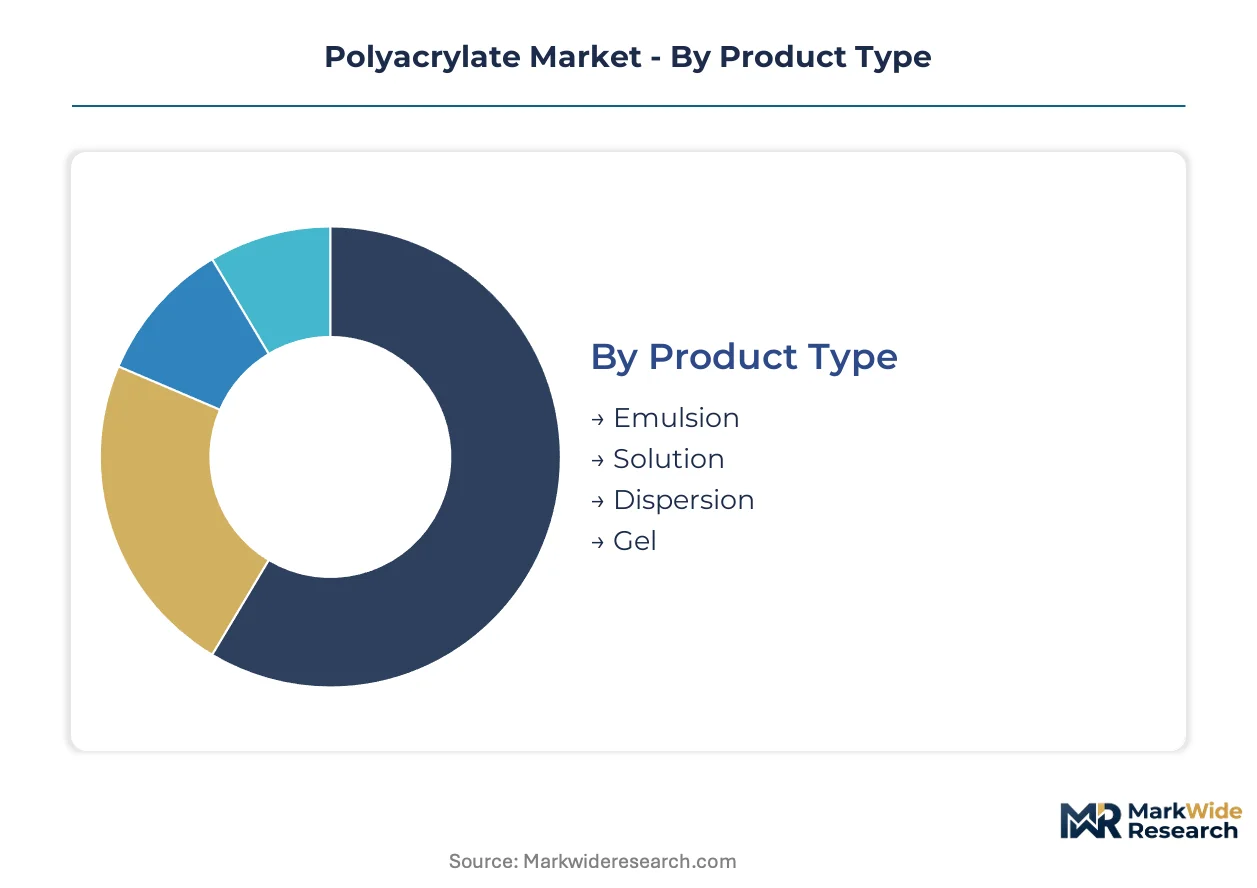
Polyacrylate value chains fracture along performance-grade lines where emulsion and gel technologies face divergent substitution threats from bio-based alternatives and inorganic thickeners. Specification-driven procurement now ties volume commitments to certified low-VOC and low-odor performance tiers rather than commodity resin pricing.
Product Type:
Emulsion-grade polyacrylates confront the most acute substitution pressure as water-borne alkyd and polyurethane dispersions capture share in premium architectural coatings.
- Emulsion:Free-radical polymerized latex particles with typical solids content of 40-60% serve as binders in water-borne architectural and automotive coatings. Demand concentrates in Germany and China where REACH VOC limits and domestic construction activity accelerate reformulation away from solvent systems.
- Gel:Crosslinked superabsorbent polymers with three-dimensional hydrophilic networks absorb hundreds of times their mass in aqueous fluids. Adult incontinence products in Japan and Western Europe sustain premium pricing despite demographic saturation, while emerging hygiene markets in Southeast Asia drive volume expansion.
- Solution:Dissolved polymers in organic solvents retain specialized footholds in pressure-sensitive adhesives where precise solids content control justifies higher unit economics.
- Dispersion:Aqueous polymer colloids with particle sizes below one micron serve textile finishing and leather coating applications requiring film-forming flexibility.
Emulsion anchors the volume base while gel gains share at the steepest rate.
Application:
Coating applications fragment across cost tiers where premium water-borne systems command certification premiums over commodity architectural grades.
- Coatings:Architectural, automotive OEM, and industrial protective formulations represent the dominant value pool. German automotive manufacturers specify core-shell emulsion structures for scrub resistance under tightening ECHA substance evaluation protocols.
- Adhesives:Pressure-sensitive, construction, and packaging bonding applications rely on solution and emulsion technologies for tack and shear strength balance. FDA indirect food contact clearances extend certification timelines by 18-24 months for packaging adhesive suppliers.
- Agriculture:Hydrogel soil conditioners and controlled-release fertilizer coatings reduce irrigation frequency in water-stressed cultivation regions.
- Personal Care:Rheology modifiers and film-formers in cosmetics and sunscreens demand low-odor, low-residual-monomer specifications that compress commodity supplier margins.
Coatings commands the revenue concentration while personal care expands most quickly on clean-label formulation trends.
End User:
Customer-type segmentation reveals divergent procurement maturity where construction specifiers lag automotive OEMs in outcome-based qualification criteria.
- Construction:Waterproofing membranes, tile adhesives, and cement modifiers drive emulsion consumption. India's BIS standards formalization for polymer-modified cement specifications creates volume expansion opportunities as compliance mandates spread.
- Automotive:OEM clearcoats and basecoats under REACH VOC mandates accelerate water-borne system adoption. Ludwigshafen and Marl production clusters supply European derivative demand with limited alternative sourcing.
- Textiles:Fabric finishing, printing binders, and nonwoven saturation applications require soft-hand and wash-durability performance that core-shell emulsion architectures address.
- Pharmaceuticals:Controlled-release tablet coatings and transdermal delivery systems demand pharmacopeial-grade polymers with validated residual monomer profiles.
Construction anchors volume pull-through while automotive drives specification escalation fastest.
Packaging Type:
Packaging configuration tracks supply chain concentration where drum and bulk container formats mirror integrated producer distribution economics.
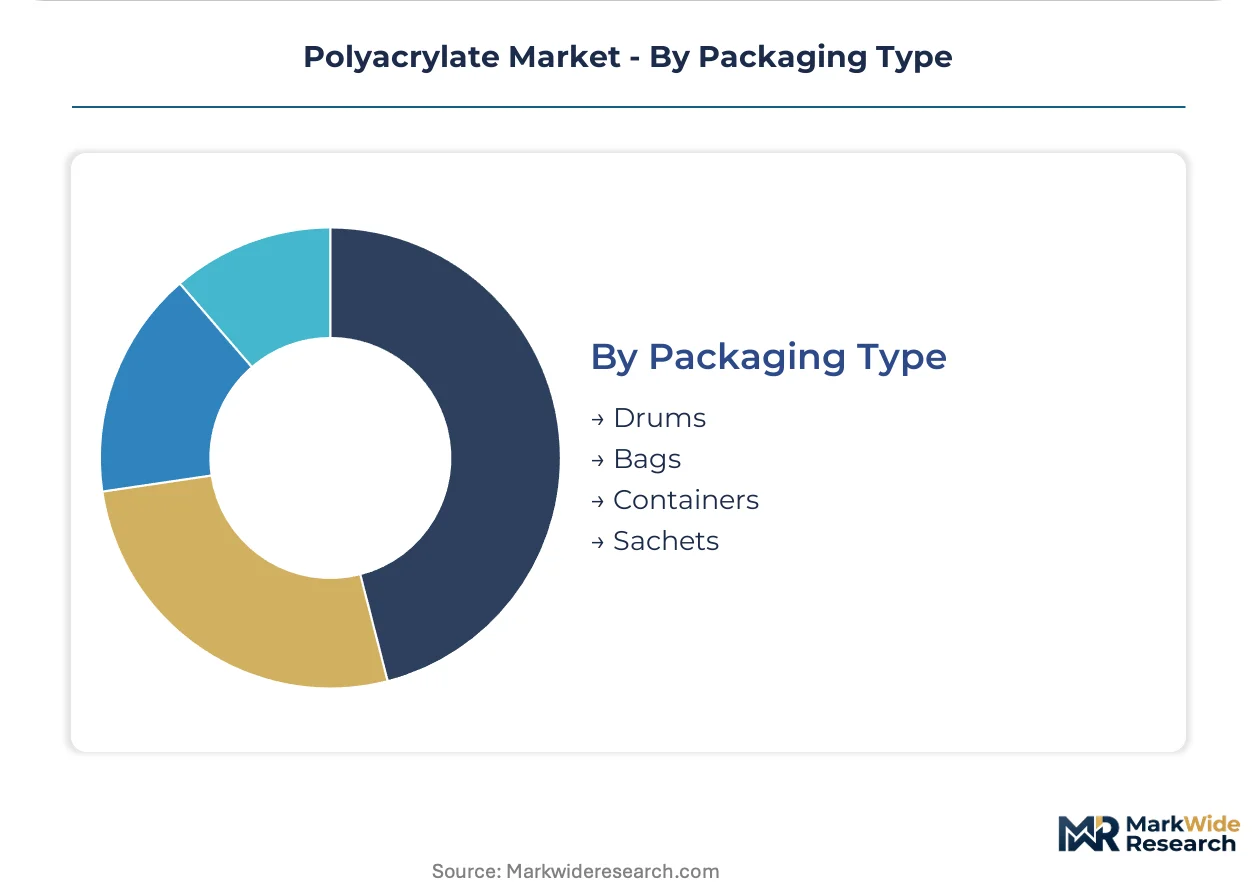
- Drums:Standard 200-liter steel and plastic drums serve mid-volume coating and adhesive manufacturers with established material handling infrastructure.
- Containers:Intermediate bulk containers and tank trucks supply large coating manufacturers with direct-to-line delivery systems that reduce handling costs.
- Bags:Multi-layer paper and polyethylene sacks package powdered superabsorbent polymers for hygiene product manufacturers.
- Sachets:Small-format flexible packaging serves laboratory sampling and specialty adhesive compounding operations.
Drums retain the installed base while containers capture share fastest on consolidation among large coating formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and India exhibit acute price sensitivity on standard emulsion grades, while German and Japanese automotive OEMs prioritize certified low-VOC performance over unit cost, creating a demand-elasticity divergence that shapes regional competitive positioning.
Germany
Automotive OEM clearcoat specifications drive premium emulsion consumption as manufacturers reformulate under REACH VOC limits. ECHA substance evaluation protocols now target residual monomer thresholds in coating applications. The Ludwigshafen and Marl production clusters supply European derivative demand with limited alternative sourcing, concentrating supply risk.
China
Domestic construction activity accelerates architectural coating binder consumption as developers shift to water-borne systems. MIIT environmental standards and dual carbon goals compress solvent-based acrylic margins. Yangtze River Delta polymerization investments reduce import dependency for emulsion-grade materials serving the country's building sector.
United States
EPA TSCA Section 5 pre-manufacture notifications create vendor qualification barriers for coating formulators seeking low-odor specifications. Architectural coating channels now tie volume commitments to certified performance tiers rather than commodity resin pricing. Texas and Louisiana petrochemical corridors anchor acrylic acid feedstock supply for derivative producers.
India
Waterproofing membrane and tile adhesive markets expand as BIS standards formalize polymer-modified cement specifications. CDSCO and BIS regulatory convergence extends certification timelines for construction chemical suppliers. Maharashtra and Gujarat manufacturing corridors attract emulsion capacity investments targeting compliance-driven specification upgrades.
Japan
Adult incontinence product demand sustains premium gel-grade superabsorbent pricing despite demographic saturation in developed economies. METI chemical safety assessments and JIS standards shape residual monomer thresholds for hygiene applications. The Kansai region's Himeji research complex anchors proprietary high-purity ester technology development.
Polyacrylate Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with backward integration into acrylic acid feedstock separating margin-stable players from exposed commodity producers. Mid-scale competitors now invest in captive polymerization capacity to collapse this divergence. Three archetypes dominate: petrochemical conglomerates with Verbund-style integration, specialty additive producers with proprietary ester technology, and Asian chemical groups with scale-driven emulsion operations. Capacity expansion and crosslinker chemistry reconfiguration represent the dominant competitive moves as formaldehyde-free mandates tighten.
Within the integrated petrochemical tier, BASF SE and Dow exemplify backward-controlled supply structures, while Nippon Shokubai occupies a position among specialty ester technology specialists. Arkema sits within the photopolymer-grade differentiation segment, representing UV-curable oligomer performance positioning. These three anchors illustrate how geographic and technological specialization fragments competitive dynamics across performance-grade lines.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Kao Corporation |
| BASF SE |
| Nippon Shokubai |
| Lucite International |
| Arkema |
| LG Chem |
| Sanyo Chemical |
| Dow |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day acrylic acid inventory cycles at European coating manufacturers compress margin buffers when propylene oxide prices spike, concentrating pricing power with Ludwigshafen-integrated suppliers while forcing toll-manufactured emulsion producers into spot market exposure. This lead-time asymmetry between captive feedstock holders and non-integrated compounders defines competitive economics across water-borne coating supply chains.
Pricing Analysis
Technical service contracts and reformulation support drive lifetime value more than resin unit pricing, with three-tier pricing structure across premium, standard, and economy levels stratifying by REACH certification grade and VOC compliance tier. Price differentiation separates ECHA-registered low-residual-monomer grades from commodity emulsions, with German automotive OEMs showing lowest sensitivity and Indian construction chemical distributors highest. Cost compression in standard emulsion tiers is intensifying because Yangtze River Delta capacity additions expand supply faster than REACH-mandated reformulation demand.
Supply Chain Analysis
Germany and China anchor emulsion-grade polyacrylate production, with Ludwigshafen Verbund structures and Yangtze River Delta polymerization investments supplying downstream coating and adhesive markets. Acrylic acid feedstock draws from Texas and Louisiana petrochemical corridors, while specialty ester inputs rest on Kansai region high-purity technology. Single-source vulnerability concentrates in Marl and Ludwigshafen clusters for European derivative supply. Distribution runs through intermediate bulk containers for large coating manufacturers and standard drums for mid-volume compounders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory fragmentation across REACH, EPA TSCA, and MIIT standards creates specialist niches where mid-scale producers capture share from commodity incumbents through certification-speed advantages.
For Market Incumbents: Fortify captive acrylic acid supply through backward integration into propylene oxide derivatives, prioritizing Ludwigshafen-style Verbund economics to offset margin pressure from Yangtze River Delta emulsion imports. Accelerate glyoxal and aziridine crosslinker validation to preempt formaldehyde-free mandate timelines in hygiene and coating applications. For New Entrants and Emerging Players: Lead with India construction chemicals as the most penetrable geography, where BIS standards formalization for polymer-modified cement specifications outpaces domestic emulsion capacity. Target waterproofing membrane and tile adhesive applications with technical service bundling that compensates for scale disadvantages against integrated German and Chinese suppliers. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because mid-scale emulsion producers with regional certification expertise face acquisition pressure from petrochemical conglomerates seeking REACH-compliant European positioning. The signal to watch is bio-based acrylic acid pilot scale-up announcements, which would recalibrate feedstock cost structures and first-mover valuations for renewable-attributed polymer certificates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | Captive propylene oxide supply insulates margin stability against feedstock volatility at Ludwigshafen-scale operations. |
| Crosslinker Chemistry Reconfiguration | Glyoxal and aziridine validation accelerates formaldehyde-free compliance ahead of ECHA substance evaluation protocols. |
| Core-Shell Emulsion Capacity Expansion | Hard-soft phase separation technology captures premium architectural coating specifications from German and Chinese OEMs. |
| Long-term Supply Agreement with Automotive OEMs | Volume commitments tied to REACH VOC certification reduce spot market exposure for emulsion-grade producers. |
| Joint Venture for Bio-Based Feedstock Development | EU Green Deal alignment positions first-movers for renewable-attributed polymer certificates in European markets. |
Study Parameters
Two parallel data streams informed the analysis: structured conversations with plant managers at emulsion polymerization facilities, procurement leads at downstream coating OEMs, and technical R&D directors specializing in free-radical kinetics, alongside secondary validation through customs and trade data, ACC and Cefic industry reports, and SEC 10-K filings from listed chemical producers. Bottom-up capacity and demand modeling triangulated against top-down macroeconomic indicators across the analysis window.
Across the projection horizon, the analytical framework modeled polyacrylate segmentation by grade tier, end-use industry, packaging format, and regional production hub, with CAGRs derived from elasticity-adjusted demand curves and capacity utilization assumptions. Feedstock cost trajectories, regulatory pre-registration timelines, and construction activity indices served as primary forecast inputs.
The analysis sits within stated boundaries; outcomes outside REACH authorization timelines, propylene oxide price stability, and construction sector demand patterns would require recalibration. Forecasts reflect documented assumptions regarding ECHA substance evaluation protocols and MIIT environmental standard enforcement. Recalibration cycles align with material shifts in bio-based acrylic acid commercialization and regional capacity addition announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
PCR Polyolefins Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Polyphthalamide (PPA) Resin Market
Polymers & Resins
Polyisobutylene (PIB) Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
Marine-grade Polyurethane Market
Polymers & Resins
Polyurethanes (PU) Market
Polymers & Resins
Global Thermoset Resin Market
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
Middle East Polymer Market
Polymers & Resins
Flexible Epoxy Resin Market
Polymers & Resins
Middle-East and Africa Fluoropolymers Market
Polymers & Resins
Global Engineering Plastic Market
Polymers & Resins
Global Corrosion Resistant Resin Market
Polymers & Resins
Concrete Containing Polymer Market
Polymers & Resins
Polymer Filler Market