
 Solder Paste for Mini LED Market | 2026-2036
Solder Paste for Mini LED Market Size, Share, and Industry Trends Forecast 2026-2036
Solder Paste for Mini LED Market Insights
Asset-light contract manufacturing and equipment leasing is narrowing the capital barrier for mid-tier solder paste suppliers to serve Mini LED chip-on-board lines. Indium Corporation leverages its indium supply chain to sustain specialty alloy pricing power across East Asian display fabs. Senju Metal Industry anchors its position through integrated flux chemistry and solder sphere production for ultra-fine pitch applications.
Solder paste for Mini LED is a precision-engineered suspension of solder alloy powder, flux medium, and rheology modifiers formulated for stencil printing at 50–100 micron apertures, enabling reliable interconnection of Mini LED chips onto substrates during reflow. The product serves the critical function of forming thermally stable, electrically conductive joints between thousands of microscopic emitters and driver circuitry in high-density display backlights. Lead-free formulations now dominate volume shipments as RoHS-aligned OEM procurement hardens across consumer electronics supply chains, while water-soluble variants capture premium positioning in medical and aerospace display tiers where residue cleanliness standards exceed no-clean capabilities. Surface Mount Technology application lines absorb the largest share of paste volume as Mini LED backlight units displace conventional edge-lit configurations in television and monitor panels.
EPA hazardous substance reporting and OSHA workplace exposure limits shape formulation decisions for U.S.-based electronics manufacturers, while China's GB standards and MEE environmental enforcement tighten volatile organic compound thresholds in solder flux systems. REACH substance restrictions and CE marking requirements in Europe filter market access for non-compliant Asian suppliers. Stakeholders must monitor evolving alloy compositions as thermal management demands from higher-brightness Mini LED architectures test the reliability boundaries of existing SAC305 and low-silver alternatives.
Market Dynamics
Stencil printing at 50–100 micron apertures is compressing yield tolerances across Mini LED backlight production, forcing paste suppliers to co-develop rheology profiles with display panel fabs or forfeit qualification slots.
Growth Catalysts
- RoHS-aligned OEM procurement:Consumer electronics brands now mandate lead-free formulations across backlight unit supply chains, eliminating legacy tin-lead alternatives from qualified vendor lists.
- Chip-on-board line expansion:Display panel manufacturers in Shenzhen and Wuhan are scaling COB capacity for television and monitor backlights, pulling precision solder paste volumes upward.
- Water-soluble paste premiumization:Medical and aerospace display tiers specify residue cleanliness standards that exceed no-clean capabilities, creating parallel demand for specialized flux chemistry.
Market Restraints
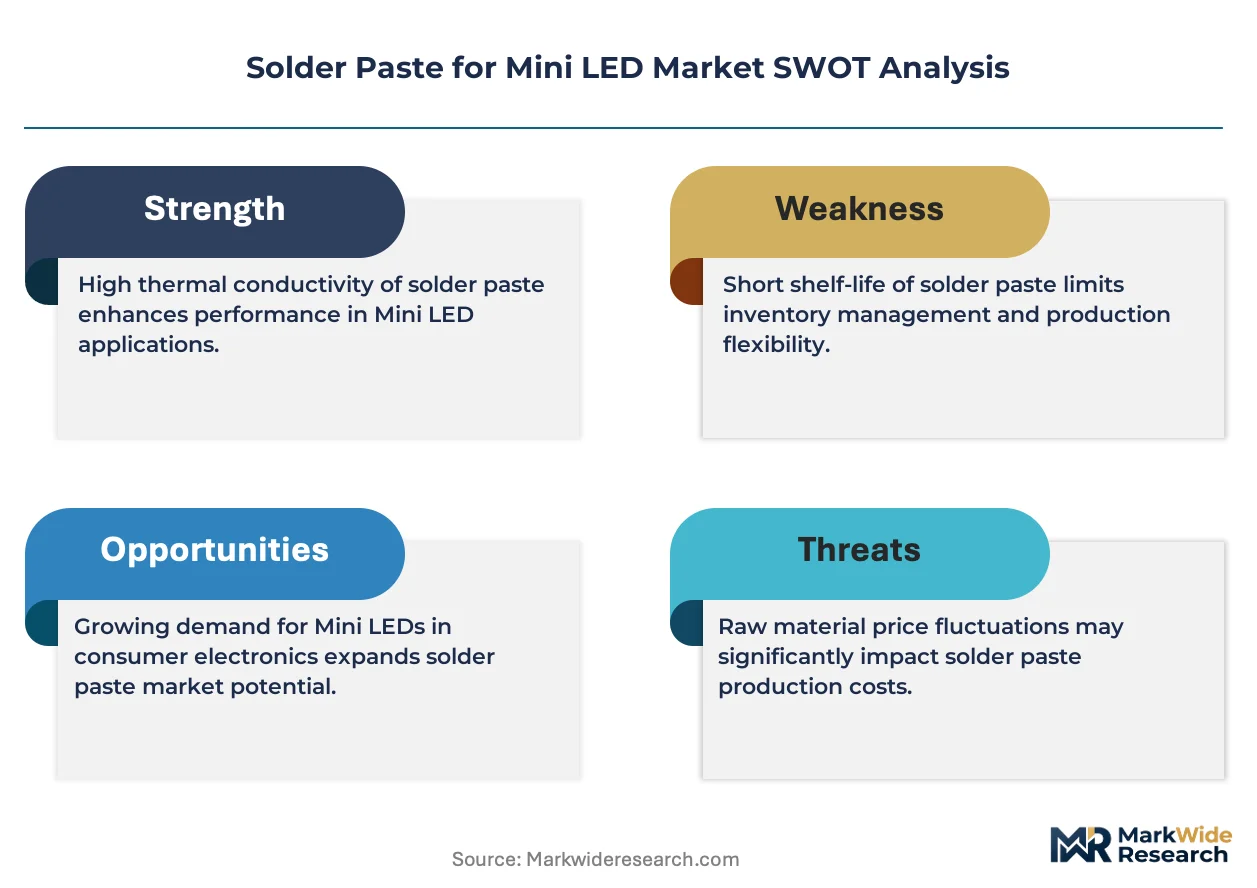
- Indium supply concentration:Specialty alloy pricing power rests with a narrow upstream base, exposing formulators to raw material volatility when indium concentrates in specific mining jurisdictions.
- Flux VOC thresholds:China's MEE environmental enforcement and GB standards are tightening volatile organic compound limits, requiring costly reformulation of established paste systems.
- SAC305 reliability boundaries:Higher-brightness Mini LED architectures are testing thermal cycling performance of standard SAC305 compositions, limiting deployment in premium display tiers without silver-content increases.
Strategic Opportunities
- Asset-light contract manufacturing:Equipment leasing models are narrowing capital barriers for mid-tier suppliers to serve Mini LED chip-on-board lines without full fab ownership.
- Integrated flux-sphere production:Captive control over solder sphere manufacturing paired with proprietary flux chemistry enables tighter particle size distribution for ultra-fine pitch applications.
- Dual carbon alignment:China's dual carbon goals are accelerating low-temperature reflow paste development, opening formulation partnerships with domestic display panel producers.
Industry Challenges
- Rheology engineering talent scarcity:Formulators struggle to recruit specialists capable of optimizing thixotropic behavior for 50-micron stencil apertures at production speeds.
- Cross-border certification timelines:REACH substance restrictions and CE marking requirements in Europe filter market access, creating 12–18 month qualification delays for Asian suppliers.
- Reflow profile standardization gaps:Absence of unified thermal profiling protocols across display fabs forces paste suppliers to maintain multiple formulation variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solder Paste for Mini LED Market |
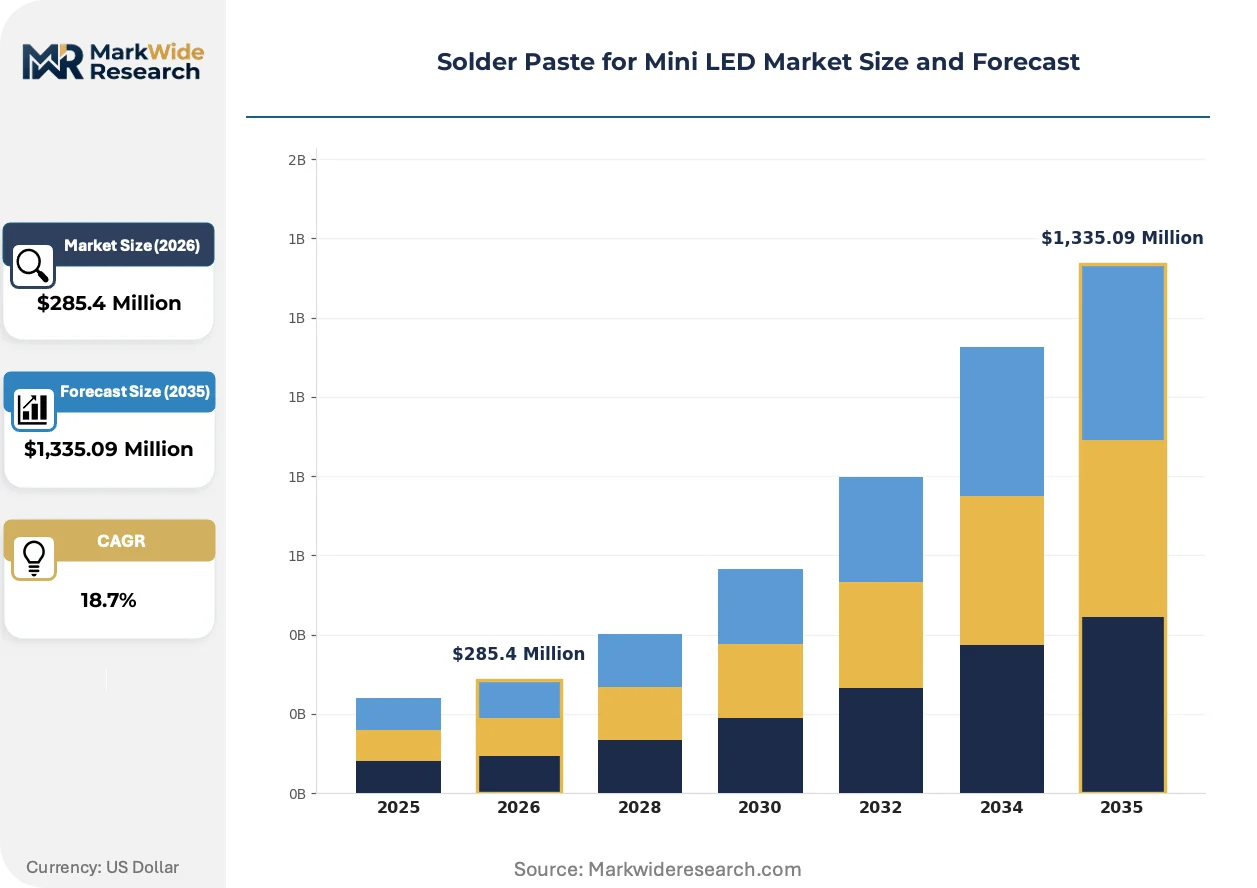
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $1,335.09 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lead-Free, No-Clean, Water-Soluble, High-Temperature Application: Surface Mount Technology, Discrete Components, IC Assembly, PCB Assembly Formulation: Paste, Gel, Liquid, Powder End User: Electronics Manufacturers, Contract Manufacturers, OEMs, Repair Services |
| Companies Covered | Henkel, Indium Corporation, Senju Metal Industry, MacDermid Alpha Electronics Solutions, Harima Chemicals, Heraeus, Nihon Superior, AIM Solder, Inventec, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solder Paste for Mini LED Market Trends and Innovations
Formulation science is converging with precision deposition equipment to enable sub-100-micron interconnect reliability at mass-production throughputs previously reserved for semiconductor packaging.
Low-temperature solder alloys incorporating bismuth and indium are hybridizing thermal management capabilities with lead-free compliance requirements. Television manufacturers adopting these compositions for Mini LED backlights are reducing reflow peak temperatures by 20–30°C versus SAC305. This temperature reduction is hybridizing process windows, enabling polyester-based flexible substrates previously excluded from high-density backlight designs.
REACH substance restrictions in Europe are hardening compliance verification across imported solder paste shipments. ECHA candidate list updates are forcing Asian suppliers to requalify flux activator chemistries ahead of sunset dates. Medical display manufacturers in Germany and Switzerland are responding by consolidating procurement around pre-certified European distributors with documented substance traceability.
Display panel fabs are consolidating qualified paste suppliers from six-plus vendors to two or three per production site. This concentration is compressing switching flexibility but securing volume commitments that justify co-development investments. The pattern is most visible in South Korea and Taiwan, where backlight unit integrators now specify single-source paste qualification for new product ramps.
Solder Paste for Mini LED Market Segmentation
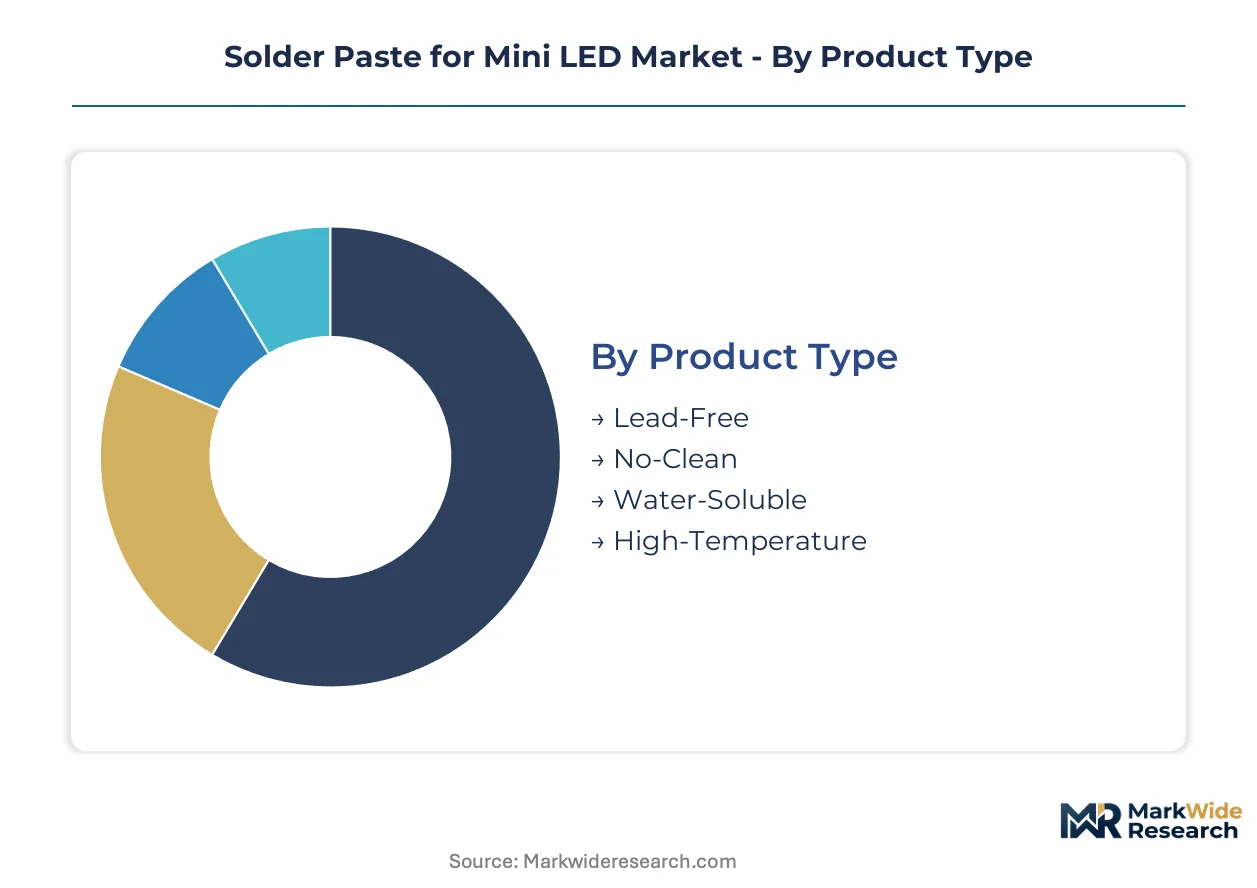
Mini LED solder paste specifications diverge sharply across thermal profiles, residue standards, and deposition methods. Understanding these dimensional splits reveals where formulation investments concentrate and which technical requirements command premium positioning.
Product Type:
Cost tier determines qualification barriers and margin structure across solder paste categories.
- Lead-Free:SAC305 and low-silver variants dominate television and monitor backlight procurement as RoHS-aligned OEM mandates eliminate tin-lead alternatives from qualified vendor lists. Shenzhen and Wuhan display panel fabs now specify lead-free exclusively for new COB line ramps.
- No-Clean:Mildly activated rosin or resin-based flux systems leave benign post-reflow residues suitable for consumer electronics where ionic contamination standards remain moderate. Volume shipments concentrate in television backlight units where downstream cleaning steps add unacceptable cycle time.
- Water-Soluble:Aggressive organic acid activators enable pristine residue removal through aqueous cleaning, satisfying medical display and aerospace tier requirements where ionic cleanliness thresholds exceed no-clean capabilities.
- High-Temperature:Gold-tin and other refractory alloys serve niche applications demanding service temperatures beyond SAC305 limits, typically in automotive display modules or harsh-environment industrial panels.
Lead-Free commands the established base. The steepest expansion runs through Water-Soluble as medical and aerospace display tiers harden cleanliness specifications.
Application:
Process technology determines rheology requirements and aperture design constraints for stencil printing systems.
- Surface Mount Technology:Stencil printing at 50–100 micron apertures absorbs the largest paste volumes as Mini LED backlight units displace conventional edge-lit configurations in premium television panels. Shenzhen-based fabs are scaling SMT-dedicated COB lines specifically for this transition.
- Discrete Components:Individual LED emitter attachment onto substrates demands precise volume control for thermal pad coverage without bridging, particularly critical for high-density matrix backlights.
- IC Assembly:Flip-chip and chip-scale package interconnections require ultra-fine pitch sphere distributions and specialized flux activators to manage oxide reduction on copper pillar bumps.
- PCB Assembly:Driver board integration for backlight units combines standard SMT with selective soldering steps, demanding paste compatibility across mixed process flows.
Surface Mount Technology anchors volume demand. Discrete Components is climbing the fastest as chip-on-board architectures proliferate in direct-lit Mini LED designs.
Formulation:
Physical state governs deposition equipment compatibility and process window flexibility across manufacturing environments.
- Paste:Thixotropic suspensions of alloy powder and flux medium formulated for stencil printing at production throughputs exceeding 100,000 components per hour in high-volume display fabs.
- Gel:Higher viscosity formulations enable needle dispensing and jetting applications where stencil tooling is impractical, common in prototype and low-volume repair scenarios.
- Liquid:Low-viscosity flux vehicles for spray or dip coating of preforms, serving specialized thermal interface applications rather than standard die-attach.
- Powder:Unfluxed alloy spheres for preform manufacturing or custom paste compounding, capturing value in captive formulation operations rather than merchant markets.
Paste holds the volume base. Gel is gaining share fastest as equipment leasing models enable mid-tier contract manufacturers to serve prototype and NPI volumes without full stencil infrastructure.
End User:
Customer type shapes procurement patterns, technical service requirements, and pricing negotiation leverage.
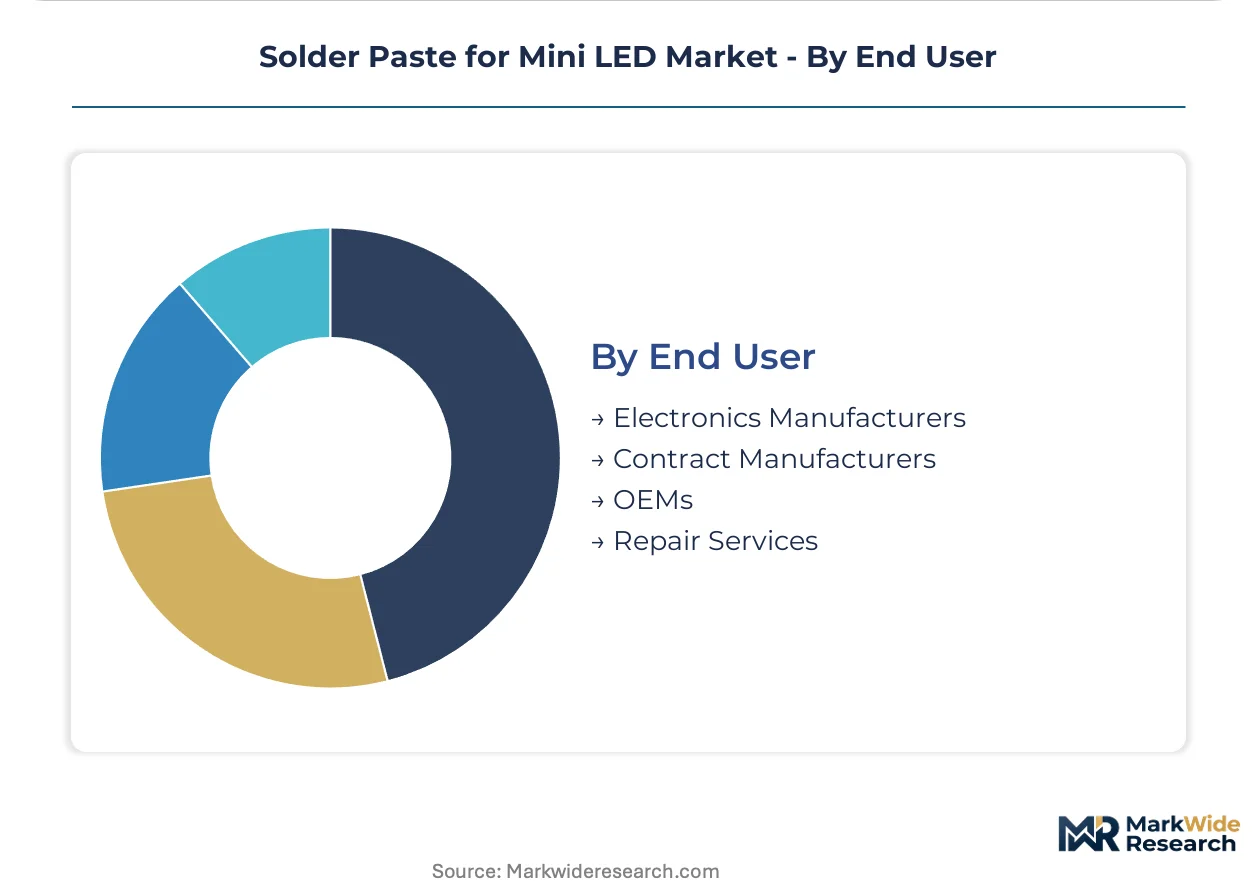
- Electronics Manufacturers:Vertically integrated display panel producers in South Korea and Taiwan maintain captive solder paste qualification teams, consolidating suppliers to two or three per production site to secure volume commitments.
- Contract Manufacturers:Asset-light EMS providers leverage equipment leasing to serve Mini LED chip-on-board lines without full fab ownership, narrowing capital barriers for mid-tier paste suppliers.
- OEMs:Television and monitor brands increasingly specify paste qualifications directly, bypassing backlight unit integrators to enforce RoHS compliance and substance traceability standards.
- Repair Services:Aftermarket refurbishment of premium displays drives small-lot demand for compatible paste formulations, typically sourced through authorized distributor networks rather than direct from formulators.
Electronics Manufacturers anchor procurement volume. Contract Manufacturers represent the steepest expansion trajectory as COB capacity scales across Shenzhen and Wuhan without captive paste formulation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government technology incentives and environmental enforcement are redrawing competitive geography for Mini LED solder paste procurement. Market access now hinges on alignment with regional substance regulations and proximity to display panel manufacturing clusters.
China
Domestic dual carbon goals are accelerating low-temperature reflow paste partnerships between formulators and display producers. MEE enforcement of GB standards on volatile organic compounds is forcing costly flux system reformulations. Shenzhen and Wuhan host the densest concentrations of chip-on-board capacity scaling for television and monitor backlights.
South Korea
Backlight unit integrators are consolidating qualified paste suppliers from six-plus vendors to two or three per production site. MFDS chemical substance notification requirements intersect with EU REACH alignment for export-oriented display manufacturers. Seoul Capital Area fabs are driving single-source paste qualification mandates for new product ramps.
Japan
METI industrial standards and JIS certification frameworks shape alloy composition approvals for domestic electronics manufacturers. Formulators face compressed development cycles as television brands specify paste qualifications directly. Kyushu and Chubu regions maintain specialized flux chemistry R&D operations serving precision deposition equipment makers.
Germany
ECHA candidate list updates are forcing Asian suppliers to requalify flux activator chemistries ahead of sunset dates. Medical display manufacturers in Bavaria and Baden-Württemberg are consolidating procurement around pre-certified European distributors with documented substance traceability. KBA chemical safety protocols add secondary compliance layers for automotive display module applications.
United States
EPA hazardous substance reporting and OSHA workplace exposure limits shape formulation decisions for domestic electronics manufacturers. Television brands headquartered in California and Texas increasingly enforce RoHS compliance through direct paste qualification rather than backlight unit integrator mediation. Pacific Northwest and Greater Boston clusters concentrate prototype and NPI volumes for aerospace display tiers.
Solder Paste for Mini LED Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a structure consolidating around integrated supply chain capabilities. The vendor base separates into three strategic archetypes: upstream alloy producers with captive indium supply, integrated flux-sphere manufacturers, and asset-light contract formulators serving regional COB lines. Dominant competitive moves include backward integration into solder sphere production and geographic co-location partnerships with display panel fabs.
Among integrated Japanese manufacturers, Senju Metal Industry and Harima Chemicals exemplify the flux-sphere integration archetype. Indium Corporation anchors the specialty alloy tier through upstream control over indium concentrate sourcing. Henkel occupies a position bridging European regulatory compliance expertise with Asian manufacturing scale.
| Leading Market Players |
|---|
| Henkel |
| Indium Corporation |
| Senju Metal Industry |
| MacDermid Alpha Electronics Solutions |
| Harima Chemicals |
| Heraeus |
| Nihon Superior |
| AIM Solder |
| Inventec |
| Others |
Pricing and Supply Chain Analysis
Indium concentrate sourcing from Chinese and South Korean mining jurisdictions anchors pricing power at the alloy tier, concentrating margin capture upstream while downstream formulators absorb volatility through long-term offtake contracts.
Pricing Analysis
Certification level creates the primary spread, with REACH-compliant and RoHS-aligned formulations commanding premium positioning over standard consumer-grade alternatives. Three-tier pricing structure separates medical-aerospace specifications from television backlight tiers and economy repair-grade products. Cost compression in standard SAC305 formulations is intensifying because Shenzhen and Wuhan display fabs are consolidating qualified suppliers to two or three per site. Contract manufacturers exhibit the highest price sensitivity due to equipment leasing models and thin margin structures, while vertically integrated panel producers in South Korea and Taiwan show lowest sensitivity through captive volume commitments.
Supply Chain Analysis
Extended payment terms from display panel fabs to solder paste suppliers are stretching working capital cycles, forcing formulators to access supply-chain finance facilities or forfeit qualification slots. Raw material sourcing draws from Chinese indium concentrates, Japanese flux chemistry precursors, and Malaysian solder sphere production. The supply chain rests on single-source vulnerability at the indium mining tier, where jurisdictional concentration exposes formulators to export restriction risk. Distribution runs through authorized distributor networks in Europe and direct technical sales teams in East Asian display clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mini LED backlight demand is recovering from panel inventory corrections, with television and monitor brand procurement cycles driving the next capacity investment wave.
For Market Incumbents: Build formulation IP moats around low-temperature bismuth-indium alloys and proprietary flux activator chemistries. Backward integration into solder sphere production tightens particle size distribution control for 50-micron aperture applications. Capacity addition in Wuhan and Shenzhen secures proximity to scaling chip-on-board lines before regional competitors qualify. For New Entrants and Emerging Players: Geographic underpenetration in European medical display manufacturing offers white-space access through REACH pre-certified distributor partnerships. Water-soluble paste specifications for German and Swiss aerospace tiers remain underserved by Asian suppliers facing ECHA requalification delays. Equipment leasing models enable contract manufacturing entry without full stencil infrastructure ownership. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across asset-light contract formulation services, improving return profiles for mid-tier entrants. Acquisition targets should profile integrated flux-sphere manufacturers with established Mini LED chip-on-board qualifications. Monitor ECHA candidate list sunset dates as inflection indicators for European market access windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Solder Sphere Production | Captive sphere manufacturing tightens particle distribution for ultra-fine pitch stencil printing. |
| REACH Pre-Certification Partnership | European distributor alliances bypass 12-18 month Asian supplier qualification delays. |
| Low-Temperature Alloy Development | Bismuth-indium formulations enable polyester flexible substrates for Mini LED backlights. |
| Geographic Co-Location with Display Fabs | Shenzhen and Wuhan proximity secures volume commitments from scaling COB lines. |
| Water-Soluble Paste Premiumization | Medical and aerospace tier specifications exceed no-clean residue standards. |
Research Methodology
A spread of perspectives from solder paste formulators, display panel procurement directors, stencil equipment manufacturers, and flux chemistry R&D heads converged on the working assumptions. Primary fieldwork combined structured interviews with technical directors at East Asian display fabs and European medical device manufacturers. Secondary validation drew from SEC filings of listed electronics materials suppliers, ECHA substance restriction updates, Chinese GB standards documentation, and customs trade data for indium concentrate flows. Bottom-up volume estimates from individual COB line capacities triangulated against top-down display panel production forecasts.
Demand-supply balance modeling anchored projections across the analysis window, with segmentation dimensions spanning product type, application process, physical formulation state, and end-user procurement archetype. CAGRs were derived from fitted growth curves calibrated to historical adoption rates of prior backlight technology transitions. Industry-specific inputs included Mini LED die attach density per backlight unit, solder paste consumption per square meter of display panel, and reflow temperature reduction trajectories from low-temperature alloy adoption.
Practitioners should monitor ECHA candidate list expansions, Chinese MEE enforcement intensity on VOC thresholds, and indium concentrate export policy shifts for early signals. Forecasts reflect documented assumptions about display panel fab capacity ramps and RoHS procurement mandate diffusion. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Digital Pulse Mixer Market
Electronic Components
Asia-Pacific USB Retimer Market
Electronic Components
Fuse Bases Market
Electronic Components
Americas MPU Market
Electronic Components
Microspeaker Market
Electronic Components
Serial Device Servers Market
Electronic Components
Single Layer Capacitors Market
Electronic Components
North America MLCC Market
Electronic Components
Plastics in Consumer Electronics Market
Electronic Components
Trackpad Market
Electronic Components
Stretchable Conductors in Electronics Market
Electronic Components
USB Retimer Market
Electronic Components
Battery Holders Market
Electronic Components
Aluminum Electrolytic Capacitor Market
Electronic Components
Electric Vehicle (EV) Electronic Components Market
Electronic Components
Global Industrial Media Converters Market