
 DVB/SAT Remote Controls Market | 2026-2036
DVB/SAT Remote Controls Market Size, Share, and Industry Trends Forecast 2026-2036
DVB/SAT Remote Controls Market Analytics
Voice-control specification tiers is reorganizing procurement priorities among broadcast operators and pay-TV platforms. Universal Electronics leverages its programmable platform architecture to sustain long-term operator contracts across North American and European cable providers. Ruwido differentiates through Austrian-engineered precision input systems that dominate premium-tier hospitality and healthcare television deployments. Philips extends its brand strength in mass-market retail channels where consumers replace legacy IR units with universal alternatives.
DVB/SAT remote controls are handheld human-interface devices that translate user commands into infrared, radio frequency, Bluetooth, or Wi-Fi signals for set-top boxes and satellite receivers, typically operating on 2.4 GHz bands with button-actuated membrane or mechanical switch assemblies. Their primary commercial purpose is to enable channel navigation, electronic program guide access, and interactive service engagement across television distribution networks. RF Remote and Bluetooth Remote categories are capturing margin pools as operators phase out line-of-sight infrared dependence, while Home Entertainment applications remain the volume anchor and Professional AV commands higher per-unit pricing through customized fleet deployments. Infrared technology segments face structural compression as radio frequency variants absorb mid-tier replacement demand.
The Federal Communications Commission governs RF emission parameters for remote controls sold in the United States, while the European Telecommunications Standards Institute certifies interoperability across member state broadcast networks. CE marking requirements under EU radio equipment directives shape product access by mandating electromagnetic compatibility and spectral efficiency testing. Stakeholders must monitor evolving spectrum reallocation decisions and energy-efficiency mandates that could force hardware redesigns before next procurement cycles conclude.
Market Dynamics
Pay-TV operators across Europe are retiring infrared fleets and mandating Bluetooth Low Energy and voice-enabled remotes, compressing replacement cycles from seven years to four years and forcing component suppliers to requalify RF chipset portfolios.
Growth Catalysts
- EU F-Gas Regulation:The directive accelerates adoption of lower-power RF transceivers by penalizing high-GWP refrigerants in manufacturing processes, pushing remote control assemblers toward energy-efficient semiconductor architectures.
- German broadcast infrastructure:Deutschland's DVB-T2 and satellite modernization programs are triggering fleet-wide remote replacements among public and private operators, concentrating demand in Central Europe's largest television market.
- Voice-control specification tiers:Operator procurement committees now require natural language processing capability as a baseline qualification, expanding addressable silicon content per unit and favoring suppliers with programmable firmware platforms.
Market Restraints
- Lithium coin cell volatility:CR2032 and CR2025 battery supply concentrates in East Asian chemical processors, exposing European remote manufacturers to input cost swings and forced-air freight premiums during contract negotiations.
- Bluetooth SIG certification backlog:The qualification queue for RF protocol compliance now extends sixteen weeks at authorized test houses, delaying product launches and freezing engineering resources on legacy redesigns.
- Smartphone universal remote substitution:IR blaster-equipped handsets and Wi-Fi bridge applications are capturing casual replacement demand among cord-cutter households, eroding standalone remote attach rates in retail channels.
Strategic Opportunities
- Nordic hospitality retrofit wave:Sweden and Norway are mandating accessibility-compliant television interfaces in hotel and healthcare settings, creating specification-driven demand for large-button, voice-activated remote variants with extended warranty terms.
- Energy-efficiency directive tailwinds:The EU Ecodesign for Energy-Related Products framework is tightening standby power limits, rewarding manufacturers who integrate sub-100nA sleep-mode microcontrollers into remote architectures.
- Matter protocol convergence:The unifying smart home standard enables single-remote control across set-top boxes, streaming sticks, and connected displays, allowing suppliers to displace multiple legacy remotes per household.
Industry Challenges
- RF engineering talent scarcity:Competent Bluetooth stack firmware developers command premium compensation in semiconductor hubs, forcing remote control OEMs to outsource core radio design or accept longer development timelines.
- Legacy IR integration complexity:Hybrid remotes must maintain backward compatibility with aging set-top box installed bases, requiring dual-transmitter architectures that increase BOM cost and mechanical design constraints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | DVB/SAT Remote Controls Market |
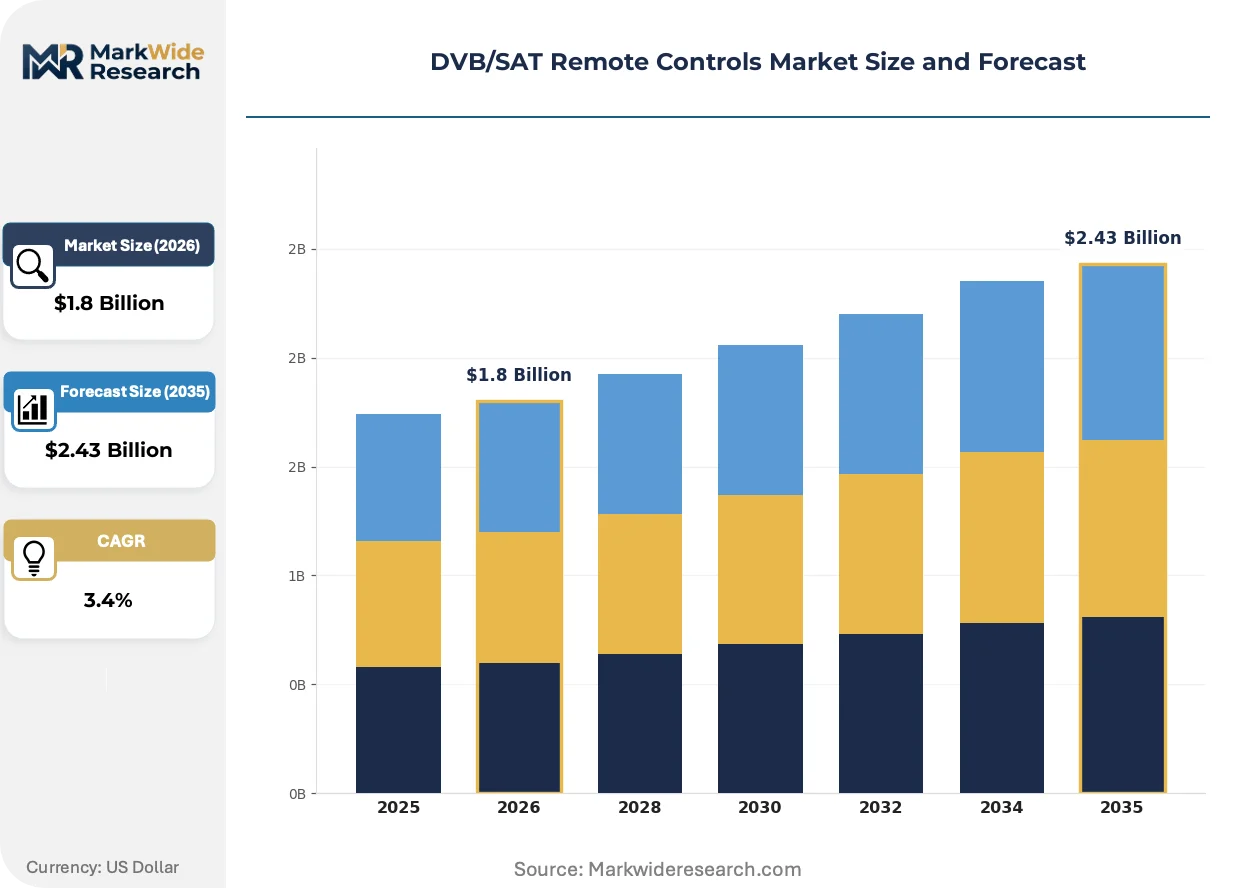
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.43 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: IR Remote, RF Remote, Bluetooth Remote, Wi-Fi Remote Application: Home Entertainment, Professional AV, Test Equipment, Industrial Automation Technology: Infrared, Radio Frequency, Bluetooth, Wi-Fi End User: Residential Users, Commercial Establishments, Institutions, Broadcast Networks |
| Companies Covered | Universal Electronics, Ruwido, SMK-Link Electronics, Philips, Logitech International, Crestron Electronics, HBC-radiomatic GmbH, Sony Corporation, LG Electronics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
DVB/SAT Remote Controls Market Evolving Landscape
Interface modalities and connectivity standards are diverging rapidly as operators, hospitality chains, and retail consumers pursue incompatible optimization paths. The market is splitting across voice-first, accessibility-first, and cost-first design philosophies.
Bluetooth Low Energy with direction-finding capability is fragmenting the premium remote segment by enabling spatial awareness for set-top box location without line-of-sight. German and Austrian cable operators are piloting these units in multi-room DVR deployments. The technology is fragmenting vendor consolidation by rewarding specialized RF module suppliers over integrated infrared-focused incumbents.
The EU F-Gas Regulation and accompanying Ecodesign directives are mandating lower standby consumption and restricted substance profiles for consumer electronics accessories. Manufacturers must redesign power management circuits and eliminate specific flame retardants from PCB assemblies. German quality-focused brands are responding fastest, leveraging existing environmental compliance infrastructure to accelerate certification timelines.
Hotel chains and assisted-living facilities are unbundling remote procurement from television hardware purchases, establishing direct supplier relationships for customized fleet deployments. This disintermediation is compressing margins for traditional set-top box bundlers while opening specification influence to accessibility consultants and interior design firms. The Netherlands and Belgium display the most advanced unbundling, with procurement committees now issuing standalone remote RFPs.
DVB/SAT Remote Controls Market Segmentation
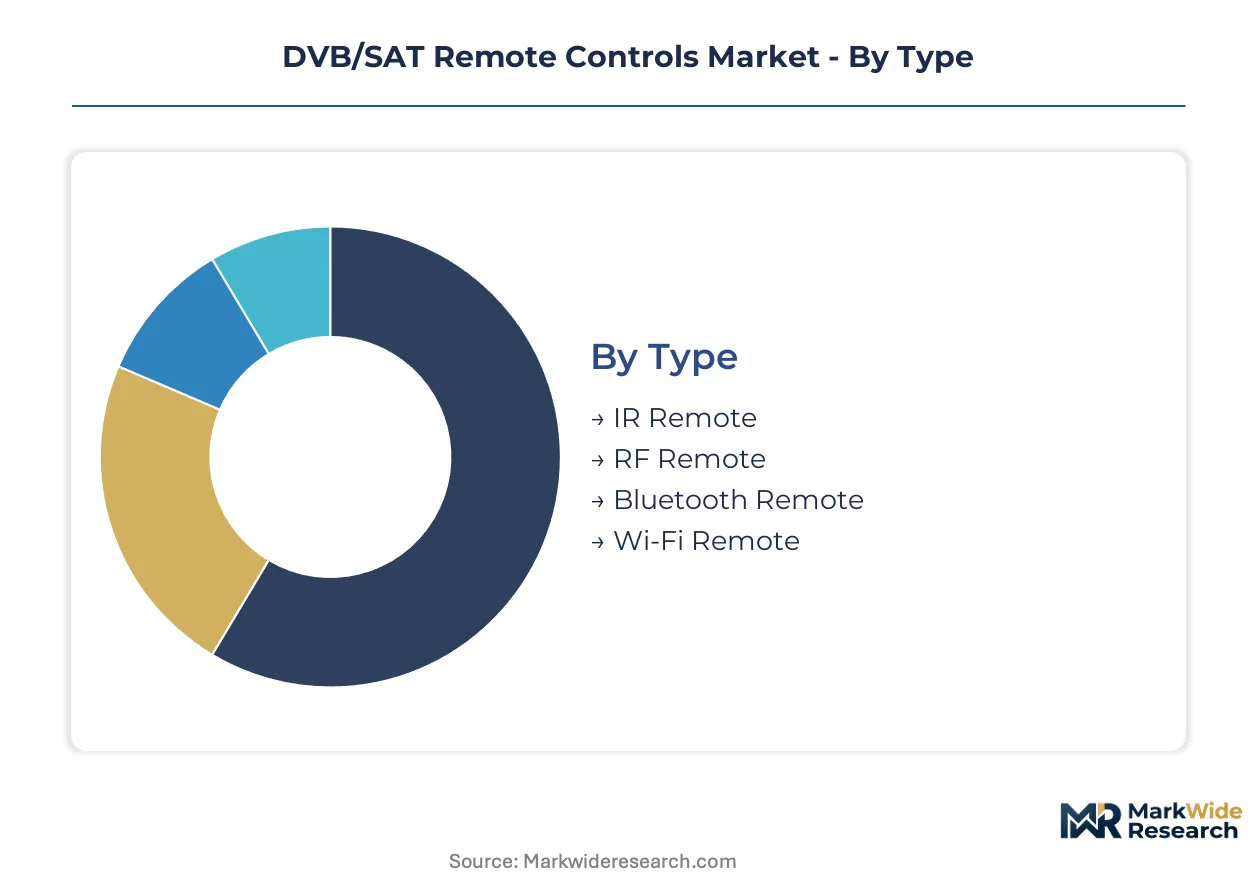
DVB/SAT remote control procurement splits across incompatible technical standards and end-use requirements. Regulatory mandates on RF emissions and energy efficiency fragment supplier qualification pathways by segment type.
Type:
CE marking under EU radio equipment directives creates divergent compliance burdens across connectivity architectures, with Bluetooth and Wi-Fi variants facing stricter electromagnetic compatibility testing than legacy infrared units.
- IR Remote:Line-of-sight infrared transmitters at 940nm wavelength dominate aging set-top box installed bases. German public broadcasters maintain these fleets for basic DVB-T2 receiver compatibility, though procurement committees now exclude them from new tenders.
- RF Remote:Proprietary 2.4 GHz and 433 MHz radio frequency units enable non-line-of-sight operation through walls and cabinets. Pay-TV operators in Austria and Switzerland specify these for multi-room DVR deployments, driving volume concentration in Alpine cable markets.
- Bluetooth Remote:BLE 5.0 and 5.2 implementations with voice-activated microphones absorb operator upgrade budgets. The Bluetooth SIG certification queue extends sixteen weeks, freezing engineering resources on firmware qualification.
- Wi-Fi Remote:Direct-to-cloud IP connectivity bypasses set-top box intermediaries entirely. Hospitality chains in the Netherlands pilot these for smart TV integration, though standby power requirements under EU Ecodesign complicate microcontroller selection.
Established volume favors IR Remote; emerging adoption favors Bluetooth Remote.
Application:
Cost tier differentiation separates commodity consumer replacements from enterprise fleet deployments with customized firmware and extended warranty terms.
- Home Entertainment:Mass-market retail channels move universal programmable units for cord-cutter households replacing legacy operator remotes. Smartphone IR blaster substitution erodes attach rates in price-sensitive segments.
- Professional AV:Corporate boardrooms and event venues demand ruggedized housings with laser pointer integration and programmable macro buttons. Per-unit pricing runs 3-4x consumer tiers due to low-volume customization and on-site support requirements.
- Test Equipment:Calibration laboratories and broadcast engineering shops require precision frequency-agile transmitters for signal analyzer control. Niche demand concentrates in Germany and Austria where transmitter manufacturing clusters support specialized sourcing.
- Industrial Automation:Harsh-environment variants with IP65 sealing and chemical-resistant keypads serve factory floor television monitoring. CE machinery directives impose additional safety certification layers beyond consumer electronics standards.
Margin concentration sits with Professional AV; volume scaling sits with Home Entertainment.
Technology:
Supply-side component availability constrains architecture selection, with RF chipset lead times stretching procurement timelines for non-infrared variants.
- Infrared:Mature 38kHz modulation schemes rely on commodity LED and photodiode components with stable Asian supply chains. BOM cost compression limits supplier differentiation to button feel and housing ergonomics.
- Radio Frequency:Proprietary protocol stacks require dedicated transceiver ICs from Nordic Semiconductor and Texas Instruments. Talent scarcity for embedded RF firmware extends development timelines 40-60% versus infrared equivalents.
- Bluetooth:Standardized BLE protocol enables interoperability across set-top box brands but mandates SIG qualification fees and test house engagement. Direction-finding capability in version 5.1+ enables spatial awareness for set-top box location without line-of-sight.
- Wi-Fi:TCP/IP stack integration demands more powerful microcontrollers with external flash, elevating BOM cost and standby power draw. EU Ecodesign standby limits below 0.5W force aggressive power management design.
Technology maturity favors Infrared; protocol standardization favors Bluetooth.
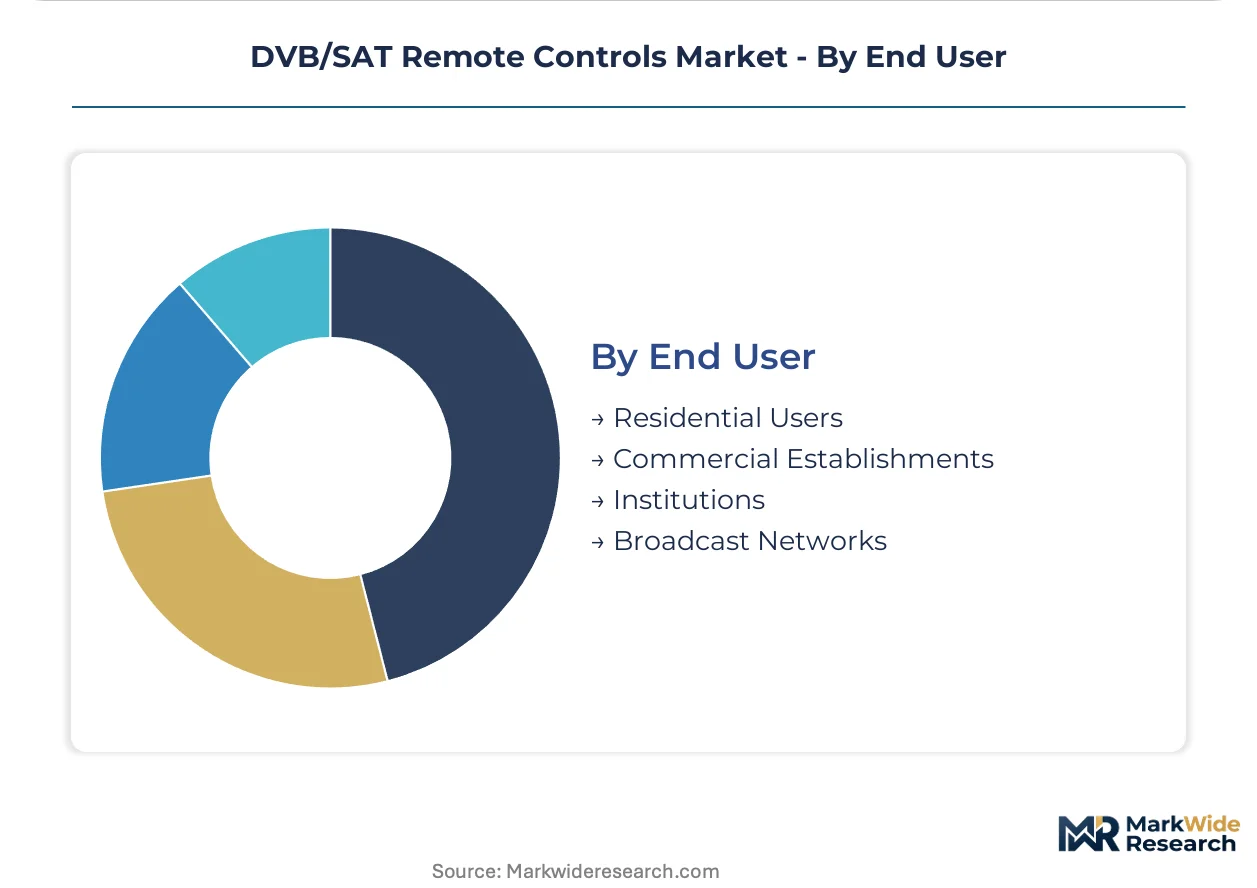
End User:
Customer type determines specification authority, with institutional buyers issuing standalone RFPs while residential demand fragments across retail channels.
- Residential Users:Individual replacement purchases through electronics retailers and e-commerce platforms. Price elasticity drives universal remote preference over operator-branded units.
- Commercial Establishments:Hotel chains and assisted-living facilities unbundle remote procurement from television hardware, establishing direct supplier relationships for customized fleet deployments with accessibility compliance.
- Institutions:Universities and government facilities mandate competitive bidding with environmental preference criteria. EU Green Deal procurement guidelines weight lifecycle carbon footprint in award decisions.
- Broadcast Networks:Public and private operators issue multi-year framework agreements with strict voice-control and accessibility specifications. German ARD and ZDF modernization programs concentrate demand in Central Europe.
Specification influence concentrates with Broadcast Networks; volume dispersion characterizes Residential Users.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import flows in DVB/SAT remote controls tilt toward manufacturing concentration in East Asia against European operator demand. Germany and Austria run structural deficits in finished remote assembly, sourcing RF modules and membrane switch components from Taiwanese and South Korean foundries. Procurement committees in Central Europe now mandate CE marking and EU F-Gas Regulation compliance as non-negotiable entry conditions.
Germany
Deutschland's DVB-T2 and satellite modernization programs are triggering fleet-wide remote replacements among ARD and ZDF public broadcasters. The EU Ecodesign for Energy-Related Products framework tightens standby power limits below 0.5W, forcing microcontroller redesigns. Berlin-Brandenburg hosts quality-focused OEMs leveraging existing environmental compliance infrastructure to accelerate certification timelines.
United States
Pay-TV cable operators in the United States are retiring infrared fleets and mandating Bluetooth Low Energy units, compressing replacement cycles. The Federal Communications Commission governs RF emission parameters for remote controls sold domestically. The Dallas-Fort Worth metroplex anchors RF engineering talent pools where embedded firmware developers command premium compensation.
Austria
Austrian cable operators specify proprietary 2.4 GHz RF remotes for multi-room DVR deployments across Alpine terrain. The country's national telecommunications regulator enforces spectral efficiency testing under EU radio equipment directives. Vienna-engineered precision input systems dominate premium-tier hospitality and healthcare television deployments through specialized supplier relationships.
Netherlands
Dutch hospitality chains are unbundling remote procurement from television hardware purchases, issuing standalone RFPs for accessibility-compliant fleet deployments. The EU Green Deal procurement guidelines weight lifecycle carbon footprint in award decisions. Eindhoven-region electronics assemblers pilot Wi-Fi direct-to-cloud remotes for smart TV integration under Ecodesign standby constraints.
Sweden
Swedish regulators are mandating accessibility-compliant television interfaces in hotel and healthcare settings, creating specification-driven demand for large-button, voice-activated variants. The country's environmental protection agency enforces restricted substance profiles for consumer electronics accessories. Stockholm-based procurement committees now require natural language processing capability as baseline qualification for operator contracts.
DVB/SAT Remote Controls Market Competitive Landscape
Listed leaders compete with private specialists across programmable platform architecture and RF engineering capability. The vendor base splits between scale-driven universal remote manufacturers and precision-engineered specialists serving hospitality and healthcare verticals. Three archetypes dominate: programmable platform providers, Austrian-engineered precision input specialists, and mass-market retail brand licensors. Competitive moves center on long-term operator contract renewal and RF chipset portfolio requalification to meet compressed replacement cycles.
Within the programmable platform tier, Universal Electronics occupies a position exemplifying sustained long-term operator contracts across North American and European cable providers. Ruwido represents the precision-engineered specialist archetype, with its Austrian GmbH structure signaling engineering-focused organizational culture. Philips anchors the mass-market retail channel position where consumers replace legacy IR units with universal alternatives. These three entities collectively illustrate the market's tripartite segmentation across operator-direct, hospitality-vertical, and consumer-retail pathways.
| Leading Market Players |
|---|
| Universal Electronics |
| Ruwido |
| SMK-Link Electronics |
| Philips |
| Logitech International |
| Crestron Electronics |
| HBC-radiomatic GmbH |
| Sony Corporation |
| LG Electronics |
| Others |
Value Network & Pricing Analysis
Bluetooth Low Energy chipset substitution for legacy infrared modules is simultaneously shifting procurement geography toward Taiwanese foundries and compressing per-unit margins for European remote control assemblers facing requalification costs.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures, with three-tier pricing stratification across premium voice-enabled, standard RF, and economy infrared tiers. Price differentiation hinges on CE marking tier and volume scale, with broadcast network procurement committees commanding lowest unit costs through multi-year framework agreements. Pricing pressure stems from lithium coin cell volatility forcing air freight premiums during contract renegotiations. Residential retail channels exhibit highest price sensitivity, while hospitality fleet buyers prioritize extended warranty bundling over per-unit cost.
Supply Chain Analysis
Strategic stockpiling of RF transceivers dominates procurement behavior as lead time uncertainty from Nordic Semiconductor and Texas Instruments stretches engineering timelines. Manufacturing concentrates in Taiwan, South Korea, and China, with membrane switch assemblies and BLE modules drawing from East Asian chemical processors and foundry networks. Single-source vulnerability in CR2032 battery supply exposes European OEMs to forced-air freight premiums. Distribution runs through operator-direct procurement channels for fleet deployments and electronics retail chains for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
After-sales firmware upgrade subscriptions and extended warranty servicing are expanding faster than hardware replacement cycles, transforming remote control procurement into a recurring revenue attachment opportunity.
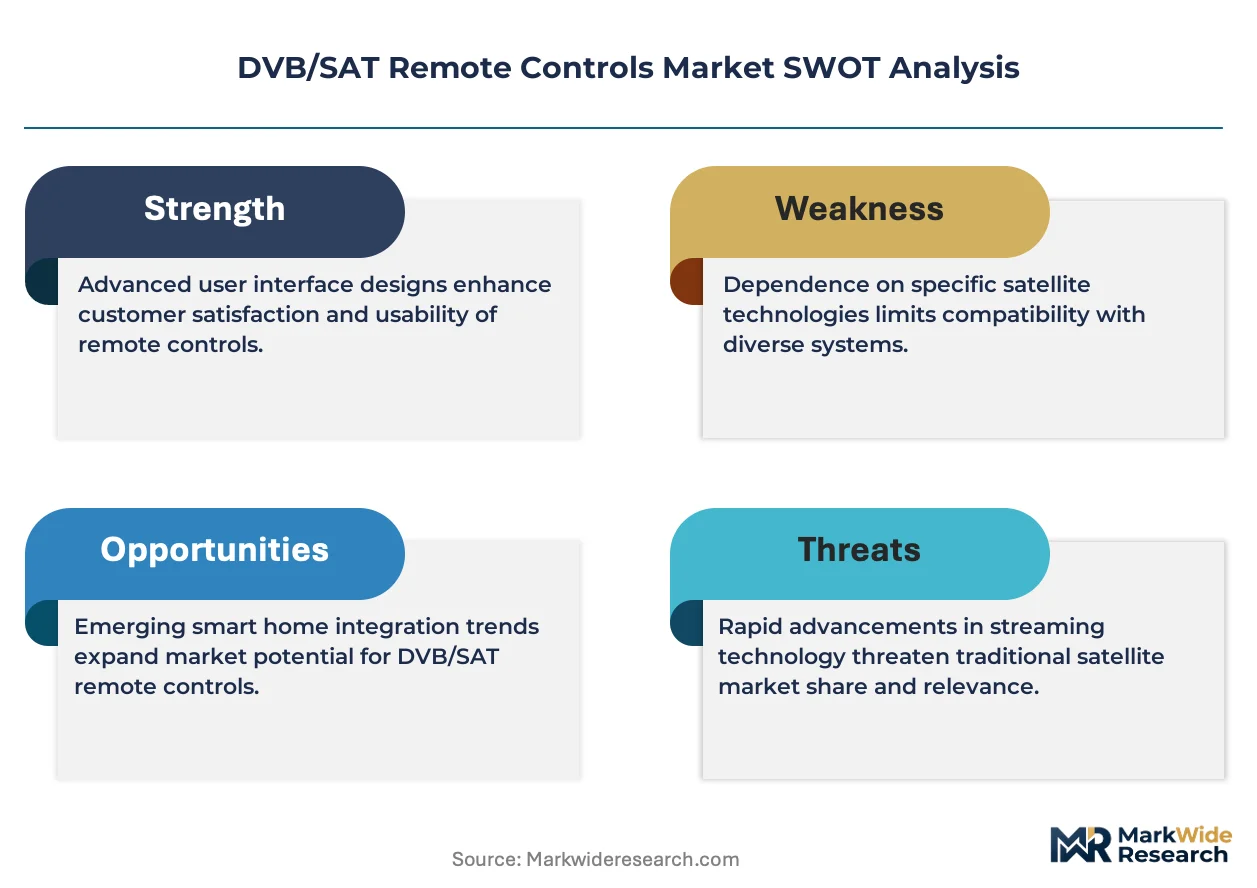
For Market Incumbents: Shield long-term operator contracts by accelerating RF chipset portfolio requalification ahead of compressed replacement cycles. Backward integration into programmable firmware platforms defends against specialized RF module suppliers capturing premium-tier hospitality procurement. CE marking and EU F-Gas Regulation compliance infrastructure becomes a lever for margin defense against lower-cost Asian competitors. For New Entrants and Emerging Players: Accessibility consulting services for Nordic hospitality retrofit mandates represent a service-layer gap where incumbents under-serve procurement committees. White-space concentrates in Swedish and Norwegian large-button, voice-activated variant specifications with compliance-driven RFP structures. Direct supplier relationships with unbundled hotel procurement committees offer the most penetrable entry angle. For Investors and Strategic Acquirers: EU Ecodesign standby power limit tightening reshapes the acquisition landscape toward manufacturers with sub-100nA sleep-mode microcontroller integration capability. Five-to-ten year viability favors precision-engineered specialists with existing environmental compliance infrastructure over commodity infrared assemblers. Bluetooth SIG certification backlog duration serves as the signal to watch for engineering resource allocation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| RF Chipset Portfolio Requalification | Accelerates certification timelines for BLE 5.2 voice-enabled units ahead of operator procurement cycles. |
| Programmable Firmware Platform Investment | Captures recurring upgrade revenue from broadcast operators mandating natural language processing baseline specifications. |
| Accessibility Compliance Specialization | Positions suppliers for Swedish and Norwegian hospitality RFPs mandating large-button voice-activated interfaces. |
| Environmental Certification Infrastructure | Leverages existing EU F-Gas and Ecodesign compliance to accelerate German public broadcaster tender participation. |
| Direct Procurement Channel Development | Disintermediates traditional set-top box bundlers through standalone remote RFP relationships with Dutch hotel chains. |
Research Methodology
Initial hypotheses were tested against primary input from pay-TV operator procurement directors, RF semiconductor product managers, hospitality technology consultants, and CE marking compliance officers, and refined through secondary validation against FCC emission filings, ETSI interoperability standards, EU customs trade data, and operator tender documentation. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions.
Variance decomposition across connectivity type, application tier, and end-user category shaped the analytical framework over the projection horizon. CAGRs derived from replacement cycle compression analysis and voice-control penetration assumptions. Modeled inputs included Bluetooth SIG certification queue dynamics, lithium battery supply concentration metrics, and German broadcast infrastructure modernization spend patterns.
Underlying assumptions cover sustained EU regulatory enforcement, stable East Asian semiconductor supply, and operator voice-control mandate adoption rates, with deviation risk concentrated in RF engineering talent scarcity and spectrum reallocation decisions. Revision becomes warranted when Bluetooth certification backlogs exceed twenty weeks or F-Gas Regulation enforcement intensity crosses thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Electronic Components
Camera Battery Charger Market
Electronic Components
Breadboards Market
Electronic Components
Gigabit Interface Converter Market
Electronic Components
Chip Ferrite Beads Market
Electronic Components
VPX SBC Market
Electronic Components
Audio and Visual Public Address System Market
Electronic Components
Braking Resistors Market
Electronic Components
Switch Diode Market
Electronic Components
Electromechanical Relay Market
Electronic Components
Data Bus Market
Electronic Components
Audio Transistors Market
Electronic Components
Wearable Technology Component Market
Electronic Components
Safety Relay Market
Electronic Components
Battery Holders Market
Electronic Components
Wearable Display Device Materials Market
Electronic Components
Chip Shield Market