
 Molded Wood Pallets Market | 2026-2036
Molded Wood Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
Molded Wood Pallets Market Foresight
Skilled press operators and composite wood technicians is rotating toward automated molding facilities, easing capacity constraints for producers serving North American automotive and retail supply chains. Litco International leverages backward integration into engineered fiber sourcing to secure raw material consistency. CABKA Group sustains European market presence through multi-site manufacturing across Germany and Belgium. Millwood Inc. anchors its competitive stance with extensive refurbishment and pooling networks.
Molded wood pallets are engineered fiber-composite platforms formed under heat and pressure from recycled wood residues, typically achieving uniform dimensions of 1200 mm by 800 mm with load ratings exceeding 1500 kg for static applications. Their primary commercial purpose centers on hygienic, ISPM-15-exempt shipping in food, pharmaceutical, and export-intensive sectors where nail-free construction eliminates contamination risks. Standard pallet configurations dominate volume shipments across grocery and mass retail distribution, while customized dimensional formats capture premium margins from automated warehouse operations requiring exact rack compatibility. Recycled wood material grade leads environmental positioning, though hardwood blends retain share in heavy manufacturing segments demanding extended duty cycles.
EPA guidelines on wood waste diversion and the EU F-Gas Regulation's indirect pressure on cold-chain packaging sustainability shape compliance investments across major producing regions. ISPM-15 standards administered by national plant protection organizations continue restricting conventional nailed pallet circulation, directly advantaging molded alternatives in transoceanic trade lanes. Stakeholders must weigh capital allocation between domestic molding capacity expansion and third-party pooling partnerships as freight volatility and energy costs reshape total cost of ownership calculations.
Market Dynamics
ISPM-15 phytosanitary compliance is compressing demand for conventional nailed pallets while redirecting export flows toward heat-pressed molded alternatives that bypass fumigation requirements entirely.
Growth Catalysts
- EU Green Deal packaging mandates:The EU F-Gas Regulation and circular economy directives are accelerating cold-chain operator transitions to recyclable fiber-composite platforms in Germany and Belgium.
- Food safety certification alignment:BRCGS and SQF audit standards now explicitly favor nail-free pallet construction for pharmaceutical and perishable goods handling.
- Automated warehouse compatibility:Dimensional precision tolerances of ±2 mm enable seamless integration with German and Chinese robotic racking systems.
Market Restraints
- Resin and engineered fiber cost volatility:Phenolic binder prices fluctuate with petrochemical feedstock indices, compressing margin stability for mid-scale producers.
- Press equipment supply concentration:German and Italian press machinery manufacturers command 18-24 month delivery lead times, throttling capacity expansion timelines.
- Load rating limitations in heavy manufacturing:Static capacity ceilings below 2,000 kg restrict penetration in steel and machinery export segments.
Strategic Opportunities
- India pharmaceutical cold chain buildout:CDSCO temperature-controlled distribution rules are creating first-mover openings for ISPM-15-exempt pallet suppliers in Mumbai and Hyderabad clusters.
- Blockchain-IoT traceability convergence:Embedded RFID and distributed ledger verification enable premium positioning for serialized pallet pooling in high-value pharmaceutical lanes.
- US Inflation Reduction Act domestic content incentives:Tax credits for sustainable packaging procurement are redirecting automotive supplier sourcing toward domestic molded fiber producers.
Industry Challenges
- Composite wood technician scarcity:Heat-press calibration and fiber-blend optimization expertise concentrates among aging workforces in traditional European woodworking regions.
- Multi-certification timeline compression:Simultaneous pursuit of EPA wood waste diversion compliance and EU CE marking extends product launch cycles by 8-14 months.
- Legacy WMS integration friction:ERP synchronization with pallet serialization databases demands custom middleware development for mid-tier 3PL operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Molded Wood Pallets Market |
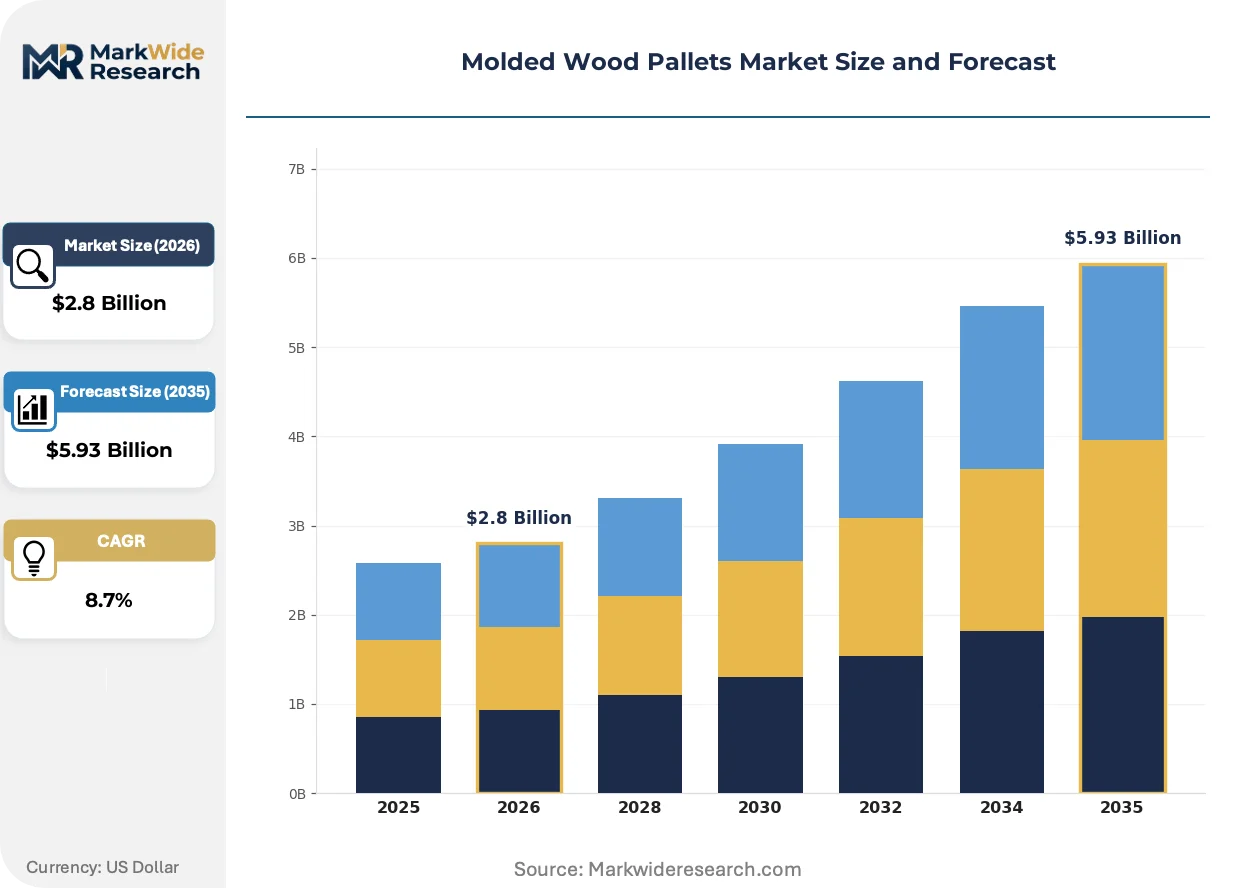
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Pallets, Customized Pallets, Stackable Pallets, Folding Pallets End User: Manufacturing, Food & Beverage, Retail, Logistics Application: Warehouse Operations, Shipping, Exporting, Inventory Management Material Grade: Recycled Wood, Hardwood, Softwood, Fiberboard |
| Companies Covered | Litco International, Millwood Inc., Sonoco Products, UFP Technologies, CABKA Group, Nefab Group, Snyder Industries, Engelvin Bois Moulé, Presswood International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Molded Wood Pallets Market Shifts & Advancements
Press automation and digital traceability are converging to reshape production economics and asset utilization models across fiber-composite pallet manufacturing.
High-frequency microwave drying technology is fragmenting the traditional thermal press cycle by reducing cure times from 8 minutes to 90 seconds. German automotive suppliers are piloting these systems at scale. The compression of batch economics is enabling smaller production runs with faster changeover between custom dimensions.
REACH Annex XVII restrictions on formaldehyde emissions in wood-based products are tightening binder formulation standards across EU manufacturing sites. Producers are reformulating with soy-based and lignin-derived alternatives. Belgian and Dutch facilities face the steepest compliance curves due to existing regional air quality enforcement protocols.
Pool-as-a-service contracting is displacing capital-heavy pallet ownership among US grocery and mass retail distributors. Third-party operators assume asset depreciation and retrieval logistics burdens. This shift concentrates procurement authority among four national pooling networks and compresses supplier margins through volume guarantee requirements.
Molded Wood Pallets Market Segmentation
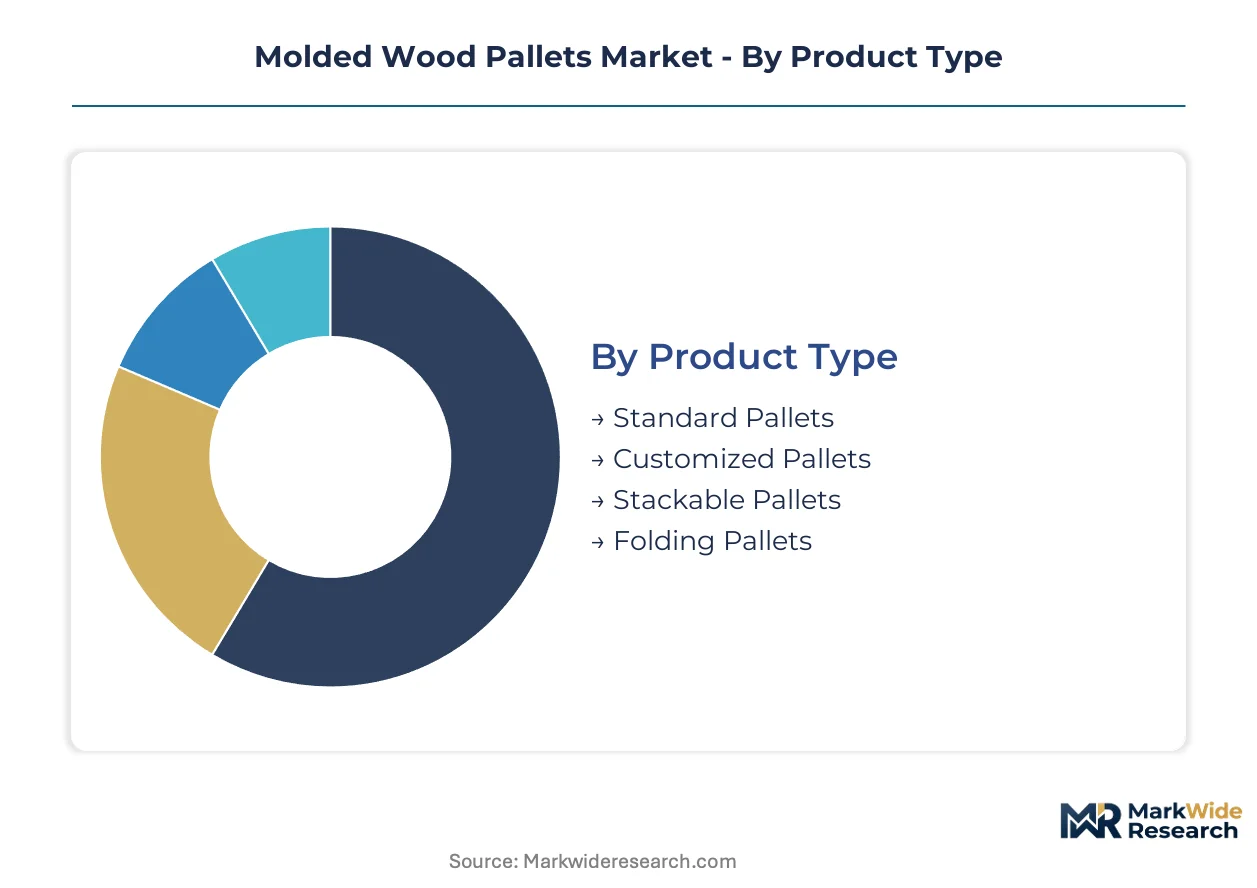
Molded wood pallet demand fragments across product configurations, end-use verticals, and material specifications. Channel dynamics and regulatory compliance requirements reshape which segments capture procurement budgets in food, pharmaceutical, and automotive supply chains.
Product Type:
Standard configurations flow through mass retail and grocery distribution networks, while custom dimensions serve automated warehouse operators requiring exact rack tolerances. Pooling providers and direct OEM procurement split volume across these channels.
- Standard Pallets:Uniform 1200 mm by 800 mm platforms dominate high-volume grocery and mass retail distribution where ISPM-15 exemption eliminates fumigation delays. German and US food distributors concentrate procurement here for cross-border efficiency.
- Customized Pallets:Precision-engineered dimensional formats with ±2 mm tolerances integrate with robotic racking systems in automated warehouses. Premium margins attach to exact rack compatibility requirements in Chinese e-commerce fulfillment centers.
- Stackable Pallets:Nesting designs reduce empty transport costs for 3PL operators managing reverse logistics.
- Folding Pallets:Collapsible structures target space-constrained urban distribution hubs in last-mile networks.
By volume, Standard Pallets leads. By growth pace, Customized Pallets is expanding most quickly.
End User:
Cost tier stratification separates capital-intensive manufacturing from margin-sensitive retail procurement, with compliance premiums concentrated in food and pharmaceutical handling.
- Manufacturing:Heavy machinery and automotive exporters demand load ratings exceeding 1500 kg for static applications. Hardwood blends retain share here despite higher material costs, as extended duty cycles offset replacement frequency.
- Food & Beverage:Cold chain operators in Germany and Belgium prioritize nail-free construction to meet BRCGS and SQF audit standards. EU F-Gas Regulation pressure accelerates fiber-composite adoption for perishable distribution.
- Retail:Mass merchants and grocery chains drive pooling-as-a-service contracting to eliminate capital ownership burdens.
- Logistics:Third-party operators balance asset utilization across multiple shipper requirements with standardized fleet configurations.
Food & Beverage commands the steepest compliance premiums. Manufacturing maintains the largest absolute tonnage throughput.
Application:
Volume concentration in shipping and exporting reflects ISPM-15 phytosanitary redirection, while warehouse operations demand precision tolerances for automation compatibility.
- Warehouse Operations:Automated storage and retrieval systems require dimensional precision for seamless robotic handling. German automotive suppliers and Chinese e-commerce operators lead specification intensity.
- Shipping:Transoceanic trade lanes favor heat-pressed molded alternatives that bypass fumigation requirements entirely. ISPM-15 compliance compression redirects export flows here from conventional nailed platforms.
- Exporting:Cross-border pallet flows concentrate in US, German, and Chinese manufacturing hubs scaling reusable packaging programs.
- Inventory Management:Serialized tracking and RFID embedding enable premium positioning in pharmaceutical cold chains.
Shipping anchors volume scale. Warehouse Operations carries the steepest specification escalation.
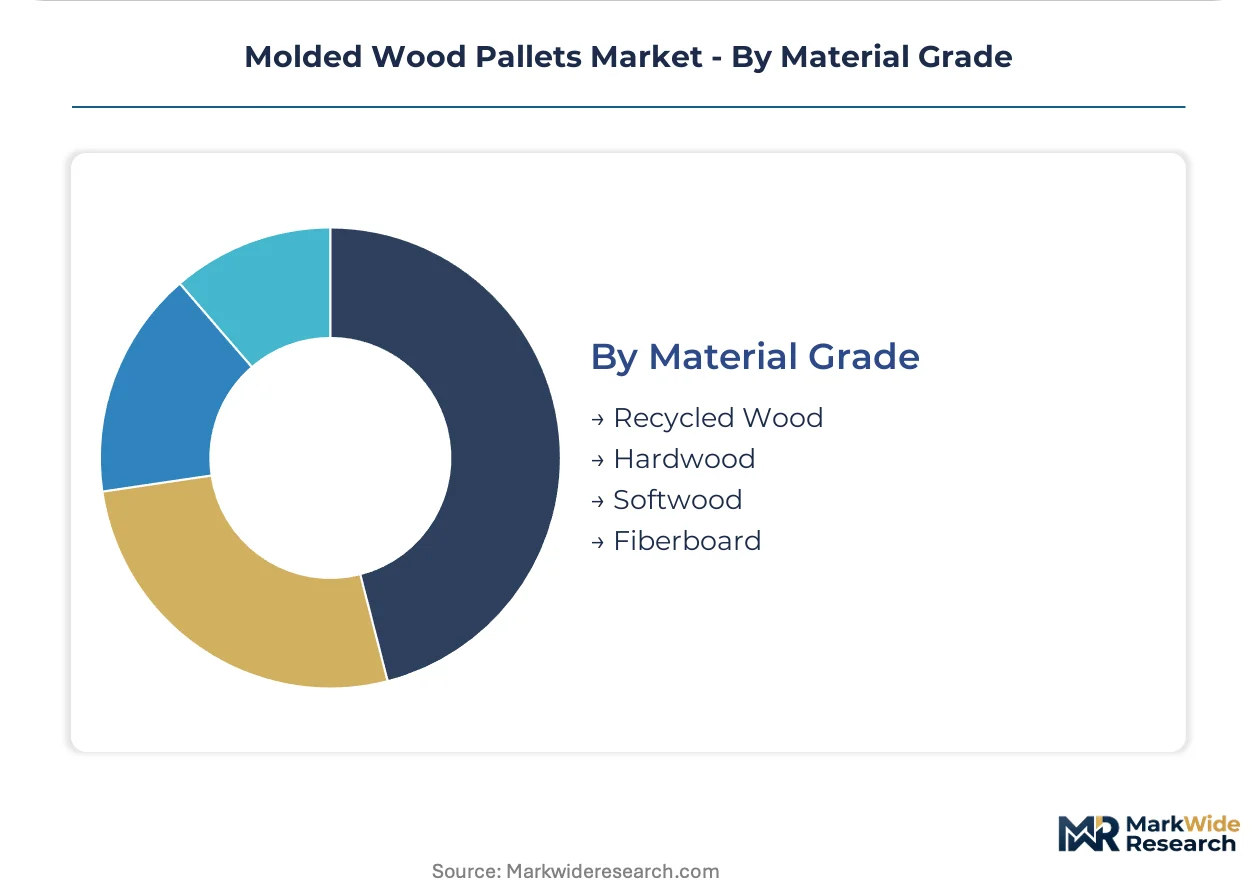
Material Grade:
Environmental positioning and load performance split procurement across recycled fiber and hardwood blends, with regional air quality enforcement shaping binder formulation choices.
- Recycled Wood:Engineered fiber-composite construction from post-industrial residues dominates environmental positioning. EPA wood waste diversion guidelines and EU circular economy directives favor this grade in sustainable packaging procurement.
- Hardwood:Dense fiber structures retain share in steel and machinery export segments where static capacity ceilings restrict lighter alternatives. Extended duty cycles justify material cost premiums.
- Softwood:Lower-density options serve lightweight consumer goods distribution with moderate load requirements.
- Fiberboard:Compressed engineered panels target display and promotional shipping with single-use economics.
Recycled Wood leads procurement volume. Hardwood maintains the most durable pricing power.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA guidelines on wood waste diversion and EU F-Gas Regulation pressure are concentrating molded wood pallet demand in manufacturing and export hubs with strict cold-chain compliance requirements.
United States
Automotive suppliers and grocery distributors drive procurement volumes under US Inflation Reduction Act domestic content incentives. EPA wood waste diversion guidelines favor recycled fiber-composite construction in sustainable packaging procurement. Midwest manufacturing corridors and Southeast distribution hubs scale reusable packaging programs for cross-border efficiency.
Germany
Automotive exporters and pharmaceutical cold-chain operators demand dimensional precision for robotic racking compatibility. EU F-Gas Regulation and REACH Annex XVII formaldehyde restrictions tighten binder formulation standards. Bavarian and North Rhine-Westphalian manufacturing clusters pilot high-frequency microwave drying systems to compress production cycle times.
China
E-commerce fulfillment centers and automotive suppliers specify custom pallet dimensions for automated warehouse integration. National plant protection organizations administer ISPM-15 standards that redirect export flows toward heat-pressed alternatives. Yangtze River Delta and Pearl River Delta logistics hubs concentrate pooling-as-a-service contracting for mass retail distribution.
India
Pharmaceutical cold chain buildout in temperature-controlled distribution creates first-mover openings for ISPM-15-exempt suppliers. CDSCO temperature-controlled distribution rules mandate hygienic handling infrastructure. Mumbai and Hyderabad pharmaceutical clusters drive specification intensity for nail-free construction in perishable goods handling.
Belgium
Perishable distribution networks and EU circular economy procurement prioritize recyclable fiber-composite platforms. Regional air quality enforcement protocols steepen compliance curves for formaldehyde emissions in wood-based products. Antwerp logistics corridors and Flemish manufacturing zones anchor multi-site production serving German retail supply chains.
Molded Wood Pallets Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in molded wood pallet supply. The upper tier commands captive fiber sourcing and multi-site manufacturing footprints across major demand clusters. Mid-scale specialists concentrate on custom dimensional engineering for automated warehouse compatibility or regional pooling network density. Competitive moves center on backward integration into engineered fiber supply and third-party pooling partnerships to defray asset ownership burdens.
Among US-based fabricators, Litco International and Millwood Inc. exemplify contrasting strategic archetypes. Litco International anchors the integrated tier through upstream control over engineered fiber sourcing. Millwood Inc. occupies a position within the pooling-services vector, emphasizing refurbishment network density. European competition concentrates through CABKA Group, which represents the multi-site manufacturing archetype with production spanning German and Belgian facilities.
| Leading Market Players |
|---|
| Litco International |
| Millwood Inc. |
| Sonoco Products |
| UFP Technologies |
| CABKA Group |
| Nefab Group |
| Snyder Industries |
| Engelvin Bois Moulé |
| Presswood International |
| Others |
Supply & Pricing Matrix
Eighteen-to-twenty-four month press machinery delivery lead times from German and Italian equipment manufacturers compress supply elasticity and amplify pricing power for incumbent producers with installed capacity. This supply bottleneck concentrates margin capture among early movers while forcing mid-scale entrants toward third-party tolling arrangements that erode unit economics.
Pricing Analysis
Transatlantic pricing spreads of 15-20 percent separate North American domestic producers from European import alternatives, reflecting freight differentials and tariff exposure. Three-tier pricing structure across premium custom-dimension, standard ISPM-15-exempt, and economy pooled-fleet levels stratifies procurement budgets. Cost compression in standard grades is intensifying because phenolic binder prices track volatile petrochemical feedstock indices. Mass retail distributors exhibit the sharpest price sensitivity through volume-guarantee negotiations, while pharmaceutical cold-chain operators accept premium positioning for BRCGS-aligned nail-free construction.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for phenolic resin and engineered fiber imports, pressuring working capital cycles. Manufacturing capacity concentrates in Germany, Belgium, and the United States, with secondary production clustering in China's Yangtze River Delta. Raw material flows draw from post-industrial wood residue streams, petrochemical-derived binders, and hardwood fiber supplements. Single-source vulnerability concentrates in German and Italian press machinery suppliers. Distribution runs through direct OEM procurement, national pooling networks, and third-party logistics fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The molded wood pallet market constitutes a defensive-moat opportunity anchored in regulatory entrenchment: ISPM-15 phytosanitary compliance creates irreversible switching costs for export-intensive shippers.
For Market Incumbents: Consolidate fiber supply security through backward integration into engineered fiber sourcing or long-term residue-stream contracts with sawmill operators. Expand microwave drying pilot capacity in Bavarian and North Rhine-Westphalian clusters to compress batch economics below competitor replication thresholds. Threat: Emerging Asian producers with state-subsidized equipment financing. For New Entrants and Emerging Players: Lead with pharmaceutical cold-chain specialization in Mumbai and Hyderabad, where CDSCO temperature-controlled distribution rules mandate hygienic handling infrastructure absent established molded pallet penetration. Target custom-dimension engineering for Chinese e-commerce fulfillment centers requiring ±2 mm robotic rack tolerances. Go-to-market angle: Blockchain-IoT traceability bundling with serialized pooling contracts. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified packaging conglomerates with under-optimized molded wood divisions lacking captive fiber supply or pooling network density. Long-term viability rests on regulatory permanence of ISPM-15 standards and EU Green Deal packaging mandates. Signal to watch: Press equipment order backlogs at German machinery manufacturers as inflection indicator for capacity expansion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Engineered Fiber Supply | Litco International's captive sourcing model secures raw material consistency against phenolic price volatility. |
| High-Frequency Microwave Drying Deployment | German automotive suppliers pilot 90-second cure cycles that fragment traditional 8-minute batch economics. |
| Pool-as-a-Service Contracting Expansion | Millwood Inc.'s refurbishment network density captures procurement authority from capital-constrained grocery distributors. |
| Blockchain-IoT Traceability Embedding | Serialized pallet pooling enables premium positioning in pharmaceutical lanes requiring distributed ledger verification. |
| Multi-Site Manufacturing Footprint | CABKA Group's German-Belgian production cluster minimizes freight exposure to EU F-Gas Regulation compliance zones. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with pallet pool operators, automotive procurement directors, pharmaceutical logistics managers, and engineered fiber procurement leads. Secondary validation drew from EPA wood waste diversion guidelines, EU F-Gas Regulation filings, ISPM-15 administration records by national plant protection organizations, and customs trade data on fiber-composite platform flows. Bottom-up shipment data triangulated against top-down capacity estimates from press machinery manufacturers.
Across the analysis window, volume and value outputs reflect segmentation by product configuration, end-use vertical, material grade, and geographic regulatory cluster. CAGRs were derived from production capacity expansion timelines, substitution elasticity estimates for conventional nailed pallets, and compliance-driven procurement shift assumptions. Industry-specific forecast inputs included phenolic resin price indices, microwave drying technology adoption curves, and pooling network contract renewal rates.
The analysis sits within stated boundaries; outcomes outside sustained ISPM-15 enforcement permanence, EU Green Deal packaging mandate continuity, or stable petrochemical feedstock pricing would require recalibration. Forecasts reflect documented assumptions regarding press equipment delivery lead times, fiber residue stream availability, and cold-chain infrastructure buildout velocity in target pharmaceutical clusters. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
GCC Pallet Market
Pallets Packaging
Asia-Pacific Lumber Pallet Market
Pallets Packaging
Foldable Pallet Container Market
Pallets Packaging
Foldable and Collapsible Pallets Market
Pallets Packaging
Foldable Plastic Pallet Boxes Market
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Europe Pallet Market
Pallets Packaging
United States Pallet Market
Pallets Packaging
Pallet Bands Market
Pallets Packaging
Italy Pallets Market
Pallets Packaging
Indonesia Pallets Market
Pallets Packaging
India Pallets Market
Pallets Packaging
Pallet Labelling System Market
Pallets Packaging
North America Lumber Pallet Market
Pallets Packaging
Composite Pallet Market
Pallets Packaging
Corrugated Pallet Containers Market