
 Latin America Pallet Market | 2026-2036
Latin America Pallet Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Pallet Market Intelligence
Brazil's CONAMA Resolution 491 on solid waste management is broadening reusable pallet adoption among food exporters. Brambles Limited (CHEP) leverages its pooled network to dominate refrigerated produce corridors across São Paulo state. Smurfit Kappa anchors corrugated pallet supply for FMCG clients seeking lightweight export formats. LOSCAM sustains competitive positioning through asset-tracking integration in Argentine grain logistics.
A pallet is a portable platform, typically constructed from wood slats, plastic resin, or metal, designed for mechanical handling of goods by forklifts, pallet jacks, or conveyors; standard dimensions follow ISO 6780 specifications to enable intermodal compatibility. Wood pallets retain cost leadership across Latin American manufacturing, though plastic pallets are gaining share in pharmaceutical cold chains where washability and contamination resistance command premium positioning. Standard-size pallets occupy the volume core, while custom formats capture margin pools in specialized agricultural equipment and automotive component exports.
ANVISA sanitary requirements in Brazil and Argentina's INTI quality standards shape material selection and surface treatment protocols for food-contact and pharmaceutical pallets. Brazil's BIS-equivalent INMETRO certification and Mexico's NOM-144-SEMARNAT on wood packaging treatment constrain market entry for untreated imports. Stakeholders must monitor Mercosur harmonization talks on circular-economy packaging rules, as unified standards would reshape cross-border pooling economics and supplier qualification costs.
Market Dynamics
Reusable pallet pooling networks are displacing single-use ownership models across Latin American food corridors, driven by ANVISA sanitary mandates and cold chain spoilage reduction targets.
Growth Catalysts
- CONAMA Resolution 491:Brazil's solid waste framework mandates reusable packaging for large generators, forcing food exporters toward pooled pallet systems.
- Pharmaceutical cold chains:Washable plastic pallets capture share from wood in vaccine and biologics distribution where contamination control is non-negotiable.
- Mercosur corridor concentration:São Paulo-Buenos Aires-Montevideo freight volumes create density economics for shared asset networks.
Market Restraints
- Tropical hardwood supply volatility:Brazilian ipê and jatoba price swings compress converter margins on traditional wood pallets.
- Asset recovery infrastructure gaps:Sparse reverse logistics networks in Paraguay and Bolivia limit pooling program expansion.
- INMETRO certification timelines:Extended approval cycles for plastic pallet formulations delay product launches by 8-14 months.
Strategic Opportunities
- Colombian agricultural exports:Flower and avocado shippers lack pooled pallet coverage, presenting greenfield network deployment potential.
- RFID-telemetry convergence:Embedded sensors tracking humidity and shock damage enable outcome-based pallet rental pricing.
- Argentina INTI quality harmonization:Aligned standards with Brazil would slash cross-border pooling qualification costs.
Industry Challenges
- ISO 6780 retrofit complexity:Automotive component exporters struggle to reconcile European EPAL specifications with local racking systems.
- Sanitation technician scarcity:Cold chain operators face shortages of certified wash-down specialists for pharmaceutical-grade pallet maintenance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Pallet Market |
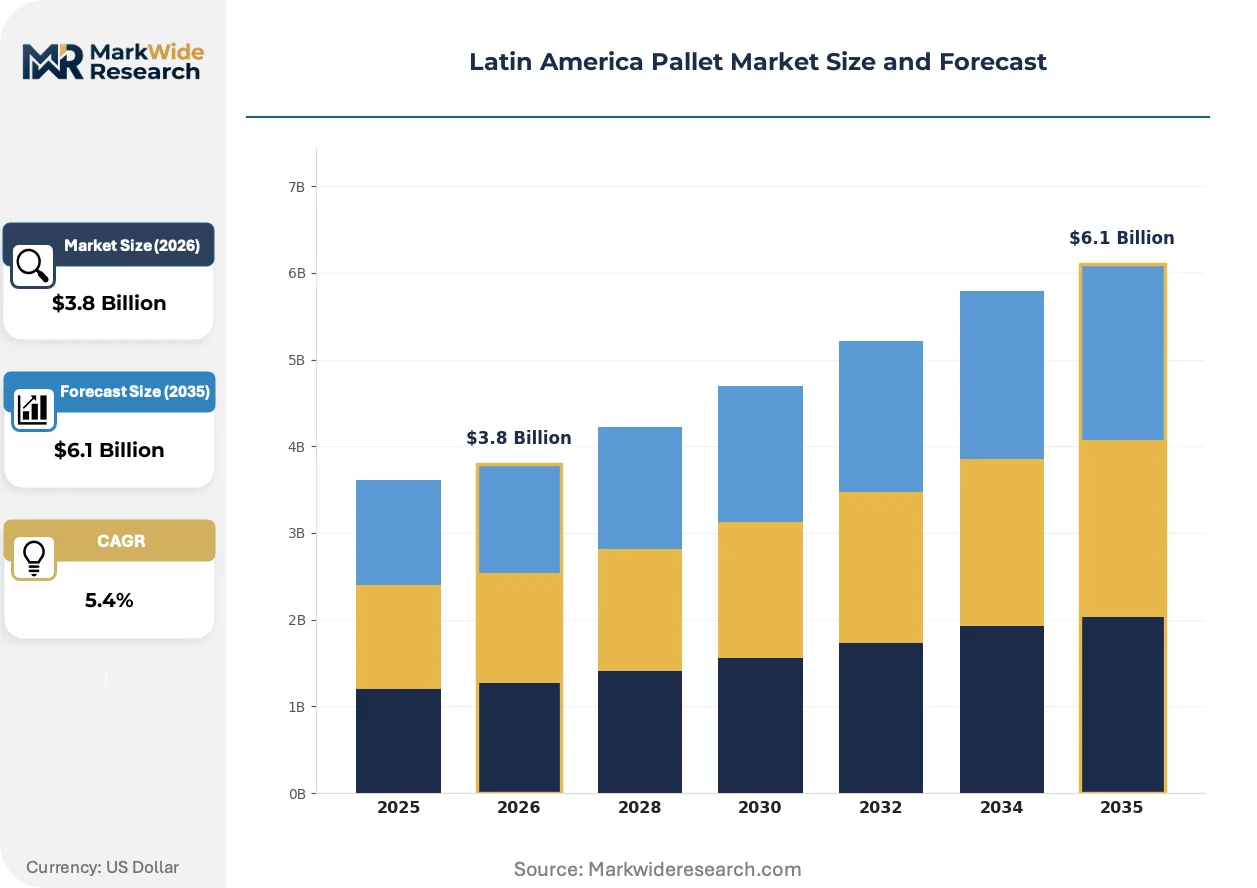
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Plastic, Metal, Composite Pallet Size: Standard, Custom, Half-Size, Quarter-Size End Use: Food & Beverage, Retail, Pharmaceuticals, Manufacturing Distribution Channel: Direct Sales, E-Commerce, Distributors, Wholesalers |
| Companies Covered | LOSCAM, DS Smith, Brambles Limited (CHEP), KRAFTPAL Technologies, Milwood, Conitex Sonoco, Rehrig Pacific Company, Pallecon Resources Ltd., Smurfit Kappa, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Pallet Market Strategic Shifts & Innovations
Digital asset tracking and regulatory harmonization are compressing friction costs in cross-border pallet circulation, while material science advances unlock pharmaceutical-grade performance at industrial price points.
RFID-integrated plastic pallets is unifying inventory visibility with structural durability in temperature-controlled logistics. Brazilian pharmaceutical distributors are deploying these units at scale for vaccine distribution. The technology is unifying previously separate asset management and quality assurance functions into single-platform operations.
ANVISA's updated sanitary requirements for food-contact surfaces are tightening surface roughness and material migration standards. Pallet converters must reformulate polypropylene blends and validate new molds. Pharmaceutical cold chain operators in São Paulo state are accelerating plastic pallet substitution to preempt compliance gaps.
Per-use rental contracts are displacing capital purchase models among mid-sized food exporters. Third-party logistics providers in Mexico are bundling pallet supply with warehousing services. Argentine grain cooperatives represent the fastest-adopting segment as they seek to offload asset management burdens onto specialized poolers.
Latin America Pallet Market Segmentation
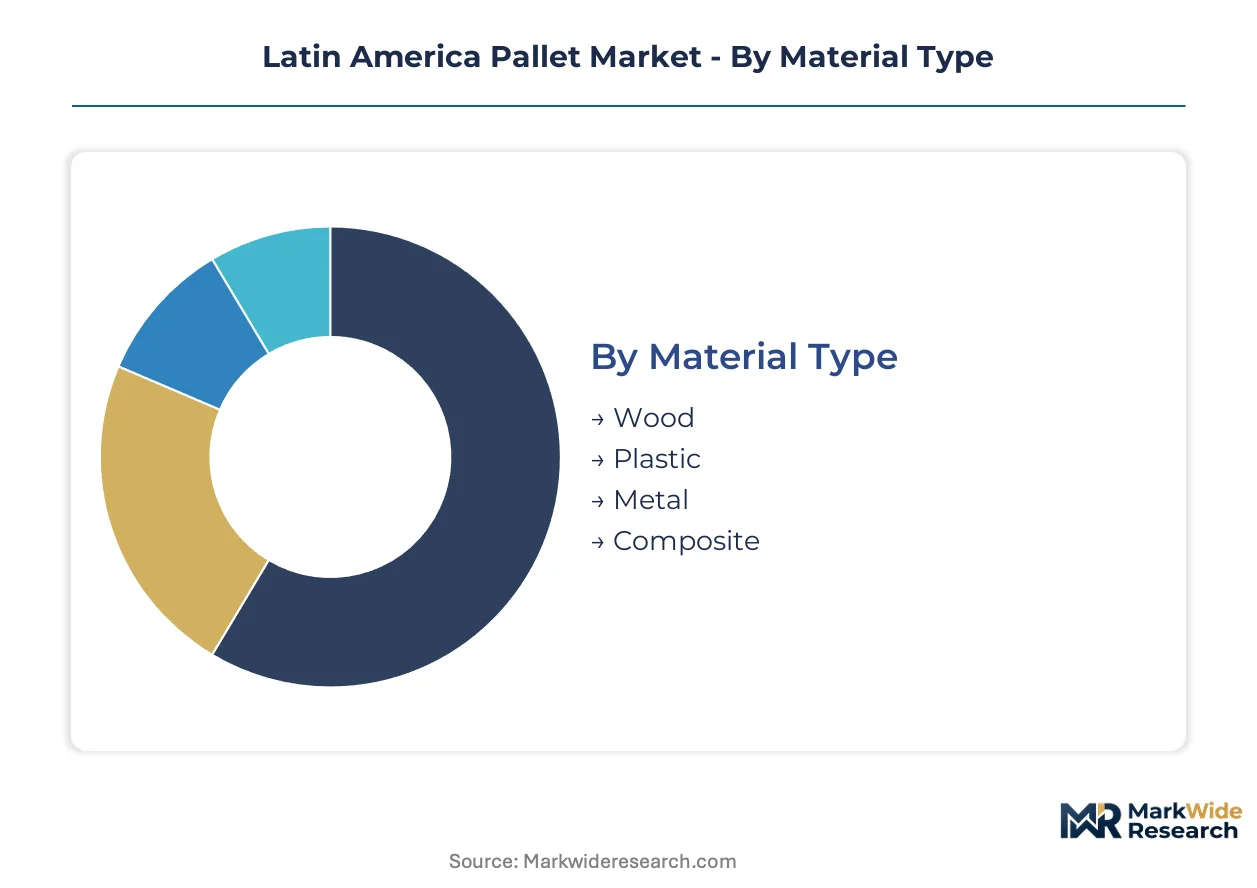
Pallet specifications in Latin America fragment across material grades, dimensional standards, and sanitary compliance tiers. Procurement decisions hinge on ANVISA food-contact certifications, INMETRO structural validations, and Mercosur cross-border compatibility requirements.
Material Type:
INMETRO certification timelines stretch longest for plastic formulations, while wood treatments face NOM-144-SEMARNAT fumigation mandates at Mexican ports. Composite materials trigger dual-track approvals spanning structural load testing and chemical migration assays.
- Wood:Tropical hardwoods dominate Brazilian manufacturing floors, with ipê and jatoba supplying load-bearing beams for heavy machinery exports. São Paulo state converters source certified lumber through Pará state sawmills to satisfy Mercosur phytosanitary protocols for grain shipments to Buenos Aires.
- Plastic:High-density polyethylene blends command premium positioning in pharmaceutical corridors, where washability and dimensional stability under thermal cycling justify rental premiums. ANVISA's updated surface roughness standards are accelerating polypropylene reformulation investments among São Paulo injection molders serving vaccine distributors.
- Metal:Steel and aluminum configurations anchor automotive component racking systems requiring extreme load tolerance and fire resistance.
- Composite:Wood-polymer hybrids capture niche demand from exporters seeking reduced weight without sacrificing fork-entry durability.
Leading the category by volume: Wood. Expanding most quickly: Plastic.
Pallet Size:
ISO 6780 dimensional compliance determines cross-border pooling economics, with deviations triggering manual handling surcharges at Montevideo and Santos port facilities.
- Standard:1200mm by 1000mm formats dominate Mercosur corridor freight, enabling forklift compatibility across São Paulo warehouses, Buenos Aires distribution centers, and Montevideo transshipment hubs. Grain cooperatives in Argentina's Santa Fe province standardize on this footprint to minimize truck loading variance.
- Custom:Automotive component suppliers in Mexico's Bajío cluster commission non-standard lengths to accommodate powertrain modules, accepting racking retrofit costs to eliminate double-handling damage. European EPAL specification mismatches with local systems force engineering trade-offs at Querétaro assembly plants.
- Half-Size:Retail display pallets optimize last-mile cube utilization for urban delivery constraints in Bogotá and Lima.
- Quarter-Size:E-commerce parcel sorting operations in São Paulo's Guarulhos district deploy these for automated conveyor compatibility.
Standard formats capture margin through pooling network density. Custom configurations gain share fastest in specialized automotive and agricultural equipment exports.
End Use:
Sanitary tier requirements stratify material selection, with pharmaceutical and food-contact applications mandating washability certifications absent from general manufacturing specifications.
- Food & Beverage:Cold chain operators across Brazil's São Paulo state and Mexico's Sinaloa corridor prioritize plastic pooling to reduce produce spoilage. CONAMA Resolution 491 mandates reusable packaging for large waste generators, redirecting fruit exporters from single-use wood ownership to CHEP and LOSCAM rental programs.
- Pharmaceuticals:Vaccine distribution networks in São Paulo, Rio de Janeiro, and Mexico City deploy RFID-integrated plastic pallets with embedded humidity sensors. ANVISA sanitary mandates on surface migration limits are disqualifying untreated wood from biologics logistics.
- Retail:FMCG distributors in Argentina's Greater Buenos Aires area balance lightweight corrugated formats against durability requirements for multi-trip center-store displays.
- Manufacturing:Industrial machinery exporters in Brazil's Minas Gerais state specify hardwood block pallets for heavy-load stability during Atlantic shipping.
Food and beverage anchors volume through Mercosur agricultural exports. Pharmaceuticals climb fastest on cold chain infrastructure buildouts and regulatory sanitization mandates.
Distribution Channel:
Channel selection reflects customer scale and technical service requirements, with large pooled-network operators bypassing intermediaries while mid-tier exporters rely on distributor inventory buffers.
- Direct Sales:CHEP and Smurfit Kappa maintain captive salesforces for multinational FMCG accounts and pharmaceutical distributors requiring integrated asset-tracking platforms. São Paulo-based cold chain operators negotiate multi-year per-use contracts directly with poolers to lock in sanitization service levels.
- Distributors:Regional warehousing specialists in Mexico's Monterrey cluster stock standardized wood and plastic inventories for mid-sized food processors lacking capital for pooling program enrollment.
- E-Commerce:Digital procurement portals capture small-lot orders from Colombian flower exporters and Peruvian avocado shippers seeking spot pallet availability without network membership fees.
- Wholesalers:Secondary market aggregators supply refurbished wood units to informal logistics operators in Paraguay and Bolivia where pooling infrastructure remains sparse.
Direct sales command the category by contract value. E-commerce channels gain traction fastest among agricultural exporters in under-penetrated Andean markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil produces the majority of Latin American pallet stock, yet Mexico and Argentina consume significant volumes through cross-border agricultural and automotive corridors. The production-consumption gap drives freight economics across the Mercosur trade zone.
Brazil
São Paulo state's cold chain operators deploy plastic pooling systems for produce exports to Europe and Asia. ANVISA's updated sanitary mandates on food-contact surfaces are disqualifying untreated wood from pharmaceutical logistics. Pará state sawmills supply certified tropical hardwood to converters serving grain shipments through Santos port.
Mexico
Sinaloa corridor tomato and berry exporters are transitioning from single-use wood to rental pallets to reduce spoilage claims. NOM-144-SEMARNAT mandates heat treatment for all wood packaging entering from Central America. Bajío automotive cluster assemblers commission custom-length pallets for powertrain module handling at Querétaro plants.
Argentina
Santa Fe province grain cooperatives represent the fastest-adopting segment for third-party pooling programs. INTI quality standards on load-bearing capacity shape material selection for soy and corn exports. Buenos Aires distribution centers standardize on 1200mm by 1000mm formats to minimize truck loading variance across the Mercosur corridor.
Colombia
Antioquia flower exporters and Cundinamarca avocado shippers lack pooled pallet coverage, presenting greenfield network deployment potential. The national agricultural regulator enforces phytosanitary treatment protocols for wooden packaging in fresh produce exports. Bogotá's last-mile distributors deploy half-size retail display pallets to optimize cube utilization in urban delivery constraints.
Chile
Central Valley wine exporters and Valparaíso port fruit handlers drive demand for sanitary-grade plastic pallets in temperature-controlled logistics. The national agricultural service mandates traceability documentation for all packaging materials in export-grade produce. Santiago's pharmaceutical distributors are accelerating RFID-integrated pallet substitution to meet cold chain verification requirements.
Latin America Pallet Market Key Industry Players
The competitive structure tilts toward pooled-network operators with captive asset bases. Consolidation among international poolers contrasts with fragmentation among regional wood converters. Three archetypes dominate: multinational pooling networks with integrated logistics platforms, corrugated specialists serving FMCG lightweight export formats, and regional hardwood fabricators anchored in tropical timber supply. Capacity expansion and RFID-telemetry integration represent the dominant competitive moves across tiers.
Within the multinational pooling tier, Brambles Limited (CHEP) and LOSCAM exemplify asset-heavy network operators with established Mercosur corridor density. Among packaging-integrated specialists, Smurfit Kappa occupies a position exemplifying corrugated pallet supply for FMCG clients seeking reduced-weight export formats. These three companies anchor the competitive landscape across distinct strategic vectors: shared asset logistics, material-integrated packaging, and pooled network scale.
| Leading Market Players |
|---|
| LOSCAM |
| DS Smith |
| Brambles Limited (CHEP) |
| KRAFTPAL Technologies |
| Milwood |
| Conitex Sonoco |
| Rehrig Pacific Company |
| Pallecon Resources Ltd. |
| Smurfit Kappa |
| Others |
Cost & Logistics Intelligence
Large food exporters across Brazil's São Paulo state concentrate procurement volumes through CHEP and LOSCAM pooled networks, locking in per-use rental contracts that displace spot-market wood purchases and compress spot-price volatility for untreated tropical hardwood units.
Pricing Analysis
Margin tightening in untreated wood pallet tiers traces to Brazilian ipê and jatoba price swings, while plastic pooling commands rental premiums justified by ANVISA washability certifications. Three-tier pricing structure across certified pharmaceutical-grade, food-contact compliant, and general industrial levels separates segments by surface migration testing and RFID-telemetry integration. Cost-down pressure on standard wood formats accelerates as CONAMA Resolution 491 redirects large generators toward reusable systems. Small-scale Paraguayan and Bolivian logistics operators exhibit highest price sensitivity, while São Paulo pharmaceutical distributors accept premium positioning for contamination-controlled assets.
Supply Chain Analysis
Tropical hardwood supply rests on Pará state sawmills feeding Brazilian converters, while injection-molded plastic resins draw from Mexican petrochemical complexes and Argentine polymer distributors. Brazilian ipê and jatoba beams, Mexican HDPE pellets, and Colombian composite binders anchor material inputs. Single-source vulnerability concentrates in certified tropical lumber chains subject to Mercosur phytosanitary restriction shifts. Distribution runs through pooled-network depots at São Paulo, Buenos Aires, and Montevideo port facilities, with secondary wholesaler channels serving informal operators in landlocked Andean markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Brazil's CONAMA Resolution 491 erects a compliance moat that favors pooled-network incumbents with sanitization infrastructure, marginalizing untreated wood converters lacking capital for circular-economy certification.
For Market Incumbents: Acquire RFID-telemetry asset-tracking platforms to preempt outcome-based rental pricing convergence. Consolidate reverse logistics depots across the Mercosur corridor to capture Argentine grain cooperative volume migrating from ownership to pooling. Defensive positioning requires preempting Smurfit Kappa's corrugated lightweight formats in FMCG export lanes through integrated sanitation service bundling. For New Entrants and Emerging Players: Enter via Colombian flower and avocado export corridors where pooled pallet coverage remains sparse and spot-market dependency creates service gaps. Target Antioquia and Cundinamarca agricultural clusters with digital procurement portals bypassing network membership fees. Go-to-market leverage rests on phytosanitary-compliant wood treatment partnerships with national agricultural regulators. For Investors and Strategic Acquirers: The window for entry favors asset-heavy pooling operators with established Mercosur depot density over capital-light trading intermediaries. Long-term viability hinges on regulatory harmonization outcomes across Brazil's ANVISA and Argentina's INTI standards. Watch Mercosur circular-economy packaging rule convergence as the inflection signal reshaping cross-border qualification economics.| Strategic Initiative | Industry Significance |
|---|---|
| RFID-Telemetry Integration | Embedded sensors enable humidity and shock-based outcome pricing for pharmaceutical cold chains. |
| Reverse Logistics Depot Expansion | Asset recovery infrastructure in Paraguay and Bolivia unlocks pooling program geographic extension. |
| Polypropylene Reformulation Investment | ANVISA surface roughness compliance accelerates mold validation for vaccine distribution pallets. |
| Per-Use Rental Contract Scaling | Mid-sized food exporters in Mexico and Argentina offload asset management burdens to specialized poolers. |
| Cross-Border Harmonization Lobbying | Aligned Brazil-Argentina standards slash qualification costs for Mercosur corridor network operators. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with cold chain operators, pallet pooling network managers, injection molding plant engineers, and agricultural export logistics coordinators. Secondary sources spanned ANVISA sanitary mandate documentation, INTI quality standard protocols, Mercosur circular-economy packaging draft regulations, and Brazilian customs wood packaging treatment records. Bottom-up volume modeling triangulated against top-down sectoral expenditure estimates across material type, size format, and end-use segmentation.
Data-stream reconciliation combined production capacity surveys at Pará state sawmills with pooled-network asset deployment metrics reported by CHEP and LOSCAM corridor operators. Segmentation dimensions modeled encompassed material grade tiers, dimensional standard compliance, sanitary certification levels, and distribution channel structures. CAGRs derived from elasticity-adjusted demand projections across food, pharmaceutical, and manufacturing end-uses, with cross-validation against cold chain infrastructure investment pipelines and automotive export volume forecasts.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Mercosur regulatory harmonization delays or tropical hardwood supply disruption scenarios. Projections reflect documented assumptions on pooling adoption rates, certification timeline durations, and cross-border freight volume growth. A small set of named triggers warrants ongoing watch: ANVISA surface migration standard enforcement intensity, INTI-Brazil standard alignment negotiations, and Colombian agricultural export logistics modernization program funding.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Stringer Pallets Market
Pallets Packaging
Europe Palletizer Market
Pallets Packaging
Pallet Labelling System Market
Pallets Packaging
Global Crates and Pallets Packaging Market
Pallets Packaging
Asia-Pacific Lumber Pallet Market
Pallets Packaging
Pallet Wraps Market
Pallets Packaging
Corrugated Pallet Wrap Market
Pallets Packaging
Corrugated Pallet Containers Market
Pallets Packaging
Pallet Packaging Market
Pallets Packaging
Palletizer Market
Pallets Packaging
Composite Pallet Market
Pallets Packaging
Europe Pallet Wrapping Machine Market
Pallets Packaging
Pallet Shippers Market
Pallets Packaging
Thermal Pallet Covers Market
Pallets Packaging
Pallet Wrappers Market
Pallets Packaging
Single Use Pallet Market