

Conventional Palletizers Market Size, Share, and Industry Trends Forecast 2026-2036
Conventional Palletizers Market Insights
Aftermarket service revenue is rewriting profit expectations for equipment suppliers. ABB leverages its global service network to capture recurring maintenance contracts on installed layer palletizer bases. FANUC sustains competitive positioning through deep integration of its servo motor control systems into hybrid palletizer architectures. KUKA anchors European demand with manufacturing scale in Germany that supports rapid spare parts fulfillment for beverage packaging clients.
Conventional palletizers are fixed-structure material handling machines that stack unit loads onto pallets through mechanical, pneumatic, or servo-driven lifting and conveying mechanisms, typically operating at throughputs of 20 to 40 cases per minute for layer-forming configurations. Their primary purpose is to automate end-of-line packaging operations in high-volume manufacturing environments where consistent load patterns and pallet stability are required. Layer palletizers occupy the mature core of the product mix with established margins in food processing applications, while robotic palletizers capture faster expansion in consumer electronics where changeover flexibility matters. Servo motor control technology leads technology-level margins due to precision positioning advantages over pneumatic and hydraulic alternatives.
OSHA machine guarding standards in the United States and CE marking requirements under the EU Machinery Directive shape product design by mandating protective enclosures and emergency stop architectures that add cost but create compliance barriers for non-certified entrants. China's GB standards and NMPA-aligned safety protocols for pharmaceutical packaging applications further segment market access by end-use. Stakeholders must monitor how regional energy efficiency regulations affect hydraulic system viability against electromechanical alternatives.
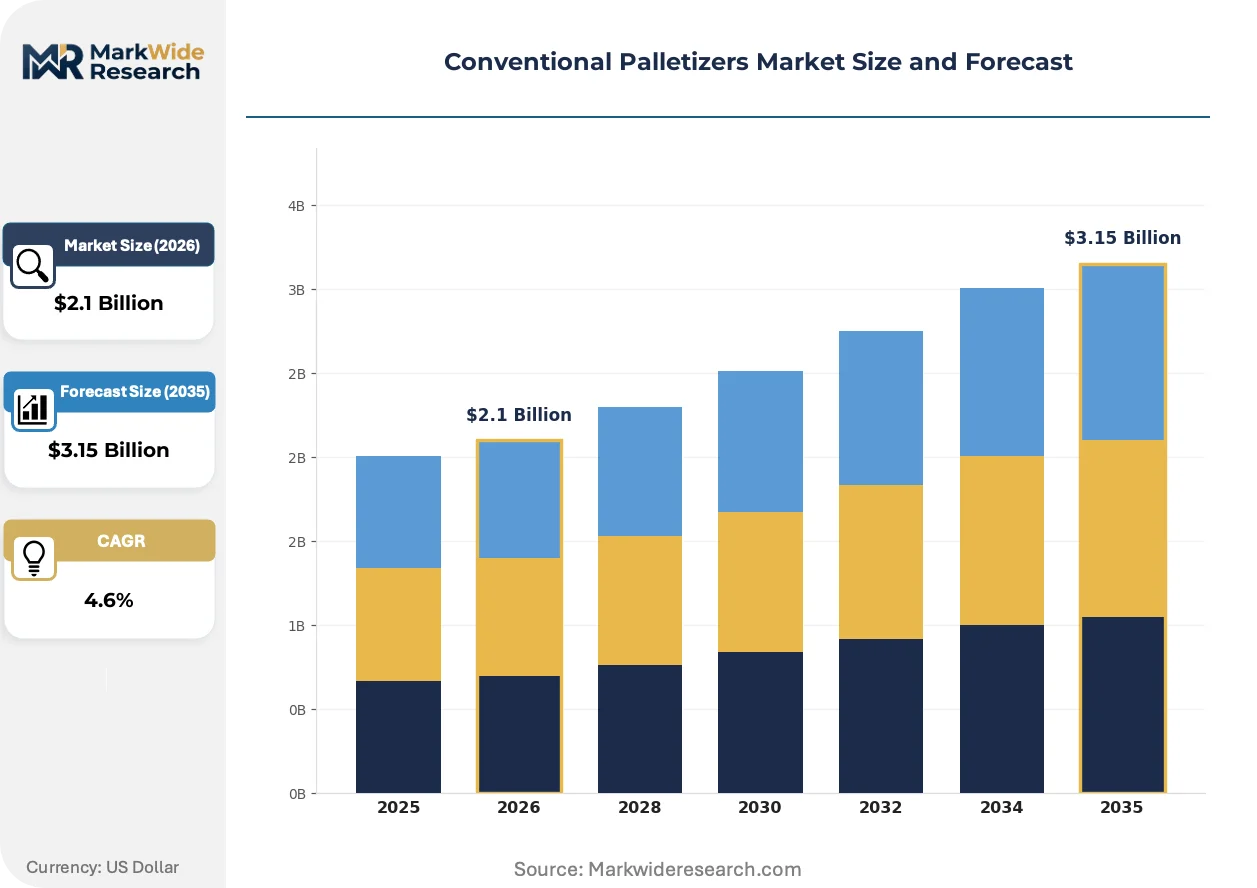
Market Dynamics
Servo motor control systems are compressing pneumatic palletizer margins as beverage packaging lines in Germany and the United States mandate precision positioning for fragile container handling.
Growth Catalysts
- EU Machinery Directive compliance mandates:CE marking requirements for protective enclosures and emergency stop architectures are forcing facility retrofits across European food processing plants.
- Pharmaceutical packaging automation:China's NMPA-aligned safety protocols for sterile drug handling are accelerating layer palletizer installations in domestic contract manufacturing facilities.
- India warehousing densification:Distribution center operators in Mumbai and Delhi are retrofitting mechanical-drive units with servo controls to maximize vertical storage utilization.
Market Restraints
- Copper and rare-earth magnet cost volatility:Servo motor supply chains concentrate in Chinese processing facilities, exposing OEMs to input price swings.
- Hydraulic system obsolescence risk:Regional energy efficiency regulations in the European Union are eroding the installed base of fluid-power palletizers.
- Robotic palletizer substitution:Articulated arm systems from FANUC and KUKA are capturing changeover-flexible applications in consumer electronics packaging.
Strategic Opportunities
- Aftermarket service unbundling:Predictive maintenance contracts on installed layer palletizer bases in the United States are generating recurring revenue streams independent of new equipment sales.
- Hybrid architecture convergence:Integration of mechanical layer-forming with robotic case handling is opening mid-throughput niches between pure conventional and fully robotic systems.
- India PLI scheme alignment:Domestic manufacturing incentives for food processing equipment are creating localized assembly opportunities for multinational suppliers.
Industry Challenges
- Servo control programming expertise scarcity:Facilities in China and India face recruitment gaps for technicians capable of commissioning precision motion systems.
- Legacy mechanical system integration friction:Retrofit projects in Germany's established beverage sector require custom mechanical-to-electronic interface engineering.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Conventional Palletizers Market Trends and Innovations
Digital thread architectures are penetrating palletizer control systems, compressing commissioning timelines and enabling remote diagnostics that reshape supplier-customer relationships across automated warehousing.
Edge computing modules embedded in servo drive controllers are digitizing vibration signature analysis for predictive maintenance. Beverage packaging operators in Germany are deploying these systems at scale to eliminate unplanned downtime during seasonal production peaks. The technology is digitizing traditional break-fix service models into continuous monitoring contracts that lock in supplier relationships.
OSHA machine guarding standards in the United States are mandating light curtain and area scanner configurations that add hardware cost but create compliance barriers for non-certified equipment imports. Food processing facilities in Wisconsin and California are absorbing these costs to avoid citation exposure. The regulation is accelerating consolidation toward suppliers with established safety engineering capabilities.
Service contract unbundling is separating hardware procurement from lifecycle maintenance in buyer decision frameworks. Large distribution center operators in India are negotiating performance-based uptime agreements rather than capital purchase models. This shift is most visible in Mumbai's third-party logistics sector where facility operators prioritize operational expenditure predictability over ownership.
Conventional Palletizers Market Segmentation
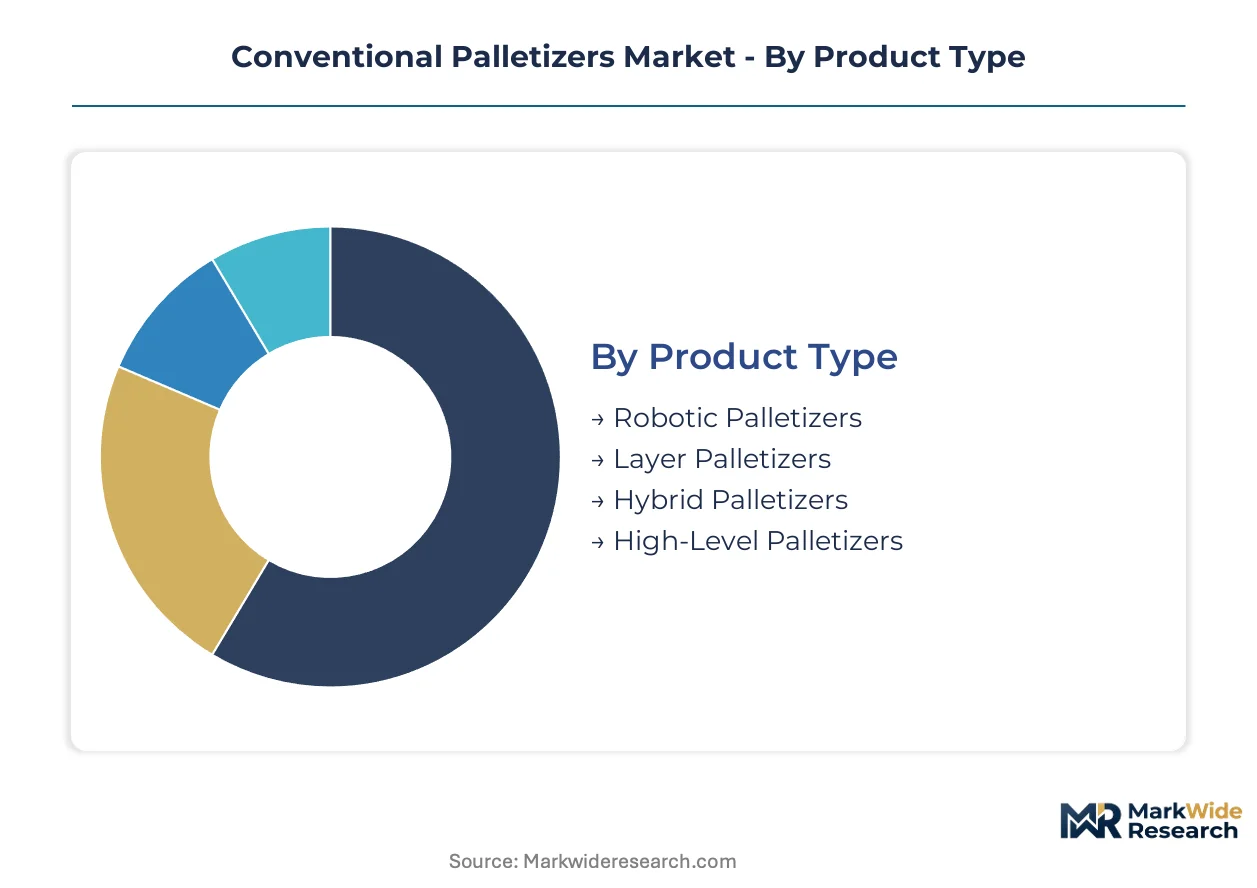
Conventional palletizers serve divergent operational requirements across throughput demands, precision needs, and facility infrastructure maturity. Segmentation reveals how layer-forming architectures dominate beverage packaging while servo motor controls capture retrofit investments in automated warehousing.
Product Type:
Use-case spectrum spans from fixed mechanical layer-forming to articulated robotic flexibility, with hybrid architectures emerging for mid-volume operations requiring changeover adaptability without full robotic cost structures.
- Layer Palletizers:Mechanical or servo-driven systems form complete product layers before depositing onto pallets, achieving throughputs of 20 to 40 cases per minute with consistent load patterns. Beverage packaging lines in Germany and the United States mandate these configurations for fragile container handling under FDA and EU machinery safety directives.
- Robotic Palletizers:Articulated arm systems from suppliers like FANUC and KUKA execute case-level placement with programmable pattern flexibility. Consumer electronics packaging in China favors these systems where SKU proliferation demands rapid changeover capability without mechanical retooling.
- Hybrid Palletizers:Integration of mechanical layer-forming with robotic case handling occupies mid-throughput niches between pure conventional and fully robotic architectures. Distribution centers in India deploy these for mixed-load palletizing where volume variability exceeds pure robotic economic thresholds.
- High-Level Palletizers:Elevated infeed configurations accommodate multi-story facility layouts common in Japanese automotive parts distribution. METI energy efficiency guidelines favor these designs for reduced vertical conveying distances.
Established volume favors Layer Palletizers; emerging adoption favors Robotic Palletizers.
Technology:
Cost tier differentiation separates precision-positioning servo architectures from legacy pneumatic and mechanical alternatives, with hydraulic systems facing obsolescence pressure from regional energy efficiency mandates.
- Servo Motor Control:Closed-loop positioning systems utilizing rare-earth magnet motors achieve ±0.5mm repeatability for fragile product handling. China's NMPA-aligned pharmaceutical packaging protocols require this precision tier for sterile drug container palletizing in domestic contract manufacturing facilities.
- Pneumatic Systems:Compressed-air actuation remains prevalent in legacy food processing installations where capital constraints limit retrofit investments. Wisconsin dairy processors maintain these systems despite OSHA machine guarding upgrade costs for light curtain integration.
- Hydraulic Systems:Fluid-power actuation persists in heavy-load applications exceeding servo motor torque density, though EU F-Gas Regulation and energy efficiency directives are accelerating replacement timelines.
- Mechanical Drives:Cam-and-linkage mechanisms dominate India's warehousing retrofit market where Mumbai and Delhi operators prioritize reliability over precision for standard case dimensions.
Margin concentration sits with Servo Motor Control; installed base preservation favors Mechanical Drives.
Application:
Customer type segmentation reflects divergent regulatory exposure, with pharmaceutical and food processing bearing compliance burdens that beverage and electronics applications avoid.
- Beverage Packaging:Glass and PET container handling demands gentle acceleration profiles and layer stability verification. German producers under KBA-aligned machinery safety standards specify interlocked guarding configurations that add hardware cost but prevent citation exposure.
- Food Processing:USDA and FDA sanitation requirements drive stainless steel construction and washdown-rated enclosures. California Central Valley tomato processors deploy layer palletizers with IP69K servo drive housings for seasonal harvest peaks.
- Pharmaceutical Packaging:Sterile drug handling under China's GB standards and NMPA protocols mandates cleanroom-compatible palletizing with HEPA filtration and vibration isolation.
- Consumer Electronics:High-value product protection prioritizes damage-free handling over throughput maximization, with robotic systems preferred for mixed-SKU fulfillment center operations.
Regulatory intensity peaks in Pharmaceutical Packaging; volume scale concentrates in Beverage Packaging.
End User:
Geography shapes facility type distribution, with manufacturing plants concentrated in industrial corridors and distribution centers clustering near port infrastructure and consumer markets.
- Distribution Centers:Third-party logistics operators in Mumbai negotiate performance-based uptime agreements rather than capital purchase models, prioritizing operational expenditure predictability.
- Manufacturing Plants:End-of-line integration requirements favor turnkey palletizer installations with upstream case conveyor synchronization. German automotive suppliers specify CE-marked systems with integrated safety PLCs.
- Warehousing Facilities:Vertical storage densification drives servo retrofit demand in India's Delhi NCR region where land costs accelerate multi-level rack utilization.
- Logistics Providers:Asset-light operators favor service-contract unbundling, with predictive maintenance agreements replacing traditional break-fix relationships.
Contract innovation originates with Logistics Providers; equipment ownership concentration remains with Manufacturing Plants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography. German beverage producers prioritize layer-forming precision under machinery safety mandates, while Indian distribution centers retrofit mechanical units for vertical density, and Chinese pharmaceutical contractors specify servo controls for sterile handling protocols.
United States
Beverage packaging lines in Wisconsin and California drive layer palletizer installations for fragile container handling. OSHA machine guarding standards mandate light curtain and area scanner configurations that add hardware cost but prevent citation exposure. Food processing clusters in the Central Valley deploy IP69K-rated servo drive housings for seasonal tomato harvest peaks.
Germany
KBA-aligned machinery safety standards enforce interlocked guarding configurations across automotive parts distribution and beverage production. EU Machinery Directive CE marking requirements accelerate facility retrofits in North Rhine-Westphalia. Layer palletizer demand concentrates in Bavarian brewing operations where precision positioning protects glass container integrity.
China
NMPA-aligned safety protocols for sterile drug handling accelerate servo-controlled layer palletizer installations in domestic contract manufacturing. GB standards segment market access for pharmaceutical packaging applications. Yangtze River Delta distribution centers retrofit mechanical-drive units with rare-earth magnet servo systems for ±0.5mm repeatability requirements.
India
Mumbai and Delhi distribution center operators retrofit mechanical-drive palletizers with servo controls to maximize vertical storage utilization. PLI scheme incentives for food processing equipment create localized assembly opportunities for multinational suppliers. Third-party logistics providers in the Delhi NCR region negotiate performance-based uptime agreements prioritizing operational expenditure predictability.
Japan
METI energy efficiency guidelines favor high-level palletizer configurations for reduced vertical conveying distances in multi-story automotive parts distribution facilities. Kanto region logistics operators deploy elevated infeed systems to optimize land-constrained facility layouts. Precision motion control requirements in Osaka-area electronics fulfillment sustain demand for hybrid palletizer architectures.
Conventional Palletizers Market Competitive Landscape
Capability concentration sits with servo control specialists; scale advantage sits with diversified automation conglomerates. The vendor base structures around three tiers: precision motion technology providers, integrated packaging line suppliers, and regional fabrication specialists. Strategic moves center on aftermarket service network expansion and hybrid architecture development bridging mechanical layer-forming with robotic flexibility.
Among diversified automation conglomerates, ABB leverages global service infrastructure for recurring maintenance contract capture. FANUC and KUKA occupy positions within precision motion tiers, with the former exemplifying servo control integration expertise and the latter anchoring European manufacturing scale for rapid spare parts fulfillment. These three represent distinct competitive archetypes: service-networked systems integrator, motion control technology originator, and regionally anchored fabrication scale player.
| Leading Market Players |
|---|
| ABB |
| BEUMER Group |
| FANUC |
| KUKA |
| Krones |
| Columbia Machine |
| PAYPER |
| Concetti |
| MSK Covertech |
| Others |
Pricing and Supply Chain Analysis
Rare-earth magnet supply concentration in Chinese processing facilities determines both servo motor pricing tier spreads and procurement geography for palletizer OEMs. Copper price volatility and tariff exposure on precision motion components compress margins for mid-tier suppliers while rewarding vertically integrated servo specialists with captive magnet sourcing.
Pricing Analysis
Long-term service contracts dominate buyer-supplier relationships, with performance-based uptime agreements replacing capital purchase models among Mumbai third-party logistics operators. Three-tier pricing structure across premium servo systems, standard pneumatic configurations, and economy mechanical drives reflects certification grade differentiation under EU Machinery Directive CE marking and OSHA machine guarding standards. Pricing pressure stems from robotic palletizer substitution in consumer electronics packaging, where FANUC and KUKA articulated arm systems capture changeover-flexible applications. Beverage packaging lines in Germany and the United States exhibit lowest price sensitivity due to regulatory compliance mandates, while Indian warehousing retrofits prioritize operational expenditure predictability over capital ownership.
Supply Chain Analysis
Tariff exposure between China and Western markets dominates supply chain risk planning for rare-earth magnet-dependent servo motor controllers. Component sourcing concentrates in Chinese rare-earth processing facilities, German precision gearbox manufacturing, and Japanese servo drive electronics. Raw material dependencies include neodymium-iron-boron magnets, copper windings, and specialized aluminum castings for structural frames. Single-source vulnerability in Chinese magnet supply creates procurement contingency requirements for OEMs serving FDA-regulated pharmaceutical packaging lines. Distribution runs through authorized service networks for aftermarket parts fulfillment, with ABB leveraging global infrastructure for recurring maintenance contract capture.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Servo control programming expertise scarcity constrains facility commissioning timelines across Chinese and Indian retrofit markets, creating competitive advantage for suppliers with certified technician networks. Technical workforce gaps in precision motion systems represent the critical capability bottleneck shaping market access.
For Market Incumbents: Entrench market position through predictive maintenance contract unbundling on installed layer palletizer bases in the United States, converting break-fix relationships into recurring revenue streams. Deepen backward integration into servo motor manufacturing to offset rare-earth magnet cost volatility exposure. Defend against robotic palletizer substitution by accelerating hybrid architecture development that merges mechanical layer-forming precision with robotic case-handling flexibility for mid-throughput beverage applications. For New Entrants and Emerging Players: India's PLI scheme-aligned domestic assembly opportunity offers the most penetrable geographic entry point for multinational suppliers seeking localized production footholds. Target Mumbai and Delhi distribution center operators with servo retrofit solutions for vertical storage densification, where mechanical-to-electronic upgrade demand outstrips qualified supplier capacity. Pursue performance-based uptime agreements rather than equipment sales to match third-party logistics procurement preferences for operational expenditure predictability. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors servo control specialists with aftermarket service network scale. Long-term viability centers on predictive maintenance platform ownership and hybrid palletizer intellectual property positions. Target acquisition archetypes include regional fabrication specialists with established CE marking safety engineering capabilities and spare parts fulfillment infrastructure. Watch for inflection signals in China's NMPA pharmaceutical packaging automation procurement velocity, which would accelerate servo-controlled layer palletizer demand beyond current contract manufacturing facility installation rates.| Strategic Initiative | Industry Significance |
|---|---|
| Aftermarket Service Network Expansion | ABB's global infrastructure captures recurring maintenance contracts independent of new equipment sales cycles. |
| Hybrid Architecture Development | Integration of mechanical layer-forming with robotic case handling opens mid-throughput niches between pure system types. |
| Servo Control Technology Integration | FANUC's deep motion control expertise sustains competitive positioning in precision-positioning applications. |
| Regional Manufacturing Scale Investment | KUKA's German production footprint supports rapid spare parts fulfillment for Bavarian beverage packaging clients. |
| Predictive Maintenance Platform Deployment | Edge computing modules digitize vibration signature analysis, eliminating unplanned downtime during seasonal production peaks. |
Research Methodology
Operator-level perspectives from plant engineers, maintenance directors, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with facility operators in German beverage packaging, Indian third-party logistics, and Chinese pharmaceutical contract manufacturing with secondary validation against EU Machinery Directive compliance documentation, OSHA machine guarding standards, and NMPA sterile handling protocols. Customs records for servo motor and rare-earth magnet trade flows, SEC filings from diversified automation conglomerates, and industry association technical specifications provided quantitative grounding. Bottom-up installation base modeling and top-down market sizing triangulated volume and value estimates.
Scenario-bracketing around regulatory compliance timelines, rare-earth supply disruption probabilities, and robotic substitution velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type architecture, technology tier, application regulatory intensity, and end-user facility category. CAGRs derived from equipment replacement cycle analysis, retrofit investment patterns, and greenfield automation adoption curves. Industry-specific forecast inputs incorporated pharmaceutical packaging automation mandates under China's GB standards and India's PLI scheme incentive structures for food processing equipment.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by rare-earth magnet processors or accelerated robotic palletizer cost reduction would shift outcomes. Forecasts reflect documented assumptions about technician availability constraints, regulatory enforcement consistency, and commodity price stabilization. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.