
 Global Wood Pallet Market | 2026-2036
Global Wood Pallet Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wood Pallet Market Outlook
Market Context
The EU Green Deal is expanding demand for reusable, repairable wood pallets across European supply chains. CHEP (Brambles Ltd.) leverages its pooled pallet network to dominate closed-loop logistics across Germany and France. UFP Industries Inc. sustains manufacturing scale through vertical sawmill operations in the US Southeast. PalletOne Inc. anchors regional density with multi-state production facilities serving grocery and automotive customers.
Technical Definition and Segment Structure
Wood pallets are portable platforms built from hardwood or softwood lumber, typically measuring 48 by 40 inches, designed to support goods during lifting, stacking, and transport by forklift or pallet jack. The grocery segment leads by product type, driven by cold chain compliance requirements and frequent turnover rates. Within end users, logistics providers represent the fastest-expanding category as third-party fulfillment networks multiply. The reconditioned grade captures significant margin pools through lower input costs and extended asset lifecycles.
Regulatory Framework
ISPM 15 phytosanitary standards, enforced by national plant protection agencies in the US, EU, and China, mandate heat treatment or fumigation for international wood pallet shipments. EPA guidelines in the US and REACH compliance in Europe shape chemical treatment protocols and emissions thresholds for pallet manufacturing. Stakeholders must monitor evolving circular economy mandates that could mandate minimum reuse quotas or restrict single-use alternatives.
Market Dynamics
The EU Green Deal's packaging waste regulations are forcing supply chain operators to abandon single-use wood pallets in favor of pooled, repairable assets. This regulatory pivot is compressing replacement cycles and concentrating procurement decisions among logistics providers with reverse-logistics capabilities.
Growth Catalysts
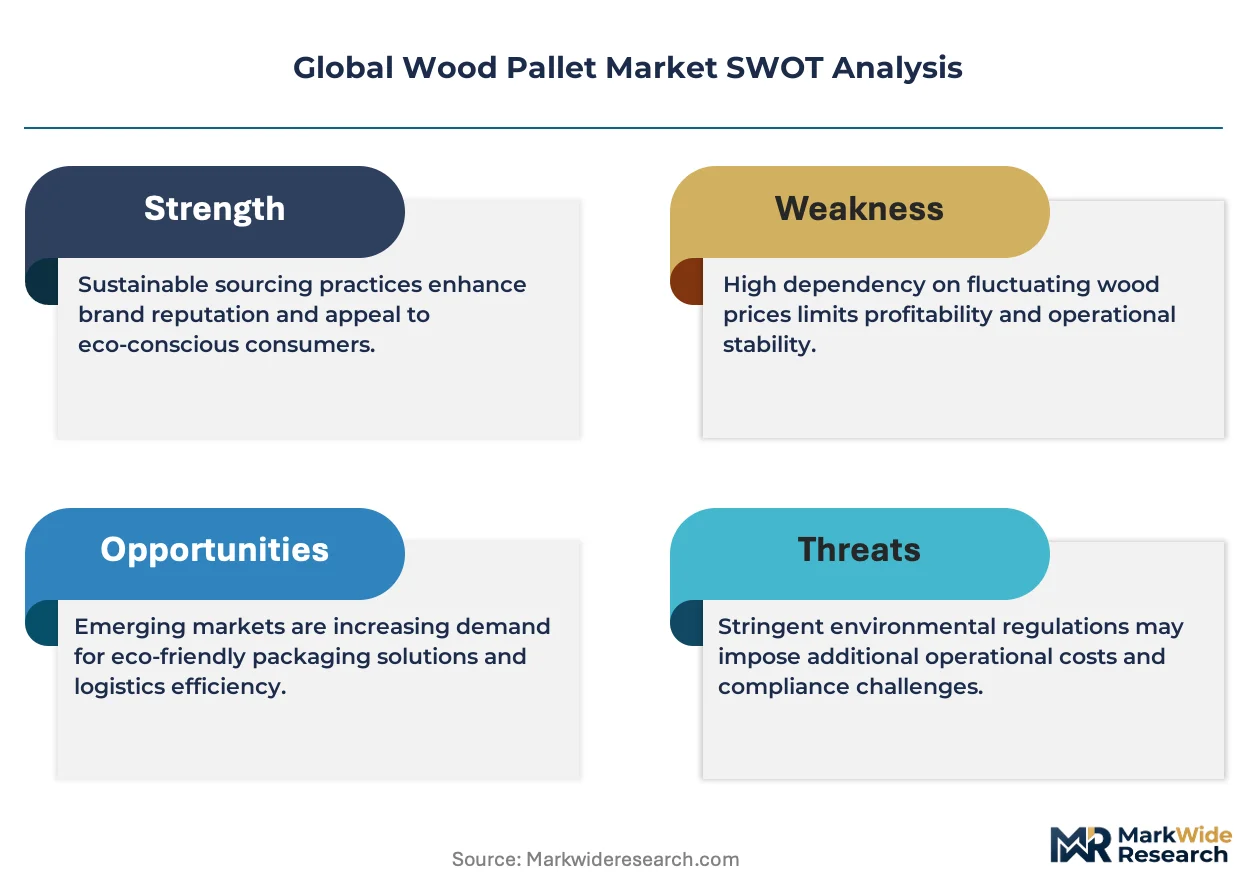
- ISPM 15 compliance mandates:Heat-treatment requirements for cross-border shipments are standardizing quality thresholds and eliminating untreated pallet suppliers from international lanes.
- E-commerce cold chain expansion:Grocery and pharmaceutical fulfillment networks are multiplying pallet touchpoints through refrigerated last-mile infrastructure.
- Germany's industrial corridor:Stuttgart and Munich manufacturing clusters are generating dense, predictable pallet demand from automotive and machinery exporters.
Market Restraints
- Lumber price volatility:Softwood input costs fluctuate with North American housing construction cycles, squeezing margins for non-integrated manufacturers.
- Regional sawmill concentration:US Southeast timber processing dominance creates freight cost penalties for Midwest and Northeast pallet producers.
- Plastic pallet substitution:Nestable, hygienic plastic alternatives are capturing pharmaceutical and electronics segments requiring washdown protocols.
Strategic Opportunities
- India's organized retail buildout:Modern grocery and FMCG distribution infrastructure remains underpenetrated by pooled pallet networks.
- RFID-embedded track-and-trace:Converging sensor technology with pallet pooling platforms enables real-time asset visibility and dynamic routing.
- EU circular economy mandates:Proposed reuse quotas for transport packaging would structurally advantage repair-grade pallet suppliers over single-use manufacturers.
Industry Challenges
- Heat-treatment certification backlog:ISPM 15 accreditation timelines create operational bottlenecks for exporters facing customs enforcement.
- Repair labor scarcity:Nail gun operators and grade-sorting technicians are aging out of the workforce faster than training programs replenish capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wood Pallet Market |
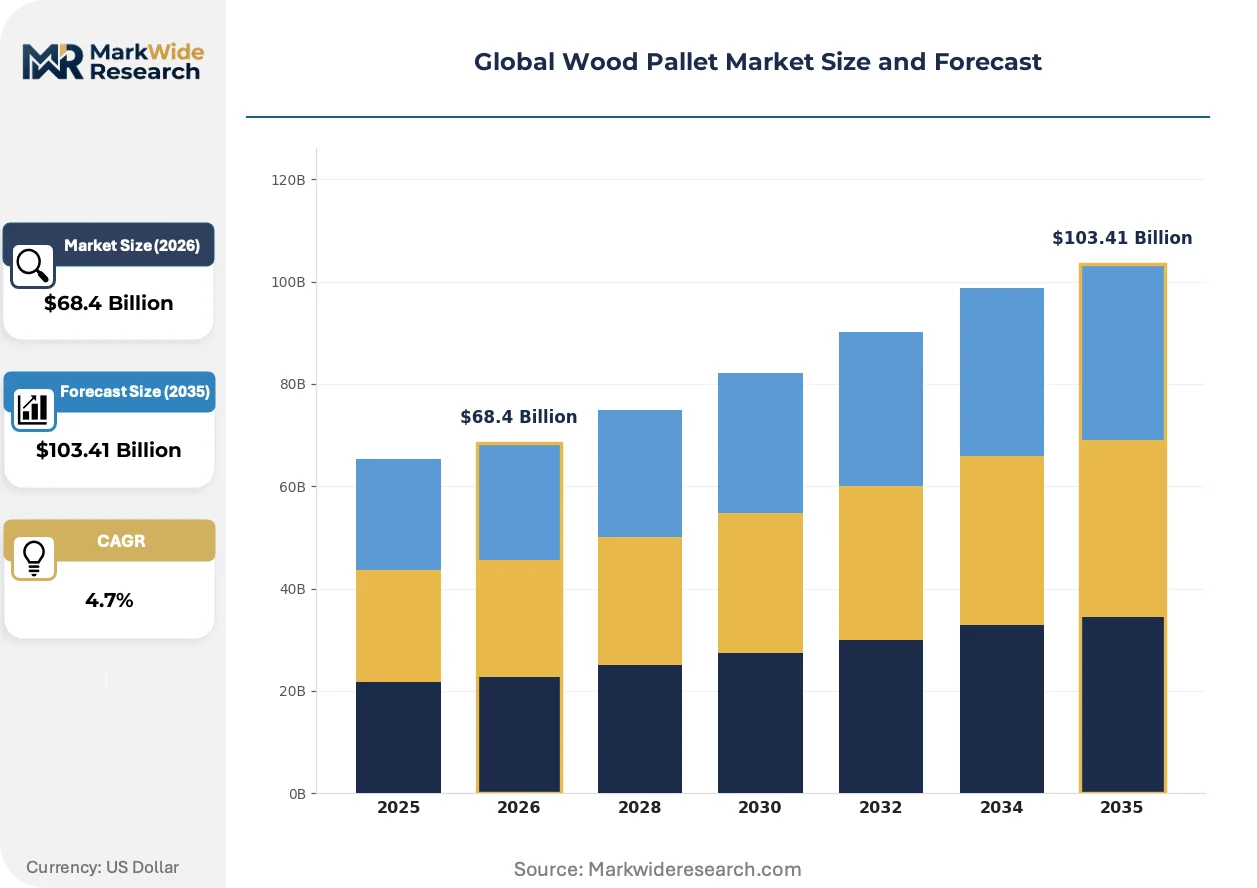
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $103.41 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Grocery, Beverage, Automotive, Electronics End User: Retail, Food Service, Manufacturing, Logistics Distribution Channel: Direct Sales, Distributors, E-commerce, Retailers Grade: New, Reconditioned, Used, Others |
| Companies Covered | CHEP (Brambles Ltd.), UFP Industries Inc., PalletOne Inc., PECO Pallet Inc., Falkenhahn AG, Kamps Inc., Millwood Inc., Loscam International Holdings Co. Ltd., NEFAB Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wood Pallet Market Strategic Shifts
Asset digitization and regulatory tightening are converging to transform wood pallets from passive commodity platforms into active data nodes and compliance instruments. Three developments are restructuring competitive requirements.
RFID and IoT sensor integration is expanding into pooled pallet fleets as Brambles and regional operators deploy track-and-trace infrastructure. Third-party logistics providers are adopting tagged assets at accelerating rates to meet retailer visibility mandates. This technology is expanding into inventory optimization and automated yard management, compressing the information advantage of vertically integrated operators.
REACH chemical compliance in Europe is restricting preservative treatments and emissions thresholds for heat-treatment kilns. Manufacturers are retrofitting facilities with emission capture systems or relocating production to Eastern European zones with looser enforcement. The reconditioned pallet segment faces the steepest adaptation costs as older stock must be re-certified under tightened protocols.
Buyer consolidation among grocery and big-box retailers is compressing supplier rosters and extending payment terms. Regional pallet manufacturers are ceding share to pooled-network operators with balance-sheet capacity to absorb working capital strain. This concentration is most visible in France and Germany, where Carrefour and Metro Group have standardized on single-source pooling contracts.
Global Wood Pallet Market Segmentation
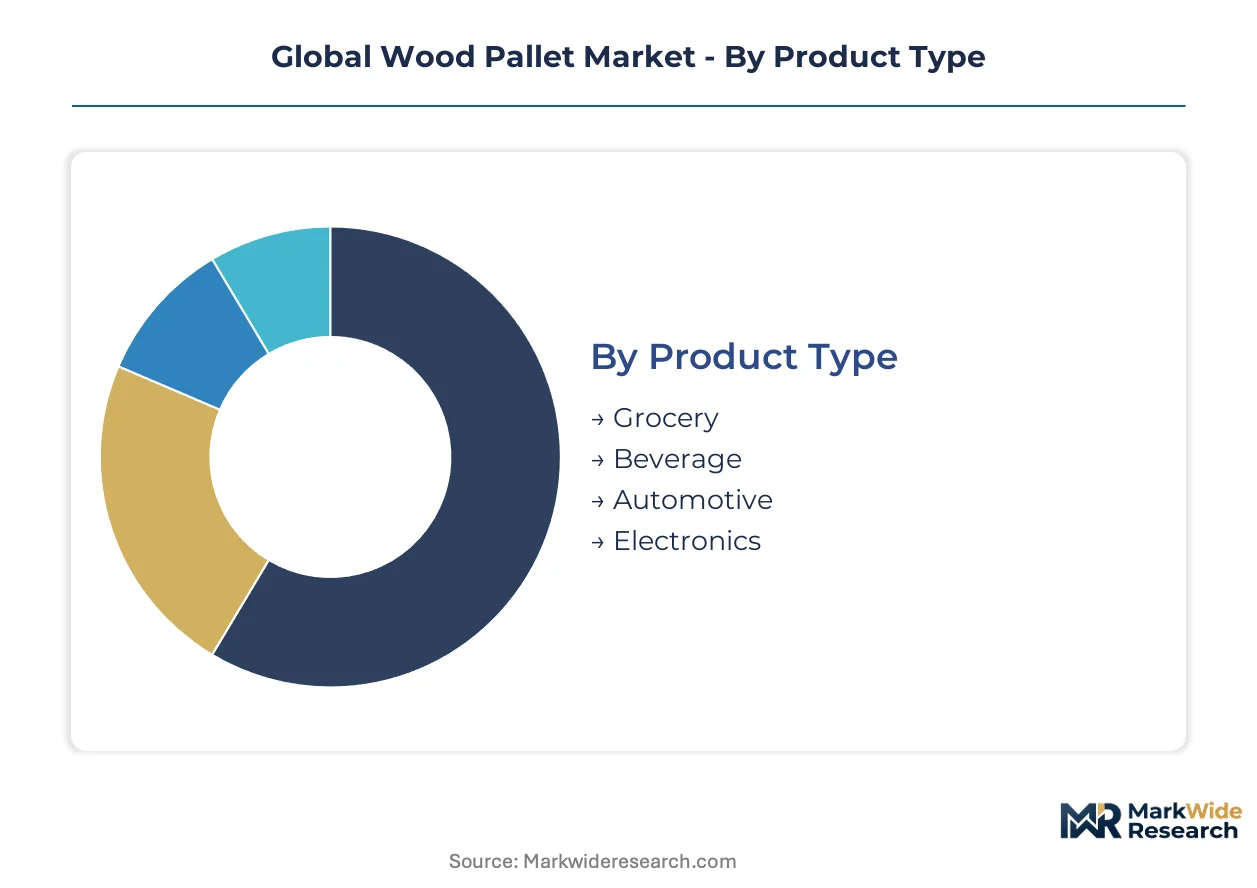
Wood pallet procurement varies sharply by buyer sophistication and asset lifecycle strategy. Grocery chains prioritize pooled, trackable pallets for cold chain compliance, while automotive exporters favor owned fleets for predictable export schedules. Understanding segment boundaries clarifies where pooled-network operators capture margin versus where spot-market suppliers compete on price.
Product Type:
Application-specific durability requirements and handling frequency drive product selection across buyer categories.
- Grocery:Moisture-resistant hardwood construction withstands refrigerated environments and repeated washdown cycles. Demand clusters in Germany's Stuttgart-Munich corridor where cold chain density supports CHEP and PalletOne pooling infrastructure.
- Beverage:Heavy-load softwood designs accommodate concentrated liquid weights during stacking and transport. German beverage exporters to EU and non-EU destinations generate consistent heat-treated pallet demand under ISPM 15 protocols.
- Automotive:Precision-grade platforms with reinforced stringers protect high-value components during just-in-time delivery sequences.
- Electronics:Static-dissipative finishes and dimensional tolerances safeguard sensitive semiconductor and consumer device shipments.
Volume sits with Grocery; growth tilts toward Electronics as semiconductor supply chains expand cleanroom-grade pallet specifications.
End User:
Asset control philosophy separates buyers who own pallets from those who rent through pooling networks.
- Logistics:Third-party fulfillment providers aggregate pallet demand across multiple shipper clients, creating scale economies for RFID-tracked pooled assets. E-commerce cold chain expansion multiplies touchpoints through refrigerated last-mile infrastructure.
- Manufacturing:Automotive and machinery producers in Germany's industrial belt maintain captive pallet fleets for export predictability. ISPM 15 heat-treatment certification backlogs create operational bottlenecks for customs-facing shipments.
- Retail:Big-box consolidation compresses supplier rosters and extends payment terms, favoring pooled-network balance sheet capacity.
- Food Service:Restaurant distribution networks favor lightweight, nestable designs for frequent truck loading and urban delivery constraints.
Logistics providers command the steepest expansion trajectory as third-party fulfillment networks multiply across European and North American markets.
Distribution Channel:
Channel selection reflects order scale, customization requirements, and buyer procurement sophistication.
- Direct Sales:Large-volume grocery and automotive accounts negotiate multi-year contracts with manufacturers or pooling operators. UFP Industries and CHEP anchor direct relationships through vertical sawmill control and balance-sheet capacity.
- Distributors:Regional pallet resellers aggregate fragmented demand from small and mid-sized manufacturers lacking pooled-network access.
- E-commerce:Digital procurement platforms serve spot-market buyers with standardized specifications and rapid fulfillment needs.
- Retailers:Big-box chains with private-label pallet programs source directly through captive supply arrangements.
Direct Sales captures margin concentration; E-commerce climbs fastest as digital procurement penetrates mid-market manufacturing segments.
Grade:
Asset lifecycle positioning determines cost structure and regulatory exposure for pallet suppliers.
- Reconditioned:Repair-grade pallets extend asset lifecycles through nail replacement, board substitution, and re-certification. REACH chemical compliance in Europe imposes steep adaptation costs as older stock requires re-certification under tightened protocols.
- New:Virgin lumber construction meets stringent export and hygiene requirements for pharmaceutical and food-grade applications. Softwood input costs fluctuate with North American housing construction cycles, squeezing margins for non-integrated manufacturers.
- Used:Single-trip or limited-reuse pallets serve low-value, non-regulated domestic freight with minimal quality assurance.
- Others:Specialty grades including heat-treated export stock and custom-engineered designs for unique load requirements.
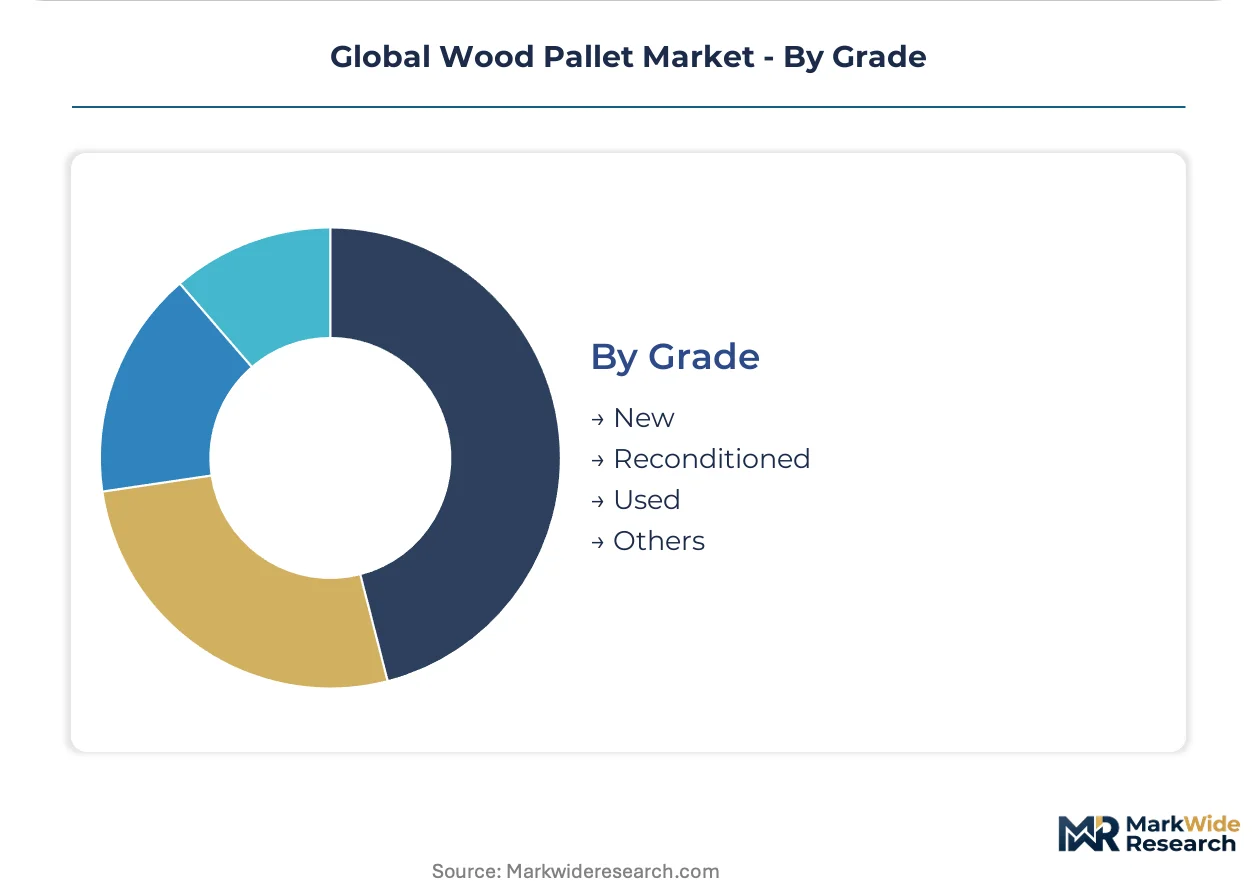
Reconditioned dominates volume throughput; New grade gains fastest as EU circular economy mandates tighten reuse quotas and quality thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors European wood pallet demand through Germany's dense automotive and machinery manufacturing belt. The EU Green Deal's packaging waste regulations are compressing replacement cycles across industrial corridors in France, Poland, and Italy.
United States
Softwood lumber availability from Southeast sawmill networks sustains pallet manufacturing scale for grocery and beverage distribution. EPA emissions guidelines shape heat-treatment kiln operations across Georgia and Alabama processing zones. The Southeast timber belt around Atlanta and Charlotte generates freight cost advantages for regional producers serving East Coast cold chain networks.
Germany
Automotive exporters in Baden-Württemberg generate predictable demand for ISPM 15-certified heat-treated pallets. EU Green Deal circular economy mandates are accelerating pooled-network adoption over single-use alternatives. The Stuttgart-Munich industrial corridor concentrates procurement decisions among logistics providers with reverse-logistics capabilities.
China
E-commerce fulfillment infrastructure expansion multiplies pallet touchpoints through refrigerated last-mile networks. GB standards and MIIT regulations govern domestic transport packaging quality thresholds. The Yangtze River Delta manufacturing zone around Shanghai generates export-grade pallet demand for cross-border electronics and machinery shipments.
India
Organized retail buildout in FMCG distribution creates underpenetrated demand for pooled pallet networks. FSSAI cold chain compliance requirements are standardizing hygiene protocols for food-grade transport platforms. Maharashtra's Mumbai-Pune industrial corridor anchors initial pooling infrastructure trials with modern grocery chains.
France
Big-box retailer consolidation compresses supplier rosters toward pooled-network operators with balance-sheet capacity. ECHA REACH compliance restricts preservative treatments for pallets serving pharmaceutical and food segments. The Île-de-France logistics zone around Paris concentrates third-party fulfillment demand from grocery and electronics distributors.
Global Wood Pallet Market Competitive Environment
Premium-margin players sit above commodity-margin players across pooled-network scale and sawmill integration depth. The vendor base stratifies between balance-sheet-heavy pooling operators, vertically integrated manufacturers, and regional repair-grade specialists. Three archetypes dominate: pooled-network platforms with RFID-tracked assets, sawmill-integrated producers with captive lumber supply, and reconditioning specialists extending asset lifecycles. Competitive moves center on M&A for regional density and kiln capacity expansion for ISPM 15 certification coverage.
Among pooled-network operators, CHEP (Brambles Ltd.) exemplifies the balance-sheet-intensive archetype through its closed-loop logistics infrastructure. UFP Industries Inc. and PalletOne Inc. represent the North American integrated manufacturing tier, with geographic naming conventions indicating US market anchoring. These three occupy positions spanning premium-margin pooling and scale-driven fabrication segments.
| Leading Market Players |
|---|
| CHEP (Brambles Ltd.) |
| UFP Industries Inc. |
| PalletOne Inc. |
| PECO Pallet Inc. |
| Falkenhahn AG |
| Kamps Inc. |
| Millwood Inc. |
| Loscam International Holdings Co. Ltd. |
| NEFAB Group |
| Others |
Value Chain & Pricing Dynamics
ISPM 15 certification tiers bifurcate the wood pallet market into export-grade premium assets and domestic-spot commodity stock, with that divergence manifesting in both per-unit pricing spreads and supply chain configurations that cluster heat-treatment capacity near customs-heavy logistics corridors. Pooled-network operators command price premiums through guaranteed availability and reverse-logistics infrastructure, while spot-market suppliers compete on lumber input costs and regional freight arbitrage.
Pricing Analysis
Throughput-based pooling fees anchor value-based pricing for logistics providers seeking asset availability guarantees over ownership. Three-tier pricing structure across premium certified-export, standard domestic-grade, and economy single-use tiers reflects ISPM 15 compliance status and repair-cycle depth. Cost compression in the new-grade segment is intensifying because softwood lumber prices fluctuate with North American housing construction cycles. Automotive exporters exhibit lowest price sensitivity due to customs-delay costs, while food service distributors prioritize per-unit minimization over lifecycle value.
Supply Chain Analysis
Freight cost penalties from sawmill concentration in the US Southeast, Germany's Baden-Württemberg timber belt, and China's Yangtze River Delta shape regional manufacturing competitiveness. Raw material flows draw from North American softwood forests, European hardwood plantations, and Russian birch imports prior to sanctions. Single-source vulnerability in ISPM 15-accredited kiln capacity creates export bottlenecks for untreated stock. Distribution runs through direct sales contracts for large grocery and automotive accounts, with regional distributors serving fragmented mid-market manufacturers lacking pooled-network access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Repair-grade labor scarcity constrains supply elasticity, propping pricing power for pooled-network operators with trained technician pipelines and automated sorting infrastructure.
For Market Incumbents: Acquire RFID-tracked pallet fleets and reverse-logistics depots to consolidate regional density against plastic pallet substitution in pharmaceutical segments. Expand heat-treatment kiln capacity in Germany's Stuttgart corridor to capture ISPM 15 certification backlogs. Backward integration into sawmill operations insulates margin from lumber price volatility in the US Southeast. For New Entrants and Emerging Players: Launch via digital procurement platforms targeting India's underpenetrated organized retail buildout in the Mumbai-Pune corridor. White-space opportunities concentrate in reconditioned-grade automation for REACH compliance adaptation costs. Partner with third-party logistics providers for pooled-network trials rather than competing against CHEP's balance-sheet scale directly. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by pooled-network operators seeking regional density or sawmill-integrated manufacturers with captive lumber supply. Long-term viability favors repair-grade specialists with technician training pipelines and emission-compliant kiln retrofits. Watch EU circular economy mandate implementation timelines as inflection indicators for reuse quota structural advantages.| Strategic Initiative | Industry Significance |
|---|---|
| Kiln Capacity Expansion | ISPM 15 heat-treatment accreditation eliminates customs bottlenecks for cross-border automotive exporters. |
| RFID Fleet Digitization | Real-time asset visibility meets retailer track-and-trace mandates in grocery cold chain networks. |
| Repair Automation Investment | Automated nail-gun and grade-sorting systems offset technician aging-out in European reconditioning facilities. |
| Backward Sawmill Integration | Captive softwood supply insulates margin from North American housing construction cycle volatility. |
| India Pooled Network Pilot | FSSAI cold chain compliance standardization creates first-mover advantage in organized retail buildout. |
Study Parameters
Multi-period observation of lumber price indices, ISPM 15 accreditation backlogs, and pooled-network fleet utilization anchored the trend analysis, supplemented by interviews with pallet manufacturing plant managers, grocery chain procurement directors, third-party logistics operations heads, and heat-treatment facility compliance officers. Secondary validation drew from EPA emissions filings, ECHA REACH substance registrations, EU customs trade data, and SEC disclosures from listed pooling operators. Bottom-up segmentation sizing and top-down macroeconomic anchoring were cross-checked for convergence.
Input-output matrices modeled pallet stock volumes against replacement rates, repair-cycle throughput, and export certification demand across the projection horizon. Segmentation dimensions included product type, end-user control philosophy, distribution channel scale, and asset lifecycle grade. CAGRs were derived from trend extrapolation of historical replacement cycles adjusted for regulatory compression effects. Industry-specific forecast inputs incorporated EU Green Deal implementation pacing and e-commerce cold chain infrastructure buildout rates.
Lumber price volatility, ISPM 15 enforcement tightening timelines, and plastic pallet substitution acceleration in pharmaceutical segments are the dominant revision risks that could shift volume trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Corner Boards Market
Pallets Packaging
Pallet Jacks Market
Pallets Packaging
Pallet Tines Market
Pallets Packaging
Molded Wood Pallets Market
Pallets Packaging
Pallet Shippers Market
Pallets Packaging
Pallet Wrappers Market
Pallets Packaging
Pallet Labeler Market
Pallets Packaging
Middle East and Africa Lumber Pallet Market
Pallets Packaging
France Pallets Market
Pallets Packaging
Stringer Pallets Market
Pallets Packaging
Single Use Pallet Market
Pallets Packaging
Disposable Plastic Pallet Market
Pallets Packaging
India Pallets Market
Pallets Packaging
Conventional Palletizers Market
Pallets Packaging
Wooden Pallet Collars Market
Pallets Packaging
North America Lumber Pallet Market