
 France Pallets Market | 2026-2036
France Pallets Market Size, Share, and Industry Trends Forecast 2026-2036
France Pallets Market Insights
Market Context with Strategic Players
EU Green Deal packaging sustainability rules are expanding the cost-of-entry calculus for pallet manufacturers serving French supply chains. PGS Group leverages backward integration into wood sourcing and repair networks to sustain competitive positioning across northern France. LPR - La Palette Rouge dominates the pooling segment through its closed-loop rental system, while Burban Palettes specializes in custom hardwood solutions for heavy manufacturing clients in the Rhône-Alpes basin.
Technical Definition and Structural Segments
A pallet is a flat transport structure built to ISO 6780 dimensions, typically assembled from nailed wooden slats, injection-molded HDPE, or welded steel tubing, designed to support goods in a stable fashion during lifting by forklifts, pallet jacks, or conveyors. Wood pallets retain volume leadership in France due to lower unit economics and established repair infrastructure, though plastic pallets are capturing share in pharmaceutical and food processing end uses where hygiene traceability commands premium positioning. Block-type configurations lead transport applications for their four-way entry efficiency, while stringer designs persist in warehousing for their simpler stacking geometry and repairability.
Regulatory Framework and Outlook
France's national implementation of EU REACH chemicals regulation, CE marking for machinery compatibility, and F-Gas rules for cold-chain equipment collectively shape material selection and product lifespan requirements across the pallet sector. ANSM pharmaceutical traceability standards and ECHA biocide restrictions on wood treatment chemicals further tighten compliance thresholds for suppliers serving regulated industries. Stakeholders must monitor evolving Extended Producer Responsibility frameworks and decide whether to invest in plastic pallet fleets or advanced wood treatment alternatives before compliance costs reshape competitive margins.
Market Dynamics
EU Green Deal packaging sustainability rules are compressing replacement cycles and forcing pooled fleet investments across French supply chains, restructuring competitive economics for manufacturers and logistics operators alike.
Growth Catalysts
- Cold-chain traceability mandates:ANSM pharmaceutical standards and EU F-Gas rules drive pooled plastic pallet adoption in vaccine and biologics distribution across Grand Est and Île-de-France corridors.
- Food processing consolidation:Major French dairy and meat processors are standardizing on RFID-tracked pooling programs to satisfy EU Green Deal circularity requirements.
- Automotive just-in-time density:The Strasbourg-Nancy logistics corridor sustains premium block-pallet demand from powertrain and component suppliers serving German OEM plants.
Market Restraints
- Treated wood chemical restrictions:ECHA biocide limitations on creosote and copper-based wood preservatives raise material costs for hardwood pallet producers serving heavy manufacturing.
- Resin price volatility:HDPE and PP feedstock fluctuations compress margins for injection-molded plastic pallet manufacturers despite hygiene premiums in food and pharma end uses.
- Repair network geographic gaps:Rural western France lacks sufficient pallet collection and refurbishment infrastructure, raising logistics costs for pooling operators.
Strategic Opportunities
- Brittany seafood export corridor:Quimper and Lorient processing hubs present untapped demand for hygienic plastic pallets with temperature logging for Asian premium markets.
- Extended Producer Responsibility frameworks:France's advancing EPR rules for packaging waste create first-mover advantages for manufacturers offering take-back and recycling programs.
- RFID-IoT convergence:Integration of passive RFID tags with cloud-based fleet management platforms enables outcome-based pooling contracts for pharmaceutical distributors.
Industry Challenges
- Repair technician shortage:Aging workforce in northern France wood pallet refurbishment facilities constrains pooling fleet turnaround capacity.
- CE marking compliance timelines:Machinery directive updates for automated pallet handling equipment delay new product introductions by 8-14 months.
- Legacy warehouse system integration:ERP compatibility gaps block real-time pallet tracking adoption among mid-sized Rhône-Alpes 3PL operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Pallets Market |
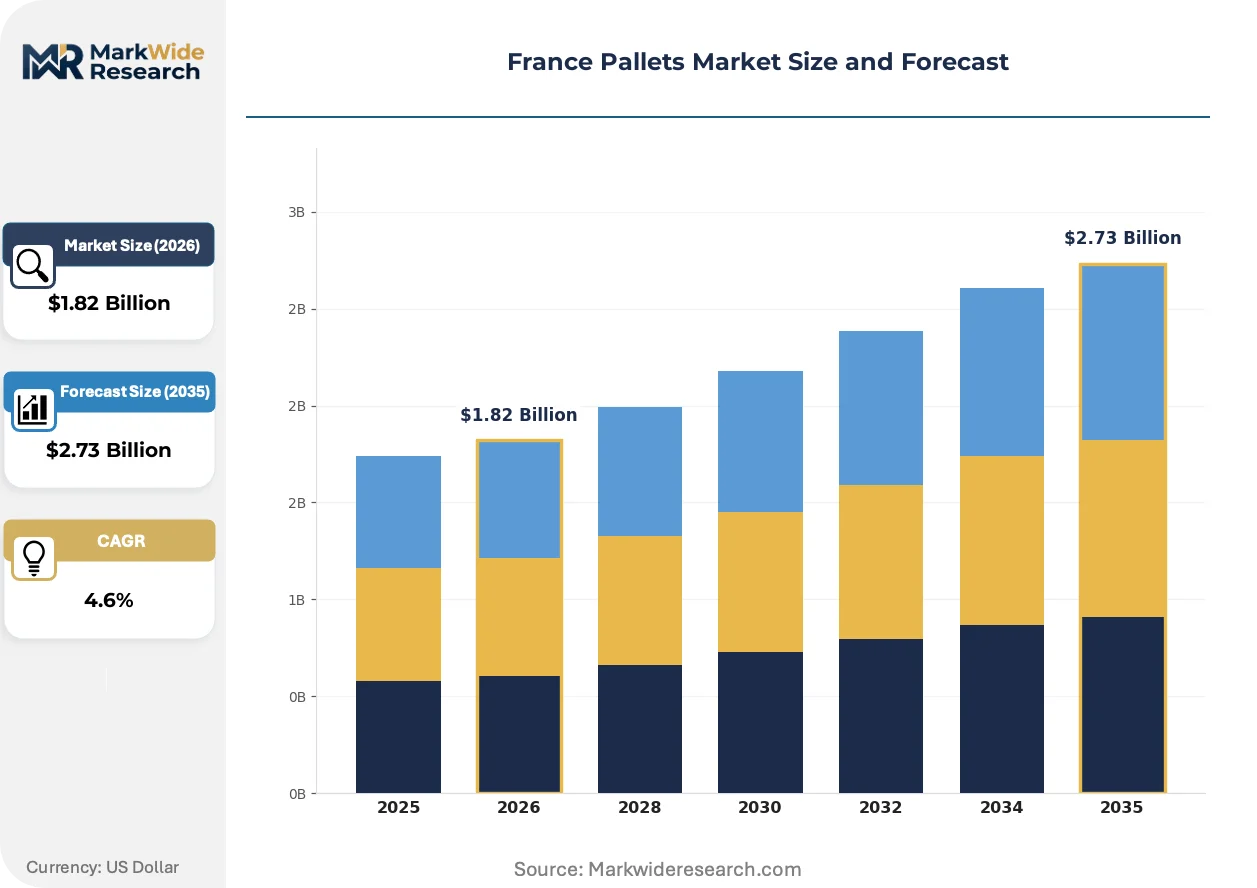
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $2.73 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Plastic, Metal, Composite, Corrugated Fiberboard Type: Block, Stringer, Perimeter Base, Double Face, Single Face Application: Warehousing, Transport, Export, Retail Display, Manufacturing End User: Logistics Providers, E-commerce, Food Processing, Pharmaceuticals |
| Companies Covered | PGS Group, PalletBiz, Sopalog, IPP Logipal, LPR - La Palette Rouge, Burban Palettes, ROTOM France Palettes, Valorpal, TDR, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Pallets Market Trends and Innovations
Digital tracking technologies and material science advances are compressing asset lifecycles while regulatory pressure on circularity accelerates pooling model dominance across French supply chains.
Embedded RFID and NFC sensor pallets are electrifying traceability capabilities in pharmaceutical cold chains. Sanofi and bioMérieux distribution networks in Lyon and Marcy-l'Étoile now mandate chip-enabled plastic pallets for temperature-sensitive shipments. This technology is electrifying competitive differentiation, forcing wood-centric manufacturers to develop hybrid offerings or exit regulated verticals entirely.
France's transposition of EU CSRD sustainability reporting rules now mandates Scope 3 emissions disclosure for large logistics operators. Industrial buyers must document pallet fleet carbon footprints, shifting procurement criteria toward repaired wood and recycled plastic options. Pharmaceutical and food processing sectors in Grand Est are responding fastest, inserting circularity clauses into multi-year pooling contracts.
Asset-light pooling subscriptions are displacing outright pallet purchases among mid-market French manufacturers. Rhône-Alpes automotive suppliers and Occitanie aerospace subcontractors now prefer per-trip pricing with maintenance included. This shift is most visible in the Strasbourg-Nancy corridor, where German-owned logistics providers have exported their home-market rental models into French cross-border operations.
France Pallets Market Segmentation
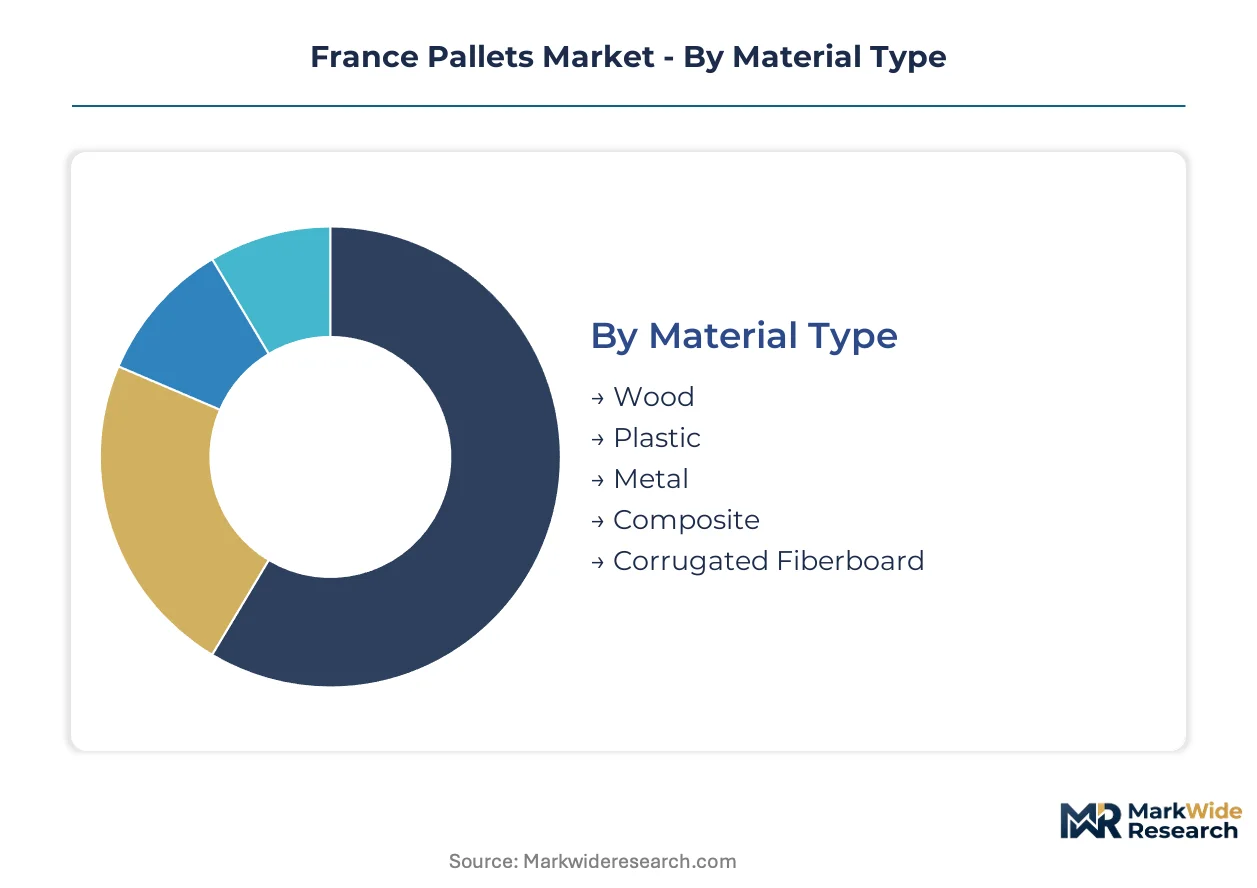
Pallet procurement in France stratifies sharply between commodity-driven volume buyers and specification-heavy regulated industries. Material selection, structural design, and end-use compliance requirements create distinct competitive arenas with diverging margin profiles and customer loyalty dynamics.
Material Type:
Standardization dominates at the commodity end while customization premiums concentrate in regulated supply chains.
- Wood:Nailed softwood and hardwood slat construction anchored by established repair infrastructure across northern France. Grand Est automotive corridors and Rhône-Alpes heavy manufacturing sustain volume leadership through PGS Group's backward integration into regional sawmill networks.
- Plastic:Injection-molded HDPE and PP configurations with embedded RFID compatibility. ANSM pharmaceutical traceability mandates in Lyon and Marcy-l'Étoile biologics clusters drive fastest expansion despite resin price volatility compressing manufacturer margins.
- Metal:Welded steel tubing for extreme load applications in aerospace subcontracting.
- Composite:Engineered wood-plastic hybrids targeting EU Green Deal circularity metrics.
- Corrugated Fiberboard:Lightweight expendable pallets for single-use export shipments to Asian markets.
Leading the category by volume: Wood. Growing fastest: Plastic.
Type:
Structural geometry separates high-velocity transport applications from static storage optimization.
- Block:Four-way entry efficiency through cubic wood block or plastic column construction. Strasbourg-Nancy automotive just-in-time corridors favor block configurations for forklift maneuverability in dense cross-dock facilities serving German OEM plants.
- Stringer:Parallel longitudinal boards with two-way or partial four-way entry. Simpler stacking geometry and field repairability sustain dominance in Rhône-Alpes warehousing operations where pallet longevity outweighs handling speed.
- Perimeter Base:Block configurations with reinforced outer frame for heavy manufacturing loads.
- Double Face:Deck boards on both top and bottom surfaces for reversible stacking.
- Single Face:Top deck only for lightweight retail display and one-way shipping.
Block pallets command transport premiums. Stringer designs retain warehousing cost advantages.
Application:
Functional requirements range from static load-bearing to dynamic traceability integration.
- Warehousing:Stringer and block configurations optimized for racking compatibility and stack stability. Île-de-France 3PL concentration drives standardization toward EUR-pool dimensions.
- Transport:Block-type dominance in high-velocity corridors where four-way entry reduces forklift cycle times.
- Export:ISPM-15 heat-treated wood or plastic alternatives for phytosanitary compliance.
- Retail Display:Single-face and corrugated options for in-store merchandising.
- Manufacturing:Custom hardwood and metal configurations for heavy component handling.
Transport applications lead by shipment volume. Warehousing generates highest per-unit pooling revenue.
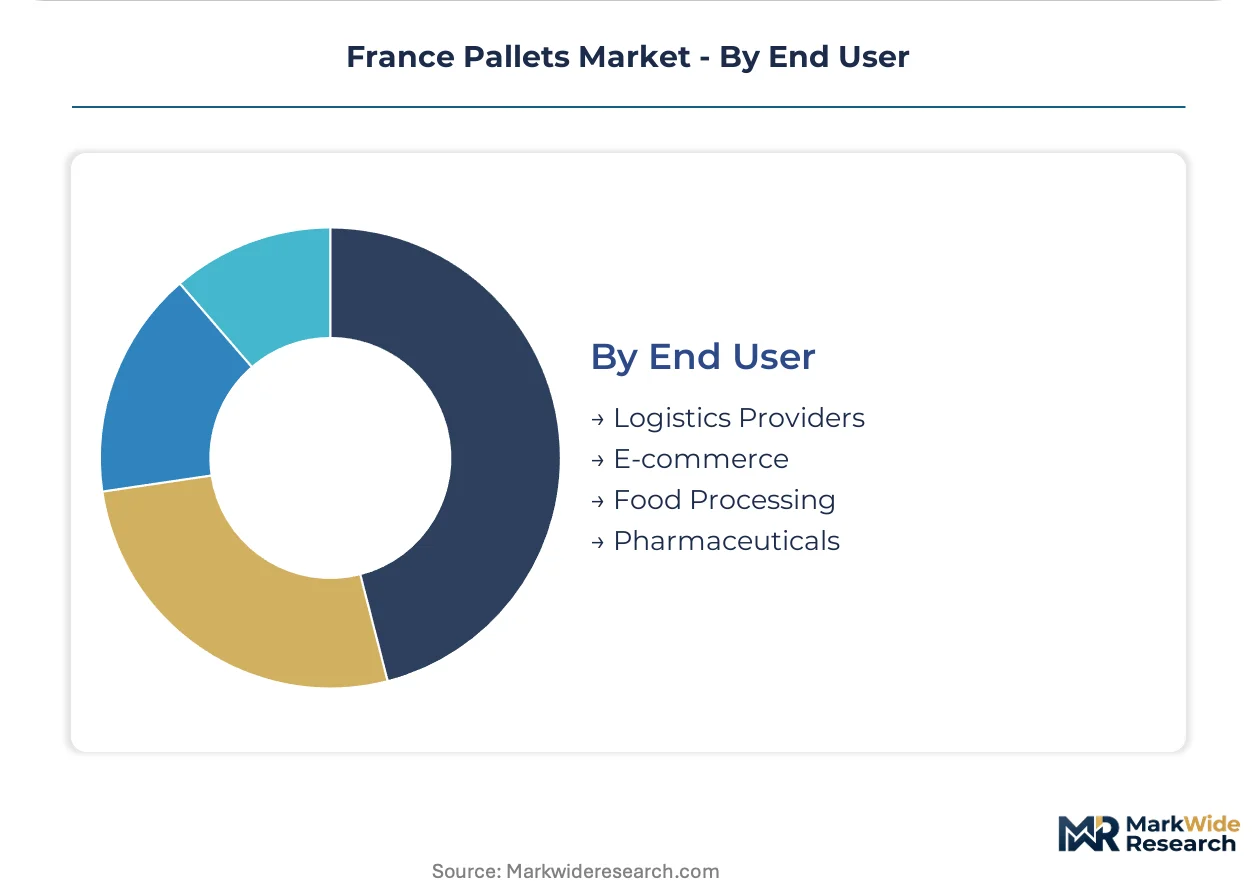
End User:
Buyer sophistication spans from price-taker logistics operators to specification-issuing pharmaceutical regulators.
- Logistics Providers:Asset-heavy 3PLs and pooling operators managing mixed fleets across EU cross-border corridors. LPR - La Palette Rouge's closed-loop rental system anchors procurement concentration in Île-de-France and Grand Est.
- Food Processing:Dairy and meat processors standardizing on RFID-tracked pooling programs under EU Green Deal circularity requirements. Brittany seafood exporters present untapped demand for temperature-logging plastic pallets.
- Pharmaceuticals:Sanofi and bioMérieux distribution networks mandating chip-enabled plastic pallets for cold-chain traceability.
- E-commerce:Fulfillment centers prioritizing lightweight, nestable configurations for returns handling.
Logistics providers dominate pallet circulation volume. Pharmaceuticals impose the steepest compliance premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's pallet demand concentrates in three logistics corridors: the Île-de-Paris freight ring, the Strasbourg-Nancy automotive axis, and the Lyon pharmaceutical cluster. Regional specialization reflects diverging end-use requirements across automotive, pharma, and food processing verticals.
Île-de-France
Paris orbital logistics parks generate the highest pooling fleet turnover in France. ANSM pharmaceutical traceability standards drive RFID-enabled plastic pallet adoption through CDG airport cold-chain facilities. Roissy and Orly cargo zones sustain premium block-pallet demand from express freight operators serving EU cross-border corridors.
Grand Est
The Strasbourg-Nancy corridor anchors automotive just-in-time pallet consumption for German OEM supply chains. EU Green Deal packaging rules compress replacement cycles for pooled fleets serving powertrain component suppliers. Mulhouse distribution centers favor four-way entry block configurations for dense cross-dock operations.
Auvergne-Rhône-Alpes
Lyon and Marcy-l'Étoile biologics clusters mandate chip-enabled plastic pallets under ANSM cold-chain standards. Sanofi distribution networks impose strict hygiene traceability requirements. Saint-Étienne heavy manufacturing sustains custom hardwood demand for metalworking and machinery component handling.
Brittany
Quimper and Lorient seafood processing hubs present untapped demand for temperature-logging plastic pallets. EU F-Gas rules for refrigerated transport equipment reshape export logistics to Asian premium markets. Brest port infrastructure expansion drives pooled fleet investment for containerized seafood shipments.
Occitanie
Toulouse aerospace subcontractors generate specialized metal pallet demand for precision component handling. Montpellier food processing clusters standardize on RFID-tracked pooling programs under advancing EPR frameworks. Perpignan cross-border logistics to Barcelona sustains EUR-pool dimension standardization.
France Pallets Market Competitive Landscape
Northern France producers anchor the volume tier; Rhône-Alpes specialists hold the custom hardwood segment. The vendor base stratifies between asset-heavy pooling operators and regional fabrication shops. Three archetypes dominate: backward-integrated sawmill owners, closed-loop rental system operators, and bespoke hardwood craftsmen. Competitive moves center on repair network densification and RFID fleet retrofitting.
Within the pooling operator tier, LPR - La Palette Rouge and IPP Logipal exemplify closed-loop rental system dominance. PGS Group occupies a position among backward-integrated producers with captive sawmill supply. Burban Palettes represents the custom hardwood specialist archetype serving heavy manufacturing clients.
| Leading Market Players |
|---|
| PGS Group |
| PalletBiz |
| Sopalog |
| IPP Logipal |
| LPR - La Palette Rouge |
| Burban Palettes |
| ROTOM France Palettes |
| Valorpal |
| TDR |
| Others |
Pricing and Supply Chain Analysis
Repair technician concentrations across northern France create labor-cost differentials that widen pricing spreads between premium pooling subscriptions and commodity spot purchases. PGS Group's captive sawmill workforce in Grand Est sustains lower per-unit wood pallet costs than Rhône-Alpes competitors sourcing treated hardwood through fragmented supplier networks.
Pricing Analysis
The volume-versus-margin split separates pooled rental models from transactional spot sales across French supply chains. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—ANSM-compliant RFID-enabled plastic pallets command top-tier rates, untreated softwood stringers occupy the economy band, and heat-treated block pallets with ISPM-15 documentation sit in the mid-market. Cost compression in the economy tier is intensifying because ECHA biocide restrictions on creosote raise material substitution expenses for hardwood producers. Logistics providers managing mixed fleets show highest price sensitivity, while pharmaceutical distributors under ANSM traceability mandates absorb premium pooling rates without volume pushback.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand through LPR - La Palette Rouge's closed-loop rental infrastructure anchored in Île-de-France and Grand Est distribution parks. Geographic supply concentration draws from French sawmill networks in Grand Est, German hardwood suppliers across the Rhine, and Belgian resin processors serving injection-molded plastic pallet manufacturers. Raw material dependencies rest on softwood lumber grades, HDPE and PP resin feedstocks, and copper-free wood treatment chemicals compliant with REACH biocide restrictions. Single-source vulnerability runs through German hardwood suppliers facing ECHA preservative limitations. Distribution runs through regional pooling depots, direct mill shipments for large accounts, and third-party logistics intermediaries serving fragmented rural western France.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal packaging sustainability rules are compressing replacement cycles and forcing pooled fleet investments, accelerating consolidation as smaller wood pallet fabricators lack capital to retrofit RFID capabilities or absorb compliance cost spikes.
For Market Incumbents: Extend repair network density into underserved western France corridors before rural logistics gaps erode pooling fleet utilization rates. Deepen backward integration into certified sustainable sawmill supply to insulate margin positions from ECHA biocide cost pass-throughs. Acquire mid-sized Rhône-Alpes hardwood specialists to capture custom manufacturing premiums before regional capacity scarcity materializes.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in Brittany seafood export corridors offers white-space entry for temperature-logging plastic pallet offerings targeting Asian premium markets. Target Occitanie aerospace subcontractors with lightweight composite configurations satisfying EU CSRD Scope 3 disclosure requirements. Lead with per-trip subscription pricing to displace outright purchase habits among mid-market food processors.
For Investors and Strategic Acquirers: Re-rating potential sits with backward-integrated pooling operators given EU EPR framework advancement and circularity clause insertion into multi-year contracts. Long-term viability favors asset-heavy rental system operators with dense depot networks and captive repair technician workforces. Monitor ANSM pharmaceutical traceability standard expansion as the inflection signal for RFID fleet retrofitting capex cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| RFID Fleet Retrofitting | ANSM pharmaceutical mandates in Lyon and Marcy-l'Étoile now require chip-enabled pallet traceability for cold-chain compliance. |
| Repair Network Densification | Rural western France infrastructure gaps constrain pooling turnaround capacity and raise logistics costs for operators. |
| Backward Sawmill Integration | PGS Group's captive softwood supply in Grand Est sustains cost advantages over resin-dependent plastic pallet competitors. |
| EPR Take-Back Program Launch | France's advancing packaging waste rules create first-mover positioning for manufacturers offering circular recycling services. |
| Composite Material Development | Engineered wood-plastic hybrids target EU Green Deal circularity metrics while bridging hygiene and sustainability requirements. |
Research Methodology
Document review covered trade association filings, EU regulatory transposition texts, and French customs pallet movement data, complemented by interviews with pooling fleet managers, sawmill procurement directors, pharmaceutical logistics coordinators, and food processing supply chain leads. Secondary validation drew from ECHA biocide restriction notices, ANSM traceability guidance documents, and Grand Est automotive corridor freight statistics. Bottom-up unit economics modeling and top-down sector expenditure estimates were cross-referenced to establish market sizing boundaries.
Historical volume trajectories were cross-referenced against panel input from industry stakeholders to anchor growth assumptions across the analysis window. Segmentation modeling incorporated material type, structural configuration, end-use application, and regional logistics corridor dimensions. CAGRs were derived from trend extrapolation adjusted for regulatory inflection points and technology adoption S-curves. Forecast inputs included EU EPR implementation timelines, resin price volatility bands, and repair technician workforce demographics.
Inputs from pharmaceutical distribution networks and automotive logistics coordinators were available through the study window; gaps in real-time pooling fleet utilization data introduce uncertainty bands around rental revenue projections. Forecasts reflect assumptions regarding EU Green Deal enforcement consistency and ANSM standard expansion scope. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Europe Palletizer Market
Pallets Packaging
Disposable Plastic Pallet Market
Pallets Packaging
Pallet Boxes Market
Pallets Packaging
China Pallets Market
Pallets Packaging
Stringer Pallets Market
Pallets Packaging
Molded Wood Pallets Market
Pallets Packaging
Wire Cage Pallet Collar Market
Pallets Packaging
India Pallets Market
Pallets Packaging
Europe Pallet Wrapping Machine Market
Pallets Packaging
Pallet Wrappers Market
Pallets Packaging
Pallet Labeler Market
Pallets Packaging
Global Crates and Pallets Packaging Market
Pallets Packaging
Pallet Tines Market
Pallets Packaging
Japan Pallets Market
Pallets Packaging
UK Pallets Market
Pallets Packaging
Stretch Hood Pallet Wrapping Market