
 Black Bricks Market | 2026-2036
Black Bricks Market Size, Share, and Industry Trends Forecast 2026-2036
Black Bricks Market Analysis
Engineering-grade compressive-strength specifications above 50 MPa is rotating the Black Bricks market toward premium-tier supply contracts. Wienerberger AG leverages its continental European kiln network to sustain specification-grade output at scale. Glen-Gery Corporation anchors North American dark-facade production through its Pennsylvania manufacturing base. Ibstock Brick Limited differentiates via dedicated architectural-specification teams serving London premium residential clusters.
Black bricks are fired-clay or concrete masonry units pigmented with manganese dioxide, carbon black, or iron-rich clays to achieve a durable dark surface with compressive strength ranging from 20 to 75 MPa depending on firing temperature and raw material grading. Their primary purpose is to deliver weather-resistant, low-maintenance facade systems with specified aesthetic consistency across large building envelopes. Solid black bricks dominate current volume owing to structural load-bearing requirements in multi-story residential frames, while hollow black bricks represent the fastest-expanding category as thermal-performance building codes tighten across temperate climates. Clay material formulations command the deepest specification loyalty among heritage-sensitive architects, whereas fly-ash blends attract cost-engineered commercial projects seeking embodied-carbon reductions.
REACH chemical-safety registrations and the EU Green Deal embodied-carbon benchmarks shape product formulation decisions across European manufacturing, while EPA air-quality standards and OSHA silica-exposure limits govern kiln emissions and worker-safety protocols at U.S. production sites. BIS certification requirements in India and GB standards administered by SAMR in China create divergent compliance pathways for exporters serving multiple construction-material jurisdictions. Stakeholders must monitor accelerating regulatory fragmentation between carbon-accounting methodologies and decide whether to pursue region-specific product certifications or invest in unified low-carbon formulations capable of crossing multiple compliance regimes.
Market Dynamics
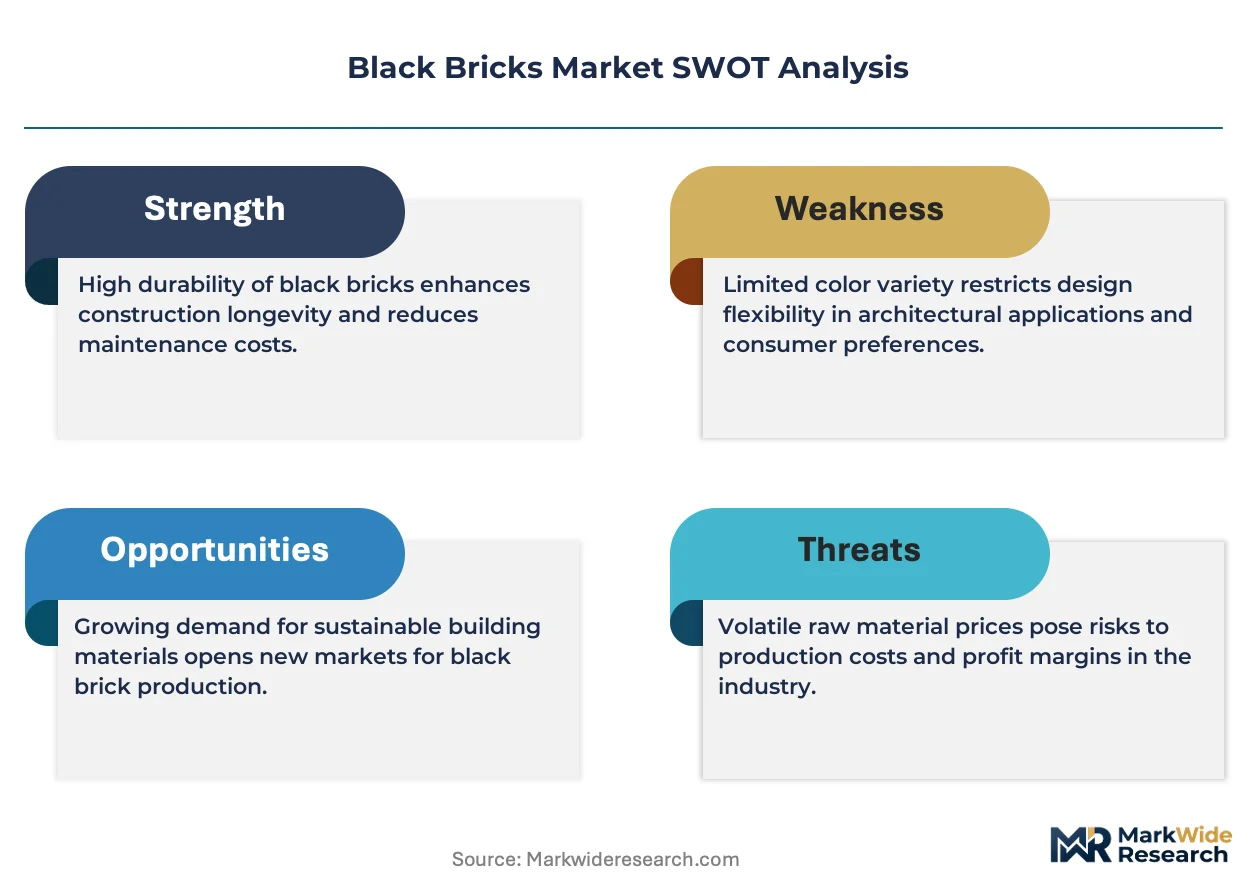
The Black Bricks market is currently shaped by the tension between specification-grade aesthetic demand and tightening embodied-carbon regulations, forcing manufacturers to reformulate high-performance dark-facade products without sacrificing compressive strength or color consistency.
Growth Catalysts
- EU Green Deal embodied-carbon benchmarks:Lower-carbon black brick formulations now qualify for green building certifications across Germany, the United Kingdom, and France, accelerating specification-grade adoption.
- Luxury residential architects:Dark-facade aesthetic specifications in metropolitan new-build corridors command sustained loyalty and premium-tier supply contracts.
- Manganese dioxide pigment systems:Advanced firing processes achieve deeper, more durable black surfaces that outperform carbon-black alternatives in weathering tests.
Market Restraints
- High-purity clay sourcing concentration:Premium-grade fireclay deposits cluster in specific geological formations, creating geographic supply vulnerability for specification-grade output.
- Natural gas price volatility:Kiln firing costs represent a substantial share of production economics, exposing margins to energy market fluctuations.
- Concrete masonry unit substitution:Cost-engineered commercial projects increasingly specify pigmented concrete alternatives that mimic black brick aesthetics at lower unit cost.
Strategic Opportunities
- Fly-ash blend formulations:Industrial byproduct integration reduces embodied carbon while meeting compressive-strength thresholds for mid-tier commercial specifications.
- Thermal-performance building codes:Hollow black brick demand accelerates as temperate climate jurisdictions mandate improved envelope insulation values.
- Heritage-sensitive restoration segments:Clay material formulations with traditional firing characteristics capture specification loyalty in conservation architecture.
Industry Challenges
- Silica-exposure compliance:OSHA workplace-safety protocols require capital-intensive dust-suppression systems and worker-monitoring infrastructure at U.S. production facilities.
- REACH chemical-safety documentation:Manganese dioxide pigment registrations demand extensive toxicological data and ongoing compliance expenditure for European market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Black Bricks Market |
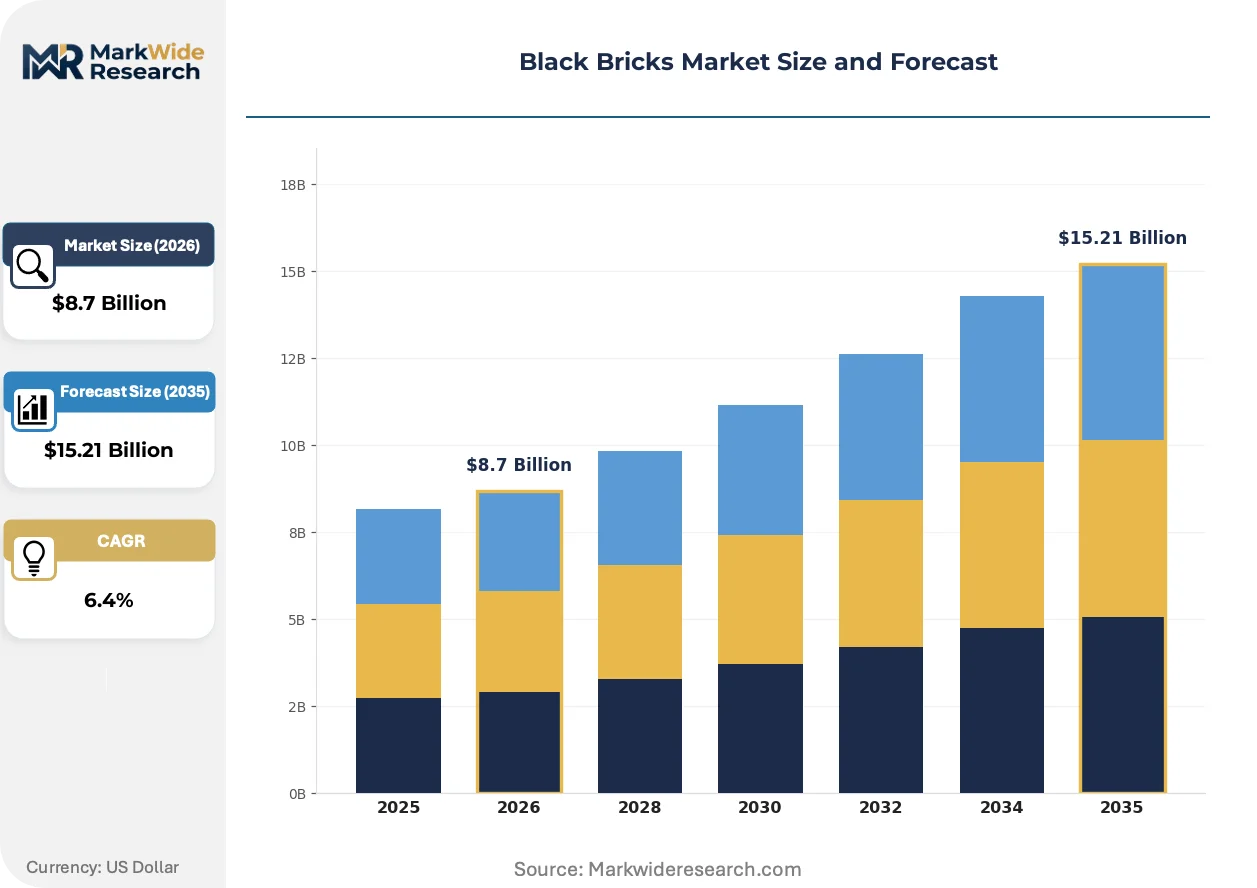
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Black Bricks, Hollow Black Bricks, Interlocking Black Bricks, Fire Bricks End Use Industry: Residential Construction, Commercial Construction, Infrastructure Development, Landscaping Material: Clay, Concrete, Fly Ash, Recycled Materials Distribution Channel: Direct Sales, Online Retail, Wholesale Distributors, Building Material Suppliers |
| Companies Covered | Boral Limited, Wienerberger AG, LafargeHolcim Ltd, HeidelbergCement AG, CRH plc, Glen-Gery Corporation, The Belden Brick, Ibstock Brick Limited, Diamond Brick Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Black Bricks Market Emerging Trajectories
Kiln technology and pigment chemistry are converging to enable darker, more durable facade surfaces while regulatory pressure compresses allowable carbon intensity across the supply chain.
Advanced manganese dioxide pigmentation systems is bifurcating the specification-grade segment from commodity black brick supply. Heritage-sensitive architects in London and Berlin specify these formulations for color consistency across large envelopes. The technology is bifurcating premium-tier contracts toward manufacturers with dedicated architectural-specification teams.
REACH chemical-safety registrations now govern manganese dioxide and carbon black pigment formulations across European manufacturing. Industrial consequence includes reformulation costs and extended product-development timelines for exporters. Specification-grade clay black bricks face the steepest compliance burden, driving some producers toward fly-ash blends with simpler chemical profiles.
Architects now bundle facade-material selection with whole-life carbon assessments rather than first-cost optimization. Specification teams serving premium residential clusters in Sydney and Melbourne lead this behavioral shift. The practice compresses switching cycles and locks in multi-project relationships with compliant black brick suppliers.
Black Bricks Market Segmentation
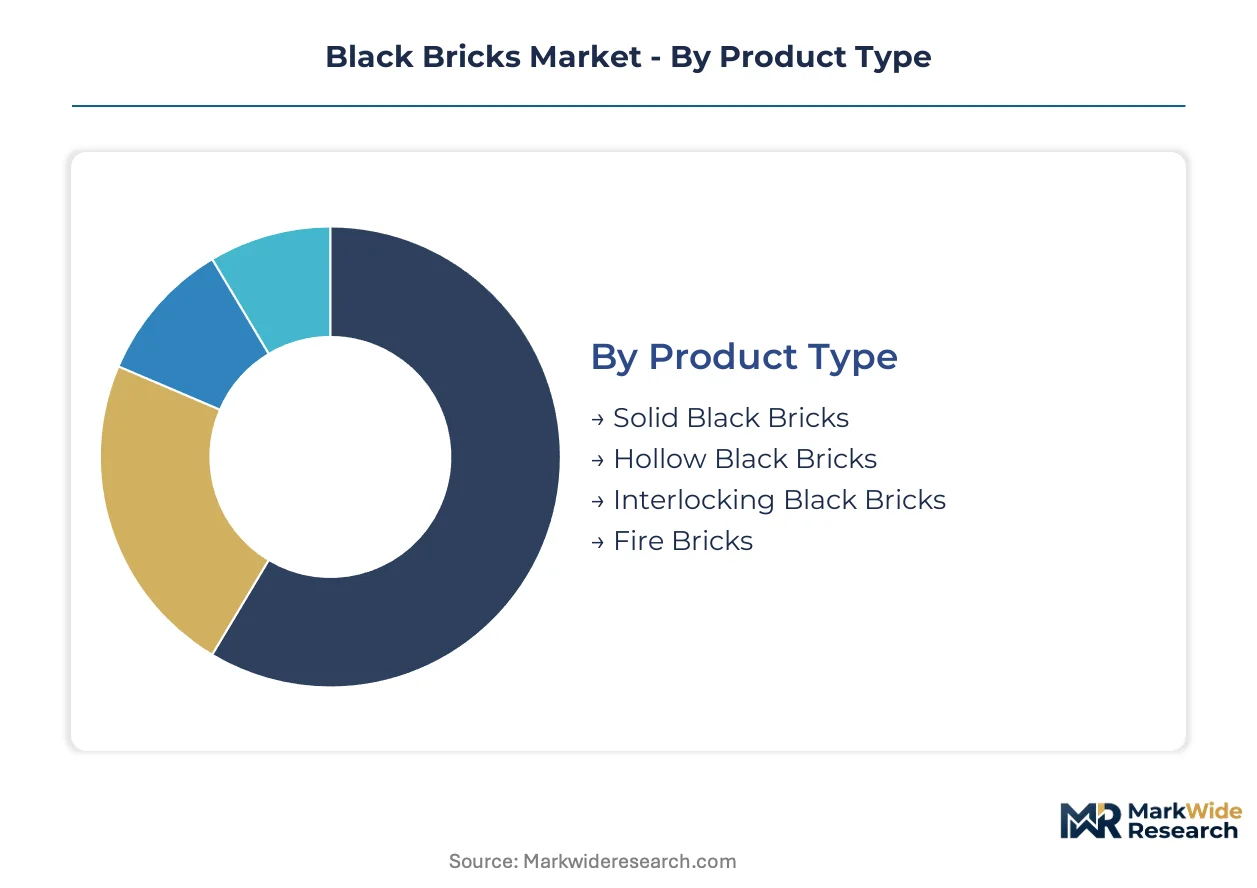
Black brick procurement patterns diverge sharply across product types, end-use sectors, and material formulations. Specification-grade architects in Germany, the United Kingdom, and Australia drive premium-tier demand, while cost-engineered commercial projects reshape material choices and channel preferences.
Product Type:
Domestic kiln networks in Germany and Pennsylvania anchor solid and hollow production, whereas interlocking and fire brick variants flow through specialized export channels serving conservation architects and industrial specifiers.
- Solid Black Bricks:Dense fired-clay units with compressive strength above 50 MPa serve structural load-bearing frames in multi-story residential construction. London and Berlin metropolitan corridors sustain specification loyalty for heritage-sensitive facades requiring color consistency across large envelopes.
- Hollow Black Bricks:Thermally optimized cavities reduce envelope U-values while maintaining 20-35 MPa structural ratings. Sydney and Melbourne building codes now mandate improved insulation values, accelerating hollow brick specification in temperate climate new-builds.
- Interlocking Black Bricks:Precision-molded tongue-and-groove profiles enable mortarless assembly for rapid commercial cladding systems.
- Fire Bricks:High-alumina formulations withstand temperatures exceeding 1,500°C for industrial furnace linings and heritage restoration kilns.
Solid black bricks command the established base. The steepest expansion runs through hollow black bricks.
End Use Industry:
Cost tier stratification separates premium residential specification from volume commercial procurement, with infrastructure and landscaping occupying distinct margin bands.
- Residential Construction:Luxury single-family and multi-family developments in London, Berlin, and Sydney specify manganese-dioxide pigmented facades. Architects bundle material selection with whole-life carbon assessments, compressing supplier switching cycles across multi-project relationships.
- Commercial Construction:Cost-engineered office and retail shells increasingly specify fly-ash blend formulations or pigmented concrete alternatives that mimic black brick aesthetics at lower unit cost.
- Infrastructure Development:Transit hubs and civic buildings specify weather-resistant dark facades for low-maintenance durability in high-traffic public environments.
- Landscaping:Garden walls, paving borders, and decorative hardscaping drive small-batch demand for aesthetic consistency without structural load requirements.
Residential construction anchors premium-tier volume. Commercial construction is gaining share fastest as fly-ash blends penetrate mid-tier specifications.
Material:
Supply concentration for premium fireclay deposits in specific geological formations creates geographic vulnerability, while industrial byproduct integration reshapes carbon-accounting compliance.
- Clay:Traditional fired-clay formulations using manganese dioxide or iron-rich deposits achieve the deepest specification loyalty among heritage-sensitive architects. REACH chemical-safety registrations for manganese dioxide impose extended compliance timelines on European manufacturers.
- Concrete:Pigmented concrete masonry units offer compressive strength parity at reduced firing energy, attracting cost-engineered commercial projects in North American markets.
- Fly Ash:Industrial byproduct integration reduces embodied carbon by 15-30% versus virgin clay, qualifying for EU Green Deal green building certifications.
- Recycled Materials:Post-industrial ceramic and glass waste streams enable circular economy specifications in conservation-driven restoration segments.
Clay formulations retain the specification-grade core. Fly ash is climbing the fastest as carbon benchmarks tighten across German and French building codes.
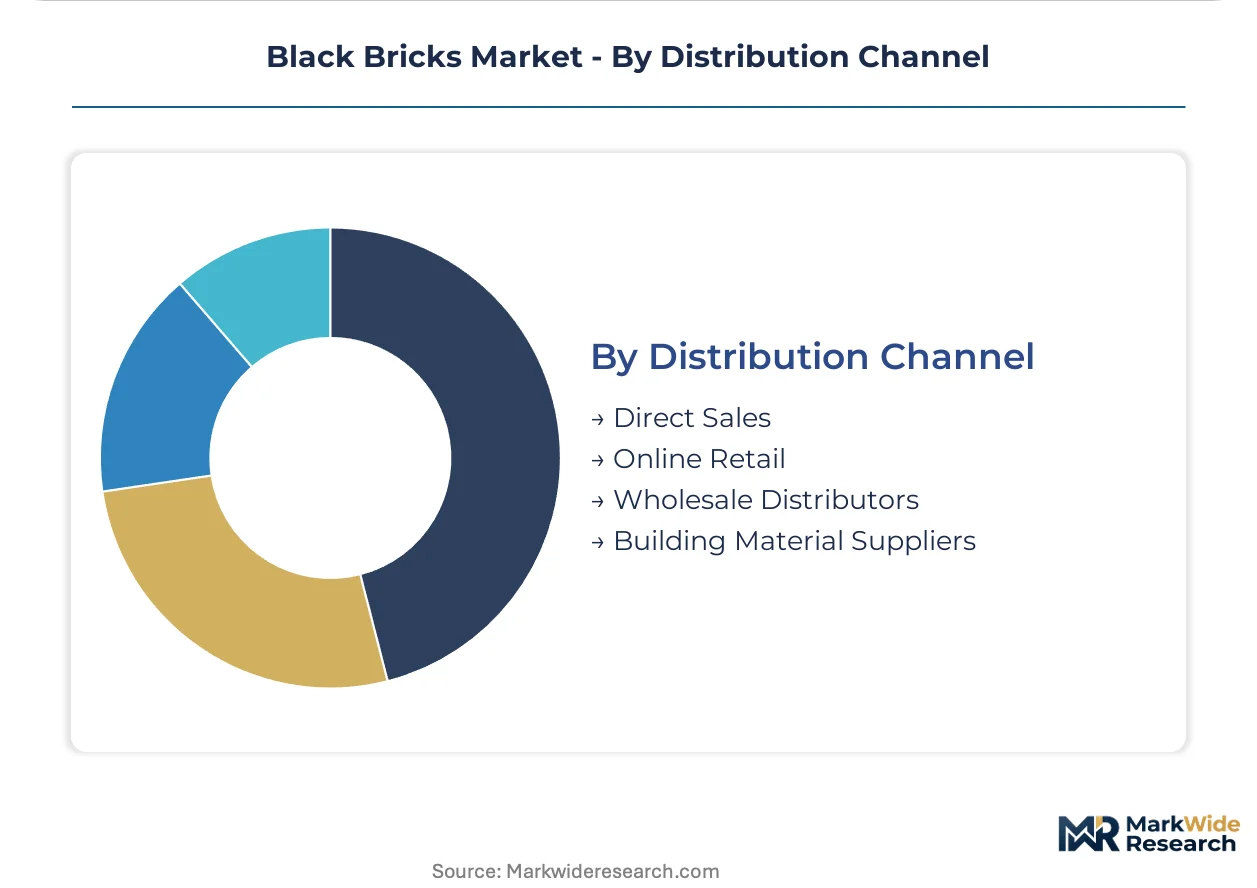
Distribution Channel:
Customer type fragmentation separates specification-team relationships from transactional procurement, with digital channels capturing share in standardized product tiers.
- Direct Sales:Dedicated architectural-specification teams at Wienerberger AG and Ibstock Brick Limited serve London and Berlin premium residential clusters through long-term project partnerships.
- Online Retail:Standardized hollow and solid variants move through digital platforms for small-scale residential renovations and landscaping contractors.
- Wholesale Distributors:Regional inventory stocking in metropolitan construction corridors enables just-in-time delivery for volume commercial developers.
- Building Material Suppliers:Integrated merchant networks bundle black brick procurement with complementary envelope materials for single-source convenience.
Direct sales lock in the highest-margin specification base. Online retail is expanding most quickly as standardized products penetrate renovation and DIY segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Continental European kiln networks and Pennsylvania manufacturing bases anchor specification-grade supply, while metropolitan construction corridors in London, Berlin, and Sydney concentrate demand for dark-facade aesthetics.
Germany
Luxury residential architects in Berlin and Munich specify manganese-dioxide pigmented facades with whole-life carbon assessments. EU Green Deal embodied-carbon benchmarks favor lower-carbon formulations qualifying for green building certifications. The Rhine-Ruhr industrial corridor hosts concentrated kiln capacity serving premium-tier contracts.
United Kingdom
Heritage-sensitive architects in London premium residential clusters demand color consistency across large envelopes. REACH chemical-safety registrations govern manganese dioxide pigment formulations, extending compliance timelines for clay-based products. Manchester and Birmingham metropolitan new-build corridors accelerate hollow brick adoption under tightening thermal-performance codes.
United States
Cost-engineered commercial projects in Chicago and New York increasingly specify fly-ash blends or pigmented concrete alternatives. EPA air-quality standards and OSHA silica-exposure limits govern kiln emissions and worker-safety protocols at Pennsylvania production sites. The Mid-Atlantic region sustains dark-facade manufacturing through established clay deposits.
Australia
Sydney and Melbourne building codes mandate improved envelope insulation values, accelerating hollow black brick specification in temperate climate new-builds. Dark-facade aesthetic specifications command sustained loyalty among specification-grade architects bundling material selection with carbon assessments. New South Wales and Victoria metropolitan corridors concentrate premium residential demand.
India
Conservation architects in Delhi and Mumbai specify traditional firing characteristics for heritage-sensitive restoration segments. BIS certification requirements create compliance pathways distinct from European and North American standards. Gujarat and Rajasthan ceramic belts supply cost-engineered variants for commercial and infrastructure applications.
Black Bricks Market Vendor Landscape
Concentration sits with continental European kiln operators and North American dark-facade specialists serving specification-grade architects. The competitive terrain separates premium-tier clay formulators from cost-engineered fly-ash blend producers. Three archetypes dominate: heritage-sensitive clay specialists, carbon-optimized blend innovators, and scale-driven concrete masonry competitors. Dominant competitive moves include geographic kiln network expansion and dedicated architectural-specification team deployment.
Among European-based producers, Wienerberger AG exemplifies the continental kiln network archetype, while Ibstock Brick Limited occupies a position within the heritage-sensitive specification tier. Glen-Gery Corporation anchors North American dark-facade production capacity. These three represent distinct strategic postures across the premium-mid-economy spectrum, with each sitting within a differentiated regulatory and customer-relationship configuration.
| Leading Market Players |
|---|
| Boral Limited |
| Wienerberger AG |
| LafargeHolcim Ltd |
| HeidelbergCement AG |
| CRH plc |
| Glen-Gery Corporation |
| The Belden Brick |
| Ibstock Brick Limited |
| Diamond Brick Company |
| Others |
Supply Flow & Price Mechanics
EU Green Deal embodied-carbon benchmarks gate both supply qualification and price differentiation simultaneously, compressing margins for non-compliant clay formulators while rewarding fly-ash blend producers with green certification premiums. Specification-grade architects in London and Berlin now bundle whole-life carbon assessments with material selection, locking in multi-project relationships that transcend transactional pricing.
Pricing Analysis
REACH chemical-safety registrations dictate the pricing tier structure across European black brick manufacturing, separating manganese-dioxide pigmented premium tiers from carbon-black commodity supply. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and compressive-strength thresholds, with heritage-sensitive architects in metropolitan corridors showing lowest price sensitivity. Cost compression in mid-tier commercial specifications is intensifying because pigmented concrete masonry units offer aesthetic parity at reduced firing energy. Volume developers and cost-engineered retail shells demonstrate highest price sensitivity, while conservation architects and luxury residential specifiers absorb premiums for color consistency.
Supply Chain Analysis
Just-in-time inventory preferences dominate metropolitan construction corridors, though strategic stockpiling of premium-grade fireclay concentrates around specific geological formations in Germany and Pennsylvania. Supply draws from concentrated kiln networks in the Rhine-Ruhr industrial corridor, Pennsylvania manufacturing bases, and Gujarat ceramic belts, with manganese dioxide pigments and high-purity fireclay anchoring raw material dependencies. Single-source vulnerability for specification-grade fireclay deposits creates geographic supply risk, compounded by natural gas price volatility affecting firing economics. Distribution runs through dedicated architectural-specification teams for premium tiers and wholesale merchant networks for standardized commercial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The black bricks market sits in cyclical recovery as embodied-carbon regulations tighten across temperate climate jurisdictions, with building code enforcement cycles driving specification-grade demand in metropolitan new-build corridors.
For Market Incumbents: Secure long-term offtake agreements for premium-grade fireclay deposits to defend against geographic supply vulnerability, while accelerating fly-ash blend capacity to capture green certification premiums. Pigmented concrete masonry substitution and natural gas price volatility represent immediate threats to margin stability in mid-tier commercial specifications. Backward integration into manganese dioxide pigment supply or captive kiln fuel hedging provides defensive leverage against input cost swings. For New Entrants and Emerging Players: Differentiate on carbon-accounting transparency to penetrate the hollow black brick segment accelerating under Sydney and Melbourne thermal-performance codes. Heritage-sensitive restoration segments in India and conservation-driven European markets offer penetrable white-space with lower incumbent concentration. A go-to-market angle bundling whole-life carbon assessments with material specification captures architect loyalty and compresses switching cycles. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed clay specialists lacking fly-ash blend capabilities or carbon-accounting infrastructure. Long-term viability favors manufacturers with unified low-carbon formulations capable of crossing multiple compliance regimes rather than region-specific certifications. The signal to watch is accelerating regulatory fragmentation between EU Green Deal benchmarks and North American building codes, which determines scale economics for multi-jurisdictional supply.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Manganese Dioxide Supply | REACH compliance timelines shorten and pigment cost volatility compresses for European kiln operators. |
| Fly-Ash Blend Capacity Expansion | EU Green Deal certification thresholds unlock green building specification premiums in German and French corridors. |
| Dedicated Architectural-Specification Team Deployment | London and Berlin premium residential clusters lock in multi-project relationships through bundled carbon assessments. |
| Hollow Black Brick Thermal Performance Investment | Sydney and Melbourne building code mandates accelerate specification in temperate climate new-builds. |
| Heritage-Sensitive Clay Formulation R&D | Conservation architects in Delhi and Mumbai specify traditional firing characteristics for restoration authenticity. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted across primary research phases, with architectural specification teams, kiln operations managers, and commercial procurement leads at volume developers providing forward-looking demand signals. Secondary validation drew from EU ETS emissions data, REACH registration databases, building permit filings in London and Sydney metropolitan corridors, and trade flow records for manganese dioxide pigment imports. Bottom-up triangulation across product-type volume estimates and top-down cross-checks against construction activity indices anchored market sizing integrity.
Across the analysis window, the forecasting framework modeled segmentation dimensions including material formulation, compressive-strength tier, end-use industry, and metropolitan corridor demand concentration. CAGRs derived from regression analysis against construction output indices and regulatory enforcement timelines, with kiln capacity utilization rates and natural gas price trajectories serving as industry-specific sensitivity inputs.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or abrupt natural gas price dislocations would require recalibration. Forecasts reflect documented assumptions regarding specification-grade architect behavior and thermal-performance code adoption trajectories. Revision becomes warranted when pigmented concrete masonry substitution rates or REACH compliance cost burdens cross thresholds that materially alter relative competitiveness between material formulations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
North America UPVC Doors and Windows Market
Building & Construction Materials
Egypt Prefab Wood Buildings Market
Building & Construction Materials
US Retractable Roofing System Market
Building & Construction Materials
Facade Materials Market
Building & Construction Materials
Middle-East and Africa Construction Adhesives Market
Building & Construction Materials
US Parking Deck Coatings Market
Building & Construction Materials
Seal Coat Market
Building & Construction Materials
Global Door Market
Building & Construction Materials
US Precast Concrete Market
Building & Construction Materials
Fiberglass Doors Market
Building & Construction Materials
Piping Systems Market
Building & Construction Materials
Roof Window Market
Building & Construction Materials
North America Fabricated Metal Products Market
Building & Construction Materials
Sandwich Panel System Market
Building & Construction Materials
GCC Concrete Blocks Market
Building & Construction Materials
Door Hinges Market