
 Boiler Insurance Market | 2026-2036
Boiler Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Boiler Insurance Market Intelligence
Comprehensive coverage tiers is rotating toward the center of product strategy as policyholders seek protection against cascading mechanical failures and business interruption losses. The Hartford Steam Boiler Inspection and Insurance Company leverages its century-old engineering inspection heritage to dominate technical risk assessment. Allianz SE anchors European commercial portfolios through integrated property and machinery breakdown bundles. Aviva plc competes in the UK residential segment with digital-first policy administration and rapid claims fulfillment.
Boiler insurance constitutes a specialized property and casualty contract covering repair, replacement, and liability costs arising from pressure vessel failures, combustion malfunctions, and ancillary system damage in steam or hot-water heating installations. Policies typically specify maximum pressure ratings, thermal output thresholds, and inspection frequency requirements tied to ASME or equivalent national boiler codes. The end user dimension shows industrial facilities commanding the deepest premium pools due to catastrophic exposure and mandatory inspection regimes, while residential units represent the volume frontier as home service plan penetration climbs. Premium tier stratification reveals mid-range products capturing the widest buyer base, though custom solutions extract superior margins from mission-critical installations in hospitals and data centers.
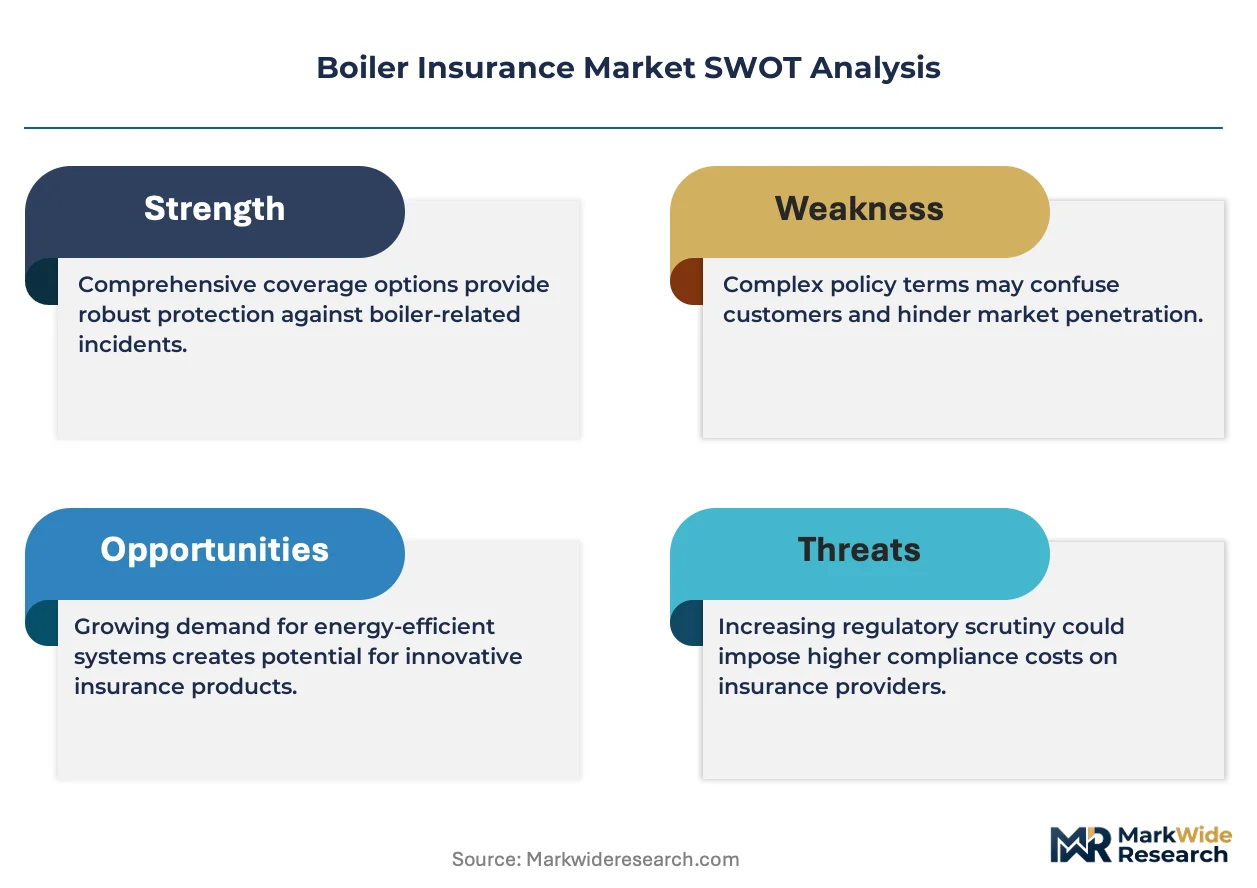
Regulatory oversight from OSHA in the United States, the EU Pressure Equipment Directive across Europe, and national boiler inspection boards in multiple jurisdictions mandate periodic certification that directly generates insurance demand and shapes coverage minimums. Compliance failure triggers coverage voidance, embedding insurers within the enforcement architecture. Stakeholders must monitor how carbon-neutral building mandates rewrite replacement timelines and whether emerging hydrogen-ready boiler standards create new liability categories requiring actuarial recalibration.
Market Dynamics
The EU Green Deal's efficiency mandates are compressing replacement cycles for aging commercial boiler fleets, forcing insurers to recalibrate risk models around accelerated equipment turnover and stricter inspection protocols.
Growth Catalysts
- Aging Infrastructure:Germany's commercial boiler fleet exceeds 25 years average age, triggering mandatory coverage expansion as mechanical failure rates climb and property owners seek protection against cascading business interruption losses.
- OSHA Inspection Mandates:US pressure vessel certification requirements embed insurers within enforcement architecture, generating recurring premium demand tied to documented compliance verification and penalty avoidance.
- Hydrogen-Ready Standards:Emerging combustion technology specifications for hydrogen-compatible boilers create new liability categories requiring specialized underwriting expertise and technical risk assessment capabilities.
Market Restraints
- Steel Price Volatility:Pressure vessel manufacturing depends on alloy steel inputs subject to commodity swings, compressing replacement cost predictability and forcing insurers to maintain larger technical reserves.
- Specialized Inspector Scarcity:Certified boiler engineers concentrate in legacy industrial regions, creating geographic coverage gaps where qualified risk assessors cannot meet inspection volume demands.
- Heat Pump Substitution:Electrification incentives in residential segments displace fossil-fuel boiler installations, eroding the addressable premium pool for traditional combustion equipment coverage.
Strategic Opportunities
- Data Center Thermal Loads:Mission-critical computing facilities require uninterrupted steam and hot-water systems, opening high-margin custom solutions for catastrophic failure protection and rapid response guarantees.
- EU Pressure Equipment Directive Expansion:Member states are tightening certification reciprocity rules, creating first-mover advantages for insurers with established cross-border technical assessment networks.
- Digital-First Distribution:Direct-to-customer platforms bypass traditional broker channels, reducing acquisition costs and enabling real-time policy customization for small commercial accounts.
Industry Challenges
- Actuarial Talent Shortage:Specialized machinery breakdown underwriting requires engineering-actuarial hybrid skills that traditional insurance programs rarely produce, constraining product development velocity.
- Legacy System Integration:Established insurers face technical debt from decades-old policy administration platforms that resist API connectivity with modern IoT sensor networks for predictive maintenance monitoring.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boiler Insurance Market |
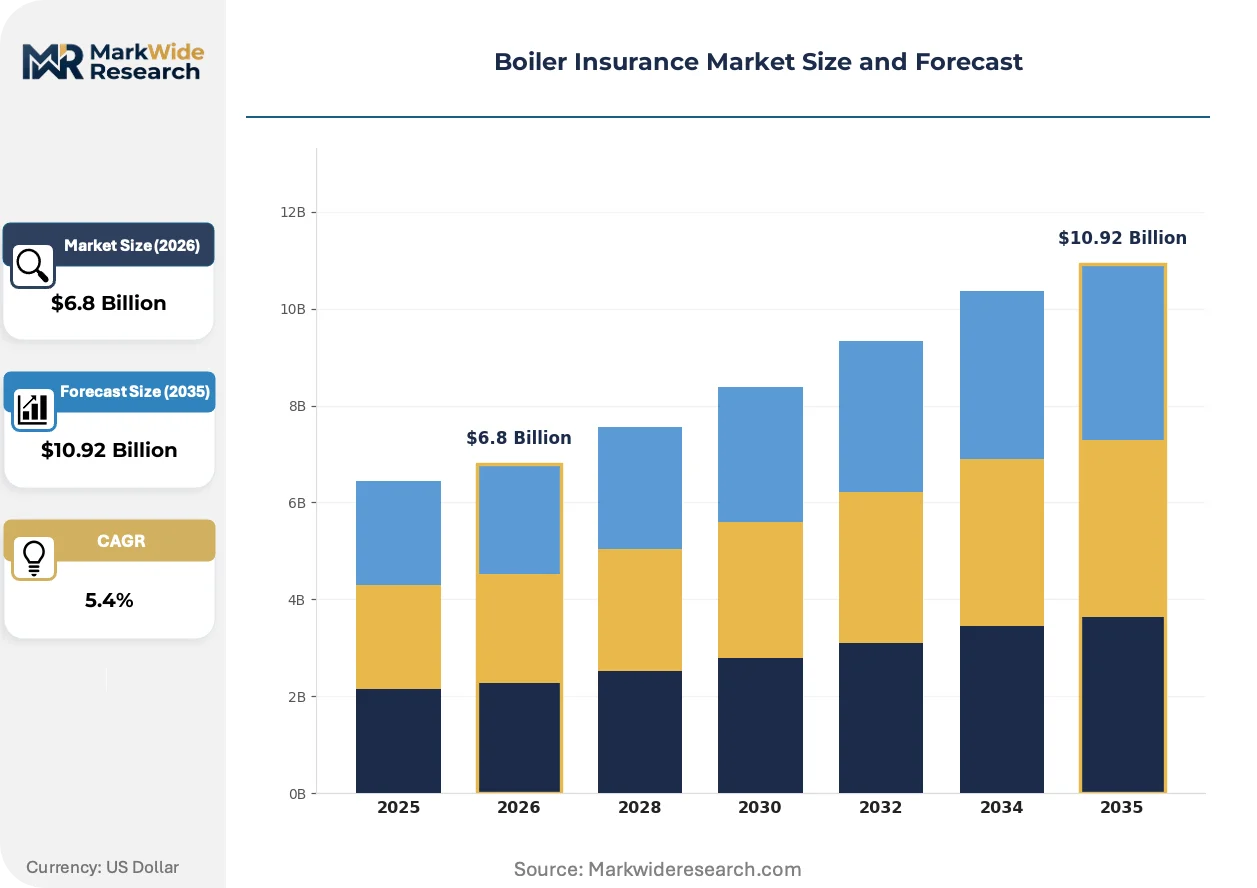
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Comprehensive, Third Party Liability, Machinery Breakdown, Fire and Theft End User: Industrial Facilities, Commercial Buildings, Residential Units, Utilities Coverage Area: National, Regional, Local, International Premium Tier: Economical, Mid-Range, High-End, Custom Solutions |
| Companies Covered | Aviva plc, Axa S.A., The Hartford Steam Boiler Inspection and Insurance Company, British Gas, HomeServe Membership Ltd., Domestic & General Group Limited, Allianz SE, Bosch Thermotechnology Ltd., CORGI HomePlan Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boiler Insurance Market Strategic Shifts & Innovations
Connected sensor networks and predictive analytics are redrawing how insurers price risk and intervene before failures occur, shifting the industry from post-loss reimbursement toward prevention-centric service models.
IoT-enabled boiler monitoring is fragmenting traditional annual inspection cycles into continuous telemetry streams. Industrial facilities in chemical processing and food manufacturing are deploying pressure and temperature sensors at the fastest adoption rates. This technology is fragmenting the market between insurers offering dynamic premium adjustments based on real-time equipment health and those locked into static annual rating structures.
The EU Green Deal's building renovation mandates are accelerating replacement timelines across member states. Commercial property owners must now demonstrate efficiency upgrades to maintain operating licenses, compressing equipment life assumptions in underwriting models. Germany and the Netherlands show the steepest policy realignment as national building codes tighten combustion emissions thresholds.
Risk transfer preferences are tilting toward bundled service contracts that merge insurance coverage with preventive maintenance obligations. Mid-sized manufacturing plants are displacing standalone policies with integrated machinery breakdown and engineering service agreements. This consolidation is most visible in the UK and France, where facilities managers prioritize single-vendor accountability over fragmented supplier relationships.
Boiler Insurance Market Segmentation
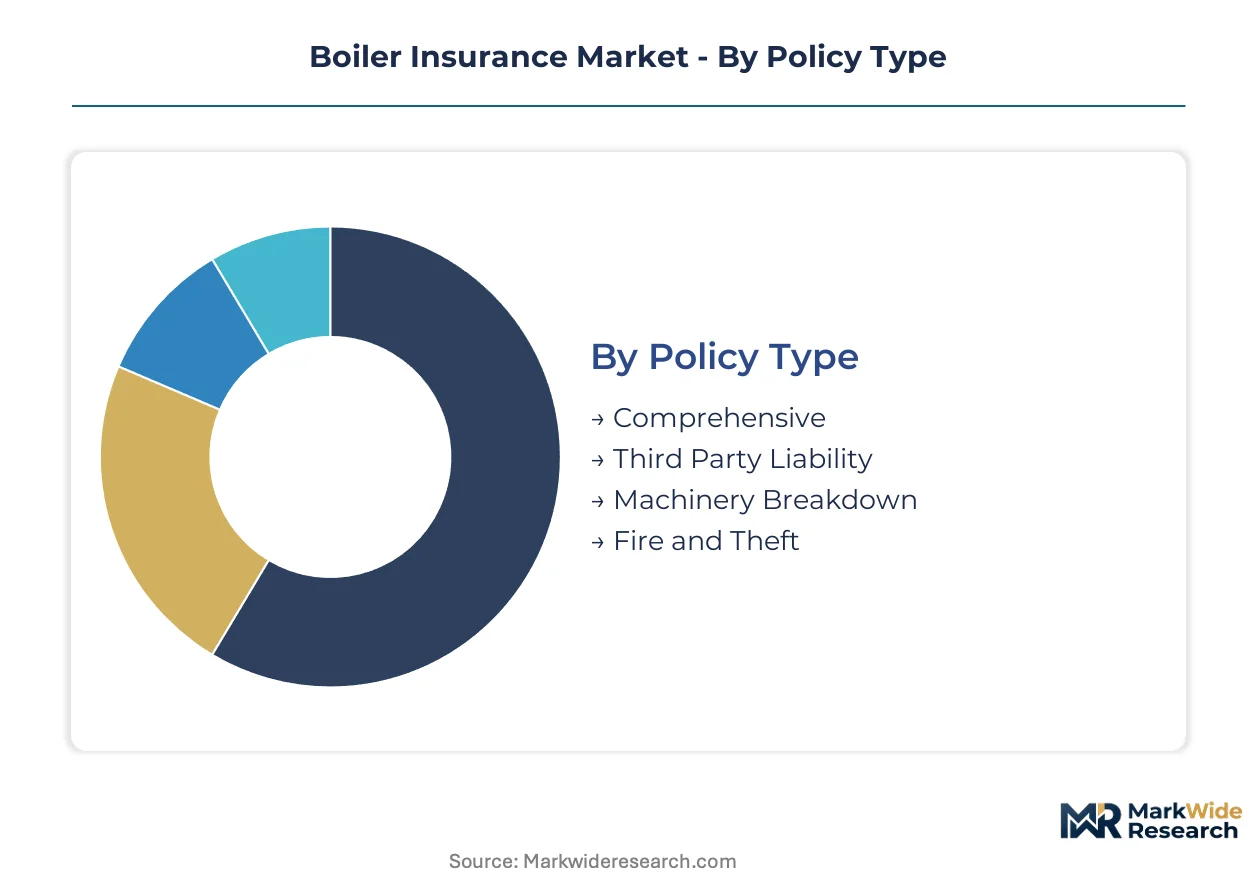
Boiler insurance segmentation reveals how risk transfer mechanisms align with equipment criticality and regulatory exposure. Policy structures vary sharply between catastrophic loss protection for industrial pressure vessels and routine maintenance coverage for residential heating systems.
Policy Type:
Comprehensive policies dominate broker-mediated placements for commercial accounts, while Machinery Breakdown and Third Party Liability flow through direct channels to cost-sensitive buyers.
- Comprehensive:Bundles property damage, business interruption, and liability exposure under unified deductibles. Demand concentrates in German chemical processing clusters where EU Pressure Equipment Directive mandates cascade into coverage minimums and inspection documentation requirements.
- Third Party Liability:Covers bodily injury and property damage to external parties from boiler explosions or steam release. Growth concentrates fastest in US manufacturing corridors where OSHA enforcement embeds insurers within penalty avoidance strategies and compliance verification workflows.
- Machinery Breakdown:Isolates mechanical failure coverage from broader property programs. Industrial facilities in legacy steel regions favor this stripped structure to contain premium outlays while satisfying lender collateral requirements.
- Fire and Theft:Addresses combustion-related property loss and equipment disappearance. Residential landlords in UK urban rental markets purchase this entry tier through digital distribution platforms.
By volume, Comprehensive leads. By growth pace, Third Party Liability is expanding most quickly.
End User:
Cost tier stratification separates mission-critical installations commanding custom solutions from standardized products serving price-sensitive accounts.
- Industrial Facilities:Chemical plants, refineries, and food processors operate pressure vessels at catastrophic exposure levels. German Ruhr Valley and US Gulf Coast petrochemical corridors generate the deepest premium pools due to mandatory inspection regimes and lender-imposed coverage floors.
- Commercial Buildings:Office complexes, hotels, and retail centers balance equipment value against business interruption severity. Netherlands commercial property owners are accelerating coverage expansion as national building codes tighten combustion emissions thresholds and efficiency renovation mandates compress replacement timelines.
- Residential Units:Single-family homes and multi-tenant dwellings represent the volume frontier. UK home service plan penetration climbs fastest among aging boiler stocks in suburban London and Manchester corridors.
- Utilities:District heating networks and power generation assets require specialized underwriting. District heating operators in Scandinavian cities are displacing standalone policies with integrated engineering service agreements.
By premium depth, Industrial Facilities dominate. By policy count velocity, Residential Units are gaining share fastest.
Coverage Area:
Geographic scope determines regulatory complexity and cross-border claims handling infrastructure requirements.
- National:Confined to single-jurisdiction risks with localized inspection protocols. US domestic programs leverage OSHA certification reciprocity across state lines to streamline multi-site manufacturing accounts.
- Regional:Spans contiguous regulatory zones with harmonized standards. EU member state coverage benefits from Pressure Equipment Directive reciprocity, though Germany and France maintain supplemental national inspection boards.
- Local:Restricted to municipal or metropolitan boundaries. Urban building codes in London and Paris create hyperlocal coverage specifications for historic district heating installations.
- International:Encompasses multi-country operations with complex jurisdiction stacking. Multinational chemical processors require this tier to align coverage across US, German, and Chinese facilities under unified claims protocols.
By policy volume, National coverage leads. By complexity premium, International commands the steepest expansion trajectory.
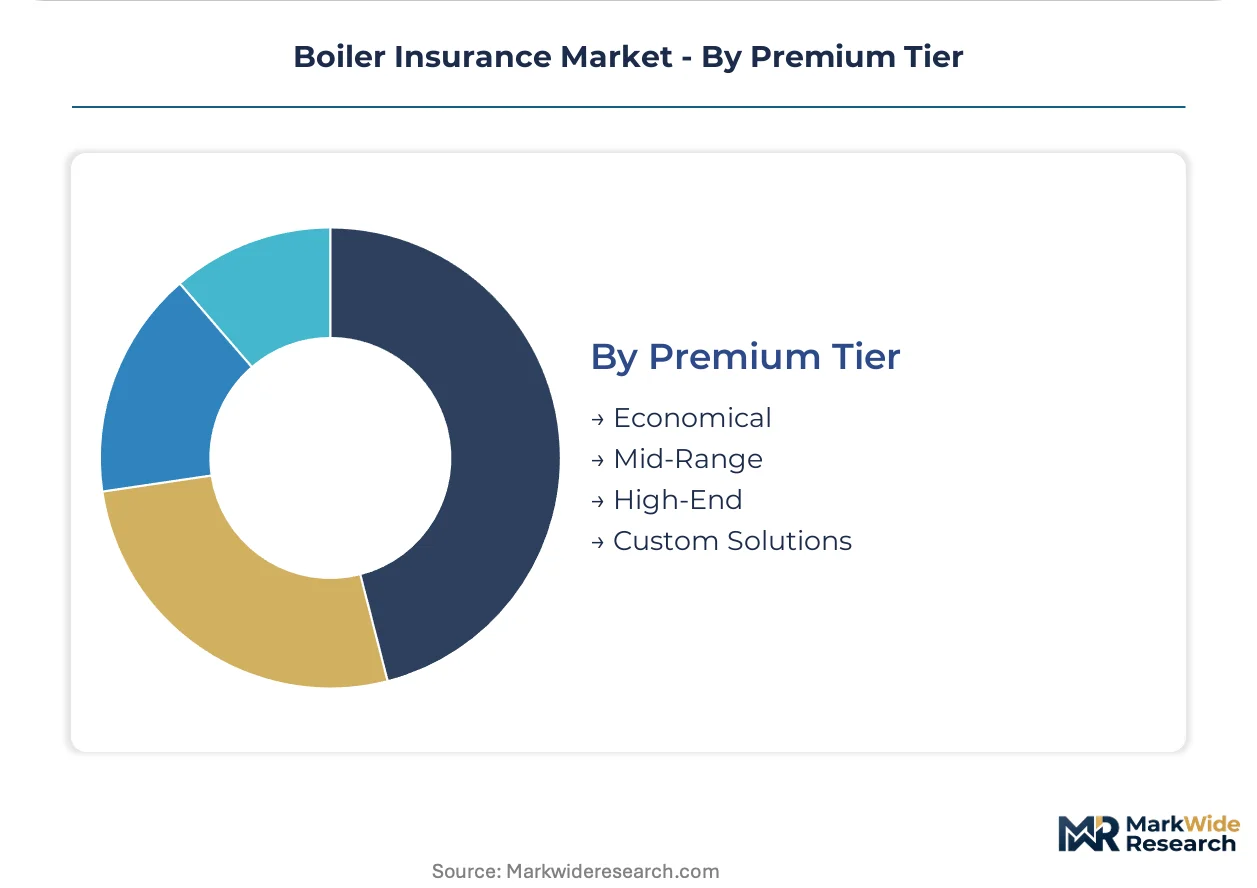
Premium Tier:
Customer type and application criticality stratify pricing architecture across standardized and bespoke product lines.
- Economical:Stripped coverage with high deductibles and capped liability limits. Residential landlords and small commercial property owners in price-sensitive UK markets purchase through aggregator platforms.
- Mid-Range:Balanced protection with moderate deductibles and standard inspection frequencies. German mid-sized manufacturing plants represent the widest buyer base in this tier.
- High-End:Enhanced limits, priority claims response, and embedded engineering services. Data center operators in Frankfurt and Amsterdam command this tier for mission-critical thermal load protection.
- Custom Solutions:Bespoke structures for catastrophic exposure with unique risk profiles. Hospital and pharmaceutical manufacturing installations in Switzerland and Belgium extract superior margins through specialized underwriting.
By buyer count, Mid-Range leads. By margin expansion, Custom Solutions are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Insurer technical capabilities cluster where pressure vessel inspection infrastructure and regulatory enforcement are most mature. Germany, the United Kingdom, the United States, France, and the Netherlands concentrate underwriting expertise and claims handling networks.
Germany
Aging commercial boiler stocks and EU Green Deal renovation mandates drive coverage expansion. The Pressure Equipment Directive and national inspection boards under KBA oversight compress replacement timelines. The Ruhr Valley petrochemical corridor generates deep premium pools as facilities upgrade thermal systems to meet emissions thresholds.
United Kingdom
Residential home service plan penetration climbs fastest among aging suburban boiler stocks. CORGI registration requirements and Gas Safe regulations embed insurers within compliance verification workflows. London and Manchester corridors concentrate digital-first distribution platforms serving landlord portfolios.
United States
OSHA pressure vessel certification mandates generate recurring premium demand tied to documented compliance. The Gulf Coast petrochemical belt and Midwest manufacturing corridors dominate commercial placements. Texas and Louisiana facilities face catastrophic exposure levels that command specialized underwriting.
France
Commercial building efficiency mandates under the EU Green Deal accelerate policy realignment. ANSM and national boiler inspection frameworks tighten certification reciprocity with neighboring jurisdictions. The Paris metropolitan area exhibits bundled service contract adoption as facilities managers prioritize single-vendor accountability.
Netherlands
National building codes tighten combustion emissions thresholds faster than EU baseline requirements. District heating operators in Amsterdam and Rotterdam displace standalone policies with integrated engineering service agreements. Efficiency renovation mandates compress equipment life assumptions in underwriting models.
Boiler Insurance Market Key Industry Players
Concentration sits with engineering-insurance hybrids possessing century-old inspection heritages and cross-border technical assessment networks. The market structure tiers between integrated property-casualty conglomerates, specialized machinery breakdown underwriters, and digital-first residential service plan administrators. Dominant competitive moves include portfolio diversification into predictive maintenance services and strategic partnerships with IoT sensor providers.
Within the engineering-insurance hybrid tier, The Hartford Steam Boiler Inspection and Insurance Company and Allianz SE anchor technical risk assessment capabilities across commercial portfolios. Aviva plc occupies a position exemplifying digital-first distribution for residential segments. Among specialized service plan administrators, HomeServe Membership Ltd. and Domestic & General Group Limited represent the volume frontier in home emergency coverage.
| Leading Market Players |
|---|
| Aviva plc |
| Axa S.A. |
| The Hartford Steam Boiler Inspection and Insurance Company |
| British Gas |
| HomeServe Membership Ltd. |
| Domestic & General Group Limited |
| Allianz SE |
| Bosch Thermotechnology Ltd. |
| CORGI HomePlan Ltd. |
| Others |
Cost & Logistics Intelligence
Heat pump substitution for fossil-fuel boilers in residential segments redraws procurement geography across Europe while compressing premium pools for traditional combustion coverage. Dutch and German building codes now mandate efficiency thresholds that disqualify aging natural-gas installations, forcing insurers to recalibrate pricing models around shrinking addressable markets for conventional boiler policies.
Pricing Analysis
The EU Pressure Equipment Directive dictates the pricing tier structure across commercial portfolios, embedding inspection frequency and certification reciprocity into premium calculations. Three-tier pricing structure across premium, standard, and economy levels separates data center operators with mission-critical thermal loads from mid-sized manufacturing plants and price-sensitive residential landlords. Cost compression in the economy tier intensifies because digital distribution platforms aggregate buyer demand and erode broker commissions. Residential landlords in UK urban rental markets exhibit the highest price sensitivity, while hospital and pharmaceutical installations in Switzerland and Belgium accept premium outlays for bespoke coverage structures.
Supply Chain Analysis
Certified boiler engineer scarcity in Eastern European markets constrains risk assessment capacity across EU member states expanding coverage mandates. Germany, the United Kingdom, and the Netherlands concentrate underwriting expertise and claims handling infrastructure, drawing from alloy steel manufacturing inputs, IoT sensor networks, and cross-border technical assessment capabilities. Single-source vulnerability sits with legacy inspection platforms that resist API connectivity with predictive maintenance systems. Distribution runs through broker-mediated placements for commercial accounts and direct-to-customer platforms for residential service plans.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Boiler insurance sits in early-cycle expansion as EU Green Deal renovation mandates force accelerated equipment turnover and realign risk transfer preferences toward bundled service contracts.
For Market Incumbents: Consolidate engineering-inspection capabilities through backward integration into IoT sensor partnerships and predictive analytics platforms. Heat pump substitution in residential segments threatens traditional premium pools, requiring capacity expansion in data center thermal load protection and hydrogen-ready boiler underwriting expertise. For New Entrants and Emerging Players: Differentiate on digital-first distribution and real-time policy customization for small commercial accounts in the Netherlands and France where national building codes outpace EU baseline requirements. Mid-sized manufacturing plants in the UK and Germany represent the most penetrable segment, with integrated machinery breakdown and engineering service agreements displacing standalone policies. For Investors and Strategic Acquirers: EU Pressure Equipment Directive expansion reshapes the acquisition landscape toward insurers with established cross-border technical assessment networks and certified inspector databases. Long-term viability centers on engineering-actuarial hybrid capabilities that traditional insurance programs rarely produce. Watch hydrogen-ready boiler standardization as the signal for liability category creation requiring actuarial recalibration.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Sensor Network Integration | Enables dynamic premium adjustments based on real-time equipment health telemetry from industrial facilities. |
| Cross-Border Technical Assessment Expansion | Captures first-mover advantages as EU member states tighten certification reciprocity rules under Pressure Equipment Directive. |
| Hydrogen-Ready Boiler Underwriting Development | Addresses emerging liability categories from combustion technology specifications for hydrogen-compatible installations. |
| Integrated Service Contract Bundling | Aligns with facilities manager demand for single-vendor accountability across UK and French commercial property markets. |
| Digital-First Distribution Platform Buildout | Reduces acquisition costs and enables real-time customization for small commercial accounts bypassing traditional brokers. |
Research Approach
A standing panel of underwriting directors, claims operations managers, certified boiler inspectors, and facilities management executives provided ongoing calibration across primary fieldwork and secondary validation. Underwriting directors at engineering-insurance hybrids supplied premium pool and risk assessment methodologies. Claims operations managers detailed response protocols and loss adjustment workflows. Certified boiler inspectors contributed technical failure mode data and inspection volume constraints. Facilities management executives described procurement patterns and service contract preferences. Secondary sources included EU Pressure Equipment Directive implementation reports, OSHA enforcement databases, national boiler inspection board filings, and commercial property insurance regulatory disclosures. Bottom-up policy count and premium volume estimates triangulated against top-down market sizing from regulatory mandate coverage minimums.
Model outputs underwent consistency checks against external benchmarks including documented compliance verification volumes, mandatory inspection regime expansion timelines, and cross-border technical assessment network coverage. Segmentation dimensions modeled encompass policy type, end user category, geographic coverage scope, and premium tier stratification across the projection horizon. CAGRs derived from equipment replacement cycle compression rates, regulatory mandate adoption curves, and penetration velocity of bundled service contracts. Industry-specific forecast inputs incorporated EU Green Deal building renovation mandate implementation schedules and hydrogen-ready boiler standardization progress.
Material uncertainties — steel price volatility, certified inspector scarcity, and heat pump substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement intensity and technology transition timelines that could shift with political or economic developments. Practitioners should keep alternative scenarios live as EU member state implementation schedules and hydrogen infrastructure deployment evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Asia-Pacific Mobile Phone Insurance Market
Insurance
Global SME Insurance Market
Insurance
Telecommunication Insurance Market
Insurance
Saudi Arabia Travel Insurance Market
Insurance
Global Cargo Transportation Insurance Market
Insurance
Identity Theft Insurance Market
Insurance
Intellectual Property Insurance Market
Insurance
Travel Insurance Market
Insurance
Asia-Pacific Extended Warranty Market
Insurance
Global Flood Insurance Market
Insurance
Europe Travel Insurance Market
Insurance
Canada Property and Casualty Insurance Market
Insurance
Mobile Phone Insurance Market
Insurance
France Liability Insurance Market
Insurance
Insurance Claims Services Market
Insurance
Earthquake Insurance Market