
 Australia Parametric Insurance Market | 2026-2036
Australia Parametric Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Parametric Insurance Market Insights
Traditional indemnity-based coverage is pivoting toward parametric structures as basis risk modeling improves and satellite data costs decline. Munich Reinsurance Company leverages its catastrophe modeling infrastructure to price weather index contracts with greater granularity. QBE Insurance Group Limited anchors its rural portfolio through parametric crop loss products tied to Bureau of Meteorology rainfall grids. Suncorp Group competes by embedding parametric triggers directly into existing farm policy endorsements.
Parametric insurance is a risk transfer mechanism where claim payments activate automatically upon the occurrence of a predefined event measured by an objective index, such as millimeters of rainfall, wind speed in knots, or seismic magnitude on the Richter scale, rather than requiring proof of actual financial loss. The primary commercial purpose is to deliver rapid liquidity to policyholders after natural disasters when traditional loss adjustment would delay recovery by weeks or months. Weather index coverage dominates premium volume due to its applicability across drought, excess rainfall, and temperature extremes affecting Australian agriculture. Digital platform delivery is expanding fastest as insurers embed API-connected data feeds that trigger instant settlement without claims adjustment overhead. Broker channels retain margin concentration in complex corporate placements where bespoke index design requires intermediary expertise.
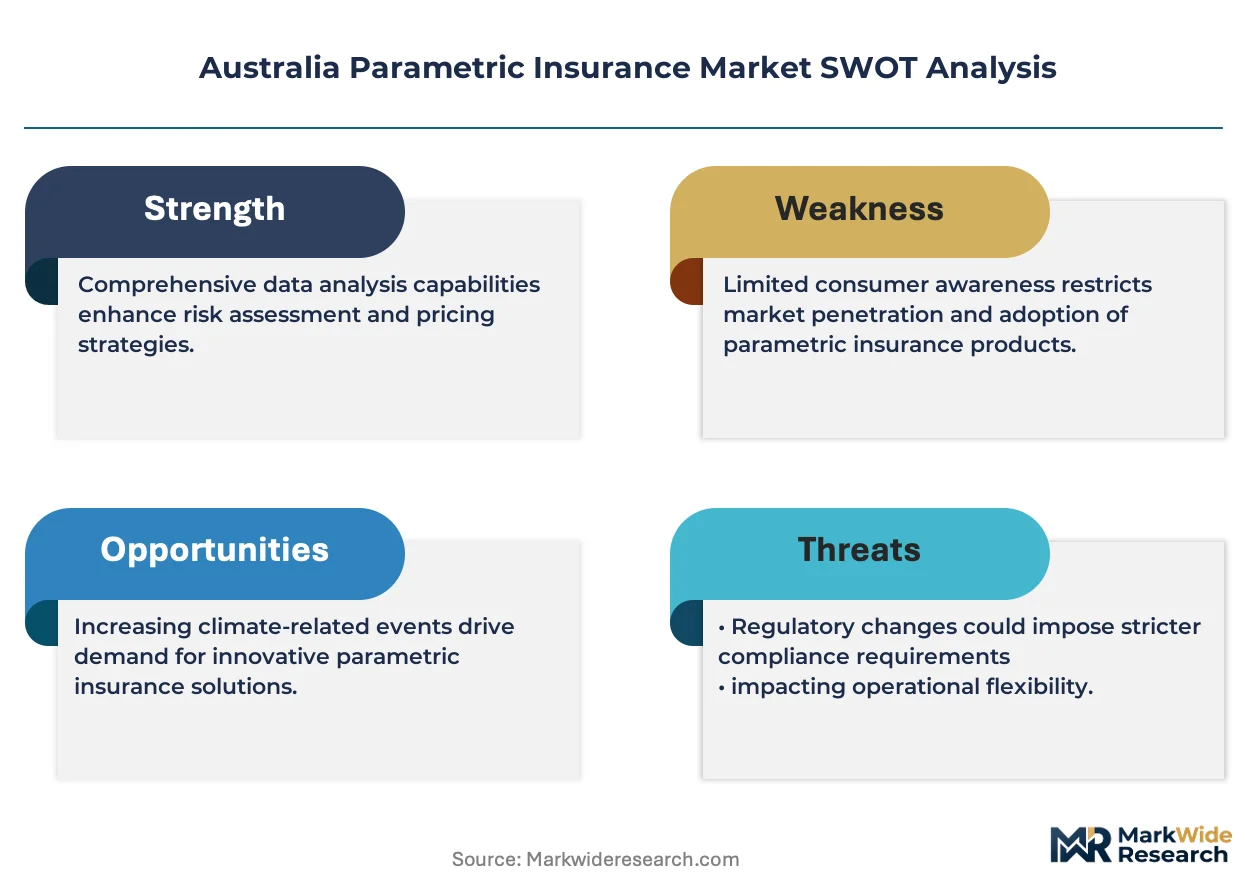
APRA's climate risk disclosure requirements and the Insurance Contracts Act framework shape product design by mandating clear trigger definitions and transparent basis risk disclosure to policyholders. The ICA's Code of Practice for general insurers extends consumer protection standards to parametric offerings sold through direct and digital channels. TGA oversight applies where parametric health coverage intersects with medical device or pharmaceutical supply chain disruption policies. Stakeholders must monitor how ASIC's evolving guidance on unfair contract terms interacts with automated payout mechanisms that remove traditional claims discretion.
Market Dynamics
APRA's climate risk disclosure mandates are compressing product development cycles as insurers redesign policy structures to meet granular trigger-definition requirements. Satellite data cost deflation is simultaneously enabling more precise index calibration across rainfall grids and temperature bands.
Growth Catalysts
- APRA Prudential Standard CPS 230:Operational risk management rules now explicitly address climate-related financial disclosures, forcing insurers to embed parametric triggers into agricultural portfolios.
- Grains sector consolidation:Large-scale wheat and barley operations across Queensland's Darling Downs are demanding coverage for multi-peril crop losses that traditional indemnity products cannot price efficiently.
- Synthetic aperture radar:Satellite soil moisture detection is improving drought index accuracy, reducing basis risk premiums for pastoral coverage in New South Wales.
Market Restraints
- Basis risk calibration costs:Granular weather station data acquisition for remote Western Australian stations consumes disproportionate actuarial resources relative to premium volume.
- Single-source satellite dependency:European Space Agency Sentinel data feeds underpin most rainfall index products, creating concentration vulnerability if orbital coverage degrades.
- Insurance Contracts Act friction:Ambiguity around " utmost good faith" obligations when automated payouts remove claims investigation creates legal uncertainty for product filings.
Strategic Opportunities
- Tasmanian aquaculture:Salmon and oyster producers face temperature-driven mortality events that parametric heatwave indices could cover with minimal loss adjustment overhead.
- ASIC unfair contract term guidance:Proposed clarifications on automated decision-making may legitimize pure parametric structures previously treated as potentially unfair.
- API-embedded micro-policies:Farm management software platforms represent a nascent distribution channel for just-in-time coverage tied to planting decisions.
Industry Challenges
- Actuarial talent scarcity:Cross-disciplinary expertise combining catastrophe modeling, agricultural science, and Australian contract law remains concentrated among senior practitioners at major reinsurers.
- Legacy system integration:Core policy administration platforms built for indemnity-based claims workflows require expensive retrofitting to handle parametric trigger automation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Parametric Insurance Market |
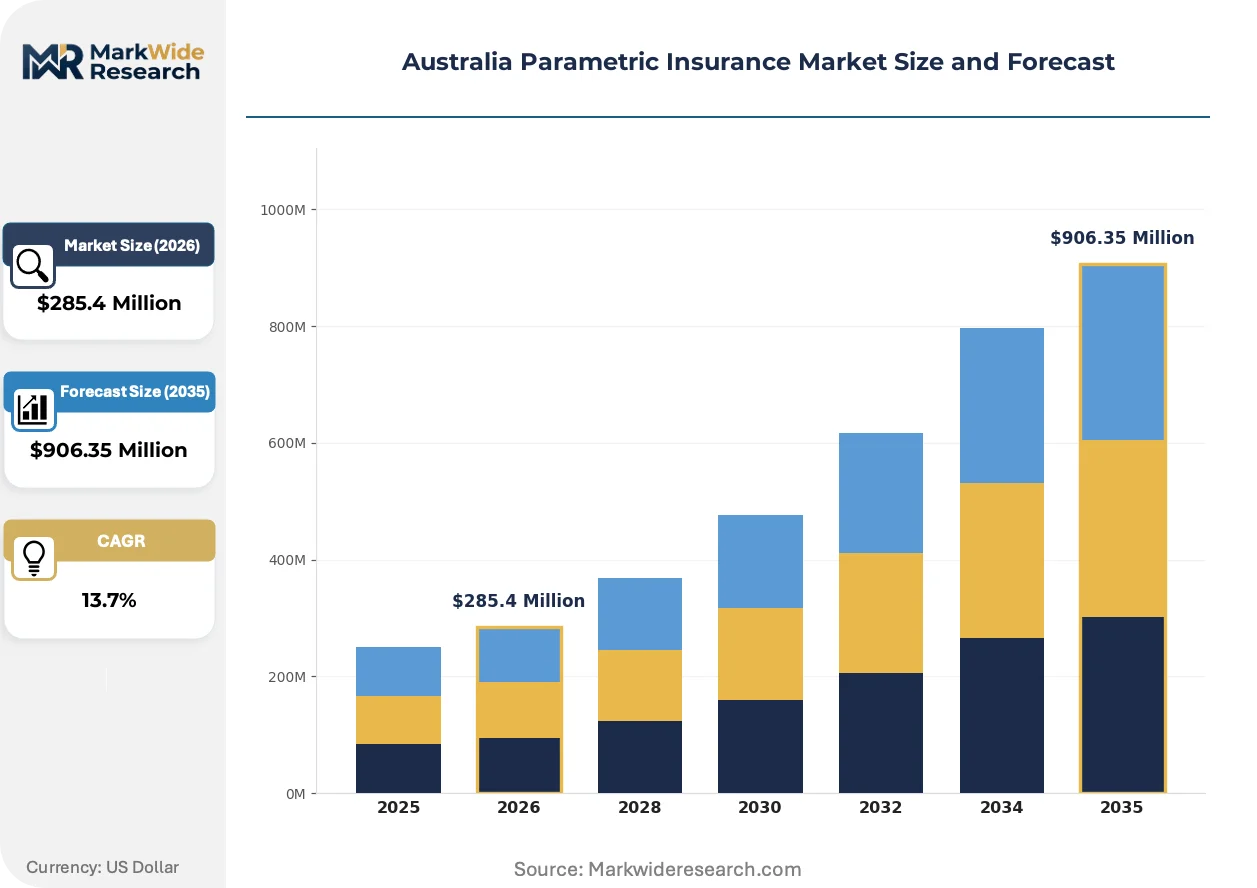
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $906.35 Million |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Weather Index, Catastrophe Bonds, Business Interruption, Health Coverage Customer Type: Individuals, Small Enterprises, Corporates, Agricultural Producers Delivery Mode: Digital Platforms, Broker Channels, Direct Sales, Third-Party Administrators Coverage Type: Property Damage, Income Protection, Crop Loss, Event Cancellation |
| Companies Covered | Insurance Australia Group, Chubb Limited, QBE Insurance Group Limited, Munich Reinsurance Company, Swiss Reinsurance Company, Allianz Australia, Zurich Insurance Group Ltd., AIG, Suncorp Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Parametric Insurance Market Trends and Innovations
Parametric insurance in Australia is pivoting from standalone products toward embedded triggers within broader risk management ecosystems. This structural shift is compressing distribution costs while expanding addressable demand beyond traditional agricultural buyers.
Blockchain-enabled smart contracts are converging with Bureau of Meteorology data feeds to execute automatic settlements without intermediary verification. Mid-sized cotton growers in the Namoi Valley are piloting these structures for flood coverage. The technology is converging with existing farm accounting software, collapsing the time between trigger event and liquidity delivery from weeks to hours.
APRA's 2023 climate risk disclosure enhancements now require insurers to publish scenario analysis for agricultural portfolios under warming trajectories. This regulatory pressure is accelerating product innovation as carriers redesign triggers to remain viable under shifting rainfall patterns. The grains sector is responding by demanding multi-year policies with adjustable index thresholds rather than annual renewal structures.
Buyer procurement patterns are fragmenting as corporate agribusinesses bypass traditional broker channels for direct platform access. Large-scale pastoral operations in northern Queensland are negotiating bespoke index designs through API-connected portals that aggregate satellite data, soil sensors, and weather station feeds. This channel shift is most visible among holdings exceeding fifty thousand hectares where internal risk management teams possess sufficient technical sophistication to evaluate basis risk independently.
Australia Parametric Insurance Market Segmentation
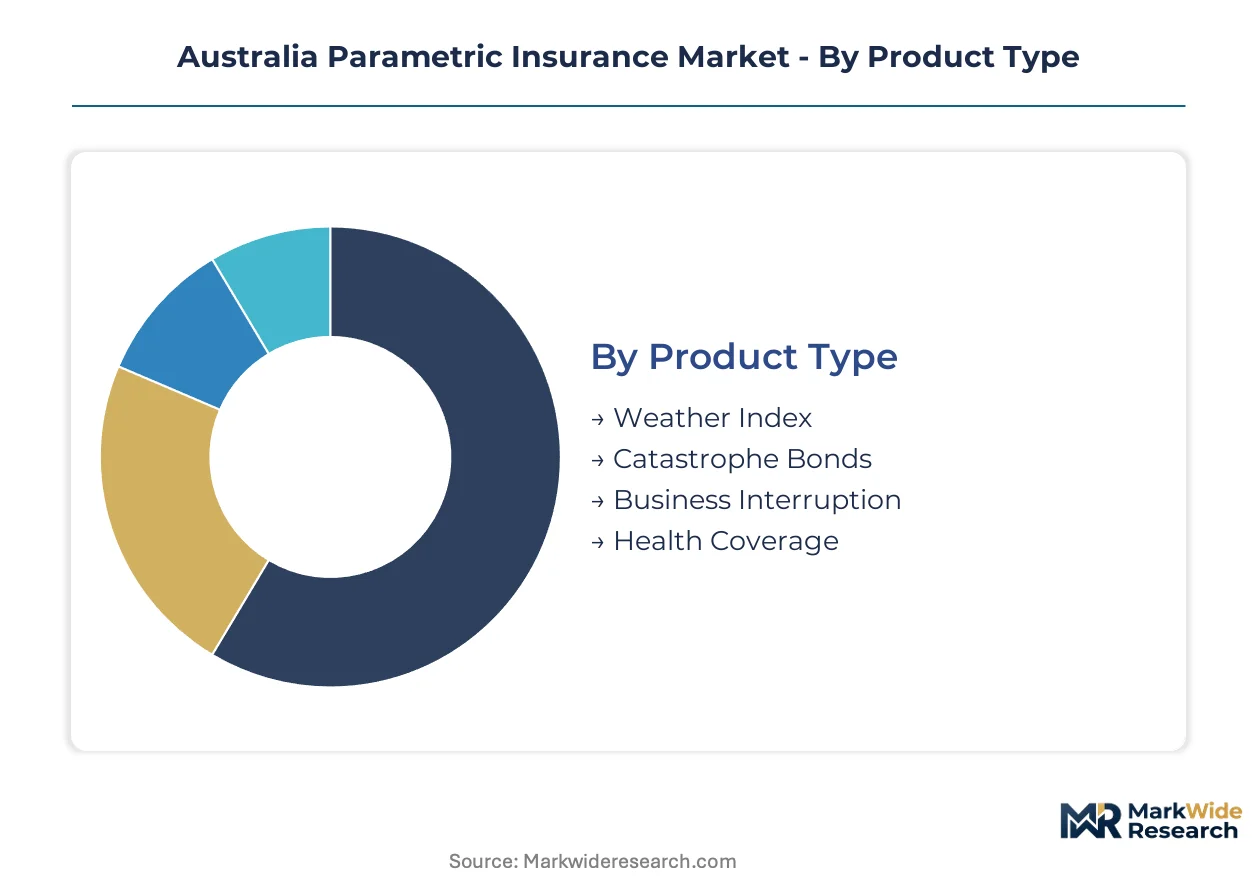
Segmentation reveals how capital deployment and distribution economics vary sharply across trigger types and buyer sophistication. Agricultural portfolios concentrate premium volume, while digital delivery platforms reshape cost structures for micro-policies.
Product Type:
Capital intensity varies dramatically across trigger mechanisms, with catastrophe bonds demanding the deepest actuarial infrastructure and satellite data integration.
- Weather Index:Rainfall and temperature triggers dominate Australian agricultural portfolios. Queensland grain operations drive demand for Bureau of Meteorology grid-based coverage, though basis risk calibration consumes disproportionate modeling resources for remote Western Australian stations.
- Catastrophe Bonds:Securities-based risk transfer structures require institutional-grade issuance capacity and ratings agency engagement. Sydney-based reinsurance intermediaries structure these for corporate agribusinesses seeking multi-peril protection beyond traditional carrier capacity.
- Business Interruption:Parametric triggers for revenue loss following predefined events. Supply chain disruption policies for pharmaceutical distributors utilize TGA-registered facility shutdown indices.
- Health Coverage:Medical supply chain and hospital service disruption triggers. Limited penetration reflects ASIC uncertainty around automated payouts for health-related financial losses.
Weather Index absorbs the bulk of installed capacity; Catastrophe Bonds is expanding most quickly.
Customer Type:
Buyer sophistication determines pricing power and basis risk tolerance, with corporate risk managers commanding bespoke index designs unavailable to retail purchasers.
- Individuals:Simplified triggers for home and vehicle damage from hail or flood events. Digital platforms reduce distribution costs, though disclosure requirements under the Insurance Contracts Act limit automation.
- Small Enterprises:Tourism operators and regional retailers utilize revenue protection tied to rainfall or temperature extremes. Broker channels retain relevance for policyholders lacking internal risk assessment capability.
- Corporates:Mining and logistics firms structure multi-location coverage across Australian states. APRA's climate disclosure mandates force these buyers to document parametric instruments in financial statements.
- Agricultural Producers:Pastoral and cropping operations across New South Wales and Queensland represent the core addressable market. Large-scale holdings exceeding fifty thousand hectares increasingly negotiate direct platform access, bypassing traditional intermediaries.
Agricultural Producers command the deepest premium pool; Corporates is gaining share fastest.
Delivery Mode:
Channel economics diverge based on policy complexity and trigger customization requirements, with API-connected platforms collapsing settlement timelines.
- Digital Platforms:Real-time data feeds from satellites and weather stations enable instant trigger verification. Farm management software integrations allow just-in-time coverage activation tied to planting decisions.
- Broker Channels:Complex corporate placements and multi-peril agricultural structures require intermediary expertise for index design and basis risk explanation. Margin concentration persists despite platform competition.
- Direct Sales:Carrier-owned channels for standardized weather index products. QBE and Suncorp utilize direct outreach for existing farm policy endorsements.
- Third-Party Administrators:Outsourced claims verification and settlement execution. Limited penetration in pure parametric products where automation eliminates traditional adjustment functions.
Broker Channels retains the largest transaction value; Digital Platforms is climbing the fastest.
Coverage Type:
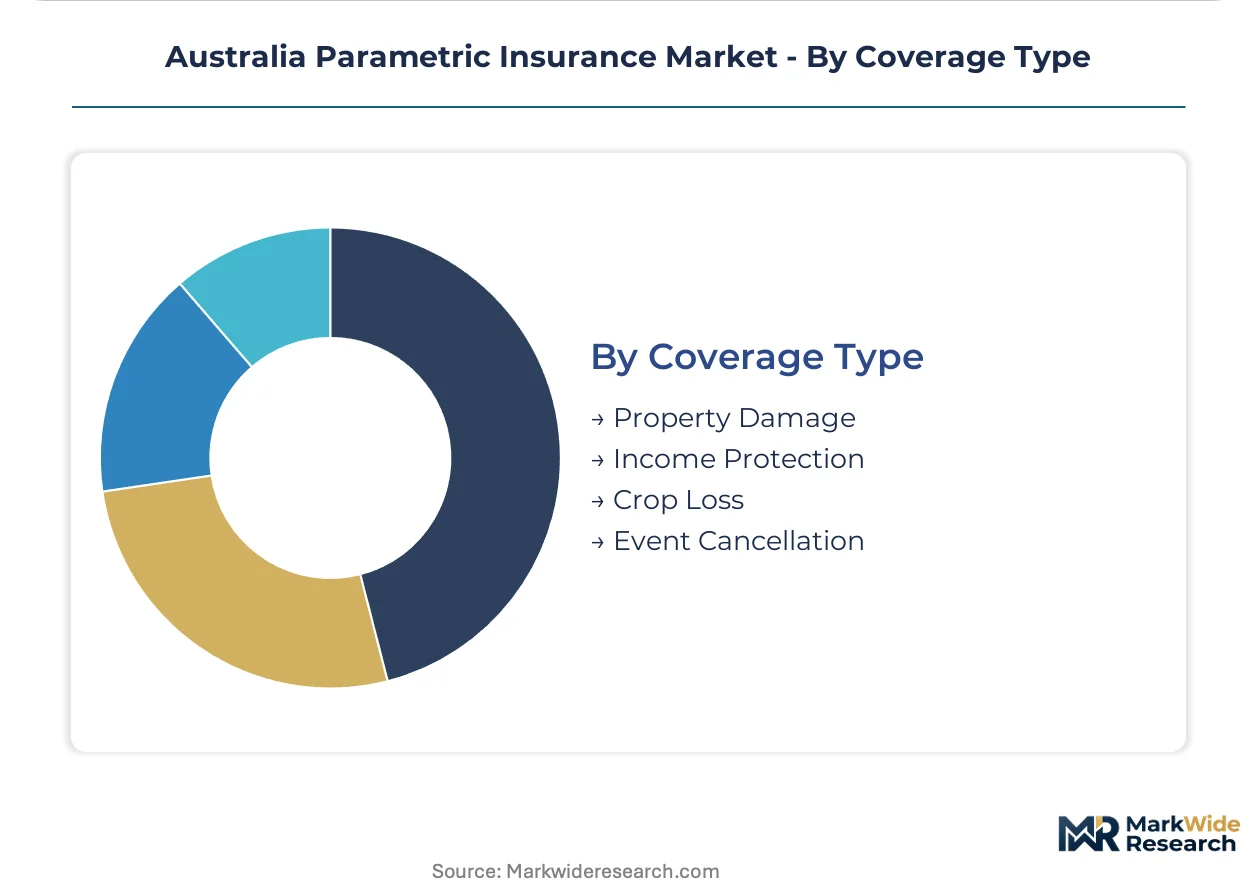
Trigger specificity and loss verification requirements shape product economics, with crop loss coverage benefiting from established satellite monitoring infrastructure.
- Property Damage:Physical asset destruction triggers utilizing seismic or wind speed indices. Industrial facilities in cyclone-prone Queensland coastal zones represent concentrated demand.
- Income Protection:Revenue-based triggers for business interruption without physical damage requirement. Professional services firms in flood-exposed Sydney and Brisbane metropolitan areas utilize these structures.
- Crop Loss:Yield-indexed coverage utilizing satellite-derived vegetation indices and rainfall grids. The grains sector across Darling Downs and Namoi Valley drives premium volume through multi-peril structures.
- Event Cancellation:Predefined triggers for festival, sporting, and conference disruption. Temperature and rainfall thresholds apply to outdoor events, though pandemic-related cancellations exposed limitations in parametric scope.
Crop Loss holds the dominant premium position; Income Protection is expanding most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Queensland and New South Wales concentrate parametric insurance demand through their drought-prone grain belts and flood-exposed coastal catchments. APRA's climate disclosure mandates have accelerated product uptake across these agricultural heartlands.
New South Wales
The Namoi Valley cotton belt and Liverpool Plains grain region drive weather index adoption for multi-peril crop coverage. APRA's CPS 230 operational risk standards force Sydney-based insurers to document climate exposure in agricultural portfolios. Newcastle and Port Macquarie serve as distribution hubs where broker channels retain dominance for complex pastoral structures.
Queensland
Darling Downs wheat operations and northern Queensland cattle stations generate concentrated demand for rainfall-triggered drought products. The state's Farm Business Resilience Program subsidizes parametric coverage uptake among eligible producers. Brisbane anchors reinsurance intermediary activity while Toowoomba functions as the grains sector's policy origination center.
Victoria
Murray-Darling Basin irrigators and Gippsland dairy operations utilize temperature-indexed heat stress coverage for livestock mortality. The Victorian Agriculture and Climate Change Council promotes parametric instruments within its farm adaptation framework. Melbourne's insurance technology cluster supports API-connected platform development for automated settlement systems.
Western Australia
Wheatbelt broadacre cropping faces acute basis risk calibration challenges due to sparse weather station density across the Wheatbelt and Great Southern regions. The state's Department of Primary Industries and Regional Development partners with satellite data providers to improve remote sensing coverage. Perth-based underwriters concentrate on corporate agribusiness placements rather than smallholder outreach.
South Australia
Eyre Peninsula grain growers and Barossa Valley viticulturists employ frost-indexed parametric triggers for yield protection. The South Australian Drought Resilience Adoption and Innovation Hub facilitates producer education on index-based instruments. Adelaide serves as the regional center for actuarial modeling services supporting cross-border coverage structures.
Australia Parametric Insurance Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent carriers embed parametric triggers into existing farm policy endorsements. The market exhibits tiered consolidation with global reinsurers anchoring catastrophe modeling infrastructure while domestic general insurers control distribution through established rural agency networks. Two strategic archetypes predominate: integrated multi-line carriers leveraging indemnity policy relationships, and specialized reinsurance intermediaries structuring bespoke index designs for large-scale agribusinesses. Technology licensing and strategic data partnerships constitute the principal competitive moves as satellite feed costs decline.
Within the integrated carrier tier, QBE Insurance Group Limited and Suncorp Group exemplify domestic incumbents converting traditional farm portfolios into hybrid parametric-indemnity structures. Munich Reinsurance Company anchors the reinsurance intermediary archetype, occupying a position where catastrophe modeling infrastructure enables granular weather index pricing. These three entities collectively represent the competitive spectrum from direct retail distribution through complex corporate placement.
| Leading Market Players |
|---|
| Insurance Australia Group |
| Chubb Limited |
| QBE Insurance Group Limited |
| Munich Reinsurance Company |
| Swiss Reinsurance Company |
| Allianz Australia |
| Zurich Insurance Group Ltd. |
| AIG |
| Suncorp Group |
| Others |
Pricing and Supply Chain Analysis
Basis risk calibration tiers split the Australian parametric insurance market into precision-priced bespoke structures for large pastoral holdings and standardized rainfall-grid products for broadacre grain operators. This bifurcation concentrates actuarial talent and satellite data procurement at the premium tier while compressing margins on commoditized weather index coverage distributed through digital platforms.
Pricing Analysis
Volume concentrates in standardized Bureau of Meteorology grid-based weather index products while margins accrue to bespoke multi-peril structures for corporate agribusinesses. Price differentiation hinges on trigger granularity and basis risk disclosure depth, with satellite soil moisture calibration commanding premium positioning. Pricing pressure stems from synthetic aperture radar data cost deflation eroding technical moats. Smallholder grain producers exhibit acute price sensitivity; mining and logistics corporates prioritize coverage customization over premium minimization.
Supply Chain Analysis
APRA prudential certification and ICA Code of Practice compliance gate access to policy filings and consumer distribution channels. Satellite data feeds draw from European Space Agency Sentinel infrastructure, Bureau of Meteorology ground stations, and commercial synthetic aperture radar providers. Single-source satellite dependency creates concentration vulnerability if orbital coverage degrades. Distribution runs through broker channels for complex placements and API-connected farm management software for micro-policies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Parametric insurance in Australia sits at a technology-transition inflection where blockchain-enabled smart contracts and automated settlement APIs displace traditional claims-adjustment workflows. This shift rewards carriers that rewire core policy administration systems around trigger automation rather than indemnity verification.
For Market Incumbents: Cement distribution control by embedding parametric triggers into existing farm policy endorsements before specialized reinsurance intermediaries capture direct platform relationships with large-scale agribusinesses. Invest in catastrophe modeling infrastructure to defend pricing power as satellite data commoditization erodes technical differentiation. Prioritize API integration with farm management software platforms to intercept planting-decision moments for just-in-time coverage activation.
For New Entrants and Emerging Players: Capture Tasmanian aquaculture and Victorian dairy heat stress segments where temperature-indexed mortality coverage remains underdeveloped relative to grain belt saturation. Target corporate risk managers at mining and logistics firms with multi-location coverage structures that incumbent legacy systems cannot price efficiently. Lead with direct platform access and transparent basis risk quantification tools that bypass broker margin extraction.
For Investors and Strategic Acquirers: Re-rating potential sits with specialized reinsurance intermediaries possessing catastrophe modeling infrastructure as APRA climate disclosure mandates force agricultural portfolio redesign across the analysis window. Acquisition focus should target actuarial teams combining agricultural science expertise with Australian contract law fluency. Monitor ASIC guidance on automated decision-making as the signal for regulatory legitimization of pure parametric structures.
| Strategic Initiative | Industry Significance |
|---|---|
| API-Connected Platform Development | Enables instant settlement via Bureau of Meteorology data feeds, collapsing liquidity delivery from weeks to hours. |
| Satellite Data Partnership Expansion | Reduces basis risk premiums through synthetic aperture radar soil moisture detection for drought index calibration. |
| Blockchain Smart Contract Deployment | Automates payout execution without intermediary verification, piloted by Namoi Valley cotton growers for flood coverage. |
| Multi-Year Policy Structure Design | Addresses grains sector demand for adjustable index thresholds under shifting rainfall patterns from climate change. |
| Farm Management Software Integration | Creates just-in-time distribution channel tied to planting decisions, bypassing traditional renewal cycles. |
Research Methodology
Multi-period observation of satellite data cost trajectories, APRA prudential standard amendments, and grains sector consolidation patterns anchored the trend analysis, supplemented by interviews with agricultural risk managers, reinsurance pricing actuaries, farm management software developers, and broker channel heads. Secondary validation drew from APRA regulatory filings, Bureau of Meteorology climate datasets, Insurance Council of Australia industry statistics, and agricultural commodity production records. Bottom-up policy volume estimates triangulated against top-down premium pool calculations across the projection horizon.
Input-output matrices mapped weather index triggers, catastrophe bond issuance capacity, and digital platform penetration against customer sophistication tiers and delivery mode economics. Segmentation dimensions included product type, customer archetype, coverage mechanism, and state-level agricultural exposure. CAGRs were derived from trend extrapolation of satellite data adoption, climate disclosure compliance costs, and farm policy endorsement conversion rates, stress-tested against drought frequency and flood severity scenarios.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to European Space Agency orbital coverage continuity, ASIC unfair contract term rulings on automated payouts, and rainfall pattern non-stationarity under warming trajectories. A model refresh is warranted upon material change in APRA climate risk disclosure enforcement intensity or synthetic aperture radar data cost deflation acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Reinsurance Carriers Market
Insurance
Canada Health and Medical Insurance Market
Insurance
Green Insurance Market
Insurance
Germany Health and Medical Insurance Market
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
UK Commercial Insurance Market
Insurance
Agricultural Insurance Market
Insurance
Extended Warranty Agreement Market
Insurance
Greece Property and Casualty Insurance Market
Insurance
Drone Insurance Market
Insurance
Fire Insurance Market
Insurance
Liability Insurance Market
Insurance
Cloud Computing in Insurance Market
Insurance
USA Travelers Insurance Market
Insurance
Russia Property and Casualty Insurance Market
Insurance
Group Health Insurance Market