
 Agricultural Insurance Market | 2026-2036
Agricultural Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Agricultural Insurance Market Analysis
Parametric index pricing is rewriting how underwriters capture margin from weather-correlated agricultural risk. Munich Re Group leverages its catastrophe modeling infrastructure to dominate parametric product design across emerging markets. PICC Property and Casualty Company Limited anchors its portfolio through state-backed crop programs in China's major grain-producing provinces. Zurich Insurance Group competes by extending climate analytics services beyond pure indemnity into farm-level advisory platforms.
Agricultural insurance constitutes a specialized risk-transfer mechanism that pools production volatility across geographically dispersed farming operations, utilizing satellite-derived normalized difference vegetation index (NDVI) data, soil moisture probes, and automated weather station networks to trigger settlements without physical loss adjustment. Its primary commercial purpose centers on stabilizing farm cash flows to sustain credit access and input purchasing power across planting cycles. Crop insurance occupies the dominant share of premium volume globally, while revenue insurance commands expanding share as commodity futures integration enables price-yield bundled protection. Livestock insurance remains structurally underpenetrated outside OECD markets due to moral hazard constraints in individual animal verification.
The USDA's Risk Management Agency shapes product standardization through actuarial rate certification and premium subsidy tiers in the United States, while India's CEA and Agriculture Insurance Company of India jointly administer the world's largest subsidized crop program under PMFBY guidelines. EIOPA's solvency calibration for catastrophe reserve requirements across the European Union directly influences capacity allocation toward multi-peril coverage. Stakeholders must monitor how sovereign fiscal constraints on premium subsidies interact with private capital deployment into insurance-linked securities as alternative risk-bearing structures.
Market Dynamics
Parametric index insurance is collapsing traditional loss-adjustment cost structures across emerging-market smallholder segments, forcing incumbents to rebuild pricing models around satellite-triggered payouts rather than field-verified damage assessments.
Growth Catalysts
- India's PMFBY subsidy framework:The Pradhan Mantri Fasal Bima Yojana redirects sovereign capital toward revenue-based products, expanding addressable farmer populations beyond yield-only coverage pools.
- NDVI satellite integration:Normalized difference vegetation index data streams enable automated claims settlement, eliminating 60-90 day loss verification cycles that previously constrained policy uptake.
- Sub-Saharan cooperative aggregation:Smallholder farmer cooperatives in Kenya, Ethiopia, and Nigeria pool risk at village scale, creating viable premium pools that individual farmers cannot achieve alone.
Market Restraints
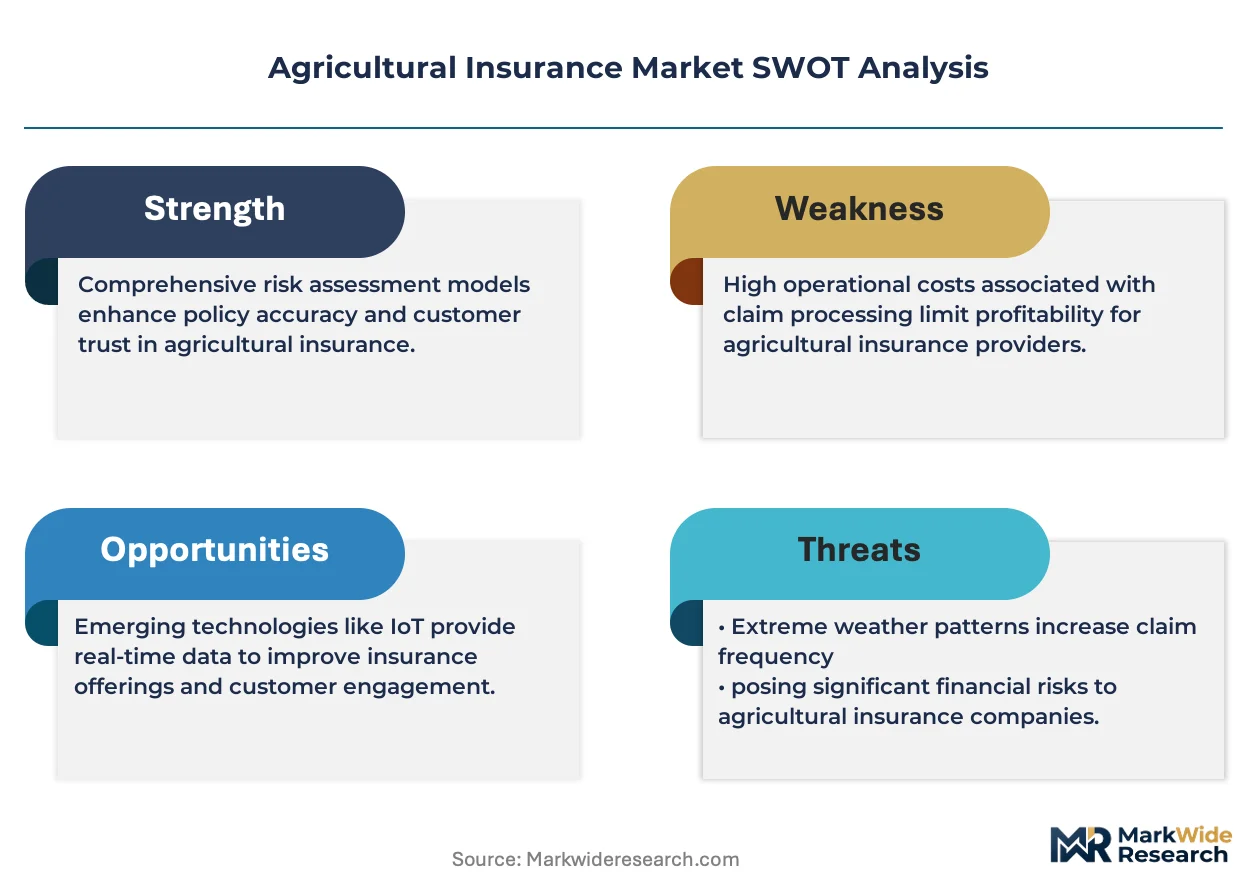
- Basis risk in index design:Parametric triggers based on rainfall or vegetation indices frequently misalign with actual on-farm losses, eroding policyholder trust and renewal rates in drought-prone regions.
- Livestock verification costs:Individual animal identification systems remain prohibitively expensive outside OECD markets, capping penetration in cattle-dependent economies like Brazil and Argentina.
- Sovereign fiscal constraints:Premium subsidy obligations under Brazil's Proagro and India's PMFBY face mounting pressure from fiscal consolidation targets, threatening demand elasticity.
Strategic Opportunities
- Microinsurance channel innovation:Mobile network operators and digital payment platforms in East Africa now distribute weather-index products through USSD interfaces, bypassing traditional agent networks entirely.
- Carbon credit bundling:Regenerative agriculture protocols create dual-revenue streams where soil carbon verification overlaps with risk data collection, opening new farmer value propositions.
- China's provincial expansion:PICC's state-backed programs in Heilongjiang and Henan provinces demonstrate scalable templates for penetrating underinsured interior grain belts.
Industry Challenges
- Actuarial data scarcity:Historical yield records remain fragmented across developing-market agricultural ministries, forcing underwriters to price policies with confidence intervals that compress margin.
- Climate model recalibration:Catastrophe risk models require continuous updating as weather volatility exceeds historical baselines, demanding specialized meteorological talent that insurers struggle to attract.
- Legacy core system integration:Established carriers face technical debt when embedding satellite data APIs into policy administration platforms built for manual claims workflows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Agricultural Insurance Market |
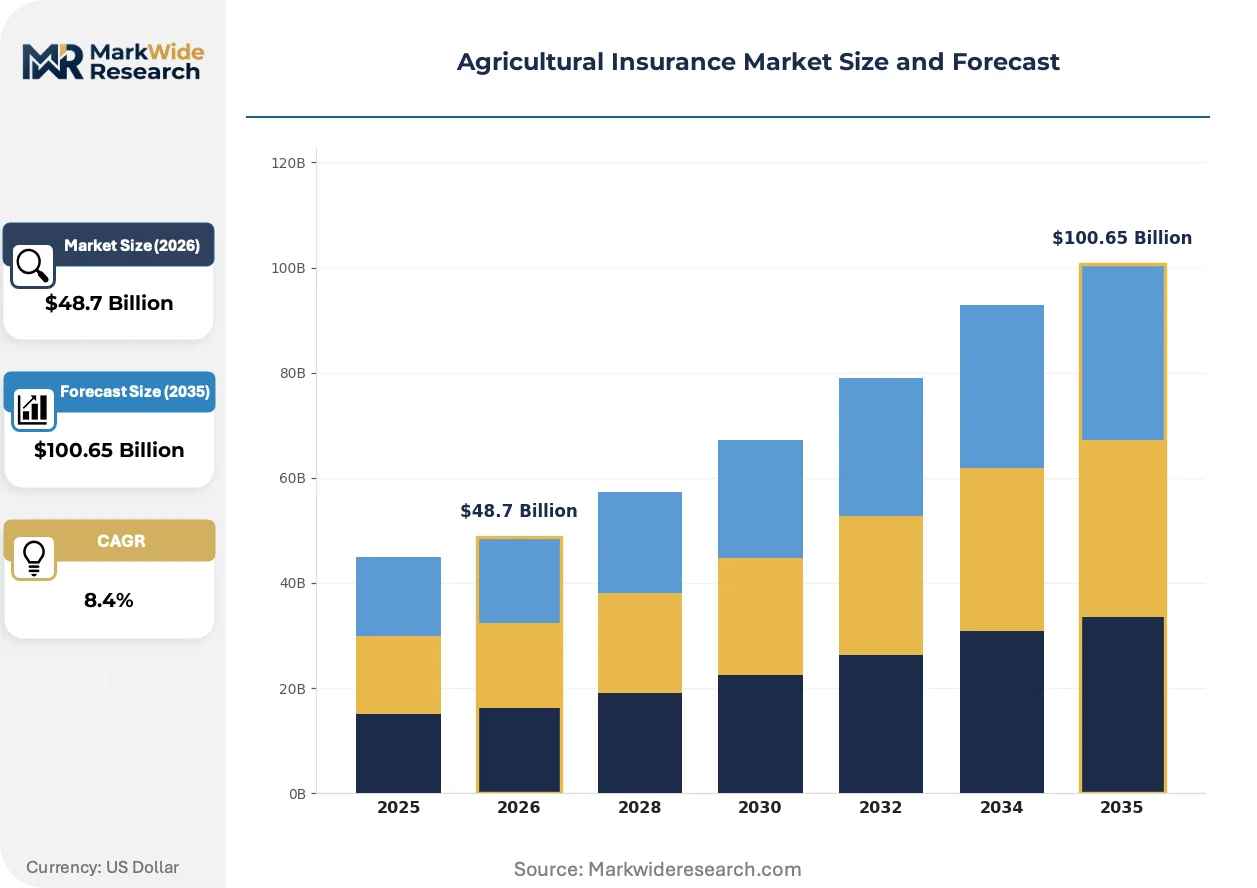
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $100.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crop Insurance, Livestock Insurance, Revenue Insurance, Farm Equipment Insurance Coverage Type: Yield Protection, Actual Revenue Coverage, Whole Farm Revenue Protection, Multi-Peril Coverage Policy Type: Individual Policy, Group Policy, Indexed Policy, Traditional Policy End User: Farmers, Agricultural Cooperatives, Agribusinesses, Insurers |
| Companies Covered | QBE Insurance Group, Chubb Ltd., Sompo Holdings, Zurich Insurance Group, Allianz SE, Munich Re Group, AXA, Agriculture Insurance Company of India, PICC Property and Casualty Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Agricultural Insurance Market Emerging Trajectories
Remote sensing infrastructure is collapsing the information asymmetry that historically separated agricultural underwriters from ground-truth production conditions, enabling real-time risk monitoring that reshapes contract design and capital deployment.
Blockchain-based smart contracts are collapsing settlement latency for parametric products by automating payout execution when satellite data feeds trigger predefined index thresholds. Ethiopian coffee cooperatives and Filipino rice farmer associations now pilot these systems, compressing the claims cycle from months to hours and eliminating disputes over damage verification that previously consumed administrative overhead.
The EU's CSRD sustainability disclosure requirements are mandating climate risk transparency across agricultural supply chains, forcing food processors and commodity traders to document insurance coverage as part of Scope 3 emissions reporting. German and Dutch agricultural cooperatives now require member farmers to maintain minimum coverage levels, converting voluntary risk transfer into procurement preconditions that stabilize premium volumes.
Buyer procurement patterns are fragmenting as large agribusiness operators bypass traditional broker channels to negotiate direct capacity arrangements with reinsurance markets. Brazilian soybean conglomerates and Australian wheat exporters now structure captive insurance vehicles or insurance-linked securities, disintermediating retail underwriters and capturing risk margin that previously accrued to distribution layers. This concentration of buying power is most visible in commodity-exporting economies where single entities control harvest volumes sufficient to diversify risk internally.
Agricultural Insurance Market Segmentation
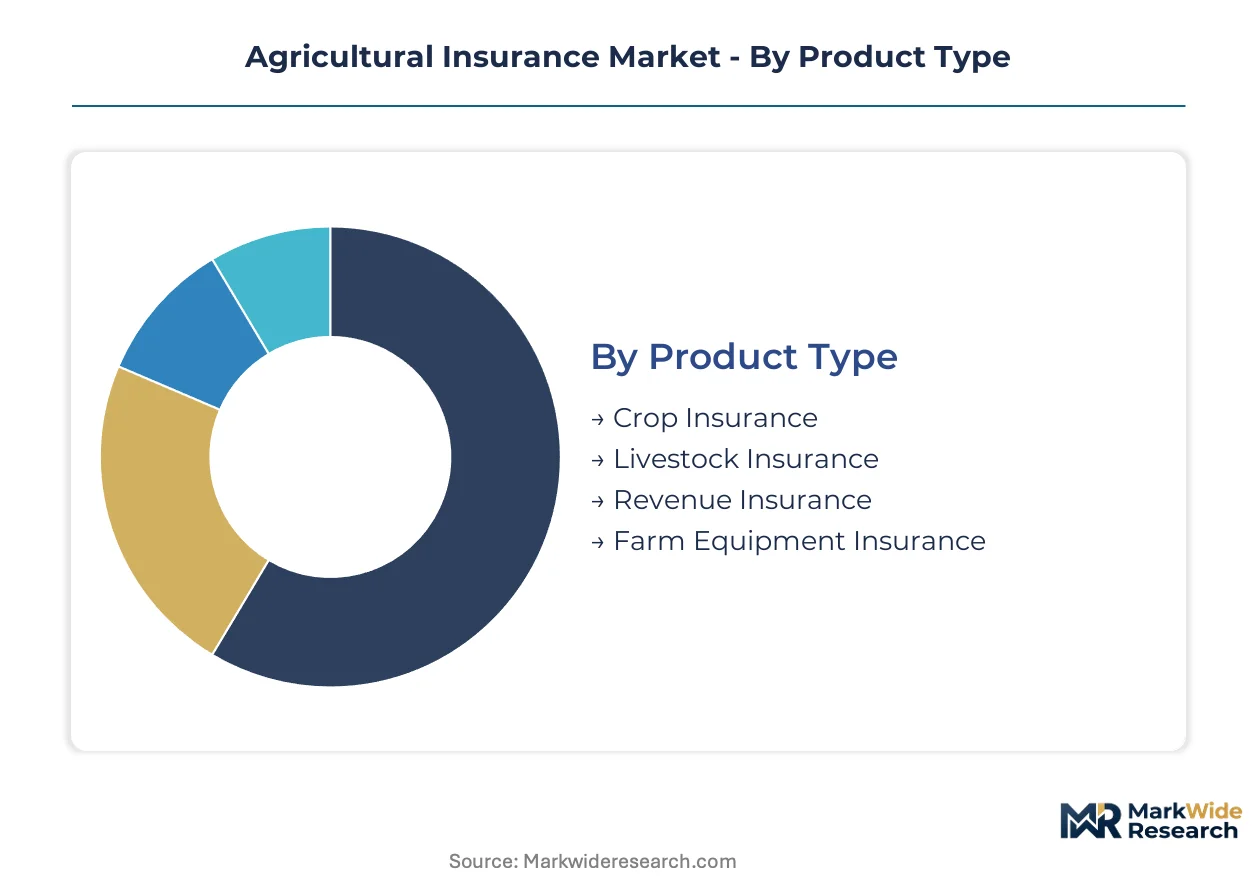
Agricultural insurance segments diverge sharply between mature indemnity products and emerging parametric structures, with each category demanding distinct underwriting capabilities and distribution channels. Understanding these fault lines reveals where capital deployment and technology investment concentrate across the value chain.
Product Type:
Mature indemnity products dominate premium volumes while satellite-triggered alternatives reshape emerging-market penetration.
- Crop Insurance:Traditional indemnity products covering yield shortfalls from named perils including drought, flood, and pest infestation. Demand concentrates in India's PMFBY-subsidized belt and the US Corn Belt where credit requirements mandate coverage; sovereign subsidy obligations constrain margin expansion despite volume scale.
- Revenue Insurance:Bundled price-yield protection integrating commodity futures benchmarks with production guarantees. Adoption accelerates in Brazil's Mato Grosso soybean belt and Iowa corn operations where price volatility now exceeds yield risk; futures market integration enables real-time premium adjustment.
- Livestock Insurance:Mortality and productivity coverage for cattle, poultry, and dairy operations. Verification costs limit penetration outside OECD markets with functional animal identification systems.
- Farm Equipment Insurance:Physical damage and business interruption coverage for mechanized planting and harvesting assets. Premium pools concentrate in capital-intensive Australian wheat operations and Ukrainian grain exporters.
Crop insurance retains volume leadership; revenue insurance holds the steepest expansion curve.
Coverage Type:
Cost tier stratification separates subsidized basic protection from premium-priced comprehensive alternatives.
- Yield Protection:Indemnity triggered when realized yield falls below historical average guarantees. Dominates China's PICC-backed programs in Heilongjiang and Henan provinces where provincial governments absorb catastrophic layer risk.
- Multi-Peril Coverage:Comprehensive protection bundling weather, disease, and market access risks in single contracts. Premium concentration in California specialty crop operations and Florida citrus groves facing compound climate threats; reinsurance capacity constraints elevate pricing.
- Actual Revenue Coverage:Payouts based on realized revenue versus guaranteed benchmarks without yield verification. Gains traction among Kenyan smallholder cooperatives piloting satellite-indexed settlement.
- Whole Farm Revenue Protection:Enterprise-level coverage aggregating multiple commodities and income streams. Appeals to diversified operations in France's mixed-crop-livestock regions and New Zealand dairy-beef combinations.
Yield protection captures the largest premium base; multi-peril coverage commands the highest unit economics.
Policy Type:
Customer type determines whether individual underwriting, group pooling, or algorithmic triggers deliver viable economics.
- Indexed Policy:Parametric contracts triggering automatic payout when satellite-derived NDVI or rainfall indices breach thresholds. Mobile network operators distribute these via USSD in Ethiopia and Nigeria, eliminating agent commissions and compressing distribution cost to sub-dollar per policy.
- Group Policy:Cooperative-level risk pooling enabling village-scale premium aggregation. Kenyan coffee farmer societies and Filipino rice associations leverage collective bargaining for reinsurance access unavailable to individual smallholders.
- Individual Policy:Tailored coverage with field-verified loss adjustment. Persists in developed markets with established agent networks and subsidy-linked compliance requirements.
- Traditional Policy:Named-peril indemnity with documented damage assessment. Retains share in livestock segments where individual animal verification remains feasible.
Indexed policies are expanding most quickly; group policies anchor emerging-market penetration.
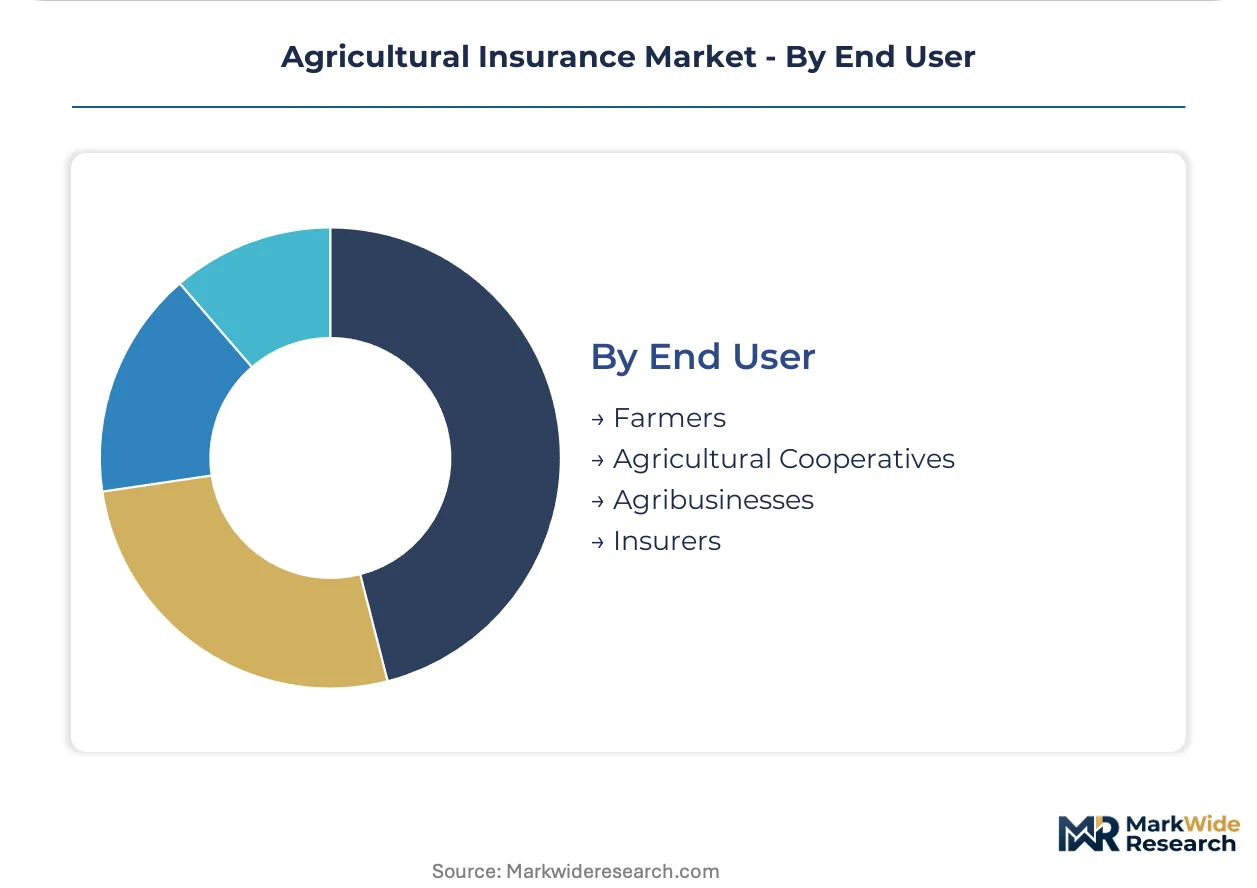
End User:
Volume scale and data sophistication separate fragmented smallholder demand from concentrated agribusiness procurement power.
- Farmers:Individual producers ranging from subsistence smallholders to commercial operators. Sub-Saharan smallholders access coverage through cooperative aggregation; North American row-crop producers drive parametric adoption via precision agriculture data integration.
- Agribusinesses:Vertically integrated operators controlling planting through export. Brazilian soybean conglomerates and Australian wheat exporters negotiate direct reinsurance capacity, disintermediating retail underwriters.
- Agricultural Cooperatives:Member-owned entities pooling risk and purchasing power. German and Dutch cooperatives now mandate minimum coverage levels under EU CSRD supply chain disclosure requirements.
- Insurers:Risk-bearing entities seeking portfolio diversification or reinsurance placement. Captive vehicles proliferate among commodity traders managing counterparty exposure.
Farmers constitute the largest addressable population; agribusinesses concentrate procurement leverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Underwriting capacity concentrates in jurisdictions with sovereign subsidy frameworks and catastrophe modeling infrastructure. Brazil, India, China, the United States, and Germany anchor premium generation through divergent regulatory architectures.
United States
The USDA's Risk Management Agency certifies actuarial rates and administers premium subsidy tiers that sustain the world's largest crop insurance program. Iowa corn operations and California specialty crop regions drive indemnity volume through credit-linked coverage mandates. Private carriers compete alongside the Federal Crop Insurance Corporation in a dual-layer market structure.
Brazil
Proagro subsidizes premiums for smallholder operations while commercial soybean conglomerates in Mato Grosso negotiate direct reinsurance capacity. ANVISA oversees agricultural input regulations that intersect with coverage validation protocols. The Cerrado expansion corridor generates concentrated demand for revenue-based products bundling price and yield protection.
India
The Pradhan Mantri Fasal Bima Yojana redirects sovereign capital toward revenue-based coverage, administered jointly by CEA and Agriculture Insurance Company of India. Punjab and Haryana wheat belts anchor premium volumes under state-mandated enrollment. Mobile distribution platforms now penetrate Maharashtra cotton districts previously excluded from agent networks.
China
PICC Property and Casualty anchors state-backed programs across Heilongjiang and Henan grain provinces, with provincial governments absorbing catastrophic layer risk. SAMR coordinates subsidy frameworks that prioritize food security over commercial margin. The Yangtze River Delta pilot zones test satellite-indexed settlement for rice cooperatives.
Germany
EIOPA's solvency calibration for catastrophe reserves shapes multi-peril coverage pricing across EU member states. Bavarian dairy cooperatives and Lower Saxony arable operations now mandate minimum coverage under CSRD supply chain disclosure requirements. Munich Re's catastrophe modeling infrastructure dominates parametric product design for emerging market export.
Agricultural Insurance Market Vendor Landscape
Global reinsurance groups and state-backed national carriers split the market between cross-border capacity deployment and domestic subsidy capture. The vendor base concentrates around catastrophe modeling infrastructure and sovereign program administration. Three archetypes dominate: European reinsurance conglomerates with parametric design capabilities, Asian state-owned insurers anchoring provincial subsidy schemes, and North American multi-line carriers with federal program integration. Competitive positioning hinges on satellite data partnerships and direct-to-farmer digital distribution buildouts.
Within the reinsurance tier, Munich Re Group and Zurich Insurance Group exemplify the catastrophe modeling archetype, leveraging meteorological infrastructure to design index-triggered products. PICC Property and Casualty Company Limited occupies a position within the state-backed tier, anchoring provincial programs through sovereign risk absorption. QBE Insurance Group and Chubb Ltd. represent the multi-line international carrier segment, competing through agricultural specialty divisions integrated with broader commercial portfolios.
| Leading Market Players |
|---|
| QBE Insurance Group |
| Chubb Ltd. |
| Sompo Holdings |
| Zurich Insurance Group |
| Allianz SE |
| Munich Re Group |
| AXA |
| Agriculture Insurance Company of India |
| PICC Property and Casualty Company Limited |
| Others |
Supply Flow & Price Mechanics
Sovereign fiscal constraints on premium subsidies in Brazil and India determine both the spread between subsidized and commercial pricing tiers and the geographic concentration of underwriting capacity around state-backed program administration.
Pricing Analysis
The Pradhan Mantri Fasal Bima Yojana dictates the pricing tier structure across emerging-market agricultural insurance, separating sovereign-subsidized yield coverage from commercial revenue products. Premium-mid-economy pricing differentiation rests on subsidy eligibility tiers and actuarial rate certification by national regulators. Cost compression in the commercial tier is intensifying because agribusiness buyers negotiate direct reinsurance capacity, bypassing retail margin layers. Smallholder cooperatives exhibit highest price sensitivity, while Brazilian soybean conglomerates and Australian wheat exporters demonstrate inelastic demand for bundled price-yield protection.
Supply Chain Analysis
Export-control regimes on satellite remote sensing technology limit parametric product design capacity flows between European reinsurance hubs and emerging-market distribution points. Underwriting capacity concentrates in Germany, India, and the United States, drawing from catastrophe modeling infrastructure, actuarial talent pools, and regulatory certification systems. Raw material dependencies include meteorological data feeds, NDVI satellite imagery, and mobile network operator distribution rails. Single-source vulnerability sits with concentrated reinsurance capacity at Munich Re and Zurich Insurance Group. Distribution runs through state-backed program administrators, agricultural cooperatives, and increasingly through USSD-enabled mobile platforms in East Africa.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Parametric index insurance represents a high-growth disruption, with satellite-triggered settlement collapsing traditional loss-adjustment economics and opening addressable populations previously excluded by verification costs.
For Market Incumbents: Pre-empt disintermediation by agribusiness direct-reinsurance negotiations through captive capacity vehicles or insurance-linked securities structures. Deepen backward integration into satellite data partnerships and climate analytics platforms to defend pricing power against algorithmic entrants. Prioritize certification investment for EIOPA solvency calibration and USDA actuarial rate standards to maintain program administration eligibility.
For New Entrants and Emerging Players: Pursue livestock insurance gaps in Brazil and Argentina where individual animal verification costs have suppressed penetration, leveraging emerging biometric identification technologies. Target sub-Saharan cooperative aggregation models in Kenya and Ethiopia as the most penetrable distribution architecture, bypassing traditional agent networks entirely through mobile network operator partnerships.
For Investors and Strategic Acquirers: The EU CSRD sustainability disclosure requirements reshape the acquisition landscape by converting voluntary agricultural coverage into procurement preconditions across European food supply chains. Long-term viability favors targets with parametric design capabilities and direct-to-farmer digital distribution infrastructure. Watch for sovereign fiscal consolidation announcements in India and Brazil as inflection indicators for subsidy-dependent premium volumes.
| Strategic Initiative | Industry Significance |
|---|---|
| Satellite Data Partnership | Munich Re's meteorological infrastructure enables index-triggered product design across emerging markets. |
| Mobile Distribution Platform | USSD interfaces in Ethiopia and Nigeria compress distribution cost to sub-dollar per policy. |
| Captive Insurance Vehicle | Brazilian soybean conglomerates capture risk margin previously accruing to retail underwriters. |
| Carbon Credit Bundling | Regenerative agriculture protocols create dual-revenue streams through soil carbon verification overlap. |
| Provincial Program Expansion | PICC's Heilongjiang and Henan templates demonstrate scalable penetration of underinsured interior grain belts. |
Methodological Framework
Cross-validation between reinsurance capacity disclosures and sovereign program administration records anchors the qualitative findings in this agricultural insurance analysis. Primary interviews with crop underwriters, agricultural cooperative managers, satellite data platform engineers, and national regulator program officers combined with secondary validation from USDA Risk Management Agency filings, EIOPA solvency calibration reports, and India's CEA enrollment statistics. Bottom-up premium pool modeling and top-down catastrophe capacity assessments triangulate volume estimates.
Calibration across product type, coverage tier, policy structure, and end-user segmentation dimensions shapes the analytical framework over the projection horizon. CAGRs derive from actuarial rate trajectories and subsidy obligation forecasts. Modeled inputs include NDVI satellite coverage expansion, mobile network operator distribution penetration curves, and sovereign fiscal consolidation scenarios.
Sensitivities concentrate around subsidy obligation reductions, parametric basis risk events, and climate model recalibration cycles. Forecasts reflect documented assumptions on satellite data cost trajectories and cooperative aggregation economics. Material shifts in sovereign premium support levels or export-control regimes on remote sensing technology would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Family Floater Health Insurance Market
Insurance
Asia-Pacific Group Health Insurance Market
Insurance
Global SME Insurance Market
Insurance
Travel Insurance Market
Insurance
Credit Insurance Market
Insurance
India Property & Casualty Insurance Market
Insurance
United States Bancassurance Market
Insurance
Europe Embedded Insurance Market
Insurance
China Liability Insurance Market
Insurance
North America Liability Insurance Market
Insurance
Europe Road Assistance Insurance Market
Insurance
Asia-Pacific Insurance Aggregators Market
Insurance
Usage-Based Insurance for Automotive Market
Insurance
Financial Guarantee Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
Japan Property and Casualty Insurance Market