
 Ethylhexyl Palmitate Market | 2026-2036
Ethylhexyl Palmitate Market Size, Share, and Industry Trends Forecast 2026-2036
Ethylhexyl Palmitate Market Foresight
Prestige skincare brands are gaining share over mass-market labels, and this shift is reorganizing volume commitments across the ethylhexyl palmitate supply base. KLK OLEO leverages integrated oleochemical feedstocks from Southeast Asian palm oil operations to secure cost-advantaged supply. BASF SE anchors its position through specialty ester R&D facilities in Germany that serve European cosmetic houses. Croda International Plc differentiates via biotechnology-derived alternatives that complement conventional synthetic routes.
Ethylhexyl palmitate is a branched-chain fatty acid ester synthesized from 2-ethylhexanol and palmitic acid, exhibiting a dry, silky skinfeel with a viscosity range of 7-12 cSt at 25°C and a refractive index near 1.440; cosmetic chemists deploy it as a primary emollient and solvent to improve spreadability and reduce greasiness in leave-on formulations. The emollient category within product type segmentation commands the largest volume share due to its ubiquity in facial moisturizers and body lotions, while skin conditioning agents represent the fastest-growing segment as multifunctional claims gain regulatory traction. Among applications, cosmetics outpaces personal care in absolute tonnage though pharmaceutical-grade specifications are tightening and capturing margin pools through USP-grade certification requirements.
The US FDA governs cosmetic ingredient safety through the Federal Food, Drug, and Cosmetic Act, while the EPA monitors manufacturing effluent under Clean Water Act provisions for oleochemical processors; in Europe, REACH registration dossiers for ethylhexyl palmitate determine market access thresholds based on tonnage band toxicological data. China's SAMR enforces GB standards for cosmetic raw material purity that now reference heavy metal limits stricter than prior editions. Stakeholders must monitor evolving biobased content certification schemes and regional palm oil sustainability mandates that threaten to fragment feedstock sourcing strategies.
Market Dynamics
Clean beauty certification mandates are restructuring procurement priorities for cosmetic-grade esters, forcing formulators to document feedstock provenance and biobased content through mass-balance chain-of-custody systems.
Growth Catalysts
- REACH registration dossiers:European chemical safety requirements under ECHA are screening out non-compliant suppliers and consolidating volume among certified producers.
- Color cosmetics formulators:Premium makeup brands in China are expanding ester procurement for long-wear foundations and transfer-resistant lip products.
- Palm oil sustainability certification:RSPO and ISCC schemes are creating preferential sourcing channels for segregated supply chains.
Market Restraints
- Crude palm oil price volatility:Malaysian and Indonesian feedstock costs swing with El Niño weather patterns and export duty adjustments.
- Specialty ester production concentration:German and Dutch oleochemical complexes control pharmaceutical-grade capacity, creating single-source vulnerability.
- Silicone emollient substitution:Dimethicone and cyclopentasiloxane alternatives threaten volume in mass-market hair care applications.
Strategic Opportunities
- India personal care expansion:Domestic ayurvedic-cosmetic hybrids are creating demand for natural-origin emollients with documented traceability.
- Sun care SPF boosters:Photostabilizer formulations require non-polar solvents that enhance UV filter compatibility and skin adhesion.
- EU Green Deal biobased mandates:Corporate sustainability reporting obligations under CSRD are accelerating verified renewable content procurement.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation science programs lack graduates trained in ester chemistry and emulsion stabilization.
- USP-grade certification timelines:FDA drug master file preparation stretches 18-24 months for pharmaceutical excipient qualification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ethylhexyl Palmitate Market |
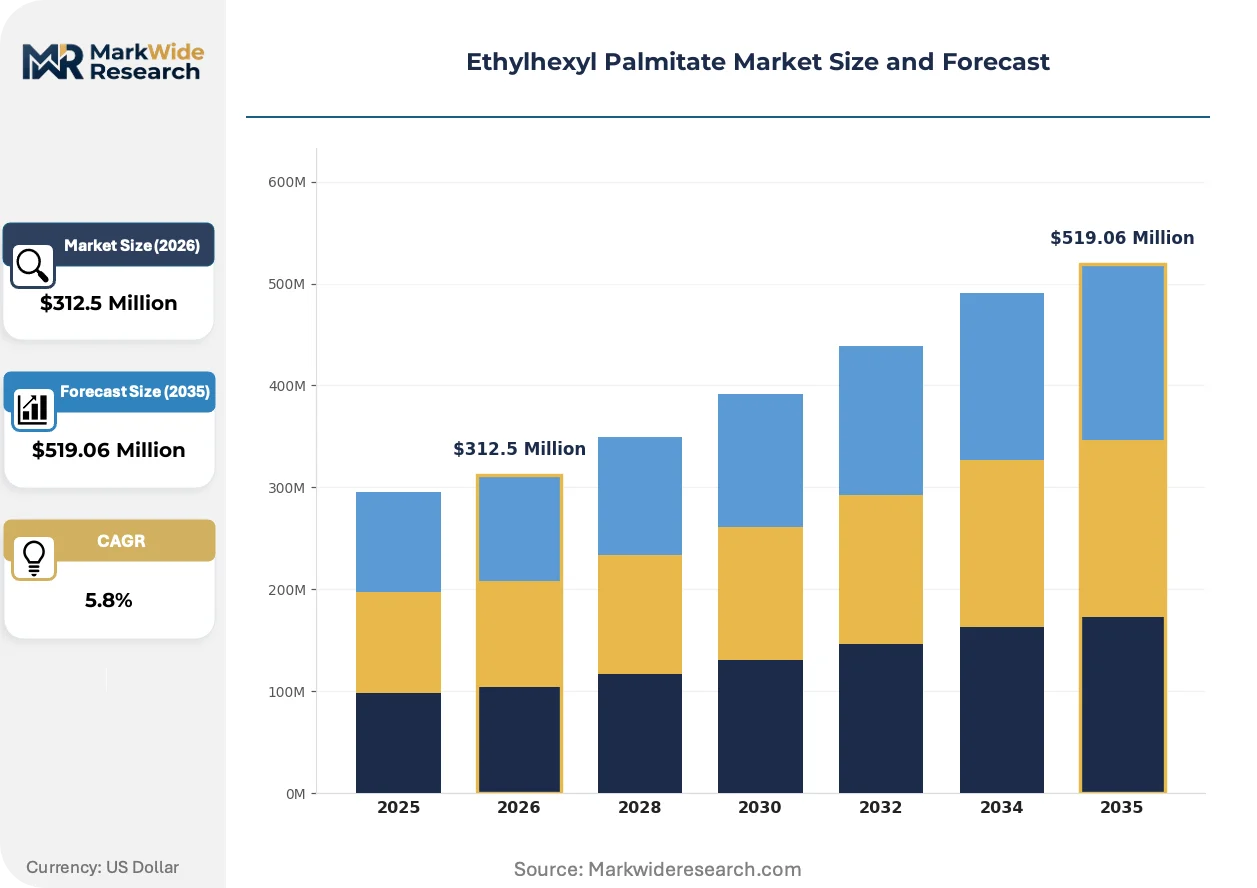
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emollients, Solvents, Skin Conditioning Agents, Thickeners Application: Cosmetics, Personal Care, Pharmaceuticals, Industrial Formulation: Lotion, Cream, Gel, Ointment End User: Manufacturers, Retailers, Distributors, Wholesalers |
| Companies Covered | Stearinerie Dubois SAS, KLK OLEO, BASF SE, Alzo International, Lubrizol Corporation, Croda International Plc, Vantage Specialty Ingredients, Inc., Esters and Solvents LLP, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ethylhexyl Palmitate Market Shifts & Advancements
Biotechnology-derived ester platforms are compressing the innovation cycle for cosmetic ingredients, enabling fermentation-based alternatives to compete with traditional oleochemical routes on performance metrics.
Enzymatic esterification using immobilized lipase catalysts is miniaturizing batch reactor footprints and cutting solvent waste in specialty ester manufacturing. Korean and Japanese cosmetic manufacturers are piloting these biocatalytic routes for high-purity emollients. The technology is compressing capital requirements for mid-scale producers entering the cosmetic-grade segment.
China's GB standards for cosmetic raw materials are tightening heavy metal and residual solvent specifications beyond prior editions. SAMR enforcement is disqualifying legacy suppliers lacking analytical capabilities. European exporters to China are restructuring quality systems to meet these documentary requirements.
Direct-to-brand supply contracts are displacing distributor intermediaries in the North American and European specialty ester trade. Indie beauty brands with clean beauty positioning are negotiating directly with Malaysian and Indonesian oleochemical producers. This channel shift is most pronounced in California and New York cosmetic clusters where transparency claims command price premiums.
Ethylhexyl Palmitate Market Segmentation
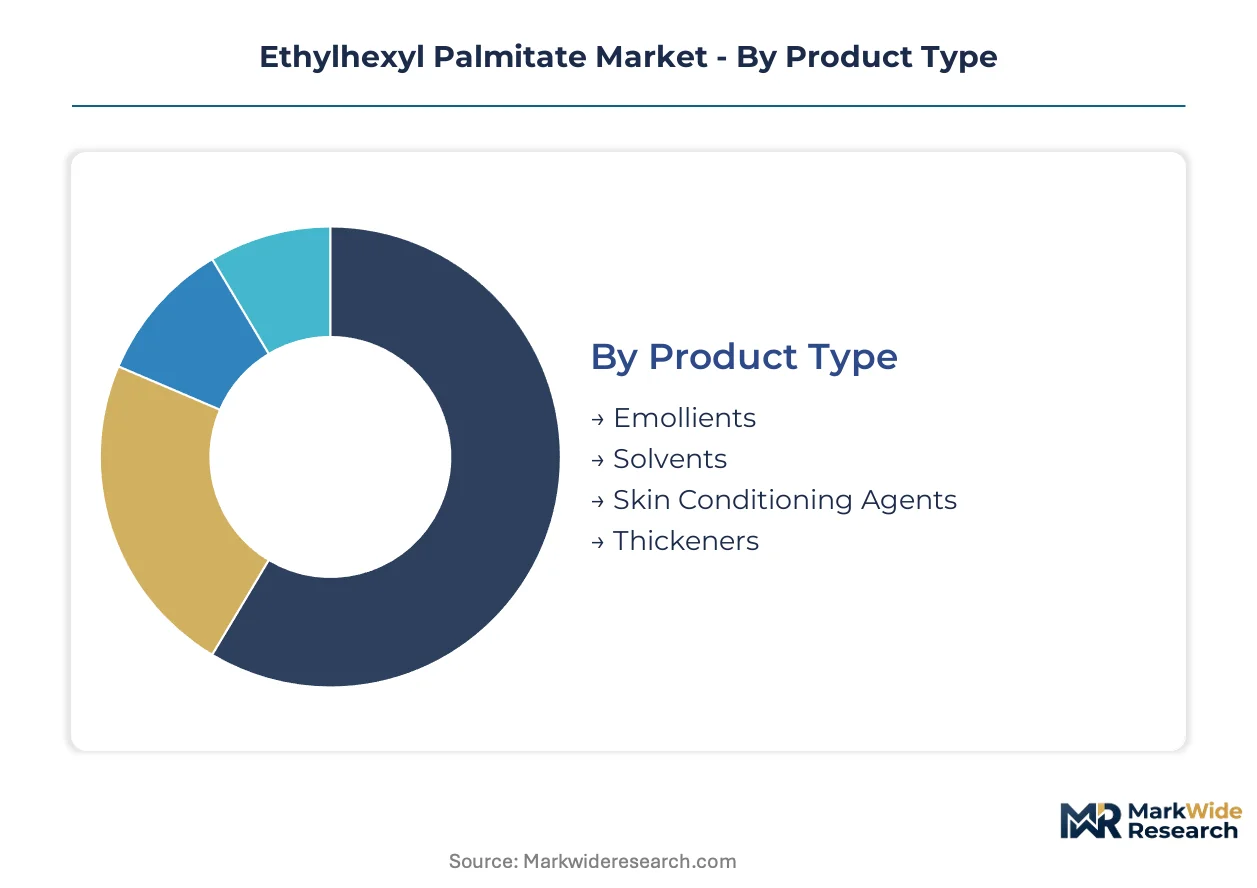
Segmentation in the ethylhexyl palmitate market exposes how procurement patterns split between domestic personal care brands and export-oriented pharmaceutical manufacturers. Understanding these divides clarifies where purity premiums concentrate and which channels absorb volume at scale.
Product Type:
Domestic skincare brands in China and India drive emollient procurement through local compounders, while European pharmaceutical buyers import solvent-grade material through specialized distributors.
- Emollients:This branched-chain fatty acid ester delivers a dry, silky skinfeel with viscosity ranging 7-12 cSt at 25°C. Facial moisturizers and body lotions in China's premium skincare lines absorb the largest volumes, though REACH compliance costs are filtering out smaller compounders.
- Solvents:Non-polar characteristics enhance UV filter compatibility in sun care formulations. Photostabilizer demand from Korean and Japanese manufacturers is climbing fastest as SPF booster formulations proliferate.
- Skin Conditioning Agents:Multifunctional claims are gaining regulatory traction under tightening clean beauty standards. SAMR's GB standards now enforce stricter heavy metal limits than prior editions.
- Thickeners:Viscosity modification in anhydrous color cosmetics. Transfer-resistant lip products from premium makeup brands in China are expanding procurement.
Emollients hold the largest share; momentum sits with skin conditioning agents.
Application:
Cost tiers separate pharmaceutical-grade specifications commanding purity premiums from mass-market personal care absorbing standard cosmetic grades.
- Cosmetics:Color cosmetics formulators deploy this ester to improve spreadability and reduce greasiness in leave-on foundations. Long-wear formulations from Chinese prestige brands are reorganizing volume commitments across the supply base.
- Personal Care:Hair care applications face substitution pressure from dimethicone alternatives. Mass-market conditioners are shifting silicone-heavy, though indie beauty brands in California and New York maintain ester preference for transparency claims.
- Pharmaceuticals:USP-grade certification requires 18-24 month FDA drug master file timelines. German and Dutch oleochemical complexes control this capacity, creating single-source vulnerability for excipient buyers.
- Industrial:Lubricant and coating applications outside cosmetic scope. Malaysian palm oil sustainability certification is fragmenting feedstock sourcing for non-cosmetic uses.
Cosmetics dominates absolute tonnage; pharmaceuticals captures the steepest margin expansion trajectory.
Formulation:
Volume concentration follows emulsion stability requirements, with higher-complexity formats demanding certified emollient grades.
- Lotion:Fluid emulsions for body and facial applications. Domestic personal care expansion in India is driving demand for natural-origin emollients with documented traceability.
- Cream:Higher viscosity leave-on products requiring enhanced skinfeel modulation. European cosmetic houses source through BASF's specialty ester R&D facilities in Germany.
- Gel:Anhydrous and hydroalcoholic systems. Korean manufacturers are piloting enzymatic esterification routes for high-purity gel bases.
- Ointment:Occlusive pharmaceutical preparations. USP-grade specifications are tightening and capturing margin pools through certification requirements.
Lotion absorbs the greatest volume; gel formats are expanding most quickly on biocatalytic innovation.
End User:
Customer type determines channel structure, with direct-to-brand contracts displacing traditional distribution in clean beauty segments.
- Manufacturers:Compounders and finished goods producers. KLK OLEO leverages integrated Southeast Asian palm oil operations to secure cost-advantaged supply for this tier.
- Retailers:Private label and store-brand skincare lines. Clean beauty certification mandates are restructuring procurement priorities through mass-balance chain-of-custody systems.
- Distributors:Traditional intermediaries facing compression. Direct negotiations between indie beauty brands and Malaysian oleochemical producers are most pronounced in North American cosmetic clusters.
- Wholesalers:Bulk material traders serving mid-scale formulators. Croda International's biotechnology-derived alternatives are creating parallel sourcing channels through this tier.
Manufacturers command the largest share; retailers are gaining share fastest on private label clean beauty expansion.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian oleochemical exporters ship ethylhexyl palmitate to Chinese cosmetic compounders and European pharmaceutical buyers. This trade corridor channels Southeast Asian palm oil derivatives into premium skincare manufacturing clusters.
China
Domestic personal care brands in Shanghai and Guangzhou scale premium skincare lines requiring high-performance emollients. SAMR enforces GB standards with heavy metal limits stricter than prior editions. The Yangtze River Delta absorbs the largest import volumes for facial moisturizer production.
Germany
Specialty ester R&D facilities serve European cosmetic houses demanding REACH-compliant cosmetic-grade esters. ECHA registration dossiers screen out non-compliant suppliers. The Rhine-Ruhr industrial corridor concentrates pharmaceutical-grade capacity for excipient buyers.
United States
Indie beauty brands in California and New York negotiate direct supply contracts for transparency claims. FDA governs cosmetic ingredient safety through the Federal Food, Drug, and Cosmetic Act. The Los Angeles-Long Beach port complex handles Southeast Asian oleochemical imports.
India
Ayurvedic-cosmetic hybrids in Mumbai and Ahmedabad create demand for natural-origin emollients with documented traceability. BIS standards and CDSCO pharmaceutical regulations shape import specifications. The Gujarat chemical belt hosts domestic esterification capacity expansion.
Japan
Korean and Japanese cosmetic manufacturers pilot enzymatic esterification routes for high-purity gel bases. METI oversees chemical manufacturing standards and biobased content certification. The Kansai region around Osaka anchors specialty ester formulation expertise.
Ethylhexyl Palmitate Market Competitive Landscape
Player mix skews toward integrated oleochemical producers and specialty ester specialists. The vendor base concentrates among Southeast Asian palm oil processors and European chemical conglomerates with dedicated cosmetic ingredient divisions. Three archetypes dominate: backward-integrated feedstock owners, biotechnology-enabled alternative suppliers, and pharmaceutical-grade certification holders. Competitive moves center on mass-balance chain-of-custody systems and enzymatic manufacturing partnerships.
Among European chemical conglomerates, BASF SE and Evonik Industries AG exemplify the specialty ester archetype through dedicated cosmetic ingredient divisions. KLK OLEO represents the backward-integrated model with captive Southeast Asian palm oil operations. Croda International Plc occupies a position in biotechnology-derived alternatives that complement conventional synthetic routes.
| Leading Market Players |
|---|
| Stearinerie Dubois SAS |
| KLK OLEO |
| BASF SE |
| Alzo International |
| Lubrizol Corporation |
| Croda International Plc |
| Vantage Specialty Ingredients, Inc. |
| Esters and Solvents LLP |
| Evonik Industries AG |
| Others |
Supply & Pricing Matrix
REACH registration dossiers under ECHA simultaneously gate supply qualification and stratify price tiers, forcing non-compliant compounders out of European procurement channels while allowing certified producers to command purity premiums for cosmetic-grade esters.
Pricing Analysis
Current-generation enzymatic esterification routes command price premiums over conventional acid-catalyzed processes, while legacy solvent-based methods face margin compression from waste-disposal cost escalation. Three-tier pricing structure across premium, standard, and economy levels separates USP-certified pharmaceutical grades from REACH-compliant cosmetic grades and industrial lubricant specifications. Pricing pressure stems from silicone emollient substitution in mass-market hair care, where dimethicone alternatives undercut ester bids. Mass-market personal care buyers exhibit highest price sensitivity; prestige skincare brands absorb certification-driven premiums with minimal volume elasticity.
Supply Chain Analysis
Port congestion at the Los Angeles-Long Beach complex and container availability constraints on Southeast Asia-North America trade lanes are extending lead times for Malaysian oleochemical shipments. Production concentrates in Malaysia, Indonesia, and Germany, with German and Dutch complexes controlling pharmaceutical-grade capacity. Feedstock draws from crude palm oil, 2-ethylhexanol, and immobilized lipase catalysts. Single-source vulnerability threatens excipient buyers dependent on Rhine-Ruhr pharmaceutical-grade output. Distribution runs through direct-to-brand contracts displacing traditional distributor intermediaries in North American and European specialty ester trade.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ethylhexyl palmitate market is recovering from cyclical trough conditions as El Niño-driven palm oil price volatility moderates and cosmetic formulators restock premium emollient inventories.
For Market Incumbents: Secure backward integration into Southeast Asian palm oil operations to insulate margin structures from feedstock price swings. Invest in enzymatic esterification capacity to defend against biotechnology-enabled alternative suppliers threatening conventional synthetic routes. Prioritize USP-grade certification timelines to capture pharmaceutical excipient margin pools before German and Dutch complexes expand capacity. For New Entrants and Emerging Players: Lead with fermentation-based ester platforms targeting the skin conditioning agent segment where multifunctional claims command regulatory traction and pricing power. India's ayurvedic-cosmetic hybrid market offers the most penetrable geography, with domestic brands scaling premium skincare lines requiring documented traceability. Pursue direct supply contracts with California and New York indie beauty clusters where transparency claims justify price premiums over distributor channels. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across enzymatic manufacturing sub-segments as immobilized lipase catalysts compress batch reactor footprints. Long-term viability favors acquisition targets with mass-balance chain-of-custody certification and established relationships with Chinese cosmetic compounders. Monitor RSPO and ISCC palm oil sustainability certification uptake as the inflection indicator for feedstock sourcing competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Palm Oil | KLK OLEO's captive Southeast Asian feedstock operations demonstrate cost-advantaged supply security. |
| Enzymatic Esterification Scale-Up | Korean and Japanese manufacturers piloting biocatalytic routes compress capital requirements for mid-scale entry. |
| USP-Grade Certification Investment | German and Dutch oleochemical complexes control pharmaceutical-grade capacity with 18-24 month FDA qualification timelines. |
| Direct-to-Brand Channel Development | Indie beauty brands in California and New York cosmetic clusters negotiate transparency-premium contracts with Malaysian producers. |
| Biotechnology-Derived Alternative R&D | Croda International's fermentation-based platforms create parallel sourcing channels complementing conventional synthetic routes. |
Research Methodology
Desk research of customs trade data, SEC filings from oleochemical processors, and REACH registration dossiers preceded structured interviews with cosmetic formulation chemists, procurement leads at personal care manufacturers, technical R&D directors at specialty ester producers, and distribution channel partners across North American and European markets. Primary fieldwork combined with secondary validation from BIS standards documentation, SAMR GB standard revisions, and ECHA toxicological data submissions. Bottom-up volume estimates from end-use application modeling were triangulated against top-down value projections from trade flow analysis.
Variance decomposition across product type, application, formulation complexity, and end-user channel dimensions structured the analytical framework over the projection horizon. CAGRs were derived from segmented growth rate modeling incorporating feedstock price elasticity, regulatory compliance cost pass-through, and substitution threat intensity from silicone emollients. Forecast inputs included palm oil futures curve dynamics, clean beauty certification penetration rates, and pharmaceutical-grade capacity expansion announcements from German and Dutch chemical complexes.
The analysis sits within stated boundaries; outcomes outside sustained REACH enforcement, stable El Niño patterns, and continued prestige skincare brand expansion would require recalibration. Forecasts reflect assumptions regarding biobased content certification scheme adoption and regional palm oil sustainability mandate implementation. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Global Creosote Oil Market
Oleochemicals
Iso-Octene Market
Oleochemicals
Sodium Lauroyl Isethionate Market
Oleochemicals
Allyl Caproate Market
Oleochemicals
Global Wax Market
Oleochemicals
Global White Oil Market
Oleochemicals
Disodium Oleamido MIPA Sulfosuccinate Market
Oleochemicals
Butyl Stearate Market
Oleochemicals
Asia-Pacific Oleochemicals Market
Oleochemicals
Ozokerite Wax Market
Oleochemicals
Mexico Glycerine Market
Oleochemicals
Oxo-Octyl Acetate Market
Oleochemicals
Ethylhexyl Pelargonate Market
Oleochemicals
Glycerine Market
Oleochemicals
Carbolic Oil Market
Oleochemicals
Stearyl Tartrate Market