
 Global Tetrahexyldecyl Ascorbate Market | 2026-2036
Global Tetrahexyldecyl Ascorbate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tetrahexyldecyl Ascorbate Market Analytics
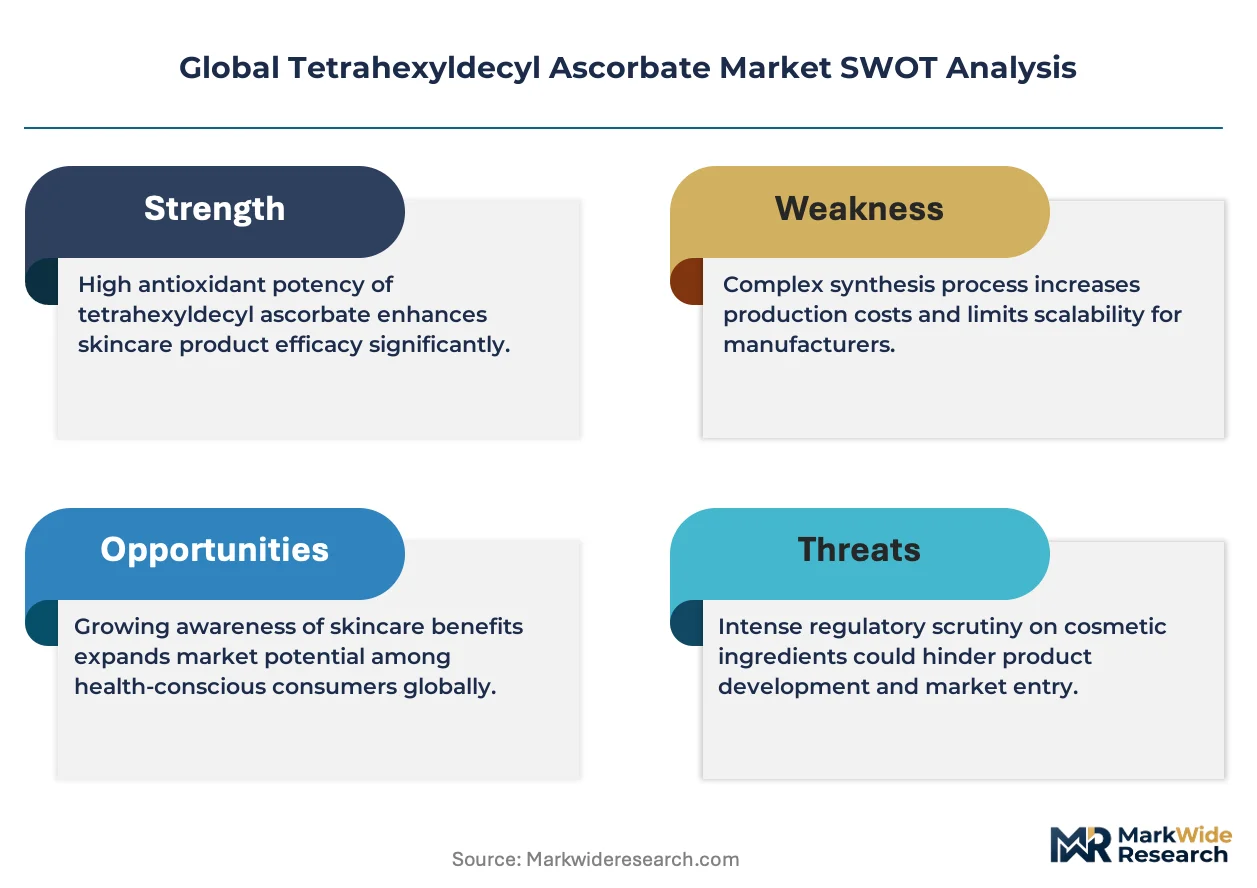
REACH is repositioning the cost-of-entry calculus for tetrahexyldecyl ascorbate suppliers entering European cosmetics supply chains. BASF leverages its integrated vitamin chemistry platform to sustain formulation-grade output across multiple continents. Syensqo anchors its position through lipid-derivative expertise that dominates high-purity ester production. Lubrizol differentiates via specialty chemical infrastructure originally built for personal care oleochemistry.
Tetrahexyldecyl ascorbate is a fat-soluble ester of L-ascorbic acid and isopalmitic acid, typically formulated at concentrations between 1% and 10% in topical preparations to deliver antioxidant activity without the instability of water-soluble vitamin C. Its primary commercial purpose centers on cosmetic formulations seeking collagen synthesis stimulation and melanin inhibition with reduced oxidative degradation. Serums command the premium margin pool due to concentrated actives positioning and dermatologist-channel pricing power. Skincare applications lead volume absorption while haircare represents the fastest-expanding addressable category as scalp health positioning gains traction. Online retail channels are displacing specialty stores for ingredient-aware consumer segments seeking direct-to-brand purchasing.
The EU Green Deal and REACH frameworks constrain petrochemical feedstock pathways while FDA cosmetic ingredient oversight under modernized authority raises documentation burdens for US market access. EMA-aligned cosmetic safety standards in Europe and evolving BIS purity benchmarks in India collectively filter supplier eligibility across major demand centers. Stakeholders must monitor regulatory divergence between jurisdictions to anticipate reformulation costs and qualification timelines.
Market Dynamics
REACH compliance costs are restructuring supplier economics across European cosmetics supply chains, forcing mid-tier producers to consolidate or exit while integrated chemical platforms capture formulation-grade volume.
Growth Catalysts
- K-beauty manufacturing concentration:South Korea's cosmetic ingredient cluster drives sustained procurement of high-purity esters for export-oriented serum production.
- EU Green Deal feedstock rules:Bio-based isopalmitic acid pathways gain preferential access to European formulators seeking regulatory alignment.
- Scalp health positioning:Haircare brands are incorporating tetrahexyldecyl ascorbate into pre-shampoo treatments targeting follicle oxidative stress.
Market Restraints
- Isopalmitic acid cost volatility:Palm oil derivative pricing fluctuations compress margins for non-integrated ester producers.
- East Asian supply concentration:Overreliance on South Korean and Chinese intermediate manufacturers creates single-source vulnerability.
- L-ascorbic acid instability:Precursor degradation during esterification limits batch yield consistency below pharmaceutical-grade standards.
Strategic Opportunities
- Indian BIS purity benchmarks:Early alignment with evolving national standards positions suppliers for domestic cosmetics manufacturing growth.
- Direct-to-brand e-commerce:Ingredient-aware consumers bypass specialty retailers for manufacturer-direct serum purchases.
- Encapsulation technology convergence:Liposome and niosome delivery systems enhance tetrahexyldecyl ascorbate bioavailability claims.
Industry Challenges
- Esterification process engineering talent:Shortage of lipid-chemistry specialists delays scale-up from pilot to commercial production.
- REACH registration timelines:Extended ECHA dossier preparation cycles block market entry for new supplier entrants.
- Legacy water-soluble vitamin C inventory:Formulator reluctance to reformulate stable product lines slows active ingredient switching.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tetrahexyldecyl Ascorbate Market |
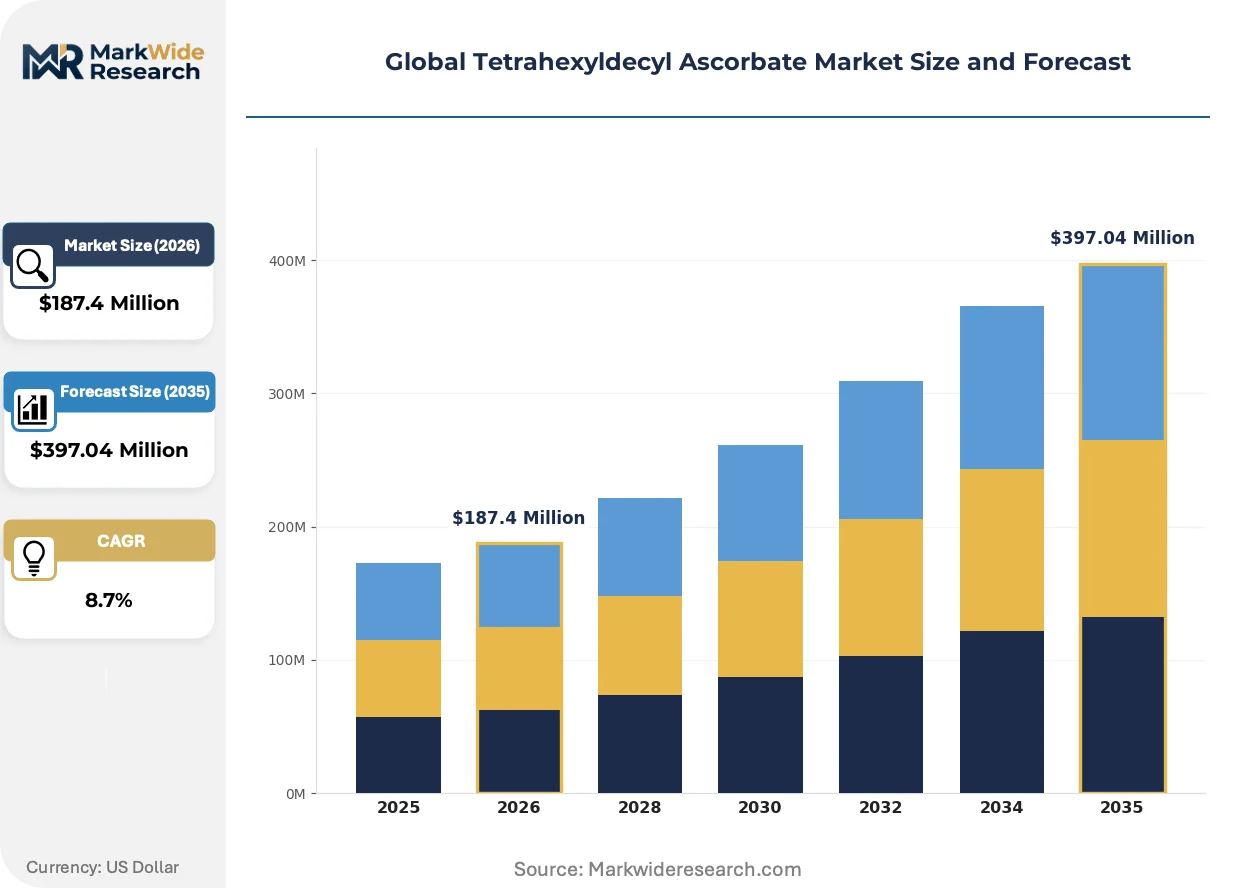
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Serums, Oils, Creams, Lotions Application: Skincare, Haircare, Cosmetics, Supplements Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies End User: Consumers, Dermatologists, Retailers, Manufacturers |
| Companies Covered | BASF, Syensqo, Medik8, Lubrizol, Ashland, Shay and Company, DSM, Kao Corporation, KRI Skin, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tetrahexyldecyl Ascorbate Market Evolving Landscape
Biotechnology-derived feedstocks and precision encapsulation systems are reshaping how tetrahexyldecyl ascorbate reaches end-formulators, with regulatory compliance now inseparable from technical performance claims.
Microfluidic encapsulation technology is expanding into high-end cosmetic manufacturing, enabling uniform particle-size distribution for enhanced skin-penetration marketing. Prestige skincare houses in France and Japan are adopting these systems for limited-edition launches. The technology is expanding into mid-market serums as equipment costs decline and contract manufacturers build captive capabilities.
REACH Annex XVII restrictions on petrochemical-derived emollients are tightening formulation flexibility for European cosmetics producers. Suppliers must document renewable carbon content across tetrahexyldecyl ascorbate supply chains to maintain qualified vendor status. German and Dutch formulators are prioritizing bio-based ester certifications in procurement specifications.
Ingredient transparency platforms are displacing traditional distributor relationships for professional-channel skincare brands. Dermatology clinics and medical spas in the United States and Australia now require batch-level certificates of analysis before stocking vitamin C serums. This verification demand concentrates procurement among suppliers with integrated quality documentation systems.
Global Tetrahexyldecyl Ascorbate Market Segmentation
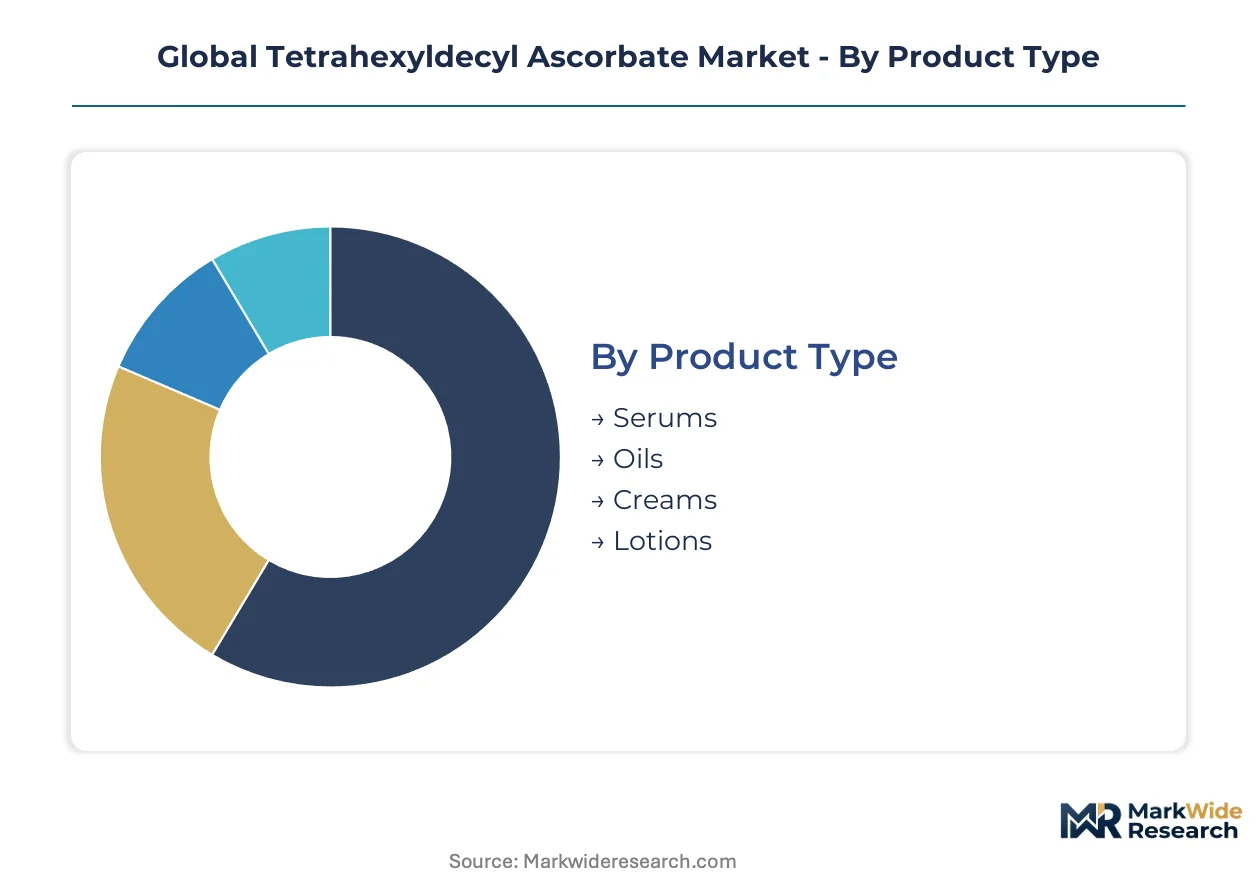
Formulators select tetrahexyldecyl ascorbate grades based on oxidative stability requirements, regional regulatory alignment, and end-product positioning. Segmentation reveals how procurement patterns diverge between mass-market cosmetic manufacturers and clinical-grade skincare houses.
Product Type:
Concentration thresholds and delivery format chemistry separate premium serum producers from mass-market lotion manufacturers.
- Serums:Water-free or minimal-water matrices stabilize the ester at 10-20% concentration for maximum collagen-signaling claims. South Korean contract manufacturers dominate procurement for export-oriented ampoule formats targeting Chinese duty-free channels.
- Oils:Lipid-dissolved formulations leverage the molecule's inherent fat solubility for overnight repair positioning. Indie beauty brands in California and Provence favor this format for clean-beauty marketing compatibility.
- Creams:Emulsion-stabilized variants balance oxidative protection with sensorial elegance. European formulators specify these for day-use products requiring SPF compatibility.
- Lotions:Lower active loading spreads unit economics across volume skincare lines. Mass retailers in India and Brazil drive procurement for entry-price anti-aging ranges.
Serums lead volumes today; oils are gaining share fastest.
Application:
Clinical validation depth and regulatory pathway complexity distinguish dermatological positioning from cosmetic-grade deployment.
- Skincare:Facial anti-aging and brightening formulations absorb the majority of high-purity supply. REACH-compliant documentation requirements filter supplier eligibility for European premium brands.
- Haircare:Scalp antioxidant treatments and follicle health serums represent expanding off-label usage. K-beauty manufacturers in Seoul's Songdo cluster pioneer pre-shampoo concentrate formats.
- Cosmetics:Color-correcting primers and hybrid makeup-skincare products incorporate lower concentrations. Japanese cosmeceutical houses favor this application for multifunctional compact formulations.
- Supplements:Oral delivery systems remain experimental with limited commercial scale. Australian TGA oversight and US FDA GRAS self-determination frameworks create divergent qualification timelines.
Skincare commands the dominant revenue pool; haircare shows the steepest expansion trajectory.
Distribution Channel:
Buyer information access and ingredient literacy levels determine channel-specific formulation specifications.
- Online Retail:Direct-to-consumer brands bypass traditional distribution markups with batch-transparency marketing. Sephora and Cult Beauty platform algorithms prioritize products with documented tetrahexyldecyl ascorbate concentration disclosure.
- Specialty Stores:Sephora, Ulta, and Douglas brick-and-mortar locations stock prestige lines with clinical packaging aesthetics. In-store sampling programs drive trial of stabilized vitamin C derivatives over legacy L-ascorbic acid products.
- Supermarkets:Mass-market skincare aisles in Tesco, Carrefour, and Walmart stock entry-price anti-aging ranges. Private-label penetration pressures branded suppliers on cost-per-gram metrics.
- Pharmacies:French parapharmacies and German Apotheken channels require dermocosmetic positioning with tolerability testing documentation. Vichy, La Roche-Posay, and Eucerin parent companies dominate shelf placement.
Specialty stores retain the largest transaction value; online retail is climbing the fastest.
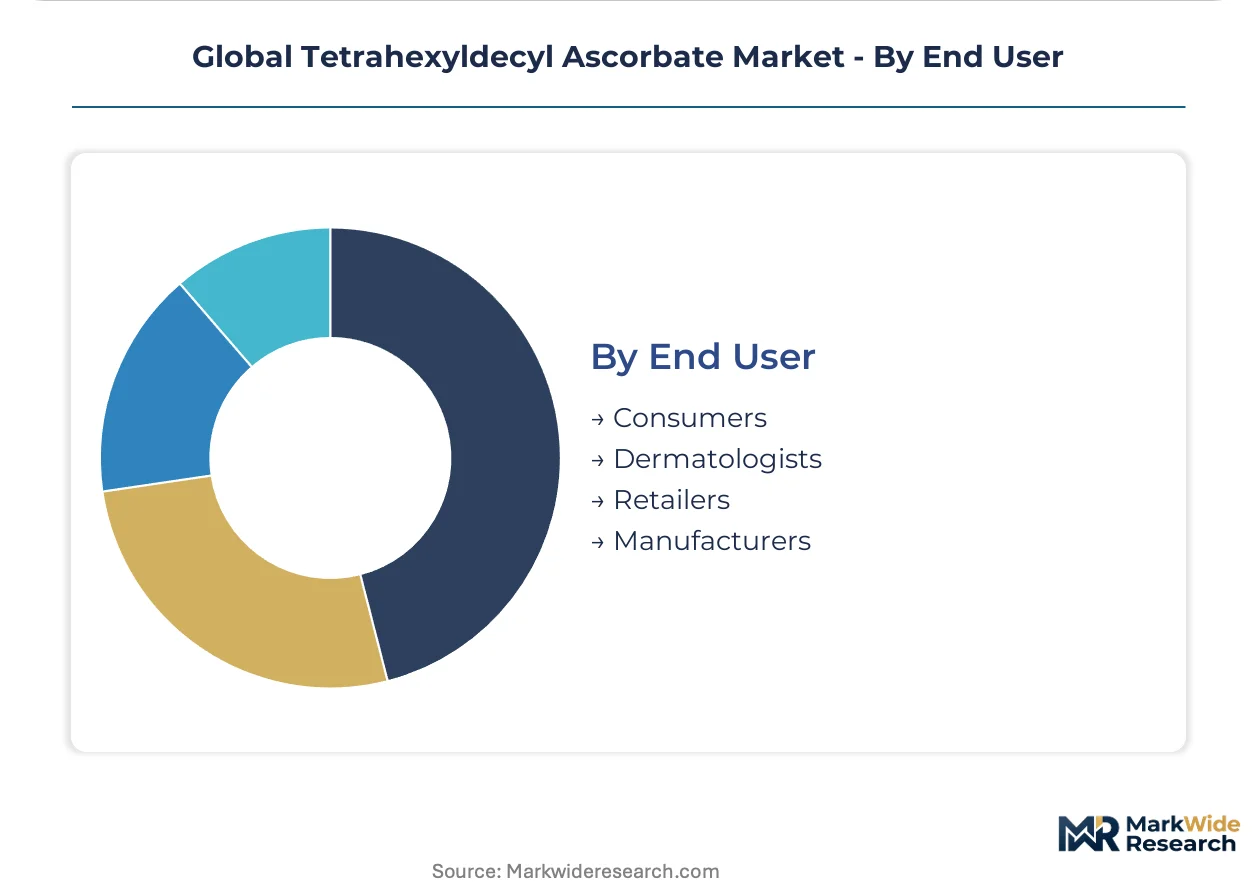
End User:
Technical sophistication and procurement scale separate institutional buyers from individual consumers.
- Consumers:Ingredient-aware purchasers research INCI lists and concentration percentages before purchase. Reddit's r/SkincareAddiction and Korean beauty forums drive awareness of tetrahexyldecyl ascorbate stability advantages.
- Dermatologists:Medical practices and medi-spas specify pharmaceutical-grade esters for in-office procedures and retail resale. US-based dermatology groups increasingly require COA documentation for inventory stocking.
- Retailers:Buyers at beauty specialty chains and department stores negotiate exclusivity windows for new launches. Sephora's Clean Beauty program criteria influence supplier formulation decisions upstream.
- Manufacturers:Contract manufacturers and brand owners purchase bulk active ingredients for captive formulation. South Korea's Incheon and China's Guangzhou cosmetic manufacturing clusters concentrate procurement volume.
Manufacturers absorb the highest ingredient tonnage; dermatologists are expanding procurement most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic chemists and lipid-derivatives specialists concentrate in South Korea's Songdo cluster, Germany's Rhine-Ruhr corridor, and California's Bay Area biotech belt. These talent pools anchor formulation-grade ester production for export-oriented skincare brands.
South Korea
K-beauty contract manufacturers in Seoul's Incheon corridor drive bulk procurement of high-purity tetrahexyldecyl ascorbate for ampoule and serum exports. MFDS cosmetic safety standards enforce batch-level documentation for China-bound duty-free channels. Songdo's biotech cluster hosts dedicated esterification facilities serving Amorepacific and LG Household & Health Care supply chains.
Germany
Rhine-Ruhr chemical complexes leverage century-old oleochemistry expertise for REACH-compliant ester production targeting European dermocosmetic brands. ECHA registration timelines filter supplier eligibility, favoring integrated players with existing dossier infrastructure. BASF's Ludwigshafen platform anchors continental supply for Vichy, La Roche-Posay, and Eucerin parent companies.
United States
FDA cosmetic ingredient oversight under modernized authority raises documentation burdens for tetrahexyldecyl ascorbate importers. California's clean-beauty formulators in Los Angeles and San Francisco Bay Area indie labs specify bio-based isopalmitic acid pathways for sustainability marketing. Sephora's San Francisco headquarters influences upstream supplier certification requirements through Clean Beauty program criteria.
India
Domestic cosmetics manufacturing growth in Maharashtra and Gujarat drives procurement alignment with evolving BIS purity benchmarks. CDSCO and FSSAI frameworks create divergent qualification timelines for topical versus ingestible applications. Mumbai's contract manufacturing cluster concentrates volume absorption for entry-price anti-aging ranges targeting mass retail.
Japan
Prestige skincare houses in Tokyo and Osaka adopt microfluidic encapsulation systems for limited-edition tetrahexyldecyl ascorbate launches. METI industrial standards and PMDA cosmetic safety guidelines enforce tolerability testing documentation for dermocosmetic positioning. Kao Corporation's integrated supply chain anchors domestic procurement for hybrid makeup-skincare multifunctional formats.
Global Tetrahexyldecyl Ascorbate Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across formulation-grade ester supply. The vendor base stratifies into three tiers: integrated chemical platforms with captive vitamin C chemistry, lipid-derivatives houses with esterification expertise, and regional distributors serving contract manufacturers. Strategic moves concentrate on REACH registration completion for European access and bio-based feedstock certification for Green Deal alignment.
Within the integrated chemical platform tier, BASF and DSM exemplify multinational conglomerates leveraging backward integration into vitamin C precursor supply. Syensqo and Lubrizol occupy positions as specialty chemical operators with heritage oleochemistry infrastructure. Shay and Company represents the focused pure-play archetype, anchoring regional supply relationships without diversified portfolio distraction.
| Leading Market Players |
|---|
| BASF |
| Syensqo |
| Medik8 |
| Lubrizol |
| Ashland |
| Shay and Company |
| DSM |
| Kao Corporation |
| KRI Skin |
| Others |
Value Network & Pricing Analysis
EU Green Deal documentation requirements for renewable carbon content are forcing formulators to qualify new suppliers, compressing procurement timelines and elevating premium pricing for REACH-registered ester producers with integrated bio-based feedstock pathways.
Pricing Analysis
Bundled certification-and-documentation services command substantial premiums over commodity-grade ester supply. Three-tier pricing structure across pharmaceutical-grade, formulation-grade, and technical-grade levels separates dermatology-channel suppliers from mass-market distributors. Cost compression in the technical-grade tier is intensifying because Indian and Brazilian contract manufacturers negotiate volume-driven procurement contracts. Dermatology clinics and medical spas show the least price sensitivity due to reimbursement-adjacent positioning, while entry-price mass retailers in emerging markets drive the hardest unit-economics negotiations.
Supply Chain Analysis
REACH dossier completion and BIS purity benchmark alignment now gate supplier eligibility for European and Indian formulators respectively. Production concentrates in South Korea, Germany, and China, with Songdo's biotech cluster and Ludwigshafen's chemical complex anchoring high-purity output. Isopalmitic acid, L-ascorbic acid precursor, and specialized esterification catalysts constitute critical input dependencies. Single-source vulnerability runs through South Korean intermediate manufacturers serving China's duty-free export channel. Distribution runs through integrated chemical platforms with captive formulation-grade capabilities rather than fragmented distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where REACH registration completion and EU Green Deal alignment now drive procurement preference as strongly as technical performance metrics.
For Market Incumbents: Acquire bio-based isopalmitic acid production assets to secure feedstock pathways against palm oil derivative volatility. Integrated players should expand esterification capacity in India's Maharashtra corridor ahead of BIS purity benchmark enforcement. Threats from mid-tier Chinese suppliers with expedited registration timelines demand defensive certification investments in ECHA dossier maintenance and MFDS alignment for Seoul's export channel. For New Entrants and Emerging Players: Direct-to-consumer serum brands represent the most penetrable channel partner type for bypassing established distributor relationships. White-space targets include scalp health pre-shampoo concentrates for K-beauty contract manufacturers and microfluidic encapsulation services for Japanese prestige houses. A formulation-science content marketing approach builds credibility with ingredient-aware consumers on Reddit and Korean beauty forums before retail listing negotiations. For Investors and Strategic Acquirers: Asymmetric upside sits with lipid-derivatives specialists possessing esterification process engineering talent pools and existing REACH dossier infrastructure. Long-term viability favors suppliers with backward integration into vitamin C precursor chemistry rather than toll-manufacturing-dependent models. Watch for inflection signals in Indian domestic cosmetics manufacturing growth rates and Sephora's Clean Beauty program certification requirement expansions.| Strategic Initiative | Industry Significance |
|---|---|
| REACH Dossier Completion | ECHA registration unlocks qualified vendor status for Vichy, La Roche-Posay, and Eucerin supply chains. |
| Bio-Based Feedstock Certification | Renewable carbon documentation satisfies EU Green Deal procurement specifications from German and Dutch formulators. |
| Microfluidic Encapsulation Partnership | Precision delivery system access enables premium positioning for Japanese limited-edition serum launches. |
| Indian Manufacturing Footprint Expansion | Maharashtra and Gujarat capacity captures domestic cosmetics growth under evolving BIS purity benchmarks. |
| Direct-to-Brand E-Commerce Channel Development | Manufacturer-direct relationships bypass specialty retailer markups for ingredient-aware consumer segments. |
Research Methodology
Bottom-up skincare formulation modeling reconciled against top-down lipid-derivative supply tracking forms the analytical core of this study. Primary interviews with cosmetic chemists, contract manufacturing procurement leads, dermatology clinic inventory managers, and REACH regulatory consultants combined with secondary validation from ECHA registration databases, MFDS cosmetic safety filings, customs trade records, and SEC 10-K disclosures from integrated chemical platforms. Triangulation across these sources ensures convergence between demand-side absorption estimates and supply-side production capacity.
Input-output matrices map isopalmitic acid feedstock availability through esterification yield rates to formulation-grade output volumes across the projection horizon. Segmentation dimensions include product concentration tier, delivery format chemistry, application category depth, distribution channel information access level, and regional regulatory cluster. CAGRs derive from regression analysis against precursor chemical pricing indices and cosmetics manufacturing output trends. Forecast inputs incorporate REACH registration timeline probabilities and K-beauty export channel growth trajectories.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU Green Deal enforcement intensity and palm oil derivative price volatility. Model outputs reflect documented assumptions regarding esterification batch yield consistency and dermatology-channel procurement expansion rates. A model refresh is warranted upon material change in ECHA dossier processing timelines or Sephora's Clean Beauty program certification criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Hyaluronic Acid Market
Specialty Chemicals
Eitelite Market
Specialty Chemicals
Global Flame Retardants Market
Specialty Chemicals
Diindolylmethane Market
Specialty Chemicals
Calcium D-Pantothenate Market
Specialty Chemicals
Inorganic Flame Retardants Market
Specialty Chemicals
Global Silanes Market
Specialty Chemicals
Plastic Stabilizer Market
Specialty Chemicals
Phenyl Trimethicone Market
Specialty Chemicals
Cloud Emulsions Market
Specialty Chemicals
Global Chitin Market
Specialty Chemicals
Mexoryl SX (Ecamsule) Market
Specialty Chemicals
Acesulfame Potassium Market
Specialty Chemicals
Solanesol Market
Specialty Chemicals
Silicone Acrylate Market
Specialty Chemicals
Organosilicon Electrolyte Market