
 Bismuth Oxychloride Market | 2026-2036
Bismuth Oxychloride Market Size, Share, and Industry Trends Forecast 2026-2036
Bismuth Oxychloride Market Outlook
Buyer concentration in cosmetics is rebalancing as multinational beauty houses consolidate supplier rosters while indie color cosmetics brands fragment procurement across smaller batches. BASF SE leverages its pigment synthesis expertise to anchor supply relationships with premium makeup houses. Zhonglan Industry Co., Ltd. competes on crystallization scale and cost position for industrial-grade powder. Uni-Powder specializes in sub-micron particle engineering for high-luster cosmetic applications.
Bismuth oxychloride is a synthetically produced inorganic crystalline compound with the chemical formula BiOCl, manufactured through controlled precipitation of bismuth salts in chloride media to yield a white, pearlescent solid with refractive index near 2.15. It serves primarily as a nacreous pigment in cosmetics and as an active pharmaceutical intermediate for gastrointestinal and antimicrobial formulations. The cosmetics product type segment leads absolute volume, though pharmaceutical-grade specifications command the widest margin pools due to stringent purity requirements. Powder form dominates current shipments, while liquid dispersions are gaining traction among makeup manufacturers seeking streamlined compounding workflows.
REACH registration and the EU Cosmetics Regulation govern ingredient disclosure and purity thresholds for bismuth oxychloride entering European cosmetic supply chains, while FDA color additive regulations and EPA effluent guidelines shape compliance costs for U.S.-based manufacturers. China's GB standards for cosmetic raw materials and pharmaceutical intermediates impose additional testing protocols on domestic producers. Stakeholders must monitor evolving purity specifications across these jurisdictions and assess captive crystallization investments versus merchant supply dependence.
Market Dynamics
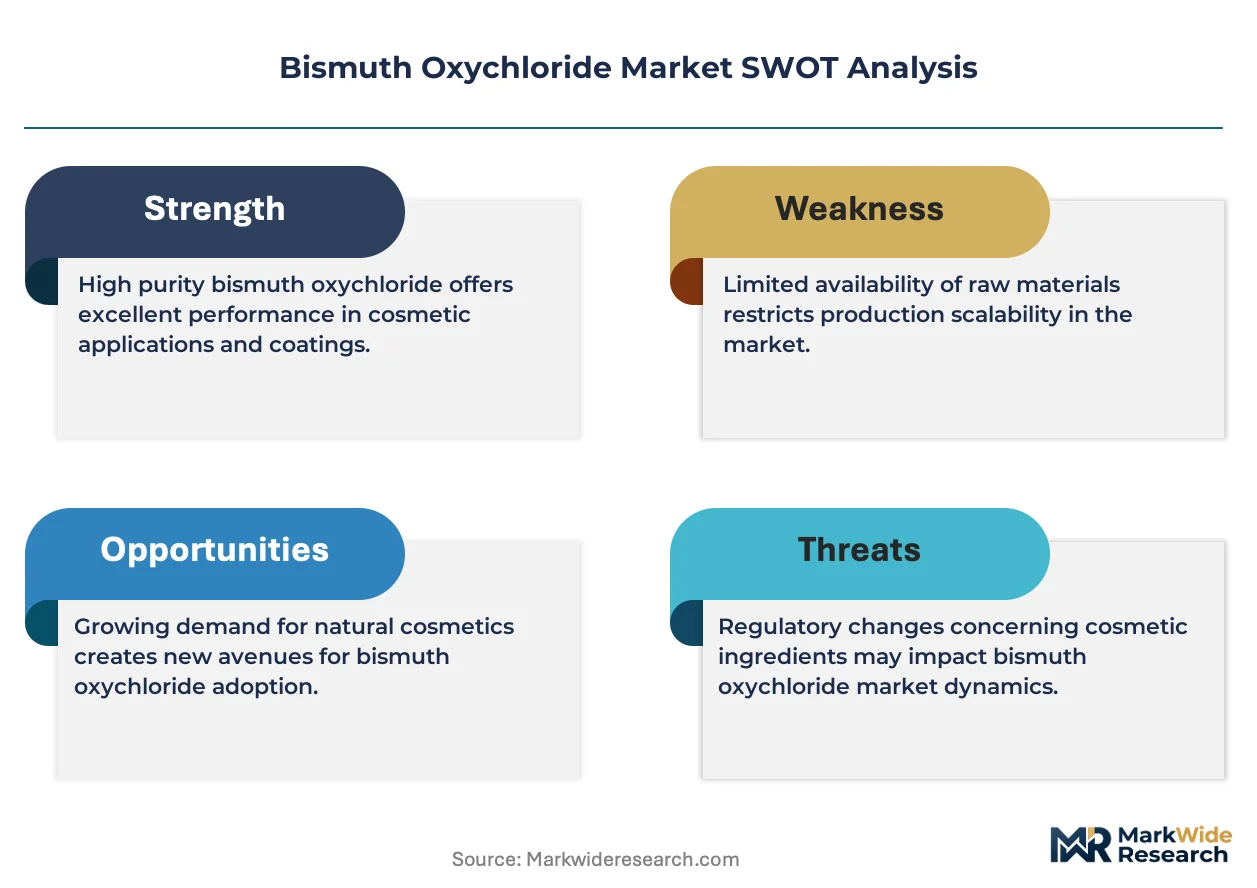
Cosmetic-grade bismuth oxychloride procurement is consolidating around REACH-registered European suppliers and FDA-compliant US crystallizers as purity thresholds tighten and batch traceability becomes non-negotiable for premium makeup houses.
Growth Catalysts
- REACH purity mandates:The EU Cosmetics Regulation's disclosure requirements are pushing formulators toward certified crystallizers with documented heavy-metal testing protocols, locking in supplier relationships.
- Pharmaceutical intermediate demand:Antimicrobial and gastrointestinal drug pipelines are absorbing higher volumes of USP-grade BiOCl as bismuth subsalicylate formulations expand.
- China's crystallization scale-up:Domestic pigment producers in Jiangsu and Zhejiang provinces are adding precipitation capacity to serve both cosmetic and industrial nacreous pigment demand.
Market Restraints
- Bismuth metal price volatility:Concentrated supply from Chinese smelters creates input cost instability that squeezes margin pools for merchant pigment manufacturers.
- Substitution by synthetic mica:Ethical sourcing concerns around natural mica are redirecting some pearlescent demand toward aluminum-based alternatives with comparable refractive properties.
- EPA effluent compliance:Chloride-rich precipitation wastewater requires costly treatment infrastructure for US-based crystallization facilities.
Strategic Opportunities
- India cosmetic manufacturing:CDSCO's evolving color additive framework and expanding domestic makeup production create entry points for compliant BiOCl suppliers.
- Liquid dispersion formats:Pre-dispersed slurries eliminate powder handling and milling steps for cosmetic compounders seeking workflow efficiency.
- PLI scheme alignment:India's production-linked incentive framework for active pharmaceutical ingredients supports backward integration into bismuth salt processing.
Industry Challenges
- Crystallization process engineering talent:Precipitation parameter control and particle-size distribution mastery require specialized chemists in short supply across merchant suppliers.
- Multi-jurisdiction certification timelines:Parallel FDA color additive petitions, REACH dossier updates, and NMPA registrations delay product commercialization by 18-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bismuth Oxychloride Market |
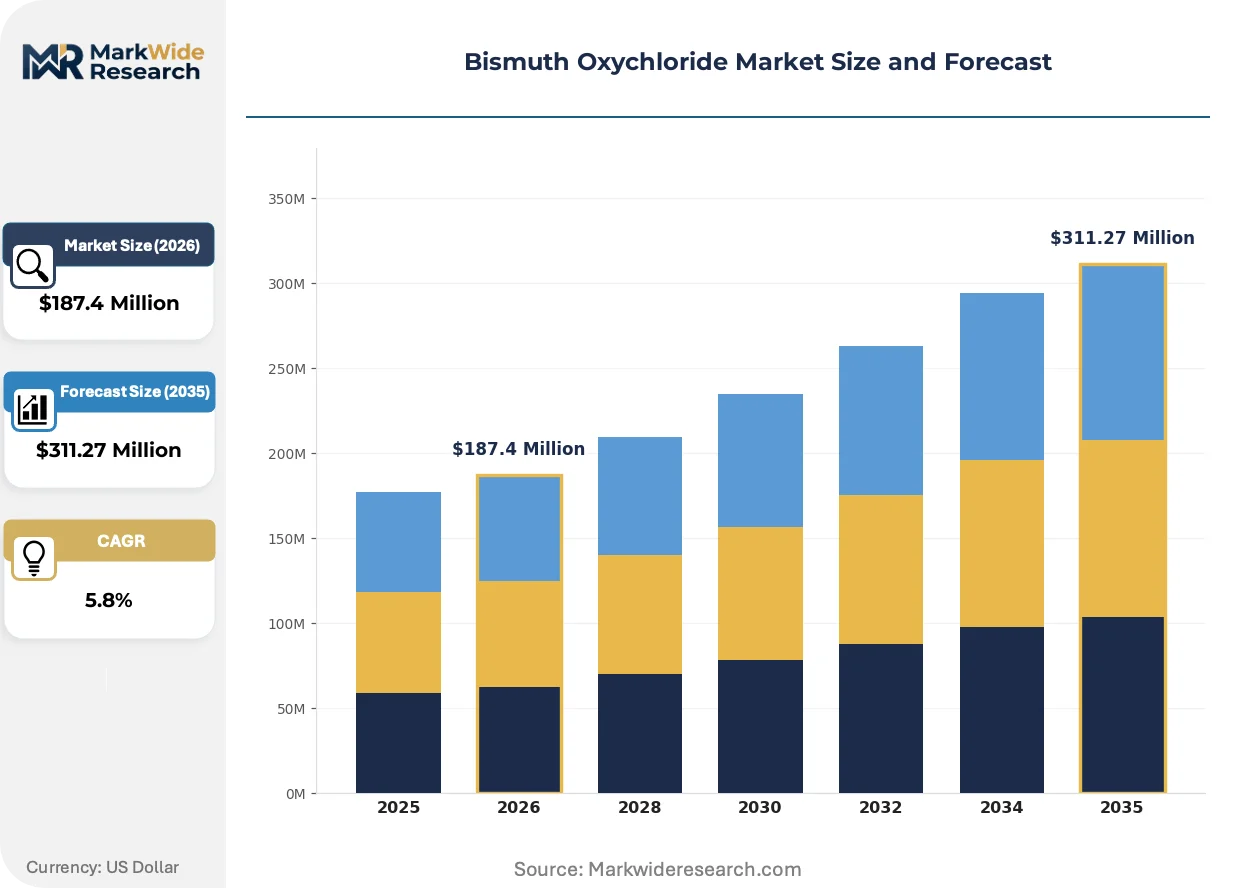
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetics, Pharmaceuticals, Coatings, Pigments Application: Skin Care, Makeup, Industrial Use, Healthcare Form: Powder, Liquid, Granules, Paste End User: Manufacturers, Retailers, Distributors, Consumers |
| Companies Covered | BASF SE, Geotech International B.V, Omkar Speciality Chemicals Ltd., Satyam Pharma-Chem Pvt. Ltd., Uni-Powder, Zhonglan Industry Co., Ltd., Ava Chemicals Pvt. Ltd., Vital Materials Co., Limited, Hangzhou Rebtech Novel Material Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bismuth Oxychloride Market Strategic Shifts
Particle engineering and regulatory compliance automation are redefining competitive advantage in bismuth oxychloride supply, with sub-micron control and batch-level traceability becoming baseline capabilities rather than differentiators.
Sub-micron particle engineering is expanding into cosmetic applications previously dominated by larger-flake pearlescent pigments. High-luster makeup formulations now demand BiOCl with median particle sizes below 5 micrometers, achievable through controlled double-jet precipitation. This precision is compressing the addressable market for conventional crystallizers lacking microfluidic or sonochemical refinement capabilities.
EU Cosmetics Regulation ingredient disclosure requirements are forcing reformulation transparency across European supply chains. The mandate for nanomaterial labeling and safety dossier maintenance is raising compliance costs for importers. Premium cosmetic houses are responding by consolidating supplier rosters around crystallizers with in-house toxicology and regulatory affairs functions.
Direct procurement from crystallizers is displacing traditional pigment distributor intermediaries in North American cosmetic supply chains. Large beauty houses now negotiate annual volume contracts with REACH-registered producers, bypassing regional wholesalers. This disintermediation is most visible in California and New Jersey, where compounding facilities cluster near ports and domestic crystallization plants.
Bismuth Oxychloride Market Segmentation
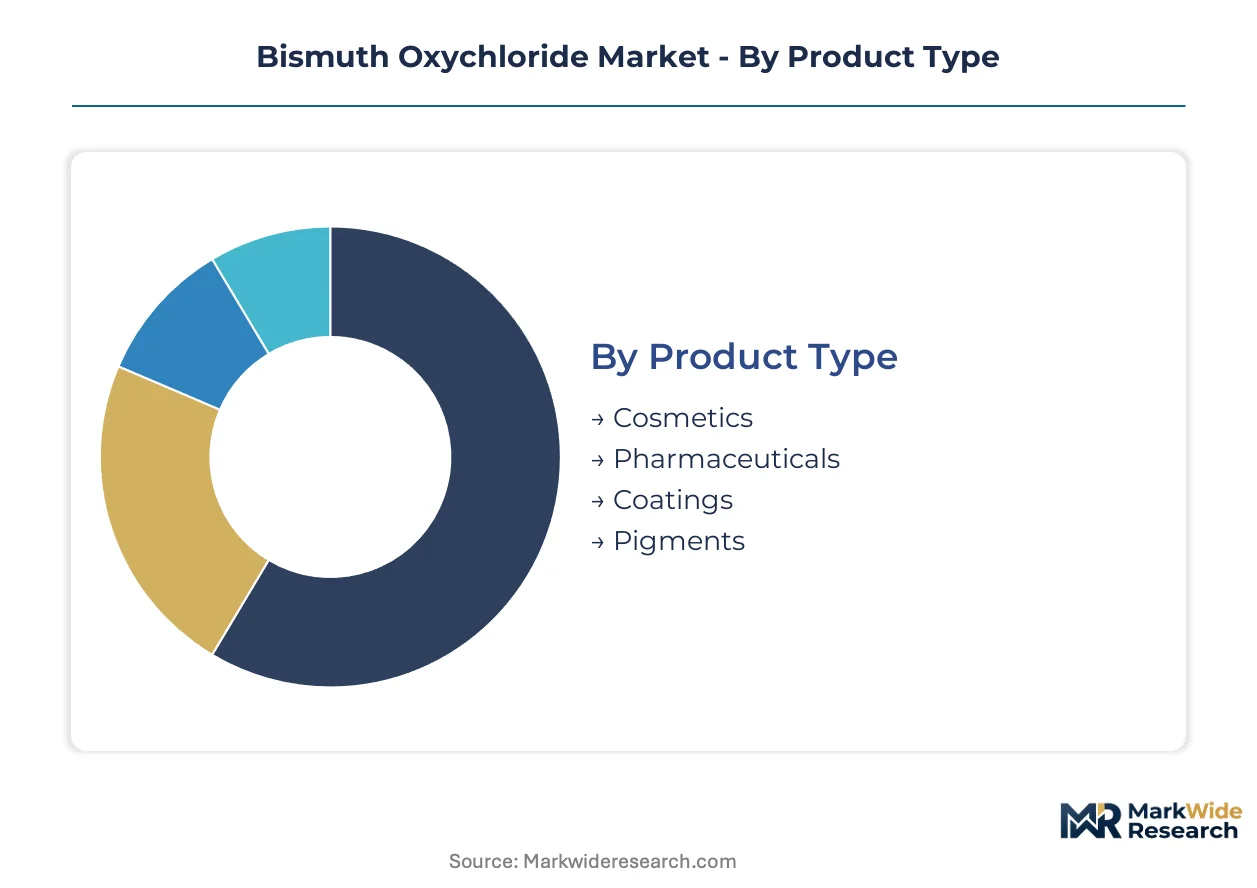
Bismuth oxychloride procurement patterns diverge sharply across end-use verticals, with cosmetic formulators prioritizing sub-micron particle consistency while pharmaceutical buyers enforce USP-grade purity protocols. Coatings and industrial pigment buyers operate on cost-per-kilogram efficiency metrics that reshape crystallization capacity allocation.
Product Type:
Cosmetic houses differentiate procurement by luster grade and heavy-metal certification, while pharmaceutical buyers lock in multi-year supply agreements against USP monograph compliance.
- Cosmetics:Pearl-effect pigments for premium makeup formulations demand median particle sizes below 5 micrometers with REACH-registered batch traceability. North American and Western European beauty houses are consolidating supplier rosters around crystallizers with in-house toxicology capabilities as EU Cosmetics Regulation disclosure requirements tighten.
- Pharmaceuticals:USP-grade bismuth oxychloride serves as an active intermediate for gastrointestinal and antimicrobial drug pipelines. Stringent purity requirements command the widest margin pools, with CDSCO and FDA color additive petitions driving 18-36 month commercialization timelines.
- Coatings:Industrial nacreous pigment applications prioritize cost position over particle-size precision, with Chinese crystallizers in Jiangsu and Zhejiang provinces scaling precipitation capacity to serve this segment.
- Pigments:Standalone pearlescent pigment sales to merchant compounders concentrate in powder form, with liquid dispersions gaining traction among workflow-optimizing manufacturers.
Cosmetics leads volumes today; pharmaceuticals is gaining share fastest on antimicrobial formulation expansion.
Application:
Formulation complexity and regulatory exposure separate premium makeup applications from commodity industrial absorption.
- Skin Care:Lotion and serum formulations utilize sub-micron BiOCl for subtle luminosity without visible particle detection. EU nanomaterial labeling mandates and FDA guidance on color additives in leave-on products are elevating compliance costs for importers.
- Makeup:High-luster foundations, eyeshadows, and pressed powders represent the most technically demanding segment, requiring controlled double-jet precipitation and refractive index consistency near 2.15. Direct procurement from crystallizers is displacing traditional pigment distributors in California and New Jersey compounding clusters.
- Industrial Use:Coatings, plastics, and printing inks absorb volume at lower specification tiers, with price volatility in Chinese bismuth metal supply squeezing margin pools for merchant manufacturers.
- Healthcare:Bismuth subsalicylate formulations and antimicrobial drug pipelines absorb USP-grade material with documented heavy-metal testing protocols, locking in supplier relationships through multi-year agreements.
Makeup dominates absolute consumption; skin care is expanding most quickly on serum and luminosity-tinted moisturizer trends.
Form:
Handling economics and compounding workflow efficiency determine format selection across customer tiers.
- Powder:Dominant shipment format for pigment manufacturers and pharmaceutical compounders with in-house milling capabilities. Powder handling requires dust control infrastructure that smaller cosmetic brands often lack.
- Liquid:Pre-dispersed slurries eliminate milling steps and powder exposure risks, streamlining workflows for makeup manufacturers in North American and Western European compounding facilities. Liquid formats command price premiums that compress at volume scale.
- Granules:Intermediate format for industrial coatings and plastics compounding, offering flow properties superior to fine powder without liquid dispersion costs.
- Paste:Niche format for specialized cosmetic applications requiring extreme particle suspension stability, produced by select crystallizers with proprietary dispersion chemistry.
Powder leads volumes today; liquid is climbing the fastest on workflow efficiency priorities among mid-scale cosmetic houses.
End User:
Procurement scale and technical capability separate direct crystallizer relationships from distributor-mediated supply.
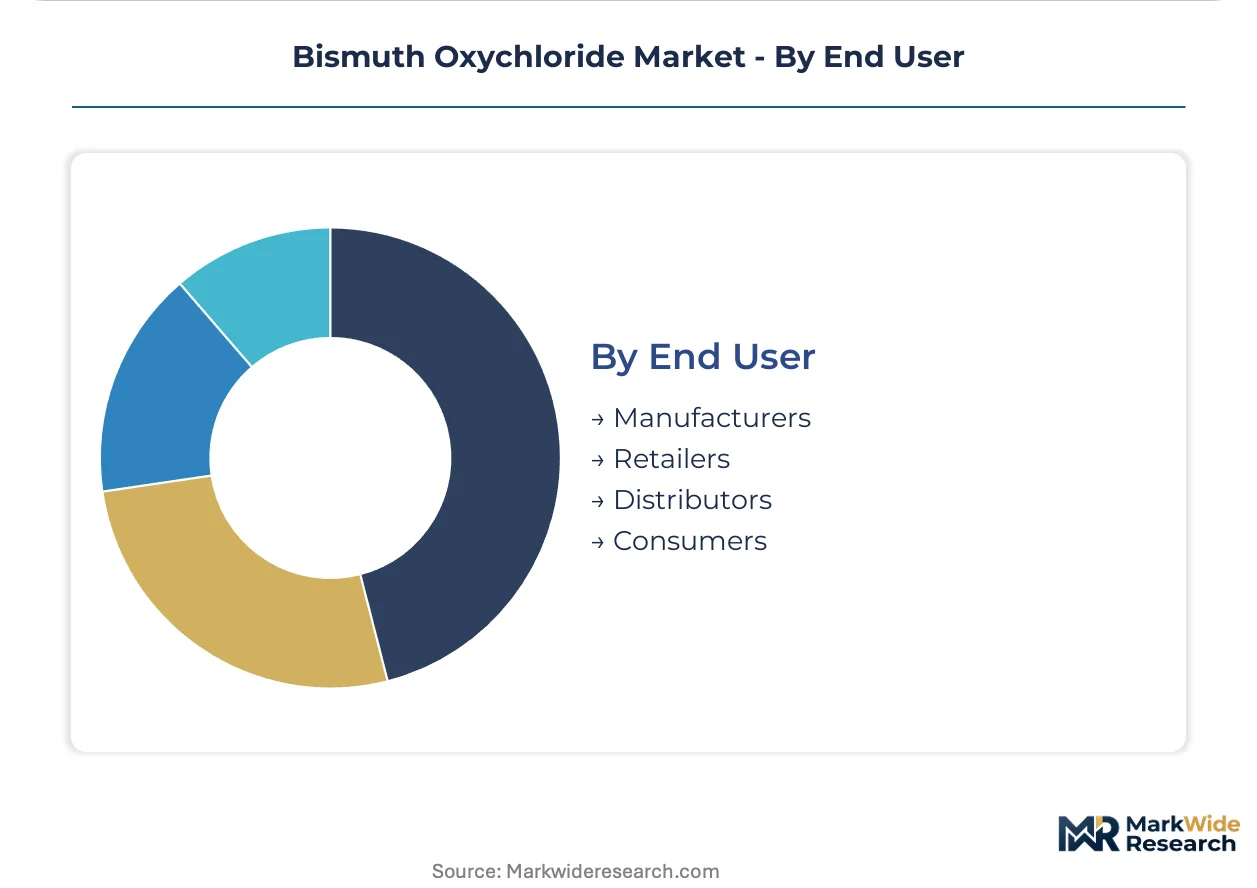
- Manufacturers:Cosmetic compounders, pharmaceutical formulators, and coatings producers with annual volume requirements sufficient to justify direct crystallizer contracts. Large beauty houses now negotiate annual volume agreements with REACH-registered producers, bypassing regional wholesalers.
- Retailers:Indie color cosmetics brands and specialty beauty retailers fragment procurement across smaller batches, often sourcing through pigment distributors with limited batch traceability documentation.
- Distributors:Traditional pigment and chemical distributors face disintermediation pressure as premium makeup houses consolidate supplier rosters, with survival dependent on technical service capabilities and inventory flexibility.
- Consumers:Minimal direct exposure; artisan cosmetic makers and research institutions purchase laboratory-scale quantities through specialty chemical channels.
Manufacturers lead volumes today; retailers are gaining share fastest on indie brand proliferation and e-commerce direct sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands crystallization scale advantages while Germany anchors REACH-registered supply chains for European cosmetic houses. This divergence shapes procurement geography across premium and industrial-grade segments.
China
Jiangsu and Zhejiang provinces drive precipitation capacity expansion for both cosmetic pigment and pharmaceutical intermediate demand. GB standards for cosmetic raw materials and pharmaceutical intermediates impose testing protocols on domestic producers. Hangzhou and surrounding Yangtze River Delta cities concentrate crystallization facilities serving export-oriented nacreous pigment manufacturers.
Germany
BASF SE leverages Ludwigshafen-based pigment synthesis expertise to anchor supply relationships with premium makeup houses across Western Europe. REACH registration and ECHA compliance requirements lock in supplier relationships through documented heavy-metal testing protocols. The Rhine-Neckar industrial cluster maintains specialized precipitation engineering capabilities for sub-micron particle control.
United States
California and New Jersey compounding facilities cluster near ports and domestic crystallization plants, driving direct procurement from FDA-compliant producers. EPA effluent guidelines on chloride-rich precipitation wastewater elevate treatment infrastructure costs for crystallizers. FDA color additive petitions and evolving guidance on color additives in leave-on products extend commercialization timelines for new entrants.
India
Maharashtra and Gujarat pharmaceutical hubs absorb expanding volumes of bismuth oxychloride for antimicrobial and gastrointestinal drug pipelines. CDSCO's evolving color additive framework and PLI scheme for active pharmaceutical ingredients support backward integration into bismuth salt processing. Mumbai-Pune industrial corridor houses formulators scaling domestic makeup production.
Japan
Osaka-based cosmetic compounders demand sub-micron particle consistency for high-luster makeup formulations serving premium domestic brands. METI oversight and PMDA pharmaceutical standards enforce purity thresholds comparable to USP-grade specifications. Kansai region technical service capabilities support specialized dispersion chemistry for paste-format niche applications.
Bismuth Oxychloride Market Competitive Environment
Chinese producers anchor the scale-driven tier; European and American specialists hold the premium-grade segment through regulatory certification advantages. The vendor base splits between consolidated multinational pigment houses and fragmented regional crystallizers. Two strategic archetypes dominate: REACH-registered integrated chemical conglomerates with in-house toxicology functions, and sub-micron engineering specialists serving cosmetic luster requirements. Capacity expansion and direct procurement relationships with beauty houses constitute the dominant competitive moves.
Among Germany-based chemical conglomerates, BASF SE exemplifies the regulatory-anchored archetype through its pigment synthesis heritage. Chinese crystallizers including Zhonglan Industry Co., Ltd. and Hangzhou Rebtech Novel Material Co., Ltd. occupy positions within the scale-focused tier, representing cost-competitive precipitation capacity for industrial and mid-market cosmetic applications. Uni-Powder sits within the particle-engineering specialist category, serving sub-micron requirements for high-luster cosmetic formulations.
| Leading Market Players |
|---|
| BASF SE |
| Geotech International B.V |
| Omkar Speciality Chemicals Ltd. |
| Satyam Pharma-Chem Pvt. Ltd. |
| Uni-Powder |
| Zhonglan Industry Co., Ltd. |
| Ava Chemicals Pvt. Ltd. |
| Vital Materials Co., Limited |
| Hangzhou Rebtech Novel Material Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Controlled double-jet precipitation technology is displacing conventional crystallization methods across Jiangsu and Zhejiang provinces, compressing production costs for sub-micron grades while concentrating supply leverage among scale-capable producers. This process shift simultaneously enables REACH-registered European crystallizers to defend premium pricing through particle-engineering certification and forces mid-tier merchant suppliers into volume-based competition.
Pricing Analysis
Capacity additions in China's Yangtze River Delta are reshaping price floors for industrial-grade bismuth oxychloride, compressing margins for conventional crystallizers lacking microfluidic refinement capabilities. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered cosmetic-grade material with nanomaterial dossiers from unregistered industrial pigment and basic pharmaceutical intermediate tiers. Cost compression in standard-grade powder reflects bismuth metal price volatility from Chinese smelter concentration. Coatings compounders exhibit highest price sensitivity; premium makeup houses prioritize batch traceability over unit cost.
Supply Chain Analysis
Specialized precipitation chemist shortages in Ludwigshafen and Hangzhou constrain crystallization capacity expansion timelines for sub-micron particle engineering. Supply concentrates in China, Germany, and the United States, with Jiangsu province anchoring industrial-grade scale and Germany anchoring REACH-registered premium supply. Merchant producers draw from bismuth metal feedstock concentrated in Chinese smelters, chloride reagents, and energy-intensive precipitation infrastructure. Single-source vulnerability runs through bismuth metal supply from concentrated Chinese refining. Distribution runs through direct annual volume contracts between crystallizers and large beauty houses, displacing traditional pigment distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bismuth oxychloride procurement economics favor margin expansion through liquid dispersion format premiums and pharmaceutical-grade certification tiering, as workflow efficiency demands and USP monograph compliance requirements concentrate purchasing power among qualified suppliers.
For Market Incumbents: Extend REACH dossier maintenance capabilities and in-house toxicology functions to lock in multi-year supply relationships with premium makeup houses facing EU Cosmetics Regulation disclosure mandates. Anchor position through backward integration into bismuth salt processing in India under PLI scheme alignment, defending against Chinese crystallizer scale advantages. Capacity additions in sub-micron particle engineering represent the critical defensive lever against substitution by synthetic mica alternatives. For New Entrants and Emerging Players: Enter via CDSCO-compliant pharmaceutical intermediate supply to Maharashtra and Gujarat formulators scaling antimicrobial drug production, where USP-grade purity requirements command widest margin pools. Target India's emerging domestic makeup manufacturing corridor around Mumbai-Pune for cosmetic-grade material, exploiting regulatory compliance gaps among incumbent distributors. Position through liquid dispersion format specialization for mid-scale cosmetic houses seeking workflow efficiency without capital-intensive powder handling infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among scale-focused Chinese crystallizers lacking REACH registration and sub-micron engineering capabilities, presenting consolidation targets for regulatory-anchored Western pigment houses. Long-term viability hinges on captive access to bismuth metal supply and crystallization process engineering talent pools. Watch for inflection in FDA color additive petition timelines for new cosmetic-grade entrants, as 18-36 month commercialization delays compress competitive pressure from unregistered suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bismuth Salt Processing | PLI scheme alignment in India secures feedstock cost position against Chinese smelter volatility. |
| REACH Dossier Expansion | ECHA compliance locks in supplier relationships with EU cosmetic houses facing disclosure mandates. |
| Liquid Dispersion Format Scale-Up | Pre-dispersed slurry capacity captures workflow efficiency demand from mid-scale makeup manufacturers. |
| Sub-Micron Particle Engineering Investment | Double-jet precipitation mastery defends premium tier against conventional crystallizer competition. |
| Long-Term Supply Agreement Structuring | Annual volume contracts with beauty houses displace distributor intermediaries in California and New Jersey. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with crystallization plant managers, cosmetic procurement leads at premium beauty houses, pharmaceutical formulators, and pigment distribution channel partners with secondary validation. Bottom-up and top-down triangulation anchored volume estimates in customs trade data, SEC filings from disclosed pigment producers, ECHA REACH registration databases, and FDA color additive petition records.
Segment-weighting approaches distributed value and volume across product type tiers, application verticals, form factors, and end-user procurement archetypes throughout the forecast period. CAGRs derived from capacity expansion timelines, regulatory commercialization lag assumptions, and substitution elasticity parameters for synthetic mica alternatives. Crystallization capacity utilization rates and bismuth metal price volatility bands served as industry-specific sensitivity inputs.
The model holds under stable REACH and FDA regulatory frameworks; deviation in color additive petition timelines or sudden bismuth metal supply disruption would shift competitive positioning and margin pool distribution. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Electrical Insulating Varnish for Motor Vehicle Market
Specialty Chemicals
Nucleotides Market
Specialty Chemicals
Synthetic and Bio-Based Adipic Acid Market
Specialty Chemicals
Special Boiling Point Solvents Market
Specialty Chemicals
Taurine Market
Specialty Chemicals
North America Sulfonylureas Market
Specialty Chemicals
Washable Marker Market
Specialty Chemicals
Sulfonated Melamine Formaldehyde Market
Specialty Chemicals
Carbocernaite Market
Specialty Chemicals
Global Tetrahexyldecyl Ascorbate Market
Specialty Chemicals
Cloud Emulsions Market
Specialty Chemicals
1,2 Hexanediol Market
Specialty Chemicals
Crystal Hard Wax Market
Specialty Chemicals
Gallic Acid Market
Specialty Chemicals
Global Tetrakis (Hydroxymethyl) Phosphonium Sulfate Market
Specialty Chemicals
Cellulose Ether Market