
 Global Non-Phthalate Plasticizers Market | 2026-2036
Global Non-Phthalate Plasticizers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Non-Phthalate Plasticizers Market Outlook
Medical-grade specification tiers is rotating toward the center of purchasing decisions as healthcare OEMs reject legacy plasticizers with migration risks. BASF SE leverages its integrated adipate and sebacate chains to supply certified medical compounds. Eastman Chemical Company anchors North American demand through its non-phthalate portfolio targeting pediatric and neonatal applications. Evonik Industries AG specializes in high-purity citrate formulations for European pharmaceutical packaging.
Non-phthalate plasticizers are ester-based additives, typically derived from adipic, sebacic, or citric acid feedstocks, that impart flexibility and processability to polyvinyl chloride and other polymers without relying on ortho-phthalate chemistry. These compounds function by inserting between polymer chains to reduce glass transition temperature and enhance elongation at break, with medical and food-contact applications demanding purity levels below 0.1 percent residual phthalate content. Adipate and sebacate product types dominate volume due to their cost-performance balance in flooring and automotive interiors, while citrate formulations command premium positioning in medical devices and food films where biocompatibility certifications apply. Liquid formulations lead consumption across coatings and adhesives applications, though powder and emulsion variants are gaining traction in specialized construction sealants.
REACH restrictions through ECHA, FDA guidance under 21 CFR 175.105, and EPA TSCA Section 6 rules collectively restrict phthalate content in consumer and medical applications, directly redirecting formulation procurement toward certified non-phthalate alternatives. The EU MDR and F-Gas Regulation add further compliance layers for devices and building materials sold in Europe. Stakeholders must monitor evolving substance restriction lists and certification reciprocity between jurisdictions to anticipate qualification timelines for new plasticizer chemistries.
Market Dynamics
REACH substance restrictions and FDA 21 CFR guidance are compressing qualification timelines for legacy phthalate alternatives, forcing compounders to pre-certify non-phthalate formulations before tender participation. This regulatory acceleration is restructuring supplier-buyer power dynamics across medical and automotive supply chains.
Growth Catalysts
- EU MDR migration limits:Medical device manufacturers must eliminate DEHP and DBP from neonatal and long-term exposure applications by certified deadlines, redirecting procurement toward adipate and citrate alternatives with documented biocompatibility.
- Automotive interior air quality standards:OEMs in Germany and Japan now specify non-phthalate plasticizers for dashboard and seating foams to meet cabin air quality protocols and prevent fogging-related warranty claims.
- Sebacic acid feedstock expansion:Castor oil-derived sebacate production in India and Brazil is diversifying supply origins beyond petrochemical adipic acid, reducing price volatility exposure for flexible PVC compounders.
Market Restraints
- Adipic acid price volatility:Cyclohexane oxidation feedstock costs fluctuate with benzene pricing, compressing margin stability for mid-volume plasticizer producers without backward integration into acid production.
- Citrate supply concentration:High-purity citrate ester manufacturing clusters in Western Europe, creating single-source risk for pharmaceutical packaging certification requirements.
- Performance gaps in low-temperature flex:Non-phthalate alternatives exhibit higher glass transition temperatures than legacy DINP formulations, limiting adoption in Arctic-grade cable and outdoor membrane specifications.
Strategic Opportunities
- Brazilian medical device localization:ANVISA import substitution incentives and local PVC resin capacity expansion create white space for certified non-phthalate compounders to displace European imports.
- Food-contact film certification:EFSA positive opinions on specific citrate formulations open penetration into cling film and lidding applications previously locked by migration test failures.
- Construction sealant emulsion formats:Powder and high-solids emulsion variants enable water-based adhesive formulations, accessing VOC-regulated building markets in California and Nordic countries.
Industry Challenges
- Migration testing protocol fragmentation:FDA, ECHA, and BfR employ different extraction conditions and simulants, forcing compounders to run parallel qualification studies for multi-jurisdiction tenders.
- Legacy equipment retrofit costs:Switching from phthalate to non-phthalate formulations requires dryer temperature and screw speed recalibration, extending commissioning timelines for extrusion and calendering lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Non-Phthalate Plasticizers Market |
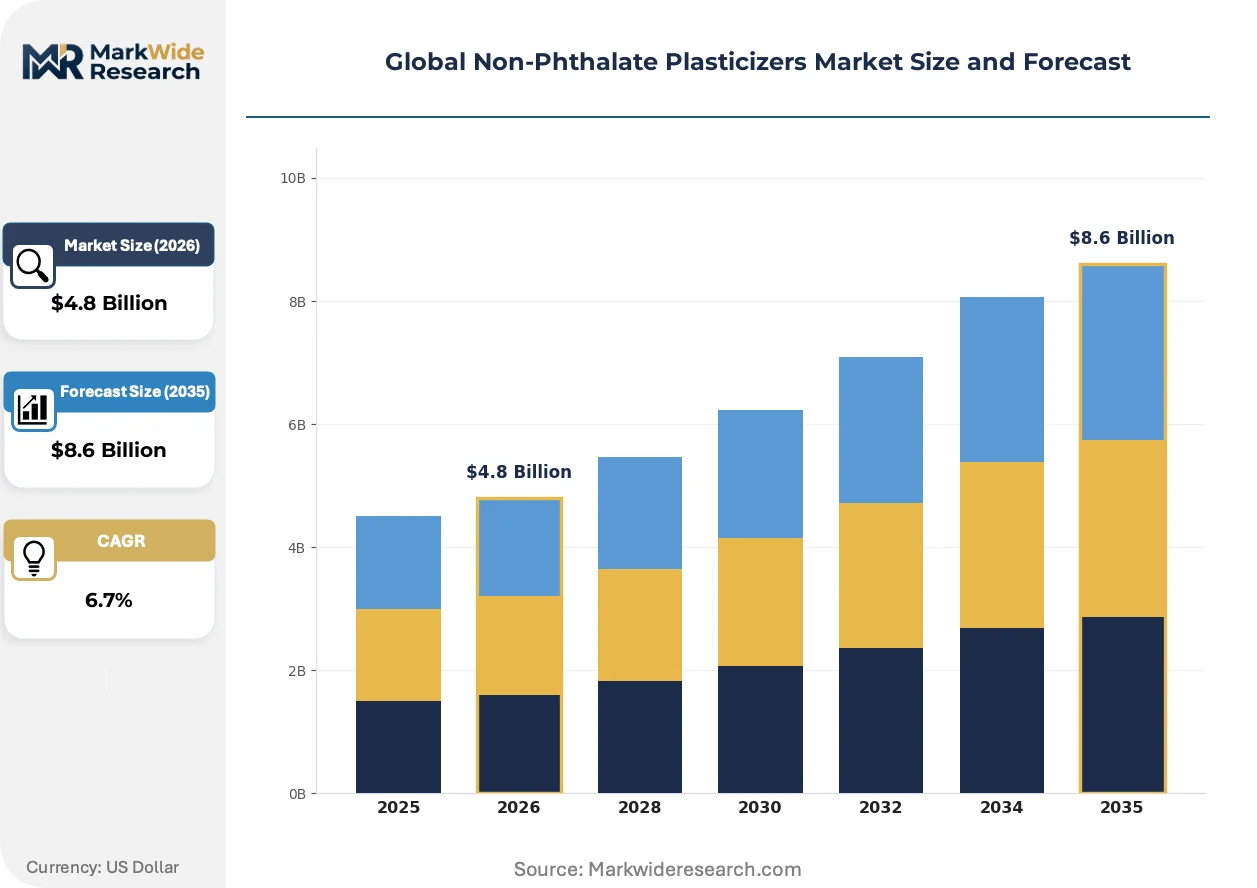
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Adipate, Citrate, Sebacate, Ether End User: Construction, Automotive, Consumer Goods, Medical Application: Flooring, Coatings, Adhesives, Films Formulation: Liquid, Solid, Emulsion, Powder |
| Companies Covered | BASF SE, Eastman Chemical Company, Arkema Inc., Dow Chemical Company, Emery Oleochemicals Group, ExxonMobil Chemical Company, Evonik Industries AG, LANXESS AG, DIC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Non-Phthalate Plasticizers Market Strategic Shifts
Formulation science is compressing the performance gap between bio-based and petrochemical plasticizers while regulatory chemistry is forcing faster substitution cycles than equipment replacement schedules allow.
Reactive plasticizer technology is miniaturizing. These graft-compatible additives covalently bond to PVC backbones during processing, eliminating migration risks entirely. Medical tubing manufacturers in Germany and Switzerland are piloting these systems for implantable device applications. The technology is miniaturizing the acceptable residual extractables threshold from parts-per-thousand to parts-per-million detection limits.
REACH Annex XIV authorization requirements for DEHP, DBP, BBP, and DIBP are eliminating sunset date extensions. Compounders must now submit substitution plans to ECHA before continued use permissions expire. Flooring and wall covering segments face the most compressed transition timelines, with German and French distributors already delisting non-compliant product lines.
Certification-driven specification is consolidating buying power. Healthcare OEMs now require ISO 10993 biocompatibility documentation and REACH SVHC attestation before vendor onboarding, displacing spot-market purchasing. This pattern concentrates procurement through qualified compounders in the US Northeast and Rhine-Ruhr corridor, excluding smaller regional blenders from tender participation.
Global Non-Phthalate Plasticizers Market Segmentation
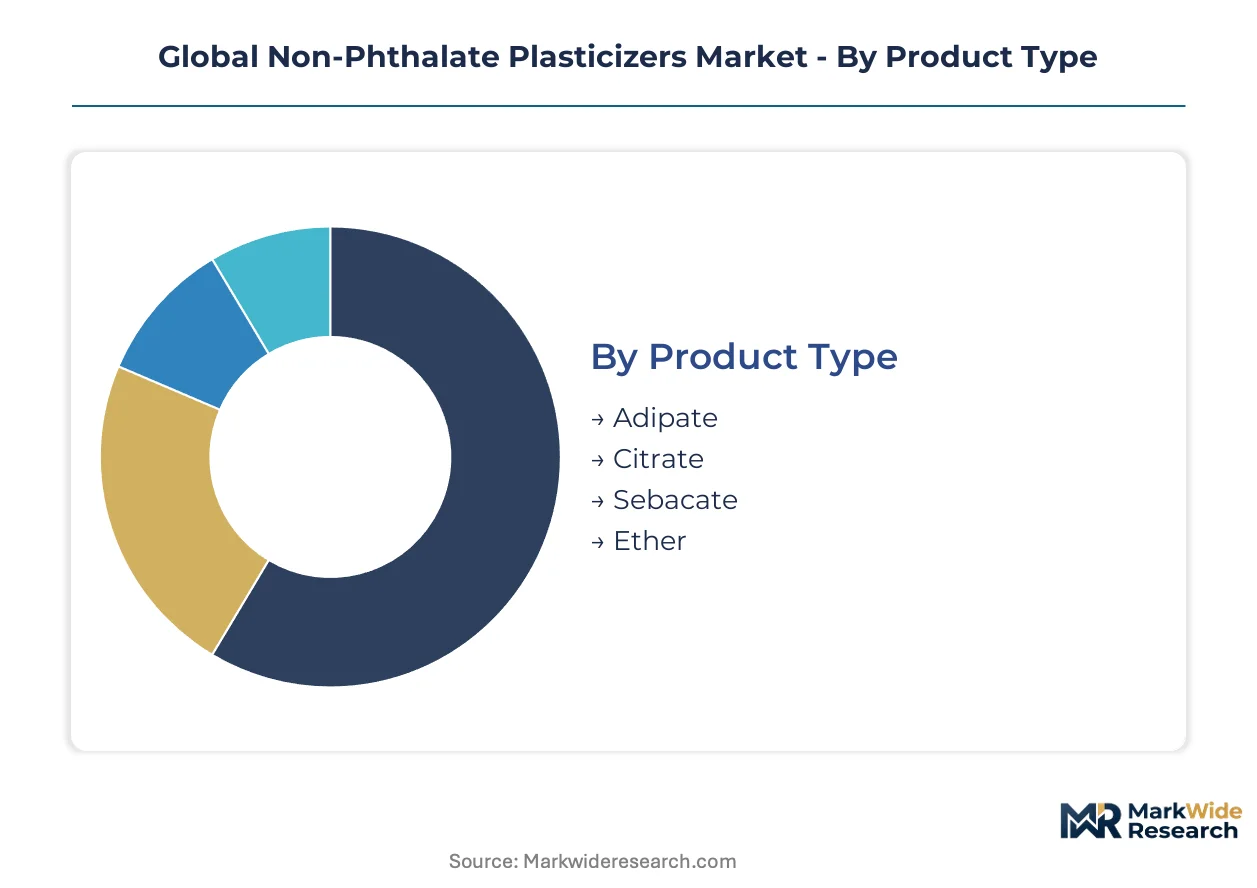
Segmentation in the non-phthalate plasticizers market reveals how regulatory pressure and end-use certification requirements fragment procurement patterns. Buyers select product types and formulations based on migration limits, biocompatibility standards, and processing equipment compatibility rather than price alone.
Product Type:
Margin pools concentrate in high-purity citrate and sebacate grades where pharmaceutical and medical device certifications command premium positioning over commodity adipate volumes.
- Adipate:Derived from cyclohexane oxidation, these petrochemical esters deliver cost-performance balance in flooring and automotive interiors. Demand concentrates in German automotive supply chains where OEMs specify low-fogging formulations for dashboard and seating applications to meet cabin air quality protocols.
- Citrate:High-purity esters of citric acid serve pharmaceutical packaging and neonatal medical devices requiring ISO 10993 biocompatibility documentation. European healthcare OEMs in the Rhine-Ruhr corridor now mandate REACH SVHC attestation before vendor onboarding, excluding uncertified suppliers from tender participation.
- Sebacate:Castor oil-derived esters diversify supply origins beyond petrochemical feedstocks, reducing benzene price volatility exposure for flexible PVC compounders in India and Brazil.
- Ether:Polymeric ether plasticizers offer permanence in high-temperature cable applications where migration resistance outweighs initial cost premiums.
The dominant share belongs to Adipate, while Citrate is closing the gap fastest on certification-driven substitution in healthcare applications.
End User:
Application requirements across end-use sectors determine formulation selection, with medical and automotive buyers imposing the strictest material qualification protocols.
- Construction:Flooring and wall covering manufacturers face compressed transition timelines under REACH Annex XIV sunset dates, with German and French distributors already delisting phthalate-containing product lines.
- Automotive:Japanese and German OEM specifications now mandate non-phthalate plasticizers for interior components to prevent fogging-related warranty claims and meet cabin air quality standards.
- Consumer Goods:Toy and childcare product manufacturers respond to FDA guidance and state-level restrictions in California and New York, shifting procurement toward certified alternatives with documented safety profiles.
- Medical:Device manufacturers must eliminate DEHP and DBP from neonatal and long-term exposure applications by regulatory deadlines, redirecting procurement toward adipate and citrate alternatives with biocompatibility certification.
Medical commands the steepest expansion trajectory as EU MDR migration limits and FDA guidance compress qualification timelines, while Construction maintains volume leadership through flooring substitution cycles.
Application:
Processing method and exposure conditions dictate plasticizer selection, with film and coating applications requiring the lowest residual extractables thresholds.
- Flooring:Flexible PVC sheet and tile manufacturers in Germany and France face immediate reformulation pressure as REACH authorization deadlines eliminate sunset date extensions for phthalate alternatives.
- Coatings:Liquid plasticizer formulations dominate industrial and decorative coatings where viscosity control and film formation properties determine specification.
- Adhesives:Construction sealant applications are shifting toward powder and high-solids emulsion variants to access VOC-regulated building markets in California and Nordic countries.
- Films:Food-contact cling film and lidding applications require EFSA-positive opinions on specific citrate formulations, opening penetration into segments previously locked by migration test failures.
Flooring retains the largest installed base, though Films demonstrates the most rapid share gain on food-contact certification expansion.
Formulation:
Physical form selection tracks equipment compatibility and environmental compliance requirements, with water-based formats gaining ground in regulated construction applications.
- Liquid:Standard pourable esters dominate coatings and adhesives processing where pumpability and metered dosing integrate with existing compounding lines without dryer temperature recalibration.
- Solid:Flake and pellet formats reduce shipping costs for high-volume flooring compounders while enabling precise gravimetric feeding in automated blending systems.
- Emulsion:Water-based dispersions enable VOC-compliant adhesive formulations for building sealants in California and Nordic regulatory jurisdictions.
- Powder:Free-flowing solid variants serve specialized construction sealants where dust-free handling and rapid incorporation into dry blends outweigh liquid convenience.
Liquid formulations hold the majority position, yet Emulsion formats are gaining share fastest on water-based regulatory compliance in construction end uses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics reveal a market tilting toward regional self-sufficiency, with Germany and China reducing external sourcing dependence while Brazil and India build domestic compounding capacity to capture substitution-driven demand.
Germany
Automotive OEM specifications for cabin air quality and low-fogging interiors drive adipate and sebacate consumption in dashboard and seating applications. REACH Annex XIV authorization deadlines for DEHP and DBP eliminate sunset extensions, forcing immediate reformulation across flooring and wall covering supply chains. The Rhine-Ruhr corridor concentrates qualified compounder capacity, with BASF SE leveraging integrated adipate production to serve medical device manufacturers facing EU MDR migration limits.
United States
FDA guidance under 21 CFR 175.105 and state-level restrictions in California and New York redirect pediatric and neonatal device procurement toward certified citrate alternatives. Construction sealant demand in California accesses water-based emulsion formats to meet VOC regulations. The US Northeast clusters healthcare OEM procurement power, with Eastman Chemical Company anchoring North American supply through non-phthalate portfolios targeting medical-grade specifications.
China
Domestic PVC resin capacity expansion and GB standards alignment with international migration limits accelerate substitution in flooring and consumer goods. NMPA medical device regulations tighten extractables thresholds for imported and locally manufactured products. The Yangtze River Delta concentrates flexible PVC compounding for automotive and construction exports, with local producers scaling adipate production to reduce benzene price volatility exposure.
Brazil
ANVISA import substitution incentives and local PVC resin capacity expansion create procurement redirection toward certified non-phthalate compounders. Medical device localization programs displace European imports in tubing and bag applications. São Paulo state anchors domestic formulation development, with castor oil-derived sebacate production diversifying feedstock origins beyond petrochemical supply chains.
India
BIS standards evolution and CDSCO medical device regulations compress qualification timelines for phthalate alternatives in pharmaceutical packaging. Construction flooring demand in Maharashtra and Gujarat faces reformulation pressure as export-oriented manufacturers align with REACH-equivalent specifications. Domestic sebacic acid production from castor oil in Gujarat reduces import dependence for high-performance plasticizers in automotive wire and cable applications.
Global Non-Phthalate Plasticizers Market Competitive Environment
Concentration sits with integrated petrochemical majors and specialized ester manufacturers serving certification-driven healthcare procurement. The supplier base structures across three tiers: multinational chemical conglomerates with backward integration into acid feedstocks, regional compounders qualified for automotive and construction specifications, and niche biobased specialists leveraging castor oil supply chains. Competitive positioning hardens around pre-certification investments, with qualification documentation for ISO 10993 and REACH SVHC attestation becoming table stakes for healthcare OEM vendor onboarding. Capacity expansion and strategic technology licensing represent the dominant competitive moves, as compounders seek to capture substitution cycles ahead of regulatory deadlines.
Among integrated chemical conglomerates, BASF SE and Eastman Chemical Company exemplify the tier serving medical and automotive certification requirements, while Evonik Industries AG occupies a position within the high-purity citrate specialization segment for pharmaceutical packaging applications. These entities represent archetypes of supplier consolidation around documentation capabilities and feedstock integration rather than commodity volume positioning.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Arkema Inc. |
| Dow Chemical Company |
| Emery Oleochemicals Group |
| ExxonMobil Chemical Company |
| Evonik Industries AG |
| LANXESS AG |
| DIC Corporation |
| Others |
Value Chain & Pricing Dynamics
Castor oil-derived sebacate substitution for petrochemical adipate simultaneously redraws supply geography toward India and Brazil while compressing pricing differentials between bio-based and conventional ester grades. This feedstock diversification forces compounders to recalculate landed cost models as benzene price volatility exposure diminishes for flexible PVC manufacturers.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures across automotive and medical supply chains. Price differentiation stratifies across medical-grade certification tiers, ISO 10993 documentation levels, and volume scale commitments. Cost compression in commodity adipate volumes is intensifying because cyclohexane oxidation feedstock costs fluctuate with benzene pricing. Construction flooring compounders exhibit highest price sensitivity due to thin margins, while pharmaceutical packaging buyers accept premium positioning for REACH SVHC-attested citrate formulations.
Supply Chain Analysis
Gujarat castor oil processing clusters and Rhine-Ruhr petrochemical corridors constitute dual chokepoints for sebacate and adipate feedstock availability. Raw material sourcing draws from cyclohexane oxidation streams, citric acid fermentation batches, and castor oil crushing operations. Single-source vulnerability concentrates in high-purity citrate ester manufacturing clusters across Western Europe. Distribution runs through qualified compounder networks in Germany, the United States, and China, with spot-market access restricted for healthcare OEM procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Pre-certification documentation capabilities for ISO 10993 and REACH SVHC attestation represent the scarcest asset class, excluding uncertified compounders from healthcare OEM vendor onboarding and consolidating procurement power through qualified suppliers in the Rhine-Ruhr corridor and US Northeast.
For Market Incumbents: Compound backward integration into adipic acid production to defend margin stability against cyclohexane oxidation feedstock volatility. Expand capacity in Gujarat and São Paulo to capture castor oil-derived sebacate substitution cycles ahead of REACH Annex XIV authorization deadlines. Certification investment represents the critical lever for excluding emerging regional blenders from medical device tender participation. For New Entrants and Emerging Players: Lead with ANVISA import substitution incentives in Brazilian medical device tubing and bag applications, where local PVC resin capacity expansion creates white space for certified compounders. Target construction sealant emulsion formats in California and Nordic VOC-regulated markets. A go-to-market angle anchored to water-based adhesive formulations bypasses legacy equipment retrofit barriers facing phthalate-to-non-phthalate converters. For Investors and Strategic Acquirers: Capital is best deployed toward mid-cap compounders possessing integrated ester production and existing ISO 10993 documentation libraries. Long-term viability across the projection horizon rests on capturing substitution cycles ahead of regulatory deadlines rather than commodity volume positioning. The signal to watch is ECHA substitution plan submission timelines, which foreshadow delisting velocity for non-compliant product lines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive adipic acid production insulates BASF and Eastman from benzene price volatility exposure. |
| Capacity Expansion | Gujarat and São Paulo sebacate buildout diversifies supply origins beyond petrochemical feedstocks. |
| Green Manufacturing Transition | Castor oil-derived esters align with EU Green Deal bio-based content thresholds for automotive interiors. |
| Long-term Supply Agreement | Healthcare OEMs lock in citrate volumes through REACH SVHC-attested contracts ahead of EU MDR deadlines. |
| Joint Venture | Regional compounders partner with Rhine-Ruhr qualified suppliers to access medical device certification pathways. |
Study Parameters
A spread of perspectives from PVC compounding plant managers, automotive OEM procurement leads, pharmaceutical packaging technical directors, and ECHA regulatory affairs specialists converged on the working assumptions. Secondary validation drew from REACH Annex XIV authorization databases, FDA 21 CFR guidance documents, SEC 10-K chemical segment disclosures, and customs trade data for adipic acid and sebacic acid derivatives. Bottom-up volume modeling triangulated against top-down market sizing across product type and end-use segments.
Segmentation dimensions modeled encompass grade tier (medical, food-contact, industrial), end-use industry (automotive, medical, construction, consumer goods), formulation type (liquid, solid, emulsion, powder), and regional production hub. CAGRs were derived from regression analysis of historical substitution patterns and regulatory deadline compression effects. Industry-specific forecast inputs included EU MDR migration limit implementation schedules and ANVISA import substitution incentive trajectories.
Underlying assumptions cover sustained REACH enforcement without sunset date extensions, with deviation risk concentrated in FDA guidance timeline acceleration or Brazilian real currency volatility affecting castor oil economics. Practitioners should keep alternative scenarios live as ECHA authorization list expansion and NMPA extractables threshold tightening evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Palm Methyl Ester Derivatives Market
Specialty Chemicals
Biobased Propylene Glycol Market
Specialty Chemicals
Europe Sugarcane Wax Market
Specialty Chemicals
Ethyl Cellulose Market
Specialty Chemicals
Zinc Eugenol Market
Specialty Chemicals
Global 1,5-Cyclooctadiene Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
Ricinoleic Acid Market
Specialty Chemicals
Flame-Retardant Synergist Systems with Low Smoke Toxicity Market
Specialty Chemicals
Europe Optical Brighteners Market
Specialty Chemicals
Abierixin Market
Specialty Chemicals
Carnauba Wax Market
Specialty Chemicals
Lanolin Market
Specialty Chemicals
Polyacrylamide Gel Electrophoresis (PAGE) Market
Specialty Chemicals
Structure Directing Agents Market
Specialty Chemicals
Eitelite Market