
 2-Ethylhexyl Acetate Market | 2026-2036
2-Ethylhexyl Acetate Market Size, Share, and Industry Trends Forecast 2026-2036
2-Ethylhexyl Acetate Market Outlook
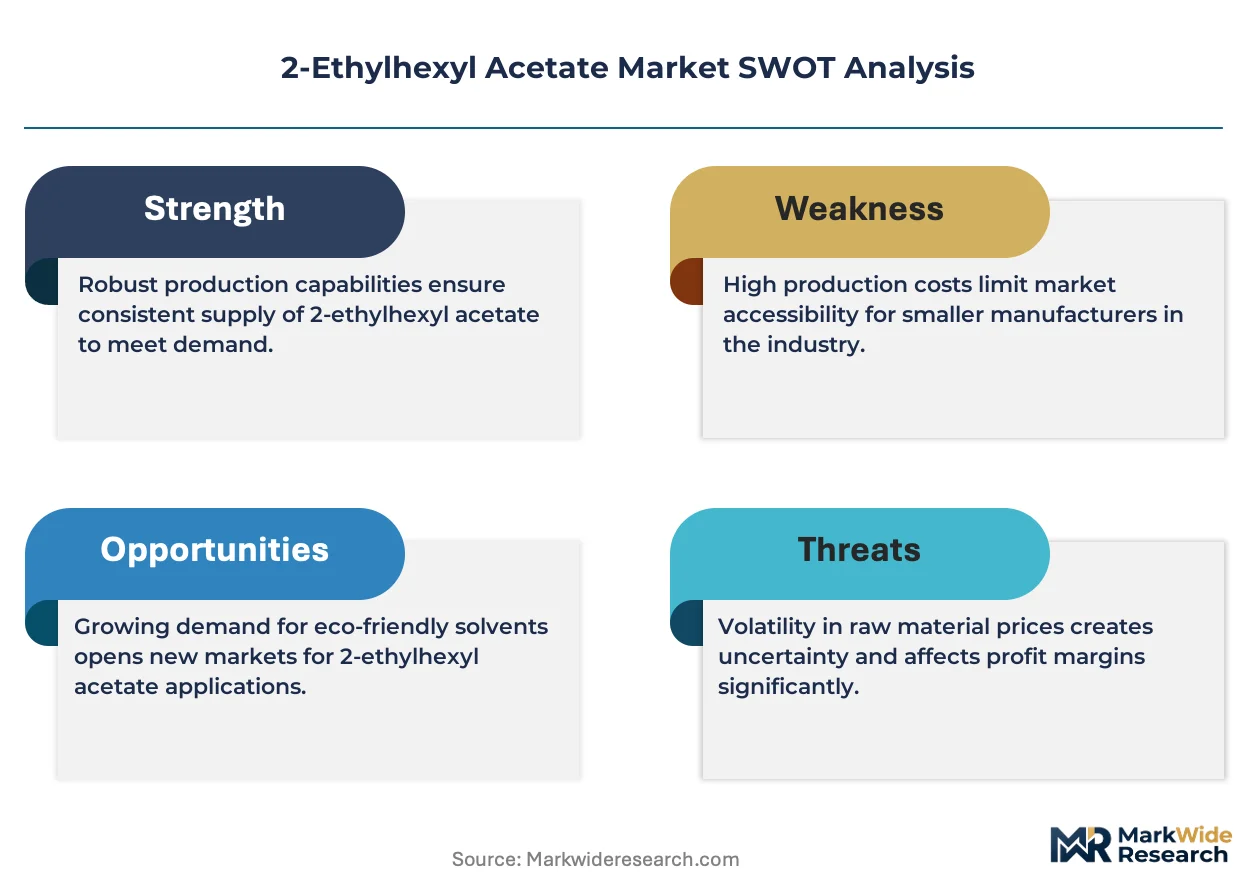
Waterborne polyurethane dispersions is expanding their share in automotive OEM clearcoats, displacing solvent-borne 2-ethylhexyl acetate formulations in premium segments. BASF SE leverages integrated acrylic acid back-integration to stabilize ester feedstock costs across European coating additive lines. Eastman Chemical Company anchors North American supply through Kingsport manufacturing scale, while Polynt SpA specializes in tailored ester blends for Italian industrial coating houses.
2-Ethylhexyl acetate functions as a high-boiling ester solvent with a molecular weight of 172.27 g/mol and a boiling point near 200°C, manufactured via esterification of 2-ethylhexanol with acetic acid. Its primary commercial purpose centers on reducing viscosity in nitrocellulose lacquers and improving flow properties in coil coating formulations. Coatings applications dominate volume throughput due to mature architectural and industrial maintenance demand, while adhesives segments attract margin focus from pressure-sensitive tape producers seeking low-odor, slow-evaporating diluents. Pharmaceutical grade represents a narrower but higher-margin pool tied to excipient qualification protocols.
EPA hazardous air pollutant standards under NESHAP constrain solvent emissions at US coating operations, while REACH registration dossiers in the European Union mandate full toxicological profiles for import volumes exceeding one tonne annually. China's MEE enforces volatile organic compound emission caps at Jiangsu and Shandong chemical parks where ester manufacturing concentrates. Stakeholders must monitor bio-based ester pilot programs and regional carbon border adjustment mechanisms that could restructure cost competitiveness across solvent supply chains.
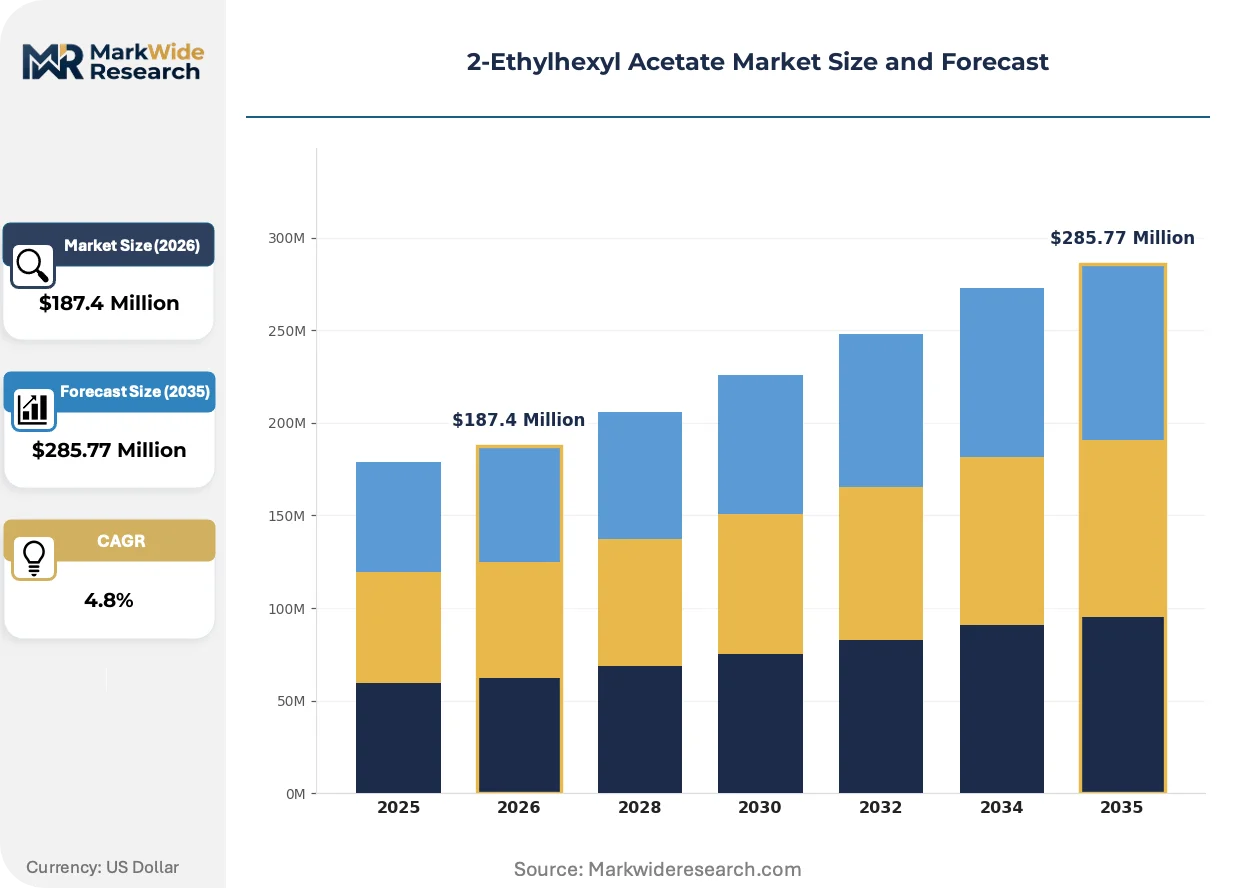
Market Dynamics
Waterborne coating technologies are compressing solvent-grade ester demand in automotive OEM clearcoats while REACH volatile organic compound limits tighten across European formulation houses. This structural tension between regulatory compliance and performance requirements defines current competitive positioning.
Growth Catalysts
- Automotive refinishing recovery:Collision repair volume in Germany drives solvent consumption for high-gloss refinishing lacquers requiring slow-evaporation flow control.
- Pressure-sensitive adhesive expansion:Tape manufacturers specify low-odor ester diluents for medical and electronics bonding applications.
- MEE emission cap enforcement:China's Ministry of Ecology and Environment mandates volatile organic compound reductions at Jiangsu chemical parks, accelerating compliant ester qualification.
Market Restraints
- Acetic acid feedstock volatility:Ester production margins compress when methanol-to-acetic acid spreads widen unpredictably.
- Waterborne polyurethane substitution:Dispersion technologies eliminate solvent requirements in premium automotive OEM segments.
- REACH registration burden:Full toxicological dossiers for import volumes exceeding one tonne annually raise barrier costs for non-EU suppliers.
Strategic Opportunities
- Pharmaceutical excipient qualification:USP-grade ester certification opens higher-margin supply to generic drug manufacturers.
- Bio-based ester pilot scaling:Fermentation-derived 2-ethylhexanol pathways align with EU Green Deal carbon border adjustment mechanisms.
- Coil coating export growth:Middle East infrastructure projects specify high-solids formulations using slow-evaporating ester solvents.
Industry Challenges
- Specialized chemical engineering talent scarcity:Esterification process optimization requires expertise in reactive distillation design that outpaces university pipeline output.
- Multi-jurisdiction compliance synchronization:Formulators must reconcile EPA NESHAP hazardous air pollutant standards with REACH substance restrictions and China's GB emission limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2-Ethylhexyl Acetate Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Solvents, Coatings, Adhesives, Inks End Use Industry: Paints, Automotive, Construction, Cosmetics Grade: Industrial, Pharmaceutical, Food Grade, Cosmetic Grade Packaging Type: Bottles, Drums, Tankers, IBCs |
| Companies Covered | BASF SE, Eastman Chemical Company, Chemoxy International Ltd., Polynt SpA, Dow Chemical Company, Arkema, ExxonMobil Chemical, Huntsman Corporation, Changzhou Xiaqing Technological Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2-Ethylhexyl Acetate Market Strategic Shifts
Formulation chemistry is pivoting toward high-solids and waterborne systems that reduce solvent loading while maintaining film formation properties. This transition is compressing traditional solvent demand curves and forcing ester producers to defend position through specialty grades and geographic diversification.
Waterborne polyurethane dispersions is electrifying automotive OEM clearcoat specifications by eliminating solvent-borne ester requirements in premium vehicle segments. German luxury manufacturers have adopted these systems for basecoat-clearcoat architectures since 2022. The technology is compressing solvent-grade ester volume in the highest-margin coating applications while pushing suppliers toward industrial maintenance and refinish segments.
REACH chemical registration requirements continue tightening volatile organic compound limits across European Union formulation houses. The regulation mandates full substance dossiers including reproductive toxicity endpoints for continued market access. Italian industrial coating houses are responding by qualifying alternative ester blends with lower vapor pressure profiles to maintain compliance.
Specification-driven procurement now dominates coating raw material selection, with automotive OEMs unbundling solvent purchasing from formulation supply agreements. Tier-1 suppliers in China's eastern manufacturing provinces are consolidating qualified vendor lists to three approved ester sources per plant. This concentration is most visible in Jiangsu province where solvent-grade production capacity clusters and buyer power has intensified.
2-Ethylhexyl Acetate Market Segmentation
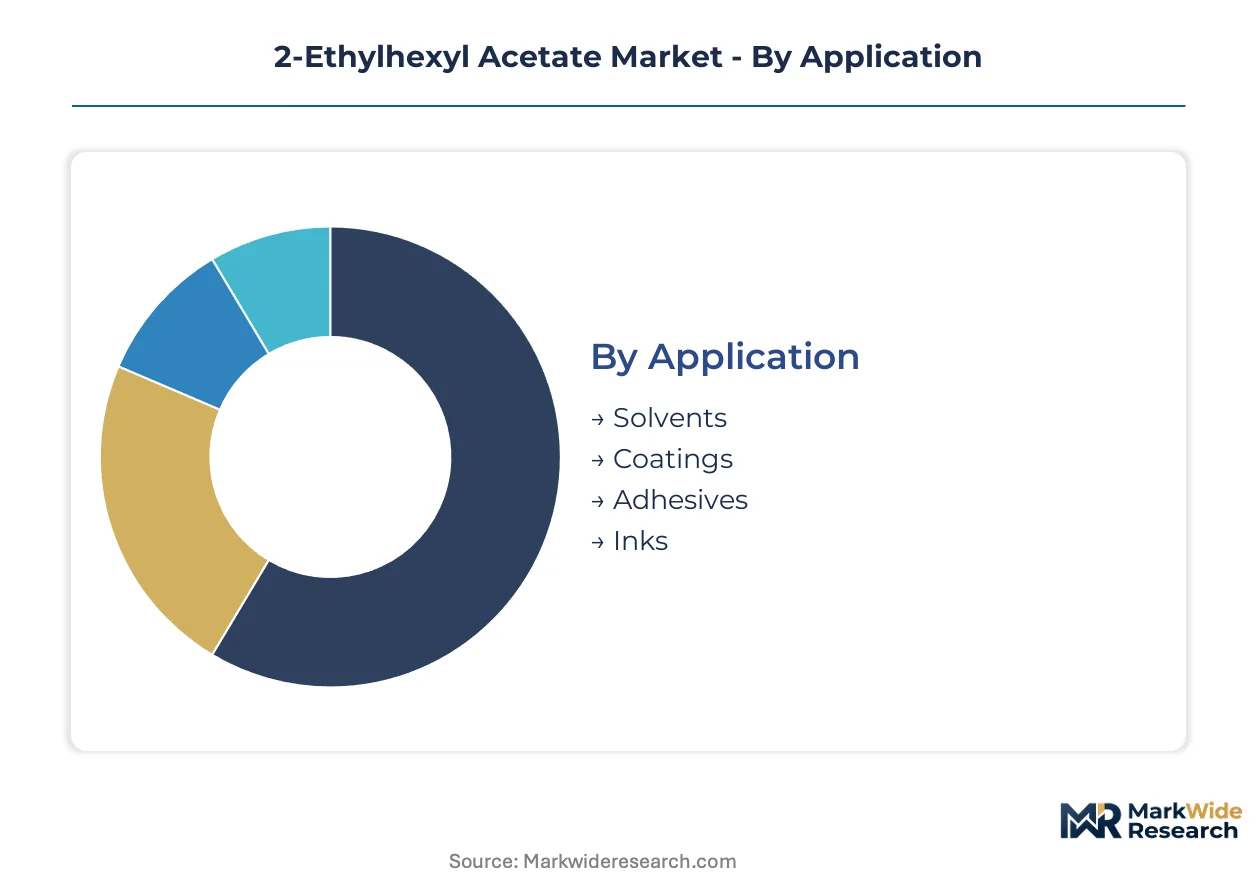
Segmentation in the 2-ethylhexyl acetate market reveals how solvent-grade volumes concentrate in industrial coatings while specialty grades capture margin premiums. Understanding these divisions exposes where feedstock integration and regulatory compliance investments yield differentiated returns.
Application:
Supply concentration in ester manufacturing clusters shapes how application segments compete for qualified output.
- Coatings:Nitrocellulose lacquers and coil coating formulations consume the majority of solvent-grade ester volume, with demand concentrating in German automotive refinishing operations where slow-evaporation flow control commands specification premiums. REACH volatile organic compound limits are compressing solvent loading in premium automotive OEM clearcoats, displacing traditional ester requirements.
- Solvents:High-boiling ester solvents with 200°C boiling points serve as viscosity reducers across architectural and industrial maintenance coatings, with procurement consolidating around three approved vendors per plant in China's Jiangsu province.
- Adhesives:Pressure-sensitive tape manufacturers specify low-odor, slow-evaporating diluents for medical and electronics bonding applications.
- Inks:Publication gravure and flexographic printing formulations utilize ester co-solvents for controlled drying profiles.
Coatings absorbs the bulk of installed capacity; Adhesives is expanding most quickly.
End Use Industry:
Cost tier differentiation separates commodity solvent supply from qualified ester grades commanding certification premiums.
- Paints:Architectural and industrial maintenance coatings drive mature volume throughput, with specification-driven procurement unbundling solvent purchasing from formulation supply agreements.
- Automotive: Collision repair volume in Germany sustains solvent consumption for high-gloss refinishing lacquers, while waterborne polyurethane dispersions eliminate ester requirements in OEM clearcoats.
- Construction:Coil coating exports to Middle East infrastructure projects specify high-solids formulations using slow-evaporating ester solvents.
- Cosmetics:Fragrance and personal care applications utilize refined ester grades meeting odor and purity thresholds.
Paints commands the largest share of qualified supply; Automotive faces the steepest substitution pressure.
Grade:
Margin stratification across certification tiers rewards upstream investment in purification and qualification protocols.
- Industrial:Standard solvent-grade esters serve coatings and adhesives applications where specification compliance centers on boiling range and moisture content rather than trace impurity profiles.
- Pharmaceutical:USP-grade certification opens higher-margin supply to generic drug manufacturers requiring excipient qualification protocols with full toxicological dossiers.
- Food Grade:Flavor and fragrance applications demand ester purity meeting food contact regulatory standards.
- Cosmetic Grade:Personal care formulations require low-odor profiles and documented absence of sensitizing impurities.
Industrial grade dominates volume throughput; Pharmaceutical grade offers the steepest margin expansion trajectory.
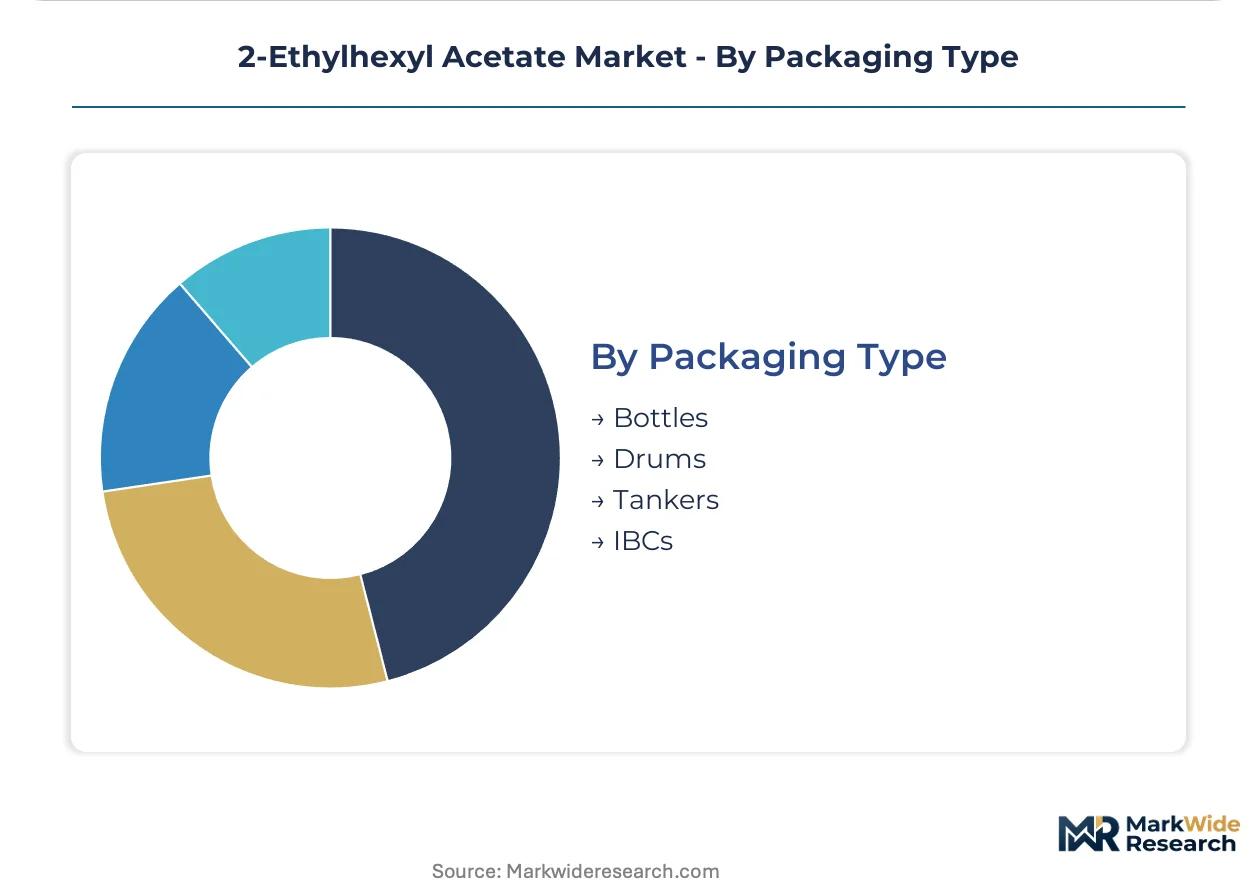
Packaging Type:
Customer type and order scale determine packaging configuration, with bulk formats serving integrated formulators and smaller units addressing specialty distributors.
- Tankers:Large-volume coating manufacturers receive bulk ester deliveries direct from production facilities, minimizing handling costs and contamination risk.
- Drums:Mid-scale industrial coating houses and adhesive compounders source 200-liter units for flexible inventory management.
- IBCs:Intermediate bulk containers serve regional formulators requiring ton-scale deliveries without tanker access.
- Bottles:Laboratory and pilot-scale users procure liter-scale quantities for formulation development and qualification testing.
Tankers moves the greatest absolute volume; IBCs is gaining share fastest among mid-tier formulators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for 2-ethylhexyl acetate concentrates in automotive refinishing clusters and industrial coating corridors across Germany, China, and the United States, with regulatory pressure on volatile organic compound emissions reshaping regional supply requirements.
Germany
Collision repair volume in Bavaria and Baden-Württemberg sustains solvent consumption for high-gloss refinishing lacquers requiring slow-evaporation flow control. REACH registration dossiers mandate full toxicological profiles including reproductive toxicity endpoints for continued market access. Stuttgart's automotive OEM supplier ecosystem drives specification-driven procurement unbundling solvent purchasing from formulation agreements.
China
Jiangsu and Shandong chemical parks host concentrated solvent-grade production capacity serving eastern manufacturing provinces. MEE emission caps enforce volatile organic compound reductions at production facilities, accelerating compliant ester qualification protocols. Shanghai's coating formulators consolidate qualified vendor lists to three approved ester sources per plant.
United States
Pressure-sensitive adhesive manufacturers in the Southeast specify low-odor ester diluents for medical and electronics bonding applications. EPA NESHAP hazardous air pollutant standards constrain solvent emissions at coating operations across industrial corridors. Texas Gulf Coast petrochemical integration supports acetic acid feedstock availability for regional ester production.
Italy
Industrial coating houses in Lombardy and Emilia-Romagna qualify alternative ester blends with lower vapor pressure profiles to maintain REACH compliance. Polynt SpA specializes in tailored ester formulations for regional automotive and furniture coating segments. Milan's formulation clusters prioritize low-odor specifications for interior architectural applications.
Japan
Automotive OEM clearcoat specifications in the Nagoya industrial corridor increasingly specify waterborne polyurethane dispersions, compressing solvent-grade ester volume in premium segments. METI guidelines on chemical substance management influence supplier qualification protocols. Osaka-based electronics adhesive producers drive demand for ultra-low moisture content ester grades.
2-Ethylhexyl Acetate Market Competitive Environment
Capacity expansion dominates the current landscape as producers defend position against waterborne substitution pressure. The vendor base stratifies across three tiers: integrated petrochemical majors with captive acetic acid supply, regional ester specialists serving qualified formulation houses, and Asian manufacturers competing on solvent-grade volume. Strategic archetypes include feedstock-integrated producers, specialty ester blenders, and export-oriented commodity suppliers. Competitive moves center on backward integration into acrylic acid value chains and geographic diversification toward Middle East coil coating growth corridors.
Among European-integrated chemical majors, BASF SE anchors the feedstock-integrated tier through its Ludwigshafen acrylic acid back-integration, while Polynt SpA exemplifies the specialty blending archetype serving Italian industrial coating houses. Eastman Chemical Company represents North American manufacturing scale through its Kingsport production base. These three entities occupy positions spanning the value chain from commodity solvent supply to qualified pharmaceutical-grade certification.
| Leading Market Players |
|---|
| BASF SE |
| Eastman Chemical Company |
| Chemoxy International Ltd. |
| Polynt SpA |
| Dow Chemical Company |
| Arkema |
| ExxonMobil Chemical |
| Huntsman Corporation |
| Changzhou Xiaqing Technological Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Acetic acid feedstock volatility cascades through the 2-ethylhexyl acetate supply chain into three distinct pricing tiers: pharmaceutical-grade USP certification commands substantial premiums over industrial solvent grades, while spot-market solvent volumes trade at compressed margins tethered to methanol-to-acetic acid spreads. This cost-pass-through structure concentrates pricing power among backward-integrated producers with captive acrylic acid supply, leaving merchant ester houses exposed to margin compression during feedstock spikes.
Pricing Analysis
Volume throughput concentrates in industrial solvent grades while margin capture concentrates in pharmaceutical and cosmetic certification tiers. Price differentiation hinges on USP-grade excipient qualification versus standard solvent specifications, with odor-profile testing and moisture-content thresholds separating tiers. Pricing pressure stems from waterborne polyurethane substitution in automotive OEM clearcoats, compressing solvent-grade realizations. Mid-scale adhesive compounders exhibit highest price sensitivity due to unbundled procurement practices, while pharmaceutical generic manufacturers accept premium pricing for qualified excipient supply security.
Supply Chain Analysis
Direct-to-coating-manufacturer channels handle hyperscale buyer demand through dedicated tanker deliveries from Jiangsu and Shandong production clusters. Raw material flows draw from Texas Gulf Coast acetic acid supply, Ludwigshafen integrated acrylic acid streams, and East Asian methanol feedstock. Geographic supply concentration in China's eastern chemical parks and Germany's Ludwigshafen hub creates single-source vulnerability for European formulation houses. Distribution runs through qualified vendor lists consolidated to three approved sources per plant, with IBC formats gaining share among mid-tier regional formulators lacking tanker access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The 2-ethylhexyl acetate market sits in a technology-transition phase as waterborne polyurethane dispacements displace solvent-borne ester requirements across premium automotive OEM segments. Incumbents must navigate this substitution pressure while defending position in refinish and industrial maintenance applications where slow-evaporation flow control remains specification-critical.
For Market Incumbents: Extend pharmaceutical-grade certification investments to capture generic drug manufacturer demand as waterborne substitution erodes automotive OEM solvent volumes. Prioritize backward integration into acrylic acid value chains to stabilize feedstock cost exposure against methanol volatility. Defend coil coating supply relationships in Middle East infrastructure corridors where high-solids formulations sustain slow-evaporating ester demand. For New Entrants and Emerging Players: REACH volatile organic compound limits in the European Union open a window for bio-based ester pilot programs aligned with carbon border adjustment mechanisms. Target pharmaceutical excipient qualification as the most penetrable segment, where USP-grade certification barriers deter commodity competitors. Pursue fermentation-derived 2-ethylhexanol pathways with Italian industrial coating houses seeking lower vapor pressure alternative blends. For Investors and Strategic Acquirers: Distressed-cycle entries favor specialty ester blenders with established REACH dossiers in Lombardy and Emilia-Romagna formulation clusters. Long-term viability hinges on positioning upstream of waterborne substitution through pharmaceutical-grade margin capture. Monitor MEE enforcement intensity at Jiangsu chemical parks as an inflection indicator for compliant supply scarcity premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Acid | BASF SE's Ludwigshafen captive supply stabilizes ester feedstock costs against methanol volatility. |
| Pharmaceutical Grade Certification | USP-grade excipient qualification opens higher-margin supply to generic drug manufacturers. |
| Bio-based Ester Pilot Scaling | Fermentation-derived pathways align with EU Green Deal carbon border adjustment mechanisms. |
| Coil Coating Export Expansion | Middle East infrastructure projects specify high-solids formulations using slow-evaporating ester solvents. |
| Qualified Vendor List Consolidation | Shanghai formulators restrict supply to three approved sources per plant, intensifying buyer power. |
Study Parameters
Multi-period observation of acetic acid feedstock spreads, REACH registration dossier filings, and MEE emission cap enforcement anchored the trend analysis, supplemented by interviews with plant managers at Jiangsu chemical parks, procurement leads at German automotive refinishing operations, and technical R&D directors at Italian industrial coating houses. Secondary validation drew from customs and trade data, Cefic solvent market reports, SEC 10-K chemical segment disclosures, and EPA NESHAP compliance filings. Bottom-up volume modeling triangulated against top-down value estimates across grade tiers and end-use industries.
Segment-weighting approaches applied differential growth assumptions across pharmaceutical, industrial, cosmetic, and food-grade certification tiers, with coatings versus adhesives versus solvents application splits modeled separately. End-use industry segmentation incorporated paints, automotive, construction, and cosmetics demand trajectories. CAGRs derived from regression analysis of historical volume trends adjusted for waterborne substitution elasticities and regulatory compliance cost pass-through rates. Coil coating export flows and pressure-sensitive adhesive expansion rates served as industry-specific forecast inputs.
The model assumes a particular technology adoption path for waterborne polyurethane dispersions in automotive OEM clearcoats; alternative pathways for high-solids solvent-borne formulations would alter the outlook for solvent-grade ester demand. Forecasts reflect assumptions regarding REACH volatile organic compound limit progression and MEE enforcement consistency. Practitioners should monitor bio-based ester pilot scale-up rates and carbon border adjustment mechanism implementation timing for early signals of competitive cost structure shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Global Specialty Oleochemicals Market
Oleochemicals
Glycerol Esters of Wood Rosins Market
Oleochemicals
Narrow Range Ethoxylates Market
Oleochemicals
Hydrocarbon Waxes Market
Oleochemicals
Asia-Pacific Wax Market
Oleochemicals
Disodium Oleamido MIPA Sulfosuccinate Market
Oleochemicals
Oleochemicals Market
Oleochemicals
Isodecyl Neopentanoate Market
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Isostearic Acid Market
Oleochemicals
White Mineral Oil Market
Oleochemicals
Glycerine Market
Oleochemicals
Asia-Pacific Oleochemicals Market
Oleochemicals
Europe Arachidonic Acid Market
Oleochemicals
Fatty Acid Amides Market
Oleochemicals
Isopropyl Esters Market