
 APAC Occupancy Sensors Market | 2026-2036
APAC Occupancy Sensors Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Occupancy Sensors Market Outlook
GB/T 50378 green building certification timelines is collapsing procurement windows for non-compliant vendors. Schneider Electric SE leverages its integrated building management stack to dominate premium commercial tenders across Southeast Asian capitals. Signify Holding BV sustains R&D intensity in connected lighting-occupancy convergence, while Johnson Controls Inc anchors its position through deep channel relationships with regional system integrators.
APAC occupancy sensors are electromechanical or solid-state devices detecting human presence through infrared, ultrasonic, or acoustic wave detection, typically operating at detection ranges of 5-30 meters with response latencies under 500 milliseconds to automate lighting, HVAC, and security subsystems. Passive Infrared sensors occupy the largest installed base due to cost parity and mature supply chains, though Dual Technology units are capturing margin pools in high-security institutional settings where false-trigger immunity commands price premiums. Wireless connectivity is displacing wired architectures in retrofit-heavy markets, while Smart technology segments are concentrating vendor R&D spend as edge-computing capability becomes a discriminator in enterprise tenders.
China's GB standards and India's BEE labeling program are mandating minimum sensor efficacy thresholds that filter out uncertified imports, while Japan's METI energy conservation directives are accelerating replacement cycles in existing building stock. Australia's NCC Section J compliance pathway for commercial buildings is creating specification pull-through for ceiling-mounted integrated systems in new construction. Stakeholders must monitor divergence between national electromagnetic compatibility regimes and the interoperability claims of emerging dual-band platforms before committing to multi-country deployment architectures.
Market Dynamics
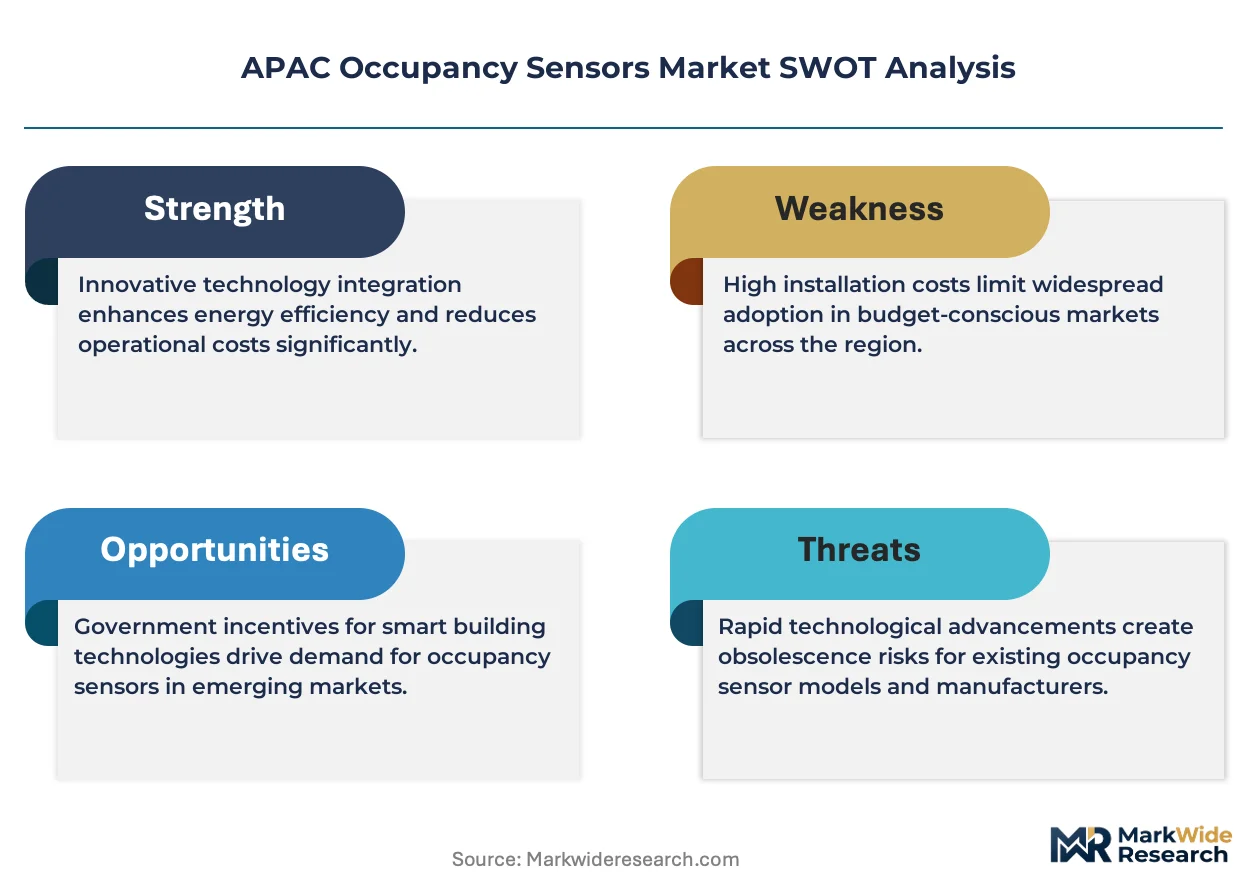
Wireless retrofit architectures are compressing replacement cycles across Australia's premium commercial stock and India's green-certified construction pipeline, while national electromagnetic compatibility regimes fragment procurement standardization.
Growth Catalysts
- India's BEE labeling program:Mandatory minimum sensor efficacy thresholds filter uncertified imports and accelerate certified hardware procurement in commercial new-builds.
- Smart building retrofits:Japan's METI energy conservation directives compress replacement timelines in existing office stock across Tokyo and Osaka metropolitan clusters.
- Dual Technology sensors:False-trigger immunity commands price premiums in high-security institutional settings across South Korean government and healthcare facilities.
Market Restraints
- Input cost volatility:Rare earth element pricing instability for infrared detection components compresses margin pools in Passive Infrared manufacturing.
- Supply concentration risk:Semiconductor foundry capacity constraints in Taiwan bottleneck sensor controller chip availability for regional OEMs.
- Regulatory friction:Divergent electromagnetic compatibility regimes between China's GB standards and Australia's ACMA requirements complicate multi-country deployment architectures.
Strategic Opportunities
- Underpenetrated tier-2 Indian cities:Green building certification penetration in Pune, Hyderabad, and Chennai lags Mumbai-Delhi corridors, creating specification whitespace.
- Edge-computing convergence:On-device processing capability integration with acoustic wave detection opens enterprise tender differentiation beyond basic presence sensing.
- Australia's NCC Section J pathway:Commercial building compliance mandates pull through ceiling-mounted integrated systems in Melbourne and Brisbane new construction.
Industry Challenges
- Integration complexity:BACnet and KNX protocol interoperability gaps between legacy building management systems and dual-band wireless platforms delay project commissioning.
- Certification timeline compression:China's collapsing GB/T 50378 green building procurement windows strain vendor testing and documentation throughput.
- Skill gap in commissioning:Shortage of certified systems integrators capable of ultrasonic-infrared hybrid calibration extends project handover schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Occupancy Sensors Market |
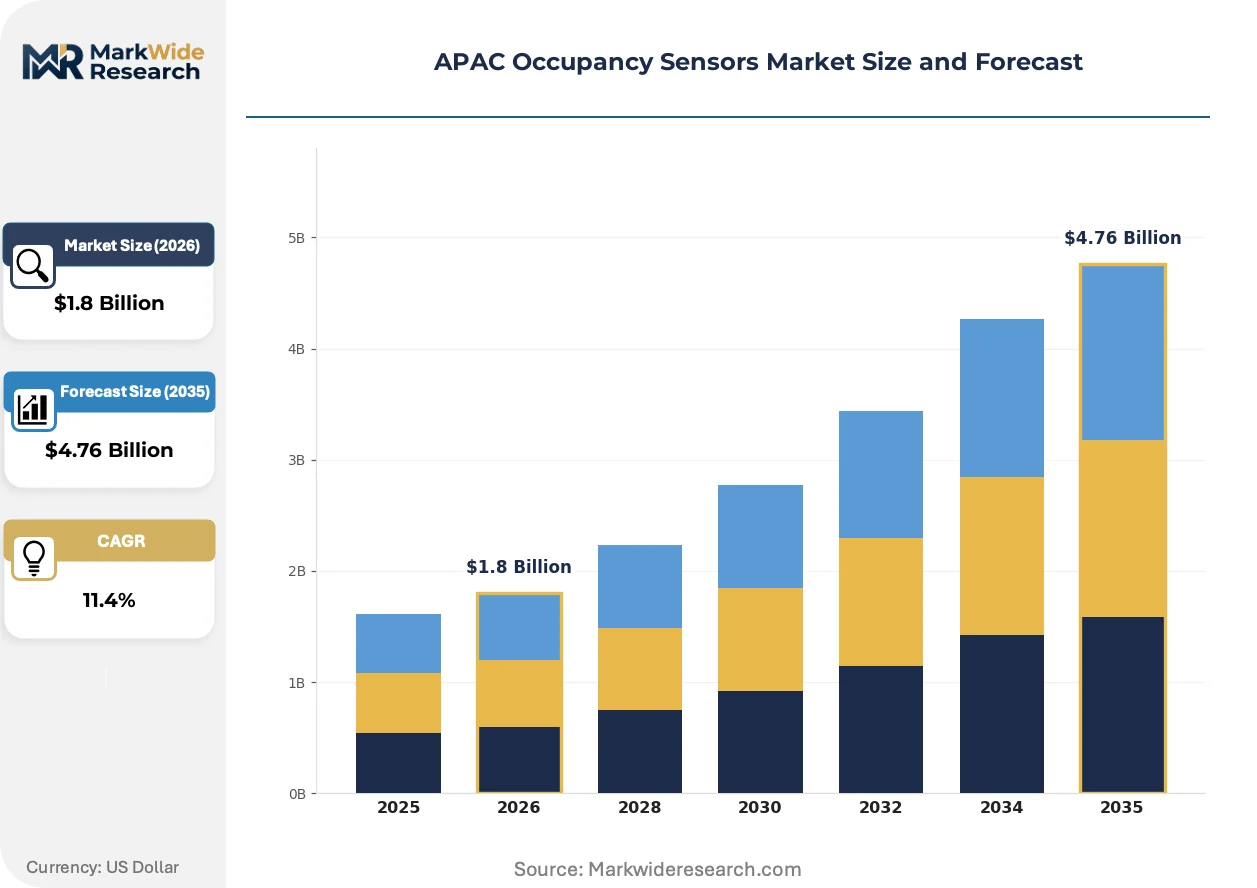
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Passive Infrared, Ultrasonic, Dual Technology, Microphonic End User: Commercial, Residential, Industrial, Institutional Installation Type: Wall-mounted, Ceiling-mounted, Desktop, Integrated Technology: Wired, Wireless, Smart, Dual-band |
| Companies Covered | Schneider Electric SE, Signify Holding BV, Texas Instruments Inc, Honeywell Inc, Johnson Controls Inc, Eaton Corp PLC, General Electric Co, Legrand SA, Analog Devices Inc, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Occupancy Sensors Market Strategic Shifts
Edge-native processing capability is fragmenting competitive positioning away from hardware cost toward software-defined detection algorithms, while regulatory tightening and procurement model evolution reshape vendor-customer relationships.
Machine learning inference at the sensor node is fragmenting the traditional architecture where raw detection data streams to centralized building management systems. Premium commercial developers in Singapore and Sydney specify on-device pattern recognition for occupancy counting and predictive HVAC load balancing. This capability compression enables tier-2 sensor vendors to compete on algorithm performance rather than manufacturing scale alone.
China's MIIT cybersecurity certification for IoT building devices imposes encryption and firmware update mandates on wireless sensor platforms. The regulation's industrial consequence is disqualification of uncertified imports from state-affiliated procurement channels. Smart office deployments in Shanghai and Shenzhen now specify domestic-certified hardware exclusively, redirecting tender flows toward compliant regional suppliers.
Facility managers increasingly unbundle sensor hardware from long-term maintenance contracts, compressing vendor recurring revenue streams. Australia's premium commercial stock leads this disintermediation, with property groups self-managing wireless mesh networks through in-house engineering teams. The shift concentrates pricing pressure on initial equipment margins while elevating firmware update and cybersecurity patch services as discrete procurement categories.
APAC Occupancy Sensors Market Segmentation
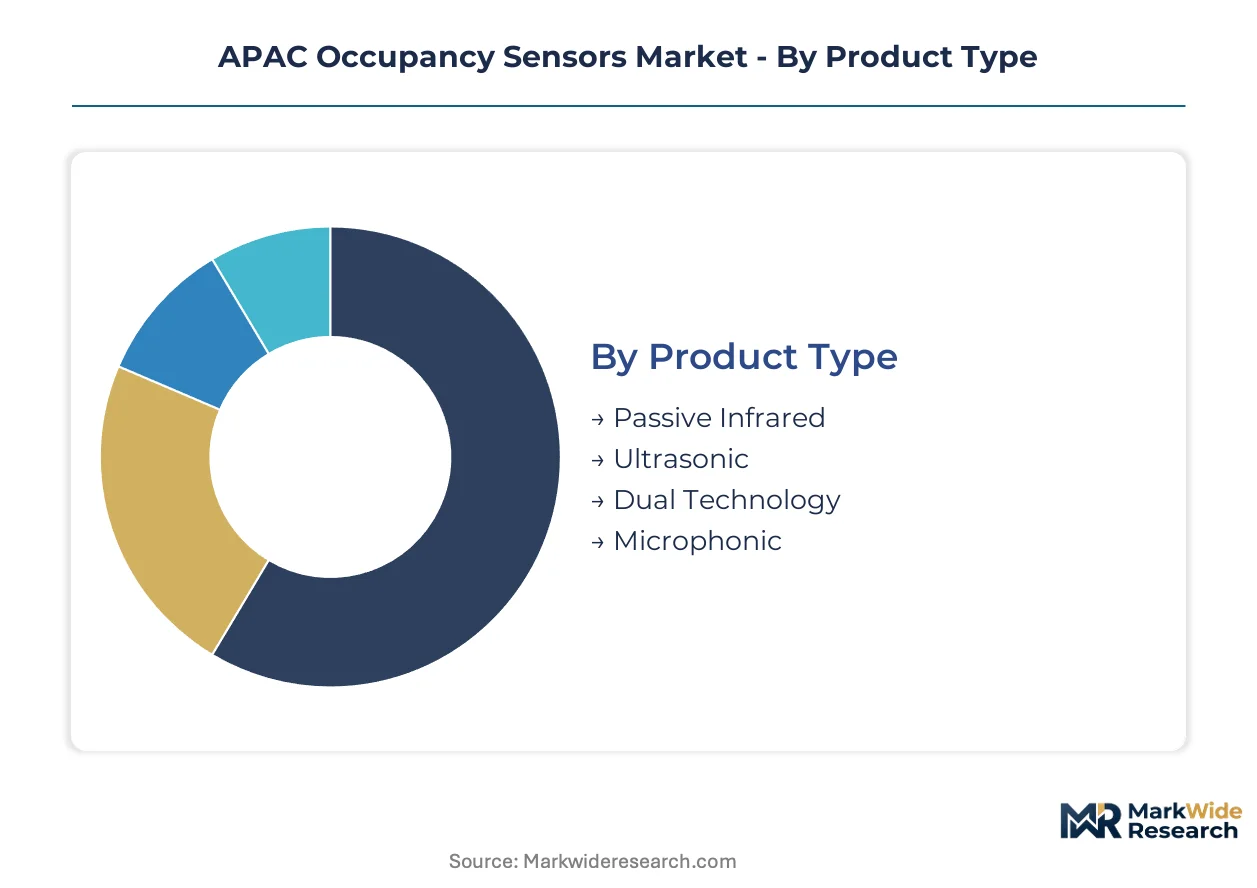
Segmentation in the APAC occupancy sensors market reveals how regulatory fragmentation and retrofit economics split procurement patterns across technology tiers. India's BEE labeling and China's GB standards create divergent compliance pathways that reshape product mix by installation environment and connectivity architecture.
Product Type:
India's Bureau of Energy Efficiency mandates and China's GB standards for intelligent building controls apply differential efficacy thresholds across detection technologies, filtering import eligibility by certification status.
- Passive Infrared:Solid-state pyroelectric detectors sense body heat through differential infrared measurement, typically spanning 5-12 meter coverage zones with sub-500 millisecond response latencies. Demand concentrates in India's commercial new-builds where BEE labeling mandates minimum efficacy thresholds that favor mature, certified supply chains. Established volume favors Passive Infrared; emerging adoption favors Dual Technology.
- Dual Technology:Hybrid infrared-ultrasonic architectures cross-validate presence signals to eliminate false triggers in high-security environments. South Korean government and healthcare facilities in Seoul command price premiums for false-trigger immunity in access-controlled zones. Australia's premium commercial stock specifies these units for lobby and elevator bank applications where detection reliability outweighs hardware cost.
- Ultrasonic:Acoustic wave emission and echo analysis detects motion through Doppler shift, effective in line-of-sight obstructed environments.
- Microphonic:Ambient sound pattern recognition identifies occupancy through footfall and activity signatures without optical components.
Passive Infrared anchors installed base economics; Dual Technology captures security-premium segments.
End User:
Customer procurement sophistication varies sharply by asset class, with institutional buyers demanding predictive maintenance integration and residential channels prioritizing plug-and-play simplicity.
- Commercial:Office towers and retail complexes in Tokyo, Sydney, and Singapore specify networked sensor arrays with BACnet protocol integration for centralized HVAC load balancing. Japan's METI energy conservation directives compress replacement timelines in existing Osaka and Tokyo metropolitan office stock.
- Institutional:Government facilities, hospitals, and educational campuses require hardened detection with audit-grade occupancy logging. South Korean healthcare procurement mandates dual-validation architectures for patient safety zones.
- Residential:Smart home integration in Australian and Japanese urban apartments drives demand for compact, battery-operated units with consumer-grade app interfaces.
- Industrial:Warehousing and manufacturing floors specify dust-resistant housings with extended detection ranges for high-bay ceiling mounting.
Commercial buyers dominate volume throughput; institutional contracts deliver margin concentration.
Installation Type:
Retrofit versus new-build dynamics split hardware form factors, with wireless retrofit demand compressing replacement cycles in Australia's premium commercial stock.
- Ceiling-mounted:Recessed and surface-mount housings integrate with suspended tile systems for 360-degree coverage in open-plan environments. Australia's NCC Section J compliance pathway for commercial buildings pulls through integrated ceiling systems in Melbourne and Brisbane new construction.
- Wall-mounted:Corner and switch-replacement configurations serve corridor and private office applications with directional detection patterns.
- Integrated:Luminaire-embedded sensors merge detection with LED driver control, eliminating separate hardware procurement.
- Desktop:Portable, USB-powered units serve hot-desking and co-working spaces with temporary occupancy zoning.
Ceiling-mounted systems capture new construction specification; wall-mounted units dominate retrofit replacement.
Technology:
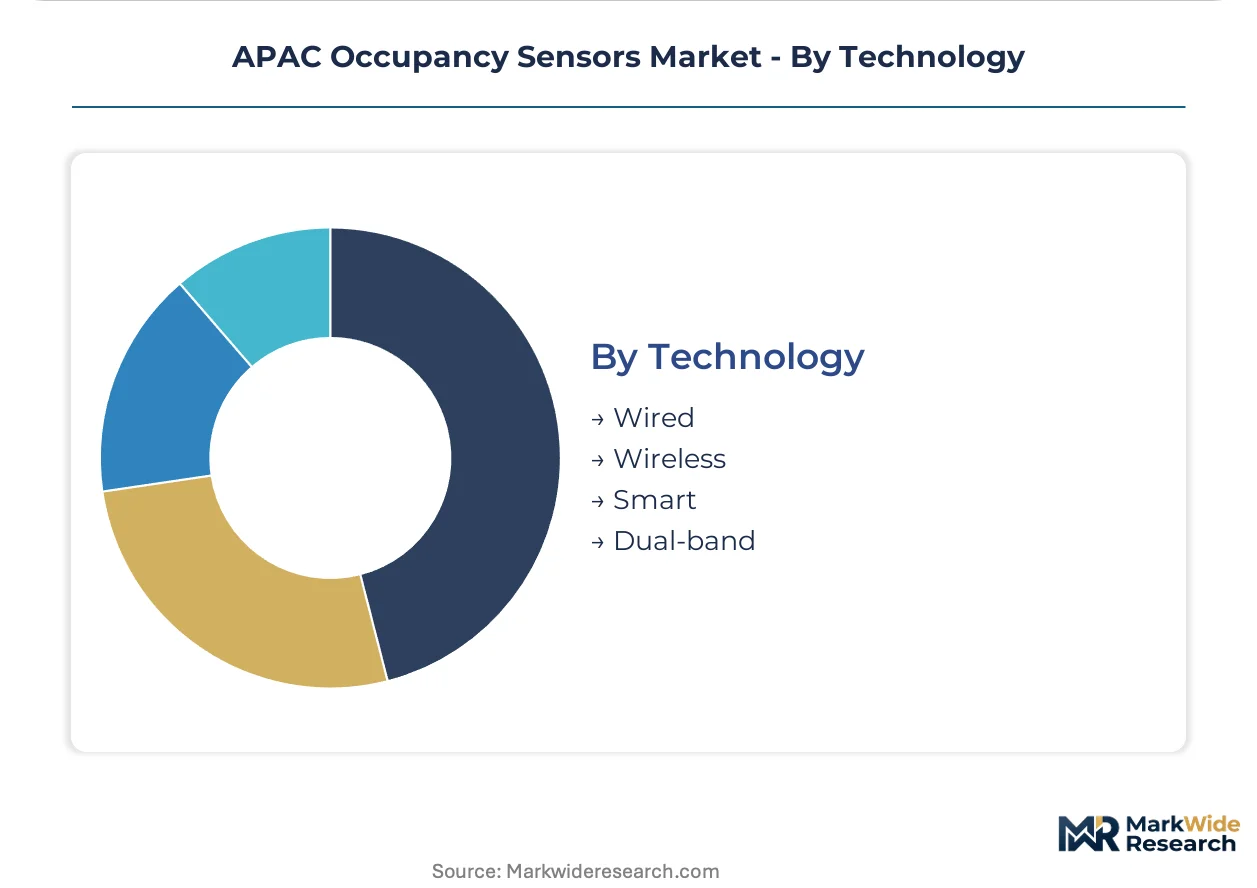
Connectivity architecture selection determines cybersecurity compliance scope, with China's MIIT certification mandates disqualifying uncertified wireless imports from state-affiliated procurement channels.
- Smart:Edge-native processing enables on-device pattern recognition for occupancy counting and predictive HVAC load balancing without centralized data streaming. Premium commercial developers in Singapore and Sydney specify these capabilities for enterprise tender differentiation.
- Wireless:Mesh network protocols eliminate conduit installation in retrofit-heavy markets. India's green-certified new construction pipeline concentrates demand for battery-operated and energy-harvesting architectures.
- Wired:PoE and low-voltage hardwired connections persist in new construction where electromagnetic compatibility certification costs amortize across project scale.
- Dual-band:Concurrent sub-GHz and 2.4 GHz operation addresses interoperability gaps between legacy building management systems and emerging wireless platforms.
Smart technology segments concentrate vendor R&D spend; wireless architectures gain share fastest in retrofit-dominant geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial property developers and institutional facility managers concentrate procurement authority across metropolitan clusters in China, Japan, India, South Korea, and Australia. Each geography applies distinct regulatory filters that reshape vendor eligibility and technology specifications.
China
State-affiliated smart building deployments in Shanghai and Shenzhen drive specification volumes for MIIT-certified wireless platforms. GB/T 50378 green building certification timelines compress vendor testing windows, disqualifying uncertified imports from procurement channels. The Yangtze River Delta corridor anchors domestic manufacturing scale for sensor controller chips.
Japan
Tokyo and Osaka metropolitan office stock generates retrofit replacement cycles for networked ceiling-mounted systems. METI energy conservation directives mandate efficacy thresholds that accelerate hardware refresh in existing commercial buildings. Kansai region facility managers specify BACnet-integrated arrays for centralized HVAC optimization.
India
Bureau of Energy Efficiency labeling mandates filter import eligibility in Mumbai and Delhi commercial new-builds. Green-certified construction pipelines in Pune, Hyderabad, and Chennai create specification whitespace for wireless battery-operated architectures. National electromagnetic compatibility requirements diverge from neighboring markets, complicating multi-country deployment strategies.
South Korea
Seoul government and healthcare procurement mandates dual-validation infrared-ultrasonic hybrids for patient safety zones. False-trigger immunity commands price premiums in access-controlled institutional environments. Busan-Ulsan manufacturing corridors supply pyroelectric detector components to regional OEMs.
Australia
NCC Section J compliance pathways pull through ceiling-integrated systems in Melbourne and Brisbane new construction. Premium commercial property groups in Sydney self-manage wireless mesh networks, compressing vendor recurring revenue streams. ACMA electromagnetic requirements fragment standardization with Asian certification regimes.
APAC Occupancy Sensors Market Competitive Environment
Player mix skews toward diversified industrial conglomerates with building management system integration capabilities, supplemented by specialized lighting-electronics hybrid vendors and semiconductor component suppliers. Strategic archetypes separate into integrated platform providers, connectivity-focused specialists, and sensor component fabricators. Competitive moves concentrate on strategic partnerships with regional systems integrators and portfolio diversification into edge-computing-enabled detection platforms.
Within the integrated platform tier, Schneider Electric SE and Johnson Controls Inc occupy positions exemplifying deep channel relationships with regional system integrators across Southeast Asian capitals. Signify Holding BV represents the lighting-convergence archetype, anchoring R&D intensity in connected detection platforms. These three entities illustrate how vendor-customer relationships reshape around software-defined detection algorithms and unbundled maintenance contract structures.
| Leading Market Players |
|---|
| Schneider Electric SE |
| Signify Holding BV |
| Texas Instruments Inc |
| Honeywell Inc |
| Johnson Controls Inc |
| Eaton Corp PLC |
| General Electric Co |
| Legrand SA |
| Analog Devices Inc |
| Others |
Value Chain & Pricing Dynamics
China's MIIT cybersecurity certification gates both vendor qualification and price stratification simultaneously, compressing margins for uncertified imports while enabling domestic suppliers to command premiums on compliant wireless platforms. This regulatory filter reshapes procurement economics across state-affiliated smart building deployments in Shanghai and Shenzhen.
Pricing Analysis
Cost-plus contracts with rare earth element indexation dominate Passive Infrared manufacturing agreements, transferring input volatility risk to buyers. Three-tier pricing structure across premium, standard, and economy levels separates Dual Technology units with false-trigger immunity from basic infrared detectors. Pricing pressure stems from facility managers unbundling hardware from maintenance contracts in Australia's premium commercial stock. Residential channels exhibit highest price sensitivity; institutional buyers in South Korean healthcare tolerate premiums for audit-grade logging capabilities.
Supply Chain Analysis
Strategic stockpiling of pyroelectric detector components prevails over just-in-time approaches among Japanese and South Korean OEMs confronting Taiwan semiconductor foundry bottlenecks. Manufacturing concentrates in China, Taiwan, and South Korea for sensor controller chips and infrared detection elements. Supply chains draw from rare earth processors in Inner Mongolia and pyroelectric crystal growers in Osaka. Single-source vulnerability in 12-inch wafer capacity threatens regional OEM output. Distribution runs through building management system integrators and electrical wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart building retrofits across Tokyo and Sydney signal early-cycle expansion with substantial runway in green-certified construction penetration. Wireless retrofit architectures compress replacement timelines while expanding addressable building stock.
For Market Incumbents: Fortify channel control through exclusive arrangements with certified systems integrators in Southeast Asian capitals. Deepen firmware update service capabilities as property groups in Sydney self-manage wireless mesh networks. Vertical integration into edge-computing chip design protects margin pools from algorithm commoditization.
For New Entrants and Emerging Players: Differentiate on acoustic wave detection with on-device machine learning inference for occupancy counting. Target green-certified new construction pipelines in Pune, Hyderabad, and Chennai where specification whitespace lags Mumbai-Delhi corridors. Pursue direct procurement relationships with tier-2 Indian commercial developers bypassing incumbent distributor networks.
For Investors and Strategic Acquirers: China's collapsing GB/T 50378 certification timelines reshape the acquisition landscape toward vendors with accelerated testing throughput. Five-to-ten year viability favors regional suppliers with MIIT-compliant wireless platforms and domestic manufacturing scale. Monitor BEE labeling mandate expansion into tier-2 Indian cities as inflection indicator for volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Computing Platform Integration | On-device pattern recognition differentiates tenders from Singapore premium developers. |
| MIIT Certification Acceleration | Cybersecurity compliance unlocks state-affiliated procurement channels in Shanghai and Shenzhen. |
| Systems Integrator Partnership | Deep channel relationships with regional integrators anchor project specification authority. |
| Dual Technology R&D Expansion | False-trigger immunity captures price premiums in South Korean government healthcare tenders. |
| Wireless Mesh Network Service | Unbundled maintenance contracts elevate firmware update services as discrete revenue category. |
Study Parameters
A spread of perspectives from building automation engineers, facility management directors, electrical contracting procurement leads, and green building certification consultants converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation against customs records, Bureau of Energy Efficiency labeling databases, METI energy conservation directive filings, and NCC Section J compliance documentation. Bottom-up unit economics triangulated against top-down construction pipeline valuations.
Segmentation dimensions modeled span detection technology, connectivity architecture, installation environment, and end-user sophistication across the projection horizon. CAGRs derive from installed base replacement velocity and new construction specification capture rates. Forecast inputs incorporate green building certification pipeline data and semiconductor foundry capacity utilization indicators.
The analysis sits within stated boundaries; outcomes outside sustained regulatory tightening on electromagnetic compatibility would require recalibration. Forecasts reflect assumptions on wireless retrofit adoption curves and rare earth element supply stability. Revision becomes warranted when BEE labeling mandate enforcement crosses thresholds affecting import eligibility.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Surface Acoustic Wave Sensors Market
Sensors and Controls
In-Display Fingerprint Sensors Market
Sensors and Controls
Smart Pressure Sensors Market
Sensors and Controls
Thermo Hygrometer Market
Sensors and Controls
Nano Positioning System Market
Sensors and Controls
Global Acceleration and Yaw Rate Sensors Market
Sensors and Controls
MEMS Gyroscope Market
Sensors and Controls
MEMS Market
Sensors and Controls
Reflective Encoder Market
Sensors and Controls
Microseismic Monitoring Technology Market
Sensors and Controls
Actigraphy Sensors Market
Sensors and Controls
Yaw Rate Sensors Market
Sensors and Controls
Piezoelectric Materials Market
Sensors and Controls
Anti-Collision Sensor Market
Sensors and Controls
Europe Wearable Sensors Market
Sensors and Controls
Force Sensor Market