
 Lithium Battery for Passenger Car Market | 2026-2036
Lithium Battery for Passenger Car Market Size, Share, and Industry Trends Forecast 2026-2036
Lithium Battery for Passenger Car Market Insights
Korean cathode material producers is consolidating around integrated precursor-to-cell pipelines. CATL leverages its vertical reach into lithium refining to lock in feedstock security. LG Energy Solution sustains its European plant network to serve German OEM assembly lines. BYD Company anchors its cost position through in-house LFP cathode production.
A lithium battery for passenger car stores electrochemical energy through lithium-ion intercalation between layered oxide cathodes and graphite or silicon-composite anodes, typically operating at nominal voltages of 3.2-3.7 V per cell depending on cathode chemistry, with energy densities ranging from 140 Wh/kg for LFP formulations to over 300 Wh/kg for high-nickel NMC variants. Prismatic cells dominate volume share among global automakers seeking pack-level space efficiency, while solid-state cells represent the fastest-growing technology category as Toyota and Samsung SDI advance sulfide-electrolyte prototypes toward pilot production. NMC chemistry retains margin concentration in premium long-range segments, whereas LFP chemistry captures fleet and entry-level passenger car demand through lower material costs and extended cycle life.
China's MIIT enforces GB/T cell safety standards and NEV credit mandates that dictate minimum domestic battery procurement ratios. Europe's ECHA REACH framework and EU Battery Regulation impose carbon footprint declarations and recycled-content thresholds on cells sold within the single market. The US IRA domestic content bonus credit reshapes supplier qualification criteria for North American vehicle assembly. Stakeholders must track how jurisdictional compliance divergence affects cell factory siting and cathode chemistry selection across their production networks.
Market Dynamics
Cell chemistry bifurcation between nickel-rich NMC and iron-phosphate LFP is forcing parallel supply chain investments as automakers split their portfolios between range-optimized and cost-optimized vehicle lines. This structural tension reshapes cathode procurement, gigafactory equipment selection, and recycling infrastructure planning across every major production cluster.
Growth Catalysts
- China's NEV mandate:Domestic credit trading schemes enforce minimum battery procurement ratios, compelling foreign cell makers to localize production within the Yangtze River Delta industrial corridor.
- Fleet electrification:Ride-hail and logistics operators are converting entire vehicle pools to electric powertrains, creating concentrated demand for LFP cells with extended cycle life specifications.
- Solid-state pilot lines:Sulfide-electrolyte prototypes from Toyota and Samsung SDI are advancing toward commercial validation, promising energy density thresholds that compress pack size for premium sedans.
Market Restraints
- Lithium carbonate volatility:Spot price swings for spodumene and brine-derived feedstock compress cathode producer margins and destabilize long-term contract negotiations with automakers.
- Refining concentration:Over 60% of global lithium hydroxide conversion capacity sits within China's Fujian and Sichuan provinces, creating single-point vulnerability for non-Chinese cell makers.
- Silicon anode degradation:Volume expansion during lithiation cycles limits silicon-composite anode adoption to sub-10% graphite blends, capping energy density gains for NMC formulations.
Strategic Opportunities
- US IRA domestic content bonus:The Inflation Reduction Act's tax credit reshapes qualification criteria, rewarding cell factories sited in Michigan, Tennessee, and Kentucky with captive cathode precursor supply.
- Second-life stationary storage:Retired automotive packs with 70-80% remaining capacity are diverting toward grid-scale buffering applications, unlocking residual value streams for fleet operators.
- Direct recycling hydrometallurgy:Emerging cathode regeneration processes bypass full elemental decomposition, preserving crystal structure and cutting reprocessing energy intensity by half versus pyrometallurgical routes.
Industry Challenges
- Dry electrode coating expertise:Solvent-free electrode manufacturing reduces energy and capital costs but demands rare process engineering talent familiar with powder rheology and roll-compaction parameters.
- GB/T 38031 certification timelines:China's mandatory cell safety testing protocol requires 12-18 months for foreign suppliers to complete, delaying market entry against domestic competitors.
- Pack-to-vehicle integration complexity:Cell-to-pack architectures eliminate module housings but force simultaneous redesign of vehicle floor pans, thermal management loops, and crash structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lithium Battery for Passenger Car Market |
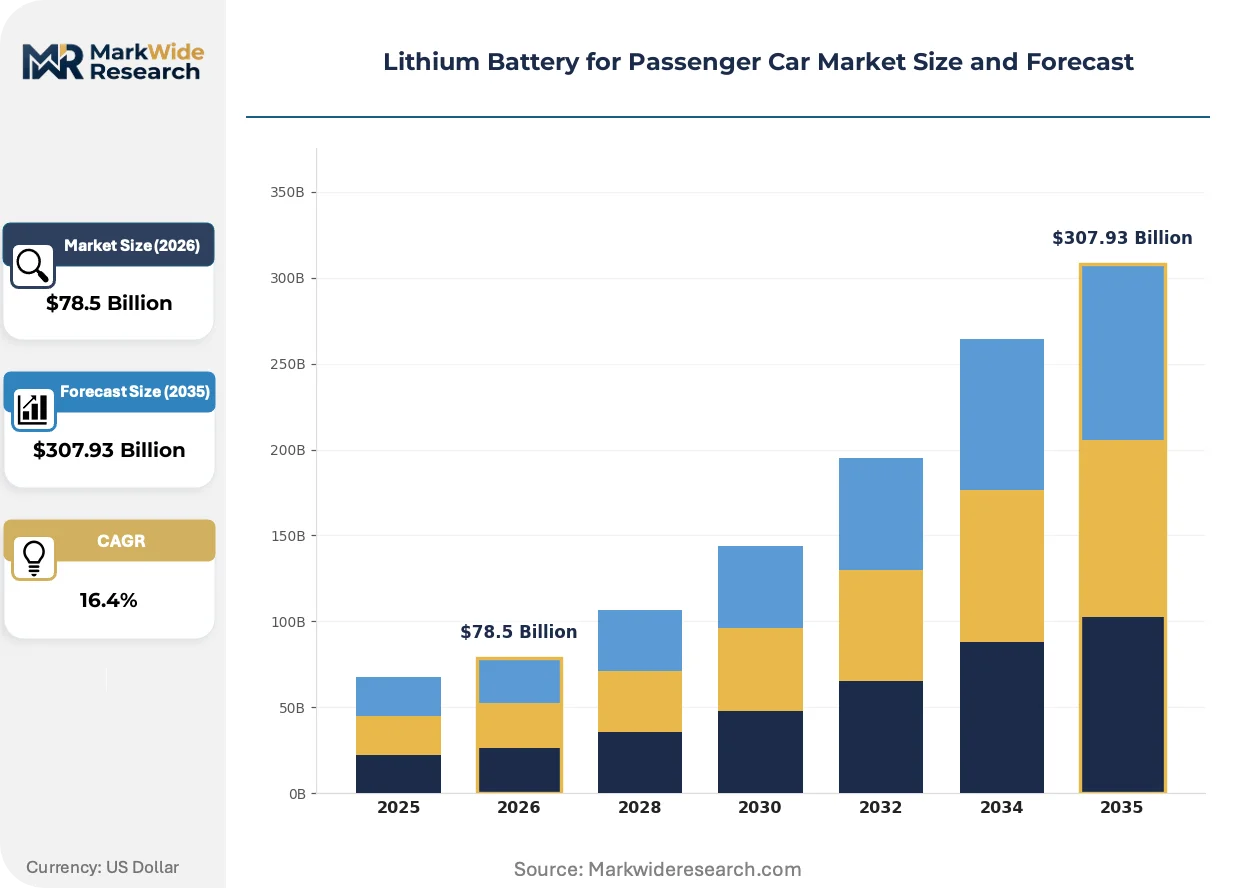
| Market Size in 2026 | $78.5 Billion |
| Market Size in 2035 | $307.93 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Prismatic Cells, Cylindrical Cells, Polymer Cells, Solid-State Cells End User: OEMs, Aftermarket Providers, Fleet Operators, Individual Consumers Technology: LFP, NMC, NCA, LiCoO2 Capacity: 20-40 Ah, 40-60 Ah, 60-80 Ah, 80-100 Ah |
| Companies Covered | CATL, LG Energy Solution, BYD Company, Panasonic, Samsung SDI, SK On, Sunwoda, EVE Energy, Gotion High-Tech, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lithium Battery for Passenger Car Market Trends and Innovations
Electrode manufacturing and cell formation processes are converging toward continuous-flow production methods that slash energy intensity and floor space requirements. This technical trajectory favors capital-rich incumbents capable of retooling existing gigafactories while squeezing out smaller batch-oriented competitors.
Lithium iron phosphate cathode chemistry is overtaking nickel-manganese-cobalt formulations in volume terms as Chinese automakers and Tesla's standard-range vehicles prioritize cost control over maximum range. Fleet operators and entry-market passenger segments are driving this pivot, compressing the addressable market for high-nickel cathode materials and forcing Korean suppliers to idle NMC-specific precursor lines.
Europe's EU Battery Regulation imposes carbon footprint declarations and recycled-content thresholds on cells sold within the single market, compelling Asian suppliers to establish European recycling partnerships or local black mass processing facilities. Premium long-range vehicle segments face the steepest compliance costs, prompting BMW and Mercedes-Benz to specify low-carbon nickel from Indonesian hydropower-fed operations.
Automaker procurement teams are consolidating cell supply relationships from six-to-eight vendors down to two-to-three strategic partners per region, trading price competition for supply security and co-development access. This concentration is most visible in Germany, where Volkswagen and BMW have anchored multi-billion-euro offtake agreements with CATL and LG Energy Solution for their respective Zwickau and Debrecen assembly networks.
Lithium Battery for Passenger Car Market Segmentation
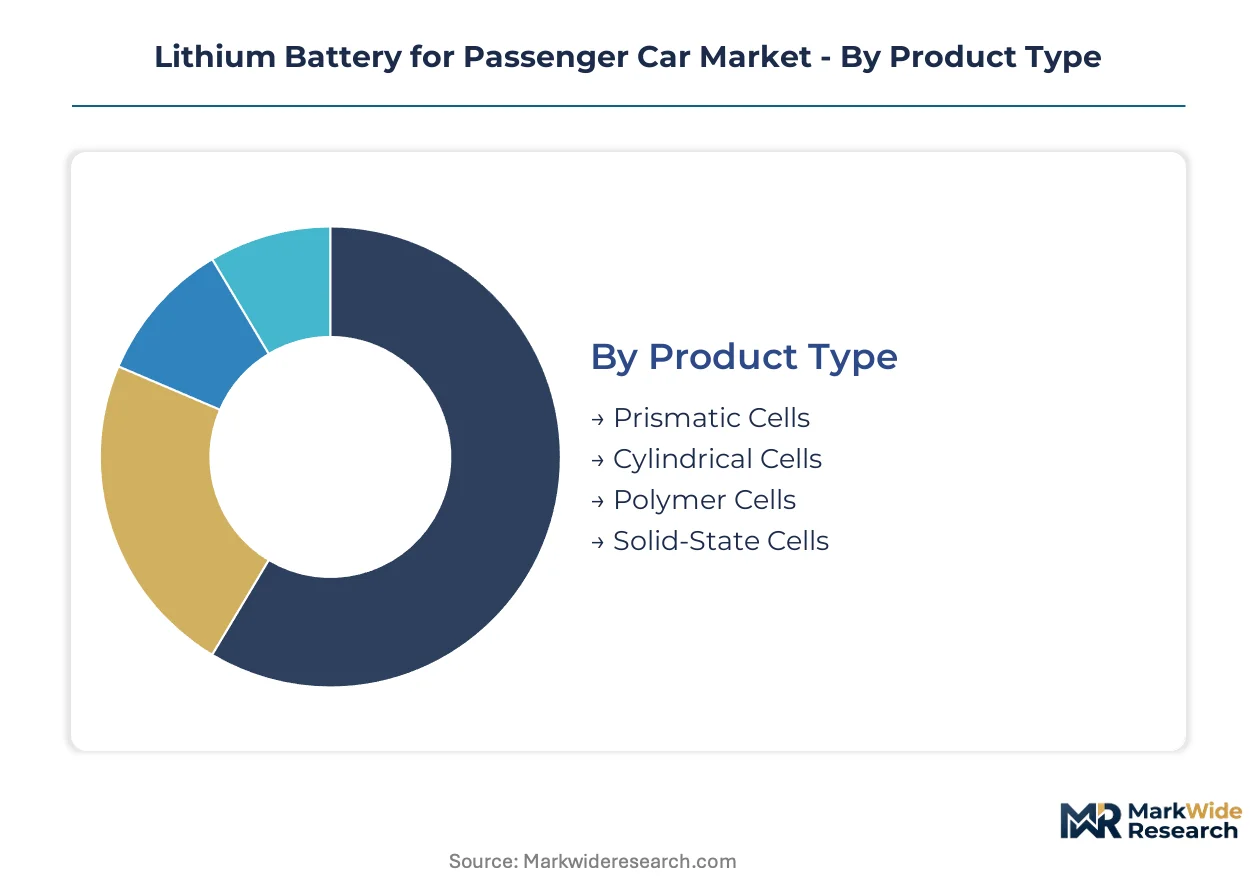
Passenger car battery procurement splits across cell geometry, cathode chemistry, and customer type, each dimension carrying distinct margin profiles and technical roadmaps. Upgrade cycles differ dramatically between fleet operators seeking cycle-life extensions and individual consumers chasing range improvements.
Product Type:
Fleet electrification and platform redesigns are accelerating replacement decisions as automakers shift from modular to cell-to-pack architectures.
- Prismatic Cells:Rectangular aluminum-cased cells deliver superior volumetric efficiency when stacked directly into battery trays without module housings. German OEM assembly lines in Zwickau and Debrecen specify prismatic formats for their dedicated EV platforms, driven by pack-level space optimization and thermal management integration.
- Solid-State Cells:Sulfide-electrolyte prototypes from Toyota and Samsung SDI promise energy density thresholds above 400 Wh/kg by eliminating liquid electrolyte volume. Pilot production lines in Japan and Korea target premium sedan introductions where pack size reduction justifies manufacturing complexity premiums.
- Cylindrical Cells:Tesla's 4680 format drives continued investment in high-speed winding equipment for standardized cell geometries.
- Polymer Cells:Pouch formats retain niche positions in hybrid vehicles requiring irregular pack shapes.
Prismatic cells sit at the top of the volume ranking, with solid-state climbing the fastest as pilot lines validate manufacturing scalability.
End User:
Procurement scale and contract duration separate customer tiers, with fleet operators commanding bespoke cycle-life specifications unavailable to retail buyers.
- Fleet Operators:Ride-hail and logistics pools convert entire vehicle lines simultaneously, creating concentrated demand for LFP cells rated beyond 3,000 cycles. Operators specify residual value guarantees for second-life grid storage applications, compressing total cost of ownership calculations against diesel equivalents.
- OEMs:Volkswagen, BMW, and BYD negotiate multi-year offtake agreements binding cell suppliers to assembly line cadence and chemistry roadmaps. OEM procurement teams now consolidate from six-to-eight vendors down to two-to-three strategic partners per region, trading price competition for supply security.
- Aftermarket Providers:Independent repair networks face certification barriers from GB/T 38031 testing protocols and manufacturer software locks.
- Individual Consumers:Retail replacement demand concentrates in warranty expiration windows, with limited price transparency versus OEM captive channels.
OEMs command the largest contract values, with fleet operators expanding most quickly as electrification mandates tighten across urban logistics.
Technology:
Cathode chemistry selection now determines factory equipment investment, with LFP and NMC requiring incompatible precursor supply chains and thermal processing lines.
- LFP:Lithium iron phosphate formulations sacrifice energy density for thermal stability and cobalt-free cost structures. CATL and BYD anchor cost positions through in-house LFP production, capturing standard-range passenger vehicles and entry fleet segments where cycle life outweighs maximum range.
- NMC:Nickel-manganese-cobalt layered oxides retain margin concentration in premium long-range segments, with high-nickel variants exceeding 300 Wh/kg. Korean cathode producers idle NMC-specific precursor lines as Chinese automakers pivot toward iron-phosphate dominance.
- NCA:Nickel-cobalt-aluminum cathodes from Panasonic supply Tesla's performance variants with silicon-composite anodes.
- LiCoO2:Cobalt-rich formulations persist in limited hybrid applications where cell mass minimization outweighs material cost.
LFP holds the volume lead, with high-nickel NMC formulations gaining share fastest in premium segments demanding 600+ kilometer range ratings.
Capacity:
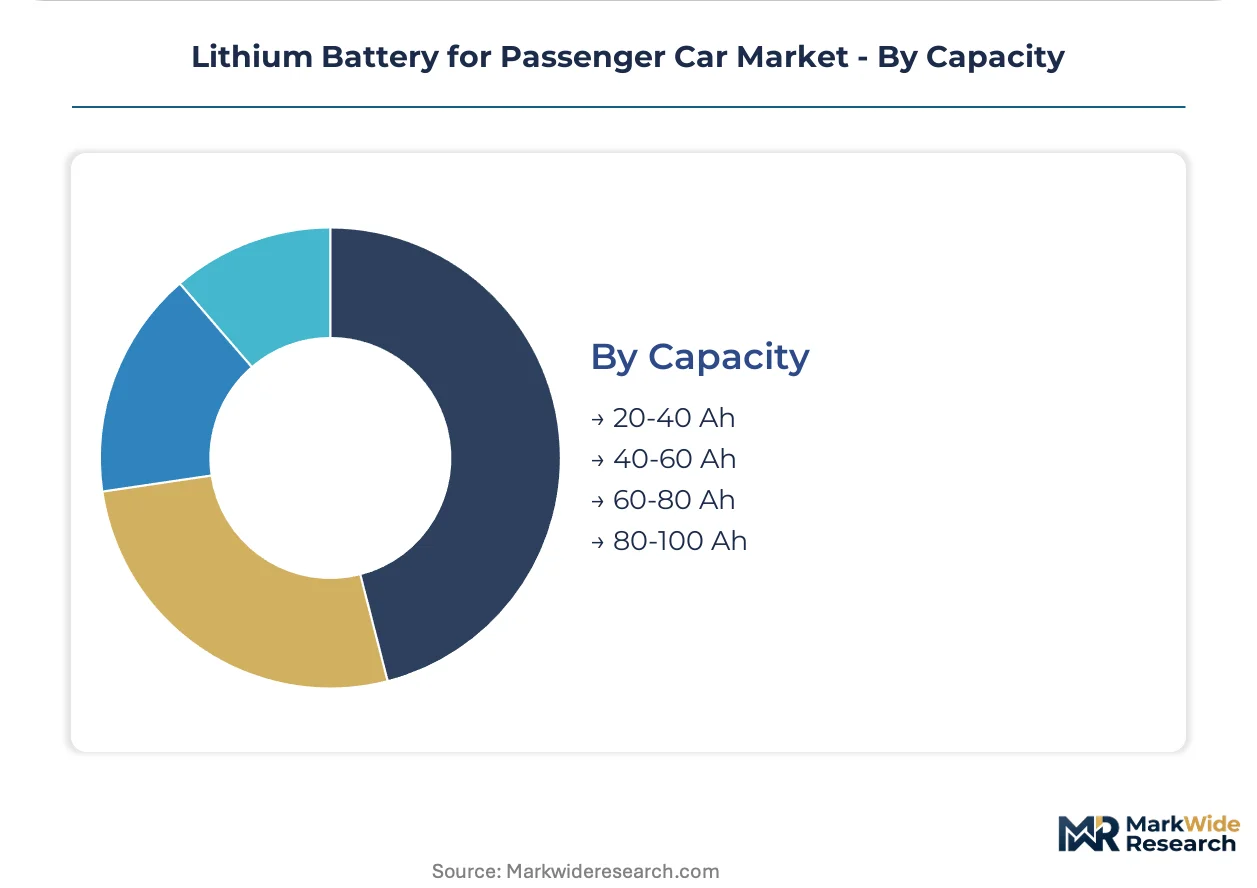
Pack sizing decisions track platform voltage architecture and thermal management boundaries, with higher capacities demanding liquid cooling and reinforced crash structures.
- 60-80 Ah:Mid-range capacities dominate compact and midsize passenger platforms, balancing cell count against pack mass. Chinese NEV credit mandates favor this segment for domestic market compliance, with CATL and BYD supplying standardized modules across multiple OEM programs.
- 80-100 Ah:Large-format cells reduce connection complexity in premium sedans and SUVs, though silicon anode degradation limits energy density gains to sub-10% graphite blends. European CO2 fleet standards push German OEMs toward this capacity tier for their executive vehicle lines.
- 40-60 Ah:Smaller capacities serve hybrid and range-extended platforms with limited pure-electric range requirements.
- 20-40 Ah:Compact formats retain positions in mild-hybrid systems and auxiliary power units.
60-80 Ah cells occupy the highest shipment volumes, with 80-100 Ah configurations showing the steepest expansion trajectory in premium platform launches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cell factory siting decisions increasingly track regulatory-arbitrage opportunities, with producers migrating toward jurisdictions offering carbon-accounting exemptions or domestic-content bonuses that offset higher labor costs. This geographic repositioning concentrates investment in three to five national production clusters where policy incentives align with feedstock access.
China
CATL and BYD anchor cathode-to-cell pipelines across Fujian and Sichuan provinces, exploiting captive lithium hydroxide conversion capacity. MIIT enforces GB/T 38031 safety certification and NEV credit mandates that compel foreign suppliers to localize within the Yangtze River Delta industrial corridor. The Ningde-Zhenjiang battery cluster now hosts over forty gigafactories serving domestic OEM assembly networks.
Germany
Volkswagen and BMW have consolidated multi-billion-euro offtake agreements around Zwickau and Debrecen assembly networks, demanding prismatic cell formats for dedicated EV platforms. ECHA REACH carbon-footprint declarations and recycled-content thresholds under the EU Battery Regulation force Asian suppliers to establish European black-mass processing partnerships. LG Energy Solution sustains its European plant network to serve these German OEM lines directly.
United States
The IRA domestic-content bonus credit reshapes qualification criteria, rewarding cell factories in Michigan, Tennessee, and Kentucky with captive cathode precursor supply. Fleet electrification mandates in California and New York accelerate LFP procurement for ride-hail vehicle pools. SK On and Samsung SDI have announced southeastern US expansion to capture these tax-advantaged supply positions.
South Korea
Korean cathode material producers consolidate around integrated precursor-to-cell pipelines serving premium long-range NMC segments. METI-aligned technology partnerships advance sulfide-electrolyte solid-state prototypes toward pilot validation. The Gyeonggi-Do battery corridor concentrates R&D-intensive cell formation and electrode coating expertise for export-oriented supply.
Japan
Toyota advances sulfide-electrolyte solid-state prototypes through pilot production lines targeting premium sedan introductions. METI enforces JIS standards for cell safety and recycling infrastructure that shape domestic procurement specifications. The Nagoya-Kyoto industrial corridor hosts concentrated materials science expertise for next-generation cathode development.
Lithium Battery for Passenger Car Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue solid-state validation and direct recycling hydrometallurgy. The market structure reflects moderate consolidation, with six-to-eight vendors historically serving each regional automaker now compressing toward two-to-three strategic partnerships. Three archetypes dominate: vertically integrated Chinese producers with captive lithium refining, Korean specialists in high-nickel NMC formulations, and Japanese solid-state pioneers. Competitive moves center on multi-year offtake agreements binding suppliers to assembly line cadence, and geographic expansion into IRA-eligible North American production zones.
Within the integrated-producer tier, CATL exemplifies backward integration into lithium refining that locks in feedstock security, while BYD Company anchors cost positioning through in-house LFP cathode production. LG Energy Solution occupies a position among Korean specialists sustaining European plant networks to serve German OEM assembly lines directly. These three represent distinct strategic archetypes: captive supply chain control, regional manufacturing proximity, and chemistry-specific portfolio concentration.
| Leading Market Players |
|---|
| CATL |
| LG Energy Solution |
| BYD Company |
| Panasonic |
| Samsung SDI |
| SK On |
| Sunwoda |
| EVE Energy |
| Gotion High-Tech |
| Others |
Pricing and Supply Chain Analysis
Backward integration into lithium refining anchors CATL's supply position and pricing power against spot-market volatility. The company's captive hydroxide conversion capacity in Fujian province insulates contract negotiations from brine-derived feedstock swings that compress Korean cathode producer margins.
Pricing Analysis
Direct-to-OEM contract structures dominate volume procurement, with multi-year offtake agreements binding cell suppliers to assembly line cadence. Pricing stratifies across premium long-range, standard-range, and entry fleet tiers based on cathode chemistry and cycle-life certification. Cost compression in LFP cells is intensifying because BYD and CATL scale in-house cathode production. Fleet operators command the steepest price sensitivity through concentrated volume bids, while premium OEMs absorb NMC premiums for range-optimized platforms.
Supply Chain Analysis
Regional distribution centers in Michigan, Tennessee, and Kentucky feed IRA-eligible cell factories serving Detroit and Nashville assembly networks. The chain draws from spodumene concentrate in Australia, Chilean brine operations, and Indonesian nickel-cobalt intermediates. Single-source vulnerability concentrates in China's Fujian and Sichuan provinces, where over sixty percent of global lithium hydroxide conversion sits. Distribution runs through cathode precursor pipelines into gigafactory electrode coating lines, with finished cells shipping direct to OEM pack assembly.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
LFP chemistry scale-up compresses input costs while premium solid-state introductions expand margin ceilings. The market structure rewards producers capturing both volume efficiency and technology differentiation.
For Market Incumbents: Deploy dry electrode coating expertise to cut energy intensity and capital requirements in gigafactory retooling. Secure captive precursor supply through joint ventures in Australia and Chile to offset Chinese refining concentration. Solid-state pilot validation from Toyota and Samsung SDI threatens NMC margin pools if sulfide-electrolyte manufacturing achieves commercial scalability. For New Entrants and Emerging Players: Begin with second-life stationary storage applications, where retired automotive packs with seventy to eighty percent residual capacity face limited incumbent competition. Target fleet operator procurement teams seeking residual value guarantees for grid-scale buffering. Direct recycling hydrometallurgy offers a technology-licensing entry angle that bypasses full cathode manufacturing scale. For Investors and Strategic Acquirers: Roll-up economics work for regional recycling specialists because EU Battery Regulation recycled-content thresholds force Asian suppliers into European black-mass processing partnerships. Long-term viability hinges on exposure to IRA-eligible North American production zones and solid-state pilot line validation. Watch for GB/T 38031 certification completion timelines as an inflection signal for foreign supplier market entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Cathode Precursor Joint Venture | Lock-in spodumene and brine feedstock security against Chinese refining concentration. |
| Solid-State Pilot Line Scale-Up | Validate sulfide-electrolyte manufacturing for premium sedan energy density thresholds. |
| IRA-Eligible Factory Siting | Capture domestic content bonus credits in Michigan, Tennessee, and Kentucky corridors. |
| Direct Recycling Hydrometallurgy | Cut reprocessing energy intensity by half versus pyrometallurgical routes for EU compliance. |
| Fleet Operator Residual Value Guarantee | Unlock second-life grid storage revenue streams for ride-hail and logistics vehicle pools. |
Research Methodology
Coverage spans China, Germany, the United States, South Korea, and Japan, with primary inputs from each regional battery cluster. The approach combines interviews with cathode material procurement leads, OEM platform engineers, gigafactory operations directors, and recycling facility managers with secondary validation from MIIT production databases, ECHA REACH filings, and IRA domestic content guidance documents. Bottom-up cell shipment tallies triangulate against top-down OEM production schedules.
Rate-of-change decomposition separates volume expansion from chemistry mix shifts and pricing tier migration across the analysis window. The framework models passenger car battery demand by cell geometry, cathode chemistry, end-user type, and regional regulatory cluster. CAGRs derive from segment-level growth rate blending weighted by base-year shipment composition. Forecast inputs incorporate NEV credit mandate trajectories, CO2 fleet standard stringency, and solid-state pilot production timelines.
Caveats apply where lithium carbonate spot volatility, silicon anode degradation limits, or GB/T 38031 certification delays could materially shift the outlook. Forecasts reflect documented assumptions around policy incentive continuity and cathode chemistry adoption curves. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Automotive Sodium-Ion Battery Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Materials Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Lithium-Ion Forklift Battery Market
Lithium-ion Battery
North America Lithium-Ion Battery Market
Lithium-ion Battery
Lithium-Ion UPS System Market
Lithium-ion Battery
Automotive Lithium Ion Battery Market
Lithium-ion Battery
LAMEA Solid State Battery Market
Lithium-ion Battery
Global Lithium Ion Cell and Battery Pack Market
Lithium-ion Battery
Next Generation Advanced Battery Market
Lithium-ion Battery
Sodium Battery Electrolyte Market
Lithium-ion Battery
Germany Electric Vehicle Battery Electrolyte Market
Lithium-ion Battery
Asia Pacific Electric Vehicle Battery Anode Market
Lithium-ion Battery
United Kingdom Lithium-Ion Battery for Electric Vehicle Market
Lithium-ion Battery
Lithium-Ion Battery Separator Market
Lithium-ion Battery
Lithium-Ion Manganese Oxide Battery Market