
 Cathode Material of Power Lithium Battery Market | 2026-2036
Cathode Material of Power Lithium Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Cathode Material of Power Lithium Battery Market Insights
Automotive offtake is shifting toward electric vehicle platforms with extended-range specifications, pulling cathode chemistry selection decisively toward nickel-rich systems. CATL leverages integrated precursor capacity across Fujian and Sichuan to secure feedstock certainty. LG Chem anchors its cathode supply through captive partnerships with Korean nickel refiners. Umicore differentiates via closed-loop recycling streams that recover cobalt and nickel from end-of-life batteries.
Cathode material of power lithium battery denotes the lithium-bearing compound coated onto aluminum current collectors, typically formulated as lithium iron phosphate, nickel-manganese-cobalt oxide, lithium cobalt oxide, or nickel-cobalt-aluminum oxide with particle sizes engineered to 5-15 micrometers for optimal ionic conductivity and energy density. NMC formulations dominate value capture due to their energy density advantage in premium electric vehicle segments. LFP occupies volume leadership in entry and mid-range automotive applications where cost per kilowatt-hour governs procurement decisions. Solid-state technology development is redirecting R&D spending toward sulfide and oxide electrolyte interfaces compatible with high-voltage cathode architectures.
China's MIIT enforces GB standards for battery cell safety and cycle-life certification that constrain cathode impurity thresholds. The EU Battery Regulation mandates recycled-content quotas and supply-chain due diligence that reshape material sourcing economics for cathode producers serving European automotive OEMs. REACH compliance in Europe and evolving EPA hazardous-material classifications in the United States add parallel compliance layers. Stakeholders must track regulatory divergence between jurisdictions to avoid stranded capacity in chemistries that fail emerging carbon-accounting or recycling-mandate requirements.
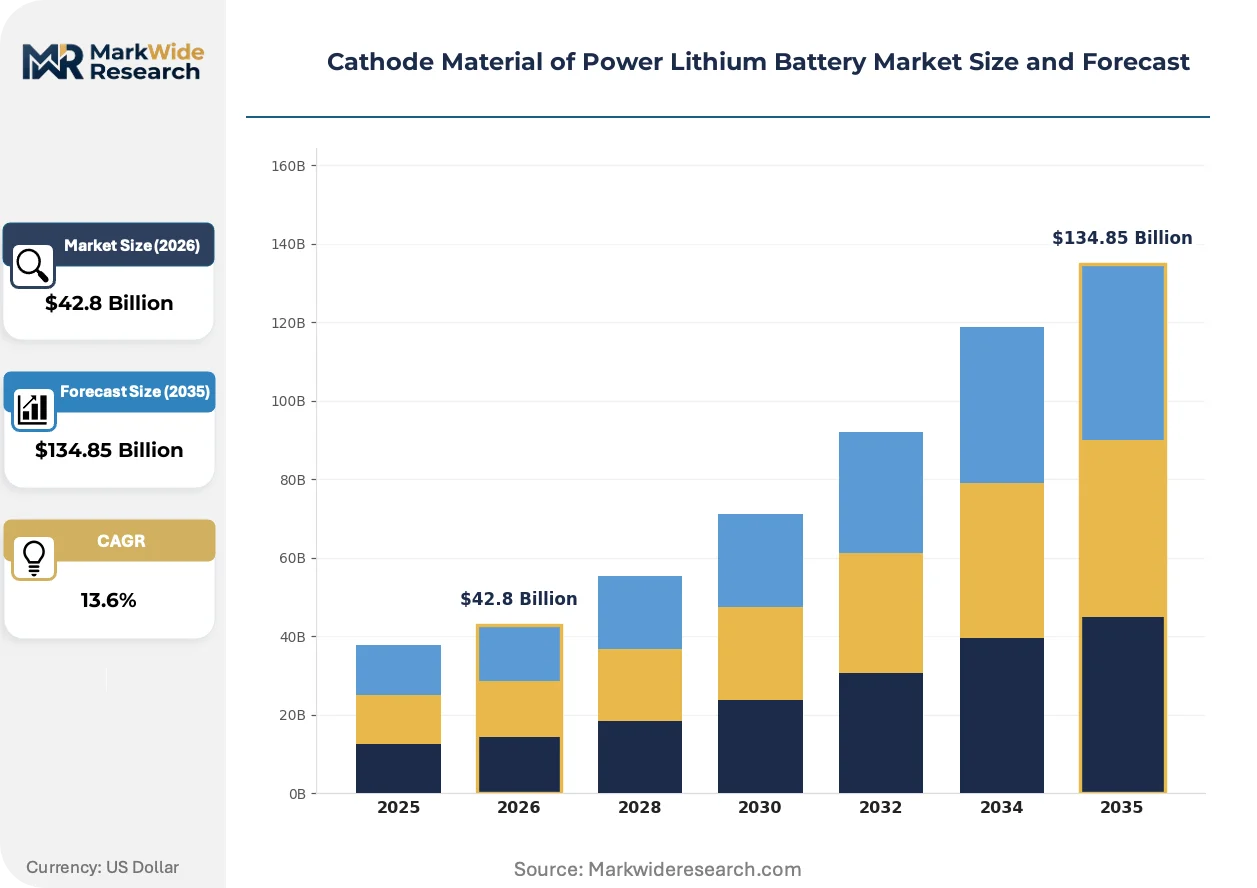
Market Dynamics
Automotive electrification mandates and nickel supply concentration are compressing cathode chemistry selection timelines, forcing cell manufacturers to secure precursor feedstock through long-term offtake agreements rather than spot markets.
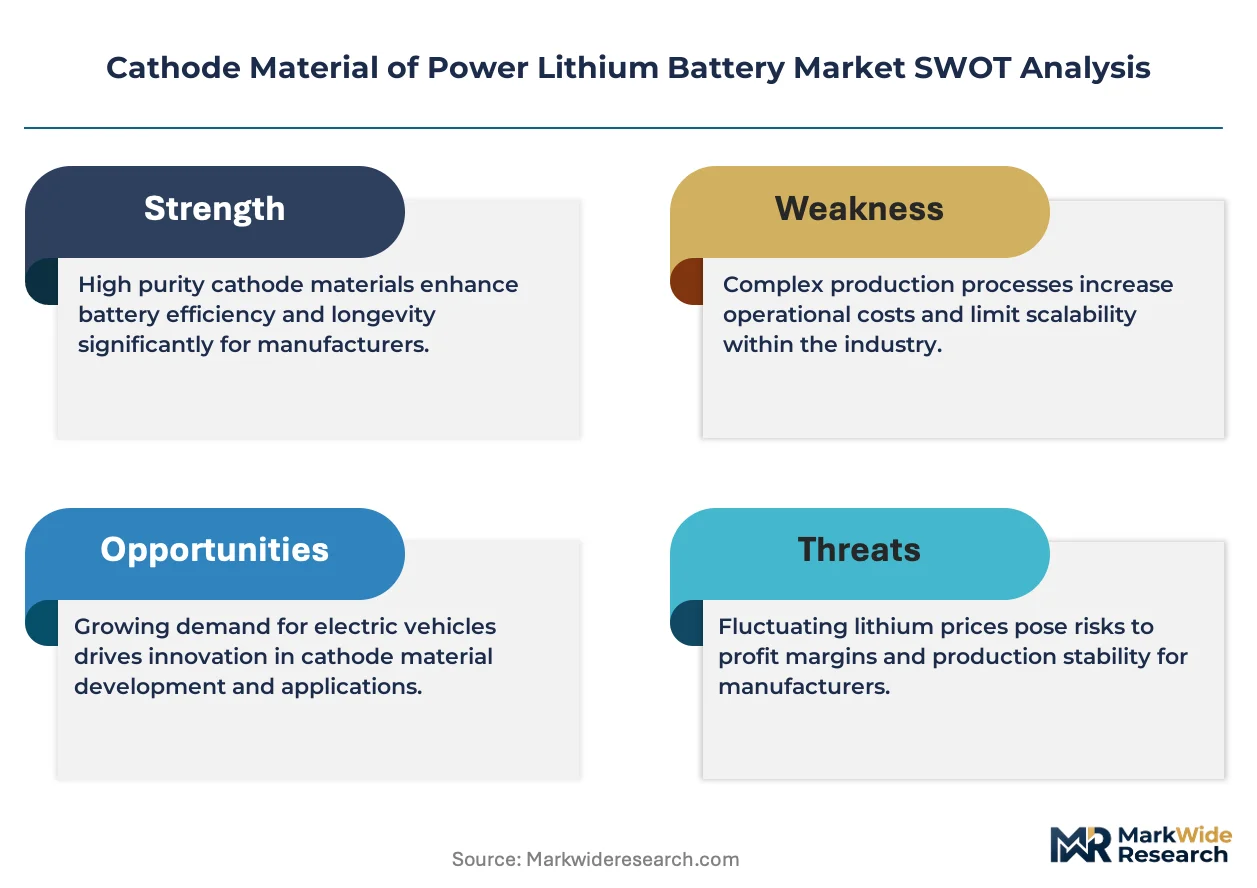
Growth Catalysts
- EU Battery Regulation recycled-content quotas:Mandates for minimum recovered cobalt and nickel in new cells pull investment toward closed-loop refining infrastructure serving European automotive OEMs.
- Extended-range electric vehicle platforms:Premium passenger vehicle segments with range targets above 600 kilometers specify NMC 811 and 9-series cathode formulations exclusively.
- Jiangsu-Hunan production corridor:Integrated precursor-to-cathode manufacturing clusters in these provinces reduce logistics costs and processing time for Chinese cell suppliers.
Market Restraints
- Nickel price volatility:Class 1 nickel cathode-grade premiums fluctuate with Indonesian ore export policy shifts, compressing margin predictability for high-nickel cathode producers.
- Cobalt supply geographic concentration:DRC-origin cobalt dominates refined feedstock, exposing cathode manufacturers to ESG due-diligence compliance costs and supply disruption risk.
- Energy density ceiling in LFP:Lithium iron phosphate formulations plateau below 200 Wh/kg at cell level, excluding them from premium long-range vehicle segments regardless of cost advantage.
Strategic Opportunities
- Solid-state electrolyte convergence:Sulfide and oxide solid electrolytes enable high-voltage cathode operation above 4.5V, opening energy density gains beyond current liquid-electrolyte limits.
- Direct recycling technology:Hydrometallurgical processes that regenerate cathode crystal structure without full elemental separation cut recovery costs versus conventional pyrometallurgy.
- Stationary storage demand in India:Grid-scale battery procurement under CEA mandates and state-level storage obligations creates volume demand for lower-cost LFP cathode formulations.
Industry Challenges
- High-purity nickel sulfate refining capacity:Battery-grade nickel sulfate supply lags cathode demand expansion, requiring capital-intensive HPAL or matte conversion investments with 3-4 year construction timelines.
- MIIT GB standard cycle-life certification:Chinese safety and performance testing protocols extend product qualification periods, delaying commercialization of next-generation high-nickel formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cathode Material of Power Lithium Battery Market |
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $134.85 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LFP, NMC, LCO, NCA Application: Electric Vehicles, Consumer Electronics, Renewable Energy, Industrial Equipment End User: OEMs, Tier-1 Suppliers, Aftermarket Providers, Utilities Technology: Solid-State, Liquid Electrolyte, Hybrid Systems, Rapid Charging |
| Companies Covered | CATL, LG Chem, BYD, Sumitomo Metal Mining, Umicore, XTC New Energy Materials, Shenzhen Dynanonic, Hunan Yuneng New Energy Battery Materials, POSCO Future M, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cathode Material of Power Lithium Battery Market Trends and Innovations
Single-crystal cathode architectures and dry electrode coating processes are compressing manufacturing energy intensity while pushing energy density boundaries for next-generation cells.
High-nickel low-cobalt cathode formulations are expanding into premium electric vehicle battery packs as automakers balance range targets with supply chain ESG scrutiny. Korean and Chinese cell suppliers dominate NMC 9-series commercialization, locking in cathode precursor supply through equity stakes in Indonesian HPAL projects. This chemistry transition is expanding into mid-range vehicle segments previously served by NMC 622, compressing the addressable market for cobalt-intensive alternatives.
China's MIIT enforces progressively stricter GB standards for thermal runaway propagation resistance and cycle-life degradation rates, forcing cathode suppliers to tighten impurity thresholds for sodium, calcium, and magnetic particles. Cell manufacturers serving domestic automotive OEMs must recertify products against updated protocols annually. European cathode producers responding to EU Battery Regulation due-diligence requirements face parallel compliance burdens, diverting technical resources from process optimization.
Automotive OEMs are consolidating cathode procurement through direct long-term agreements with precursor and cathode material suppliers, displacing merchant market transactions. Cell manufacturers in Germany and Hungary negotiate directly with Korean nickel refiners and Chinese cobalt processors, bypassing traditional trading house intermediaries. This channel compression is most visible in European electric vehicle supply chains, where OEMs seek supply certainty ahead of 2030 fleet electrification targets.
Cathode Material of Power Lithium Battery Market Segmentation
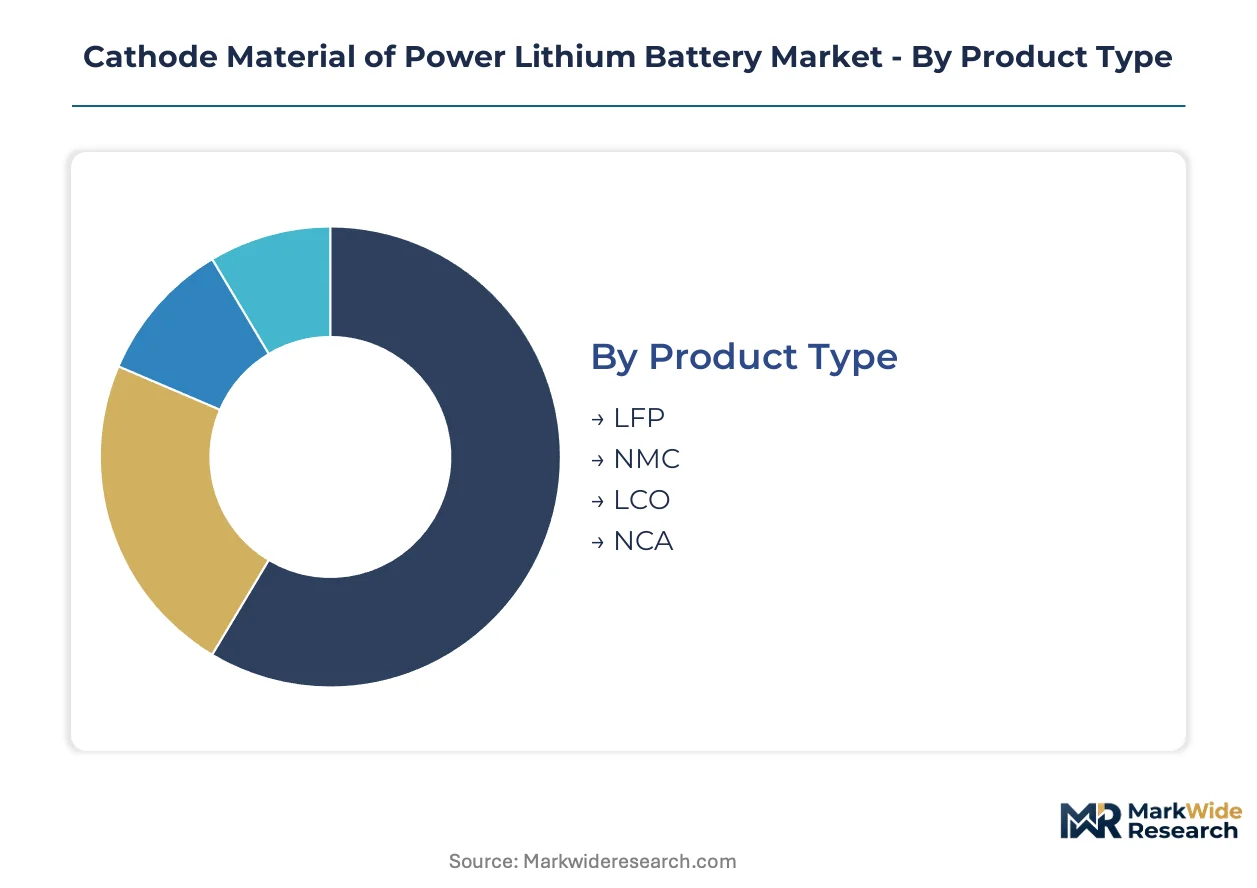
Cathode chemistry selection governs cell performance, cost structure, and regulatory compliance across divergent application requirements. Segmentation reveals how material formulations align with power density needs, cycling durability demands, and supply chain risk tolerance in automotive and stationary storage procurement.
Product Type:
Upgrade cycles in electric vehicle platforms are compressing cathode chemistry selection timelines, with automakers specifying next-generation formulations two to three model years ahead of production ramp.
- LFP:Lithium iron phosphate delivers thermal stability and cycle life exceeding 3,000 cycles at the cost of energy density below 200 Wh/kg. Procurement from BYD and CATL concentrates in China's entry-level passenger vehicle segment where cost per kilowatt-hour dominates battery pack economics.
- NMC:Nickel-manganese-cobalt oxide formulations span 523, 622, 811, and 9-series variants with nickel content climbing toward 90 percent. European and Korean automakers specify NMC 811 for premium extended-range platforms above 600 kilometers, locking in cathode supply through direct precursor offtake agreements with Chinese and Indonesian processors.
- LCO:Lithium cobalt oxide maintains position in high-end consumer electronics where volumetric energy density prioritizes over unit cost.
- NCA:Nickel-cobalt-aluminum oxide serves Tesla's cylindrical cell architecture and select Korean cell supplier portfolios, constrained by cobalt supply concentration from DRC-origin feedstock.
NMC sits at the top of the volume ranking, with LFP climbing the fastest as Chinese automakers expand iron phosphate penetration into mid-range vehicle segments.
Application:
Cost tier differentiation separates cathode procurement strategies across mobility, stationary, and portable power segments with divergent performance premiums.
- Electric Vehicles:Automotive platforms specify cathode chemistry by range tier — LFP for urban commuter vehicles below 400 kilometers, NMC 811 and 9-series for premium long-range configurations. CATL's Qilin battery and BYD's Blade Cell architecture demonstrate LFP's encroachment into segments previously reserved for nickel-rich formulations.
- Consumer Electronics:Smartphones, laptops, and power tools prioritize volumetric energy density, sustaining cobalt-containing LCO and mid-nickel NMC demand despite ESG sourcing pressures.
- Renewable Energy:Grid-scale storage procurement under India's CEA mandates and European capacity market mechanisms favors LFP for 4-8 hour discharge duration applications where cycle life and capital cost outweigh energy density.
- Industrial Equipment:Forklifts, mining vehicles, and port automation systems specify cathode formulations based on duty cycle intensity and charging infrastructure availability.
Electric Vehicles commands the largest procurement volume, with Renewable Energy expanding most quickly as grid-scale battery installations accelerate under national storage obligations.
End User:
Customer type determines contracting structure, with direct OEM engagement displacing merchant market transactions in high-volume cathode procurement.
- OEMs:Volkswagen, BMW, and Hyundai negotiate long-term cathode supply agreements directly with Umicore, POSCO, and Chinese precursor producers, bypassing cell manufacturer intermediaries to secure volume certainty ahead of 2030 fleet electrification targets.
- Tier-1 Suppliers:Battery cell manufacturers including CATL, LG Energy Solution, and Samsung SDI aggregate cathode demand across multiple OEM customers, maintaining formulation flexibility through diversified precursor sourcing.
- Aftermarket Providers:Replacement battery procurement for legacy electric vehicle fleets and second-life stationary storage applications generates demand for certified refurbished cathode materials.
- Utilities:State-owned power generators in India and European transmission system operators issue tenders specifying LFP chemistry for grid balancing and renewable integration projects.
Tier-1 Suppliers process the highest cathode tonnage, with OEMs gaining share fastest through direct supply chain compression.
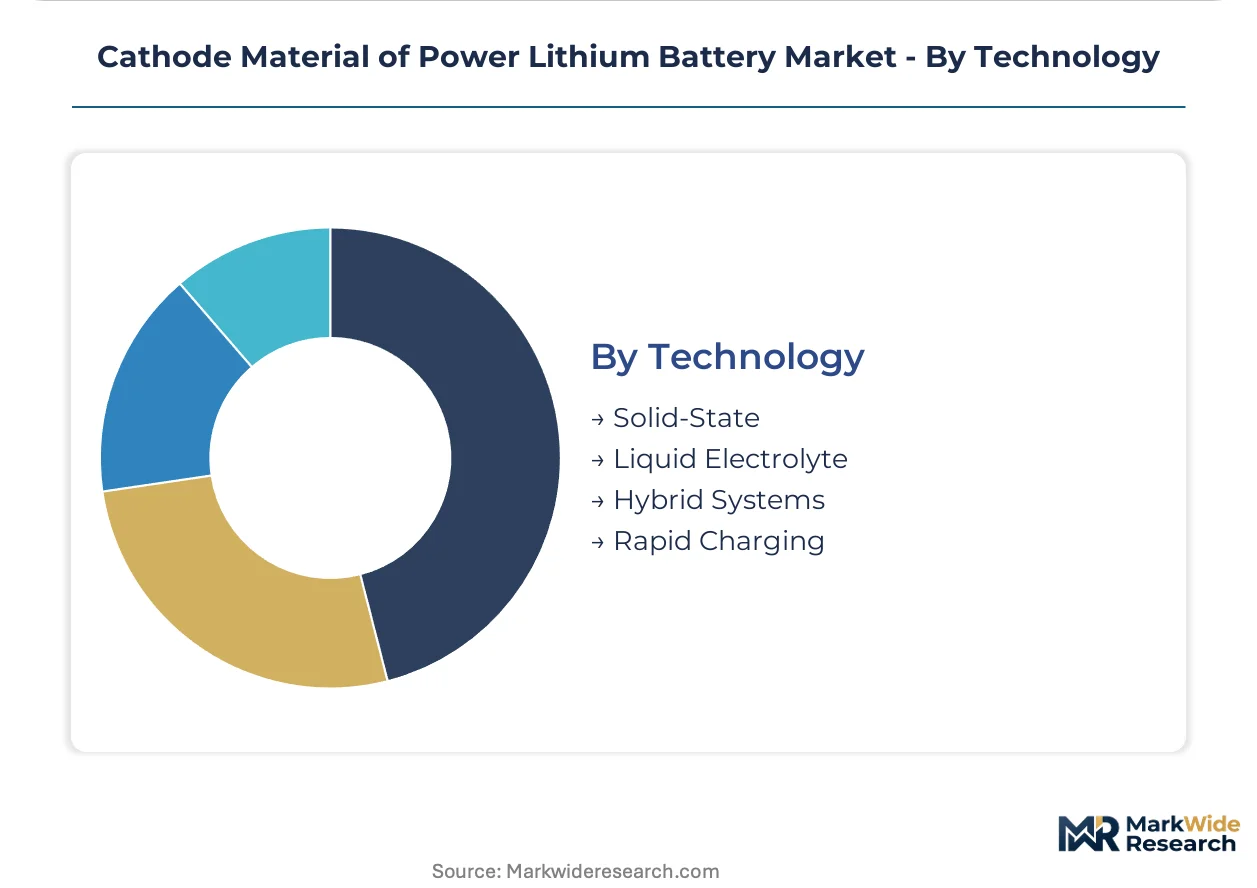
Technology:
Manufacturing process maturity separates commercially deployed liquid electrolyte systems from emerging solid-state architectures requiring cathode-electrolyte interface engineering.
- Solid-State:Sulfide and oxide electrolyte systems enable high-voltage cathode operation above 4.5V, promising energy density gains beyond liquid electrolyte limits. Toyota, QuantumScape, and Samsung SDI target automotive qualification timelines constrained by MIIT GB standard certification protocols.
- Liquid Electrolyte:Conventional carbonate-based electrolyte systems with lithium hexafluorophosphate salt dominate current production, with cathode suppliers optimizing particle morphology and carbon coating for rate capability and cycle stability.
- Hybrid Systems:Semi-solid electrolyte formulations and gel polymer architectures bridge performance gaps for niche applications requiring enhanced safety margins.
- Rapid Charging:Cathode materials engineered for 10-15 minute fast-charge capability require modified particle size distribution and surface treatment to mitigate lithium plating and thermal runaway risk.
Liquid Electrolyte retains dominant production scale, with Solid-State gaining development investment fastest as sulfide electrolyte processing yields improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cathode production is migrating toward jurisdictions where carbon-accounting compliance costs remain below European thresholds, creating arbitrage opportunities for integrated precursor-to-cathode manufacturers.
China
CATL and BYD anchor demand for high-nickel and LFP cathode formulations across Fujian, Sichuan, and Guangdong provinces. MIIT enforces progressively stricter GB standards for thermal runaway resistance and cycle-life degradation. The Jiangsu-Hunan production corridor concentrates integrated precursor refining and cathode finishing capacity, reducing logistics costs for cell suppliers serving domestic automotive OEMs.
South Korea
LG Energy Solution and Samsung SDI drive procurement of NMC 811 and 9-series cathodes for premium electric vehicle exports to Europe and North America. The MFDS maintains battery safety certification protocols aligned with UN 38.3 transport regulations. The Gyeonggi-Seoul industrial cluster hosts cathode precursor joint ventures with Korean nickel refiners securing Indonesian HPAL feedstock.
United States
Tesla's cylindrical cell demand and emerging domestic cell factories pull cathode supply toward North American assembly. The EPA's evolving hazardous-material classifications and IRA domestic content bonuses reshape sourcing economics. The Midwest battery belt forming across Michigan, Ohio, and Kentucky attracts cathode precursor investments seeking proximity to Ford and GM electric vehicle plants.
Germany
Volkswagen, BMW, and Mercedes-Benz negotiate direct cathode supply agreements bypassing traditional merchant markets. The EU Battery Regulation mandates recycled-content quotas and supply-chain due diligence that elevate compliance costs for Asian exporters. The Saxony-Anhalt and Thuringia regions host Umicore and POSCO Future M cathode facilities serving European automotive OEM electrification timelines.
Japan
Toyota's solid-state battery development and Panasonic's cylindrical cell production sustain demand for high-purity cathode materials with tight impurity thresholds. METI's battery supply chain security initiatives subsidize domestic precursor stockpiling and recycling infrastructure. The Osaka-Kyoto industrial corridor concentrates Sumitomo Metal Mining's nickel refining and cathode precursor operations.
Cathode Material of Power Lithium Battery Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated precursor-cathode producers commanding premium positions in high-nickel formulations while merchant suppliers compete on volume in LFP. The vendor base concentrates around three strategic archetypes: integrated mining-to-cathode conglomerates, dedicated cathode material specialists, and cell manufacturer captives with backward-controlled precursor supply. Dominant competitive moves include equity stakes in Indonesian nickel HPAL projects and direct long-term offtake agreements with automotive OEMs that displace spot market transactions.
Within the integrated conglomerate tier, CATL and BYD exemplify cell manufacturers with captive upstream control over precursor and cathode production. Among dedicated material specialists, Umicore occupies a position representing European closed-loop recycling capabilities, while POSCO Future M anchors Korean integrated steel-to-battery material diversification. These named entities serve as reference points for archetype analysis rather than comprehensive competitive enumeration.
| Leading Market Players |
|---|
| CATL |
| LG Chem |
| BYD |
| Sumitomo Metal Mining |
| Umicore |
| XTC New Energy Materials |
| Shenzhen Dynanonic |
| Hunan Yuneng New Energy Battery Materials |
| POSCO Future M |
| Others |
Pricing and Supply Chain Analysis
Automotive OEM procurement consolidation toward direct cathode offtake agreements is compressing channel margins and forcing precursor suppliers to absorb volatility in Indonesian nickel sulfate premiums. This demand-side restructuring elevates pricing power for integrated producers while squeezing merchant cathode specialists unable to secure captive feedstock.
Pricing Analysis
Direct-to-OEM contracting discounts dominate high-volume NMC procurement, with pricing stratifying across premium, standard, and economy tiers based on nickel purity grade and MIIT GB certification status. Cost compression in LFP formulations is intensifying because BYD and CATL are expanding in-house precursor capacity. Tier-1 cell manufacturers exhibit lowest price sensitivity due to pass-through mechanisms in automotive supply agreements, while aftermarket providers face acute margin pressure from spot-market nickel volatility.
Supply Chain Analysis
Skilled chemical engineering labor scarcity in Indonesia's Obi Island and China's Jiangsu corridor is constraining HPAL project ramp rates and delaying cathode precursor output expansion. Battery-grade nickel sulfate supply draws from Indonesian HPAL operations, Finnish matte conversion, and Chinese intermediate refining, with cobalt hydroxide feedstock resting on DRC-origin mining concentration. Single-source vulnerability in Indonesian nickel processing exposes cathode producers to export policy shifts. Distribution runs through long-term offtake contracts directly to cell manufacturer gigafactories, displacing spot-market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cathode material procurement has entered a late-cycle quality phase as European OEMs mandate EU Battery Regulation compliance and carbon-accounting transparency ahead of recycled-content quota enforcement. Premium NMC 811 and 9-series specifications now command disproportionate margin capture over commodity LFP grades.
For Market Incumbents: Deploy equity stakes in Indonesian HPAL nickel projects to lock in Class 1 sulfate supply before refining capacity bottlenecks worsen. Secure MIIT GB standard pre-certification for next-generation high-nickel formulations to accelerate qualification timelines against emerging solid-state competitors. Channel control through direct OEM agreements defends margin position against merchant market price erosion. For New Entrants and Emerging Players: Capture stationary storage procurement in India under CEA mandates where LFP specifications favor cost-competitive entrants over automotive-certified incumbents. Target grid-scale battery integrators seeking second-source cathode supply outside Chinese merchant market concentration. Establish tolling partnerships with existing precursor refiners to bypass capital-intensive HPAL construction timelines. For Investors and Strategic Acquirers: Asymmetric upside sits with closed-loop recycling specialists possessing hydrometallurgical direct regeneration technology compatible with EU Battery Regulation recycled-content quotas. Five-to-ten year viability hinges on securing feedstock agreements with end-of-life battery aggregators before incumbent miners integrate downstream. Monitor Indonesian ore export license suspensions as inflection indicator for nickel sulfate price spikes.| Strategic Initiative | Industry Significance |
|---|---|
| HPAL Equity Partnership | Secures Class 1 nickel sulfate feedstock from Indonesian operations for NMC 9-series production. |
| Direct Recycling Infrastructure | Enables EU Battery Regulation compliance through hydrometallurgical cathode regeneration without elemental separation. |
| MIIT GB Pre-Certification | Accelerates commercialization timelines for high-nickel formulations ahead of solid-state competition. |
| CEA Grid Storage Tender | Captures volume demand from Indian state utilities specifying LFP for 4-8 hour discharge applications. |
| OEM Direct Offtake Agreement | Bypasses merchant market volatility through long-term contracts with Volkswagen, BMW, or Hyundai procurement. |
Research Methodology
Direct dialogue with cathode plant managers, Tier 1 cell supplier procurement directors, OEM platform battery engineers, and Indonesian HPAL project developers grounded qualitative assessment in operational reality. Secondary validation drew from MIIT GB standard filings, EU Battery Regulation delegated acts, Indonesian mining export license records, and SEC 10-K disclosures from listed materials companies. Bottom-up cathode capacity build-out schedules were triangulated against top-down electric vehicle production forecasts across the analysis window.
Bottom-up modeling aggregated individual precursor refinery and cathode finishing facility capacities by chemistry type, then mapped to OEM platform specifications by range tier. Segmentation dimensions included cathode chemistry (LFP, NMC variant, LCO, NCA), application (automotive, stationary, consumer electronics), and technology (liquid electrolyte, solid-state, rapid-charge optimized). CAGRs were derived from slope analysis of year-over-year demand progression adjusted for inventory cycle effects. Nickel sulfate supply elasticity and MIIT certification timeline assumptions shaped high-nickel formulation penetration curves.
Underlying measurement precision varies by segment; automotive NMC demand carries tighter precision than emerging solid-state qualification timelines. Forecasts embed assumptions regarding Indonesian HPAL ramp schedules, EU Battery Regulation enforcement intensity, and Chinese dual carbon policy implementation. Practitioners should monitor Indonesian nickel export policy announcements, MIIT GB standard revision schedules, and European OEM recycled-content mandate clarifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Lithium-ion Battery
Italy Electric Vehicle Battery Materials Market
Lithium-ion Battery
Italy Electric Vehicles Battery Anode Market
Lithium-ion Battery
Silicon Anode Battery Market
Lithium-ion Battery
Lawn Mower Lithium Battery Market
Lithium-ion Battery
Sodium Battery Electrolyte Market
Lithium-ion Battery
Germany Electric Vehicle Battery Materials Market
Lithium-ion Battery
Large Capacity Lithium Battery Packs Sales Market
Lithium-ion Battery
Lithium and Lithium Ion Battery Electrolytes Market
Lithium-ion Battery
Europe NMC Battery Pack Market
Lithium-ion Battery
Asia-Pacific Solid State Battery Market
Lithium-ion Battery
Radial Lithium-Ion Capacitor Market
Lithium-ion Battery
Automotive Lithium-Sulfur Battery Market
Lithium-ion Battery
Global Nanowire Battery Market
Lithium-ion Battery
18650 Lithium Battery for Electric Vehicle Market
Lithium-ion Battery
Consumer Lithium-Ion Battery Market
Lithium-ion Battery
High Temperature Lithium Battery Market