
 Test Tube Market | 2026-2036
Test Tube Market Size, Share, and Industry Trends Forecast 2026-2036
Test Tube Market Analytics
Chinese borosilicate glass production capacity is shifting toward medical-grade certification standards, tightening supply availability for European converters. DWK Life Sciences GmbH leverages its German manufacturing footprint to sustain ISO 13485-certified output for diagnostic OEMs. Thermo Fisher Scientific anchors North American distribution through direct hospital and laboratory contracts. Eppendorf SE differentiates with precision-molded polypropylene tubes optimized for automated liquid handling systems.
A test tube is a cylindrical, open-top vessel manufactured from borosilicate glass, soda-lime glass, or polymer resins such as polypropylene, typically ranging from 10mm to 20mm in diameter with capacities from 5ml to 25ml, designed to contain, mix, or heat small liquid or solid samples during laboratory procedures. The borosilicate segment dominates value generation due to thermal shock resistance and reusability in analytical chemistry, while polypropylene tubes lead volume growth in single-use diagnostic and clinical workflows where sterility and disposability eliminate cross-contamination risk. Glass tubes retain structural importance in educational institutions and traditional wet chemistry applications where visual observation and direct flame heating remain essential.
FDA quality system regulations and EU REACH chemical compliance frameworks govern material composition, biocompatibility testing, and supply chain documentation for test tubes entering clinical and research channels. ISO 10993 biological evaluation standards further constrain polymer selection and leachable profiles for manufacturers targeting in vitro diagnostic applications. Laboratories and procurement consortia must monitor evolving EPA and ECHA substance restrictions that could disqualify specific plasticizers or surface treatments from certified product lines.
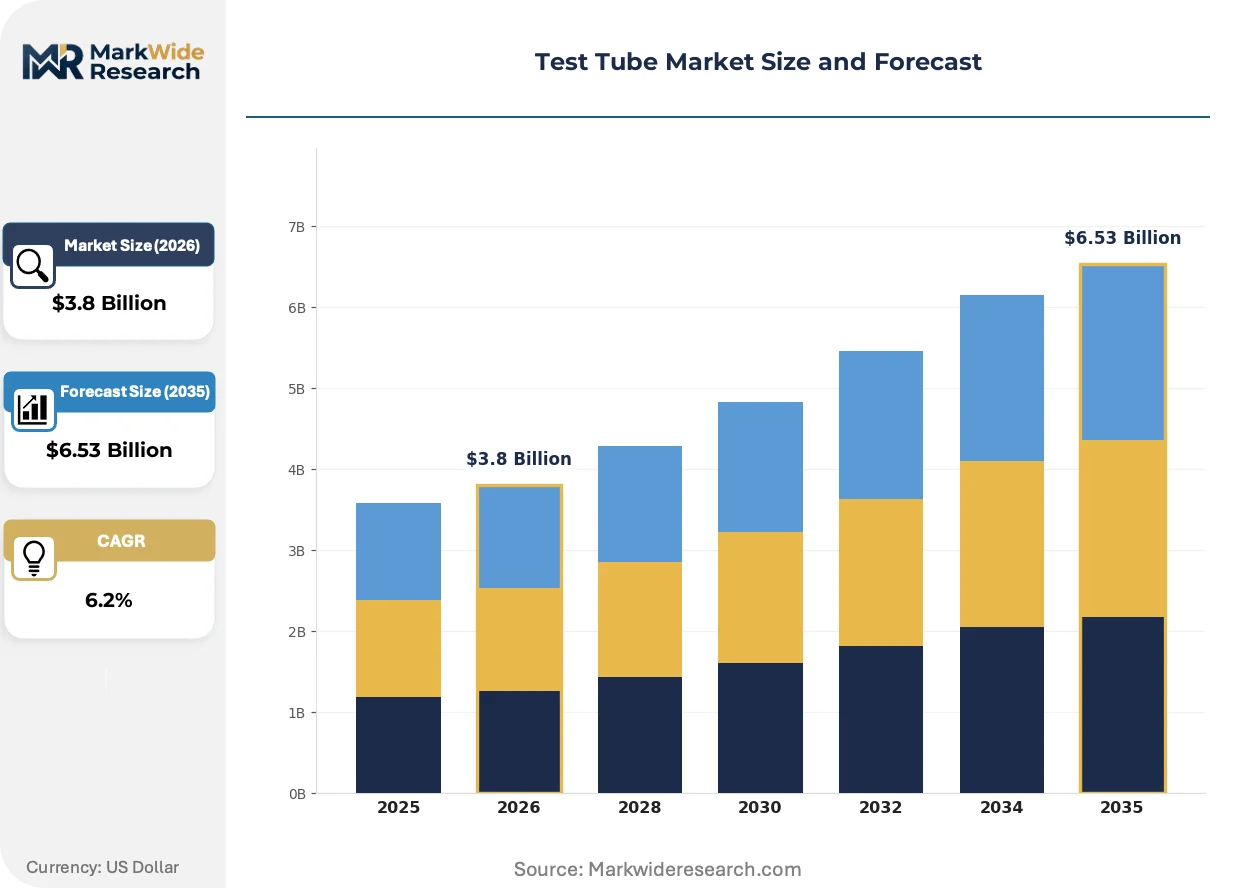
Market Dynamics
Hospital consolidation in the United States and diagnostic laboratory expansion across Germany are compressing procurement cycles and forcing standardization of consumables specifications, shifting purchasing power toward integrated health networks and reference laboratory chains.
Growth Catalysts
- High-throughput screening automation:Diagnostic laboratories in Germany and the United States are scaling automated liquid handling platforms that require precision-molded polypropylene tubes with dimensional tolerances compatible with robotic gripper systems.
- REACH compliance enforcement:ECHA substance restrictions on plasticizers and surface treatments are accelerating replacement of legacy polymer formulations with certified medical-grade resins in European Union supply chains.
- Reference laboratory expansion:Consolidated hospital networks in the United States are centralizing testing volumes into regional reference laboratories, creating concentrated demand for standardized borosilicate and plastic tube specifications.
Market Restraints
- Medical-grade borosilicate supply concentration:Chinese glass manufacturers are redirecting capacity toward domestic medical certification standards, constraining export availability for European converters dependent on imported tubing.
- Raw material cost volatility:Polypropylene resin prices fluctuate with petrochemical feedstock markets, compressing margins for single-use tube producers serving price-sensitive clinical diagnostics segments.
- ISO 10993 certification timelines:Extended biological evaluation protocols for polymer leachable profiles delay product launches for manufacturers targeting in vitro diagnostic applications.
Strategic Opportunities
- Point-of-care testing expansion:Decentralized diagnostic workflows in rural United States health systems are creating demand for pre-sterilized, individually packaged tubes optimized for near-patient testing environments.
- EU Green Deal circularity mandates:Packaging reduction requirements and recyclability standards are opening markets for bio-based polymer formulations and closed-loop manufacturing processes in European Union member states.
- Automated storage and retrieval integration:Convergence of tube manufacturing with RFID tagging and barcode serialization is enabling direct integration with laboratory information management systems in high-volume German diagnostic facilities.
Industry Challenges
- ISO 13485 quality management implementation:Smaller polymer converters face capital intensity and technical documentation burdens when upgrading from research-grade to medical-device-certified production lines.
- Legacy equipment compatibility:Automated liquid handling platforms from different OEMs require subtly varied tube geometries, forcing manufacturers to maintain multiple tooling configurations or risk exclusion from approved vendor lists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Test Tube Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.53 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glass, Plastic, Borosilicate, Polypropylene Size: 5ml, 10ml, 15ml, 25ml End User: Laboratories, Educational Institutions, Research Facilities, Hospitals Application: Chemical Analysis, Sample Storage, Biological Testing, Educational Experiments |
| Companies Covered | Hirschmann Laborgeräte GmbH & Co. KG, Adrian Sistem SRL, DWK Life Sciences GmbH, Irish Life Sciences, Quarzglas Komponenten und Service QCS GmbH, Eppendorf SE, Glassco Laboratory Equipments Pvt. Ltd., Thermo Fisher Scientific, Carl Roth GmbH + Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Test Tube Market Evolving Landscape
Material science advances and regulatory traceability mandates are converging to reshape tube manufacturing specifications, with automation compatibility and chemical compliance emerging as the primary axes of product differentiation.
Precision-molded polypropylene formulations with enhanced dimensional stability are integrating directly into automated liquid handling workflows. High-throughput screening facilities in German diagnostic laboratories are adopting these tubes at accelerated replacement cycles. This integration is compressing the market for legacy soda-lime glass alternatives that lack robotic handling compatibility.
EU REACH substance restrictions and evolving FDA quality system regulations for in vitro diagnostics are tightening material traceability requirements across supply chains. Manufacturers must now document polymer sourcing, additive compositions, and sterilization validation for every production lot. Clinical diagnostic OEMs in the United States and European Union are responding by consolidating supplier bases around ISO 13485-certified converters with integrated quality management systems.
Consolidated purchasing by United States hospital networks and reference laboratory chains is displacing fragmented distributor-based procurement. Integrated health systems are negotiating direct contracts with tube manufacturers for multi-year supply agreements with volume commitments and specification lock-ins. This behavioral shift is most visible in the Northeast and Midwest United States, where hospital merger activity has concentrated testing volumes into fewer procurement decision points.
Test Tube Market Segmentation
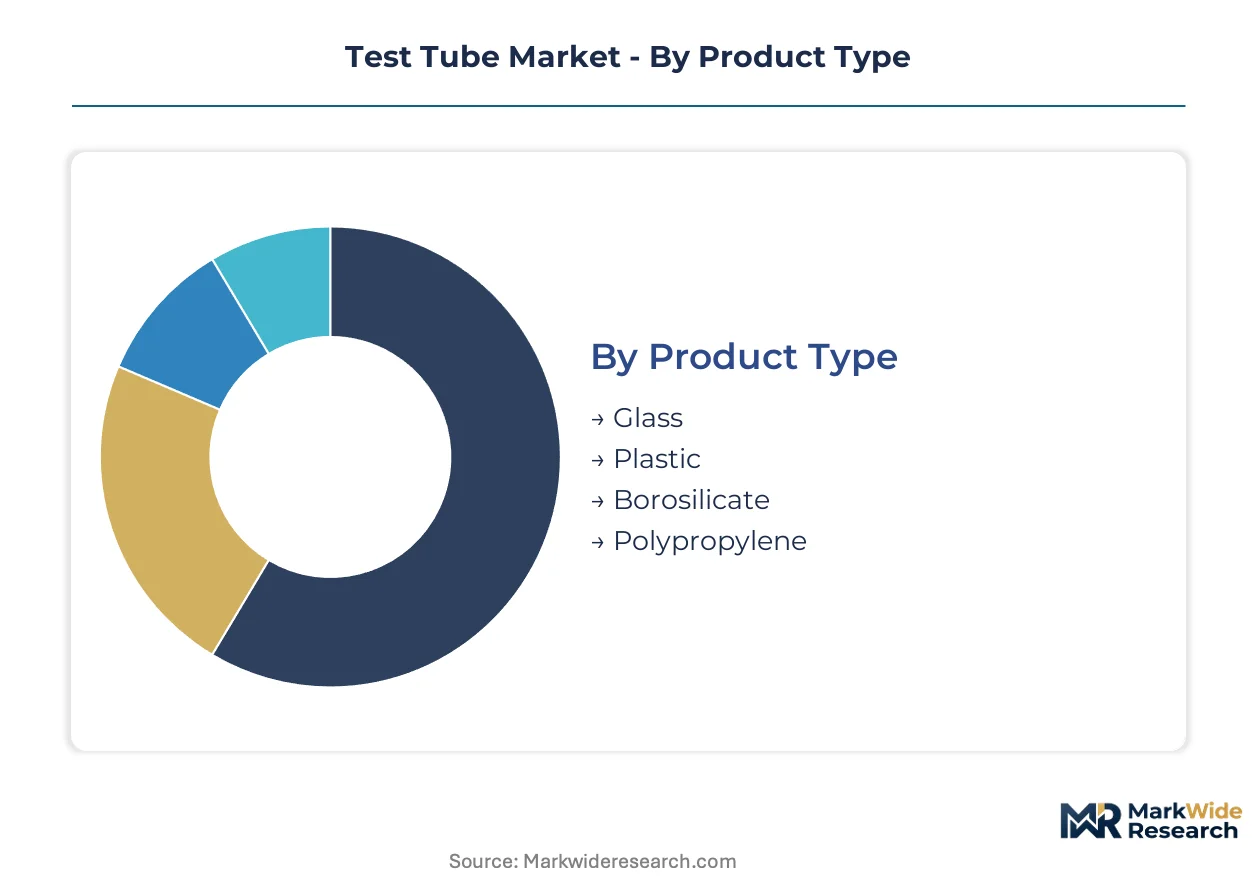
Material composition and dimensional precision determine automation compatibility and regulatory compliance pathways for test tube procurement. Segmentation reveals how capital deployment varies sharply across manufacturing technologies and end-use certification requirements.
Product Type:
Glass and borosilicate manufacturing demand substantial furnace infrastructure and thermal processing equipment, while polymer conversion requires precision molding tooling and cleanroom certification.
- Glass:Soda-lime formulations dominate educational and basic wet chemistry applications where direct flame heating and visual sample observation remain essential. Schools and community colleges across the United States sustain replacement demand for this lowest-cost category despite limited automation compatibility.
- Borosilicate:Thermal shock resistance enables repeated autoclave sterilization cycles, making this specification mandatory for analytical chemistry workflows in German pharmaceutical quality control laboratories. REACH compliance documentation and ISO 13485 certification requirements concentrate supply among established European converters with integrated quality management systems.
- Plastic:General-purpose polymer tubes serve non-certified research applications where cost minimization outweighs traceability requirements. University research facilities in India and Southeast Asia absorb significant volumes of this specification.
- Polypropylene:Precision-molded variants with tight dimensional tolerances integrate directly into automated liquid handling platforms deployed by United States reference laboratory chains. FDA quality system regulations for in vitro diagnostics constrain supplier qualification to ISO 10993-certified manufacturers with documented leachable profiles.
Borosilicate absorbs the bulk of installed capacity; polypropylene is expanding most quickly.
Size:
Volume specifications align with distinct workflow economics — larger formats serve bulk reagent handling while micro-volumes enable high-density automated screening.
- 5ml:Micro-volume tubes optimize plate-based screening densities in German diagnostic facilities running high-throughput immunoassay workflows. Precision molding tolerances become critical at this scale for robotic gripper reliability.
- 10ml:Standard clinical chemistry volumes dominate hospital laboratory procurement in the United States, where consolidation into regional reference labs has standardized around this intermediate specification for general-purpose testing.
- 15ml:Centrifuge-compatible conical derivatives serve cell culture and sample preparation workflows in biotechnology manufacturing. Single-use adoption rates climb fastest among contract research organizations in Massachusetts and California.
- 25ml:Large-format tubes retain niche demand for bulk media preparation and environmental sample collection. Limited automation compatibility constrains growth outside educational and field research applications.
10ml specifications command the largest procurement volumes; 5ml formats are climbing the fastest.
End User:
Certification intensity varies dramatically across customer types — clinical diagnostics demands medical-device-grade documentation while education markets prioritize cost minimization.
- Laboratories:Diagnostic and analytical facilities drive premium specification demand, with ISO 13485-certified supply chains mandatory for United States hospital network procurement. Automated platform integration requirements favor precision-molded polypropylene from qualified vendors.
- Educational Institutions:Secondary schools and undergraduate chemistry programs sustain soda-lime glass demand through replacement cycles. Budget constraints limit penetration of borosilicate or certified polymer alternatives despite superior durability.
- Research Facilities:Academic and government laboratories exhibit fragmented procurement with mixed requirements — some workflows demand medical-grade traceability while others accept research-grade specifications. Funding volatility complicates multi-year supply agreements.
- Hospitals:Consolidated health networks in the United States Northeast and Midwest have centralized testing into regional reference laboratories, concentrating purchasing power and standardizing around ISO 13485-certified borosilicate and polypropylene specifications.
Laboratories absorb the bulk of certified capacity; hospital network consolidation is concentrating demand fastest.
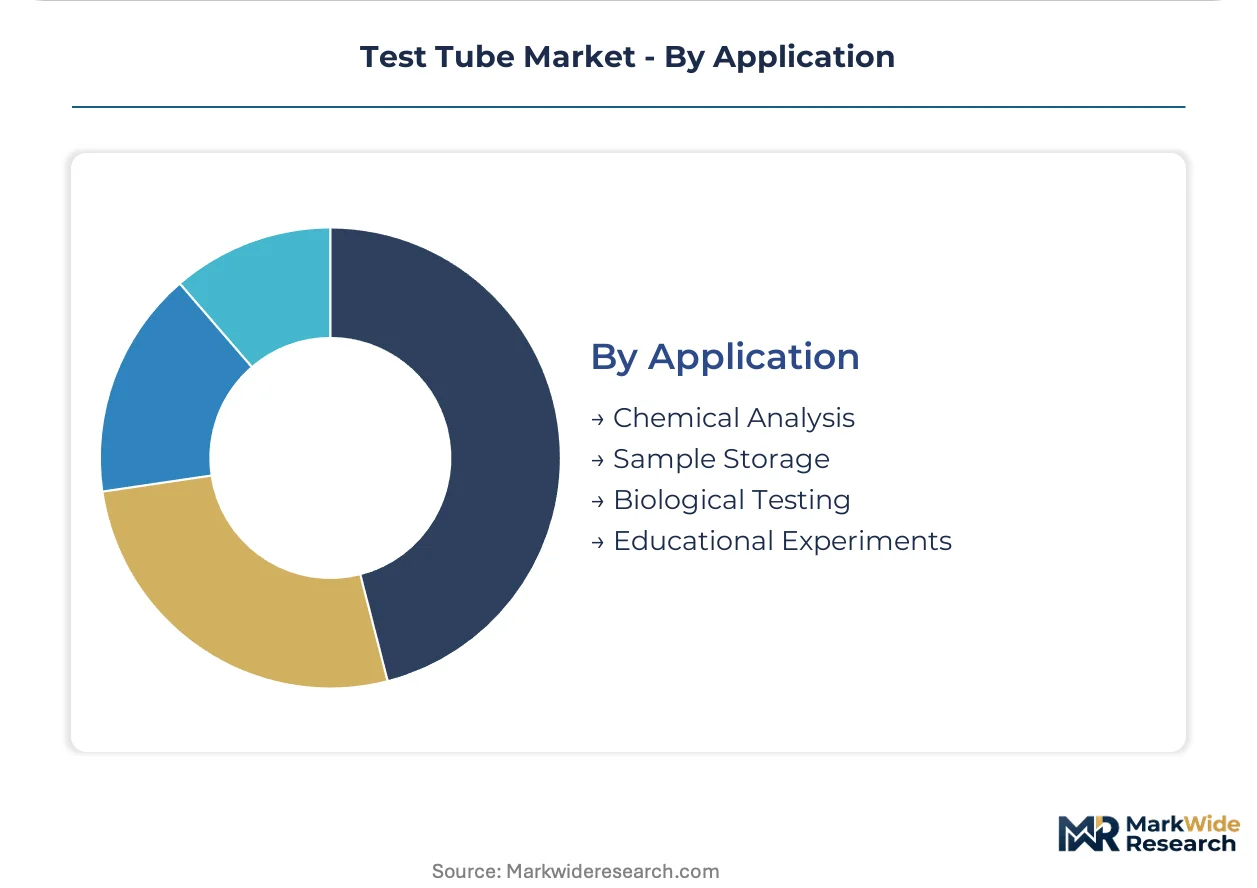
Application:
Functional requirements determine material selection — thermal stress and chemical compatibility differentiate analytical workflows from biological containment needs.
- Chemical Analysis:Borosilicate glass dominates titration, distillation, and thermal decomposition workflows where direct flame heating and solvent resistance are non-negotiable. German industrial laboratories maintain stringent specifications for pharmaceutical quality control applications.
- Sample Storage:Cryogenic compatibility and seal integrity drive demand for polypropylene formats with threaded closures in biobanking and clinical reference laboratories. United States biopharma manufacturing expansion sustains double-digit demand growth for certified storage tubes.
- Biological Testing:Sterility assurance and endotoxin limits constrain supplier qualification for cell culture and diagnostic applications. FDA quality system regulations enforce lot-level traceability from polymer resin through sterilization validation.
- Educational Experiments:Visual observation requirements and flame heating compatibility preserve soda-lime glass demand despite fragility and limited reusability. Budget pressures in public education systems resist conversion to polymer alternatives.
Chemical analysis absorbs the bulk of borosilicate capacity; sample storage applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Borosilicate glass feedstock from Chinese foundries anchors supply availability for European converters, while polypropylene resin pricing tied to Gulf Coast petrochemical output shapes North American manufacturing economics.
United States
Hospital network consolidation in the Northeast and Midwest concentrates testing volumes into regional reference laboratories, driving standardized procurement of ISO 13485-certified consumables. FDA quality system regulations for in vitro diagnostics enforce lot-level traceability from polymer resin through sterilization validation. Greater Boston hosts contract research organizations absorbing single-use polypropylene tubes at accelerated replacement cycles.
Germany
Diagnostic laboratory expansion across Bavaria and North Rhine-Westphalia scales automated liquid handling platforms requiring precision-molded tubes with robotic gripper compatibility. EU REACH substance restrictions on plasticizers accelerate replacement of legacy polymer formulations with certified medical-grade resins. The Rhine-Main cluster around Frankfurt anchors ISO 13485-certified conversion capacity for pharmaceutical quality control applications.
China
Domestic medical-grade certification standards redirect borosilicate glass production capacity toward internal market fulfillment, constraining export availability for European converters. The country's national pharmaceutical regulator tightens material traceability requirements for clinical diagnostic applications. The Yangtze River Delta concentration of glass foundries prioritizes output for domestic biopharma manufacturing expansion.
India
University research facilities and government laboratories sustain fragmented procurement with mixed certification requirements across basic and applied science workflows. The country's central drug regulator enforces biocompatibility testing protocols for polymer leachable profiles in diagnostic applications. Maharashtra's Mumbai-Pune corridor concentrates educational institution demand for soda-lime glass alternatives.
Japan
Precision manufacturing standards in analytical chemistry sustain demand for thermal shock-resistant borosilicate specifications in pharmaceutical quality control. METI industrial policy supports domestic medical-device-grade certification for polymer converters targeting export markets. The Kansai region around Osaka maintains specialized conversion capacity for high-purity glass tubing.
Test Tube Market Competitive Landscape
Global majors compete with regional champions across certification tiers and automation compatibility specifications. The vendor base organizes around ISO 13485-certified medical-device specialists, precision-molded polymer converters, and legacy glass fabricators serving educational markets. Three archetypes dominate: integrated life science conglomerates with direct hospital contracts, mid-cap German converters leveraging REACH-compliant supply chains, and Asian fabricators competing on research-grade volume. Competitive moves concentrate on strategic partnerships with diagnostic OEMs and backward integration into medical-grade resin sourcing.
Within the German converter tier, DWK Life Sciences GmbH and Carl Roth GmbH + Co. KG exemplify ISO 13485-certified manufacturers sustaining integrated quality management systems. Thermo Fisher Scientific anchors North American distribution through direct contracting with consolidated hospital networks. Eppendorf SE occupies a position among precision-molded polypropylene specialists optimized for automated liquid handling integration.
| Leading Market Players |
|---|
| Hirschmann Laborgeräte GmbH & Co. KG |
| Adrian Sistem SRL |
| DWK Life Sciences GmbH |
| Irish Life Sciences |
| Quarzglas Komponenten und Service QCS GmbH |
| Eppendorf SE |
| Glassco Laboratory Equipments Pvt. Ltd. |
| Thermo Fisher Scientific |
| Carl Roth GmbH + Co. KG |
| Others |
Value Network & Pricing Analysis
Polypropylene resin pricing indexed to Gulf Coast petrochemical benchmarks cascades through converter margins into three distinct procurement tiers for end-users across United States hospital networks and German diagnostic facilities.
Pricing Analysis
Warranty and lot-level traceability documentation are unbundled from base unit pricing in research-grade segments, while ISO 13485-certified supply chains command bundled validation services. Three-tier pricing structure across premium certified, standard medical-grade, and economy research levels separates procurement economics. Cost compression in single-use polypropylene is intensifying because petrochemical feedstock volatility passes directly through to clinical diagnostics producers. United States reference laboratories exhibit lowest price sensitivity due to consolidated purchasing power, while Indian educational institutions remain most cost-constrained.
Supply Chain Analysis
Single-source vulnerability sits with Chinese borosilicate glass foundries redirecting capacity toward domestic medical certification standards. Raw material dependencies draw from Yangtze River Delta glass production, Louisiana Gulf Coast polymer resin, and German ISO-certified conversion equipment. Tariff exposure on medical-grade tubing imports into the European Union compounds supply risk for converters dependent on Asian feedstock. Distribution runs through direct manufacturer contracts with consolidated health networks, displacing legacy distributor intermediation in North America and Western Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
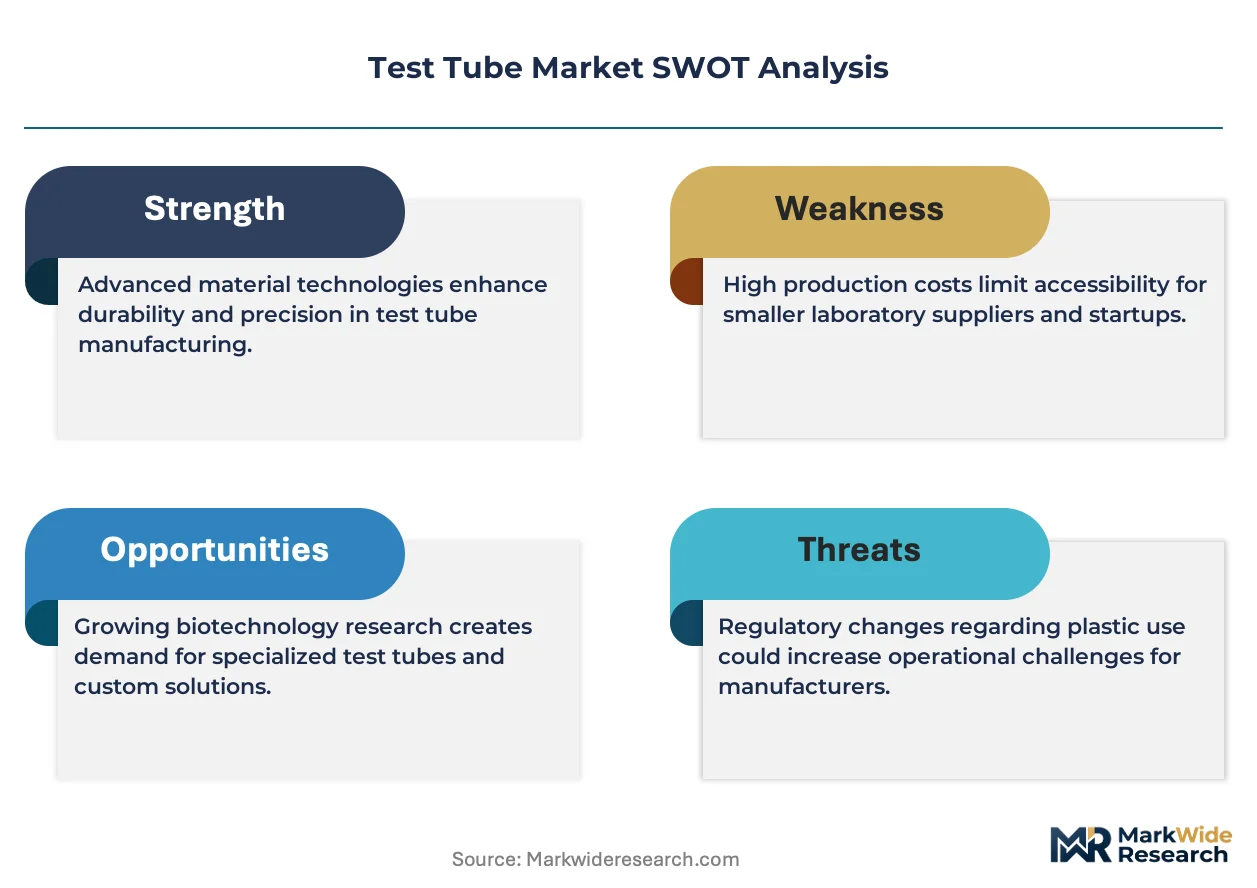
Medical-grade borosilicate capacity constraints in China prop pricing power for converters with REACH-compliant European supply chains, creating a supply-constrained market structure favoring incumbent consolidation.
For Market Incumbents: Anticipate margin compression from automated liquid handling OEMs demanding tighter dimensional tolerances by securing captive resin supply through backward integration into medical-grade polypropylene sourcing. Defend positioning against emerging Asian converters by accelerating ISO 10993 certification timelines for expanded leachable profile documentation. For New Entrants and Emerging Players: Capture white-space opportunity in point-of-care testing consumables for rural United States health systems requiring pre-sterilized individual packaging. Target bio-based polymer formulations serving EU Green Deal circularity mandates as the most penetrable regulatory-driven segment, with go-to-market execution through diagnostic OEM co-development partnerships. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap German ISO 13485-certified converters with integrated quality management systems and established REACH documentation capabilities. Long-term viability over a multi-year horizon hinges on automation compatibility certification and direct hospital network contract relationships. Watch for inflection signals in FDA quality system regulation enforcement timelines affecting polymer leachable profile requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Medical-Grade Resin Sourcing | Secures supply continuity for polypropylene converters facing Gulf Coast petrochemical volatility. |
| ISO 10993 Biological Evaluation Investment | Accelerates FDA pathway approval for in vitro diagnostic tube applications in United States markets. |
| RFID Tagging and Barcode Serialization Integration | Enables direct laboratory information management system connectivity for German diagnostic facilities. |
| EU Green Deal Bio-Based Polymer Transition | Opens procurement channels with circularity-mandated European Union member state health systems. |
| Direct Hospital Network Contract Consolidation | Displaces distributor intermediation in United States Northeast and Midwest reference laboratory procurement. |
Research Methodology
Independent corroboration across primary interviews with diagnostic laboratory procurement managers, polymer converter operations directors, and hospital GPO contracts specialists, combined with secondary validation through FDA quality system regulation filings, ECHA REACH substance restriction databases, and ISO certification registries, underwrites the qualitative findings. Bottom-up demand modeling from end-user procurement volumes triangulates against top-down supply capacity assessments across Chinese glass foundries and Gulf Coast resin production.
Comparable-period anchoring to historical certification timeline data and automation adoption curves structures the projection horizon across material type, end-user certification intensity, and regional regulatory cluster dimensions. CAGRs derive from segmented volume-weighted growth trajectories incorporating polypropylene resin price elasticity, REACH compliance cost pass-through rates, and reference laboratory consolidation pace as industry-specific forecast inputs.
The model holds under stable regulatory enforcement intensity and petrochemical feedstock supply continuity; deviation in FDA quality system regulation timeline acceleration or Chinese export restriction implementation would shift volume and value trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Histopathology Testing Equipment Market
Laboratory Equipment
C-Reactive Protein Analyzers Market
Laboratory Equipment
Global Laboratory Grinders Market
Laboratory Equipment
Ion-Selective Clinical Lab Analyzers Market
Laboratory Equipment
Glycohemoglobin Analyzers Market
Laboratory Equipment
Histopathology Laboratory Equipment Market
Laboratory Equipment
Global Pipettes and Pipettors Market
Laboratory Equipment
Capillary Blood Collection Tubes Market
Laboratory Equipment
Global Hematology Instruments and Reagents Market
Laboratory Equipment
Automated Nucleic Acid Extraction Systems Market
Laboratory Equipment
Microplate Luminometer Market
Laboratory Equipment
Scalable Clinical Chemistry Analyzers Market
Laboratory Equipment
Colony Counters Market
Laboratory Equipment
Blood Bank Analyzers Market
Laboratory Equipment
Electrophoresis Transilluminator Market
Laboratory Equipment
Human Platelet Lysate Market