
 Histopathology Laboratory Equipment Market | 2026-2036
Histopathology Laboratory Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Histopathology Laboratory Equipment Market Insights
A widening capability gap between fully automated platform providers and manual-equipment suppliers is reorganizing competitive tiers in histopathology instrumentation. Thermo Fisher Scientific leverages its life sciences conglomerate structure to bundle reagent contracts with hardware placements across hospital networks. Leica Biosystems anchors its position through backward integration into consumables and embedded software workflows for cancer diagnostics. Sakura Finetek competes on manufacturing scale in tissue-processing equipment, particularly in high-throughput pathology laboratories in East Asia.
Histopathology laboratory equipment encompasses instruments for tissue acquisition, fixation, processing, embedding, sectioning, staining, and microscopic examination, typically operating with section thickness precision of 1–500 micrometers and temperature-controlled paraffin embedding at 56–62°C to preserve cellular morphology for disease diagnosis. The primary commercial purpose is enabling pathologists to render definitive cancer diagnoses from biopsy specimens with reproducible quality. Digital pathology systems are capturing margin pools as laboratories convert glass-slide archives to whole-slide imaging databases, while automated equipment categories are displacing traditional methods in high-volume diagnostic centers where labor costs and turnaround-time pressures intensify. AI-enabled imaging remains concentrated in research laboratories and select cancer-diagnosis workflows, with regulatory clearance pathways determining pace of hospital adoption.
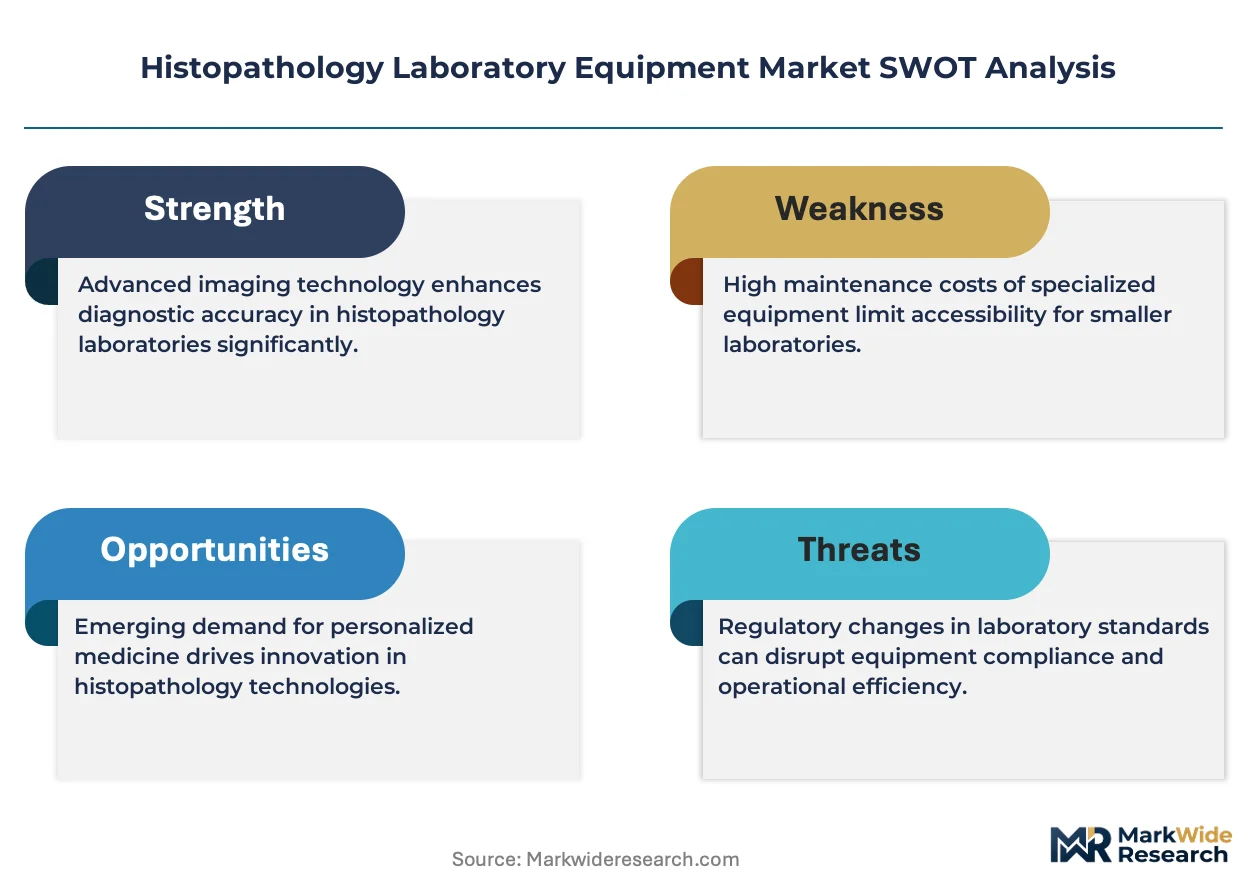
FDA quality system regulation and CLIA laboratory certification requirements shape equipment validation protocols and service documentation obligations for manufacturers selling into US diagnostic centers. The EU Medical Device Regulation and IVDR transition impose conformity assessment burdens on slide stainers and digital pathology scanners marketed in Europe, while ISO 15189 accreditation standards drive preventive maintenance and traceability specifications across hospital laboratories worldwide. Stakeholders must monitor how FDA guidance on artificial-intelligence-enabled diagnostic devices reshapes product development roadmaps and go-to-market timelines for automated imaging platforms.
Market Dynamics
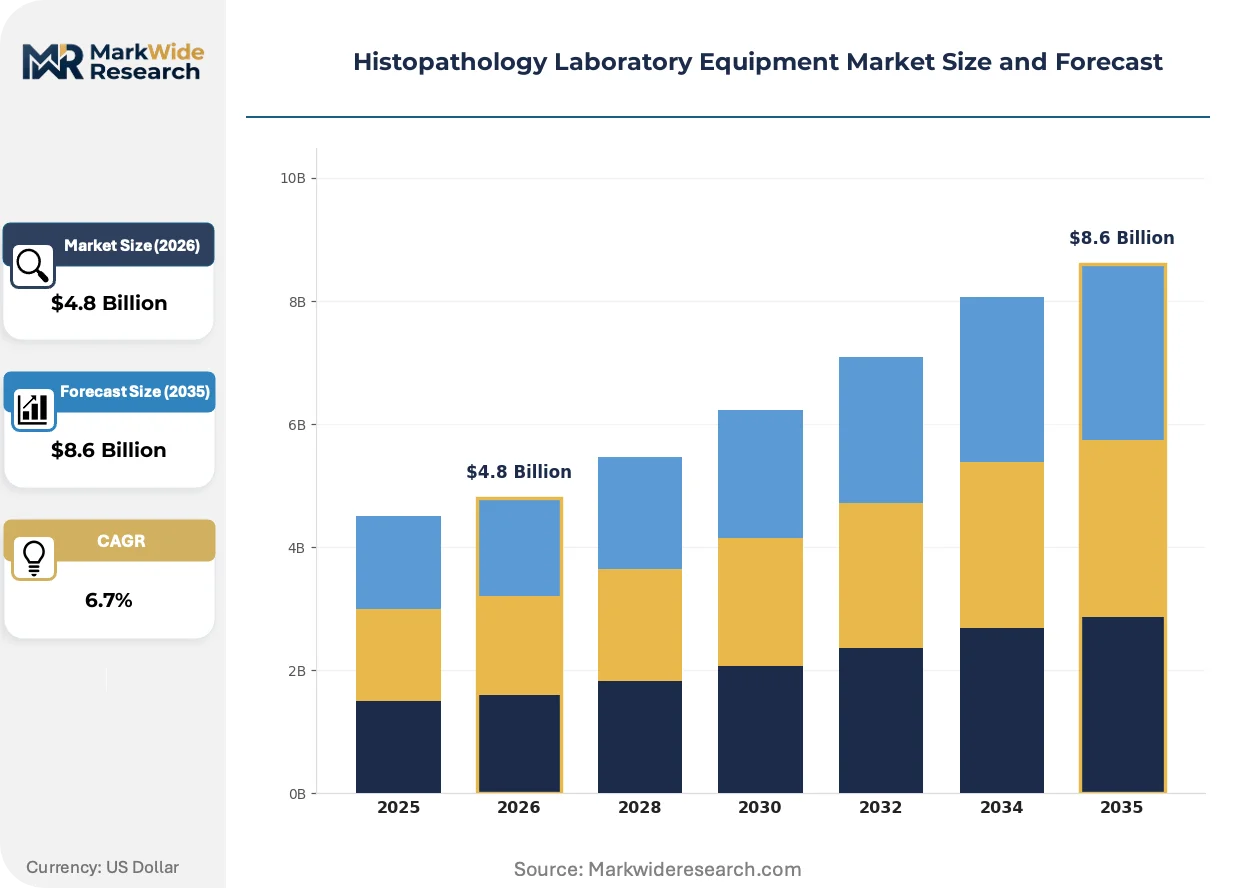
Automated tissue processing systems are compressing turnaround times in high-volume diagnostic centers while FDA quality system regulations tighten validation protocols for in vitro diagnostic devices. This dual pressure of operational speed demands and compliance complexity is restructuring procurement patterns across hospital-based laboratories.
Growth Catalysts
- CLIA Laboratory Certification:US diagnostic centers must maintain rigorous quality standards, driving replacement cycles for aging manual equipment with validated automated platforms that ensure reproducible specimen processing.
- Digital Pathology Infrastructure:Academic medical centers are converting glass-slide archives to whole-slide imaging databases, creating pull-through demand for compatible tissue preparation and staining instrumentation.
- Cancer Diagnostics Volume:Rising biopsy specimen loads in integrated delivery networks necessitate high-throughput processing capacity that manual methods cannot sustain.
Market Restraints
- Capital Equipment Intensity:Automated tissue processors and digital pathology scanners require substantial upfront investment that constrains independent pathology laboratories and smaller diagnostic facilities.
- Consumables Lock-In:Proprietary reagent contracts bundled with hardware placements create switching costs that limit vendor flexibility for hospital procurement departments.
- EU IVDR Transition:The In Vitro Diagnostic Regulation imposes extended conformity assessment timelines and clinical evidence requirements on slide stainers and imaging systems marketed in Europe.
Strategic Opportunities
- AI-Enabled Diagnostic Workflows:FDA guidance on artificial-intelligence-enabled devices is creating regulatory pathways for automated image analysis that can differentiate platform offerings in research-to-clinic transitions.
- Service Unbundling:After-sales preventive maintenance and remote monitoring contracts represent margin expansion opportunities beyond initial hardware placement.
- Emerging Asia-Pacific Markets:High-throughput pathology laboratories in East Asia present demand concentration for manufacturing-scale tissue processing equipment.
Industry Challenges
- Technical Workforce Scarcity:Pathology laboratories face shortages of histotechnologists trained to operate sophisticated automated platforms and troubleshoot complex staining protocols.
- Legacy System Integration:Digital pathology adoption requires interoperability with existing laboratory information systems and electronic medical records, creating implementation friction.
- ISO 15189 Accreditation Burden:Preventive maintenance documentation and traceability specifications demand dedicated quality management resources that strain smaller laboratory operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Histopathology Laboratory Equipment Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microscopes, Tissue Processors, Slide Stainers, Embedding Centers Application: Cancer Diagnosis, Research Laboratories, Educational Institutions, Biobanking End User: Hospitals, Diagnostic Centers, Academic Institutes, Pharmaceutical Companies Technology: Digital Pathology, AI-enabled Imaging, Automated Equipment, Traditional Methods |
| Companies Covered | Thermo Fisher Scientific, Roche, Leica Biosystems, Agilent Technologies, Danaher Corporation, Sakura Finetek, Hologic, PerkinElmer, Epredia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Histopathology Laboratory Equipment Market Trends and Innovations
Whole-slide imaging and automated staining platforms are converging to create integrated diagnostic workflows that compress the time from specimen acquisition to pathologist review. This technological consolidation is altering competitive positioning and procurement evaluation criteria.
Autostainers with multiplex immunohistochemistry capability are displacing manual staining protocols in cancer diagnostic workflows. Academic medical centers are deploying these platforms to handle rising biomarker testing volumes. The technology is displacing traditional single-marker methods by enabling simultaneous detection of multiple protein targets on a single tissue section, reducing both reagent consumption and pathologist review time.
The EU Medical Device Regulation and IVDR transition impose stricter conformity assessment burdens on equipment marketed in Europe. Manufacturers must now compile extensive clinical evidence and quality management documentation. Digital pathology scanners and automated tissue processors face extended certification timelines, compressing product launch windows and favoring established vendors with regulatory affairs infrastructure.
Hospital procurement departments are consolidating vendor relationships through multi-year reagent and service contracts tied to hardware placements. Integrated delivery networks favor suppliers offering embedded software workflows and backward integration into consumables. The United States anchors this pattern, where academic medical centers and large health systems leverage volume concentration to negotiate bundled pricing arrangements.
Histopathology Laboratory Equipment Market Segmentation
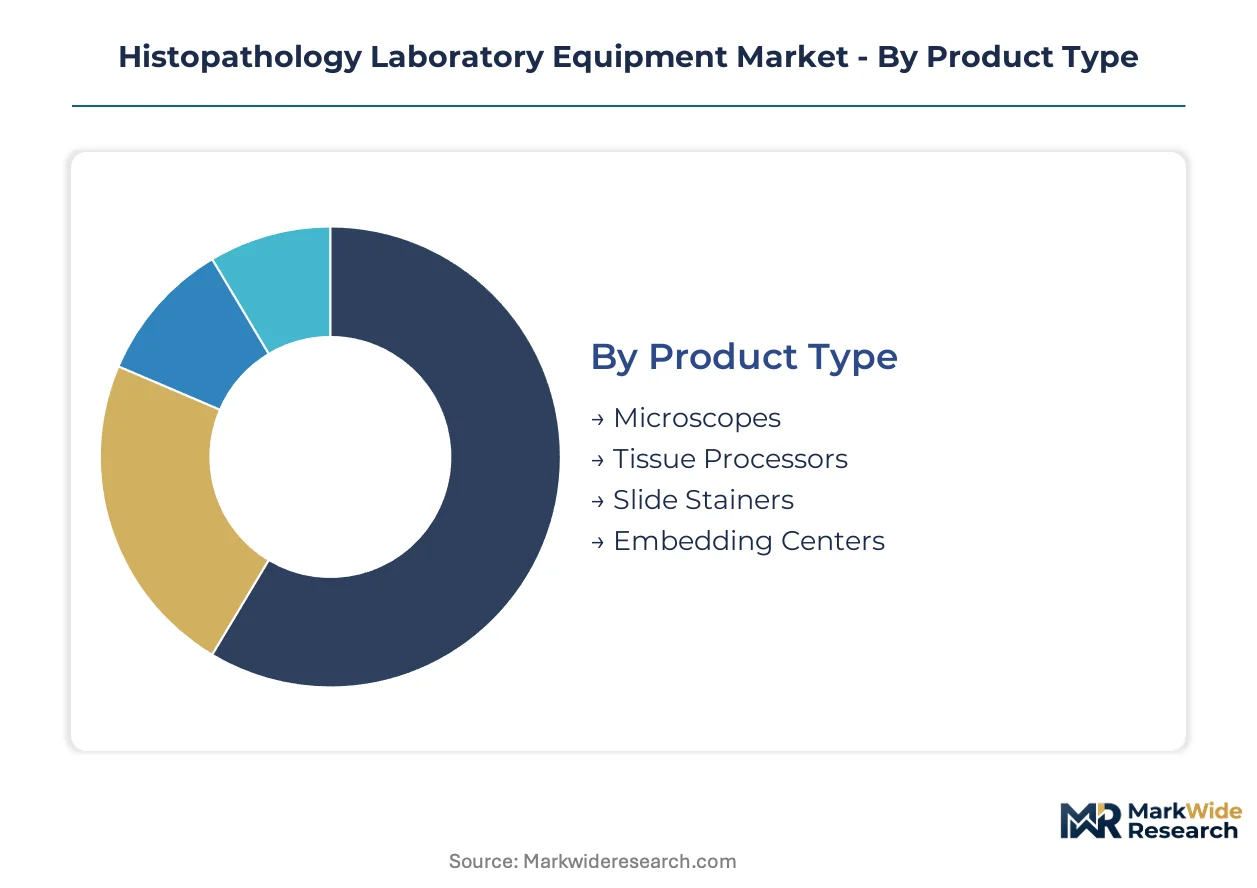
Histopathology equipment purchasing patterns diverge sharply across product categories and user settings. Automated platforms command premium placement in high-throughput hospital networks while manual systems retain footholds in resource-constrained environments. Understanding these segment boundaries clarifies where capital deployment concentrates and where replacement cycles accelerate.
Product Type:
Domestic manufacturing dominates tissue processors and embedding centers, while digital microscopy platforms flow through concentrated import channels from German and Japanese suppliers.
- Microscopes:Optical systems with 40x-1000x magnification ranges and LED illumination modules. Demand clusters in academic medical centers across the United States upgrading from halogen to solid-state light sources for whole-slide imaging compatibility.
- Tissue Processors:Automated vacuum-infiltration systems processing 100-300 cassettes per run with programmable ethanol-xylene-paraffin sequences. Hospital-based diagnostic laboratories in Germany and Japan prioritize these units to compress turnaround times under CLIA-equivalent accreditation pressures.
- Slide Stainers:Hematoxylin-eosin and special stain automation platforms with reagent carousel capacities exceeding 500 slides daily.
- Embedding Centers:Temperature-controlled paraffin dispensing workstations operating at 56-62°C with cold plate integration for rapid block solidification.
Microscopes command the established base. The steepest expansion runs through tissue processors.
Application:
Cancer diagnosis workflows absorb the majority of high-margin automated placements, while research and biobanking applications drive modular, configurable system specifications.
- Cancer Diagnosis:Immunohistochemistry and in-situ hybridization protocols requiring antigen retrieval and multiplex staining capabilities. Integrated delivery networks in the United States deploy these platforms to handle rising biomarker testing volumes from precision oncology programs.
- Research Laboratories:Flexible instrumentation supporting experimental protocols with customizable staining parameters and open reagent architectures. Demand concentrates at NIH-funded cancer centers and pharmaceutical discovery sites where protocol variation exceeds clinical standardization.
- Educational Institutions:Entry-level microscopes and manual processing equipment for histotechnology training programs.
- Biobanking:High-capacity tissue processors and barcode-integrated tracking systems for specimen repository operations.
Cancer diagnosis commands the established base. The steepest expansion runs through biobanking.
End User:
Hospital procurement departments negotiate multi-year bundled contracts, while diagnostic centers and academic institutes purchase through more fragmented, project-based channels.
- Hospitals:Enterprise-wide standardization of automated platforms with service contracts covering preventive maintenance and remote diagnostics. Academic medical centers in the United States anchor this segment through centralized pathology departments serving multiple affiliated sites.
- Diagnostic Centers:Independent laboratories prioritizing throughput-per-square-foot and lean staffing models. These facilities in India and Brazil select compact, multi-function platforms to maximize specimen processing capacity within limited facility footprints.
- Academic Institutes:Research-oriented configurations with emphasis on publication-grade image quality and flexible workflow integration.
- Pharmaceutical Companies:GLP-compliant systems with extensive validation documentation and audit trail capabilities for regulatory submissions.
Hospitals command the established base. The steepest expansion runs through diagnostic centers.
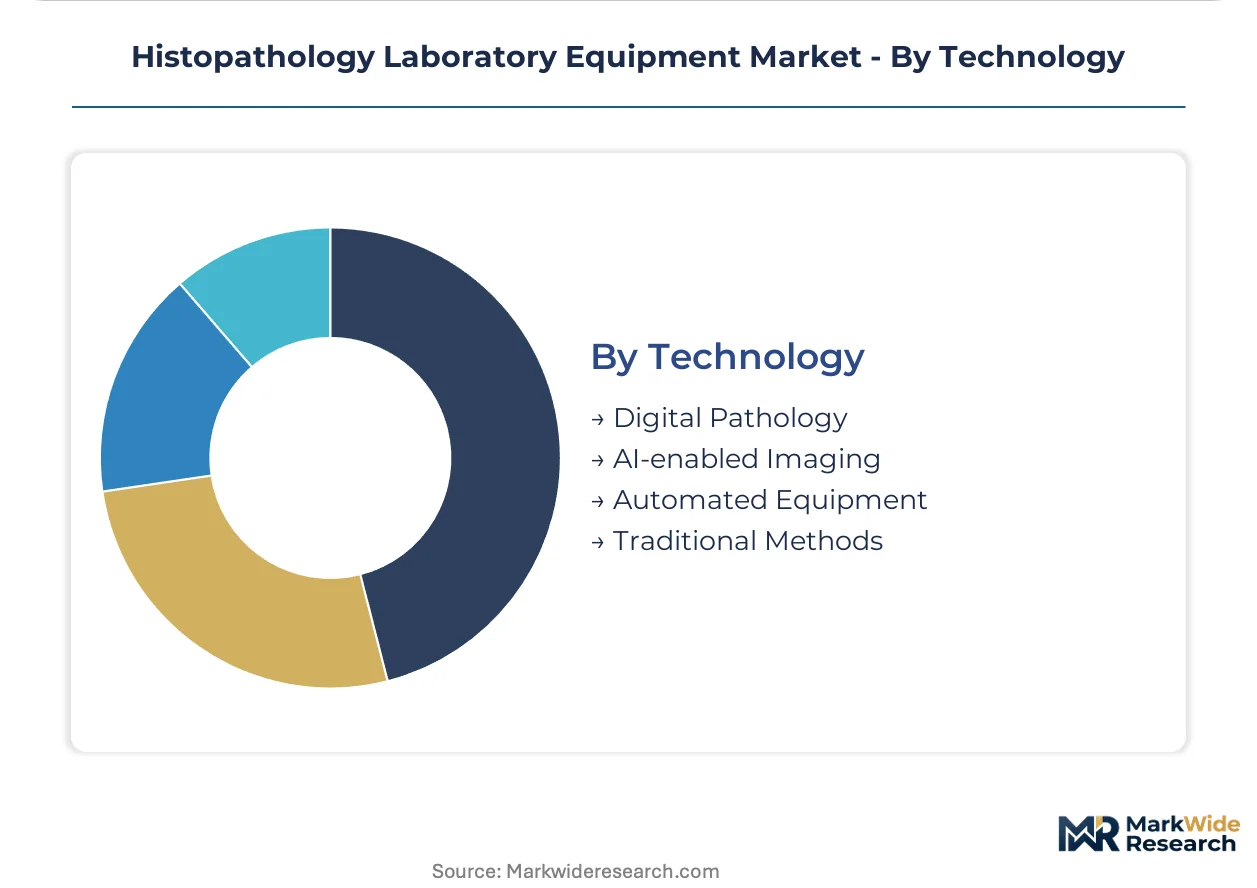
Technology:
Digital pathology adoption splits between greenfield installations in new facilities and retrofit integrations with legacy laboratory information systems.
- Digital Pathology:Whole-slide imaging scanners with 20x-40x objective magnification and z-stack capabilities for cytology applications. Deployment concentrates in the Netherlands and United Kingdom where national health systems fund centralized digitization initiatives for remote consultation networks.
- AI-enabled Imaging:Algorithm-assisted screening tools for lymph node metastasis detection and biomarker quantification. FDA breakthrough device designation pathways are accelerating hospital adoption in the United States for specific cancer indications.
- Automated Equipment:Robotic tissue handling and staining platforms with barcode tracking and load-leveling algorithms.
- Traditional Methods:Manual microtomy, hand staining, and conventional brightfield microscopy for low-volume or specialized applications.
Traditional methods command the established base. The steepest expansion runs through AI-enabled imaging.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where bundled reagent contracts anchor premium placements, while procurement in India and Brazil prioritizes throughput-per-square-foot economics that compress hardware margins.
United States
Academic medical centers and integrated delivery networks drive capital deployment for digital pathology infrastructure. FDA quality system regulations tighten validation protocols for in vitro diagnostic devices, extending procurement cycles. The Boston-Cambridge corridor hosts concentrated precision oncology programs generating sustained biomarker testing demand.
Germany
Hospital-based diagnostic laboratories prioritize automated tissue processors to compress turnaround times under CLIA-equivalent accreditation pressures. EU Medical Device Regulation and IVDR transition impose extended conformity assessment timelines on slide stainers. The Rhine-Ruhr industrial cluster anchors manufacturing-scale demand for high-throughput pathology equipment.
Japan
High-throughput pathology laboratories in East Asia concentrate procurement of manufacturing-scale tissue processing equipment. METI standards and PMDA oversight shape equipment validation documentation requirements. The Osaka-Kobe biomedical corridor drives adoption of multiplex immunohistochemistry platforms for cancer diagnostics.
China
Domestic manufacturing dominates tissue processors and embedding centers while digital microscopy platforms flow through concentrated import channels. NMPA regulations and GB standards govern in vitro diagnostic device registration. The Yangtze River Delta cluster concentrates biobanking infrastructure investment driving barcode-integrated tracking system demand.
India
Diagnostic centers in Mumbai and Delhi-NCR select compact multi-function platforms to maximize specimen processing capacity within limited facility footprints. CDSCO regulatory pathways and BIS standards shape equipment import and validation protocols. The Hyderabad biotech corridor anchors GLP-compliant system demand from pharmaceutical contract research organizations.
Histopathology Laboratory Equipment Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with life sciences conglomerates bundling reagent contracts against specialized manufacturers competing on manufacturing scale. The market structure organizes around three tiers: diversified conglomerates with backward integration into consumables, mid-scale specialists with geographic concentration advantages, and regional fabricators serving price-sensitive procurement. Dominant competitive moves include strategic partnerships embedding software workflows and portfolio diversification into AI-enabled imaging platforms.
Among diversified life sciences conglomerates, Thermo Fisher Scientific and Danaher Corporation exemplify the integrated-platform archetype through captive reagent supply and multi-year service contracts. Leica Biosystems and Sakura Finetek occupy distinct positioning within the specialist tier, with the former representing backward integration into consumables and embedded software workflows and the latter exemplifying manufacturing-scale concentration in tissue-processing equipment for high-throughput laboratories.
| Leading Market Players |
|---|
| Thermo Fisher Scientific |
| Roche |
| Leica Biosystems |
| Agilent Technologies |
| Danaher Corporation |
| Sakura Finetek |
| Hologic |
| PerkinElmer |
| Epredia |
| Others |
Pricing and Supply Chain Analysis
FDA quality system regulation gates both supplier qualification and price differentiation in histopathology equipment, compressing margins for uncertified fabricators while enabling premium placement for validated platforms in hospital networks. CLIA laboratory certification requirements create tiered procurement access that separates ISO 15189-accredited vendors from price-competitive regional alternatives.
Pricing Analysis
Configured-to-order pricing for multiplex immunohistochemistry platforms commands substantial premiums over standard tissue processors, with customization depth tied to biomarker panel complexity and LIS integration requirements. Three-tier pricing structure across premium, standard, and economy levels reflects FDA clearance status, after-sales bundling, and reagent contract duration. Cost compression in economy tiers intensifies as domestic manufacturers in China and India scale production of embedding centers and manual microtomes. Independent diagnostic centers in Brazil and India exhibit highest price sensitivity, while academic medical centers in the United States prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Just-in-time inventory strategies dominate consumables procurement for high-throughput laboratories, while strategic stockpiling of optical components and precision motors buffers against semiconductor supply volatility. Manufacturing concentrates in Germany for digital microscopy platforms, Japan for automated tissue processors, and China for embedding centers and manual equipment. Optical glass, stepper motors, and paraffin formulations constitute critical input dependencies. Single-source vulnerability in specialized objective lens supply creates exposure for whole-slide imaging scanner production. Distribution runs through hospital procurement departments and group purchasing organizations in the United States, regional distributors in Europe, and direct sales teams serving pharmaceutical clients.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities expand faster than hardware placements as preventive maintenance contracts and remote monitoring subscriptions capture recurring revenue from installed automated platforms. After-sales revenue layers now exceed 35 percent of lifetime customer value in hospital-based diagnostic laboratories.
For Market Incumbents: Fortify backward integration into reagent supply and embedded software workflows to defend against modular platform disruptors. Leica Biosystems exemplifies this through consumables captivity and cancer diagnostic workflow integration. Capacity addition in East Asia addresses manufacturing-scale competition from Sakura Finetek. Certification investment in FDA breakthrough device pathways for AI-enabled imaging creates differentiation moats. For New Entrants and Emerging Players: Lead with compact multi-function platforms targeting diagnostic centers in India and Brazil where throughput-per-square-foot economics outweigh brand premium. Biobanking infrastructure in China's Yangtze River Delta presents underpenetrated demand for barcode-integrated tracking systems. Open reagent architectures and flexible staining parameters attract research laboratory procurement at NIH-funded cancer centers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified life sciences conglomerates seeking to divest non-core histopathology assets. Mid-scale specialists with geographic concentration in East Asia or backward integration into consumables offer viable acquisition profiles. Long-term viability over a five-to-ten year window depends on regulatory clearance momentum for AI-enabled diagnostic workflows. The signal to watch is FDA guidance publication pace on artificial-intelligence-enabled devices.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU IVDR transition timelines compress product launch windows for slide stainers. |
| Hospital System Partnership | Integrated delivery networks negotiate multi-year bundled contracts with reagent lock-in. |
| Software Companion Development | Embedded LIS integration differentiates automated platforms in academic medical centers. |
| Reimbursement Strategy | Precision oncology program adoption hinges on CPT code alignment for biomarker testing. |
| Backward Integration | Captive reagent supply secures margin pools beyond initial hardware placement. |
Research Methodology
Initial hypotheses were tested against primary input from hospital procurement managers, pathology laboratory directors, biomedical engineers, and regulatory affairs specialists and refined through secondary validation. FDA 510(k) filings, EU MDR technical documentation, hospital GPO contract databases, and ISO 15189 accreditation records anchored quantitative sizing. Bottom-up instrument placement counts triangulated against top-down diagnostic procedure volume estimates.
Variance decomposition across product type, application, end user, technology, and regional regulatory cluster shaped the analytical framework. CAGRs were derived from instrument replacement cycle analysis and diagnostic volume elasticity modeling. Immunohistochemistry protocol expansion rates and digital pathology adoption curves informed segment-specific trajectories across the projection horizon.
The analysis sits within stated boundaries; outcomes outside sustained FDA clearance momentum for AI-enabled devices or prolonged EU IVDR transition delays would require recalibration. Forecasts reflect assumptions regarding CLIA laboratory certification maintenance and precision oncology program expansion. Revision becomes warranted when biomarker testing volume growth crosses regulatory infrastructure capacity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Laboratory Equipment
Europe Laboratory Hoods and Enclosure Market
Laboratory Equipment
Cuvettes Market
Laboratory Equipment
Global Slide Stainer Market
Laboratory Equipment
Albumin Analyzers Market
Laboratory Equipment
Global Laboratory Glassware Washers Market
Laboratory Equipment
Global Laboratory Equipment Services Market
Laboratory Equipment
Blood Testing Equipment Market
Laboratory Equipment
Automated Cell Counter Market
Laboratory Equipment
Mobile Sterile Units Market
Laboratory Equipment
Hotplate Stirrers Market
Laboratory Equipment
Vacuum Blood Collection Tube Market
Laboratory Equipment
Vacuum Tissue Processors Market
Laboratory Equipment
Global Hematology Analyzers and Reagents Market
Laboratory Equipment
Western Blotting Processors Market
Laboratory Equipment
Multi-Cuvette Spectrophotometer Market
Laboratory Equipment
Laboratory Freezers Market