
 Europe Kiwi Fruit Market | 2026-2036
Europe Kiwi Fruit Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Kiwi Fruit Market Foresight
Subscription-based cold-chain monitoring is shifting how European kiwi distributors guarantee shelf-life compliance. Zespri Group Limited leverages its proprietary quality assurance system to sustain premium positioning across German and French retail channels. SanLucar Fruit S.L. anchors its Mediterranean sourcing network to compete on year-round availability. Jingold S.p.A differentiates through patented yellow-flesh cultivars that command higher margins in Italian supermarkets.
Kiwi fruit comprises the edible berry of Actinidia deliciosa and related species, typically harvested at soluble solids content of 6.5-8.0 degrees Brix before controlled-atmosphere storage at 0°C with ethylene scrubbing extends commercial life to 16-24 weeks. Its primary commercial purpose centers on fresh consumption and ingredient supply to juice, dairy, and confectionery manufacturers. Organic kiwi captures expanding shelf space as E.U. organic regulation 2018/848 tightens conversion requirements and certifier oversight. Food service end users represent the fastest-growing demand channel, driven by kiwi's inclusion in health-positioned menu items across European quick-service and fast-casual chains.
E.U. Plant Health Regulation 2016/2031 mandates strict phytosanitary certification for kiwi imports, while REACH governs post-harvest chemical treatments on packaging materials. EFSA residue monitoring shapes grower spray programs and maximum residue limits for key pesticides. Stakeholders must monitor evolving E.U. deforestation-free supply chain rules and their traceability demands on non-European kiwi origins.
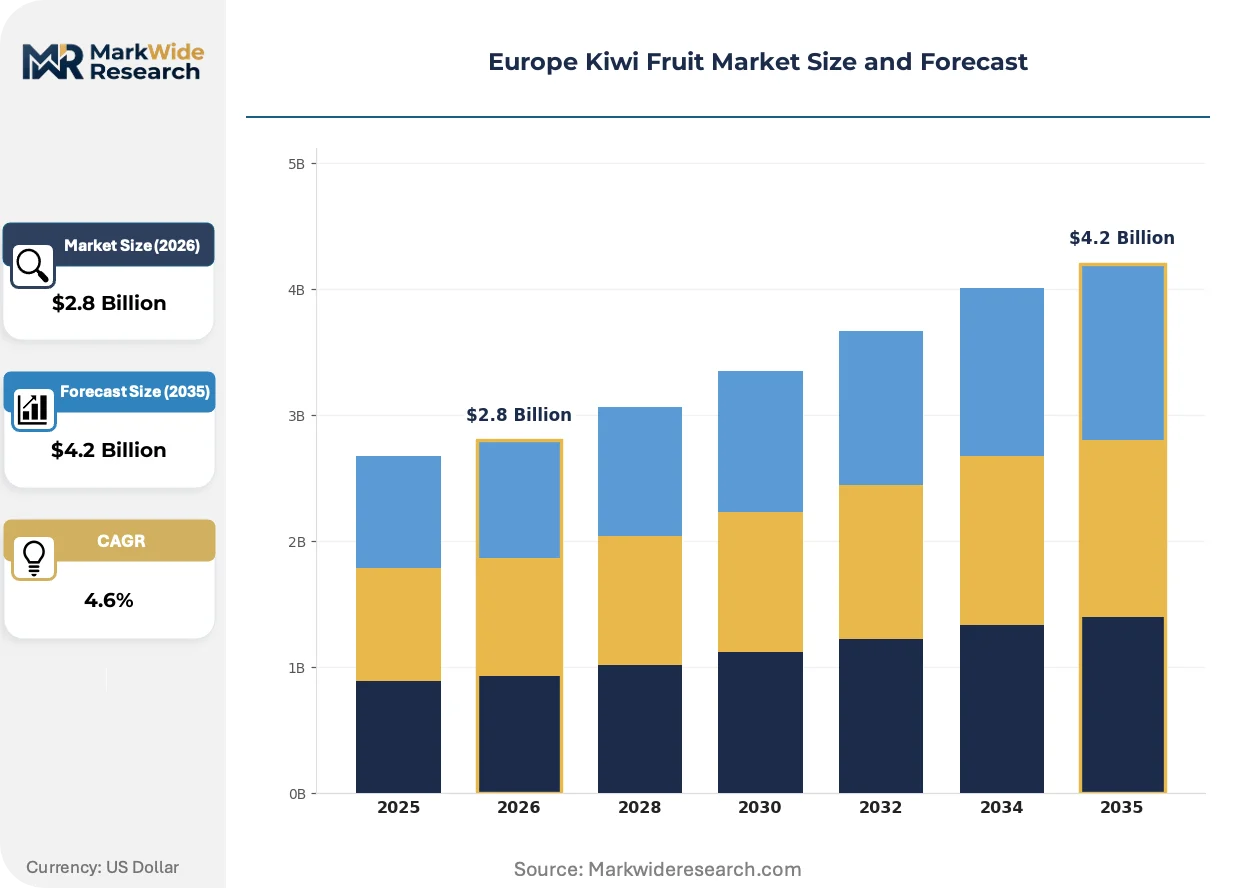
Market Dynamics
EU Green Deal's Farm to Fork Strategy is compressing grower spray programs and forcing rapid adoption of integrated pest management across European kiwi orchards, particularly in Italy's Po Valley production cluster.
Growth Catalysts
- Food service procurement expansion:European quick-service and fast-casual chains are embedding kiwi into wellness-positioned smoothies and bowls, creating pull-through demand for processed and fresh fruit suppliers.
- REACH compliance infrastructure:Post-harvest chemical treatment standards on packaging materials are driving investment in certified cold-chain facilities that double as quality assurance marketing tools.
- Organic conversion acceleration:E.U. organic regulation 2018/848's tightened certifier oversight is creating shelf-space premiums for compliant Italian and Greek growers who complete the 36-month conversion cycle.
Market Restraints
- Input cost volatility:Natural gas-dependent controlled-atmosphere storage facilities face margin compression from energy price swings, particularly affecting German and Dutch distribution hubs.
- Phytosanitary certification friction:E.U. Plant Health Regulation 2016/2031 creates documentation bottlenecks for non-European origins, limiting New Zealand and Chilean volume flexibility during Southern Hemisphere harvest windows.
- Substitution threat from berries:Blueberry and raspberry processors compete for identical dairy and confectionery ingredient contracts, often winning on year-round supply consistency.
Strategic Opportunities
- Polish retail underpenetration:Modern grocery format expansion in Warsaw and Kraków creates first-mover positioning for yellow-flesh cultivar suppliers who bypass saturated Western European channels.
- Subscription cold-chain monitoring:IoT-enabled quality tracking services allow distributors to guarantee 16-24 week shelf-life compliance, unlocking premium pricing in French and German retail.
- CSRD-aligned carbon accounting:Corporate Sustainability Reporting Directive mandates are pushing food manufacturers toward verified low-carbon kiwi sourcing, rewarding Italian growers with photovoltaic-powered storage.
Industry Challenges
- Integrated pest management skill gaps:Po Valley growers struggle to recruit agronomists trained in biological control agent deployment, slowing compliance with EFSA residue monitoring protocols.
- Ethylene scrubber capex intensity:Retrofitting legacy storage facilities with advanced scrubbing systems requires capital outlays that strain mid-scale Italian cooperatives.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Kiwi Fruit Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Kiwi, Conventional Kiwi, Dried Kiwi, Kiwi Juice Distribution Channel: Supermarkets, Online Retail, Wholesale, Farmers' Markets End User: Households, Food Service, Retailers, Food Processing Packaging Type: Cartons, Bags, Clamshells, Bulk Packaging |
| Companies Covered | Kiwi Atlantico, S.A., SanLucar Fruit S.L., Zespri Group Limited, Zeus Kiwi S.A., Consorzio Kiwi Passion S.C.A.R.L., Jingold S.p.A, Ortofruit Italia Societa Agricola Cooperativa, Minikiwi Farm Sp. z o.o., Granfrutta Zani Societa Cooperativa Agricola, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Kiwi Fruit Market Shifts & Advancements
Controlled-atmosphere technology and digital traceability systems are converging to redefine how European kiwi distributors guarantee quality and prove provenance to retail and food service buyers.
Smart container monitoring is modularizing how cold-chain compliance is delivered across European kiwi logistics. Food service distributors in Germany and France are adopting subscription-based sensor networks that transmit real-time ethylene and temperature data. This technology is compressing insurance and quality-assurance costs into single platform fees, displacing traditional third-party inspection contracts.
EU Green Deal's pesticide residue limits are tightening maximum allowable thresholds for key active ingredients used in kiwi orchards. EFSA monitoring protocols now shape grower spray calendars with quarterly compliance audits. Italian Hayward producers in Emilia-Romagna are responding by accelerating biological control agent trials and reducing synthetic fungicide applications by half.
Direct contracting between processors and grower cooperatives is displacing spot-market procurement across European kiwi supply chains. Large dairy and juice manufacturers in the Netherlands and Spain are locking in multi-season volume agreements with Italian and Greek suppliers. This pattern is most visible in the ingredient supply segment, where traceability requirements under pending deforestation-free supply chain rules favor relationship-based sourcing over auction platforms.
Europe Kiwi Fruit Market Segmentation
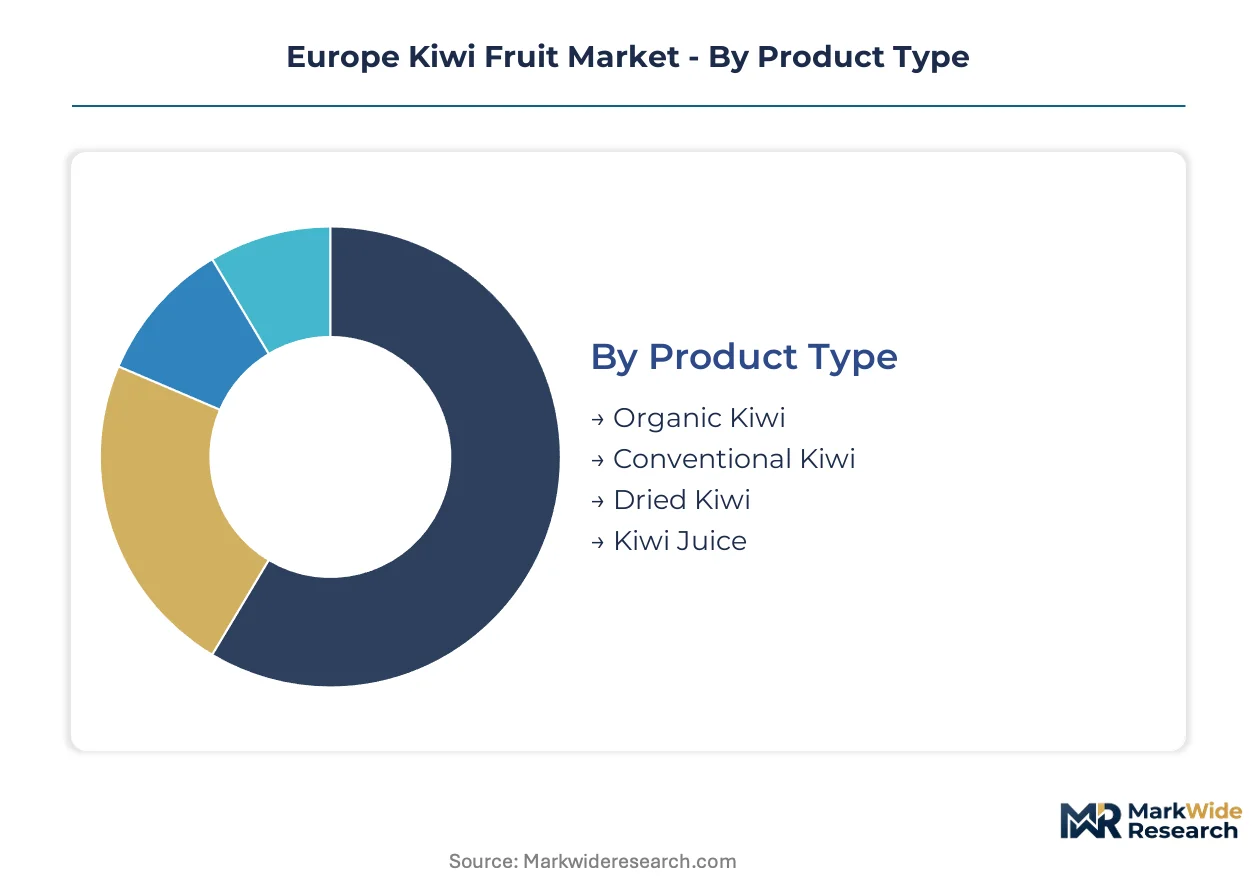
European kiwi fruit segmentation reveals divergent capital requirements across supply chain tiers. Controlled-atmosphere storage infrastructure and organic certification cycles create stark investment thresholds that reshape competitive positioning among Italian, Greek, and emerging Polish suppliers.
Product Type:
Capital intensity varies sharply across cultivation methods and processing stages, with cold-chain infrastructure representing the dominant fixed-cost burden.
- Organic Kiwi:E.U. organic regulation 2018/848 mandates 36-month conversion cycles and intensified certifier oversight. Italian growers in Emilia-Romagna absorb upfront yield penalties to capture shelf-space premiums in German and French retail channels.
- Conventional Kiwi:Hayward and Jingold varieties dominate Po Valley production clusters with established integrated pest management protocols. REACH-compliant post-harvest treatments on packaging materials drive investment in certified handling facilities.
- Dried Kiwi:Dehydration equipment and energy contracts shape processor margins. Greek cooperatives leverage solar thermal drying to offset natural gas price volatility.
- Kiwi Juice:Concentrate extraction and aseptic filling lines require seven-figure capital outlays. Dutch and Spanish dairy manufacturers source directly from Italian processors to secure traceability documentation.
Conventional kiwi absorbs the bulk of installed capacity; organic kiwi is expanding most quickly.
Distribution Channel:
Channel selection determines working capital cycles and quality-assurance liability exposure for European distributors.
- Supermarkets:Edeka, Carrefour, and Conad demand subscription-based cold-chain monitoring with real-time ethylene tracking. Slotting fees and promotional calendars compress margins for mid-scale Italian suppliers.
- Online Retail:Last-mile temperature control and return logistics create operational complexity. French e-grocers embed kiwi in wellness-positioned subscription boxes with 48-hour delivery guarantees.
- Wholesale:Rotterdam and Hamburg hub-and-spoke networks serve food service distributors with pallet-scale consolidation. Multi-temperature warehousing requirements favor vertically integrated operators.
- Farmers' Markets:Direct producer-to-consumer sales bypass certification overhead but limit volume scalability. Italian agritourism circuits in Lazio and Campania leverage this channel for premium cultivar trials.
Supermarkets command the greatest share of throughput; online retail is climbing the fastest.
End User:
End-user segmentation maps directly to formulation requirements and contract structures across European procurement.
- Households:Fresh consumption patterns concentrate in Italy, Germany, and France with seasonal preference for yellow-flesh varieties. Retail loyalty programs and origin labeling influence purchase decisions.
- Food Service:Quick-service and fast-casual chains embed kiwi in smoothie and bowl applications. German distributors guarantee 16-24 week shelf-life compliance through IoT-enabled container monitoring.
- Retailers:Private-label sourcing demands EFSA residue documentation and deforestation-free supply chain verification. Polish modern grocery expansion creates first-mover positioning for yellow-flesh suppliers.
- Food Processing:Juice, dairy, and confectionery manufacturers lock in multi-season volume agreements. Traceability mandates under pending E.U. supply chain rules favor direct contracting over spot markets.
Households represent the largest volume sink; food service is gaining share fastest.
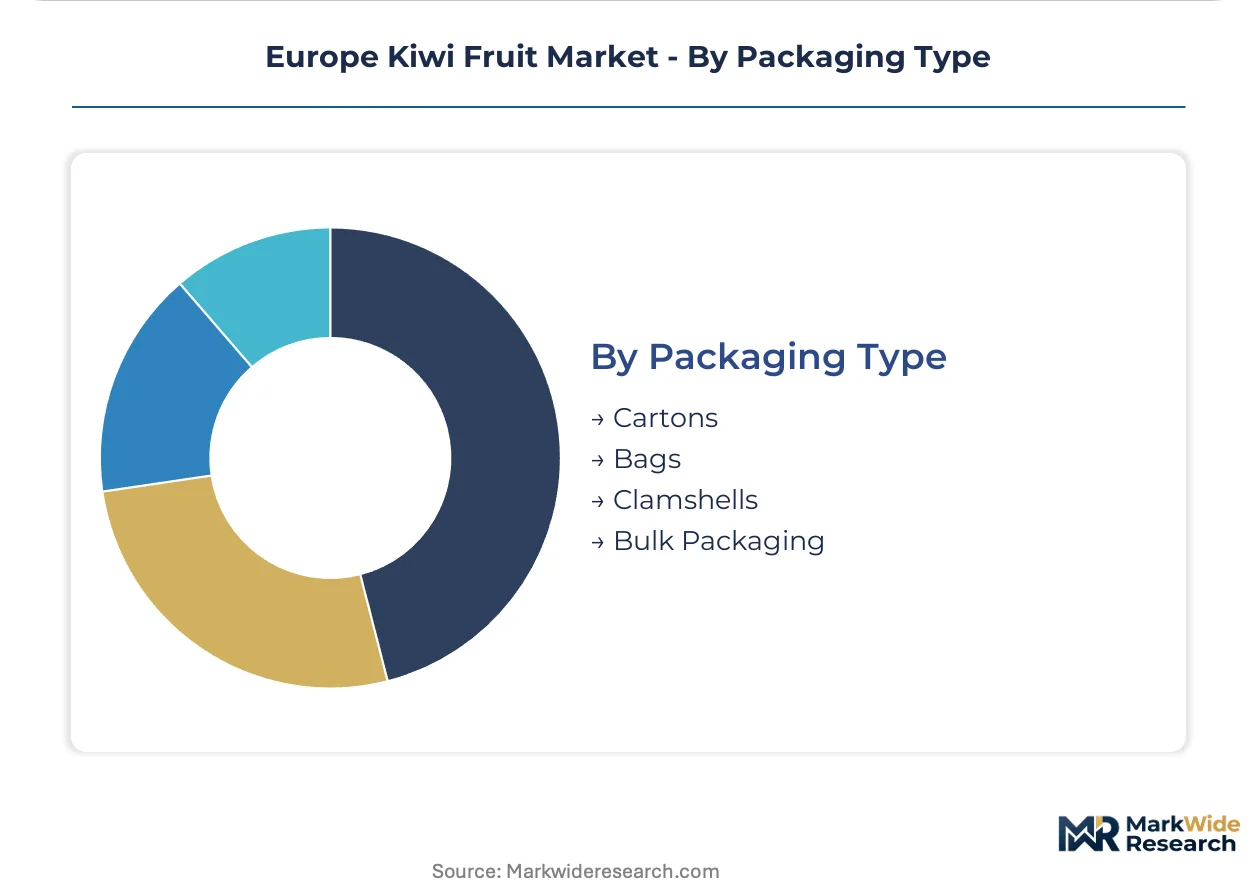
Packaging Type:
Packaging selection balances mechanical protection, shelf-life extension, and regulatory compliance costs.
- Cartons:Corrugated fiberboard with modified-atmosphere liners dominates retail-ready formats. REACH compliance on adhesives and inks drives specification tightening.
- Bags:Flexible films with micro-perforation suit club-store and discount channels. Italian converters invest in recyclable mono-material structures to meet E.U. packaging waste directives.
- Clamshells:Rigid PET or molded pulp protects premium cultivars in produce departments. German retailers mandate minimum recycled content thresholds.
- Bulk Packaging:Wooden bins and macro-perforated liners serve processor intake with minimal unit cost. Phytosanitary certification under E.U. Plant Health Regulation 2016/2031 governs reusable container circulation.
Cartons handle the majority of unit volume; clamshells are expanding most quickly in premium channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italian orchards supply the bulk of European kiwi volume, yet German and French retail channels absorb the highest per-capita consumption. This production-consumption mismatch shapes cross-border logistics investment and cold-chain infrastructure deployment.
Italy
Emilia-Romagna's Po Valley hosts the densest kiwi orchard concentration in Europe, with Hayward and Jingold varieties supplying processors across the continent. EU Green Deal pesticide residue limits are compressing grower spray programs and accelerating integrated pest management trials. The Ravenna-Cesena corridor anchors controlled-atmosphere storage clusters that feed German and French distribution hubs.
Germany
Edeka and Rewe demand subscription-based cold-chain monitoring with real-time ethylene tracking for premium cultivar placement. REACH compliance on post-harvest packaging materials drives specification tightening across supplier contracts. The Hamburg wholesale hub serves as the primary consolidation point for Italian and Greek kiwi entering Northern European retail channels.
France
Carrefour and Intermarché prioritize deforestation-free supply chain verification under pending EU traceability rules. EFSA residue monitoring protocols shape procurement calendars, favoring Italian growers with quarterly compliance documentation. The Rungis wholesale market outside Paris coordinates food service distribution for quick-service chains embedding kiwi in wellness-positioned menu items.
Spain
Valencia and Murcia production clusters compete on early-season harvest windows, supplying Northern Europe before Italian volumes peak. SanLucar Fruit S.L. anchors Mediterranean sourcing networks that compete on year-round availability. Spanish processors lock in multi-season volume agreements with Dutch dairy manufacturers seeking traceability documentation for CSRD-aligned carbon accounting.
Poland
Warsaw and Kraków modern grocery expansion creates first-mover positioning for yellow-flesh cultivar suppliers bypassing saturated Western European channels. Minikiwi Farm Sp. z o.o. represents emerging domestic production capacity targeting premium retail placement. Polish distributors leverage lower slotting fees to test innovative packaging formats before Western scale-up.
Europe Kiwi Fruit Market Competitive Landscape
Capital-heavy producers with controlled-atmosphere storage infrastructure compete with asset-light distributors relying on third-party logistics networks. Orchard ownership and cold-chain asset control define tier boundaries, with integrated operators capturing margin across cultivation, storage, and retail placement. Three archetypes dominate: multinational brand licensors, Mediterranean cooperative federations, and specialized yellow-flesh cultivar developers. Competitive moves concentrate on direct contracting with food manufacturers and photovoltaic-powered storage retrofits that satisfy CSRD carbon disclosure requirements.
Within the multinational brand tier, Zespri Group Limited and SanLucar Fruit S.L. exemplify divergent geographic anchoring strategies. Zespri leverages proprietary quality assurance systems to sustain premium positioning across German and French retail channels, while SanLucar anchors Mediterranean sourcing networks to compete on year-round availability. Jingold S.p.A occupies a distinct position among cultivar specialists, with patented yellow-flesh varieties commanding higher margins in Italian supermarkets and creating differentiation vectors for export expansion.
| Leading Market Players |
|---|
| Kiwi Atlantico, S.A. |
| SanLucar Fruit S.L. |
| Zespri Group Limited |
| Zeus Kiwi S.A. |
| Consorzio Kiwi Passion S.C.A.R.L. |
| Jingold S.p.A |
| Ortofruit Italia Societa Agricola Cooperativa |
| Minikiwi Farm Sp. z o.o. |
| Granfrutta Zani Societa Cooperativa Agricola |
| Others |
Supply & Pricing Matrix
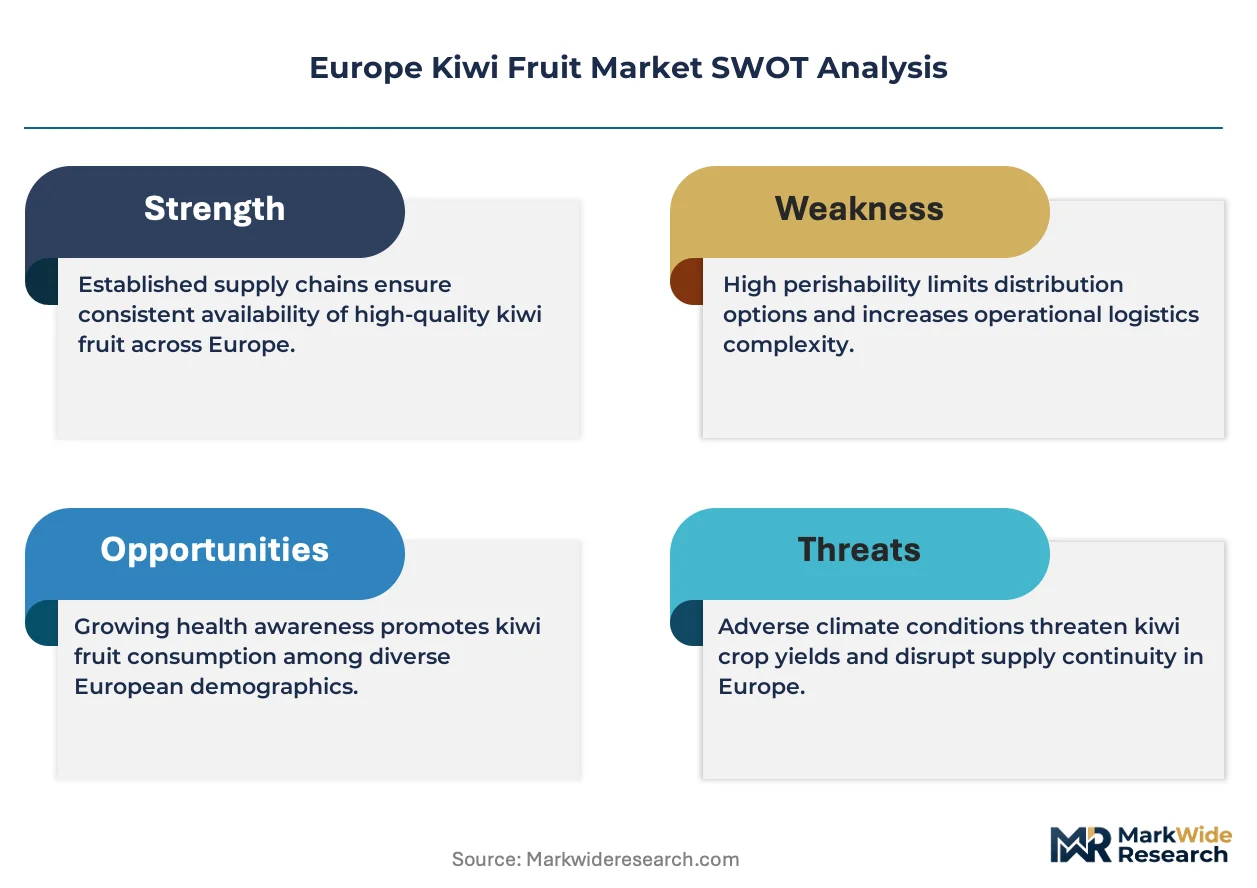
Backward integration into controlled-atmosphere storage anchors pricing power for Italian kiwi cooperatives, locking in quality premiums through captive cold-chain capacity while REACH-compliant packaging investments create tiered entry barriers for smaller Mediterranean growers.
Pricing Analysis
Cost-down pressure on mid-scale distributors accelerates because natural gas-dependent storage facilities face margin compression from energy price volatility. Three-tier pricing structure across premium organic, standard Hayward, and economy-grade conventional levels stratifies by certification status and cold-chain documentation depth. Italian growers with photovoltaic-powered storage capture shelf-space premiums in German retail, while spot-market buyers absorb the steepest price erosion during Southern Hemisphere harvest windows when Chilean and New Zealand volumes pressure contract rates.
Supply Chain Analysis
Agronomist shortages in Emilia-Romagna slow integrated pest management adoption, forcing Po Valley cooperatives to outsource biological control agent deployment at premium labor rates. Supply concentrates in Italy, Greece, and Spain, with raw material dependencies on Chilean and New Zealand counter-seasonal volumes, ethylene scrubber equipment, and REACH-compliant packaging substrates. Single-source vulnerability runs through the Ravenna-Cesena storage corridor, where legacy facility retrofits lag EFSA residue monitoring compliance timelines. Distribution runs through Rotterdam and Hamburg hub-and-spoke networks serving Northern European retail consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-atmosphere storage capacity constraints prop pricing premiums, as ethylene scrubber capex requirements and skilled agronomist scarcity limit supply expansion faster than food service demand growth.
For Market Incumbents: Hedge margin erosion by retrofitting Italian storage clusters with photovoltaic arrays that satisfy CSRD carbon disclosure requirements, while locking multi-season volume agreements with Dutch and Spanish dairy processors before deforestation-free supply chain rules tighten traceability documentation standards. For New Entrants and Emerging Players: Enter via Polish modern grocery channels in Warsaw and Kraków, where lower slotting fees and underpenetrated yellow-flesh cultivar positioning allow first-mover capture before Western European saturation forces direct competition with Zespri and SanLucar established networks. For Investors and Strategic Acquirers: Exit pathways concentrate in mid-scale Italian cooperatives with captive cold-chain assets and organic certification completion, where long-term viability hinges on EFSA audit compliance rates and the pace of biological control agent adoption as synthetic fungicide applications face regulatory compression.| Strategic Initiative | Industry Significance |
|---|---|
| Photovoltaic Storage Retrofit | CSRD-aligned carbon accounting rewards Italian growers with documented renewable energy integration. |
| Direct Processor Contracting | Multi-season volume agreements with Dutch dairy manufacturers displace spot-market procurement volatility. |
| Biological Control Agent Trials | EU Green Deal pesticide limits force accelerated integrated pest management adoption in Po Valley orchards. |
| Subscription Cold-Chain Monitoring | IoT-enabled ethylene tracking guarantees 16-24 week shelf-life compliance for German retail placement. |
| Yellow-Flesh Cultivar Expansion | Patented Jingold varieties command margin premiums in Italian supermarkets and Polish entry channels. |
Research Methodology
Independent corroboration across primary interviews with Italian cooperative agronomists, German retail category buyers, Dutch dairy procurement directors, and Greek dehydration equipment operators underwrites the qualitative findings, validated against EU trade statistics, EFSA residue monitoring reports, customs import records, and cold-chain infrastructure investment disclosures, with bottom-up orchard capacity modeling triangulated against top-down consumption estimates.
Rate-of-change decomposition across the projection horizon segments volume and value by cultivation method, distribution channel, end-user application, and packaging format, with CAGRs derived from trend extrapolation of food service procurement patterns, organic conversion cycle completion rates, and controlled-atmosphere storage capacity expansion timelines relative to import volume seasonality from Southern Hemisphere origins.
Revisions become necessary when EU deforestation-free supply chain rules accelerate traceability mandates, natural gas price volatility disrupts storage facility economics, or EFSA tightens maximum residue limits beyond current integrated pest management adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Dry Beans Market
Fruits and Vegetables
North Africa Table Olives Market
Fruits and Vegetables
Global Fresh Cranberries Market
Fruits and Vegetables
Global Not from Concentrate (NFC) Puree Market
Fruits and Vegetables
Packaged Fresh Fruits Market
Fruits and Vegetables
United Kingdom Berries Market
Fruits and Vegetables
Global Dried Apricots Market
Fruits and Vegetables
Mexico Lime Market
Fruits and Vegetables
Pea Flakes Market
Fruits and Vegetables
Europe Canned Fruits Market
Fruits and Vegetables
Asia-Pacific Fruit and Vegetable Ingredient Market
Fruits and Vegetables
Fruit Puree Market
Fruits and Vegetables
Fruit Pulp Market
Fruits and Vegetables
Europe Orange Market
Fruits and Vegetables
Tropical Fruit Puree Market
Fruits and Vegetables
Banana Flakes Market