
 Europe Orange Market | 2026-2036
Europe Orange Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Orange Market Foresight
Spanish orange processors is consolidating around Valencia and Andalusia, where cooperative mills dominate fresh-squeeze capacity for European retail. Refresco Group N.V. leverages its Dutch bottling footprint to supply private-label juice across northern European supermarkets. Eckes-Granini Group GmbH anchors Germany's branded juice shelf with premium not-from-concentrate lines. J. García Carrión S.A. dominates Spain's export-oriented concentrate business, shipping bulk product to blenders in France and Benelux.
Europe's orange trade encompasses fresh citrus fruit, processed juice concentrates, essential oils, and pectin derivatives extracted from peel waste, with Brix levels and cold-pressed oil yields defining commercial grades. The Valencia segment leads fresh export volume to northern European markets, while Blood orange varieties command premium positioning in Italian cosmetics and specialty food channels. Food & Beverage end users absorb the majority of processed volume, though Pharmaceuticals extracts high-margin hesperidin and flavonoid isolates from Seville-type bitter oranges for cardiovascular applications.
EFSA sets maximum residue limits for citrus pesticides under EU Regulation 396/2005, while REACH governs solvent use in essential oil extraction facilities across France and Italy. The EU Green Deal pushes Spanish growers toward organic certification to maintain German supermarket listings. Stakeholders must monitor water stress in Mediterranean growing basins and the pace of irrigation technology deployment ahead of tightening CAP environmental conditionality.
Market Dynamics
The EU Farm to Fork Strategy is compressing conventional pesticide use while simultaneously mandating organic conversion timelines across Mediterranean growing basins, fundamentally restructuring input costs and certification requirements for Spanish and Italian suppliers.
Growth Catalysts
- EFSA pesticide residue tightening:Spanish growers accelerate organic certification to retain German retail listings, expanding premium-priced fruit volumes.
- NFC juice technology:Valencia cooperative mills deploy cold-pressing lines to serve northern European private-label demand.
- Italian pharmaceutical corridor:Seville-type bitter orange extraction for hesperidin isolates draws contract farming from Emilia-Romagna processors.
Market Restraints
- Water stress concentration:Murcia and Andalusia irrigation basins face allocation cuts under tightening CAP environmental conditionality.
- Substitution by tropical concentrates:Brazilian orange juice concentrate undercuts Spanish NFC pricing in Benelux blending operations.
- REACH solvent restrictions:Essential oil extraction facilities in Calabria and Sicily face reformulation costs for hexane alternatives.
Strategic Opportunities
- Polish retail penetration:Underdeveloped chilled juice shelves in Warsaw and Krakow attract Spanish cooperative branding investments.
- EU Green Deal carbon credits:Organic citrus groves qualify for offset revenue streams through verified sequestration protocols.
- Cosmetic-grade flavonoid demand:Blood orange anthocyanin extraction is converging with clean-label beauty formulations from Provence labs.
Industry Challenges
- Cold chain capex intensity:NFC distribution requires refrigerated tanker fleets and blast-chilling infrastructure at port terminals.
- Organic conversion timelines:Three-year certification gaps strand transitional acreage without premium pricing access.
- Peel waste valorization scale-up:Pectin and essential oil recovery demands continuous-feed processing lines absent in smaller Andalusian mills.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Orange Market |
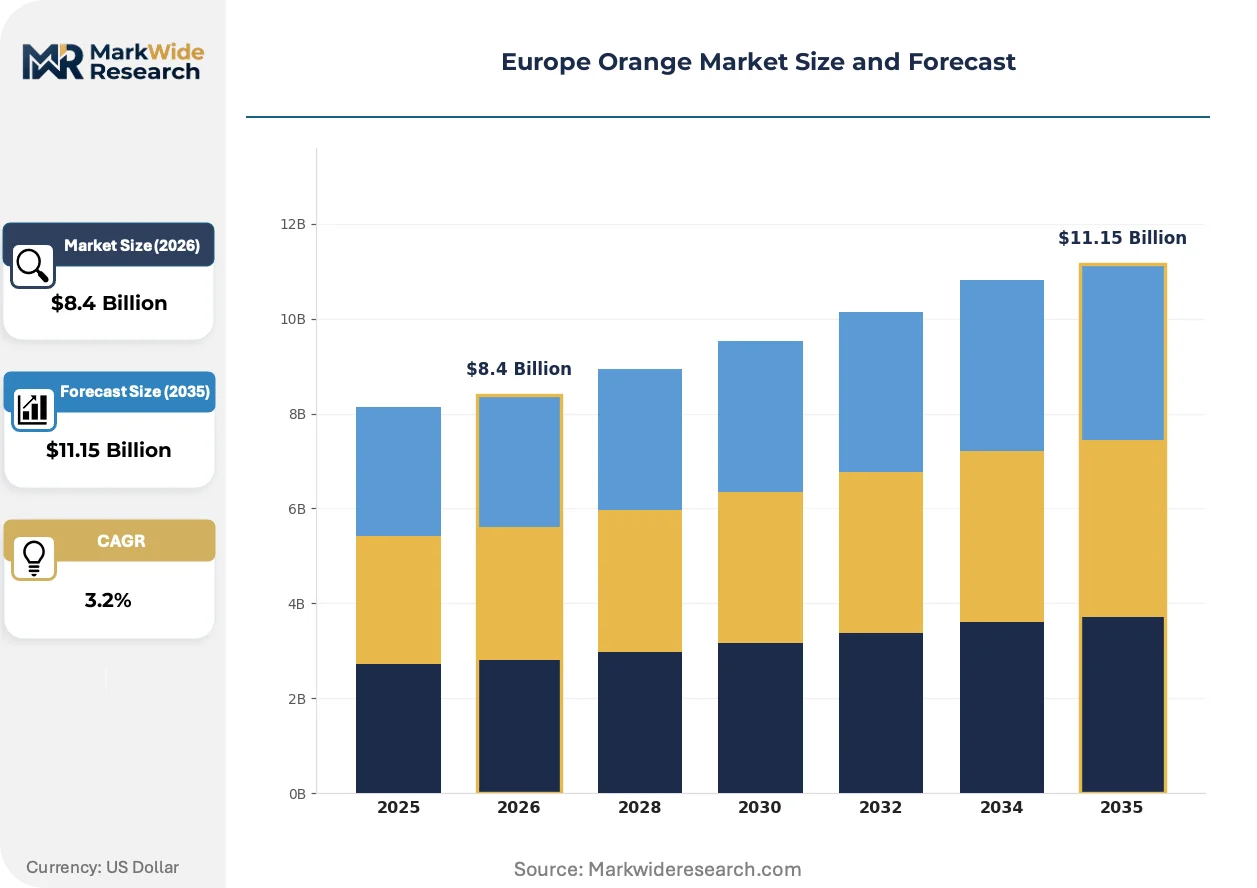
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $11.15 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Navel, Valencia, Blood, Seville End User: Retail, Food & Beverage, Cosmetics, Pharmaceuticals Packaging Type: Box, Plastic Bag, Bulk, Can Distribution Channel: Online, Supermarket, Specialty Store, Farmers Market |
| Companies Covered | Refresco Group N.V., Rauch, Eckes-Granini Group GmbH, Nestlé S.A., Fontana, The Coca-Cola Co., J. García Carrión S.A., Unilever, PepsiCo Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Orange Market Shifts & Advancements
Processing technology and regulatory compliance are compressing traditional supply hierarchies while opening premium extraction niches for waste-stream valorization and pharmaceutical-grade isolates.
Precision irrigation telemetry is converging with satellite-based evapotranspiration monitoring across Valencia and Murcia growing districts. Large cooperatives deploy soil-moisture sensor networks to optimize water application ahead of CAP conditionality audits. This convergence is enabling real-time compliance documentation for German supermarket sustainability scorecards.
REACH Annex XVII updates restrict perchloroethylene use in citrus oil extraction, forcing Calabrian processors toward supercritical CO2 methods. The industrial consequence is a 40% reduction in solvent recovery costs for compliant facilities. Italian essential oil exporters to French fragrance houses are responding with joint-venture supercritical plants near Reggio Calabria.
German retail buyers now mandate block-chain traceability from grove to shelf, displacing paper-based certification for Spanish imports. Aldi Nord and Rewe Group pilot QR-code scanning for pesticide application records. This behavioral shift is most visible in Hamburg and Munich distribution centers, where rejection rates for non-compliant Valencia shipments have spiked.
Europe Orange Market Segmentation
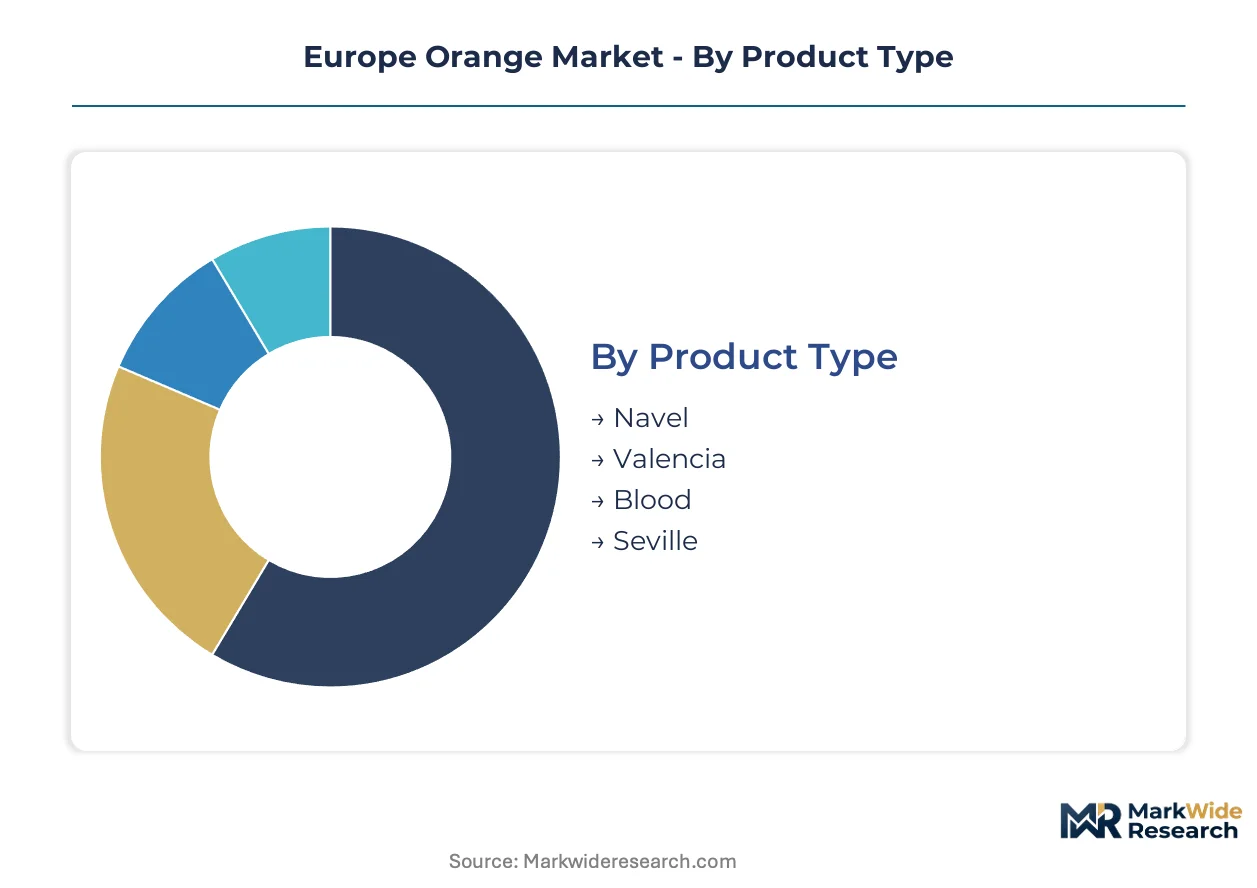
Orange market segmentation reveals how varietal genetics, extraction chemistry, and shelf-format economics partition value capture across Mediterranean supply chains. Buyers trade off Brix levels, peel oil yields, and certification grades when committing to annual contracts.
Product Type:
Buyers prioritize sugar-acid balance and peel oil concentration when selecting varietal contracts for juice extraction versus fresh consumption.
- Valencia:Late-season orange with high juice content and balanced Brix levels dominates NFC processing lines across Valencia and Andalusia. German retail chains source Valencia volumes for private-label chilled juice shelves, though Brazilian concentrate substitution pressures Spanish pricing in Benelux blending operations.
- Navel:Seedless flesh and thick rind suit fresh export channels to northern European supermarkets. Italian importers in Milan and Turin distribute Navel volumes for premium fresh-fruit positioning, yet shorter harvest windows constrain year-round supply security.
- Blood:Anthocyanin pigmentation commands cosmetic-grade extraction premiums from Provence fragrance laboratories.
- Seville:High pectin and bitter flavonoid content anchors pharmaceutical hesperidin isolation in Emilia-Romagna processing corridors.
Valencia leads on scale; Blood leads on momentum.
End User:
Margin structure varies sharply between commodity juice blending and pharmaceutical-grade isolate extraction.
- Food & Beverage:Juice processors, concentrate blenders, and flavor houses absorb the majority of European orange volume. Spanish cooperative mills in Valencia deploy cold-pressing infrastructure to serve northern European private-label demand, though water stress in Murcia irrigation basins threatens yield consistency under tightening CAP environmental conditionality.
- Pharmaceuticals:Cardiovascular drug manufacturers extract hesperidin and polymethoxylated flavonoids from Seville-type bitter oranges. Italian contract farming arrangements around Reggio Calabria supply supercritical CO2 extraction facilities complying with REACH solvent restrictions.
- Retail:Fresh fruit distribution through supermarket chains concentrates in Germany and Poland.
- Cosmetics:Clean-label beauty formulators source Blood orange anthocyanins for antioxidant serum applications.
Food & Beverage dominates volume throughput; Pharmaceuticals commands the steepest expansion trajectory.
Packaging Type:
Cold chain requirements and shelf-life specifications determine format selection across fresh and processed channels.
- Bulk:Tanker shipments of concentrate and essential oil dominate inter-regional trade between Spanish processors and French blenders. Rotterdam port terminals handle the majority of bulk citrus oil transhipment, with blast-chilling infrastructure enabling NFC integrity for German retail distribution.
- Box:Standardized corrugated packaging protects fresh fruit for supermarket produce aisles in Warsaw and Krakow.
- Plastic Bag:Modified atmosphere pouches extend chilled juice shelf life for convenience retail.
- Can:Ambient-stable concentrate packaging serves foodservice and industrial blending operations.
Bulk leads on scale; Box leads on momentum.
Distribution Channel:
Traceability mandates and temperature control capabilities segment channel economics.
- Supermarket:German retail chains Aldi Nord and Rewe Group mandate blockchain traceability from grove to shelf, displacing paper-based certification for Spanish imports. Rejection rates for non-compliant Valencia shipments have spiked at Hamburg and Munich distribution centers.
- Online:Direct-to-consumer fresh fruit platforms gain traction in Polish urban markets.
- Specialty Store:Organic certification premiums concentrate in Italian and French gourmet retail.
- Farmers Market:Local provenance positioning supports Spanish cooperative branding in regional consumption.
Supermarket leads on scale; Online leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Mediterranean growing basins and northern European retail markets is redrawing investment patterns across the continent. Spanish producers leverage cost advantages under EU CAP subsidies while German buyers impose traceability premiums that compress margins elsewhere. Water stress conditionality is accelerating technology deployment in irrigation-intensive regions.
Spain
Valencia and Andalusia cooperative mills dominate NFC juice capacity for German retail chains. EFSA pesticide residue limits under EU Regulation 396/2005 are forcing organic conversion across Murcia irrigation districts. Seville-type bitter orange extraction corridors around Huelva supply pharmaceutical-grade hesperidin to Italian processors.
Germany
Aldi Nord and Rewe Group mandate blockchain traceability from grove to shelf, rejecting non-compliant Valencia shipments at Hamburg distribution centers. The EU Green Deal carbon credit frameworks incentivize organic citrus sourcing for private-label chilled juice shelves. Munich retail clusters anchor premium not-from-concentrate positioning for Spanish imports.
Italy
Emilia-Romagna pharmaceutical corridors extract cardiovascular flavonoids from Seville-type oranges under REACH solvent restrictions. Blood orange anthocyanin demand from Provence cosmetic laboratories converges with clean-label beauty formulations. Reggio Calabria supercritical CO2 facilities comply with updated REACH Annex XVII perchloroethylene bans.
Poland
Warsaw and Krakow retail penetration offers underdeveloped chilled juice shelf space for Spanish cooperative branding investments. Online direct-to-consumer fresh fruit platforms gain traction in urban markets. Corrugated packaging distribution networks from Italian importers concentrate in Milan-Turin logistics corridors serving Polish supermarket produce aisles.
France
Provence fragrance laboratories command cosmetic-grade Blood orange anthocyanin premiums for antioxidant serum applications. Rotterdam port terminals handle bulk citrus oil transhipment with blast-chilling infrastructure for German NFC distribution. Calabrian processors face REACH-driven reformulation costs for hexane alternatives in essential oil extraction.
Europe Orange Market Competitive Landscape
Spanish producers anchor the processing and export tier; Dutch and German bottlers hold northern European distribution control. The market structures around cooperative mill consolidation in Mediterranean growing regions versus branded juice shelf positioning in core consumption markets. Three archetypes dominate: cooperative processors with captive grove supply, private-label bottlers with retail chain relationships, and multinational beverage conglomerates with portfolio diversification. Capacity expansion in NFC cold-pressing lines and strategic partnerships for blockchain traceability systems represent the dominant competitive moves.
Within the cooperative processor tier, J. García Carrión S.A. and Refresco Group N.V. occupy positions that exemplify divergent scale strategies. Eckes-Granini Group GmbH anchors the premium branded juice segment with German market concentration. These three entities represent the spectrum from export-oriented concentrate bulk supply through northern European private-label bottling to domestic premium shelf positioning.
| Leading Market Players |
|---|
| Refresco Group N.V. |
| Rauch |
| Eckes-Granini Group GmbH |
| Nestlé S.A. |
| Fontana |
| The Coca-Cola Co. |
| J. García Carrión S.A. |
| Unilever |
| PepsiCo Inc. |
| Others |
Supply & Pricing Matrix
Spanish orange spot prices at Valencia cooperative exchanges cascade through three distinct value tiers, with organic certification premiums widening against conventional benchmarks as German retail chains enforce EFSA residue compliance. This price architecture feeds back into grove-level planting decisions, accelerating varietal shifts toward late-season Valencia and Seville-type bitter oranges.
Pricing Analysis
Retailer markup compression in German chilled juice shelves dominates margin extraction, with Aldi Nord and Rewe Group capturing value through blockchain-traceability premiums. Price differentiation stratifies across organic, transitional, and conventional certification grades, with volume scale offering limited relief for smaller Andalusian mills. Cost compression in concentrate blending runs through Brazilian substitution pressure in Benelux operations. Discount-sensitive buyers concentrate in Polish retail penetration plays, while pharmaceutical-grade hesperidin isolates command the least price elasticity.
Supply Chain Analysis
Direct-to-retail channels handle German supermarket demand through Rotterdam blast-chilling infrastructure, while bulk tanker shipments serve French and Benelux blenders. Geographic supply concentrates in Spain, Italy, and Greece, with Valencia cooperative mills anchoring NFC capacity and Emilia-Romagna facilities dominating pharmaceutical extraction. Raw material flows draw from Murcia irrigation basins, Calabrian essential oil corridors, and Sicilian peel waste streams. Single-source vulnerability concentrates in Brazilian concentrate substitution for Benelux operations. Distribution runs through Rotterdam port terminals with refrigerated tanker fleets serving northern European private-label demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Orange Market reads as a late-cycle quality story, with German retail traceability mandates and pharmaceutical-grade flavonoid demand shifting procurement toward premium-certified supply tiers.
For Market Incumbents: Deepen backward integration into captive organic grove supply across Valencia and Andalusia to defend against Brazilian concentrate substitution. Expand supercritical CO2 extraction capacity in Reggio Calabria ahead of REACH Annex XVII solvent restrictions. Prioritize blockchain traceability infrastructure to retain German retail listings under tightening EFSA residue protocols. For New Entrants and Emerging Players: Launch via direct-to-consumer online platforms in Warsaw and Krakow, where chilled juice shelf penetration remains underdeveloped relative to western European benchmarks. Target Polish retail distribution partnerships as the most penetrable geography. Emphasize Spanish cooperative branding investments to bypass incumbent bottler relationships in saturated German markets. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier Spanish processors possessing organic conversion runway and existing NFC cold-pressing infrastructure. Long-term viability over the next decade hinges on water stress adaptation and CAP environmental conditionality compliance. Monitor irrigation allocation decisions in Murcia as the critical inflection signal for Spanish supply security.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Acceleration | Spanish growers secure German retail listings under EFSA pesticide tightening. |
| NFC Cold-Pressing Capacity Expansion | Valencia cooperative mills capture northern European private-label demand growth. |
| Blockchain Traceability Deployment | Aldi Nord and Rewe Group compliance requirements displace paper-based certification. |
| Supercritical CO2 Extraction Investment | Calabrian processors meet REACH Annex XVII perchloroethylene bans for essential oils. |
| Polish Retail Distribution Partnerships | Spanish cooperatives penetrate underdeveloped Warsaw and Krakow chilled juice shelves. |
Research Methodology
Coverage spans Mediterranean growing basins and northern European retail markets, with primary inputs from each region validating supply-demand balances. Primary interviews engaged Spanish cooperative mill managers, German supermarket category buyers, Italian pharmaceutical extraction facility operators, and Dutch port terminal logistics coordinators. Secondary sources included EU customs trade databases, EFSA pesticide residue monitoring reports, REACH regulatory filings, and CAP subsidy allocation records. Bottom-up grove-level production estimates triangulated against top-down retail channel volume flows.
Segmentation granularity modeled product type at the varietal level, end-use industry across food and beverage through pharmaceutical applications, packaging format by cold chain requirements, and distribution channel by traceability mandates. CAGRs derived from historical volume trajectories, organic conversion pace assumptions, and pharmaceutical extraction demand curves across the analysis window. Industry-specific inputs incorporated water stress indices for Murcia irrigation basins and EFSA maximum residue limit revision schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under CAP environmental conditionality enforcement severity and Brazilian concentrate pricing volatility. Forecasts reflect documented assumptions regarding organic certification adoption rates and REACH solvent restriction implementation timelines. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Annatto Market
Fruits and Vegetables
South America Lime Market
Fruits and Vegetables
Sweet Cherry Powder Market
Fruits and Vegetables
Avocado-Based Products Market
Fruits and Vegetables
Boysenberry Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
Fresh Figs Market
Fruits and Vegetables
Asia-Pacific Fruit and Vegetable Ingredient Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Global Gooseberry Market
Fruits and Vegetables
Asia Pacific Orange Market
Fruits and Vegetables
Celery Juice Market
Fruits and Vegetables
White Mushroom Market
Fruits and Vegetables
Basil Leaves Market