
 Kiwi Fruit Market | 2026-2036
Kiwi Fruit Market Size, Share, and Industry Trends Forecast 2026-2036
Kiwi Fruit Market Analysis
Pre-packaged retail assortment bundles is consolidating buyer choice across the kiwi fruit trade, replacing loose-fruit bulk purchasing in mainstream channels. Zespri leverages its proprietary cultivar licensing system to control premium gold kiwi supply chains across multiple hemispheres. Seeka anchors its competitive stance through integrated orchard management and post-harvest infrastructure across New Zealand's Bay of Plenty. Turners & Growers differentiates via specialized organic handling protocols that sustain supermarket contract renewals in Australasia.
Kiwi fruit denotes the edible berry of Actinidia deliciosa and related species, botanically classified as a berry with flesh containing small black seeds distributed radially around a white core, commercially valued for vitamin C density and actinidin enzyme content that tenderizes proteins in food processing. The primary commercial purpose spans fresh consumption, ingredient supply to beverage manufacturers, and nutritional supplement extraction. Green kiwi occupies the mature volume base with established price benchmarks, while gold kiwi captures expanding margin pools through sweetness differentiation and premium retail positioning. Organic kiwi registers the fastest-growing structural segment as supermarket procurement policies tighten residue thresholds and eco-friendly packaging requirements reshape shelf-ready presentation standards.
FDA phytosanitary import protocols and EU REACH-compliant packaging material standards govern cross-border kiwi fruit circulation, with FDA inspections focusing on fruit fly mitigation documentation and REACH restricting certain plasticizers in retail film wraps. New Zealand's Ministry for Primary Industries enforces export orchard registration and traceability mandates that determine market access eligibility for third-country shipments. Stakeholders must monitor evolving cultivar patent expirations and climate adaptation breeding programs that will redistribute production geography and variety premiums.
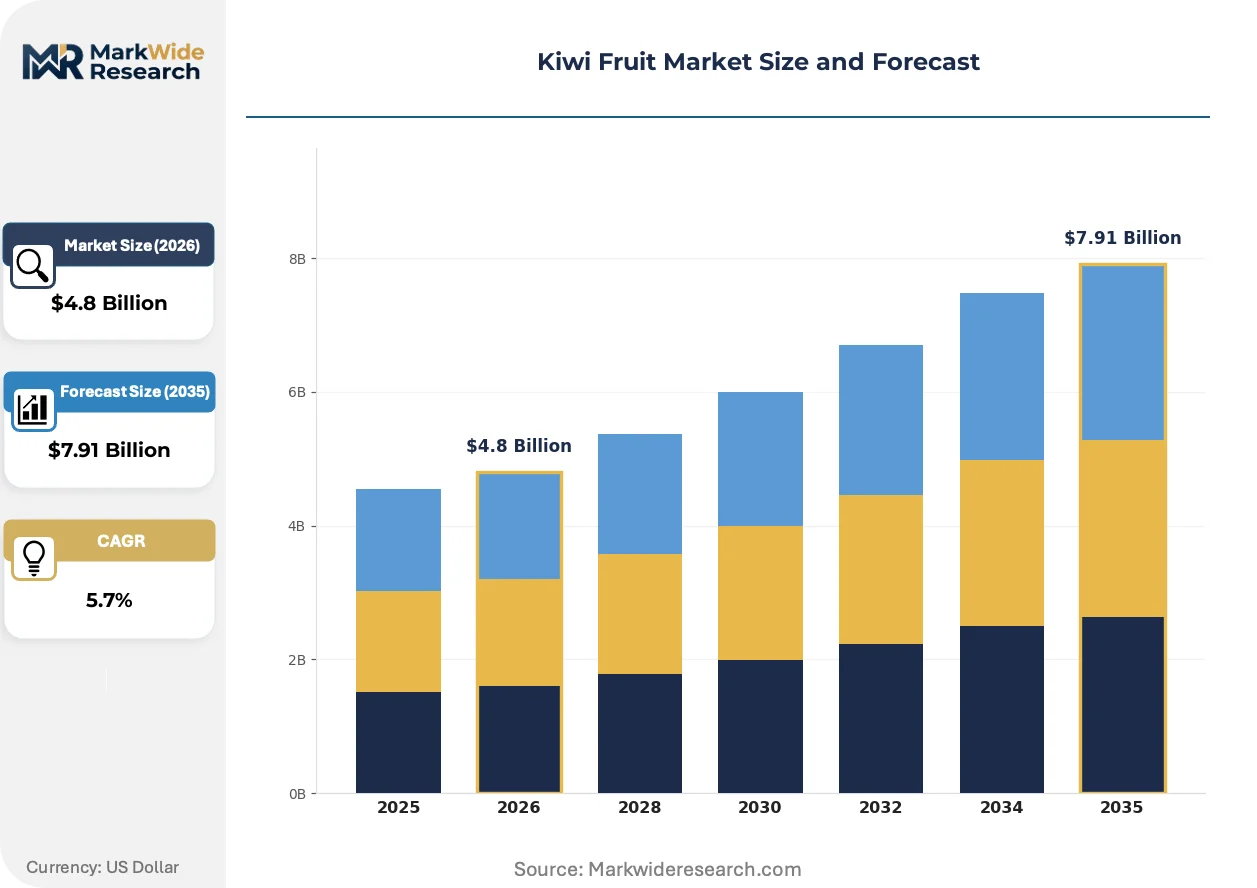
Market Dynamics
The kiwi fruit trade is restructuring around proprietary cultivar licensing systems that concentrate premium variety control among a handful of licensors, compressing margin capture for non-licensed growers and redirecting investment toward breeding program partnerships.
Growth Catalysts
- EU REACH packaging standards:Film wrap restrictions are accelerating biodegradable material substitution, creating first-mover advantages for suppliers with compliant shelf-ready formats.
- Food service smoothie procurement:Blender-ready frozen kiwi pulp contracts are expanding volume commitments from quick-service beverage chains seeking vitamin C fortification.
- Actinidin enzyme extraction:Meat tenderizer manufacturers are diversifying enzyme sourcing toward kiwi-derived actinidin as papain supply faces climate volatility.
Market Restraints
- Input cost volatility:Pollination service fees have risen sharply as hive availability contracts across New Zealand's Bay of Plenty orchard clusters.
- Supply concentration risk:Gold kiwi cultivar licensing remains concentrated with single-entity control, creating varietal supply vulnerability.
- Regulatory friction:FDA phytosanitary documentation requirements for fruit fly mitigation are extending shipment clearance timelines for third-country exporters.
Strategic Opportunities
- Underpenetrated retail channel:Direct-to-consumer subscription boxes for exotic fruit assortments remain underdeveloped in North American metropolitan markets.
- Regulatory tailwind:New Zealand's Ministry for Primary Industries traceability mandates are creating competitive moats for early-compliant exporters.
- Emerging application:Nutraceutical encapsulation of kiwi polyphenols for gut health supplements is attracting pharmaceutical contract manufacturing interest.
Industry Challenges
- Certification timeline compression:Organic conversion periods stretching three years are straining grower cash flow during transition.
- Post-harvest infrastructure capex:Controlled atmosphere storage expansion requires capital deployment that smaller orchard operators struggle to access.
- IP licensing complexity:Cultivar patent expiration schedules are creating uncertainty around royalty obligations and replanting decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kiwi Fruit Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Green Kiwi, Gold Kiwi, Organic Kiwi, Dried Kiwi Distribution Channel: Supermarkets, Online Retail, Wholesalers, Farmers Markets End User: Households, Food Service, Bakery, Smoothie Bars Packaging Type: Bulk Packaging, Retail Packs, Eco-Friendly Packaging, Plastic Containers |
| Companies Covered | Freshmax, Eurofruit, Zespri, Post Harvest Solutions, Kiwifruit New Zealand, Turners & Growers, Aongatete Coolstores, DMS Progrowers, Seeka, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kiwi Fruit Market Emerging Trajectories
Breeding programs, regulatory packaging mandates, and procurement model evolution are converging to reshape how kiwi fruit moves from orchard to retail shelf.
Gene-edited cultivar development is overtaking traditional breeding timelines, compressing variety improvement cycles from decades to single-digit years. Research consortia in New Zealand and Italy are deploying CRISPR-based techniques to enhance cold tolerance and disease resistance. This acceleration is enabling faster climate adaptation responses than conventional hybridization permitted.
REACH-compliant film wrap regulations are mandating elimination of certain plasticizers from retail packaging materials. European supermarket chains are responding by consolidating procurement around suppliers with certified biodegradable alternatives. This regulatory pressure is most acute in German and French retail channels, where shelf-ready presentation standards are tightening fastest.
Pre-packaged retail assortment bundles are displacing loose-fruit bulk purchasing in mainstream supermarket channels. Buyers are consolidating volume commitments toward fixed-weight, branded clamshell formats that reduce handling labor and shrinkage. This format shift is most visible in Australasian and North American grocery retail, where self-service produce departments are standardizing presentation protocols.
Kiwi Fruit Market Segmentation
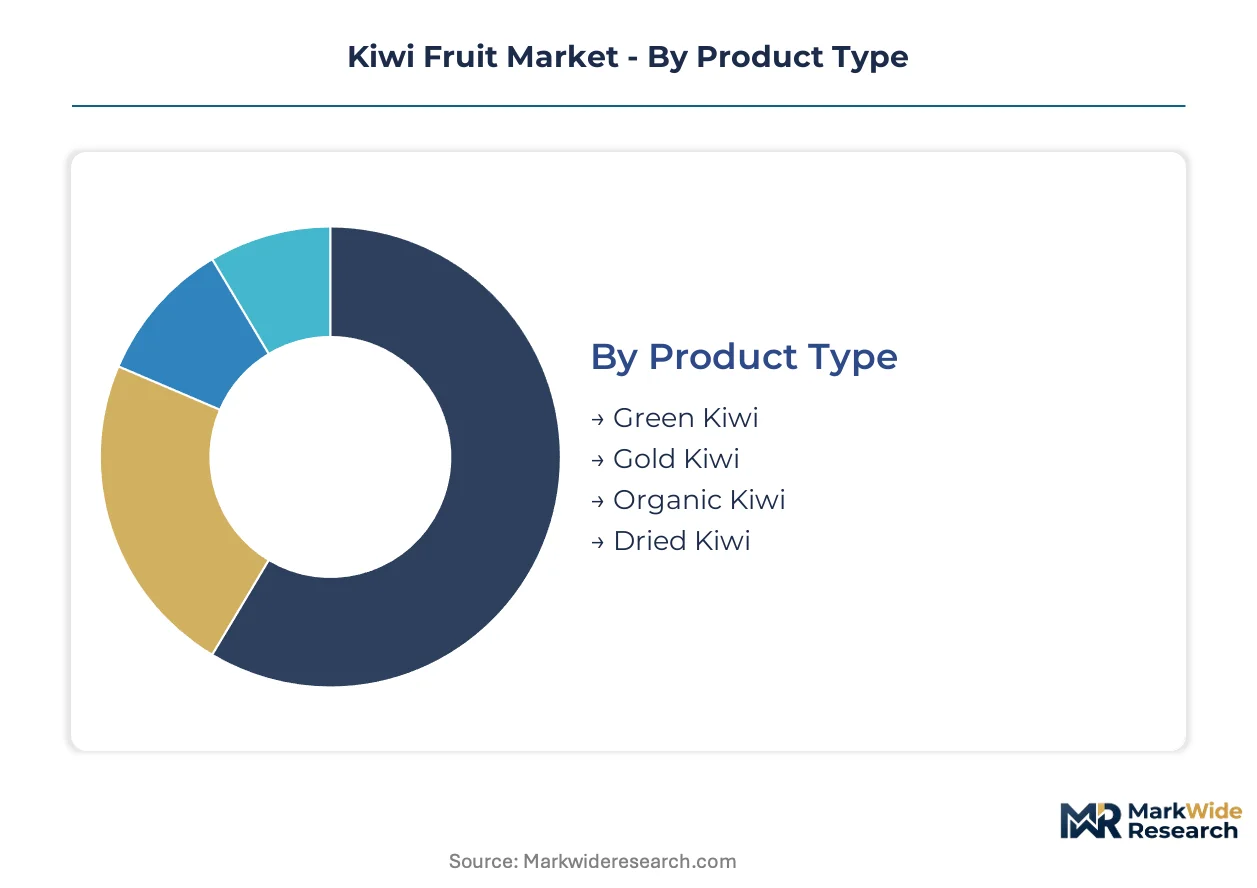
Kiwi fruit segmentation reveals how cultivar licensing, packaging mandates, and channel procurement reshape margin capture across the value chain. Category boundaries are fluid as organic certification and eco-packaging requirements cut across traditional product definitions.
Product Type:
Standardization dominates the commodity green segment while proprietary cultivar licensing creates premium customization tiers in gold and organic varieties.
- Green Kiwi:Hayward cultivar comprises the standardized volume base with established brix and firmness specifications. Demand concentrates in European supermarket chains where private-label procurement enforces tight size grading and residue compliance under EFSA monitoring protocols. Margin compression from input cost volatility limits grower reinvestment flexibility.
- Gold Kiwi:Proprietary Zespri SunGold and related licensed varieties command sweetness differentiation through controlled brix thresholds. China absorbs rising volumes through premium retail channels where domestic consumers pay substantial markups for reduced acidity and visual appeal. Licensing fees redirect substantial value from orchard operators to cultivar rights holders.
- Organic Kiwi:Three-year conversion timelines strain grower cash flow during transition periods. EFSA residue thresholds and REACH-compliant packaging mandates reshape shelf-ready presentation standards.
- Dried Kiwi:Industrial dehydration preserves actinidin enzyme activity for nutraceutical applications. Snack manufacturers in Japan source sliced formats under JIS quality standards.
Most installed capacity flows through Green Kiwi. Expansion is steepest in Organic Kiwi.
Distribution Channel:
Channel selection maps directly to handling sophistication requirements and traceability documentation burdens.
- Supermarkets:Fixed-weight clamshell formats with biodegradable film wraps displace loose-fruit bulk purchasing. German and French retail chains consolidate procurement around REACH-compliant packaging alternatives.
- Online Retail:Direct-to-consumer subscription boxes for exotic fruit assortments remain underdeveloped in North American metropolitan markets. Cold-chain integrity requirements limit geographic reach.
- Wholesalers:Volume aggregation serves food service distributors and secondary processors. New Zealand's Ministry for Primary Industries traceability mandates filter non-compliant shipments.
- Farmers Markets:Local provenance commands price premiums in Bay of Plenty clusters. Seasonal availability constrains year-round revenue stability.
Supermarkets capture the largest revenue share. Online Retail is gaining share fastest.
End User:
Application maturity separates price-tolerant premium channels from commodity procurement.
- Households:Fresh consumption drives volume through vitamin C positioning and convenience snacking formats. Retail pack sizes standardize around two-fruit and four-fruit clamshells.
- Food Service:Quick-service beverage chains expand frozen kiwi pulp contracts for smoothie fortification. Blender-ready specifications require controlled brix and seed texture profiles.
- Bakery:Ingredient supply for tarts and fruit fillings demands consistent moisture content. Industrial bakers prefer IQF frozen segments for portion control.
- Smoothie Bars:Fresh-scoop operations in Australasian urban centers source daily deliveries through specialized distributors. Perishability limits inventory holding periods.
Households absorb the majority of volume. Food Service is climbing the fastest.
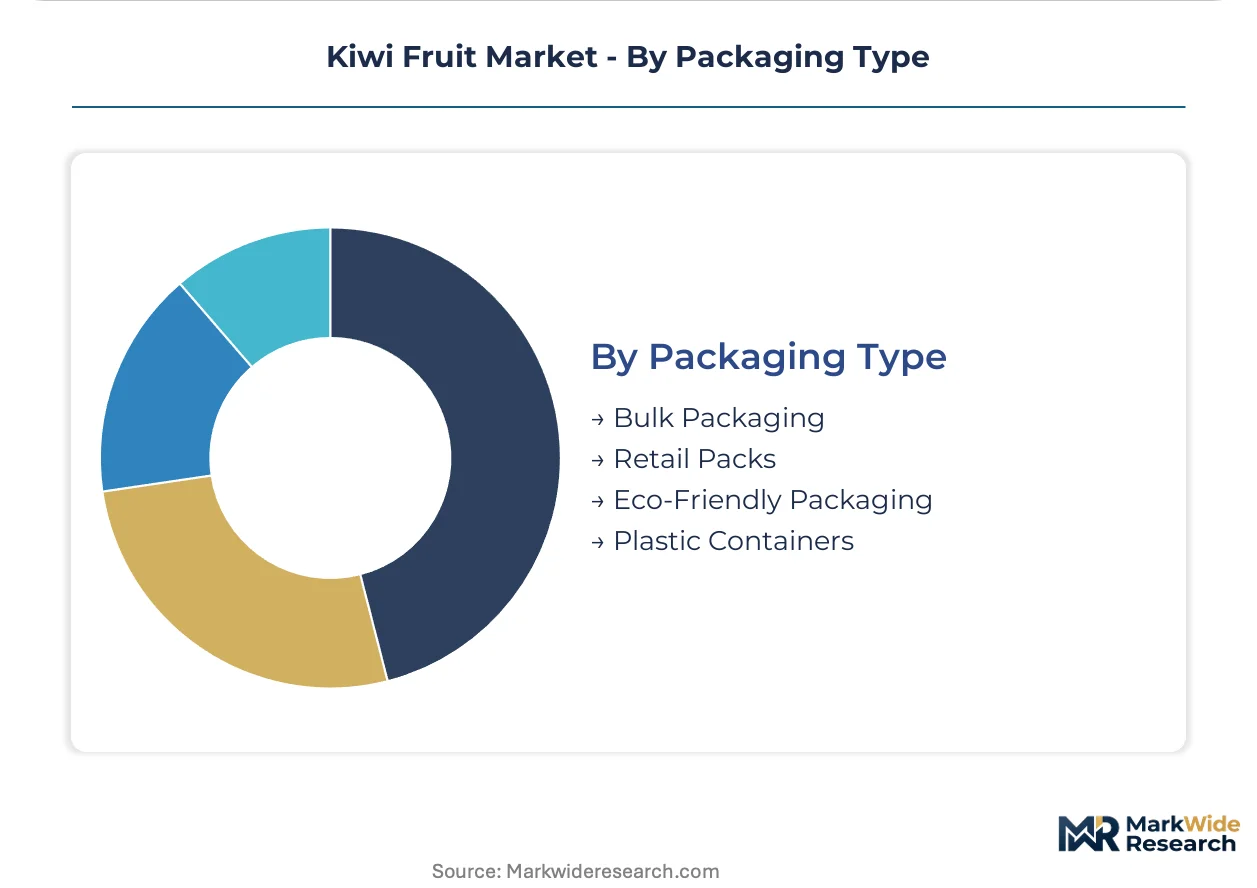
Packaging Type:
Regulatory pressure on plasticizers forces rapid material substitution across format tiers.
- Bulk Packaging:Wooden bins and macro-totes serve orchard-to-processor logistics with minimal handling labor. Controlled atmosphere compatibility extends storage duration.
- Retail Packs:Branded clamshells with modified atmosphere films dominate supermarket shelf presentation. ECHA restrictions on certain plasticizers accelerate biodegradable alternatives.
- Eco-Friendly Packaging:Cellulose-based films and molded fiber trays attract sustainability-focused procurement policies. First-mover suppliers capture German retail consolidation.
- Plastic Containers:Legacy PET formats face phase-out timelines under EU Green Deal circular economy targets. Remaining applications concentrate in price-sensitive emerging markets.
Retail Packs handle the greatest throughput. Eco-Friendly Packaging shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New Zealand pioneered commercial kiwifruit cultivation in the early twentieth century, establishing varietal breeding programs and export infrastructure that defined modern supply chains. Production geography has since diversified across multiple hemispheres as licensing systems spread proprietary cultivars.
China
Domestic consumers absorb rising volumes of imported gold kiwi through premium retail channels in Shanghai and Beijing. SAMR enforces residue limits under GB standards that determine import eligibility. Shaanxi Province hosts expanding domestic cultivation clusters where local growers trial licensed varieties.
New Zealand
Bay of Plenty orchard operators anchor global supply of proprietary gold cultivars under strict licensing terms. The Ministry for Primary Industries mandates export orchard registration and traceability documentation that filters market access. Te Puke and Tauranga host integrated post-harvest infrastructure handling controlled atmosphere storage.
Italy
Emilia-Romagna and Lazio regions concentrate European production of Hayward green kiwi for continental supermarket chains. EFSA residue monitoring protocols shape grower spray programs and harvest timing. Verona-based packhouses supply German retail channels with REACH-compliant biodegradable packaging formats.
United States
California's Central Valley hosts the dominant domestic production cluster, with Sacramento and Fresno counties supplying fresh fruit to West Coast supermarket chains. FDA phytosanitary inspections focus on fruit fly mitigation documentation for imported shipments. Quick-service beverage chains in Los Angeles and San Francisco expand frozen kiwi pulp procurement.
Chile
Counter-seasonal production in O'Higgins and Maule regions supplies Northern Hemisphere winter markets with green and gold varieties. Export phytosanitary certification aligns with EU and US import protocols. Port infrastructure at Valparaíso handles refrigerated container shipments to Asia-Pacific destinations.
Kiwi Fruit Market Vendor Landscape
The competitive structure tilts toward cultivar licensors with proprietary breeding programs. Two tiers separate premium variety controllers from commodity green growers. Licensing fees redirect substantial value from orchard operators to rights holders. Dominant competitive moves include strategic breeding program partnerships and integrated post-harvest infrastructure expansion.
Within the licensing-controlled tier, Zespri anchors proprietary gold kiwi supply chains across multiple hemispheres. Seeka exemplifies integrated orchard management and post-harvest infrastructure concentration. Turners & Growers occupies a position emphasizing specialized handling protocols for supermarket contract retention.
| Leading Market Players |
|---|
| Freshmax |
| Eurofruit |
| Zespri |
| Post Harvest Solutions |
| Kiwifruit New Zealand |
| Turners & Growers |
| Aongatete Coolstores |
| DMS Progrowers |
| Seeka |
| Others |
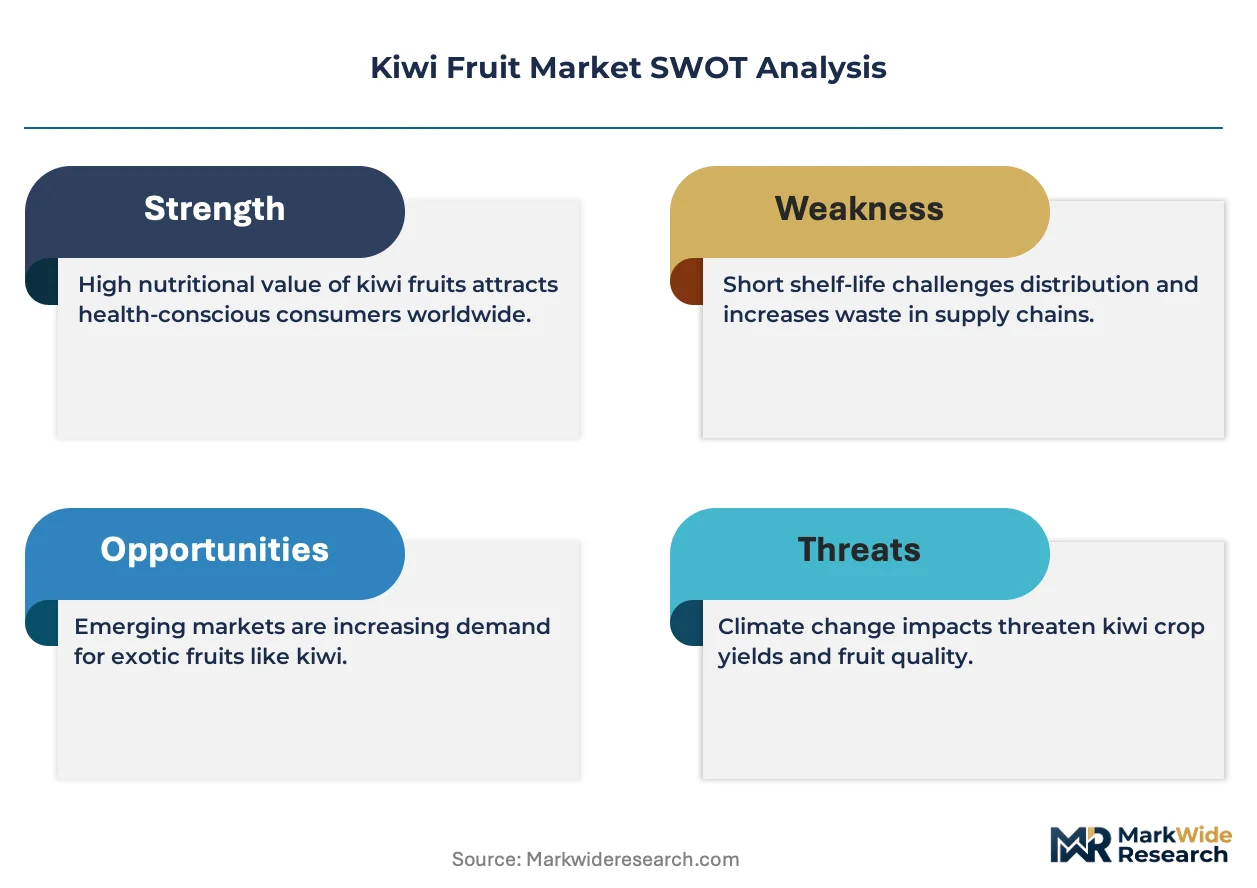
Supply Flow & Price Mechanics
Pollination specialist labor concentration in New Zealand's Bay of Plenty compresses margin spreads between premium gold and commodity green tiers, as hive service fees escalate faster than orchard gate returns.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates licensed SunGold cultivars from conventional Hayward green and unbranded bulk lots. Price differentiation rests on cultivar licensing status and organic certification grade under EFSA monitoring protocols. Cost compression in the green tier is intensifying because input volatility outpaces contract renewal negotiations. Supermarket private-label procurement teams exhibit highest price sensitivity, while quick-service beverage chains tolerate premium markups for frozen pulp with controlled brix specifications.
Supply Chain Analysis
Single-source vulnerability sits with proprietary cultivar licensors who control gold variety distribution rights across multiple hemispheres. Geographic supply concentration centers on New Zealand, Italy, and Chile as the dominant production clusters. Raw material dependencies include hive pollination services, controlled atmosphere storage infrastructure, and REACH-compliant biodegradable film wraps. Tariff exposure looms for counter-seasonal shipments from Chile to EU markets. Distribution runs through integrated packhouses with export orchard registration under New Zealand's Ministry for Primary Industries mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The kiwi fruit market functions as a stable compounder where recurring cultivar licensing revenue and expanding food service procurement sustain predictable expansion trajectories.
For Market Incumbents: Anchor competitive position through backward integration into controlled atmosphere storage capacity in Te Puke and Tauranga clusters, insulating against post-harvest infrastructure bottlenecks that strain smaller operators. Deepen breeding program partnerships ahead of patent expiration schedules to secure next-generation variety access. Defend against emerging organic entrants by accelerating three-year conversion timelines for existing orchard blocks. For New Entrants and Emerging Players: Direct-to-consumer subscription boxes for exotic fruit assortments offer the most penetrable white-space target in North American metropolitan markets with underdeveloped cold-chain last-mile solutions. Target smoothie bar procurement in Australasian urban centers where daily delivery requirements and perishability constraints deter established packhouse operators. Pursue a digital-native brand build with sustainability credentials to capture eco-packaging procurement policies consolidating German retail channels. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale organic conversion projects with partial certification timelines already elapsed. Long-term viability over a multi-year horizon rests on securing cultivar licensing access before patent cliffs redistribute variety premiums. Watch for inflection signals in CRISPR-based breeding program announcements that accelerate climate adaptation cycles and reshape production geography.| Strategic Initiative | Industry Significance |
|---|---|
| Controlled Atmosphere Storage Expansion | Extends marketing windows for Bay of Plenty orchard operators against seasonal price troughs. |
| Organic Certification Conversion | Captures tightening EFSA residue thresholds and supermarket eco-procurement consolidation. |
| Cultivar Licensing Partnership | Secures access to proprietary SunGold genetics ahead of patent expiration uncertainty. |
| Biodegradable Packaging Transition | Aligns with REACH-compliant film mandates driving German retail procurement consolidation. |
| Frozen Pulp Supply Agreement | Locks in multi-year commitments from quick-service beverage chains fortifying smoothie menus. |
Methodological Framework
Direct dialogue with orchard operators, packhouse managers, supermarket category buyers, and food service procurement directors combined with secondary validation from New Zealand Ministry for Primary Industries export registrations, EFSA residue monitoring reports, EU REACH regulatory filings, and customs trade data. Bottom-up volume modeling triangulated against top-down value estimates derived from cultivar licensing fee structures and retail price benchmarking.
Segmented outputs across product type, distribution channel, end user, and packaging format dimensions over the projection horizon reflect differential growth trajectories for organic certification tiers and proprietary variety licensing pools. CAGRs emerged from time-series analysis of export volume flows and price realization data, incorporating climate adaptation breeding timelines and regulatory packaging mandate phase-in schedules as scenario variables.
The model assumes a particular technology adoption path; alternative pathways for gene-edited cultivar development would alter the outlook if regulatory approval timelines compress faster than conventional hybridization displacement. Forecasts embed assumptions regarding pollination service availability and biodegradable material cost curves that supply-side shocks could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Cambodia Fruits and Vegetables Market
Fruits and Vegetables
Arecanut Market
Fruits and Vegetables
Plums and Sloes Market
Fruits and Vegetables
Button Mushroom Products Market
Fruits and Vegetables
Global Shiitake Mushroom Market
Fruits and Vegetables
Japan Fresh Fruits Market
Fruits and Vegetables
Asia Pacific Lime Market
Fruits and Vegetables
Fruit and Vegetable Cleaners Market
Fruits and Vegetables
Global Organic Fruits and Vegetables Market
Fruits and Vegetables
Global IQF Fruits Market
Fruits and Vegetables
Lycopene Market
Fruits and Vegetables
Dried Blueberries Market
Fruits and Vegetables
Tropical Fruit Puree Market
Fruits and Vegetables
White Mushroom Market
Fruits and Vegetables
Vaccinium Myrtillus Market
Fruits and Vegetables
Avocado-Based Products Market