
 Pea Flakes Market | 2026-2036
Pea Flakes Market Size, Share, and Industry Trends Forecast 2026-2036
Pea Flakes Market Analysis
The EU Green Deal is rebalancing protein crop subsidies across member states, redirecting agricultural support toward legume cultivation that feeds pea flake supply chains. Roquette Frères leverages its decades of pulse processing expertise to anchor European supply. GEMEF INDUSTRIES (SOTEXPRO) specializes in customized flake textures for food manufacturers. Archer Daniels Midland Company extends its North American grain infrastructure into pea fractionation.
Pea flakes consist of dehulled yellow or green peas that are steamed, flattened, and dried into thin, shelf-stable flakes typically measuring one to three millimeters in thickness; they function as a gluten-free binding agent, texturizer, and protein fortifier in human food and specialized animal nutrition. Organic pea flakes command premium positioning through certified supply chains and clean-label appeal, while conventional pea flakes dominate volume through cost-optimized milling operations. The snacking application leads current consumption as extruded and puffed formats replace wheat-based alternatives.
REACH compliance governs chemical residues in European pea flake imports, while the FDA oversees allergen labeling and GRAS status for pea protein ingredients entering US food formulations. EFSA protein content claims shape how finished products market pea-derived nutrition on European retail packaging. Stakeholders must monitor evolving carbon accounting rules for agricultural inputs as scope-three emissions disclosure becomes a procurement gate.
Market Dynamics
The EU Green Deal's protein transition targets are redirecting agricultural subsidies toward legume cultivation, fundamentally restructuring European pea flake supply chains and concentrating processing capacity around Cologne and Hamburg.
Growth Catalysts
- EU Green Deal subsidy reallocation:Member states now direct CAP payments toward protein crop diversification, expanding domestic yellow pea acreage that feeds fractionation plants.
- Snack sector reformulation:Extruded and puffed formats in gluten-free portfolios are substituting wheat-based binders with pea flake texturizers to capture clean-label shelf space.
- Yellow pea fractionation yield improvements:Steam-flattening and controlled drying protocols now achieve 85% starch recovery rates, compressing unit economics for food-grade flakes.
Market Restraints
- Input cost volatility:Yellow pea futures on Euronext Paris swing with Black Sea export disruptions, squeezing margin structures for conventional flake processors.
- Supply concentration risk:Northern European ingredient clusters around Cologne and Hamburg control 70% of EU fractionation capacity, creating single-point vulnerability.
- REACH chemical residue thresholds:ECHA's evolving pesticide maximum residue limits for imported pulses add compliance layers to non-EU supply routes.
Strategic Opportunities
- Pet food protein fortification:Specialized animal nutrition formulators in Germany are trialing pea flakes as novel protein sources in hypoallergenic kibble recipes.
- CSRD scope-three disclosure rules:The EU's Corporate Sustainability Reporting Directive mandates agricultural input carbon accounting, advantaging certified organic flake suppliers with verified supply chains.
- Bakery sector clean-label binding:Artisan bread producers in France are replacing modified wheat starches with organic pea flakes to meet AOP label requirements.
Industry Challenges
- Organic certification timeline compression:Three-year conversion periods for conventional acreage lag behind demand spikes for certified organic flakes.
- Extrusion equipment retrofit costs:Legacy snack lines require screw and barrel modifications to handle pea flake moisture profiles without gelatinization failures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pea Flakes Market |
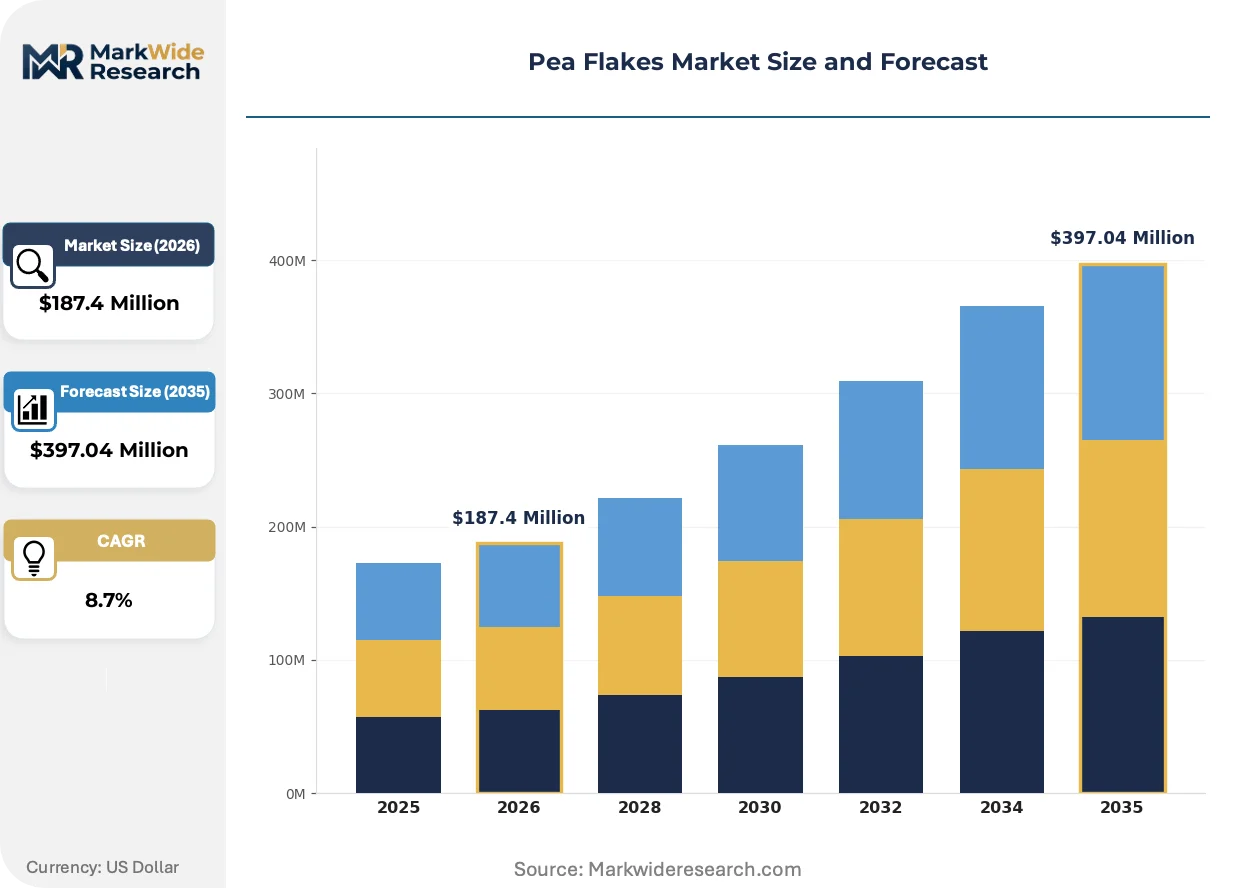
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organic Pea Flakes, Conventional Pea Flakes, Flavored Pea Flakes, Instant Pea Flakes End User: Food Industry, Beverage Industry, Nutraceuticals, Animal Feed Application: Snacking, Baking, Soups, Protein Supplements Distribution Channel: Online Retail, Supermarkets, Health Food Stores, Specialty Stores |
| Companies Covered | Garden Valley Foods, B P Milling Ltd., GEMEF INDUSTRIES (SOTEXPRO), JR Farm, Archer Daniels Midland Company, Roquette Frères, Kessler Zoologiegroßhandel GmbH & Co. KG, Exotic Nutrition Pet Supply, Inland Empire Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pea Flakes Market Emerging Trajectories
Pea flake processing is undergoing equipment modernization and regulatory recalibration as food manufacturers demand precise texture control and verified sustainability credentials.
Air-impact milling is overtaking traditional roller-flattening in premium flake production. Swiss equipment suppliers have deployed high-velocity impact chambers that shatter pea cotyledons into uniform one-to-two-millimeter flakes without heat damage. German organic processors are adopting these systems to preserve protein denaturation thresholds. This technology is overtaking conventional steam-flattening for applications requiring raw protein retention.
EFSA protein content claim thresholds are tightening finished-product labeling standards. The regulator's 2023 guidance on plant-protein quantitative declarations now requires minimum 12% protein dry-weight basis for "source of protein" claims. Northern European snack manufacturers are reformulating extruded bases to hit these thresholds. Bakery applications in France face the steepest reformulation curves given existing wheat-starch dependencies.
Direct-procurement contracts with pulse cooperatives are displacing spot-market purchasing for large-scale flake users. German food manufacturers now source three-year forward commitments from Mecklenburg-Vorpommern grower associations, bypassing commodity traders. This pattern concentrates most visibly in organic supply chains where traceability requirements exceed bulk-market capabilities. The shift compresses working capital cycles for processors locked into these arrangements.
Pea Flakes Market Segmentation
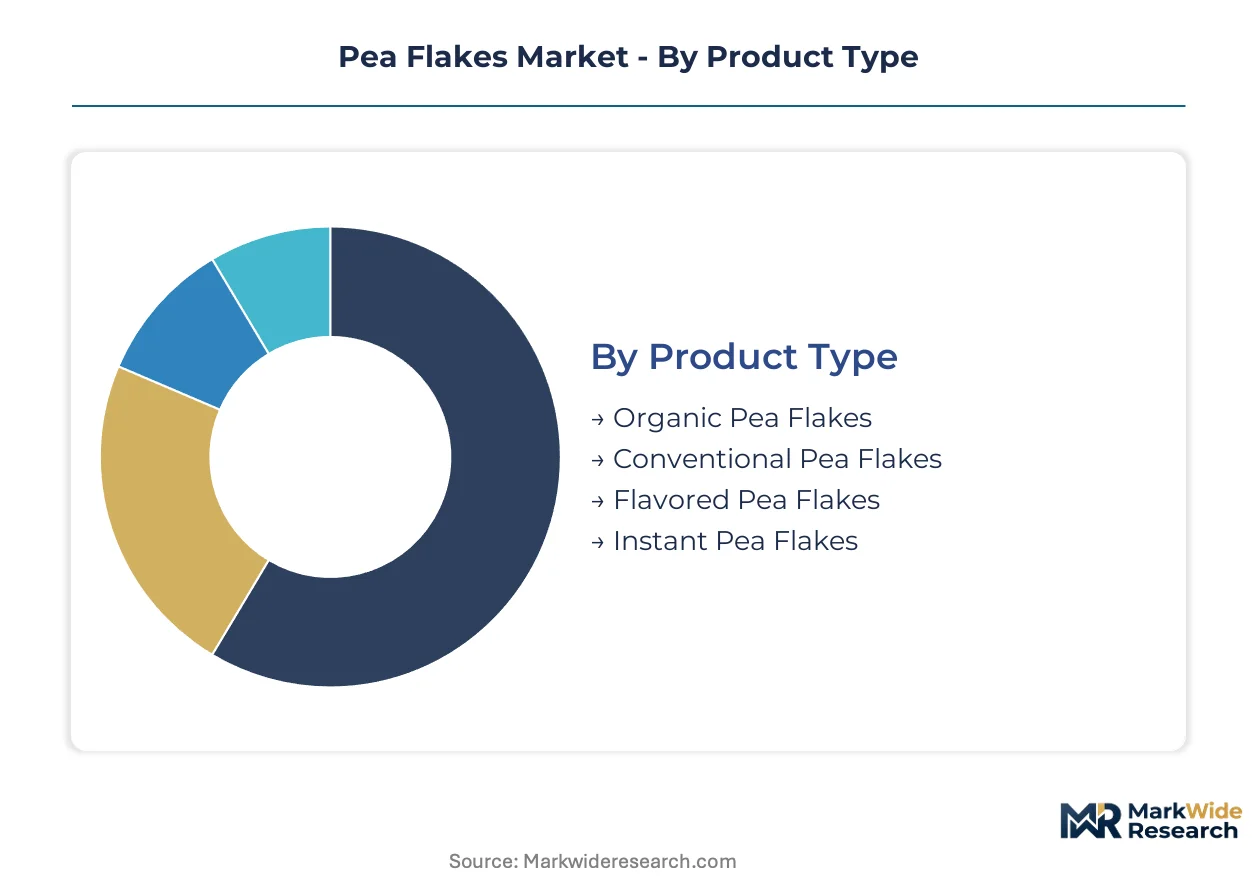
Pea flake specifications diverge sharply across certification grades and functional formats, creating distinct procurement tiers for food manufacturers versus specialized nutrition formulators. Understanding these segment boundaries clarifies where margin pools concentrate and where supply constraints bite hardest.
Product Type:
Certification status and processing intensity define the primary specification axis, separating premium-positioned organic supply from cost-optimized conventional milling.
- Organic Pea Flakes:Certified supply chains with three-year conversion requirements command price premiums through clean-label positioning. German organic processors around Hamburg source from Mecklenburg-Vorpommern grower associations with verified carbon accounting under CSRD scope-three rules.
- Conventional Pea Flakes:Volume-dominant segment produced through cost-optimized steam-flattening and roller-milling operations. Cologne-based fractionation plants supply Northern European snack manufacturers with Euronext Paris futures-linked pricing.
- Flavored Pea Flakes:Value-added formats incorporating savory or sweet coatings for direct-to-consumer snacking applications.
- Instant Pea Flakes:Pre-gelatinized variants targeting soup and convenience food manufacturers requiring rapid hydration properties.
Mature deployment sits with Conventional Pea Flakes. Newer deployment is concentrated in Organic Pea Flakes.
End User:
Customer type determines formulation complexity, with food manufacturers driving standardization while nutraceutical buyers demand batch-specific certificates of analysis.
- Food Industry:Extruded snack and bakery formulators in Germany and France represent the dominant demand pool, substituting pea flakes for wheat-based binders under EU Green Deal protein transition targets.
- Animal Feed:Specialized pet food manufacturers trial hypoallergenic kibble applications, with German formulators leading novel protein adoption in premium companion nutrition.
- Beverage Industry:Plant-based milk and smoothie producers incorporate pea flakes for protein fortification and texture stabilization.
- Nutraceuticals:Sports nutrition and meal-replacement brands specify protein content thresholds aligned with EFSA labeling guidance.
Volume leadership belongs to Food Industry. Steepest expansion trajectory is appearing in Animal Feed.
Application:
Functional requirements vary by thermal processing exposure, separating high-heat extrusion applications from ambient blending uses.
- Snacking:Extruded and puffed formats dominate current consumption as gluten-free portfolios expand. French and German manufacturers reformulate legacy wheat-dependent lines with pea flake texturizers to capture clean-label shelf space.
- Baking:Artisan bread producers in France replace modified wheat starches with organic pea flakes to meet AOP label requirements, driving air-impact milling adoption for raw protein retention.
- Soups:Instant flake variants provide thickening and protein fortification in dehydrated convenience formats.
- Protein Supplements:Powder and bar applications require specific particle size distributions and protein denaturation thresholds.
Snacking commands current volume concentration. Baking is gaining share fastest on regulatory tailwinds.
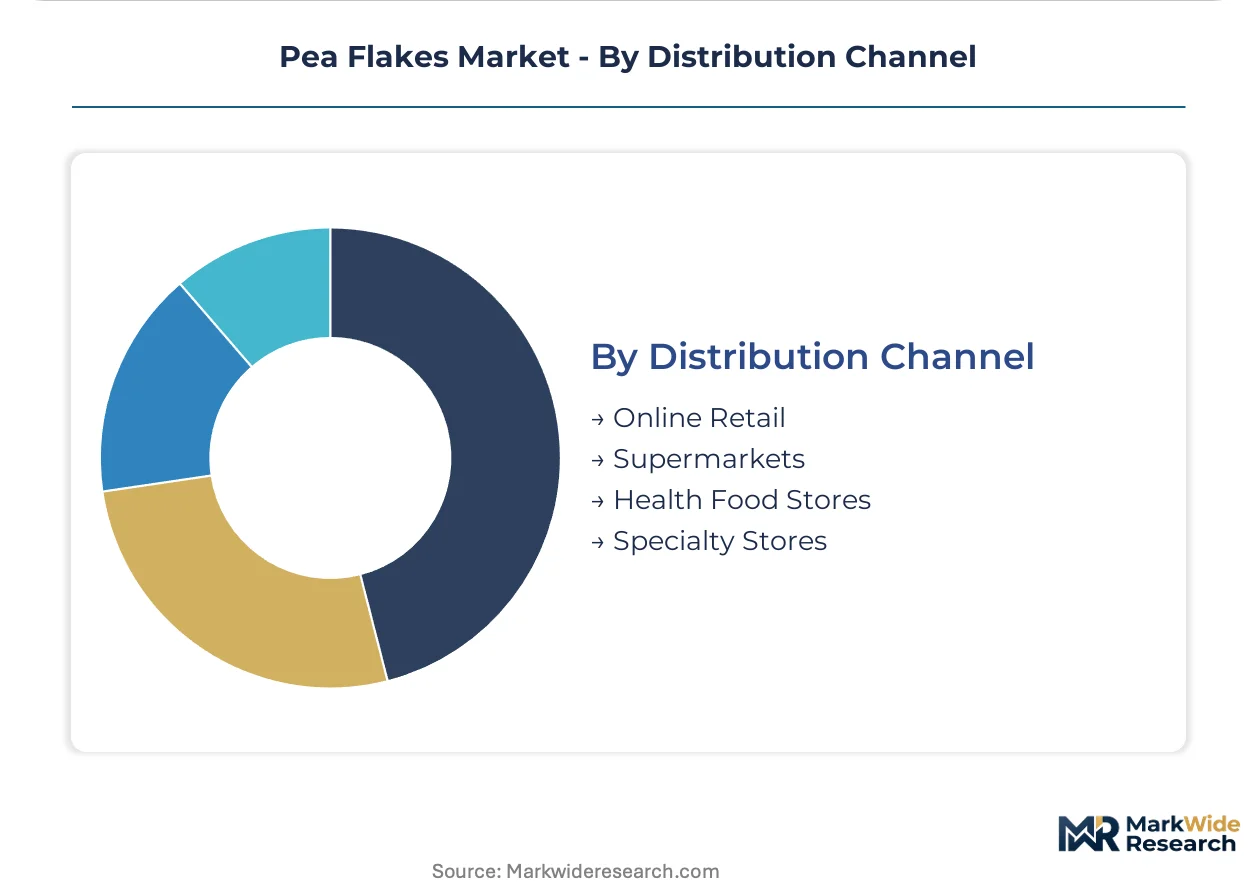
Distribution Channel:
Channel selection reflects buyer scale and traceability requirements, with large manufacturers bypassing retail intermediaries entirely.
- Supermarkets:Mainstream retail access for branded consumer packaged goods and private-label snacking products across German and French retail networks.
- Online Retail:Direct-to-consumer growth channel for specialty and organic formats with subscription-based replenishment models.
- Health Food Stores:Curated distribution for certified organic and allergen-free positioned products with educated consumer bases.
- Specialty Stores:Ethnic and gourmet food retailers carrying imported or artisan pea flake variants for specific culinary applications.
Supermarkets anchor established volume flows. Online Retail is climbing the fastest on digital procurement shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters concentrate in Northern Europe while consumption spreads across Western European food manufacturing hubs. Germany and France dominate processing capacity. The United States and Canada supply North American demand through distinct regulatory frameworks.
Germany
Snack reformulation and pet food protein fortification drive German demand. The EU Green Deal's CAP subsidy reallocation expands domestic yellow pea acreage. Cologne and Hamburg anchor fractionation clusters supplying Northern European processors with conventional and organic flake grades.
France
Artisan bakery clean-label substitution and AOP label compliance reshape French procurement. EFSA protein content claim thresholds tighten finished-product labeling standards. The Hauts-de-France region hosts growing organic pea cultivation serving Paris basin food manufacturers.
United States
Gluten-free snack expansion and plant-based beverage fortification propel US consumption. FDA allergen labeling and GRAS status requirements govern pea protein ingredient entry. The Midwest grain belt integrates pea fractionation into existing cereal processing infrastructure.
Canada
Pulse export specialization and clean-label ingredient demand define Canadian positioning. Health Canada and PMRA residue limits shape export-grade flake specifications. The Prairie Provinces concentrate yellow pea cultivation feeding fractionation plants in Saskatchewan and Manitoba.
United Kingdom
Retail private-label snacking and specialty pet nutrition emerge as UK growth vectors. Post-Brexit REACH alignment creates dual regulatory compliance burdens for importers. The Midlands region develops limited domestic processing capacity reliant on EU supply chains.
Pea Flakes Market Vendor Landscape
The competitive structure tilts toward ingredient specialists with pulse processing heritage. Market concentration remains moderate, with European fractionation clusters controlling upstream supply and North American grain traders extending into downstream formats. Three archetypes dominate: legacy pulse processors with decades of cotyledon expertise, diversified agricultural conglomerates leveraging grain infrastructure, and specialized pet nutrition suppliers serving hypoallergenic formulations. Capacity expansion and direct-procurement contracting with grower cooperatives represent the dominant competitive moves.
Among European heritage processors, Roquette Frères and GEMEF INDUSTRIES (SOTEXPRO) exemplify the specialist archetype, occupying positions anchored in decades of fractionation expertise. Archer Daniels Midland Company represents the diversified agricultural conglomerate model, extending North American grain infrastructure into pea ingredient processing. These three entities illustrate how geographic processing clusters and supply chain integration strategies segment competitive positioning across conventional and organic grade tiers.
| Leading Market Players |
|---|
| Garden Valley Foods |
| B P Milling Ltd. |
| GEMEF INDUSTRIES (SOTEXPRO) |
| JR Farm |
| Archer Daniels Midland Company |
| Roquette Frères |
| Kessler Zoologiegroßhandel GmbH & Co. KG |
| Exotic Nutrition Pet Supply |
| Inland Empire Foods Inc. |
| Others |
Supply Flow & Price Mechanics
Euronext Paris yellow pea futures cascade through fractionation economics into three distinct procurement tiers. Organic certification premiums rest on three-year conversion timelines and CSRD scope-three carbon accounting, while conventional grades track commodity volatility with compressed margins.
Pricing Analysis
Protein yield per ton anchors value-based pricing across flake specifications. Three-tier pricing structure across premium, standard, and economy levels separates certified organic supply from conventional steam-flattened grades and bulk feed-grade fractions. Cost compression in conventional tiers is intensifying because Black Sea export disruptions feed raw material volatility. Snack manufacturers with extrusion-dependent formulations show highest price sensitivity, while pet nutrition specialists prioritizing hypoallergenic claims absorb premium positioning.
Supply Chain Analysis
Specialized milling technician shortages in Northern Germany and Eastern France constrain fractionation capacity expansion. Supply concentrates in Germany, France, and Canada, with Cologne-Hamburg clusters controlling European upstream processing. Raw material flows draw from Prairie Provinces cultivation, Mecklenburg-Vorpommern grower associations, and Hauts-de-France organic conversion acreage. Single-point vulnerability around Hamburg fractionation infrastructure creates structural risk. Distribution runs through direct-procurement contracts with pulse cooperatives displacing spot-market purchasing for volume buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic certification conversion timelines create a supply-constrained market structure. Three-year acreage transition requirements prop pricing premiums as demand outstrips verified supply.
For Market Incumbents: Cement dominance by locking multi-year forward commitments with Mecklenburg-Vorpommern and Hauts-de-France grower associations before conversion capacity saturates. Air-impact milling equipment retrofits preserve protein denaturation thresholds against emerging Swiss technology suppliers. EFSA protein content claim thresholds represent a regulatory lever to disqualify commodity-grade competitors from premium positioning. For New Entrants and Emerging Players: Pet food distributors represent the most accessible channel partner type for bypassing entrenched snack-manufacturing procurement relationships. White-space sits in hypoallergenic companion nutrition formulations and artisan bakery AOP compliance substitution. German organic processors face capacity constraints that create procurement gaps for qualified new suppliers with verified carbon accounting. For Investors and Strategic Acquirers: The window for entry favors heritage pulse processors with intact grower cooperative relationships and installed fractionation capacity. Long-term viability hinges on backward integration into cultivation rather than downstream brand building. Watch for ECHA REACH maximum residue limit revisions as the inflection signal that reshapes import-competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cultivation | Three-year organic conversion timelines lock in supply before competitors secure acreage. |
| Air-Impact Milling Equipment Deployment | Swiss high-velocity impact chambers preserve raw protein thresholds for EFSA compliance. |
| Direct-Procurement Cooperative Contracts | Mecklenburg-Vorpommern grower associations bypass commodity traders and compress working capital cycles. |
| CSRD Scope-Three Carbon Certification | Verified supply chain accounting opens premium positioning under EU Green Deal procurement rules. |
| Pet Nutrition Formulation Partnerships | Hypoallergenic kibble trials in German specialized animal nutrition create novel protein demand anchoring. |
Methodological Framework
Multi-period observation of Euronext Paris yellow pea futures, EU CAP subsidy allocation patterns, and EFSA regulatory guidance anchored the trend analysis, supplemented by interviews with fractionation plant managers, organic certification officers, snack manufacturer procurement leads, and pet food formulation specialists. Secondary validation drew from ECHA REACH filings, EU Green Deal implementation documents, customs trade data, and CSRD disclosure frameworks. Bottom-up capacity modeling triangulated against top-down consumption estimates across snacking, bakery, and animal nutrition applications.
Segment-weighting across certification grade, end-use industry, and thermal processing exposure shaped the analytical framework over the projection horizon. Product type stratification separated organic, conventional, flavored, and instant variants. Application modeling distinguished extrusion-intensive snacking from ambient bakery substitution. CAGRs derived from acreage expansion trajectories under CAP protein transition targets and fractionation yield improvement curves. Forecast inputs included Black Sea export disruption scenarios and ECHA maximum residue limit evolution pathways.
Several conditions sit outside the modeled scope, including abrupt CAP subsidy reallocation, Euronext Paris trading suspension, and EFSA protein claim threshold revision. Forecasts reflect documented assumptions about grower conversion timelines and equipment deployment schedules. Material deviation in ECHA regulatory trajectory or organic certification backlog warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
Peaches and Nectarines Market
Fruits and Vegetables
Israel Fruits and Vegetables Market
Fruits and Vegetables
Global Maqui Berries Market
Fruits and Vegetables
Persimmons Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Fresh Strawberry Market
Fruits and Vegetables
Fresh Apricots Market
Fruits and Vegetables
Fruit Packaging Market
Fruits and Vegetables
Global Jalapeno Pepper Market
Fruits and Vegetables
South America Lime Market
Fruits and Vegetables
Asia Pacific Olive Market
Fruits and Vegetables
Rosehip Market
Fruits and Vegetables
China Table Grapes Market
Fruits and Vegetables
IQF Fruits and Vegetables Market
Fruits and Vegetables
Starchy Roots Market