
 Global Dried Apricots Market | 2026-2036
Global Dried Apricots Market Size, Share, and Industry Trends Forecast 2026-2036
Global Dried Apricots Market Analysis
Sulfur dioxide is restructuring cost structures across the dried apricots industry as organic alternatives command premium positioning. Sun-Maid Growers of California leverages its integrated orchard-to-package infrastructure to sustain supply consistency through seasonal volatility. Anatolia A.S. anchors Mediterranean export corridors with specialized sun-dried production capacity. BATA FOOD competes on sulfur-free processing certifications that unlock European retail access.
Dried apricots are pitted, dehydrated stone fruit with moisture content typically below 16%, preserved through sun exposure, mechanical dehydration, or sulfur dioxide treatment to extend shelf stability and retain color for commercial distribution. The organic product type commands expanding shelf space as EU REACH and FDA residue thresholds tighten on sulfur-dried alternatives, while conventional segments retain volume dominance in food service and industrial ingredient channels. Retailers and food processors represent the most concentrated end-user demand pools, with bulk packaging formats dominating processor procurement and branded bags capturing supermarket replenishment cycles.
FDA food safety standards and EU REACH chemical regulations jointly shape permissible sulfur dioxide residue levels, directly determining which product types qualify for cross-border shipment into the United States and European Union. Turkey's national food codex and California's state agricultural inspection protocols add further compliance layers for origin-specific suppliers. Stakeholders must monitor evolving organic certification requirements and sulfur threshold adjustments to preserve market access across major import jurisdictions.
Market Dynamics
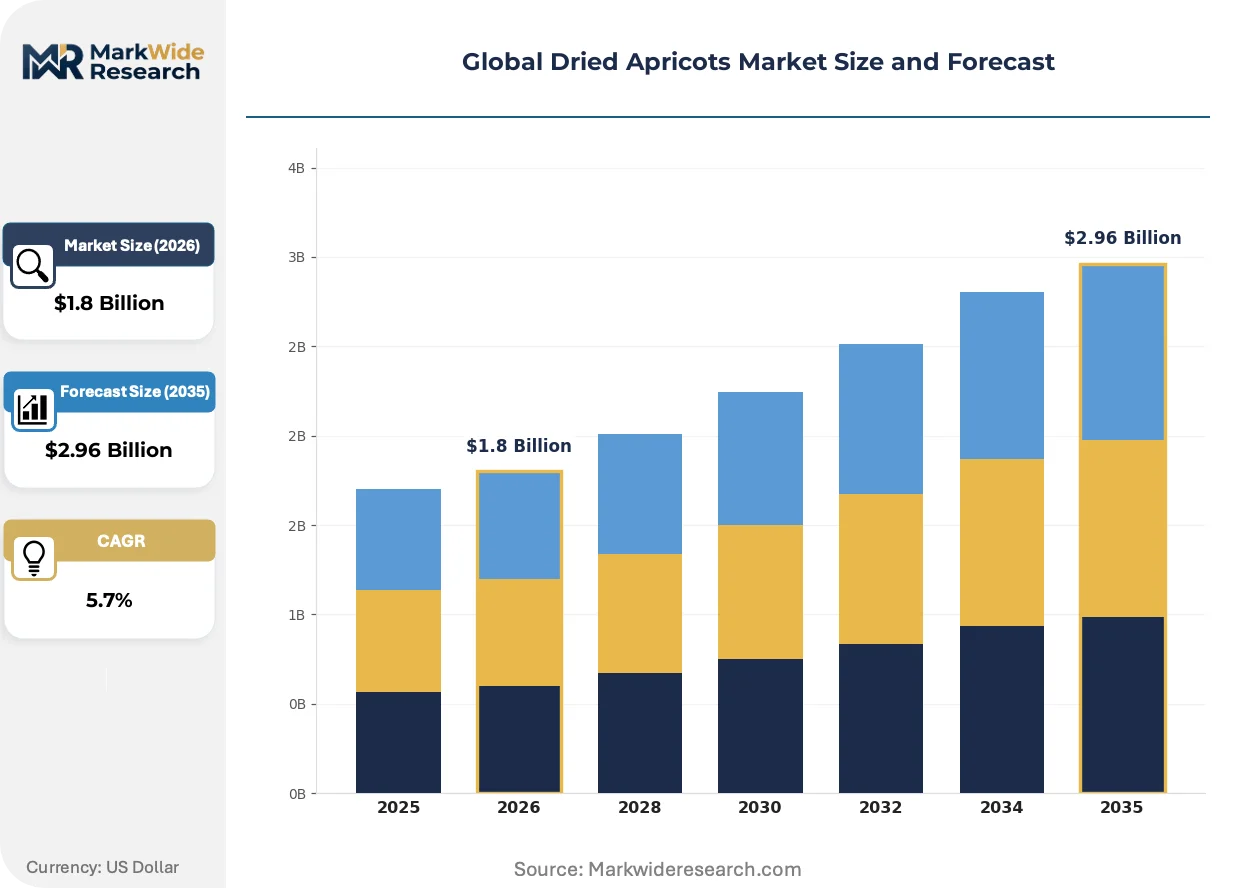
Sulfur dioxide residue limits under EU REACH and FDA standards are compressing conventional processing margins while redirecting capital toward organic certification infrastructure across Turkish and Californian supply bases.
Growth Catalysts
- EU REACH residue thresholds:Tightening sulfur dioxide limits on dried apricot imports are accelerating organic orchard conversions in Turkey's Malatya province and California's Central Valley.
- Food processor procurement:Industrial ingredient buyers in European bakery and confectionery channels are expanding sulfur-free supply contracts to meet clean-label product specifications.
- Solar tunnel drying:Mechanical dehydration systems with photovoltaic integration are reducing weather dependency in sun-dried production clusters.
Market Restraints
- Input cost volatility:Natural gas prices for mechanical dehydration and sulfur dioxide procurement costs fluctuate with energy market cycles, squeezing processor margins.
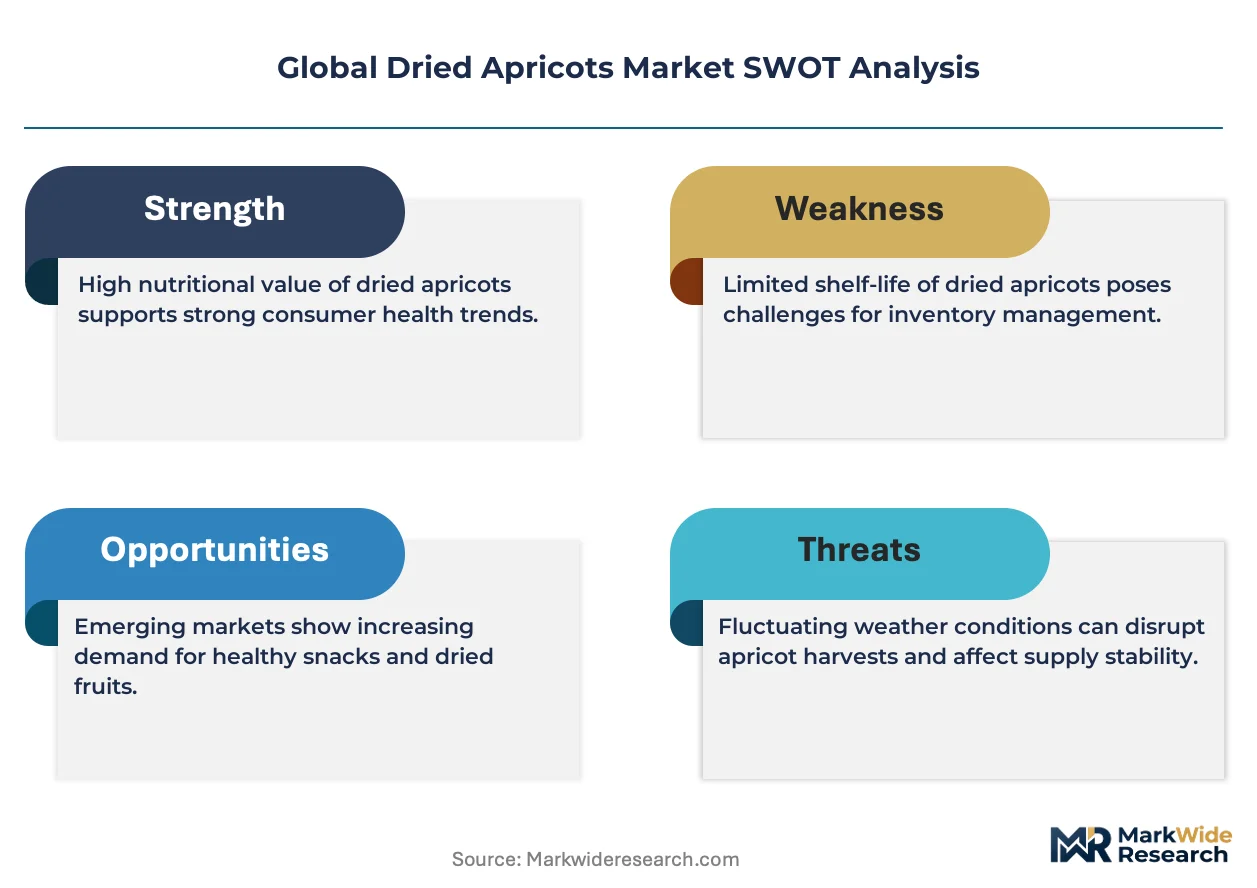
- Supply concentration risk:Turkey controls approximately two-thirds of exportable dried apricot volume, creating single-origin vulnerability for European importers.
- Technical limitation:Organic sun-dried apricots achieve shorter shelf stability without sulfur treatment, limiting distribution radius for untreated product.
Strategic Opportunities
- Indian retail expansion:Organized supermarket chains in Mumbai and Delhi are establishing dedicated dried fruit sections with premium positioning for sulfur-free imports.
- EU Green Deal agricultural incentives:Carbon footprint reduction subsidies for organic farming are lowering certification cost barriers for Turkish cooperative processors.
- E-commerce direct-to-consumer:Specialized health-food platforms in Germany and the Netherlands are bypassing traditional wholesale layers for artisanal sun-dried varieties.
Industry Challenges
- Organic certification timeline:Three-year transition periods for orchard conversion to EU organic standards delay revenue recognition for farmers switching from conventional sulfur treatment.
- Cold chain reconfiguration:Sulfur-free dried apricots require temperature-controlled warehousing and transport, demanding capital deployment that small-scale Turkish processors struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Dried Apricots Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conventional, Organic, Sun-Dried, Sulfur-Dried End User: Retailers, Food Processors, Food Service, Exporters Packaging Type: Bags, Boxes, Jars, Bulk Sales Channel: Online, Supermarkets, Specialty Stores, Wholesale |
| Companies Covered | Sun-Maid Growers of California, Anatolia A.S., BATA FOOD, Traina Foods, KENKKO CORPORATION, Sunsweet Growers, Red River Foods, National Raisin Company, Bergin Fruit and Nut Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Dried Apricots Market Emerging Trajectories
Processing technology and regulatory compliance frameworks are converging to redefine competitive advantage in dried apricot supply chains, with sulfur-free preservation methods gaining industrial scale.
Near-infrared spectroscopy is integrating into Turkish processing lines for real-time moisture and sulfur residue detection. Quality control laboratories at Malatya export facilities are adopting these systems to pre-certify shipments before EU customs entry. The technology is integrating batch-release decisions with automated sorting, compressing inspection timelines from days to hours.
EU REACH Annex XVII restrictions on sulfur dioxide in dried fruits entered full enforcement for retail-ready packages in 2023. Food manufacturers reformulating product lines are demanding certificate-of-analysis documentation from every lot. Organic-certified processors in California's Central Valley are capturing price premiums as conventional suppliers face border rejection risk.
Clean-label procurement mandates from European supermarket private-label programs are displacing sulfur-treated bulk supply contracts. German and Dutch retail chains now specify sulfur-free processing in their dried fruit tender specifications. This shift concentrates volume with processors holding EKO and BioSuisse certifications rather than conventional export houses.
Global Dried Apricots Market Segmentation
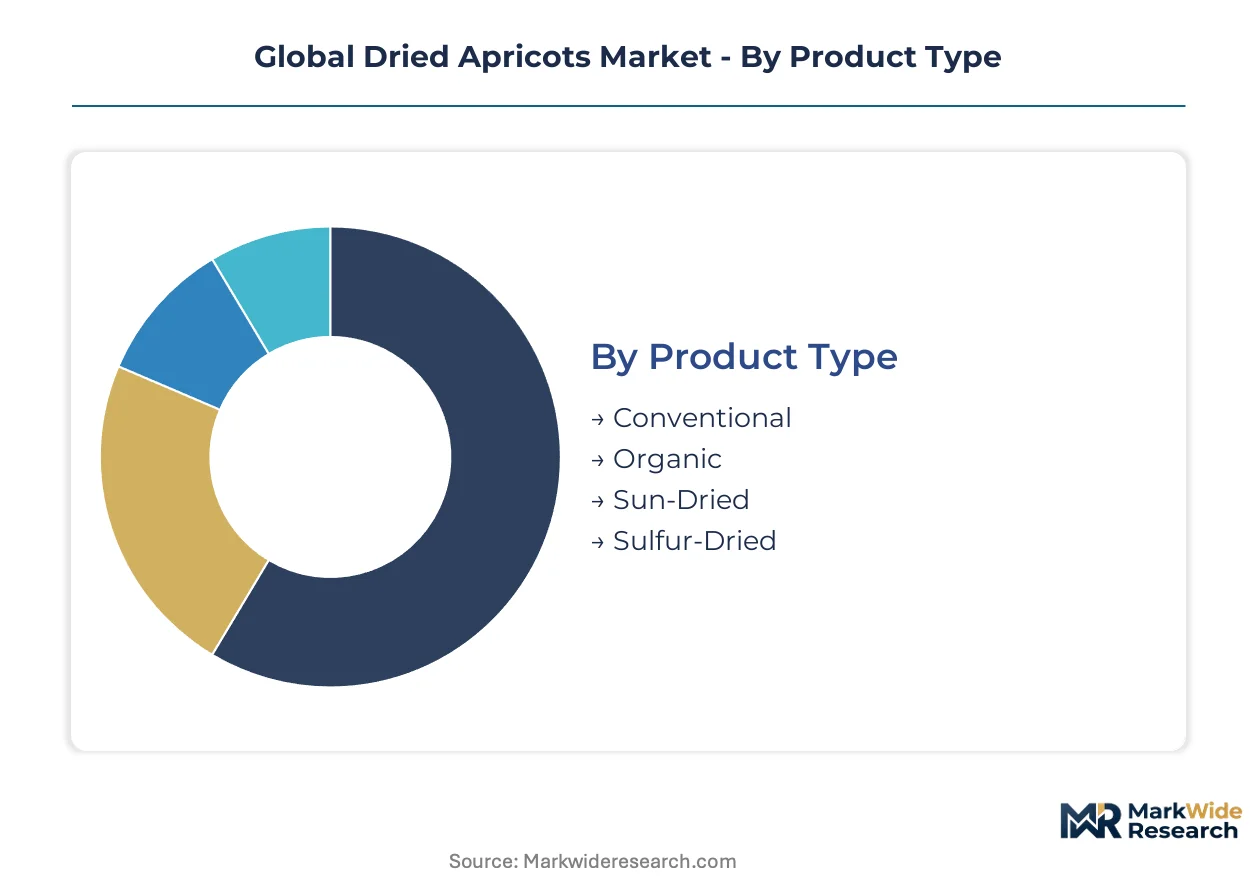
Dried apricot procurement splits sharply between industrial-scale food manufacturing and consumer-facing retail channels. Sulfur treatment status and organic certification now determine which segments qualify for EU and US market entry.
Product Type:
Standalone product formats dominate shelf-stable retail positioning, while embedded ingredient applications drive bulk sulfur-dried procurement for food manufacturing.
- Conventional:Sulfur dioxide treatment preserves bright orange color and extends shelf stability to 24 months. European bakery and confectionery manufacturers in Germany and the Netherlands maintain volume contracts for this grade despite tightening EU REACH residue thresholds.
- Organic:Orchard conversion requires three-year transition periods under EU organic standards. California's Central Valley growers and Turkish Malatya cooperatives are redirecting capital toward certification infrastructure to capture clean-label premiums in German and Dutch retail chains.
- Sun-Dried:Traditional dehydration without mechanical intervention yields darker color and denser texture. Malatya province maintains specialized tunnel drying capacity with photovoltaic integration.
- Sulfur-Dried:Gas treatment during dehydration blocks enzymatic browning for visual consistency. FDA and EU REACH residue limits are compressing addressable market for this segment.
Conventional sulfur-dried apricots lead volumes today; organic certified product is gaining share fastest.
End User:
Customer type determines packaging scale, certification requirements, and price sensitivity across procurement relationships.
- Retailers:Supermarket private-label programs in Germany and the Netherlands now mandate sulfur-free processing specifications. Branded 200-400 gram bag formats dominate replenishment cycles.
- Food Processors:Industrial ingredient buyers reformulate product lines to meet clean-label mandates. Bulk procurement concentrates in Turkish export houses with integrated quality laboratories.
- Food Service:Hotel and restaurant channels in Mumbai and Delhi are expanding dried fruit sections with premium positioning for sulfur-free imports.
- Exporters:Re-export traders manage cross-border documentation for EU REACH and FDA compliance. Certificate-of-analysis requirements from every lot have become standard.
Food processors command the largest volume contracts; retailers are expanding shelf space most aggressively.
Packaging Type:
Format selection tracks end-user scale and shelf-life requirements, with bulk and retail-ready options serving distinct supply chain tiers.
- Bags:Flexible retail packaging with resealable closures captures supermarket replenishment cycles. German health-food platforms favor this format for direct-to-consumer shipment.
- Boxes:Rigid secondary packaging protects product integrity through extended distribution. Common for gift-oriented retail positioning in Indian metropolitan markets.
- Jars:Glass container formats target premium positioning in specialty store channels. Higher unit economics justify temperature-controlled warehousing requirements.
- Bulk:10-25 kilogram food-grade containers dominate processor procurement. Turkish export facilities pre-certify bulk lots before EU customs entry using near-infrared spectroscopy.
Bulk packaging handles the greatest tonnage; bag formats are climbing the fastest in value terms.
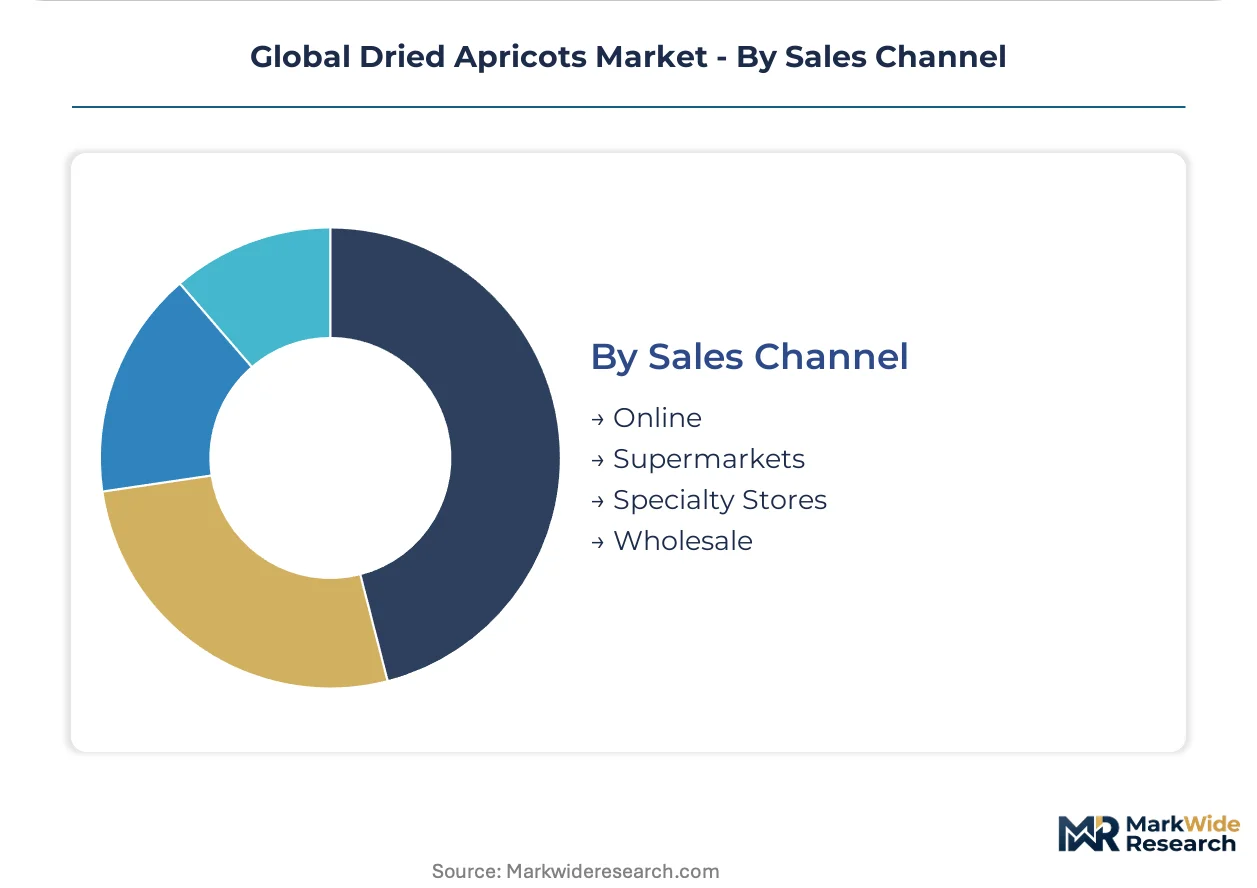
Sales Channel:
Channel structure reflects buyer scale, certification documentation requirements, and speed-to-shelf priorities.
- Online:Specialized health-food platforms in Germany and the Netherlands bypass traditional wholesale layers. Artisanal sun-dried varieties command premium positioning here.
- Supermarkets:Organized chains in Mumbai and Delhi are establishing dedicated dried fruit sections. Private-label procurement mandates now specify sulfur-free processing.
- Specialty Stores:Independent retailers focus on organic-certified and origin-specific product. BioSuisse and EKO certifications unlock shelf access.
- Wholesale:Traditional export houses manage volume aggregation from Turkish cooperative processors. EU Green Deal agricultural incentives are lowering certification cost barriers for supplier bases.
Wholesale channels move the highest volumes; online direct-to-consumer is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malatya province anchors the global dried apricots supply base, hosting specialized tunnel drying capacity and photovoltaic-integrated processing clusters that serve European export corridors.
Turkey
EU REACH Annex XVII sulfur dioxide restrictions are accelerating orchard conversions across Malatya's cooperative processor network. The country's national food codex adds compliance layers for sulfur residue documentation. Turkish export facilities now deploy near-infrared spectroscopy to pre-certify bulk lots before customs entry into Germany and the Netherlands.
United States
FDA residue thresholds and California state agricultural inspection protocols shape permissible sulfur levels for cross-border shipment. The Central Valley's integrated orchard-to-package infrastructure sustains supply consistency through seasonal volatility. Sun-Maid Growers leverages this captive production base to serve industrial ingredient buyers reformulating for clean-label specifications.
Germany
Supermarket private-label programs now mandate sulfur-free processing in dried fruit tender specifications. EKO certification requirements determine shelf access for organic-certified imports. Health-food platforms in Berlin and Hamburg bypass traditional wholesale layers through direct-to-consumer e-commerce channels for artisanal sun-dried varieties.
India
Organized retail chains in Mumbai and Delhi are establishing dedicated dried fruit sections with premium positioning for sulfur-free imports. FSSAI food safety standards govern permissible preservative levels for imported dried fruits. Food service channels in metropolitan hotels and restaurants are expanding procurement of certified organic product for health-conscious menu positioning.
Netherlands
Rotterdam's port infrastructure functions as the primary EU entry point for Turkish bulk shipments requiring REACH compliance documentation. BioSuisse certification unlocks retail access for premium organic positioning. Specialized logistics providers have developed temperature-controlled warehousing capacity to handle sulfur-free product with shorter shelf stability profiles.
Global Dried Apricots Market Vendor Landscape
Capacity expansion dominates the current landscape as processors retrofit mechanical dehydration lines for organic certification compliance. The vendor base clusters around three strategic archetypes: integrated orchard-to-package operators with captive raw material supply, specialized export houses with integrated quality laboratories, and diversified dried fruit processors leveraging multi-commodity infrastructure. M&A activity concentrates on acquiring organic-certified orchard assets, while strategic partnerships with European retail chains secure offtake agreements for sulfur-free volume.
Within the integrated operator tier, Sun-Maid Growers of California exemplifies backward control over upstream supply through captive Central Valley orchards. Anatolia A.S. occupies a position representing Mediterranean export corridor specialization with Malatya-based tunnel drying capacity. BATA FOOD sits within the certification-driven segment, anchoring sulfur-free processing credentials that unlock European retail access. These three players represent distinct competitive vectors: captive supply security, regional processing scale, and compliance-based market entry.
| Leading Market Players |
|---|
| Sun-Maid Growers of California |
| Anatolia A.S. |
| BATA FOOD |
| Traina Foods |
| KENKKO CORPORATION |
| Sunsweet Growers |
| Red River Foods |
| National Raisin Company |
| Bergin Fruit and Nut Company |
| Others |
Supply Flow & Price Mechanics
Skilled tunnel-drying specialists concentrated in Turkey's Malatya province command wage premiums that widen spreads between organic-certified and conventional sulfur-dried grades. Labor-cost differentials between Turkish cooperative processors and California's Central Valley mechanized operations feed directly into three-tier pricing stratification across premium, standard, and economy levels.
Pricing Analysis
Input-cost pass-through from natural gas and sulfur dioxide procurement compresses margins for conventional processors while organic-certified suppliers capture residual pricing power. Certification grade and volume scale drive price differentiation, with EKO and BioSuisse tiers commanding substantial premiums over conventional export grades. Cost compression in sulfur-dried segments is intensifying because EU REACH residue thresholds are disqualifying marginal suppliers from European retail access. Food processors represent the most price-sensitive buyer pool, while German health-food platforms show lowest sensitivity due to clean-label mandate compliance.
Supply Chain Analysis
Freight cost volatility on Black Sea-Mediterranean routes and Red Sea transit alternatives reshapes landed cost structures for Turkish exports entering Rotterdam. Supply concentrates in Turkey, the United States, and Afghanistan, with Malatya province hosting two-thirds of exportable volume. Raw material dependencies center on fresh apricot harvests, natural gas for mechanical dehydration, and sulfur dioxide for conventional preservation. Single-origin vulnerability from Turkish supply dominance creates structural risk for European importers. Distribution runs through Rotterdam port infrastructure for EU REACH pre-certification, then branches to German supermarket chains and Dutch wholesale aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Turkish labor-cost advantages and California's regulatory compliance infrastructure, with EU REACH sulfur thresholds creating divergent cost structures for cross-border market access.
For Market Incumbents: Lock in long-term offtake agreements with German and Dutch retail chains before organic certification capacity floods the market. Defensive consolidation through acquiring Malatya-based tunnel drying assets with existing photovoltaic integration addresses emerging entrant competition from Indian retail expansion. Certification investment in cold chain infrastructure protects margin position as sulfur-free shelf stability requirements tighten.
For New Entrants and Emerging Players: EU REACH Annex XVII in Germany and the Netherlands opens a window for sulfur-free processing specialists to capture displaced conventional volume. White-space targets include Mumbai and Delhi organized retail chains establishing dedicated dried fruit sections, plus direct-to-consumer health-food platforms in Berlin and Hamburg. The most penetrable segment is artisanal sun-dried varieties bypassing traditional wholesale layers. Go-to-market execution should anchor on BioSuisse certification for premium positioning.
For Investors and Strategic Acquirers: Dried fruit processors with multi-commodity infrastructure are the most active acquirer in this space, seeking organic-certified orchard assets to retrofit existing mechanical dehydration lines. Long-term viability hinges on five-to-ten year organic conversion timelines aligning with EU Green Deal agricultural incentive windows. Acquisition target archetype: Turkish cooperative processors with integrated quality laboratories and existing EKO certification. The signal to watch is FSSAI enforcement tightening on sulfur residue levels in Indian metropolitan markets.
| Strategic Initiative | Industry Significance |
|---|---|
| Organic Orchard Conversion | Captures EU REACH-compliant volume as sulfur-dried alternatives face border rejection. |
| Photovoltaic Tunnel Drying Deployment | Reduces weather dependency and natural gas cost exposure in Malatya processing clusters. |
| Cold Chain Infrastructure Investment | Enables sulfur-free distribution radius extension for shorter shelf stability product. |
| Direct-to-Consumer E-commerce Launch | Bypasses wholesale margin extraction in German and Dutch health-food platform channels. |
| Near-Infrared Spectroscopy Integration | Compresses EU customs pre-certification timelines from days to hours at export facilities. |
Methodological Framework
Multiple input streams — structured interviews with Turkish cooperative processors and California orchard operators, trade flow analysis from Turkish Statistical Institute and US Census Bureau customs records, and regulatory filing review from ECHA and FDA guidance documents — were reconciled to construct supply and demand estimates. Primary fieldwork engaged dried fruit export house managers, German supermarket category buyers, Dutch wholesale aggregators, and Indian organized retail procurement heads. Secondary validation drew from EU REACH Annex XVII enforcement notices, California state agricultural inspection protocols, and FSSAI food safety standard updates. Bottom-up orchard capacity modeling and top-down retail channel revenue triangulation anchored volume and value projections.
Data-stream reconciliation across product type, end user, packaging format, and sales channel segmentation dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from growth rate convergence modeling applied to historical trade volumes and forward-looking certification capacity buildout. Industry-specific forecast inputs included EU organic transition timeline assumptions and photovoltaic drying adoption curves in Malatya province.
Revisions become necessary when EU REACH sulfur dioxide thresholds tighten beyond current Annex XVII specifications, when natural gas price volatility disrupts mechanical dehydration economics, or when Indian FSSAI enforcement accelerates on imported dried fruits. Forecasts reflect documented assumptions about orchard conversion rates and retail clean-label mandate diffusion. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Jackfruit Market
Fruits and Vegetables
South America Olive Market
Fruits and Vegetables
Dehydrated Beets Market
Fruits and Vegetables
Packaged Fresh Fruits Market
Fruits and Vegetables
Chile Fruits and Vegetables Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Colombia Fruits and Vegetables Market
Fruits and Vegetables
Mung Beans Market
Fruits and Vegetables
Yacon Fruit Extract Market
Fruits and Vegetables
Annatto Market
Fruits and Vegetables
Cyanidin Market
Fruits and Vegetables
Japan Frozen Fruit Puree Market
Fruits and Vegetables
Freeze Dried Bananas Market
Fruits and Vegetables
Global Morel Mushroom Market
Fruits and Vegetables
Haskap Berry Powder Market
Fruits and Vegetables
Fruit Packaging Market