
 Mexico Lime Market | 2026-2036
Mexico Lime Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Lime Market Outlook
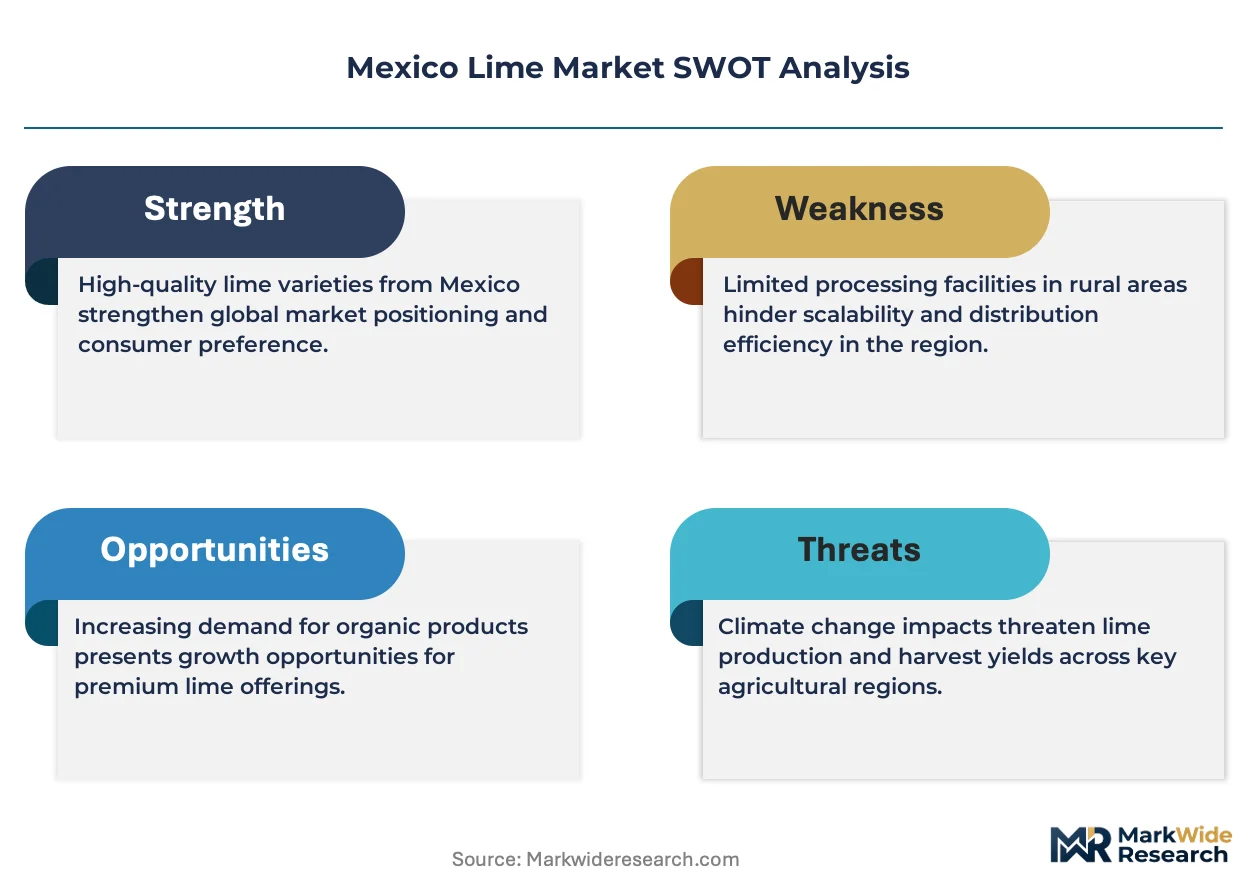
SADER's revised phytosanitary certification framework is rebalancing the cost-of-entry calculus for export-oriented growers. AVOSTACK S. de R.L. de C.V. leverages its vertically integrated cold-chain infrastructure to sustain year-round supply consistency into US retail channels. SiCar Farms anchors its competitive posture through direct control over Michoacán orchard acreage and proprietary grading protocols. Grupo Maipo differentiates via specialized organic certification streams that command premium positioning in domestic supermarket tiers.
Lime denotes the citrus fruit of species primarily Citrus latifolia (Persian lime) and Citrus aurantiifolia (Key lime), characterized by high citric acid content exceeding 5% by weight, green-to-yellow peel coloration at maturity, and juice vesicle structures optimized for extraction efficiency. The fruit serves commercial purposes spanning beverage acidulation, culinary flavoring, essential oil distillation, and industrial pectin recovery. Persian Lime occupies the dominant volume position due to seedless morphology and extended post-harvest durability, while Key Lime retains concentrated demand within authentic culinary applications and premium extract production. Pharmaceuticals emerges as the fastest-expanding end-user channel, driven by citric acid derivative demand in active pharmaceutical ingredient formulations and natural preservative systems.
COFEPRIS food additive standards, SADER export phytosanitary protocols, and NOM-001-FITO sanitary certification collectively govern product quality thresholds and cross-border market access for Mexican lime shipments. These frameworks elevate compliance investments for smaller orchard operators while creating structured pathways for certified producers to penetrate regulated import markets. Stakeholders must monitor evolving US FDA import alert classifications and bilateral agricultural inspection protocols to anticipate eligibility shifts before planting-cycle commitments lock in varietal and volume decisions.
Market Dynamics
SADER's updated phytosanitary certification framework is compressing export eligibility timelines while concentrating supply authority among operators with captive cold-chain infrastructure. Michoacán's irrigation districts now function as the primary volume gatekeeper for US-bound Persian lime shipments.
Growth Catalysts
- Pharmaceutical citric acid demand:Active pharmaceutical ingredient manufacturers source Mexican lime derivatives for natural preservative systems and excipient formulations. COFEPRIS food additive standards validate extract purity for cross-border ingredient trade.
- Controlled-environment orchard expansion:Michoacán growers deploy precision irrigation and climate-modulation infrastructure to extend harvest windows. Year-round production capability locks in retail shelf-space commitments from US grocery chains.
- Organic certification premium streams:SADER-accredited organic protocols enable domestic supermarket tiering. Certified producers capture price separation from conventional grade shipments through specialized handling and documentation workflows.
Market Restraints
- Input cost volatility:Fertilizer and agricultural diesel pricing swings compress margin predictability for open-field operators without forward-contract hedging.
- Supply concentration risk:Michoacán's dominance in irrigation-district volume creates single-point vulnerability to regional drought or pest pressure events.
- Regulatory friction:NOM-001-FITO sanitary certification timelines and documentation burdens delay market access for smaller orchard operators lacking dedicated compliance staff.
Strategic Opportunities
- Underpenetrated northern states:Sonora and Sinaloa offer expansion acreage with established water rights and proximity to California border crossings. Infrastructure investment here diversifies geographic risk from Michoacán concentration.
- Essential oil distillation vertical:Cold-pressed peel oil extraction for fragrance and flavor compounds represents higher-value outlet for grade-B fruit rejected from fresh export channels.
- Direct-to-retail channel innovation:Bypassing traditional wholesale produce auctions through dedicated importer relationships captures margin otherwise absorbed by intermediary handlers.
Industry Challenges
- Agricultural engineering talent scarcity:Controlled-environment horticulture and precision irrigation system management require specialized skill sets scarce in traditional citrus-growing regions.
- Cold-chain capex intensity:Export-grade post-harvest handling demands forced-air cooling, hydrocooler infrastructure, and refrigerated transport fleet investment that locks capital for multi-year depreciation cycles.
- Phytosanitary compliance timeline compression:SADER inspection scheduling bottlenecks and documentation revision cycles delay shipment releases during peak harvest windows when perishability pressure is highest.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Lime Market |
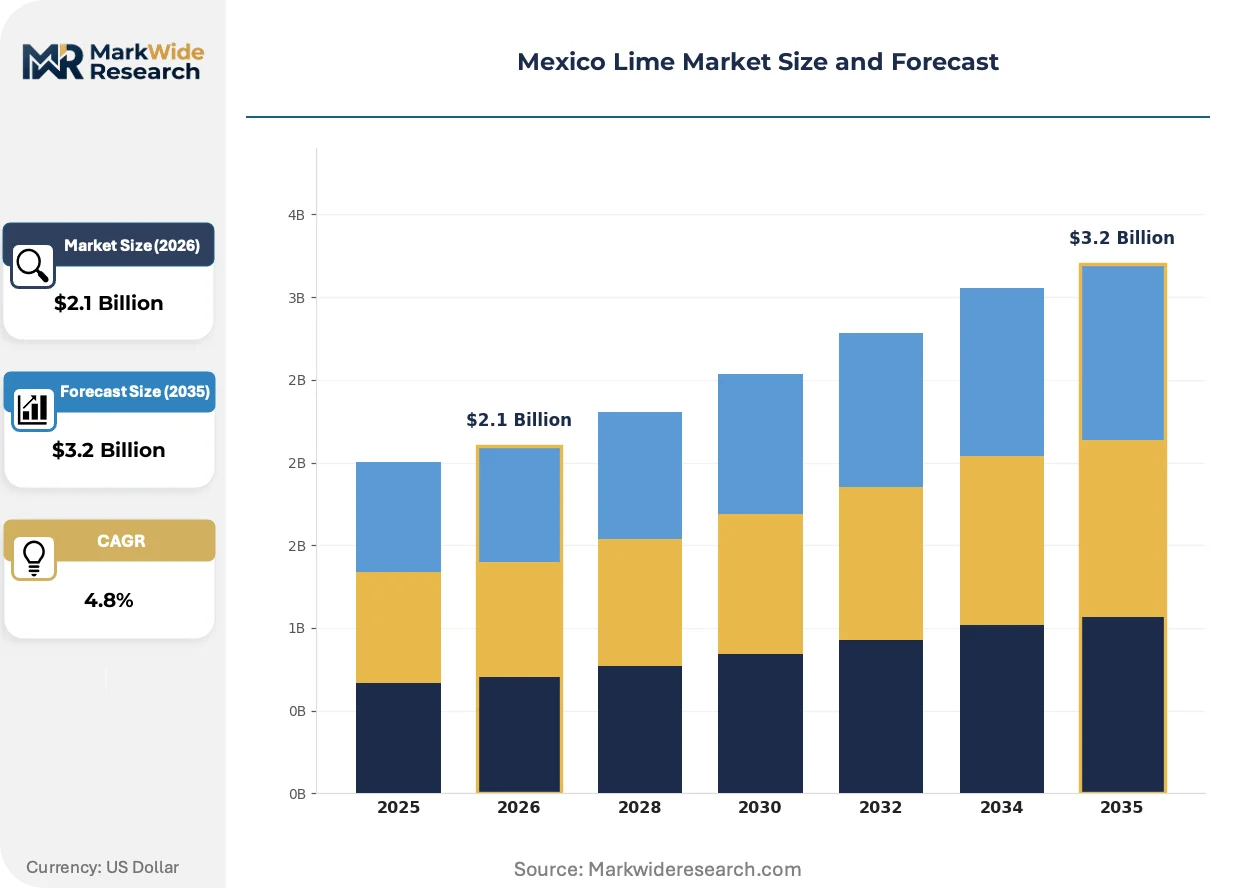
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.2 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Persian Lime, Key Lime, Finger Lime, Desert Lime End User: Food and Beverage, Cosmetics, Pharmaceuticals, Agriculture Distribution Channel: Online Retail, Supermarkets, Farmers Markets, Wholesalers Packaging Type: Bags, Boxes, Bulk, Bottles |
| Companies Covered | AVOSTACK S. de R.L. de C.V., CEMEX SAB de CV, SiCar Farms, Cheney Lime and Cement Co., Graymont Ltd., Limoneira, Grupo Maipo, Boral Ltd., Agroindustrias Peimbert S.A. de C.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Lime Market Strategic Shifts
Automation in grading and sorting infrastructure is compressing labor dependency while raising packout consistency standards. Regulatory digitization and blockchain traceability mandates are reshaping documentation workflows across the export supply chain.
Machine-vision sorting systems with multispectral imaging capability are consolidating quality control authority at packhouse level. US retail buyers now mandate defect-rate thresholds that manual inspection cannot reliably achieve. This technology is consolidating procurement power toward operators with capital reserves for infrastructure retrofitting.
SADER's phased implementation of electronic phytosanitary certification (e-Fito) is eliminating paper-based inspection documentation. Real-time traceability data submission accelerates border clearance protocols. Smallholder cooperatives face digitization investment requirements to maintain US market eligibility under evolving bilateral agricultural inspection frameworks.
Food and beverage processors now contract directly with integrated orchard-packer operations, bypassing traditional wholesale produce terminals. Long-term volume commitments with quality specifications replace spot-market purchasing for acidulation and natural flavoring inputs. This pattern concentrates most visibly in Texas and California processing facilities serving beverage manufacturing clusters.
Mexico Lime Market Segmentation
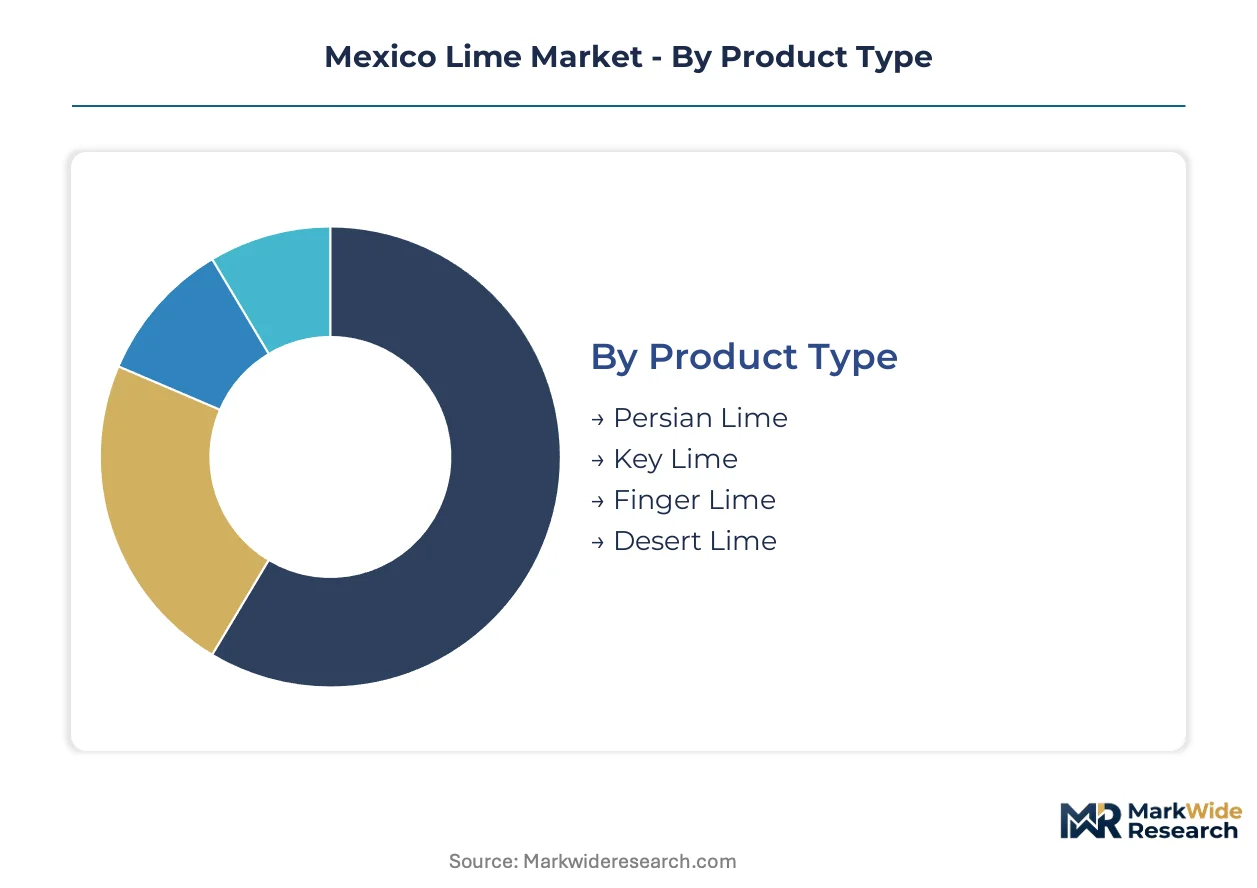
Mexico's lime segmentation reflects divergent buyer priorities across export-grade freshness requirements, pharmaceutical extract purity standards, and retail channel packaging specifications. Each dimension carries distinct margin implications and regulatory compliance burdens that reshape competitive positioning.
Product Type:
Buyers select varietals based on seed morphology, peel durability, and acid concentration profiles that determine end-use suitability and shipping viability.
- Persian Lime:Seedless morphology and thick peel structure deliver extended post-harvest shelf life exceeding three weeks under refrigerated conditions. Michoacán irrigation districts concentrate controlled-environment production for US retail chains demanding consistent year-round supply.
- Key Lime:Higher essential oil concentration in peel and distinctive aromatic profile command premium positioning in authentic culinary applications and cold-pressed extract production. Authentic Mexican cuisine processors in Texas and California maintain contracted volumes despite smaller fruit size and thinner peel vulnerability.
- Finger Lime:Caviar-like vesicle structure serves high-end gastronomy and specialty cocktail segments with unique textural applications.
- Desert Lime:Drought-tolerant genetics attract Sonora and Sinaloa growers seeking water-efficient acreage expansion with established border-crossing proximity.
Persian Lime leads on scale; Desert Lime leads on momentum through northern state expansion.
End User:
Application-specific purity thresholds and volume contracting patterns separate price-realization tiers across downstream industries.
- Food and Beverage:Natural acidulation demand from beverage manufacturers and preservative-free positioning in processed foods drive bulk contracting. Texas and California processing facilities now bypass wholesale terminals for direct orchard-packer relationships with quality specifications.
- Pharmaceuticals:Citric acid derivatives for active pharmaceutical ingredient formulations and natural preservative systems in excipient production expand most quickly. COFEPRIS food additive standards validate extract purity for cross-border ingredient trade.
- Cosmetics:Cold-pressed peel oil for fragrance compounds and natural antioxidant formulations in skincare products.
- Agriculture:Soil amendment applications and organic pesticide adjuvants utilizing lime-derived calcium compounds.
Food and Beverage dominates volume throughput; Pharmaceuticals climbs the fastest on derivative demand expansion.
Distribution Channel:
Channel selection determines margin capture versus intermediary absorption and cold-chain control authority.
- Supermarkets:Domestic retail tiering through SADER-accredited organic protocols enables price separation from conventional grade shipments. Grupo Maipo leverages specialized certification streams for premium positioning.
- Wholesalers:Traditional produce auction volumes face compression as integrated operators develop direct importer relationships.
- Online Retail:Direct-to-consumer fresh delivery and processed lime product e-commerce expanding through cold-chain logistics partnerships.
- Farmers Markets:Local consumption channels with minimal regulatory documentation burden for smallholder cooperatives.
Supermarkets concentrate procurement authority; Online Retail gains share fastest through logistics infrastructure maturation.
Packaging Type:
Packaging configuration aligns with channel requirements, perishability pressure, and buyer handling automation compatibility.
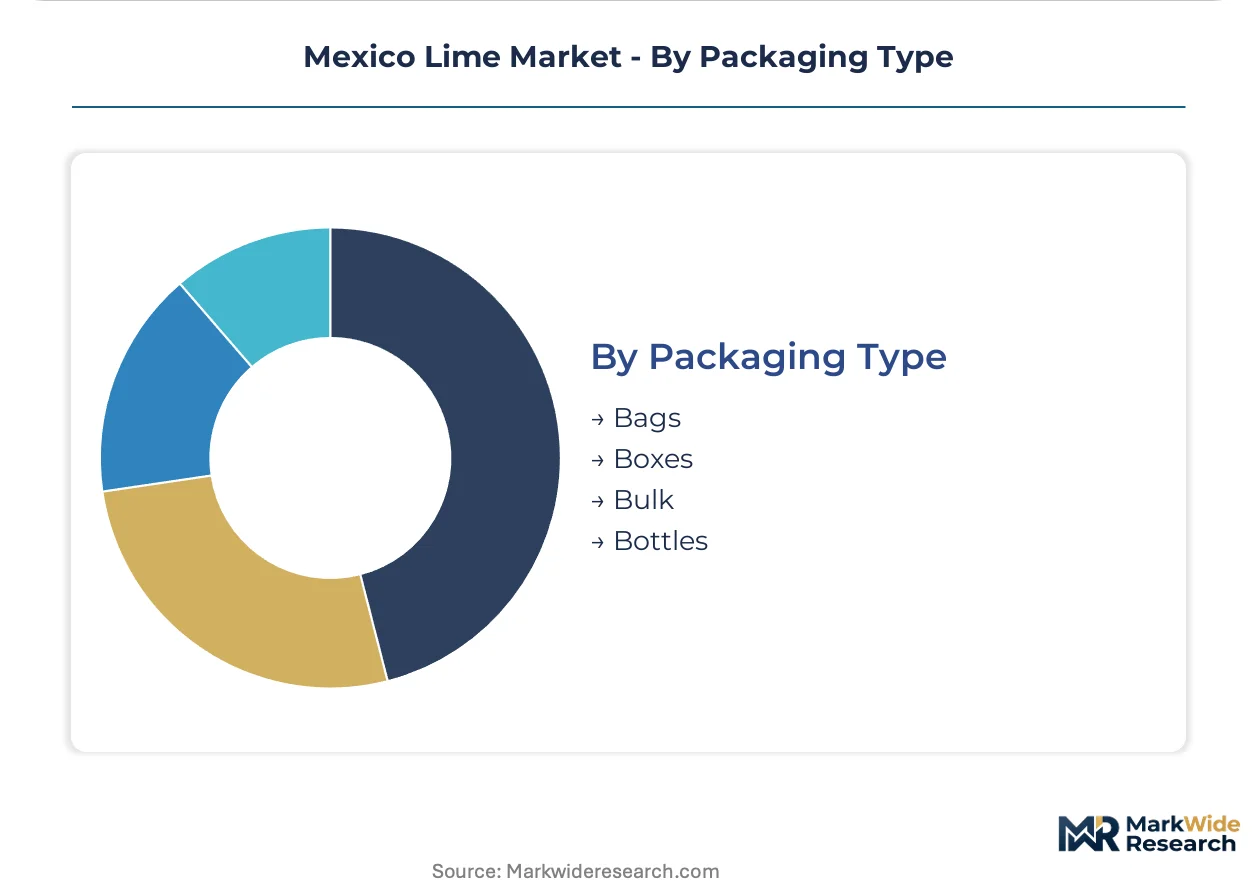
- Boxes:Standardized corrugated containers with ventilation apertures dominate export-grade shipments. Machine-vision sorting systems at packhouse level mandate uniform dimensions for automated handling.
- Bulk:Loose fruit loading for processing facilities with immediate juice extraction or oil distillation operations.
- Bags:Consumer-facing retail units with net weight standardization for supermarket shelf placement.
- Bottles:Processed lime juice and concentrate formats for food service and industrial acidulation applications.
Boxes anchor export infrastructure; Bottles expand most quickly through processed product demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Michoacán's agricultural engineering talent anchors Mexico's lime production capacity, concentrating controlled-environment horticulture expertise in the state's irrigation districts. This workforce concentration shapes national supply patterns and export eligibility frameworks.
Michoacán
Persian lime volumes for US retail chains concentrate in Michoacán's irrigation districts where precision irrigation infrastructure extends harvest windows. SADER's phytosanitary certification protocols govern export eligibility from this zone. Morelia and Uruapan anchor packhouse automation investments serving year-round supply contracts.
Jalisco
Key lime cultivation for authentic culinary applications and cold-pressed extract production clusters in Jalisco's coastal zones. The state's agricultural extension programs support organic certification transitions. Guadalajara-based processors maintain contracted volumes with Texas and California food manufacturers.
Sonora
Desert lime genetics and drought-tolerant varietals attract Sonora growers seeking water-efficient expansion with established California border-crossing proximity. The state's water rights frameworks enable predictable irrigation scheduling. Hermosillo and Ciudad Obregón host emerging packhouse infrastructure for alternative export routing.
Nuevo León
Pharmaceutical-grade citric acid derivative demand drives Nuevo León's processing facility investments near Monterrey's industrial corridor. COFEPRIS food additive standards compliance clusters here for cross-border ingredient trade. Apodaca and Santa Catarina house cold-pressed oil extraction operations for grade-B fruit outlets.
Veracruz
Traditional open-field Key lime production persists in Veracruz's tropical lowlands serving domestic acidulation and culinary markets. SADER-accredited organic protocols enable premium supermarket tiering in Mexico City distribution. Xalapa and Coatepec maintain heritage cultivation practices with minimal compliance documentation burdens.
Mexico Lime Market Competitive Environment
The competitive structure tilts toward vertically integrated orchard-packer operations with captive cold-chain infrastructure. Tiered capability distribution separates capital-intensive exporters from regional processors serving domestic channels. Three archetypes dominate: integrated operators with year-round supply consistency, specialized organic certifiers capturing premium positioning, and commodity processors optimizing grade-B fruit recovery. Competitive moves concentrate on direct-to-retail channel development and essential oil distillation verticals.
Within the integrated operator tier, AVOSTACK S. de R.L. de C.V. and SiCar Farms exemplify the capital-intensive archetype with Michoacán orchard control and US retail channel penetration. Grupo Maipo occupies a position among specialized organic certifiers leveraging SADER-accredited protocols for domestic supermarket premium tiering. Agroindustrias Peimbert S.A. de C.V. represents the regional processor segment with traditional open-field operations serving commodity acidulation demand.
| Leading Market Players |
|---|
| AVOSTACK S. de R.L. de C.V. |
| CEMEX SAB de CV |
| SiCar Farms |
| Cheney Lime and Cement Co. |
| Graymont Ltd. |
| Limoneira |
| Grupo Maipo |
| Boral Ltd. |
| Agroindustrias Peimbert S.A. de C.V. |
| Others |
Value Chain & Pricing Dynamics
US grocery chain procurement concentration anchors Mexico's lime pricing model around long-term volume contracts with embedded quality specifications. SADER's phytosanitary certification tiers create price separation between export-eligible and domestic-grade shipments, compressing spot-market liquidity for smaller orchard operators.
Pricing Analysis
Fresh export versus processed derivative sales split pricing into unbundled commodity spot and bundled contract-of-take structures. Three-tier pricing structure across organic-certified, conventional export-grade, and domestic processing tiers separates SADER-accredited producers from open-field operators. Pricing pressure stems from fertilizer and agricultural diesel cost volatility squeezing margin predictability. Open-field operators in Veracruz exhibit highest price sensitivity due to limited forward-contract hedging capability, while integrated Michoacán packers with captive cold-chain infrastructure command lowest sensitivity through year-round supply commitments.
Supply Chain Analysis
Agricultural engineering talent scarcity in Michoacán's irrigation districts constrains controlled-environment orchard expansion timelines. Supply concentrates in Mexico's Michoacán and Jalisco states, with emerging Sonora acreage diversifying geographic risk. Raw material dependencies center on agricultural diesel, nitrogen-phosphorus fertilizer blends, and refrigerated transport fleet capacity. Single-point vulnerability to regional drought or pest pressure events in Michoacán irrigation districts constitutes the dominant structural risk. Distribution runs through vertically integrated orchard-packer operations with direct importer relationships, bypassing traditional wholesale produce terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's lime market functions as a regulatory compounder where SADER's electronic phytosanitary certification (e-Fito) implementation accelerates compliance investment requirements and consolidates procurement authority among digitized operators.
For Market Incumbents: Extend backward integration into essential oil distillation verticals to capture value from grade-B fruit rejected from fresh export channels. Deepen upstream control over Sonora and Sinaloa water rights to diversify geographic risk from Michoacán concentration. Machine-vision sorting infrastructure investment defends packhouse-level quality control authority against US retail buyer defect-rate mandates.
For New Entrants and Emerging Players: Blockchain-enabled traceability platforms offer a technology-first wedge into SADER's digitizing certification workflows. Underpenetrated northern states present the most penetrable geography given established California border-crossing proximity and water rights frameworks. Direct-to-retail channel innovation bypassing wholesale produce auctions captures margin otherwise absorbed by intermediary handlers.
For Investors and Strategic Acquirers: Food and beverage processors with acidulation demand are the most active acquirer in this space, seeking captive lime supply for natural preservative systems. Long-term viability hinges on operators with demonstrated COFEPRIS food additive standards compliance and cross-border ingredient trade validation. Monitor US FDA import alert classification shifts for early signals of eligibility compression affecting planting-cycle commitment decisions.
| Strategic Initiative | Industry Significance |
|---|---|
| Controlled-Environment Orchard Expansion | Michoacán precision irrigation infrastructure extends harvest windows for year-round retail contracts. |
| Organic Certification Investment | SADER-accredited protocols enable premium supermarket tiering with price separation from conventional grades. |
| Cold-Chain Infrastructure Buildout | Hydrocooler and forced-air cooling systems lock in export-grade post-harvest durability for US retail. |
| Essential Oil Distillation Vertical | Cold-pressed peel oil extraction creates higher-value outlet for grade-B fruit rejected from fresh channels. |
| Direct-to-Retail Channel Development | Bypassing wholesale produce auctions captures margin otherwise absorbed by intermediary handlers. |
Study Parameters
Direct dialogue with orchard operators, packhouse managers, SADER compliance officers, US produce buyers, and agricultural extension specialists grounded the qualitative foundation. Secondary validation drew from SADER phytosanitary certification records, COFEPRIS food additive standards documentation, USDA Agricultural Marketing Service trade data, and SEC filings of publicly traded agricultural operators. Bottom-up orchard acreage and yield estimates triangulated against top-down export volume data from Mexico's customs authority.
Segment-level value and volume trajectories across the projection horizon reflect modeled interactions between varietal mix, end-use demand shifts, and regulatory compliance cost burdens. Segmentation dimensions included product type, end user industry, distribution channel, and packaging format, with regional production cluster as an additional industry-specific dimension. CAGRs derived from regression analysis of historical export volume trends, adjusted for SADER protocol implementation timelines and US retail buyer consolidation patterns. Forecast inputs incorporated irrigation water availability projections and agricultural diesel price volatility assumptions.
The model holds under stable SADER-USDA bilateral inspection protocols; deviation in FDA import alert reclassifications or regional drought severity would shift volume and value trajectories. Practitioners should monitor e-Fito digitization rollout pace and northern state water rights adjudication for early signals of competitive position shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Rosehip Market
Fruits and Vegetables
Dried Blueberries Market
Fruits and Vegetables
North America Organic Fruits Market
Fruits and Vegetables
Qatar Fruits and Vegetables Market
Fruits and Vegetables
Dates Market
Fruits and Vegetables
Lemon Juice Concentrate Market
Fruits and Vegetables
Avocado-Based Products Market
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
US Fruit and Vegetables Market
Fruits and Vegetables
Vaccinium Myrtillus Market
Fruits and Vegetables
Dried Jujubes Market
Fruits and Vegetables
Water Chestnut Market
Fruits and Vegetables
Uruguay Fruits and Vegetables Market
Fruits and Vegetables
Freeze Dried Fruits and Vegetables Market
Fruits and Vegetables
Japan Frozen Fruit Puree Market