
 United Kingdom Berries Market | 2026-2036
United Kingdom Berries Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Berries Market Analytics
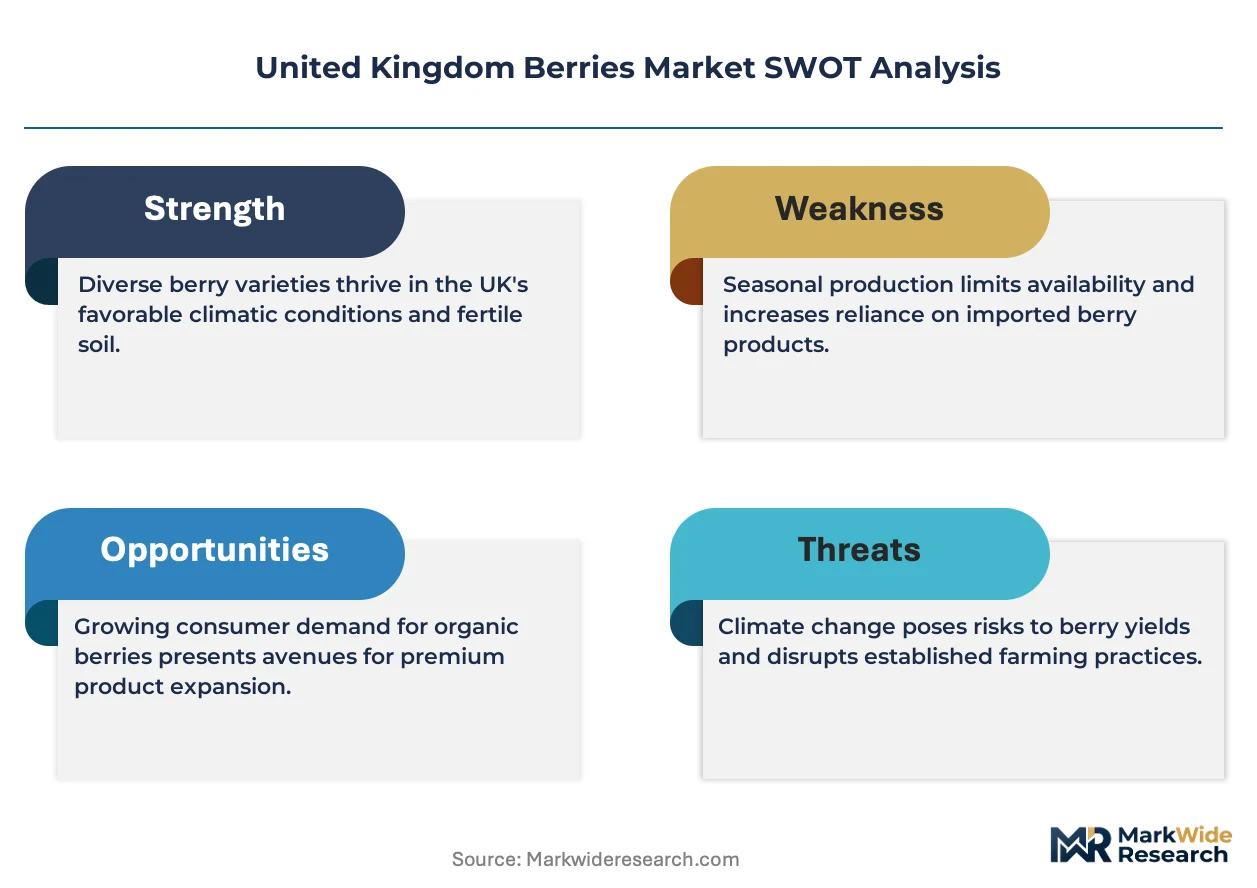
The price gap between premium glasshouse strawberries and field-grown commodity berries is hardening as input costs diverge. Driscoll's leverages its proprietary variety portfolio to command shelf price premiums in British supermarkets. A C Goatham and Son anchors Kent's protected cropping infrastructure with year-round supply capability. Berry Gardens competes through cooperative scale, pooling output from dozens of member growers to secure consistent retail listings.
United Kingdom berries comprise soft fruits cultivated across temperate growing regions, primarily under polytunnels, glasshouses, and open-field systems with harvest windows varying by cultivar and protected structure type. The commercial purpose centers on supplying fresh, frozen, and minimally processed fruit to retail, foodservice, and ingredient channels with shelf life and flavor consistency as critical quality parameters. Strawberries dominate volume throughput in British berry supply chains, while blueberries represent the fastest-expanding product type as plantings mature and consumer familiarity deepens. Punnets remain the standard retail packaging format, though vacuum packs are gaining traction in premium convenience positioning.
DEFRA's Agricultural Transition Plan and the Horticultural Trades Association's stewardship codes shape cultivation standards and environmental compliance obligations for British berry growers. The Food Standards Agency enforces residue limits and traceability requirements that filter directly into farm-level spray programs and record-keeping intensity. Stakeholders must monitor how evolving water abstraction permits and seasonal labor mobility frameworks reshape production cost structures and harvest security across the United Kingdom berry sector.
Market Dynamics
DEFRA's Agricultural Transition Plan is redirecting capital flows across British berry operations, forcing growers to reconfigure spray programs, water abstraction permits, and labor recruitment channels while supermarket procurement tightens residue and traceability specifications.
Growth Catalysts
- Seasonal Extension Technology:Advanced polytunnel cladding and supplementary LED lighting stretch Kent strawberry harvest windows from eight to eleven months, locking in year-round retail listings.
- Foodservice Channel Expansion:British restaurants and cafes are expanding fresh berry placement in breakfast and dessert menus, pulling volume through wholesale distribution networks previously dominated by frozen imports.
- DEFRA Sustainable Farming Incentive:Direct payments for cover cropping and integrated pest management are offsetting grower transition costs toward reduced-chemical cultivation protocols.
Market Restraints
- Seasonal Labor Mobility Constraints:Post-Brexit visa restrictions and rising recruitment costs from Romania and Bulgaria are compressing harvest windows and forcing wage inflation.
- Water Abstraction Permit Tightening:Environment Agency restrictions on borehole extraction in Sussex and Kent are capping expansion potential for protected strawberry operations.
- Energy Input Volatility:Glasshouse heating costs tied to natural gas pricing are widening the cost gap between field-grown and premium protected berries beyond what retail premiums can absorb.
Strategic Opportunities
- Scottish Protected Cropping Expansion:Aberdeenshire and Perthshire offer underdeveloped polytunnel capacity with cooler summers suited to raspberry and blueberry cultivars outside peak English harvest pressure.
- Controlled Environment Agriculture Convergence:Integration of hydroponic substrate systems with AI-driven climate control is opening vertical farm applications for strawberry propagation and early-stage forcing.
- Short-Channel Direct Distribution:Farm shop networks and subscription box operators are capturing margin previously allocated to supermarket listing fees and wholesale markups.
Industry Challenges
- Integrated Pest Management Skill Gaps:Growers struggle to recruit agronomists trained in biological control agent deployment and pheromone-based monitoring systems required under reduced-chemical protocols.
- Traceability System Integration:Supermarket mandates for blockchain-enabled batch tracking are forcing small-scale cooperative members to upgrade legacy record-keeping infrastructure without proportional volume returns.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Berries Market |
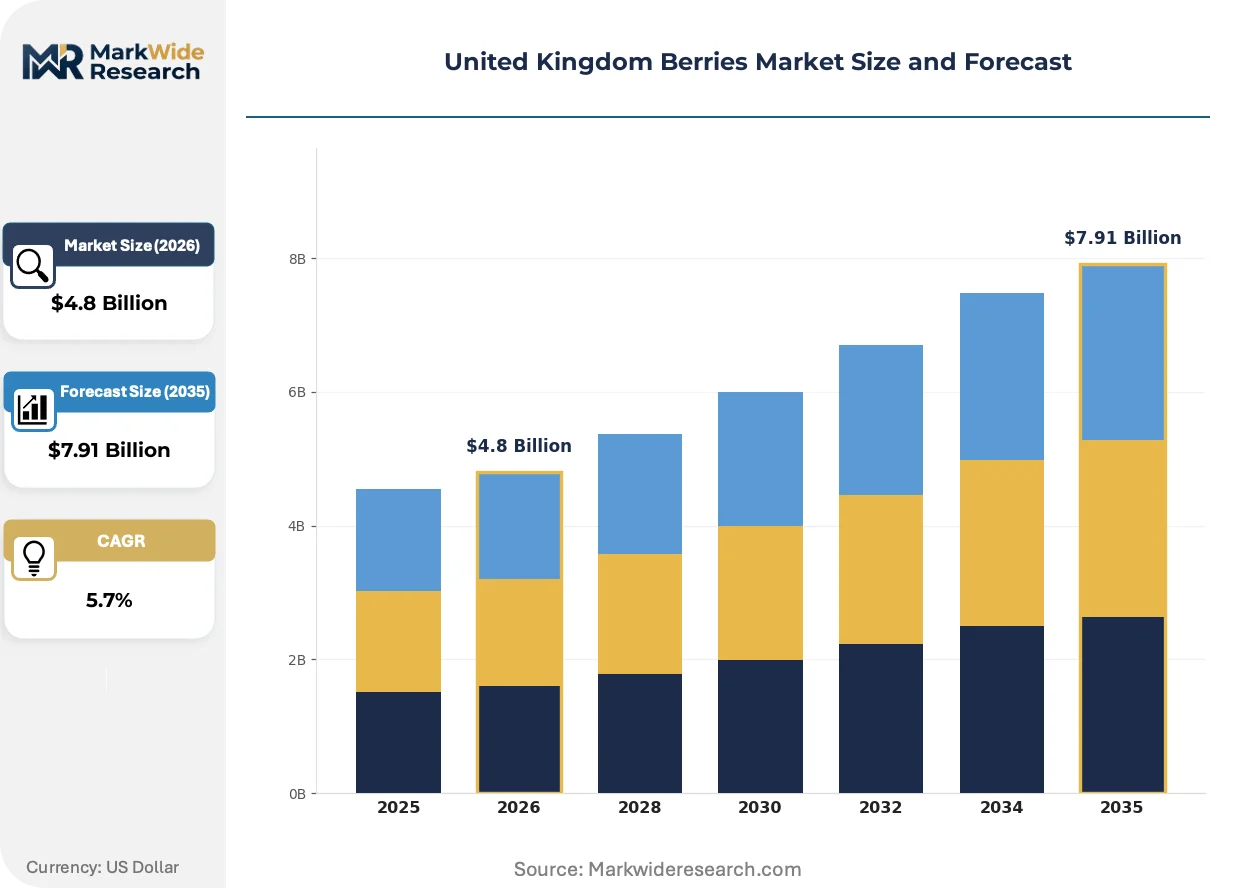
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Strawberries, Raspberries, Blueberries, Blackberries Packaging Type: Plastic Containers, Punnets, Vacuum Packs, Bulk Packaging Distribution Channel: Supermarkets, Farmers' Markets, Online Retail, Foodservice Consumer Segment: Health Conscious, Families, Food Enthusiasts, Chefs |
| Companies Covered | Driscoll’s, A C Goatham and Son, Haygrove, Berry Gardens, Hugh Lowe Farms, WB Chambers, Cobrey Farms, Withers Farm, Emery Soft Fruits, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Berries Market Evolving Landscape
Automation and environmental control technologies are compressing the traditional geography of British berry production, while regulatory compliance requirements reshape competitive access to retail channels and water resources.
Robotic harvesting systems utilizing computer vision and soft-grip end-effectors are decentralizing labor dependency across Kent and Sussex strawberry operations. Large-scale glasshouse operators are piloting these units for overnight picking cycles, reducing per-kilogram harvest costs and compressing the wage inflation pressure that has constrained field-grown competitor margins.
DEFRA's evolving water abstraction framework is tightening extraction permits for borehole-dependent operations in the South East. Growers in Kent are responding with closed-loop irrigation and rainwater harvesting infrastructure, while those unable to secure permit renewals are shifting expansion plans toward Scottish regions with less groundwater stress.
Subscription-based direct-to-consumer models are displacing traditional wholesale distribution for premium cultivar berries. Channel disintermediation is most visible in the South East, where Kent growers with established brand recognition are capturing retail-equivalent prices through weekly box schemes, bypassing supermarket listing fee structures and quality downgrades at packhouse grading lines.
United Kingdom Berries Market Segmentation
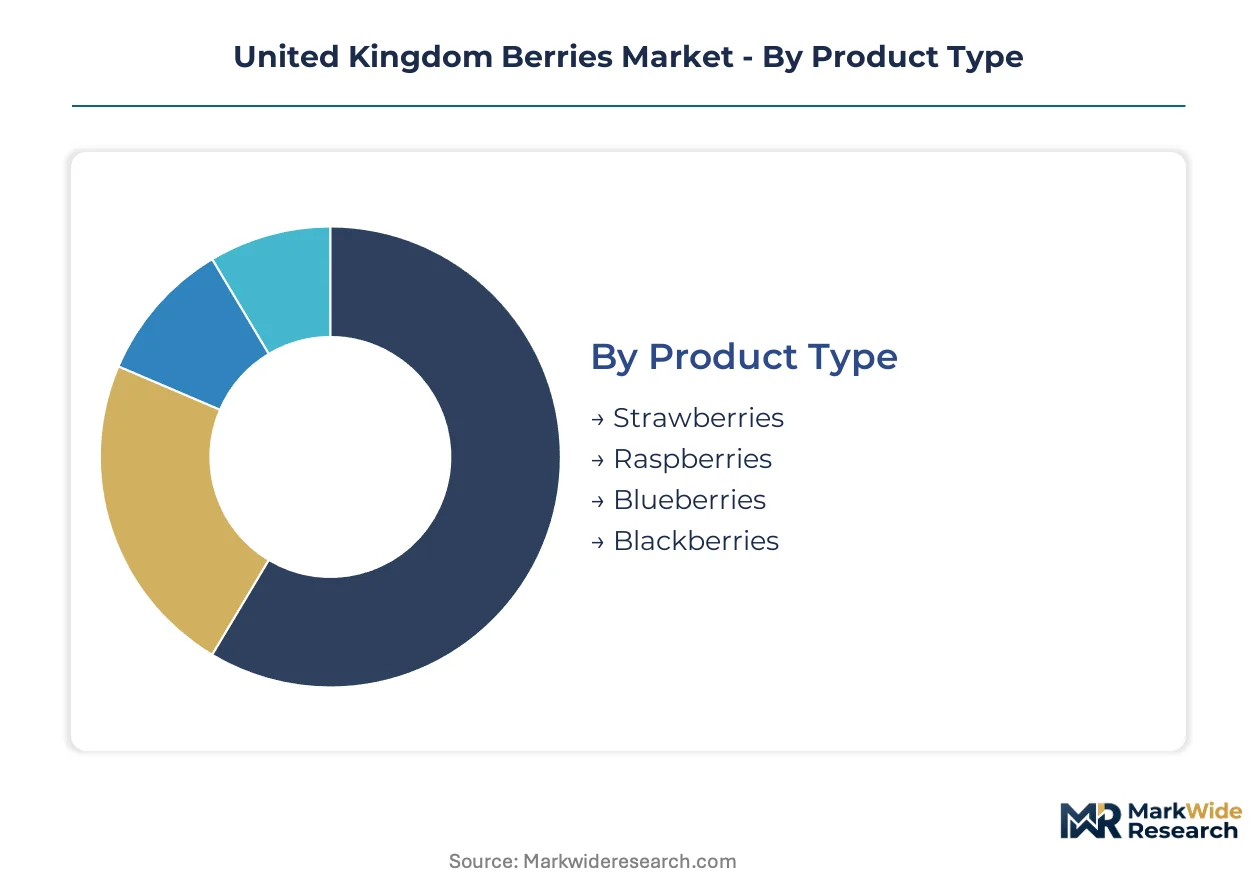
United Kingdom berry supply chains fragment across cultivation methods, packaging formats, and channel strategies that reshape margin capture and shelf-life performance. Growers and packers must align varietal selection and post-harvest handling with distinct buyer expectations across retail, foodservice, and direct channels.
Product Type:
Buyer differentiation in this category hinges on harvest window flexibility and perishability tolerance in distribution networks.
- Strawberries:Polytunnel and glasshouse cultivation dominates protected cropping acreage in Kent and Sussex, with year-round supply capability commanding premium shelf positioning in Tesco and Sainsbury's. Volume concentrates in the South East where Berry Gardens and A C Goatham anchor supply security for major retailers.
- Blueberries:Mature plantings in eastern England and expanding Scottish acreage are displacing Peruvian and Chilean imports during domestic windows. Demand from health-conscious consumers drives fastest category expansion as familiarity deepens beyond traditional berry repertoires.
- Raspberries:Shorter shelf life and higher bruising susceptibility limit distribution radius, concentrating supply in premium punnets for immediate consumption.
- Blackberries:Wild-foraged and cultivated volumes serve niche processing and fresh dessert applications with limited scale relative to core berry types.
Volume sits with strawberries; growth tilts toward blueberries.
Packaging Type:
Margin differentiation in this category tracks packaging automation investment and retail listing fee structures.
- Punnets:Standardized 400g and 227g formats dominate supermarket shelf space with automated tray-sealing lines enabling high-throughput packhouse operations. Cost efficiency at scale locks in listing security for Berry Gardens cooperative members supplying Asda and Morrisons.
- Vacuum Packs:Modified atmosphere packaging extends shelf life for convenience-oriented retail and foodservice channels, capturing premium positioning in M&S and Waitrose prepared fruit sections.
- Plastic Containers:Rigid clamshell formats serve bulk retail and foodservice wholesale with stackability advantages in distribution logistics.
- Bulk Packaging:5kg and 10kg totes supply ingredient manufacturers and institutional foodservice with minimal handling overhead.
Cost leadership concentrates in punnets; premium expansion favors vacuum packs.
Distribution Channel:
Channel selection in this category determines traceability burden and payment term exposure for growers.
- Supermarkets:Centralized procurement through Tesco, Sainsbury's, Asda and Morrisons demands full Red Tractor assurance and blockchain-enabled batch tracking. DEFRA residue protocols filter directly into spray program specifications for listed suppliers.
- Foodservice:Restaurant and cafe demand for seasonal British fruit is expanding through Bidfood and Brakes distribution networks, pulling volume from frozen import dependence.
- Online Retail:Ocado and Amazon Fresh slots require shelf-life guarantees that favor protected-cropping supply with predictable harvest scheduling.
- Farmers' Markets:Direct producer sales capture full retail margin in Kent and Sussex with minimal traceability overhead, constrained by scale and seasonality.
Procurement volume centralizes in supermarkets; margin expansion shifts toward foodservice.
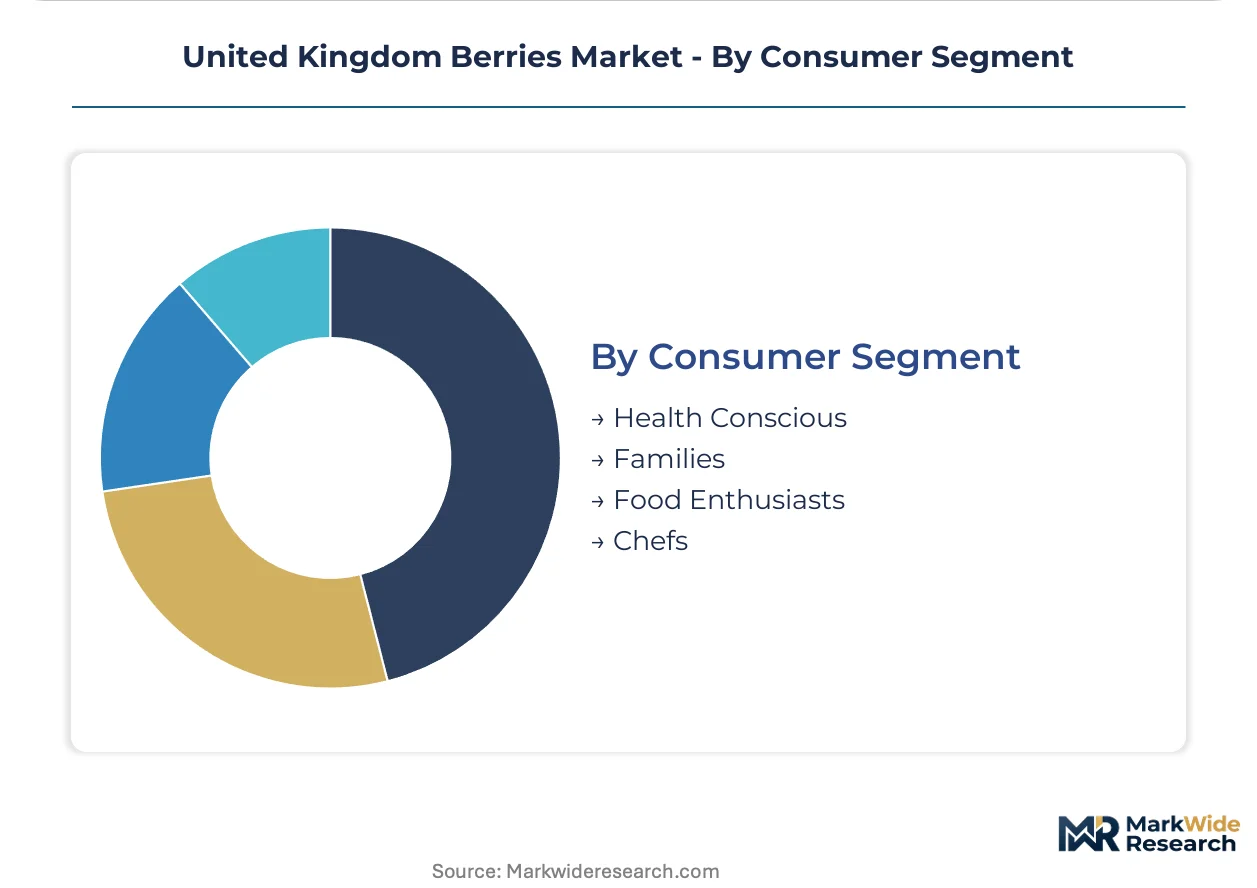
Consumer Segment:
Targeting precision in this category depends on usage occasion and willingness to pay for provenance verification.
- Health Conscious:Antioxidant messaging and low-glycemic positioning drive blueberry and blackberry preference, with organic and pesticide-free certifications commanding price premiums in Waitrose and Whole Foods.
- Families:Value-focused strawberry purchasing concentrates in multibuy promotions and seasonal price campaigns at Aldi and Lidl, with punnets as default format.
- Food Enthusiasts:Heritage varietal interest and seasonal provenance drive farmers' market and subscription box participation, bypassing standard retail grading.
- Chefs:Consistent sizing and flavor intensity requirements favor glasshouse strawberry supply with year-round availability for menu stability.
Transaction volume concentrates in families; value per kilogram peaks with health conscious buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kent anchors United Kingdom berry production through its dense concentration of polytunnel and glasshouse operations stretching from the Medway Valley to the East Kent coast.
South East England
Fresh strawberry and raspberry demand from London's retail and foodservice channels drives intensive protected cropping investment across Kent and Sussex. DEFRA's Sustainable Farming Incentive directs grower capital toward cover cropping and integrated pest management infrastructure. The Lea Valley glasshouse cluster and Thanet Earth complex host year-round production facilities supplying Tesco and Sainsbury's with premium-tier berries.
Scotland
Expanding blueberry and raspberry plantings in Aberdeenshire and Perthshire capitalize on cooler summer temperatures and extended daylight hours during peak harvest. Scottish Government Rural Payments and the Agri-Environment Climate Scheme subsidize polytunnel installation for season extension. The Tay Valley corridor attracts protected cropping investment from English growers facing water abstraction constraints.
East of England
Large-scale blueberry maturation in Norfolk and Suffolk displaces import volumes during August-October windows. Environment Agency water resource management plans restrict new borehole permits in the Fens, pushing growers toward reservoir-based irrigation systems. The Norfolk fruit belt connects through Berry Gardens cooperative infrastructure to central distribution networks.
West Midlands
Historic strawberry field production around the Evesham Vale transitions toward mixed protected cropping and agritourism direct sales. Natural England's Countryside Stewardship schemes fund hedgerow restoration and pollinator habitat creation on farm perimeters. The Vale of Evesham retains significance for heritage varietal preservation and farmers' market distribution channels.
United Kingdom Berries Market Competitive Landscape
Premium-margin players sit above commodity-margin players across protected cropping infrastructure and proprietary variety access. The United Kingdom berry sector exhibits tiered consolidation with cooperative-scale operations pooling output against vertically integrated specialists controlling year-round supply security. Three archetypes dominate: proprietary genetics licensors, cooperative aggregators, and integrated estate growers. Competitive intensity concentrates on seasonal extension capability and direct retail relationship depth rather than price alone.
Within the proprietary genetics tier, Driscoll's exemplifies variety-led premium positioning through controlled cultivar distribution. A C Goatham and Son anchors Kent's protected cropping infrastructure as an integrated estate operation. Berry Gardens represents cooperative-scale aggregation, pooling output from member growers to secure consistent supermarket listings. These three patterns illustrate how margin capture diverges across intellectual property control, asset intensity, and collective bargaining structures.
| Leading Market Players |
|---|
| Driscoll's |
| A C Goatham and Son |
| Haygrove |
| Berry Gardens |
| Hugh Lowe Farms |
| WB Chambers |
| Cobrey Farms |
| Withers Farm |
| Emery Soft Fruits |
| Others |
Value Network & Pricing Analysis
Seasonal harvest labor concentration in Kent and Sussex drives wage-cost differentials that widen spreads between premium glasshouse strawberries and field-grown commodity tiers.
Pricing Analysis
Yield-per-square-meter anchoring governs British berry pricing, with glasshouse operators commanding premiums based on predictable throughput and extended harvest windows. Three-tier pricing structure across premium, standard, and economy levels separates Driscoll's proprietary cultivars from cooperative-supplied punnets and imported frozen alternatives. Cost compression in field-grown tiers is intensifying because Romanian and Bulgarian recruitment costs have risen post-Brexit. Families purchasing multibuys at Aldi and Lidl exhibit highest price sensitivity; chefs sourcing for menu stability show lowest.
Supply Chain Analysis
Dual-sourcing requirements from Tesco and Sainsbury's procurement teams mandate redundant packhouse qualification across Berry Gardens cooperative members and integrated estate operators. Supply concentrates in the United Kingdom, with seasonal windows drawing from Spanish and Moroccan imports during domestic off-peak months. Polytunnel cladding, supplementary LED systems, and peat-reduced substrate formulations constitute critical input dependencies. Single-source vulnerability sits with seasonal labor recruitment channels. Distribution runs through centralized supermarket distribution centers and wholesale networks serving Bidfood and Brakes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
United Kingdom berry production is consolidating toward scale operators with capital reserves to absorb DEFRA compliance costs and water permit investments that weaker players cannot fund.
For Market Incumbents: Hedge against labor cost volatility through robotic harvesting pilot programs in Kent glasshouse operations. Secure water abstraction permit renewals ahead of Environment Agency tightening. Diversify varietal portfolios beyond strawberries toward faster-growing blueberry segments to offset wage inflation pressure. For New Entrants and Emerging Players: Capture white-space in Scottish protected cropping expansion across Aberdeenshire and Perthshire, where cooler summers suit raspberry and blueberry cultivars and groundwater stress remains lower. Penetrate direct-to-consumer subscription channels with heritage varietal positioning that bypasses supermarket listing fees. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated estate growers given DEFRA's Sustainable Farming Incentive redirecting capital toward environmentally responsible infrastructure. Long-term viability favors operators controlling year-round supply capability through glasshouse and advanced polytunnel assets. Watch Environment Agency water permit decisions as the inflection signal for expansion-constrained versus expansion-enabled production footprints.| Strategic Initiative | Industry Significance |
|---|---|
| Robotic Harvesting Deployment | Kent operators reduce per-kilogram labor costs through computer vision and soft-grip end-effector systems. |
| Scottish Polytunnel Expansion | Aberdeenshire and Perthshire development captures cooler summer advantages and less groundwater stress. |
| Direct-to-Consumer Channel Buildout | Subscription box operators capture margin previously allocated to supermarket listing fees and wholesale markups. |
| Integrated Pest Management Certification | DEFRA incentive payments offset transition costs toward reduced-chemical cultivation protocols. |
| Closed-Loop Irrigation Investment | Rainwater harvesting infrastructure responds to Environment Agency borehole extraction restrictions. |
Research Methodology
DEFRA agricultural statistics, Environment Agency water resource management plans, and Horticultural Trades Association production surveys formed the secondary backbone, cross-referenced against primary interviews with Kent glasshouse operators, Berry Gardens cooperative agronomists, Tesco produce category buyers, and seasonal labor recruitment specialists. Bottom-up and top-down triangulation validated volume estimates across cultivation method, packaging format, and distribution channel segments.
Bottom-up modeling anchored forecasts in planted acreage by berry type and protected structure category, while top-down verification checked aggregate value against retail scanner data and foodservice procurement patterns. Modeled dimensions included product type, packaging format, distribution channel, and consumer segment across the analysis window. CAGRs derived from historical planting trends, maturity curves for blueberry expansion, and seasonal extension technology adoption rates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Environment Agency water permit allocations, post-Brexit seasonal labor mobility frameworks, and energy input volatility affecting glasshouse heating economics. Deviation in DEFRA's Agricultural Transition Plan payment schedules would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Frozen Fruits and Vegetables Market
Fruits and Vegetables
Europe Stone Fruits Market
Fruits and Vegetables
Europe Dried Mushroom Market
Fruits and Vegetables
Dried Apple Peel Market
Fruits and Vegetables
Global Avocado Market
Fruits and Vegetables
Sudachi Market
Fruits and Vegetables
Citrus Pulp Market
Fruits and Vegetables
Passion Fruit Extract Market
Fruits and Vegetables
Asia-Pacific Sweet Potatoes Market
Fruits and Vegetables
Europe Kiwi Fruit Market
Fruits and Vegetables
Sweet Cherry Powder Market
Fruits and Vegetables
Haskap Berry Powder Market
Fruits and Vegetables
Fruit Pulp Market
Fruits and Vegetables
Rubus Idaeus (Raspberry) Seed Oil Market
Fruits and Vegetables
Europe Blueberry Market
Fruits and Vegetables
Celery Juice Market