
 Global Fresh Cranberries Market | 2026-2036
Global Fresh Cranberries Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fresh Cranberries Market Analysis
Asset-light contract farming and cooperative pooling arrangements is rewriting capital requirements for new entrants in fresh cranberry cultivation. Ocean Spray Cranberries leverages its grower-owned cooperative structure to sustain year-round supply consistency across retail channels. Fruit d'Or anchors its competitive position through vertical control over Quebec bogs and processing facilities. Decas Cranberry Products specializes in organic certification tiers that command premium positioning in health-oriented distribution.
Fresh cranberries constitute Vaccinium macrocarpon fruit harvested at optimal color development for immediate consumption, processing, or controlled-atmosphere storage, with anthocyanin content exceeding 30 mg per 100 g serving driving nutritional value propositions. The primary commercial purpose centers on supplying food manufacturers, beverage formulators, and direct retail channels with a tart, shelf-stable fruit ingredient adaptable to sweetened and unsweetened applications. Whole berries dominate volume throughput due to processing flexibility across juice extraction, drying, and puree conversion, while dried cranberries capture disproportionate margin pools in snack and bakery ingredient channels. The food industry end-user segment leads absolute demand, though health stores represent the fastest-growing outlet as functional positioning of proanthocyanidin content expands consumer willingness to pay.
The FDA enforces Grade A standards under the Agricultural Marketing Service that dictate size, color, and defect tolerances for interstate fresh cranberry commerce, while USDA Organic certification creates a parallel compliance track for premium market access. EFSA pesticide maximum residue limits under EU Regulation 396/2005 directly shape import viability for North American growers shipping into European supermarkets. Stakeholders must monitor evolving MRL harmonization between FDA and EFSA frameworks, as divergence in glyphosate and insecticide thresholds will determine which sourcing regions retain cost-competitive access to dual-continent customers.
Market Dynamics
Cooperative pooling arrangements are compressing capital barriers for new entrants while tightening procurement leverage for established processors. The shift toward grower-owned supply structures is redistributing margin capture upstream from branded finished goods toward raw material control.
Growth Catalysts
- Functional beverage formulation:Anthocyanin-rich whole berry demand from antioxidant-focused drink manufacturers is pulling volume through Quebec and British Columbia processing clusters.
- EU Farm to Fork Strategy:EFSA pesticide residue threshold tightening for imported soft fruits is creating certified-supply premiums for compliant North American growers.
- Controlled-atmosphere storage:Extended shelf-life technology is enabling year-round retail availability without frozen concentrate dependency.
Market Restraints
- Bog-specific capital intensity:Sanding, flooding infrastructure, and vine establishment require decade-long payback periods that deter speculative investment.
- Quebec-British Columbia supply concentration:North American volume dependence on two provincial clusters creates weather and logistics vulnerability.
- Glyphosate MRL divergence:FDA and EFSA threshold misalignment forces dual compliance cost burdens on exporters serving both markets.
Strategic Opportunities
- Health store channel expansion:Proanthocyanidin functional positioning is opening premium shelf space beyond conventional grocery.
- USDA Organic tier penetration:Certified supply scarcity commands measurable price premiums in European and domestic natural retail.
- Dried cranberry ingredient conversion:Snack and bakery channels capture disproportionate margin pools versus commodity juice concentrate.
Industry Challenges
- Bog management expertise scarcity:Specialized horticultural knowledge for water table control and pest management is concentrating among aging grower cooperatives.
- Organic certification timeline compression:Three-year land conversion requirements delay revenue realization for conventional-to-organic transitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fresh Cranberries Market |
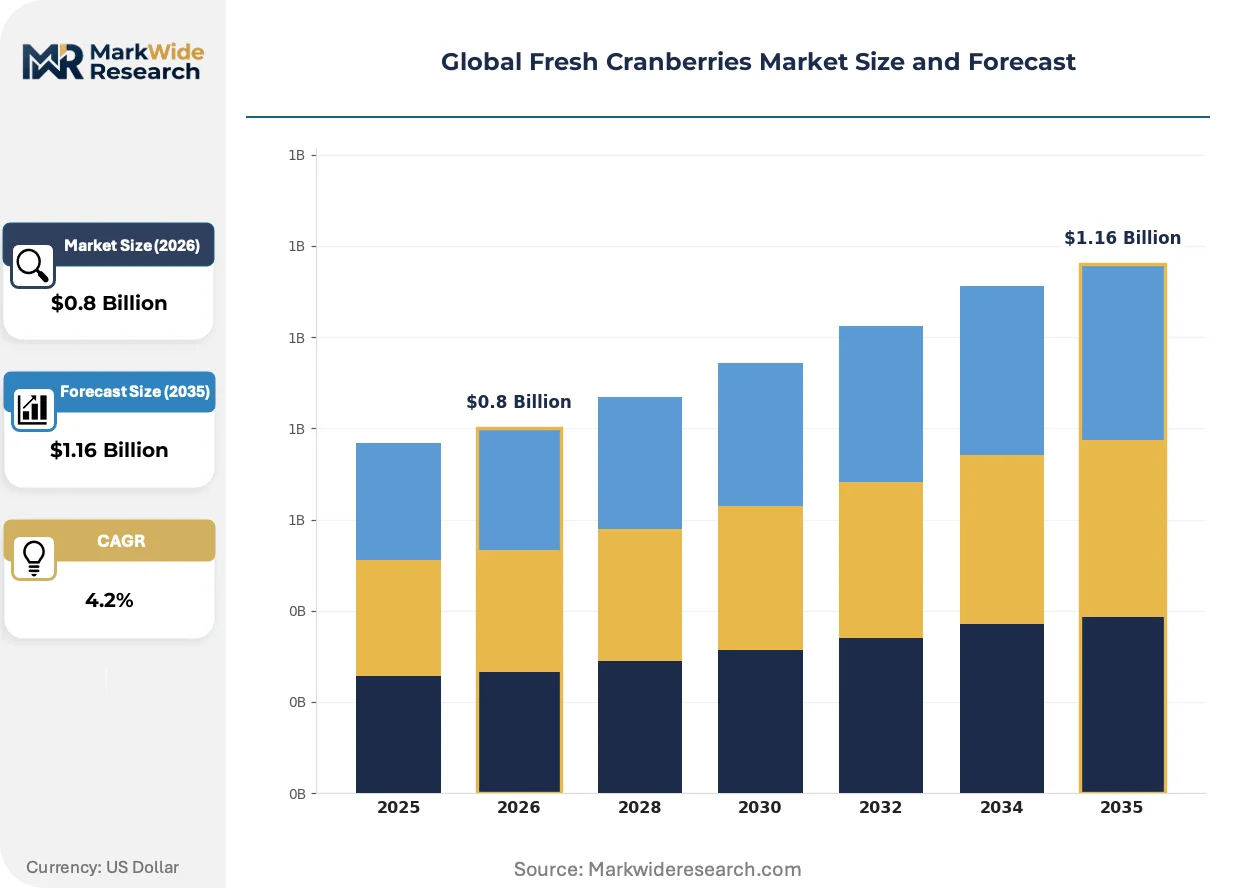
| Market Size in 2026 | $0.8 Billion |
| Market Size in 2035 | $1.16 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Berries, Dried Cranberries, Juice, Puree Packaging Type: Plastic Bags, Glass Jars, Frozen Packages, Cartons Distribution Channel: Supermarkets, Online Retail, Wholesalers, Farmers Markets End User: Food Industry, Beverage Manufacturers, Health Stores, Households |
| Companies Covered | Decas Cranberry Products, Atoka Cranberries, Ocean Spray Cranberries, Very Berry Company, Fruit d'Or, Wisconsin State Cranberry Growers Association, Cliffstar Corporation, Turkiye Cranberry Growers Association, Cranberries Canada, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fresh Cranberries Market Emerging Trajectories
Digital supply chain infrastructure is virtualizing traditional cooperative logistics. Remote sensing and predictive harvest modeling are compressing the information asymmetry that once defined processor-grower negotiations.
Hyperspectral imaging for berry quality assessment is virtualizing manual sorting and color-grading labor. Large cooperatives in Wisconsin and Massachusetts are deploying in-line spectroscopy at receiving stations. The technology is virtualizing grade disputes and accelerating payment cycles by embedding USDA Agricultural Marketing Service standards into automated acceptance protocols.
EU Regulation 396/2005 maximum residue limit harmonization efforts are forcing reformulation of crop protection protocols. North American exporters face testing cost inflation at Rotterdam and Hamburg entry points. Organic-certified supply chains are capturing preferential shelf placement as conventional lots face rejection risk from single-residue exceedances.
Direct procurement from grower cooperatives is displacing layered broker structures in retail and industrial buying. Large beverage formulators are establishing multi-year offtake agreements with Quebec pooling arrangements. This pattern is most visible in United States functional drink manufacturing, where traceability requirements and antioxidant potency guarantees favor captive supply relationships over spot market purchasing.
Global Fresh Cranberries Market Segmentation
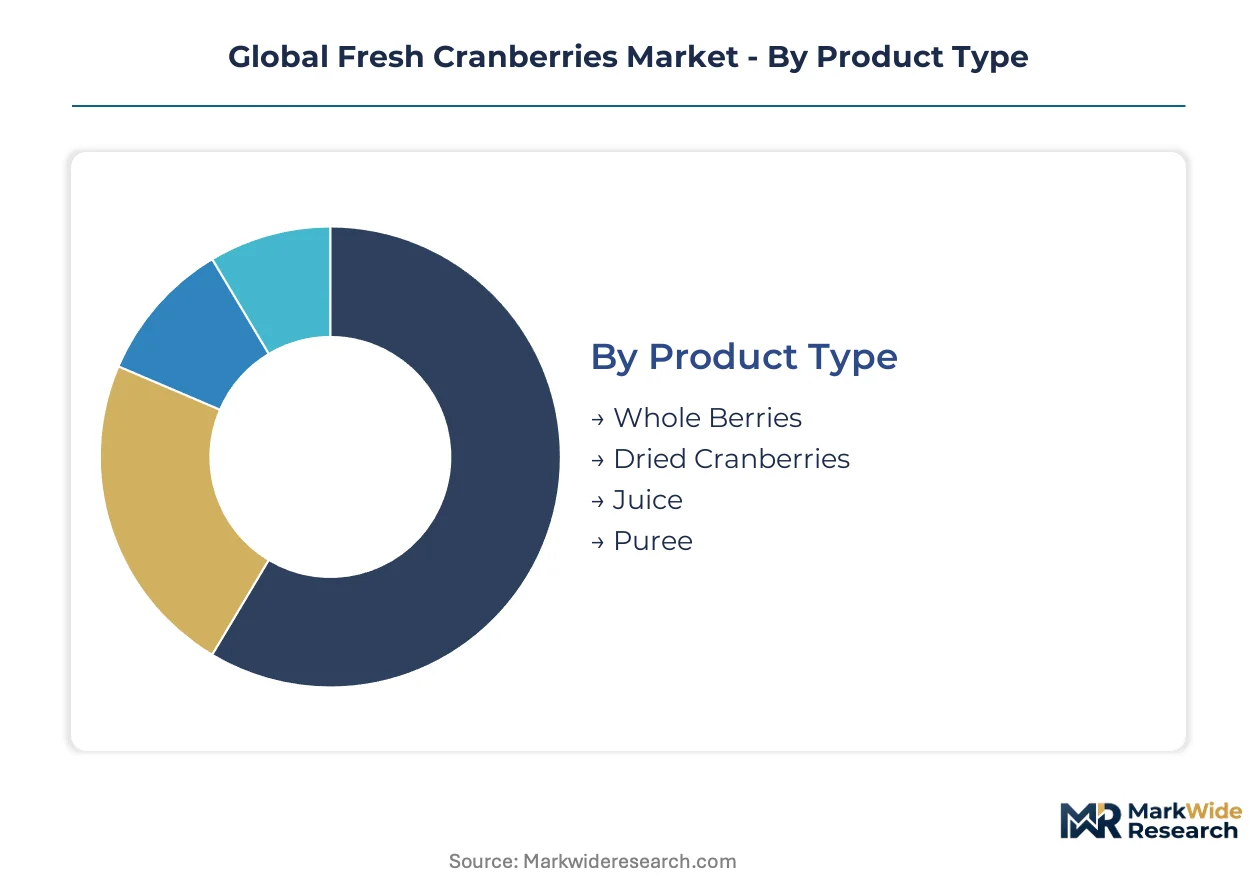
Fresh cranberry market segmentation reveals how processing flexibility, shelf-life requirements, and channel economics create divergent margin profiles across product formats. Understanding these structural divides illuminates where capital deployment yields the highest returns for growers and processors alike.
Product Type:
Whole berries turn inventory fastest during harvest windows while dried and juiced forms extend revenue recognition across calendar years.
- Whole Berries:Harvested Vaccinium macrocarpon fruit at optimal color development retains maximum anthocyanin potency above 30 mg per 100 g. Food manufacturers and beverage formulators in Canada and the United States pull volume through Quebec and British Columbia processing clusters for antioxidant-rich formulations. Whole berries anchor the volume base while dried cranberries gain share at the steepest rate.
- Dried Cranberries:Dehydrated fruit with moisture content reduced to 15-20% enables ambient distribution without cold chain dependency. Snack and bakery ingredient channels in the United States capture disproportionate margin pools versus commodity juice concentrate, with health stores representing the fastest-expanding outlet.
- Juice:Pressed liquid extract standardized for brix and acidity specifications serves beverage manufacturing at scale.
- Puree:Milled fruit pulp provides texture and tartness for sauce and smoothie applications.
Processing depth determines working capital intensity and margin capture potential across the value chain.
Packaging Type:
Packaging economics stratify by cold chain requirements, with ambient formats commanding distribution premiums in remote geographies.
- Plastic Bags:Polyethylene or polypropylene barrier films provide cost-efficient containment for bulk retail and foodservice channels. Supermarkets and wholesalers in Canada and the United States favor this format for price-sensitive household segments.
- Frozen Packages:Blast-frozen berries in laminated pouches preserve anthocyanin integrity for year-round industrial procurement. Beverage manufacturers and food industry buyers in the United States rely on frozen supply when fresh harvest windows close.
- Glass Jars:Premium positioning for gift and specialty retail with higher unit economics.
- Cartons:Paperboard-based containment for institutional and foodservice bulk delivery.
Plastic bags dominate unit volume while frozen packages capture the steepest expansion trajectory in industrial procurement channels.
Distribution Channel:
Channel selection determines traceability requirements and payment cycle length, with direct formats compressing days receivable.
- Supermarkets:Multi-banner retail chains in Canada and the United States drive mass-market penetration through seasonal promotional calendars. Controlled-atmosphere storage technology enables these retailers to stock fresh berries outside narrow harvest windows.
- Online Retail:Direct-to-consumer platforms bypass traditional broker structures, with large beverage formulators establishing multi-year offtake agreements with Quebec pooling arrangements to secure traceability guarantees.
- Wholesalers:Aggregated distribution to foodservice and secondary retail accounts.
- Farmers Markets:Localized direct sales with premium positioning for organic-certified supply.
Supermarkets anchor the volume base while online retail climbs the fastest as procurement digitization accelerates.
End User:
End-use concentration shapes specification stringency, with industrial buyers demanding certified antioxidant potency guarantees.
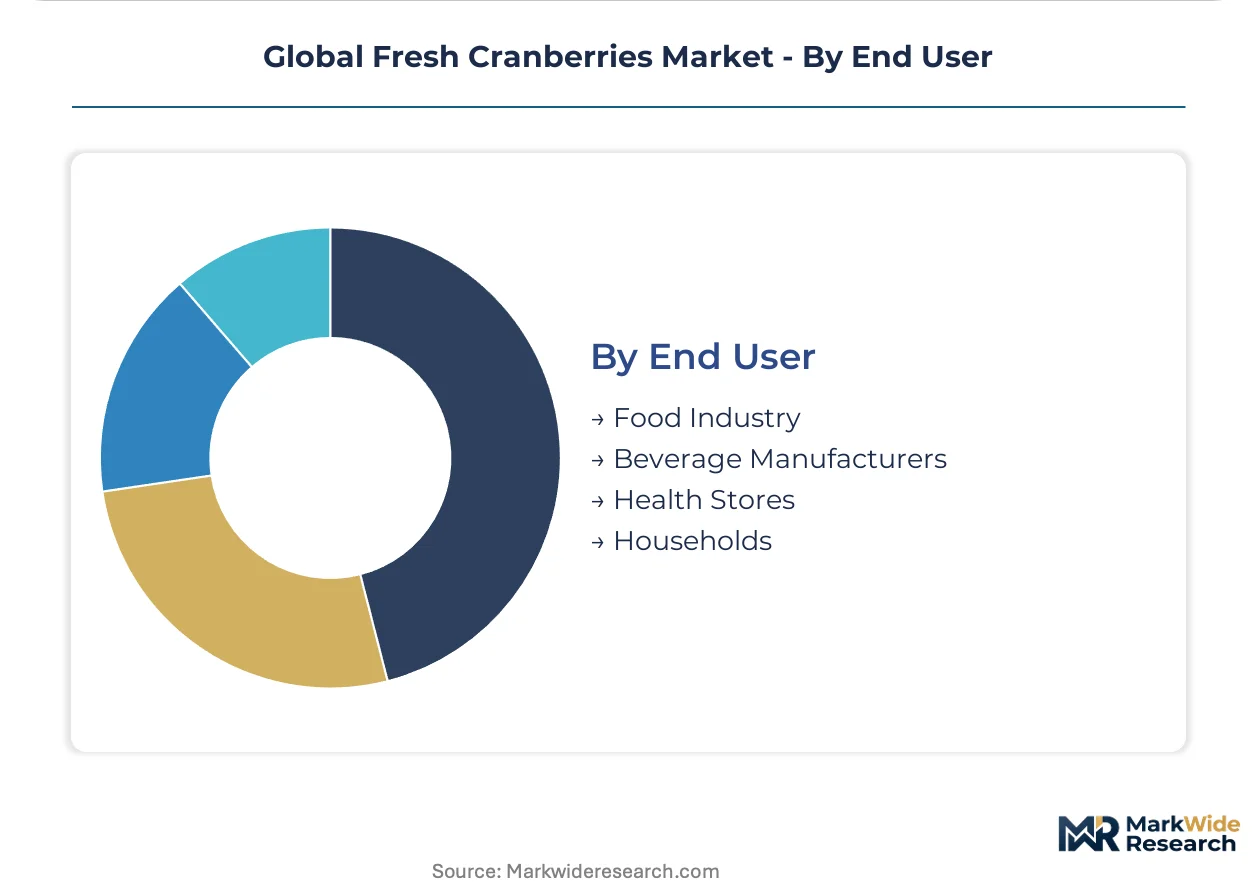
- Food Industry:Sauce, bakery, and confectionery manufacturers constitute the largest absolute demand segment by volume. Processors in Quebec supply North American retail and industrial buyers with tart, shelf-stable fruit ingredients adaptable to sweetened applications.
- Health Stores:Natural retail channels in the United States and European Union represent the fastest-expanding outlet as proanthocyanidin functional positioning expands consumer willingness to pay premium tiers.
- Beverage Manufacturers:Functional drink formulators requiring anthocyanin-rich whole berry inputs.
- Households:Direct consumption for seasonal cooking and fresh eating applications.
Food industry demand anchors the volume base while health stores expand most quickly on functional positioning premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's Farm to Fork Strategy alignment with EFSA guidelines is reshaping pesticide residue compliance costs for North American exporters. The United States leverages USDA Organic certification premiums to offset regulatory burden in cross-Atlantic trade.
United States
Functional beverage manufacturers in Massachusetts and Wisconsin pull anthocyanin-rich whole berries for antioxidant-focused formulations. FDA Grade A standards under the Agricultural Marketing Service dictate interstate commerce specifications for size and color tolerances. Wisconsin processing clusters supply retail and industrial buyers through controlled-atmosphere storage infrastructure that extends shelf-life beyond harvest windows.
Canada
Quebec and British Columbia bogs anchor North American volume concentration for fresh and processed cranberry supply. Health Canada and PMRA administer maximum residue limits that align with EFSA thresholds for European export eligibility. Montreal-area processing facilities coordinate cooperative pooling arrangements that compress capital barriers for new grower entrants.
Germany
EFSA pesticide residue enforcement at Rotterdam and Hamburg entry points is testing North American export compliance. The EU Green Deal and Farm to Fork Strategy drive tightening thresholds for glyphosate and insecticide residues in imported soft fruits. Hamburg distribution hubs channel compliant organic-certified supply into German supermarket and health store networks.
United Kingdom
Post-Brexit divergence from EU Regulation 396/2005 is creating dual testing requirements for North American exporters. The UK's national food standards regulator maintains parallel maximum residue limit frameworks with partial EFSA alignment. London-based import distributors are consolidating procurement relationships with Quebec cooperative arrangements to secure traceability guarantees.
Netherlands
Rotterdam port entry procedures enforce EFSA maximum residue limits with escalating testing cost inflation for non-compliant lots. The country's position as European distribution hub concentrates import volume from North American sourcing regions. Amsterdam-area health store chains are expanding shelf space for proanthocyanidin-positioned organic cranberry products.
Global Fresh Cranberries Market Vendor Landscape
Channel-controlling players compete with product-specialist players across cooperative, vertically integrated, and organic-certified archetypes. The structure concentrates around grower-owned pooling arrangements that redistribute margin capture upstream from branded finished goods. Three archetypes dominate: cooperative aggregators with year-round supply consistency, bog-owning processors with captive raw material control, and organic-certified specialists with premium positioning. Competitive moves center on multi-year offtake agreements with beverage formulators and hyperspectral imaging deployment for automated quality assessment.
Within the cooperative-aggregator archetype, Ocean Spray Cranberries exemplifies grower-owned structures that sustain retail channel penetration. Fruit d'Or occupies a position representing vertical control over Quebec cultivation and processing infrastructure. Decas Cranberry Products anchors the organic-certified tier, commanding premium access in health-oriented distribution channels.
| Leading Market Players |
|---|
| Decas Cranberry Products |
| Atoka Cranberries |
| Ocean Spray Cranberries |
| Very Berry Company |
| Fruit d'Or |
| Wisconsin State Cranberry Growers Association |
| Cliffstar Corporation |
| Turkiye Cranberry Growers Association |
| Cranberries Canada |
| Others |
Supply Flow & Price Mechanics
Quebec's cooperative pooling clusters compress capital barriers for new growers while concentrating upstream pricing power among established processors. This geographic concentration shapes downstream margin capture, with bog-owning processors commanding premium tiers over contract-dependent entrants.
Pricing Analysis
Certification level creates the primary spread between conventional and USDA Organic supply tiers, with three-year land conversion requirements delaying revenue realization for transitioning growers. Price differentiation hinges on EFSA MRL compliance for European export eligibility and anthocyanin potency guarantees demanded by functional beverage manufacturers. Pricing pressure stems from glyphosate threshold divergence between FDA and EFSA frameworks, forcing dual compliance cost burdens. Mass-market supermarkets exhibit highest price sensitivity, while health stores accept premium positioning for proanthocyanidin-certified supply.
Supply Chain Analysis
Contract farming concentration among Quebec and British Columbia cooperative arrangements anchors North American volume, with Wisconsin and Massachusetts processing clusters providing secondary capacity. Raw material dependencies center on sand for bog maintenance, specialized vine stock for establishment, and sulfur-based pest management inputs. Supply chain risk concentrates in weather vulnerability across the two-provincial cluster structure. Distribution runs through controlled-atmosphere storage infrastructure that extends shelf-life beyond narrow harvest windows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Controlled-atmosphere storage breakthroughs and hyperspectral imaging deployment are disrupting traditional cooperative logistics, creating asymmetric advantage for capitalized processors.
For Market Incumbents: Entrench year-round supply consistency through multi-year offtake agreements with beverage formulators seeking traceability guarantees. Deepen backward integration into bog ownership to secure captive raw material control against emerging cooperative entrants. Deploy automated quality assessment technology to compress payment cycles and virtualize grade disputes. For New Entrants and Emerging Players: European health store networks remain underpenetrated by North American organic-certified supply, presenting white-space expansion opportunity. Target Germany and Netherlands distribution hubs with EFSA-compliant lots that bypass conventional glyphosate-dependent channels. Establish direct procurement relationships with Quebec pooling arrangements to secure preferential access. For Investors and Strategic Acquirers: Carve-out targets emerge from aging grower cooperatives lacking succession planning and digital infrastructure investment. Long-term viability favors processors with vertical control over cultivation and automated sorting capability. Monitor hyperspectral imaging adoption rates as inflection indicator for operational efficiency divergence.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-year Offtake Agreement | Beverage formulators secure traceability guarantees from Quebec cooperative pools. |
| Organic Certification Investment | Three-year land conversion unlocks premium European health store placement. |
| Hyperspectral Imaging Deployment | Automated USDA grade assessment compresses payment cycles at receiving stations. |
| Controlled-Atmosphere Storage Expansion | Year-round retail availability reduces frozen concentrate dependency. |
| EFSA Compliance Program | Dual-threshold management preserves cross-Atlantic market access against divergence. |
Methodological Framework
Operator-level perspectives from cooperative managers, beverage formulator procurement leads, health store category buyers, and agricultural extension specialists anchored the qualitative base. Secondary validation drew from USDA Agricultural Marketing Service standards, EFSA pesticide residue databases, FDA Grade A compliance records, and customs trade flow data. Bottom-up grower surveys triangulated against top-down processor capacity assessments.
Scenario-bracketing around MRL harmonization outcomes and climate volatility shaped the analytical framework across the projection horizon. Segmentation modeling incorporated product format, packaging cold-chain requirements, distribution channel digitization, and end-use specification stringency. CAGRs derived from volume-weighted price trajectory analysis and input cost elasticity modeling.
The forecast holds incumbent behavior within observed patterns; aggressive moves by hyperspectral imaging early adopters would shift outcomes. Quarterly review of EFSA threshold adjustment announcements and cooperative technology deployment rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Mexico Fruits & Vegetables Market
Fruits and Vegetables
Cavendish Banana Market
Fruits and Vegetables
Arecanut Market
Fruits and Vegetables
North America Fruits & Vegetables Market
Fruits and Vegetables
Dragon Fruit Market
Fruits and Vegetables
Infused Dried Fruits Market
Fruits and Vegetables
Sea Buckthorn Market
Fruits and Vegetables
Global Dehydrated Onion Flakes Market
Fruits and Vegetables
Europe Orange Market
Fruits and Vegetables
Dried Figs Market
Fruits and Vegetables
Jicama Market
Fruits and Vegetables
North America Organic Fruits Market
Fruits and Vegetables
Global Avocado Market
Fruits and Vegetables
Israel Fruits and Vegetables Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Yacon Fruit Extract Market