
 North Africa Table Olives Market | 2026-2036
North Africa Table Olives Market Size, Share, and Industry Trends Forecast 2026-2036
North Africa Table Olives Market Intelligence
Mechanical harvesting and optical sorting is narrowing the quality gap between artisanal and industrial table olive production across North African processing facilities. Wadi Food leverages integrated estate-to-jar operations across Egypt's Nile Delta to sustain consistent supply volumes for European retail chains. AgroSevilla anchors its competitive position through specialized black olive curing expertise that dominates Iberian and North African private-label contracts.
Table olives denote cured drupe fruits from Olea europaea, processed through brine fermentation or lye treatment to achieve pH stability between 3.5 and 4.0 and shelf-ready edibility for direct consumption or culinary formulation. The Manzanilla and Kalamata product types lead current volume flows, with Kalamata commanding premium positioning in European food service channels while Manzanilla sustains mass-market penetration through glass jar and bulk packaging formats. Food manufacturers represent the fastest-growing end user segment as North African processors develop pitted and sliced olive ingredient lines for ready-meal and pizza applications.
Egypt's FSSAI-aligned food safety protocols, Tunisia's BSI-equivalent conformity assessments, and Morocco's alignment with EFSA import standards collectively govern export market access and product certification requirements across the region. These regulatory frameworks shape capital allocation toward HACCP-compliant processing upgrades and traceability system investments. Stakeholders must monitor evolving EU deforestation due diligence rules and their potential extension to olive sector supply chain documentation requirements.
Market Dynamics
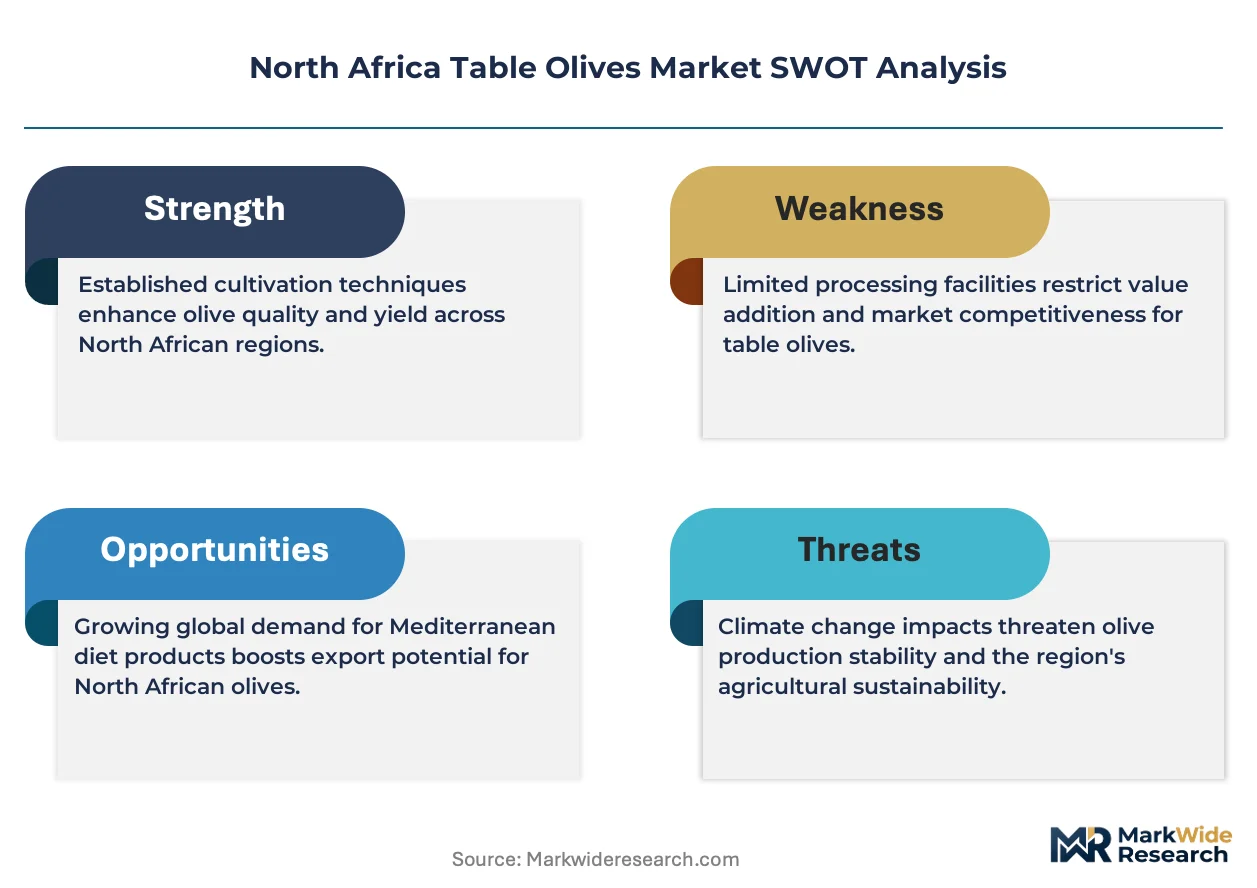
EFSA's import traceability requirements are forcing North African processors to rebuild documentation systems, redirecting capital from capacity expansion toward compliance infrastructure and third-party audit certifications.
Growth Catalysts
- EU Green Deal alignment:Moroccan and Tunisian exporters securing EFSA-compliant organic certifications access premium shelf space in German and French retail chains, commanding price multiples over conventional grades.
- Mechanical harvesting diffusion:Optical sorting systems deployed across Meknes-Fes processing clusters reduce labor dependency during seasonal peaks and stabilize throughput volumes for European private-label contracts.
- Ready-meal formulation demand:Food manufacturers in Iberia and Southern France expand procurement of pitted and sliced olive ingredient lines, pulling volume through North African toll-processing arrangements.
Market Restraints
- Input cost volatility:Glass jar and tinplate packaging material prices fluctuate with energy markets, compressing processor margins on mass-market Manzanilla formats where substitution to plastic is brand-prohibited.
- Supply concentration risk:Egypt's Nile Delta estates control disproportionate black olive curing capacity, creating single-geography vulnerability for European retailers dependent on consistent Kalamata-style supply.
- Regulatory friction:Evolving EU deforestation due diligence documentation requirements extend compliance timelines and legal review costs for small-scale Moroccan cooperatives lacking dedicated regulatory staff.
Strategic Opportunities
- Algerian capacity underpenetration:Eastern Algerian olive groves near Tlemcen remain underdeveloped for table olive conversion, offering greenfield estate investment potential for integrated processors seeking captive supply.
- E-commerce direct channels:Specialty cured olive assortments bypass traditional importer-distributor networks through platform direct-to-consumer fulfillment, capturing margin previously allocated to wholesale intermediaries.
- Tunisia's BSI-equivalent acceleration:Streamlined conformity assessment mutual recognition with EU member states reduces certification duplication costs and accelerates market entry for mid-scale processors.
Industry Challenges
- Traceability system integration:Legacy paper-based farm-to-factory documentation at Tunisian cooperatives requires digitization capex and staff retraining to meet EFSA blockchain-adjacent verification standards.
- Skilled fermentation technologist scarcity:Black olive curing expertise concentrates among aging master processors in Seville and Meknes, constraining quality replication at new Egyptian and Algerian facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North Africa Table Olives Market |
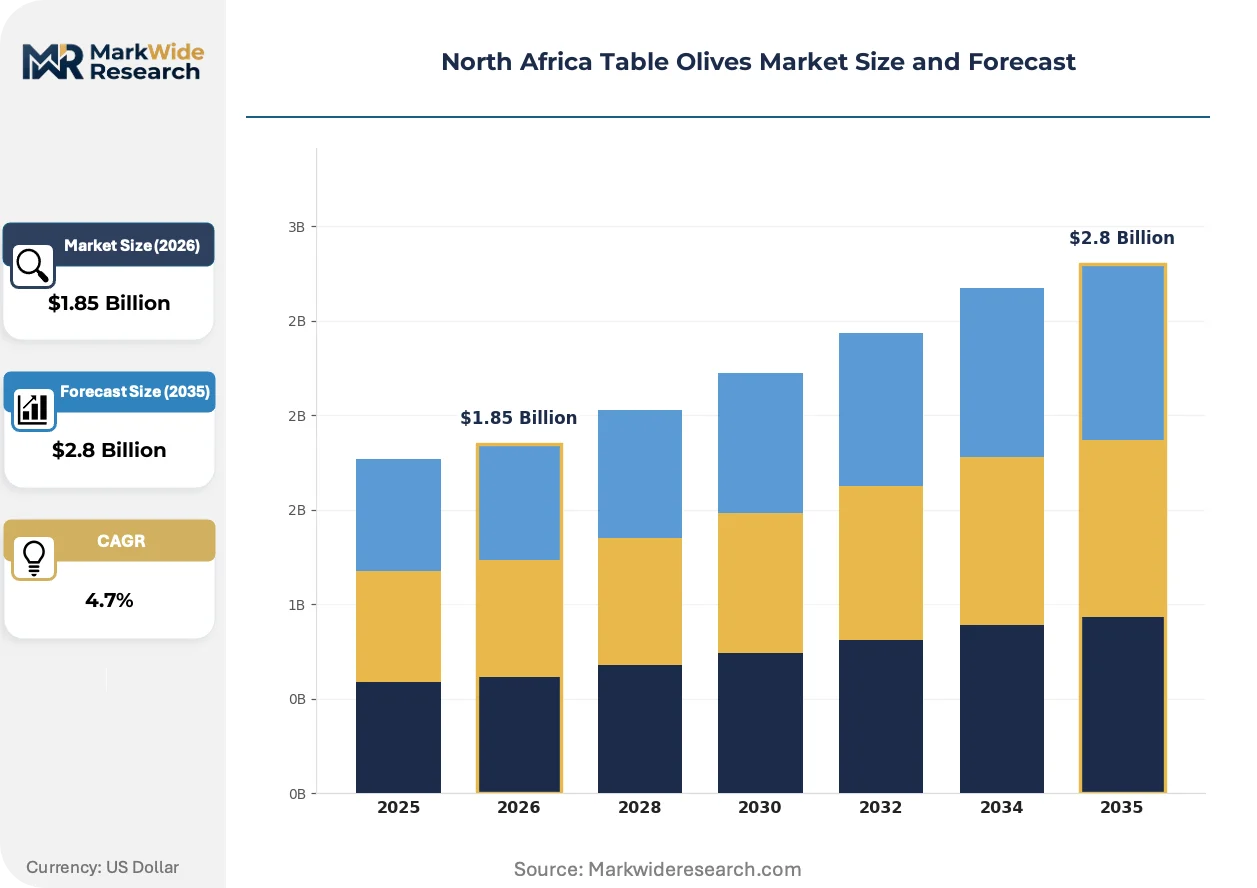
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.8 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Kalamata, Manzanilla, Castelvetrano, Ligurian Packaging Type: Glass Jar, Plastic Container, Bulk Packaging, Vacuum Pack Distribution Channel: Retail Stores, Online Retail, Food Service, Export End User: Household, Restaurants, Food Manufacturers, Caterers |
| Companies Covered | Wadi Food, Tesoro Del Rio, AgroSevilla, Olive Line International, Borges International Group, Deoleo SA, OliveOilsLand, Servicentral Agrosevilla SL, Aceituna Verde SL, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North Africa Table Olives Market Strategic Shifts & Innovations
Processing technology and supply chain verification systems are converging to compress quality variance between artisanal and industrial output, while procurement patterns fragment across traditional and emerging channels.
Computer vision grading systems is hybridizing brine fermentation monitoring with real-time defect detection, enabling continuous processing lines that previously required batch manual inspection. Mid-scale Moroccan processors deploying these systems achieve EFSA-compliant consistency metrics without estate-scale vertical integration. The technology is compressing the premium gap between cooperative-origin and industrial-origin product lines in European retail assortments.
EFSA's extended supply chain due diligence framework is extending documentation requirements from processor gates back to orchard-level geolocation data. North African exporters must now maintain GPS-tagged harvest records and pesticide application logs spanning three growing seasons. Smallholder-dependent Tunisian processors face disproportionate compliance burden relative to Egyptian estate-integrated competitors with captive farm management systems.
Food service buyers are consolidating procurement through specialized olive ingredient distributors rather than generalist broadline providers, unbundling cured olive supply from composite Mediterranean ingredient baskets. Pizza chain and ready-meal manufacturers in France and Italy now specify pitted-diced format standards directly with North African toll processors, bypassing traditional Mediterranean bulk traders. This channel compression is most visible in Iberian food service procurement, where direct contracting has displaced importer intermediaries for volume accounts.
North Africa Table Olives Market Segmentation
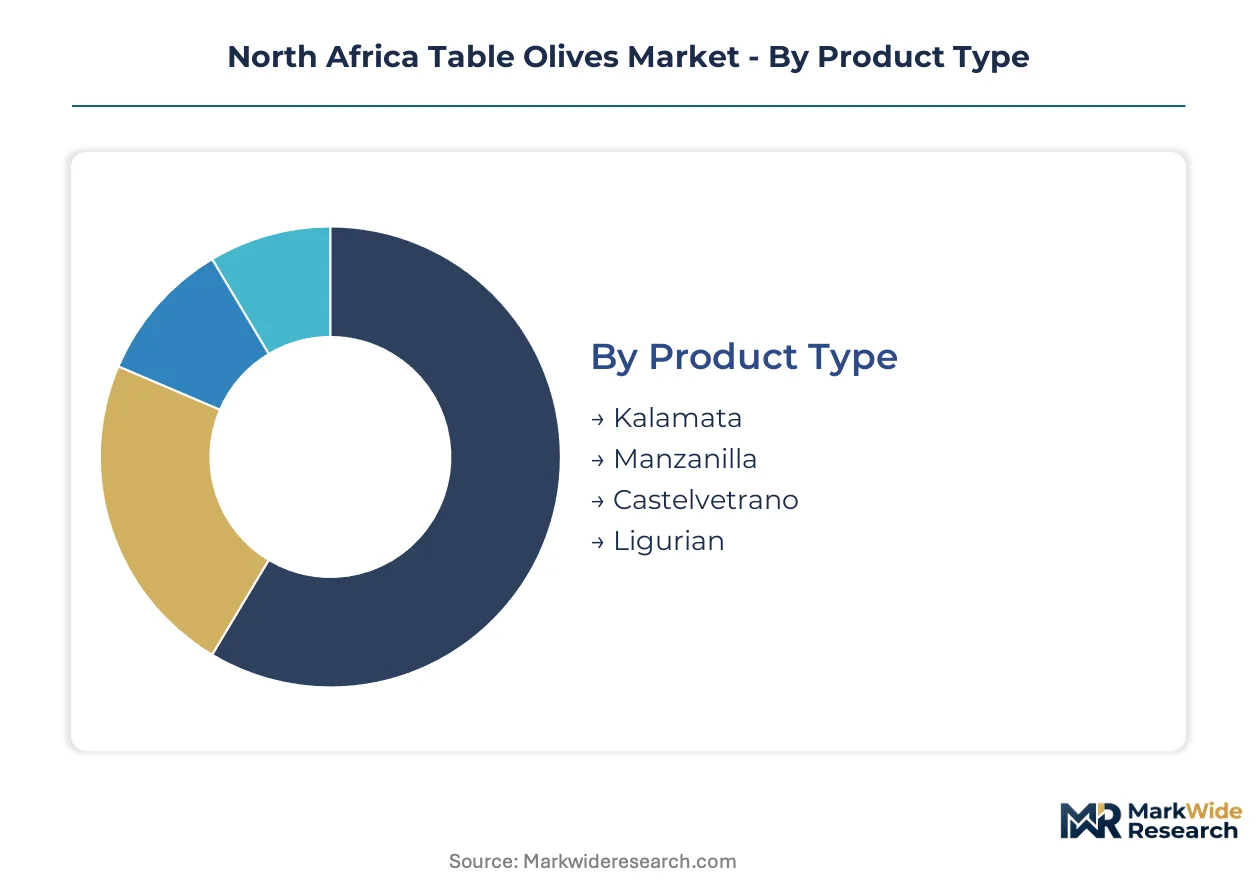
Segmentation in North African table olives reveals how curing protocols, packaging durability, and channel compliance requirements create divergent margin profiles across product lines. Understanding these divisions exposes where capital deployment yields differential returns.
Product Type:
Kalamata and Manzanilla turn inventory fastest through established European retail contracts, while Castelvetrano and Ligurian move slower through specialty channels with longer qualification cycles.
- Kalamata:Naturally black-cured drupes with distinctive almond shape and wine-vinegar fermentation profile. Demand concentrates in French and Italian food service channels where pitted formats command specification premiums for pizza and salad applications.
- Manzanilla:Spanish-origin green olives lye-cured to achieve uniform straw color and neutral pH stability. Moroccan Meknes-Fes processors supply German and French mass-market retailers through high-volume glass jar contracts with annual tender cycles.
- Castelvetrano:Bright green Sicilian-style olives processed through rapid lye treatment and minimal fermentation. Tunisian coastal processors target US specialty retail through importer-direct arrangements.
- Ligurian:Small-fruited Italian varietals brine-cured with herb infusions. Algerian Tlemcen groves experimental plantings serve niche European delichannel accounts.
Manzanilla dominates installed base. Kalamata is where expansion concentrates.
Packaging Type:
Packaging economics split between shelf-preservation requirements for export compliance and cost minimization for food service bulk procurement.
- Glass Jar:Standard 314ml and 720ml formats with vacuum-sealed metal closures. EFSA import documentation requirements favor glass for organic-certified Manzanilla lines entering German retail.
- Plastic Container:Polypropylene tubs with modified atmosphere sealing. Egyptian Nile Delta processors deploy plastic for food service pitted-diced formats where transport weight reduction offsets material cost.
- Bulk Packaging:Food-grade plastic drums and stainless steel totes for industrial ingredient supply. Moroccan toll processors fill Iberian ready-meal manufacturer specifications through bulk shipments to Seville consolidation points.
- Vacuum Pack:Multi-layer barrier films for extended shelf-life specialty lines. Tunisian cooperatives pilot vacuum formats for direct-to-consumer e-commerce channels bypassing traditional importer margins.
Glass jar commands volume leadership. Vacuum pack is climbing the fastest.
Distribution Channel:
Channel selection determines documentation burden and working capital intensity, with export and food service requiring divergent compliance infrastructures.
- Retail Stores:Hypermarket and supermarket shelf placement through distributor networks. Carrefour and Auchan procurement in France and Morocco drives Manzanilla volume through annual listing agreements.
- Online Retail:Platform-direct fulfillment and specialty grocer e-commerce. Amazon and regional platforms enable Tunisian processors to capture margin previously allocated to importer-distributor intermediaries.
- Food Service:Broadline distributor and direct manufacturer supply. Pizza chains in Iberia and Southern France specify pitted-diced Kalamata formats through toll-processing contracts with Meknes-Fes facilities.
- Export:Containerized shipment to EU, North American, and Gulf markets. EFSA traceability requirements and evolving deforestation due diligence documentation extend compliance timelines for small-scale cooperatives.
Export channels dominate installed base. Online retail is where expansion concentrates.
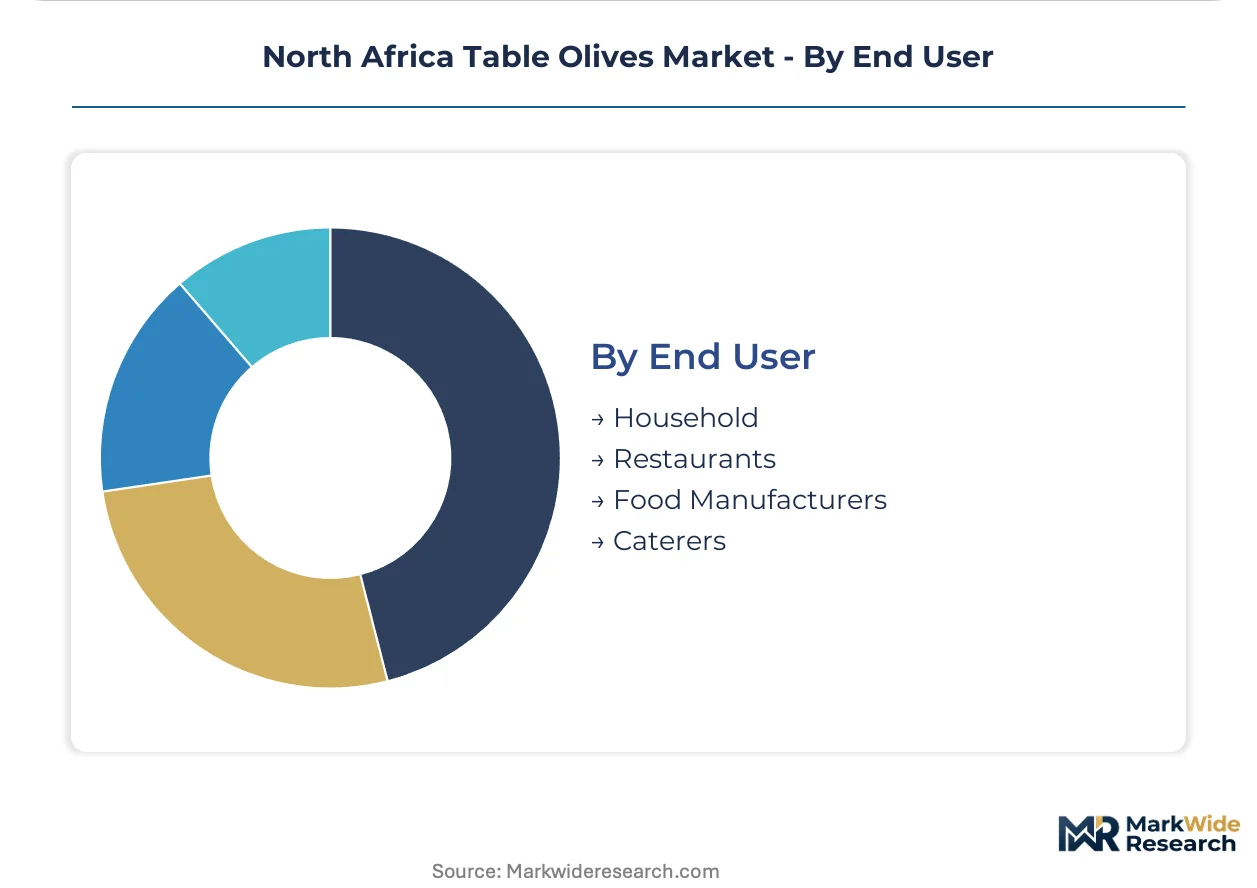
End User:
End-user differentiation reflects formulation complexity, with food manufacturers imposing strictest specification standards and households accepting broadest quality variance.
- Household:Direct consumption through retail purchase for table and recipe use. Moroccan domestic consumption absorbs significant Manzanilla volume through traditional souk and modern trade channels.
- Restaurants:Independent and chain food service operations requiring consistent portion-control formats. Kalamata pitted olives serve tapas and mezze presentations across Iberian and French independent restaurants.
- Food Manufacturers:Ready-meal, pizza, and sauce producers requiring ingredient-grade supply. Sliced and diced olive lines from Egyptian and Moroccan processors integrate into frozen pizza and pasta sauce production.
- Caterers:Institutional and event food service requiring bulk formats with extended holding stability. Algerian processors target Gulf market catering contracts through bulk black olive supply.
Household consumption dominates installed base. Food manufacturers represent the fastest-growing trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moroccan table olive exports flow through Algeciras and Marseille toward German and French retail chains, while Egyptian processors supply Iberian food manufacturers through direct toll-processing contracts.
Morocco
Meknes-Fes corridor estates supply Manzanilla volume to Carrefour and Auchan through annual tender cycles. EFSA traceability requirements under the EU Green Deal framework compel processors to digitize farm-to-factory documentation. Optical sorting deployment across Fes processing clusters reduces labor dependency during October harvest peaks.
Tunisia
Coastal processors target US specialty retail with Castelvetrano-style olives through importer-direct arrangements. BSI-equivalent conformity assessments accelerate mutual recognition with EU member states, cutting certification duplication costs. Sfax and Sousse cooperatives pilot vacuum-pack formats for Amazon and regional e-commerce platforms.
Egypt
Nile Delta estates dominate black olive curing capacity for European Kalamata-style demand. FSSAI-aligned food safety protocols govern export documentation to Gulf catering contracts. Wadi Food's integrated estate-to-jar operations across Sharqia Governorate sustain consistent supply volumes for British retail chains.
Algeria
Tlemcen groves remain underdeveloped for table olive conversion despite suitable microclimate conditions. The country's national food safety regulator enforces HACCP compliance timelines that lag Moroccan and Tunisian adoption curves. Private investors from Iberia evaluate greenfield estate opportunities near the Moroccan border.
Spain
Andalusian processors AgroSevilla and Deoleo SA anchor black olive curing expertise that dominates Iberian private-label contracts. Seville consolidation points receive bulk shipments from Moroccan toll processors for redistribution to French ready-meal manufacturers. REACH-compliant packaging material sourcing constrains margin compression on glass jar formats.
North Africa Table Olives Market Key Industry Players
On the supply side, the industry is bifurcated between estate-integrated operators with captive orchards and toll processors dependent on smallholder cooperatives. Three archetypes dominate: vertically integrated Nile Delta estates, Meknes-Fes processing clusters with optical sorting infrastructure, and Iberian curing specialists with black olive fermentation mastery. Competitive moves concentrate on backward integration into orchard control and EFSA-compliant traceability system deployment.
Among estate-integrated operators, Wadi Food exemplifies captive supply chain architecture spanning Egyptian cultivation through European retail fulfillment. AgroSevilla occupies a position as the archetypal curing specialist, its Sevilla-based operations representing the concentration of black olive expertise that North African competitors struggle to replicate. Deoleo SA sits within the diversified Iberian tier, its corporate structure reflecting the scale advantages that sustain private-label contract dominance across multiple olive product categories.
| Leading Market Players |
|---|
| Wadi Food |
| Tesoro Del Rio |
| AgroSevilla |
| Olive Line International |
| Borges International Group |
| Deoleo SA |
| OliveOilsLand |
| Servicentral Agrosevilla SL |
| Aceituna Verde SL |
| Others |
Cost & Logistics Intelligence
Underutilized curing capacity across Algeria's Tlemcen groves compresses regional pricing power, forcing Moroccan and Tunisian processors to absorb compliance cost inflation rather than pass through to European buyers while Egyptian estate operators exploit captive supply to defend margin.
Pricing Analysis
Mechanical harvesting technology widens the pricing gap between optical-sorted Manzanilla output and legacy batch-processed grades. Three-tier pricing structure across EFSA-certified organic, conventional export-grade, and domestic-standard tiers separates compliance-burdened from commodity supply. Cost compression in mass-market glass jar formats intensifies because energy-linked tinplate and packaging material volatility erodes processor margins. Food manufacturers exhibit highest price sensitivity due to specification-tender procurement cycles, while specialty retail channels absorb premium positioning for traceability-verified Kalamata lines.
Supply Chain Analysis
Toll-processing concentration among Meknes-Fes optical sorting clusters and Egyptian Nile Delta estate-integrated operators dominates contract manufacturing capacity. Supply draws from Morocco, Egypt, and Tunisia for European-bound volume, with Spain's Seville consolidation points serving as redistribution nodes. Raw material dependencies center on glass jar and tinplate packaging, brine fermentation cultures, and lye treatment chemicals. Single-geography vulnerability in Egypt's black olive curing concentration exposes European retailers to harvest disruption risk. Distribution runs through containerized export to EU ports, direct toll-processing contracts with Iberian food manufacturers, and emerging platform-direct e-commerce channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
North Africa table olives sit in cyclical recovery as EFSA compliance investment cycles mature and mechanical harvesting capex yields throughput stabilization for European contract renewal.
For Market Incumbents: Build traceability system moats through GPS-tagged harvest documentation and blockchain-adjacent verification to preempt EU deforestation due diligence extension. Incumbents should anchor Meknes-Fes processing clusters with additional optical sorting deployment to defend against Algerian greenfield entrants. Backward integration into orchard control secures supply continuity against smallholder cooperative fragmentation. For New Entrants and Emerging Players: Eastern Algerian olive groves near Tlemcen represent the most penetrable entry point for estate-integrated greenfield development bypassing legacy cooperative dependency. New entrants should target US specialty retail Castelvetrano demand through importer-direct arrangements, exploiting Tunisia's BSI-equivalent acceleration precedent. E-commerce vacuum-pack formats for platform-direct fulfillment offer margin capture absent from traditional distributor networks. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because estate-integrated operators with EFSA-compliant infrastructure will acquire distressed smallholder-dependent processors unable to digitize documentation systems. Acquisition targets cluster among Tunisian cooperatives with coastal processing assets and latent organic certification potential. Watch for EU deforestation due diligence rule finalization as inflection signal accelerating compliance-driven M&A.| Strategic Initiative | Industry Significance |
|---|---|
| Optical Sorting Deployment | Meknes-Fes processors achieve EFSA consistency metrics without estate-scale vertical integration. |
| EFSA Traceability Compliance | GPS-tagged harvest records satisfy EU Green Deal documentation requirements for German retail access. |
| E-commerce Channel Expansion | Tunisian vacuum-pack pilots capture margin previously allocated to importer-distributor intermediaries. |
| Backward Orchard Integration | Egyptian estate operators sustain supply consistency for British retail through captive cultivation control. |
| Algerian Greenfield Investment | Iberian private investors evaluate Tlemcen estate opportunities to replicate Moroccan processing cluster model. |
Research Approach
Findings reconcile primary fieldwork against secondary review of customs export records, EFSA regulatory filings, and olive sector trade association data through structured interviews with Moroccan processing plant managers, Tunisian cooperative export directors, Egyptian estate operations heads, and European retail category buyers. Bottom-up volume triangulation from named processing facility throughput data converges with top-down trade flow analysis across Mediterranean container routes.
Forecast inputs include curing technology adoption curves, EFSA compliance timeline assumptions, and mechanical harvesting diffusion rates across the analysis window. Segmentation modeling spans product type curing protocols, packaging format durability tiers, distribution channel documentation intensity, and end-user formulation complexity. CAGRs derive from elasticity-adjusted demand projections and supply-side capacity utilization trends, incorporating EU deforestation due diligence implementation pace and organic certification premium persistence.
Practitioners should monitor EFSA rulemaking velocity, Algerian regulatory HACCP adoption timelines, and glass jar energy-cost linkage for early signals of forecast revision triggers. Quarterly review of European retail tender cycle outcomes, smallholder cooperative digitization capex flows, and Nile Delta harvest yield indicators is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
Edible Flowers Market
Fruits and Vegetables
Global Papaya Puree Market
Fruits and Vegetables
Fresh Apricots Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Bamboo Shoots Market
Fruits and Vegetables
US Fruit Puree Market
Fruits and Vegetables
Global Organic Fruits and Vegetables Market
Fruits and Vegetables
Fresh Lemons Market
Fruits and Vegetables
Asia Pacific Lime Market
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market
Fruits and Vegetables
Israel Fruits and Vegetables Market
Fruits and Vegetables
Middle East and Africa Sweet Potatoes Market
Fruits and Vegetables
Fruit Puree Market
Fruits and Vegetables
Vietnam Fruits and Vegetables Market
Fruits and Vegetables
Dried Figs Market