
 Dry Beans Market | 2026-2036
Dry Beans Market Size, Share, and Industry Trends Forecast 2026-2036
Dry Beans Market Intelligence
Single-serve pouch configurations and modular retail packs is recalibrating how households and foodservice operators purchase dry beans. Cargill Incorporated leverages its grain-trading infrastructure to sustain bulk supply contracts across North American retail chains. Goya Foods dominates shelf-stable ethnic food aisles through brand strength in Hispanic grocery segments. AGT Food and Ingredients anchors specialty-grade sourcing with backward integration into Canadian prairie production.
Dry beans comprise mature seeds of leguminous plants, typically containing 20-25% protein by dry weight and requiring hydration or thermal processing before human consumption; they serve as staple protein sources, meat extenders, and textured ingredients across industrial food manufacturing. Pinto beans and black beans lead volume within the product type dimension due to entrenched consumption patterns in Mexico, the southwestern United States, and Latin American export corridors. The organic and non-GMO grades command margin premiums as European and North American retailers enforce stricter clean-label procurement mandates, while conventional grade still occupies the bulk of institutional and animal feed channels.
The USDA administers grade standards and organic certification that gate U.S. retail and export access, while the EU Green Deal and F-Gas Regulation indirectly pressure processing energy footprints across European import markets. India's FSSAI and BIS frameworks govern import tolerances and pesticide residue limits for incoming pulses shipments. Stakeholders must monitor how tightening phytosanitary protocols in multiple jurisdictions reshape origin eligibility and inspection costs before committing to long-term supply contracts.
Market Dynamics
Plant-based protein certification standards are tightening procurement eligibility across retail and foodservice channels, forcing suppliers to reconfigure sourcing networks and processing protocols to maintain market access.
Growth Catalysts
- EU Green Deal agricultural targets:The EU Green Deal mandates reduced livestock intensity, redirecting institutional protein procurement toward legume alternatives. Food manufacturers reformulate meat-extender applications to capture subsidy-aligned sourcing.
- Single-serve pouch adoption:Flexible packaging lines at retail chains accommodate smaller household sizes. Urban consumers in Mexico City and São Paulo purchase modular pack sizes weekly rather than bulk monthly.
- India FSSAI import tolerance expansion:India's FSSAI relaxed phytosanitary hold periods for containerized pulses. Brazilian and Canadian exporters redirect container volumes toward Mumbai and Mundra ports.
Market Restraints
- Input cost volatility:Diesel and nitrogen fertilizer prices swing with crude oil benchmarks. Prairie farmers in Saskatchewan and Alberta face margin compression during planting windows.
- Supply concentration risk:Bulk export infrastructure concentrates at Vancouver and Santos terminals. Weather disruptions at either port cascade through contracted delivery schedules.
- Regulatory friction:The EU F-Gas Regulation restricts refrigeration gases in processing facilities. European canners face retrofit costs or volume caps during peak harvest intake.
Strategic Opportunities
- Underpenetrated Ethiopian demand:Ethiopia's state-led nutrition programs expand school feeding initiatives. Local processors lack capacity to meet institutional tender volumes.
- Regulatory tailwind from USDA organic transition incentives:The USDA Organic Cost Share Program subsidizes certification expenses. Prairie cooperatives convert conventional acreage to capture premium retail placement.
- Direct-to-foodservice platform convergence:Digital procurement platforms connect processors with restaurant chains. Cloud kitchens in Bangalore and Jakarta source calibrated lot sizes bypassing traditional distributor markups.
Industry Challenges
- Certification timeline compression:USDA organic and non-GMO verification requires 36-month transition periods. Suppliers risk contract penalties if harvest falls outside accredited windows.
- Capex intensity in optical sorting:Color and defect detection systems require seven-figure capital deployment. Mid-scale processors defer upgrades, ceding premium grade access to integrated operators.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dry Beans Market |
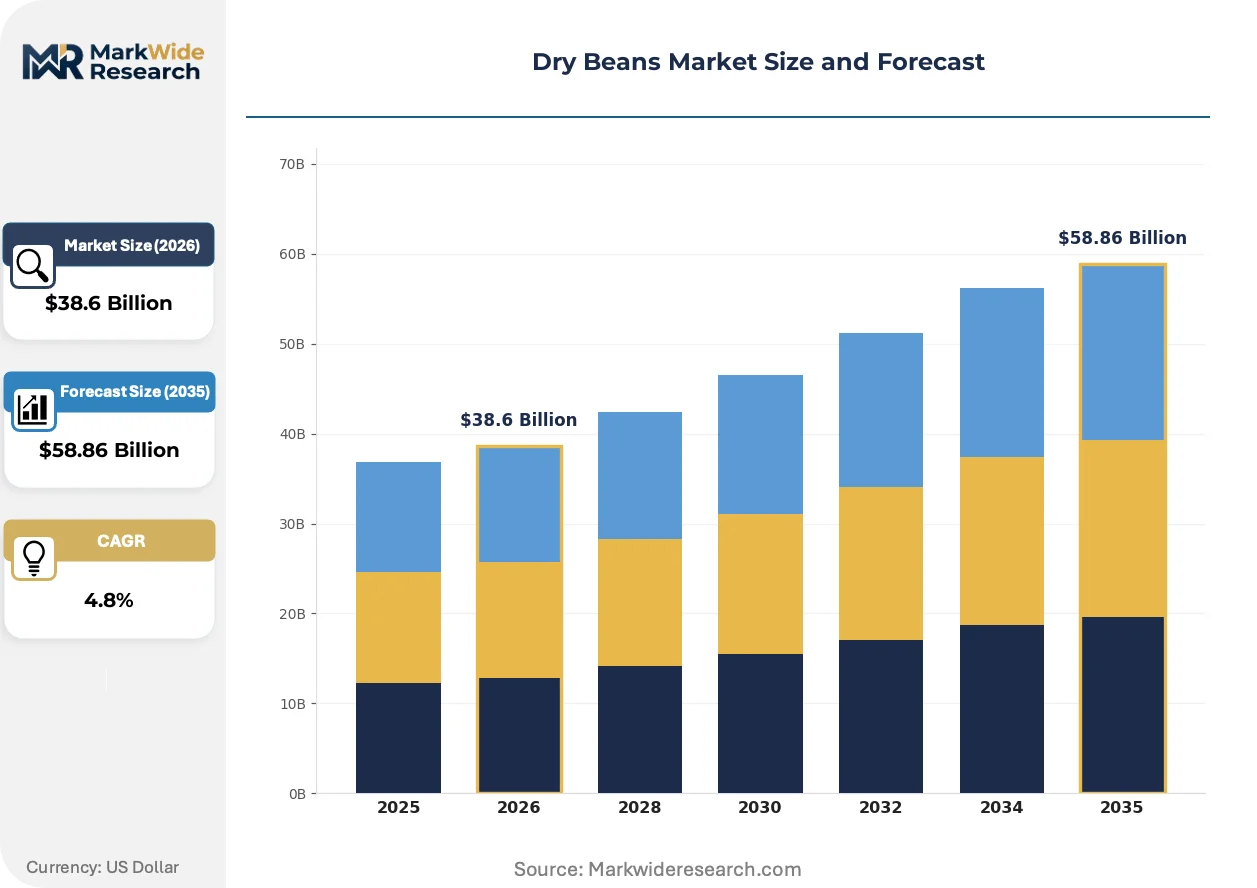
| Market Size in 2026 | $38.6 Billion |
| Market Size in 2035 | $58.86 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pinto Beans, Black Beans, Kidney Beans, Navy Beans End Use Industry: Agriculture, Food & Beverage, Animal Feed, Nutraceuticals Grade: Organic, Non-GMO, Conventional, Specialty Packaging Type: Bags, Bulk Containers, Boxes, Tins |
| Companies Covered | Archer Daniels Midland Company, Cargill Incorporated, Louis Dreyfus Company, Olam Agri Holdings, Goya Foods, Bush Brothers & Company, Conagra Brands, AGT Food and Ingredients, CHS Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dry Beans Market Strategic Shifts & Innovations
Processing automation and clean-label verification protocols are restructuring competitive advantage around traceability depth and lot-level documentation rather than scale alone.
Hyperspectral imaging systems for defect and moisture detection are expanding into primary processing facilities. Large-scale handlers in Nebraska and Manitoba deploy inline sorters to reduce manual grading labor. The technology is expanding into mid-tier cooperatives that previously relied on spot-market visual inspection, compressing quality variance across origin lots.
The EU Green Deal Farm-to-Fork Strategy mandates 25% organic farmland conversion by 2030. Bean processors serving European retail must document regenerative practices and carbon intensity per kilogram. North American exporters face audit burden expansion to maintain shelf placement in German and Dutch supermarket chains.
Foodservice operators consolidate purchase authority through centralized procurement platforms. Regional restaurant groups in São Paulo and Mexico City negotiate direct contracts with origin handlers, displacing traditional broker intermediaries. This concentration is most visible in Latin American urban corridors where chain penetration exceeds independent operator growth.
Dry Beans Market Segmentation
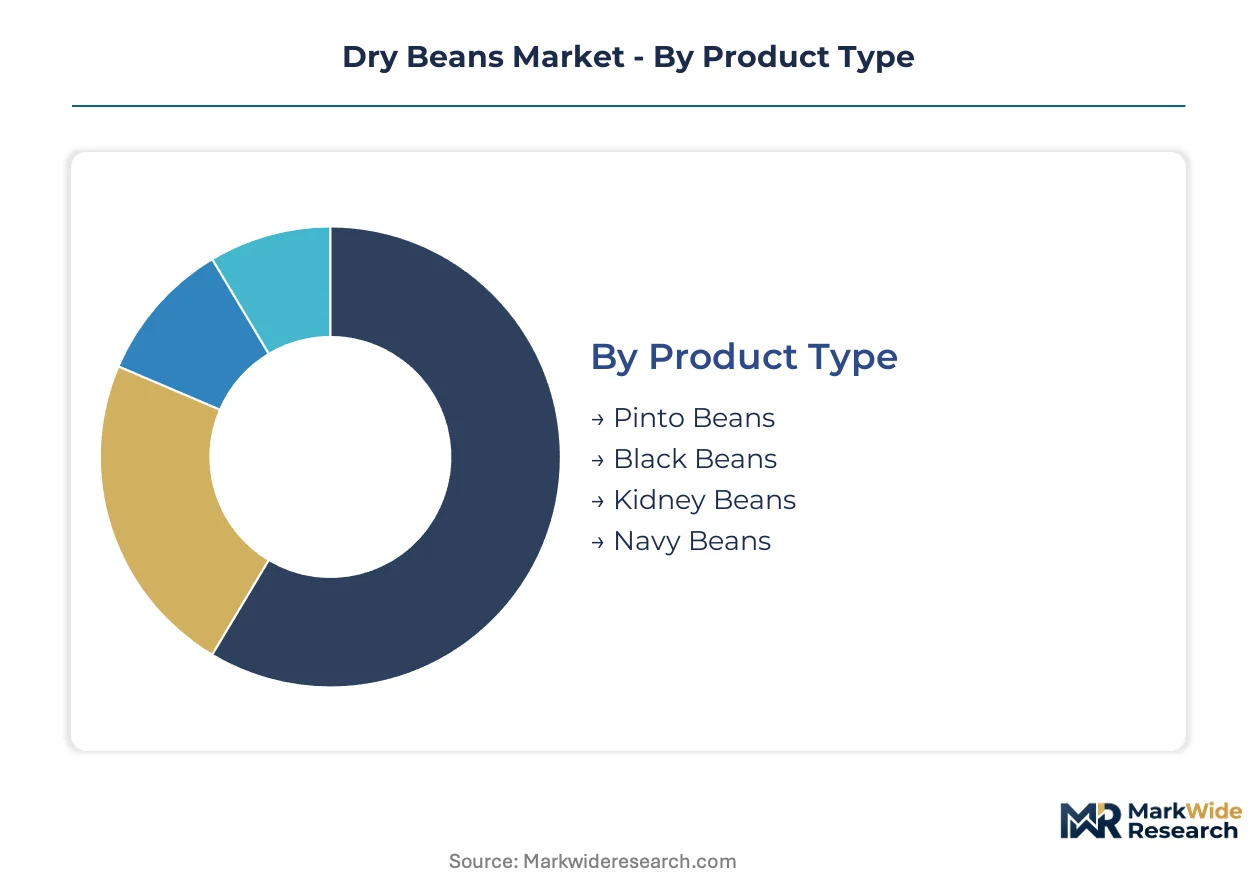
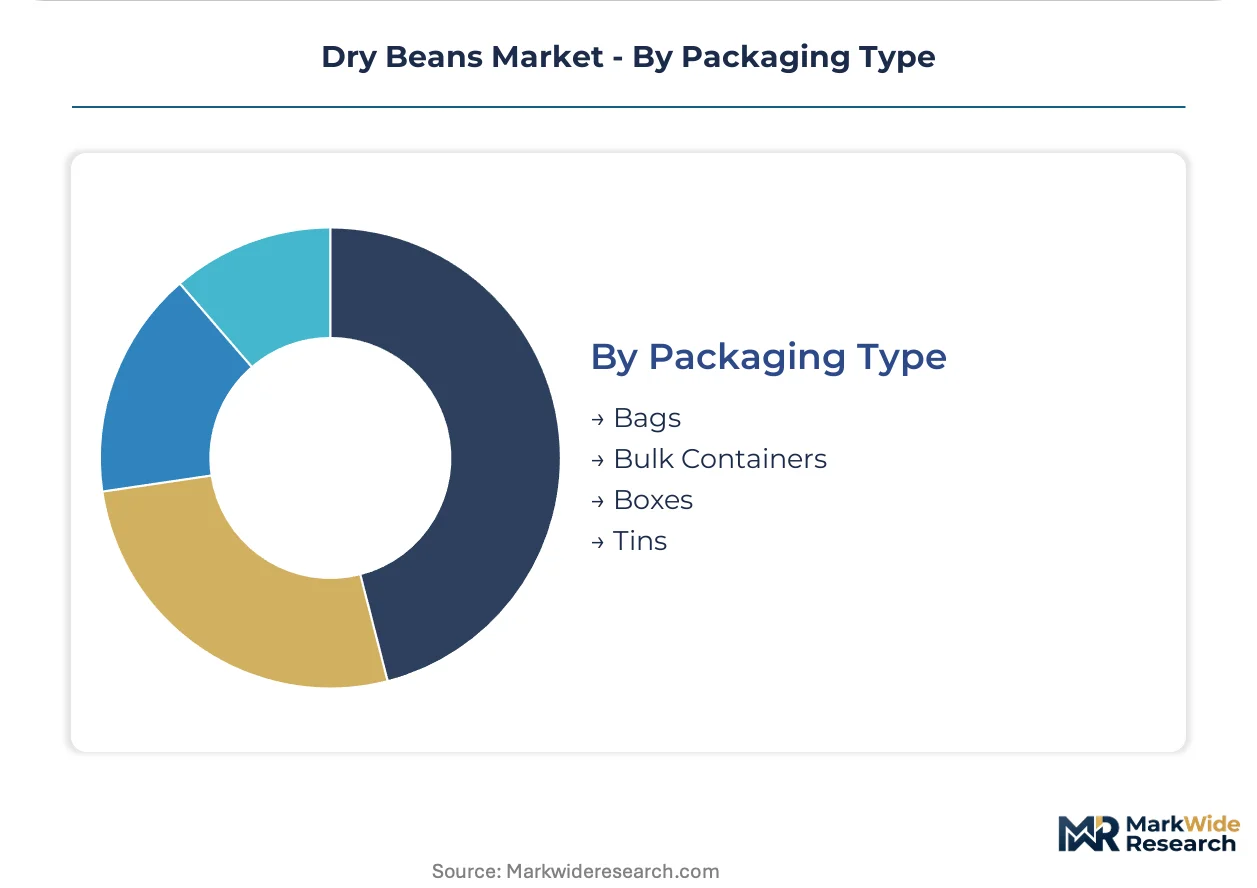
Dry bean procurement splits across four orthogonal dimensions that reshape margin capture. Product type and grade certification determine price realization, while packaging configuration and end-use channel dictate volume velocity and working capital intensity.
Product Type:
Buyer preference for protein content, cooking time, and cultural cuisine alignment drives varietal selection across retail and foodservice channels.
- Pinto Beans:Mottled beige-pink seeds containing 22% protein by dry weight with relatively short soak requirements. Mexican and southwestern U.S. households sustain bulk procurement through retail chains, while Texas and California foodservice operators specify pinto for refried and whole-bean applications.
- Black Beans:Small, glossy seeds with dense anthocyanin content and 24% protein concentration that holds shape during extended cooking. Brazilian urban consumers and Caribbean export corridors concentrate import demand, with São Paulo restaurant chains contracting calibrated lot sizes for feijoada and side-dish formulations.
- Kidney Beans:Large, kidney-shaped seeds with firm texture retention after thermal processing, favored in chili and salad applications across North American institutional channels.
- Navy Beans:Small, oval white seeds with mild flavor profile and rapid cook-down characteristics, dominant in baked bean manufacturing and U.S. military ration specifications.
Volume sits with Pinto Beans; growth tilts toward Black Beans.
End Use Industry:
Application-specific processing requirements and certification thresholds fragment procurement specifications across downstream sectors.
- Food & Beverage:Canned, dried, and ingredient-grade beans for retail and foodservice, requiring USDA or EU organic documentation for shelf placement. Clean-label reformulation in meat-extender applications expands buyer pools as European manufacturers redirect protein sourcing under EU Green Deal livestock reduction targets.
- Agriculture:Seed stock and cover-crop applications with varietal purity standards governing germination rates and disease resistance traits. Canadian prairie cooperatives backward integrate into certified seed production to capture premium farm-gate pricing.
- Animal Feed:Conventional-grade beans and processing byproducts for protein supplementation in poultry and swine rations, price-sensitive to soybean meal substitution economics.
- Nutraceuticals:Isolated protein fractions, resistant starch extracts, and fiber concentrates for supplement formulations, requiring lot-level contaminant testing and GMP facility certification.
Revenue concentrates in Food & Beverage; margin expansion is steepest in Nutraceuticals.
Grade:
Certification depth and transition timelines stratify supplier eligibility and price realization across retail channels.
- Organic:USDA-accredited production with 36-month transition windows, prohibiting synthetic inputs and requiring buffer zones from conventional acreage. German and Dutch supermarket chains enforce EU Green Deal-aligned regenerative documentation, expanding audit burden for North American exporters.
- Non-GMO:Identity-preserved supply chains with PCR testing protocols and segregated handling infrastructure. Mid-scale processors defer seven-figure optical sorting capex, ceding premium placement to integrated handlers with inline defect detection.
- Conventional:Standard agricultural practice with synthetic fertilizer and pesticide tolerance, occupying institutional and feed-channel volume at compressed margins.
- Specialty:Heirloom varieties, specific-origin designations, or culinary-grade specifications for ethnic retail and chef-direct procurement.
Conventional grade anchors tonnage; organic certification climbs fastest.
Packaging Type:
Channel configuration and household demographics determine format selection and distribution economics.
- Bags:Flexible retail pouches in 1-5 pound configurations for household replenishment, with single-serve modular packs gaining share in Mexico City and São Paulo urban corridors.
- Bulk Containers:Super-sacks and totes for foodservice and industrial processing, minimizing per-unit handling cost at volume thresholds above 1,000 kilograms.
- Boxes:Corrugated retail cases and institutional cartons for distributor palletization and foodservice inventory management.
- Tins:Shelf-stable metal cans for ready-to-eat and extended-shelf-life applications, facing EU F-Gas Regulation pressure on processing facility refrigeration retrofits.
Bulk Containers dominate foodservice procurement; Bags expand fastest in retail modular formats.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free-trade zones in Brazil's interior and India's western coastal corridors concentrate processing infrastructure and export consolidation for dry bean value chains. Government-backed agricultural credit programs in both nations subsidize storage silo construction and container terminal access. These spatial incentives reshape where origin handlers locate cleaning, grading, and bagging operations.
United States
Texas and California foodservice operators sustain pinto bean procurement for refried applications, while North Dakota and Minnesota prairie production supplies navy beans for institutional canners. USDA grade standards and organic certification gate retail access, forcing handlers to maintain segregated handling infrastructure. Nebraska processors deploy hyperspectral imaging systems to reduce manual grading labor and compress quality variance.
Brazil
São Paulo restaurant chains contract calibrated black bean lot sizes for feijoada formulations, driving demand for identity-preserved supply chains. ANVISA phytosanitary protocols govern incoming seed stock and processing facility inspections. Santos terminal concentration creates weather-disruption vulnerability that cascades through contracted delivery schedules to European importers.
India
Mumbai and Mundra ports absorb redirected container volumes from Canadian and Brazilian exporters following FSSAI relaxation of phytosanitary hold periods. State-led nutrition programs in Maharashtra and Gujarat expand school feeding initiatives that outstrip local processor capacity. BIS pesticide residue limits and import tolerances reshape origin eligibility for containerized pulses shipments.
Germany
Retail chains in Berlin and Hamburg enforce EU Green Deal-aligned regenerative documentation requirements that expand audit burden for North American exporters. The F-Gas Regulation restricts refrigeration gases in canning facilities, forcing retrofit investments or volume caps during peak harvest intake. Frankfurt-based procurement offices coordinate continental shelf placement for organic-grade beans.
Canada
Saskatchewan and Alberta prairie farmers face margin compression from diesel and nitrogen fertilizer price volatility tied to crude oil benchmarks. Vancouver terminal concentration creates supply chain vulnerability when weather disrupts bulk export infrastructure. The USDA Organic Cost Share Program subsidizes certification expenses for prairie cooperatives converting conventional acreage to capture premium retail placement.
Dry Beans Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists across procurement, processing, and branded retail tiers. The vendor base stratifies around grain-trading infrastructure ownership, ethnic brand strength, and backward integration into origin production. Three archetypes dominate: integrated agricultural traders with terminal assets, heritage brands with shelf-stable ethnic aisle positioning, and specialty-grade processors with captive prairie acreage. Competitive moves concentrate on optical sorting technology deployment and direct-to-foodservice platform bypass of traditional distributor markups.
Within the integrated trader tier, Cargill Incorporated and Archer Daniels Midland Company exemplify grain-trading infrastructure leverage for bulk supply contract fulfillment across North American retail chains. Goya Foods occupies a heritage-brand position anchoring shelf-stable ethnic food aisles through Hispanic grocery segment strength. AGT Food and Ingredients represents the specialty-grade archetype with backward integration into Canadian prairie production for premium lot sourcing.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill Incorporated |
| Louis Dreyfus Company |
| Olam Agri Holdings |
| Goya Foods |
| Bush Brothers & Company |
| Conagra Brands |
| AGT Food and Ingredients |
| CHS Inc. |
| Others |
Cost & Logistics Intelligence
Optical sorting technician concentrations in Nebraska and Manitoba compress labor-cost differentials between premium-grade and conventional-tier spreads. USDA organic certification timelines and EU Green Deal audit burdens widen price gaps as compliant handlers capture shelf placement premiums.
Pricing Analysis
Short lead-time premiums for certified organic lots command substantial markups over spot-market conventional inventory held at Vancouver and Santos terminals. Contract-based long-term offtake dominates procurement between North American prairie cooperatives and European retail chains, with price differentiation resting on USDA organic grade and EU regenerative documentation. Cost compression in conventional-grade channels is intensifying because diesel and nitrogen fertilizer volatility squeezes prairie farm margins. Institutional foodservice operators exhibit highest price sensitivity, while German and Dutch supermarket chains show least sensitivity given clean-label mandate compliance costs.
Supply Chain Analysis
India's FSSAI domestic-content tolerance expansions and Brazil's ANVISA phytosanitary protocols are reshaping sourcing eligibility for containerized pulses shipments. Geographic supply concentrates in Canada, Brazil, and India, with raw material dependencies on nitrogen fertilizer, diesel fuel, and certified seed stock. Single-source vulnerability at Vancouver and Santos bulk terminals cascades weather disruptions through contracted delivery schedules. Distribution runs through grain-trading infrastructure owners fulfilling retail chain contracts and direct-to-foodservice platforms bypassing traditional broker intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. The EU Green Deal Farm-to-Fork Strategy creates a 36-month organic transition barrier that compliant handlers exploit to defend margin position against conventional-grade competitors.
For Market Incumbents: Deploy hyperspectral imaging infrastructure to reduce manual grading labor and compress quality variance across origin lots. Integrate backward into certified seed production to capture premium farm-gate pricing and defend against specialty-grade processors with captive prairie acreage. Channel control through direct-to-foodservice platform ownership displaces broker intermediaries in São Paulo and Mexico City urban corridors.
For New Entrants and Emerging Players: Launch via digital procurement platforms targeting cloud kitchens in Bangalore and Jakarta with calibrated lot sizes bypassing distributor markups. Ethiopia's state-led nutrition programs offer the most penetrable white-space, where local processors lack capacity to meet institutional tender volumes. A chef-direct go-to-market angle leveraging heirloom variety specifications captures ethnic retail placement premiums.
For Investors and Strategic Acquirers: Re-rating potential sits with specialty-grade processors given EU Green Deal regenerative documentation requirements expanding audit burden for North American exporters. Long-term viability favors handlers with segregated organic handling infrastructure and identity-preserved supply chains over commodity-scale operators. Watch FSSAI import tolerance adjustments as the signal indicating container volume redirection between Brazilian, Canadian, and Australian exporters.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Seed Production | Captures premium farm-gate pricing for prairie cooperatives converting conventional acreage. |
| Hyperspectral Imaging Deployment | Compresses quality variance and reduces manual grading labor at Nebraska and Manitoba facilities. |
| Direct-to-Foodservice Platform Launch | Bypasses traditional distributor markups for São Paulo restaurant chains and Bangalore cloud kitchens. |
| EU Green Deal Compliance Certification | Maintains shelf placement in German and Dutch supermarket chains enforcing regenerative documentation. |
| Container Terminal Diversification | Mitigates weather-disruption vulnerability from Vancouver and Santos bulk export concentration. |
Research Approach
Independent corroboration across grain elevator operators, organic certification auditors, and foodservice procurement directors underwrites the qualitative findings in this study. Primary interviews with prairie cooperative managers, EU retail category buyers, and Indian port logistics coordinators combined with secondary validation from USDA grade standard filings, EU F-Gas Regulation disclosures, and FSSAI import tolerance notifications. Bottom-up volume triangulation against top-down trade flow analysis anchors the analytical framework.
Comparable historical reference periods spanning conventional-to-organic transition cycles anchored the projection horizon across the analysis window. Segmentation dimensions modeled include product type, grade certification, packaging configuration, and end-use channel, with CAGRs derived from origin production forecasts and import demand elasticity. Nitrogen fertilizer price volatility curves and diesel fuel benchmark movements fed into farm-gate margin projections.
EU F-Gas Regulation retrofit timelines, FSSAI phytosanitary hold period adjustments, and ANVISA inspection protocol changes are the dominant revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
South Africa Fruits and Vegetables Market
Fruits and Vegetables
Dried Apple Peel Market
Fruits and Vegetables
Organic Bananas Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
US Fruit Puree Market
Fruits and Vegetables
Europe Shiitake Mushroom Market
Fruits and Vegetables
Fresh Peaches Market
Fruits and Vegetables
Frozen Fruits Market
Fruits and Vegetables
Edible Flowers Market
Fruits and Vegetables
Button Mushroom Products Market
Fruits and Vegetables
Banana Flakes Market
Fruits and Vegetables
Guava Puree Market
Fruits and Vegetables
Europe Canned Fruits Market
Fruits and Vegetables
Japan Fresh Fruits Market
Fruits and Vegetables
Processed Fruits and Vegetables Market
Fruits and Vegetables
Jackfruit Market