
 Europe Canned Fruits Market | 2026-2036
Europe Canned Fruits Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Canned Fruits Market Foresight
Multi-pack and portion-controlled bundling is broadening buyer choice across retail and food service channels in the Europe canned fruits sector. Greenyard NV leverages its integrated sourcing network from Southern European growers to sustain year-round supply reliability. Del Monte Foods Holdings Limited anchors its position through brand recognition in supermarket canned fruit aisles. Bonduelle Group differentiates via specialization in organic and no-added-sugar recipes that command premium shelf placement.
Europe canned fruits comprise thermally processed whole, sliced, or chunked fruit preserved in syrup, juice, or water within hermetically sealed containers, with pH typically below 4.6 to ensure commercial sterility and shelf stability extending 24–36 months unrefrigerated. These products serve retail households, industrial food manufacturers, and food service operators requiring consistent fruit quality independent of harvest seasonality. Peaches and pears occupy mature volume positions sustained by established consumer habit and baking-sector demand, while pineapples represent the fastest-growing product type driven by tropical flavor trends in dairy and dessert applications. Glass jars capture margin pools in premium retail segments where visual product appeal influences purchase, whereas metal cans dominate institutional and value-oriented channels where unit cost and logistics efficiency matter most.
EU Green Deal packaging rules, EFSA food contact material standards, and national implementations of the EU Single-Use Plastics Directive collectively shape permissible container formats and recyclability claims across member states. REACH compliance for coating chemicals inside metal cans and forthcoming CSRD sustainability reporting obligations add compliance layers that favor scaled producers with dedicated regulatory affairs capacity. Stakeholders must monitor how deposit-return scheme expansions in France, Germany, and the Netherlands alter cost structures for glass and metal packaging formats.
Market Dynamics
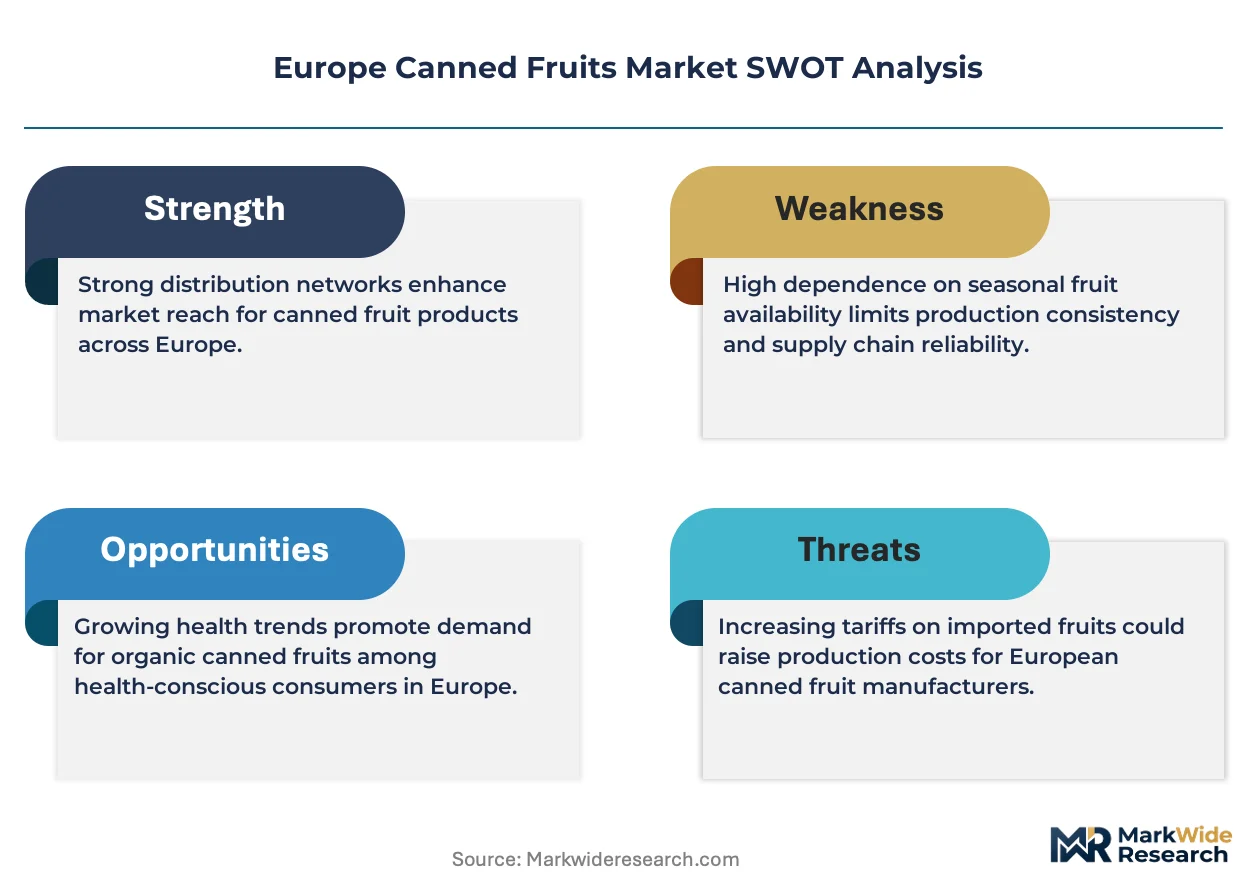
EU Green Deal packaging mandates are forcing rapid container format transitions across European canned fruit supply chains, with deposit-return scheme expansions in France, Germany, and the Netherlands recalibrating cost structures for metal and glass formats.
Growth Catalysts
- EU Single-Use Plastics Directive:National implementations in France and the Netherlands are accelerating demand for recyclable metal and glass alternatives, expanding shelf space for compliant formats.
- Food service procurement:Institutional catering contracts across German hospitals and school systems are anchoring volume for portion-controlled peach and pear SKUs.
- Tropical flavor migration:Pineapple demand in dairy and dessert applications is displacing traditional stone fruit in industrial ingredient sourcing.
Market Restraints
- Steel and tinplate volatility:Input cost swings for metal can substrates compress margin stability for mid-tier producers without long-term supplier agreements.
- Southern European sourcing concentration:Greek and Spanish peach growers supply the majority of raw material, creating harvest-weather exposure.
- Fresh fruit substitution:Extended cold chain reach in Northern Europe enables year-round fresh pineapple availability, pressuring canned equivalents in retail.
Strategic Opportunities
- Polish retail underpenetration:Private-label canned fruit shelf space remains below Western European density, offering first-mover positioning for compliant formats.
- Organic certification tailwind:EU organic regulation updates are expanding premium placement eligibility for no-added-sugar recipes.
- E-commerce bundling:Multi-pack configurations for home delivery platforms are capturing pantry-stocking behavior absent in traditional retail.
Industry Challenges
- CSRD reporting readiness:Scaled producers must build dedicated sustainability data infrastructure to meet forthcoming corporate disclosure timelines.
- REACH coating compliance:BPA-alternative interior can lining transitions require reformulation cycles that strain R&D bandwidth.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Canned Fruits Market |
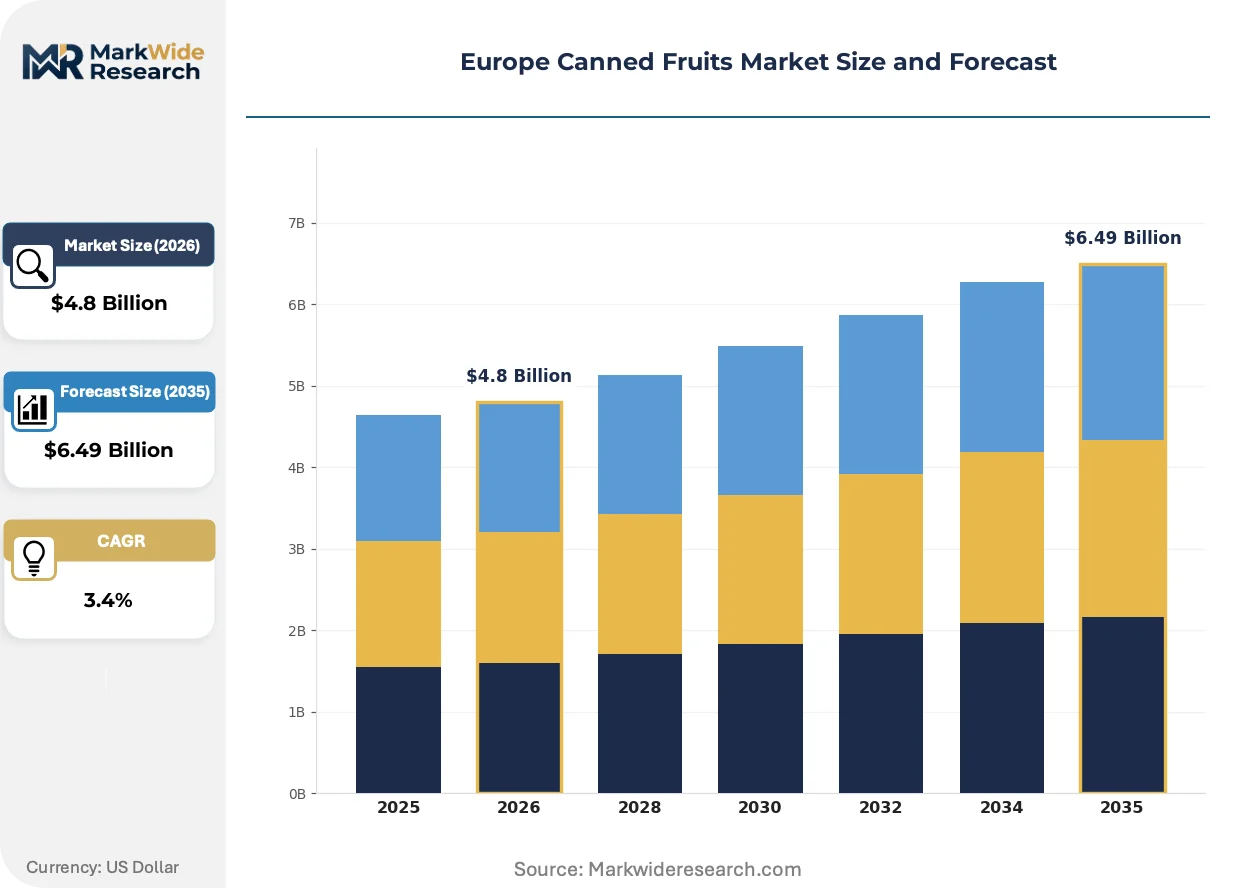
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.49 Billion |
| CAGR (2026 – 2036) | 3.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Peaches, Pears, Pineapples, Cherries Packaging Type: Glass Jars, Metal Cans, Tetra Packs, Flexible Pouches Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale End User: Food Service, Retailers, Food Manufacturers, Households |
| Companies Covered | Greenyard NV, Oregon Fruit Products, Dole, Rhodes Food Group, CHB Group, Del Monte Foods Holdings Limited, RFG Holdings Limited, Bonduelle Group, The Kraft Heinz Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Canned Fruits Market Shifts & Advancements
Active reshaping in the Europe canned fruits sector centers on thermal processing optimization, regulatory-driven material transitions, and procurement model compression across food service channels.
High-pressure processing adjuncts to traditional thermal sterilization are integrating into premium line configurations. German private-label manufacturers are adopting these hybrid systems to reduce thermal degradation in organic peach segments. The technology is integrating shorter cook times with extended shelf stability, compressing quality differentiation timelines between mass and specialty tiers.
EFSA food contact material standards revisions are tightening migration limits for epoxy-based can coatings. Industrial consequence includes accelerated supplier qualification cycles for BPA-non-intent alternatives. Glass jar formats in French premium retail are capturing displaced metal-can volume as brands preempt compliance uncertainty.
Food service operators are consolidating ingredient procurement through centralized purchasing cooperatives. German hospital networks and Dutch institutional caterers are displacing fragmented supplier relationships with multi-year single-source contracts. This concentration is most visible in Rhineland-Palatinate and Baden-Württemberg, where regional purchasing alliances now specify syrup-solid ratios and origin documentation as contract terms.
Europe Canned Fruits Market Segmentation
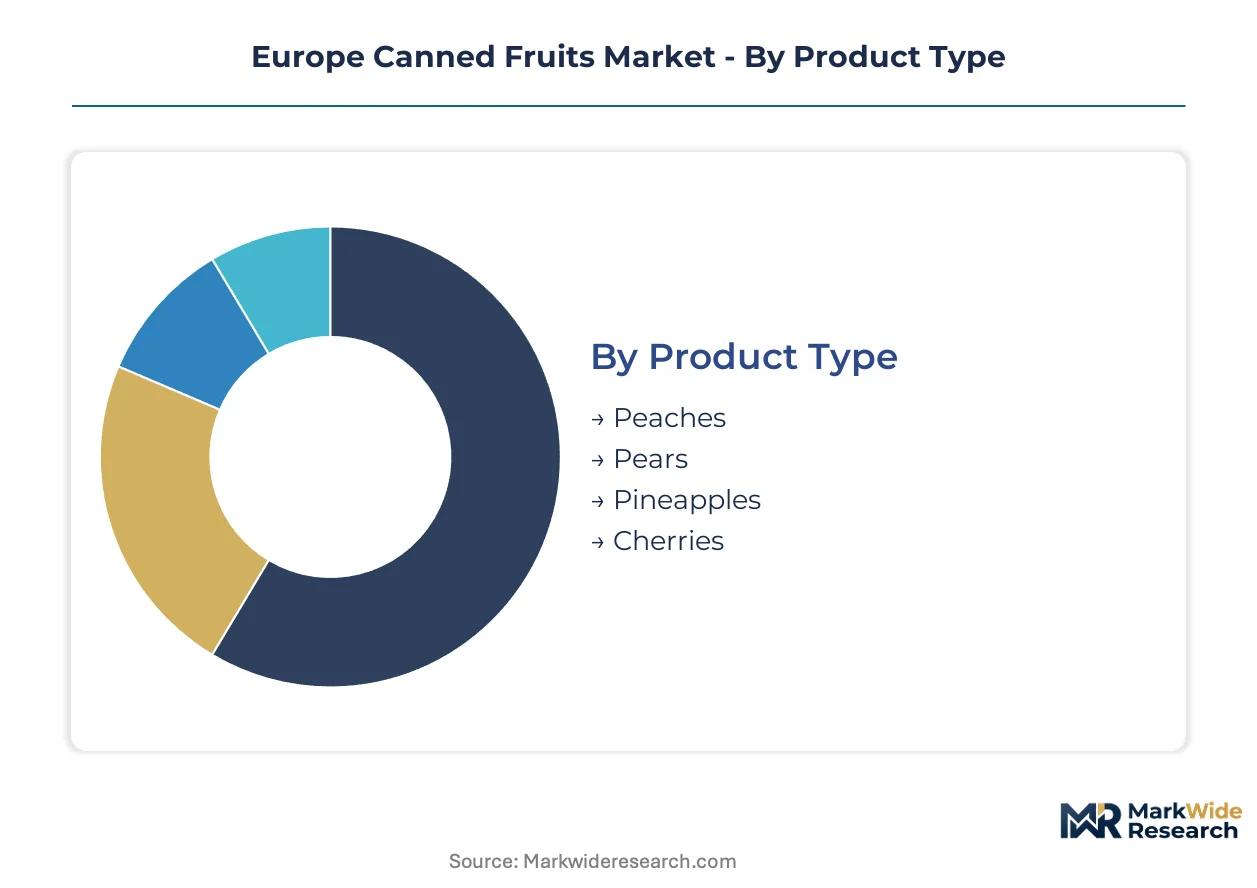
Segmentation in the Europe canned fruits market reveals how procurement patterns and format preferences diverge across retail, food service, and industrial channels. Understanding these splits enables suppliers to align thermal processing configurations and packaging investments with specific buyer requirements.
Product Type:
Consumer upgrade cycles in canned fruits follow shifting dessert and dairy application trends, with traditional stone fruit facing displacement from tropical alternatives in industrial formulations.
- Peaches:Freestone and clingstone varieties preserved in light syrup or juice dominate German retail private-label programs and institutional catering contracts. Rhineland-Palatinate hospital networks specify origin documentation and syrup-solid ratios as mandatory tender terms, anchoring volume for Greek and Spanish growers.
- Pineapples:Sliced and chunked formats in juice or light syrup are displacing traditional stone fruit in dairy and dessert ingredient sourcing across Northern European food manufacturers. German and Dutch industrial buyers prioritize year-round supply reliability over harvest-season fresh equivalence, though extended cold chain reach in Scandinavia pressures retail shelf positioning.
- Pears:Bartlett and Conference varieties in halved or diced formats serve established baking-sector demand in France and Belgium, with organic certification expanding premium placement eligibility under updated EU organic regulation.
- Cherries:Pitted sour varieties in syrup target dessert topping applications and pastry manufacturing in Austria and Switzerland, where visual product appeal influences industrial procurement decisions.
Peaches sit at the top of the volume ranking, with pineapples climbing the fastest.
Packaging Type:
Cost tier differentiation in packaging formats separates premium retail positioning from institutional logistics efficiency, with regulatory pressure accelerating format transitions.
- Metal Cans:Tinplate and aluminum formats dominate institutional and value-oriented channels where unit cost and logistics efficiency matter most. REACH compliance for BPA-alternative interior linings requires reformulation cycles that strain R&D bandwidth for mid-tier producers without dedicated regulatory affairs capacity.
- Glass Jars:Transparent formats capture margin pools in premium retail segments where visual product appeal influences purchase decisions, with French supermarkets expanding shelf space as brands preempt EFSA food contact material uncertainty.
- Tetra Packs:Aseptic carton formats serve portion-controlled food service and school catering contracts in the Netherlands, where deposit-return scheme expansions recalibrate cost structures against metal alternatives.
- Flexible Pouches:Stand-up and spouted formats target convenience-oriented retail and outdoor recreation channels in Nordic markets, though thermal processing constraints limit application to high-acid fruit preparations.
Metal cans command the largest installed base, while glass jars gain share fastest in premium retail.
Distribution Channel:
Application-specific procurement patterns separate pantry-stocking households from just-in-time food service operators, with channel mix determining pack size and bundling configurations.
- Supermarkets:Multi-pack and portion-controlled bundling broadens buyer choice across German and French retail private-label programs, where shelf space allocation favors compliant recyclable formats under EU Green Deal mandates.
- Online Retail:E-commerce bundling configurations for home delivery platforms capture pantry-stocking behavior absent in traditional retail, with Polish market underpenetration offering first-mover positioning for compliant format suppliers.
- Wholesale:Centralized purchasing cooperatives for German hospital networks and Dutch institutional caterers displace fragmented supplier relationships with multi-year single-source contracts specifying technical parameters.
- Convenience Stores:Single-serve and impulse-oriented pack sizes serve urban transit corridors and fuel station retail in Benelux markets, where space constraints favor shelf-stable over fresh alternatives.
Supermarkets anchor volume concentration, with online retail expanding most quickly in multi-pack configurations.
End User:
Customer type determines specification stringency, with food service operators imposing stricter origin documentation and syrup-solid ratio requirements than retail households.
- Food Service:Institutional catering contracts across German hospitals and school systems anchor volume for portion-controlled peach and pear SKUs, with regional purchasing alliances in Baden-Württemberg consolidating procurement through centralized cooperatives.
- Food Manufacturers:Industrial ingredient sourcing for dairy and dessert applications drives pineapple demand displacement of traditional stone fruit, with thermal processing specifications varying by end-product pasteurization requirements.
- Retailers:Private-label program operators in Germany and France negotiate year-round supply reliability through integrated sourcing networks from Southern European growers, with organic and no-added-sugar recipes commanding premium shelf placement.
- Households:Pantry-stocking behavior for baking and dessert preparation sustains mature demand for peaches and pears, though fresh fruit substitution pressures canned equivalents where cold chain infrastructure extends.
Food service commands the most stringent specification requirements, with food manufacturers showing the steepest expansion trajectory in tropical fruit sourcing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The European canned fruits industry traces its modern scale to post-war preservation cooperatives in Southern Europe, where Greek and Spanish peach growers established the continent's primary sourcing basins that still supply German and French buyers today.
Germany
Private-label retail programs and institutional catering contracts anchor continental volume demand. The EU Green Deal's packaging sustainability mandates pressure domestic distributors toward recyclable metal and glass formats. Rhineland-Palatinate and Baden-Württemberg host regional purchasing alliances that consolidate hospital and school procurement through multi-year single-source agreements.
France
Premium retail segments drive glass jar adoption where visual product appeal influences purchase decisions. EFSA food contact material standards revisions tighten migration limits for epoxy-based can coatings, accelerating format transitions. Supermarket chains in Île-de-France expand shelf space for compliant alternatives as brands preempt regulatory uncertainty.
Netherlands
Portion-controlled food service contracts for school catering sustain aseptic carton demand. National deposit-return scheme expansions recalibrate cost structures for metal and glass packaging against Tetra Pak alternatives. Rotterdam's logistics hub facilitates just-in-time distribution to institutional buyers across the Benelux corridor.
Spain
Clingstone and freestone peach cultivation in Murcia and Aragón supplies raw material for Northern European processors. REACH compliance requirements for BPA-alternative can linings strain mid-tier producers without dedicated regulatory affairs capacity. Catalan packaging specialists develop hybrid thermal processing systems for organic segment differentiation.
Poland
Private-label canned fruit shelf space remains below Western European density, offering first-mover positioning for compliant format suppliers. EU organic regulation updates expand premium placement eligibility for no-added-sugar recipes. Warsaw-based retail distributors negotiate e-commerce bundling configurations for home delivery platforms.
Europe Canned Fruits Market Competitive Landscape
Premium-margin players sit above commodity-margin players across packaging format and certification tiers, with glass jar and organic specialists commanding shelf placement advantages over standard metal-can suppliers. The vendor base clusters around three strategic archetypes: integrated growers with captive Southern European sourcing, brand-anchored multinationals with retail aisle dominance, and private-label manufacturers serving discounter channels. Competitive moves concentrate on M&A for sourcing security and portfolio diversification into no-added-sugar and organic recipes.
Within the integrated sourcing tier, Greenyard NV and Del Monte Foods Holdings Limited exemplify contrasting scale models, while Bonduelle Group occupies a specialization position in organic and reduced-sugar formulations. Greenyard NV leverages its grower network visibility for year-round supply reliability. Del Monte Foods Holdings Limited anchors brand recognition in supermarket canned fruit aisles. Bonduelle Group differentiates through recipe innovation that commands premium shelf placement under evolving EU organic standards.
| Leading Market Players |
|---|
| Greenyard NV |
| Oregon Fruit Products |
| Dole |
| Rhodes Food Group |
| CHB Group |
| Del Monte Foods Holdings Limited |
| RFG Holdings Limited |
| Bonduelle Group |
| The Kraft Heinz Company |
| Others |
Supply & Pricing Matrix
Hybrid thermal processing adoption in German organic peach manufacturing simultaneously compresses quality differentiation timelines and concentrates cost advantages among scaled producers with dedicated R&D infrastructure. This technology shift reshapes margin pools across premium and mass tiers while reinforcing procurement leverage for buyers with multi-year volume commitments.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates glass jar organic certification from metal can conventional recipes from private-label economy SKUs. Price differentiation hinges on EU organic regulation compliance and syrup-solid ratio specifications, with REACH coating compliance costs intensifying margin pressure in mid-tier metal can segments. German hospital networks exhibit lowest price sensitivity due to specification stringency, while Polish retail distributors show highest sensitivity driven by shelf space competition.
Supply Chain Analysis
Deposit-return scheme expansions in France, Germany, and the Netherlands are recalibrating reverse-logistics cost structures for metal and glass packaging formats. Raw material sourcing draws from Greek and Spanish peach cultivation regions, with tinplate substrate and BPA-alternative interior linings as critical component dependencies. Single-source vulnerability concentrates in Southern European harvest-weather exposure. Distribution runs through Rotterdam's logistics hub for just-in-time institutional delivery across the Benelux corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European canned fruits rests on BPA-alternative coating transitions that unlock premium shelf placement and compliance-driven format shifts that capture displaced metal-can volume.
For Market Incumbents: Hedge against fresh fruit substitution by securing multi-year supply agreements with Rhineland-Palatinate hospital networks and Baden-Württemberg school systems. Deepen backward integration into Southern European grower cooperatives to anchor year-round supply reliability against harvest-weather volatility. Prioritize CSRD reporting infrastructure investment to meet sustainability disclosure timelines ahead of mid-tier competitors. For New Entrants and Emerging Players: Launch via e-commerce bundling configurations targeting Polish home delivery platforms where private-label shelf space remains below Western European density. Exploit organic certification tailwinds under updated EU organic regulation to command premium placement in French supermarket chains. Position no-added-sugar recipes as first-mover compliant formats in underpenetrated Central European retail. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier metal-can producers without dedicated regulatory affairs capacity, creating acquisition targets for consolidation plays. Long-term viability favors integrated sourcing networks with captive Southern European grower relationships and glass jar manufacturing capabilities. Monitor EFSA food contact material standards revisions as inflection signal for accelerated format transition timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Organic Certification Expansion | EU organic regulation updates unlock premium shelf placement eligibility for no-added-sugar recipes in French retail. |
| Glass Jar Format Transition | EFSA coating uncertainty accelerates metal-to-glass volume capture in premium segments across Île-de-France supermarkets. |
| Food Service Procurement Consolidation | German hospital networks displace fragmented suppliers with multi-year single-source contracts specifying syrup-solid ratios. |
| BPA-Alternative Coating Reformulation | REACH compliance cycles strain R&D bandwidth for mid-tier producers without dedicated regulatory infrastructure. |
| E-Commerce Multi-Pack Bundling | Polish retail underpenetration offers first-mover positioning for compliant format suppliers on home delivery platforms. |
Research Methodology
Coverage spans Germany, France, Netherlands, Spain, and Poland, with primary inputs from each market gathered through interviews with category buyers at retail chains, procurement directors at institutional catering cooperatives, regulatory affairs managers at canning facilities, and supply planners at food manufacturing operations. Secondary validation draws from EU trade statistics, EFSA food contact material guidance documents, national packaging registry filings, and customs data on fruit concentrate imports. Bottom-up SKU-level volume builds triangulate against top-down category spend estimates from retail audit databases.
Granularity-level modeling disaggregates volume and value across product type, packaging format, distribution channel, and end user segments throughout the forecast period. CAGRs derive from segment-level growth rate reconciliation against macroeconomic consumption indicators and regulatory implementation timelines. Industry-specific forecast inputs include EU Green Deal packaging mandate compliance schedules and deposit-return scheme expansion trajectories across member states.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended cold chain infrastructure buildout in Northern Europe and accelerated fresh fruit substitution patterns. Practitioners should monitor EFSA epoxy coating migration limit revisions and CSRD disclosure timeline clarifications for early signals of format transition acceleration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Date Fruit Market
Fruits and Vegetables
Tropical Fruit Puree Market
Fruits and Vegetables
Vaccinium Myrtillus Market
Fruits and Vegetables
Avocado-Based Products Market
Fruits and Vegetables
Europe Stone Fruits Market
Fruits and Vegetables
Saudi Arabia Fruits and Vegetables Market
Fruits and Vegetables
Celery Juice Market
Fruits and Vegetables
Butterfly Pea Flowers Market
Fruits and Vegetables
Red Berries Market
Fruits and Vegetables
Middle East and Africa Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Lemon Juice Concentrate Market
Fruits and Vegetables
Tunisia Fruit and Vegetable Market
Fruits and Vegetables
Global Jalapeno Pepper Market
Fruits and Vegetables
Jicama Market
Fruits and Vegetables
Saudi Arabia Fruit Concentrate Market
Fruits and Vegetables
Spain Table Grape Market