
 Global Fracking Fluids and Chemicals Market | 2026-2036
Global Fracking Fluids and Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fracking Fluids and Chemicals Market Foresight
The capital-intensity divergence between integrated service providers and specialty chemical suppliers is rotating competitive advantage toward firms with captive manufacturing infrastructure. Halliburton Company leverages its vertical integration across pumping services and fluid chemistry to control input costs and deployment timelines. Dow Inc. anchors its position through large-scale polymer production that supplies gelling agents and friction reducers to multiple service tiers. Baker Hughes Company differentiates via digital fluid monitoring systems paired with proprietary chemical packages.
Fracking fluids and chemicals constitute engineered liquid and additive systems designed to create and propagate fractures in hydrocarbon-bearing rock formations, typically operating at pressures exceeding ten thousand psi and temperatures surpassing one hundred fifty degrees Celsius. These formulations primarily enable the extraction of trapped oil and gas by reducing friction, preventing corrosion, and transporting proppant into created fractures. Gelling agents and crosslinkers command substantial margin pools due to their technical complexity and performance-critical role in high-viscosity fracturing designs. Slickwater fracturing dominates application volumes in North American shale plays, while foam fracturing is gaining traction in water-scarce regions where liquid minimization carries operational and regulatory weight.
The EPA's underground injection control program and OSHA's hazard communication standards govern fluid composition disclosure and worker exposure limits across United States operations, compelling reformulation investments. REACH registration requirements in Europe restrict certain biocide chemistries from cross-border supply chains, fragmenting product availability by jurisdiction. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized chemical manufacturing or regional blending assets offer superior risk-adjusted returns.
Market Dynamics
The EPA's updated underground injection control standards are forcing operators to reformulate fluid systems with reduced toxicity profiles, compressing margins for legacy chemical suppliers while rewarding firms with captive R&D infrastructure.
Growth Catalysts
- Extended lateral drilling:Unconventional shale operators in the Permian Basin and Bakken formation are expanding chemical consumption as lateral lengths extend beyond fifteen thousand feet.
- REACH registration pathways:European chemical suppliers leveraging REACH-compliant biocide chemistries are capturing cross-border supply chain share previously held by non-registered competitors.
- Foam fracturing adoption:Water-scarce regions in the Middle East and Australia are deploying foam fracturing systems to minimize liquid volumes and satisfy local environmental constraints.
Market Restraints
- Guar gum price volatility:Gelling agent costs fluctuate with Indian monsoon patterns and agricultural commodity cycles, destabilizing input cost structures for fracturing fluid blenders.
- Specialty chemical supply concentration:Crosslinker and breaker manufacturing clusters in the US Gulf Coast and China's Sichuan province create geographic concentration risk for global supply security.
- Biocide substitution limits:Glutaraldehyde-based microbicides face displacement pressure from peracetic acid alternatives, though performance gaps in high-temperature formations restrict rapid substitution.
Strategic Opportunities
- Argentina Vaca Muerta development:Underpenetrated shale acreage in Neuquén province offers greenfield chemical demand as international operators deploy North American completion designs.
- Digital fluid monitoring convergence:Integration of real-time pressure-temperature sensors with automated chemical injection systems is creating premium service tiers for technology-enabled suppliers.
- EU Green Deal chemistry incentives:REACH-registered bio-based friction reducers qualify for green procurement preferences in European unconventional gas pilot projects.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in high-pressure high-temperature fluid design remains concentrated among retiring professionals in Houston and Calgary service company laboratories.
- EPA disclosure timeline compression:Accelerated chemical composition reporting deadlines under updated UIC standards strain legacy documentation systems and require IT infrastructure investment.
- Proppant-chemical compatibility testing:Extended certification cycles for new fluid systems with regional sand and ceramic proppant varieties delay field deployment and revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fracking Fluids and Chemicals Market |
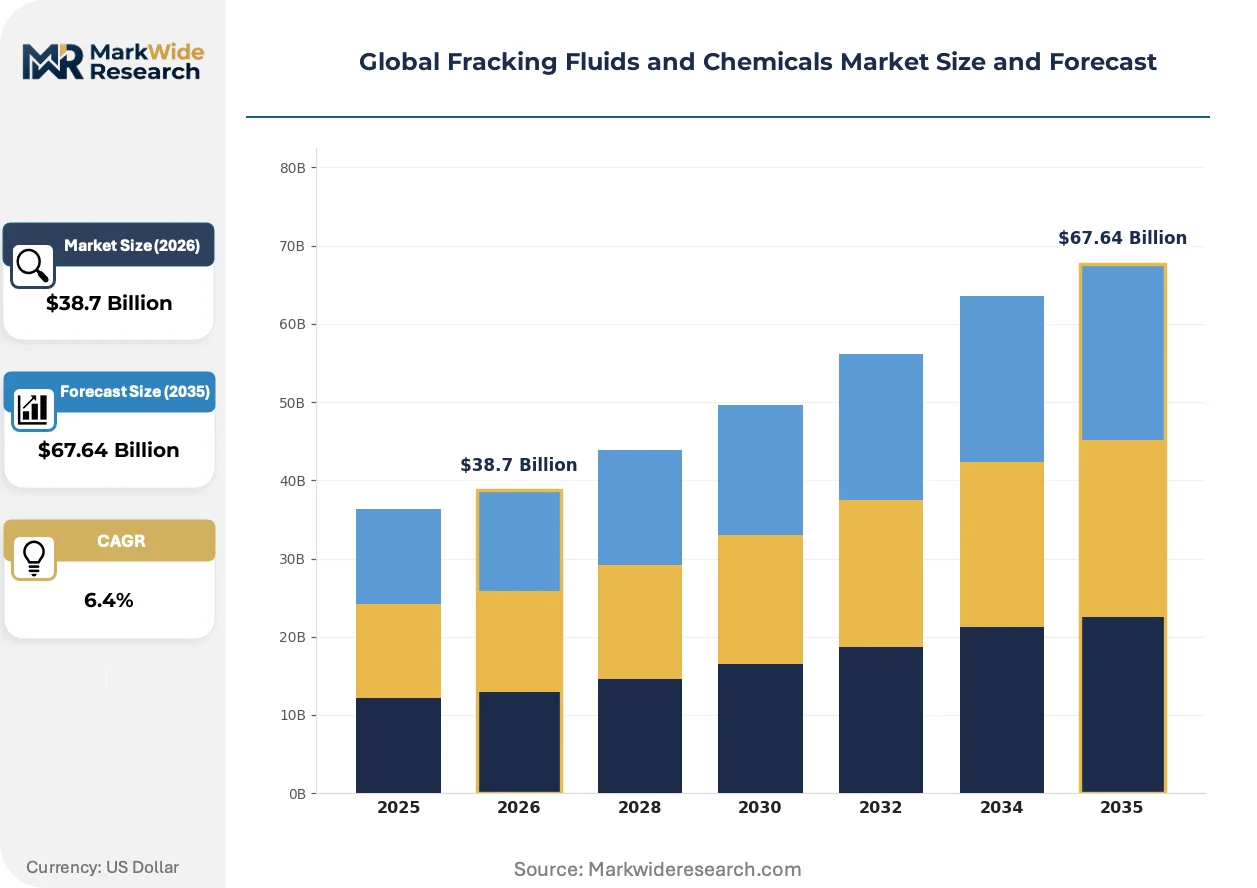
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acidizing Fluids, Gelling Agents, Scale Inhibitors, Surfactants, Crosslinkers, Biocides Technology: Hydraulic Fracturing, Slickwater Fracturing, Gel Fracturing, Foam Fracturing, Carbon Dioxide Fracturing, Nitrogen Fracturing Application: Shale Gas Extraction, Tight Gas Recovery, Coalbed Methane Production, Enhanced Oil Recovery, Tight Oil Exploitation, Geothermal Energy End User: Exploration & Production Companies, Oilfield Service Firms, Energy Consultants, Petroleum Contractors |
| Companies Covered | Weatherford International plc, Dow Inc., Halliburton Company, Solvay S.A., Ecolab Inc., Schlumberger Limited, BASF SE, Kemira Oyj, Baker Hughes Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fracking Fluids and Chemicals Market Shifts & Advancements
Polymer chemistry advances and digital field monitoring are compressing the traditional service-company-chemical-supplier boundary, creating hybrid competitors that control both formulation intellectual property and real-time downhole data.
Hybrid polyacrylamide-polyacrylate friction reducers are displacing conventional high-molecular-weight polyacrylamides in Permian Basin slickwater designs. Operators adopting these materials report reduced pumping horsepower requirements and lower surface equipment wear. The structural consequence is margin compression for commodity friction reducer suppliers unable to license or synthesize hybrid polymer architectures.
REACH authorization restrictions on quaternary ammonium biocides are compelling European operators to source alternative microbicide packages from North American and Asian suppliers. Industrial consequence includes fragmentation of previously standardized chemical specifications across the EU unconventional gas sector. Shale developers in Poland and Romania are most affected, responding with dual-qualified supply contracts spanning Atlantic and Pacific sourcing corridors.
Integrated service contracts bundling chemicals, pumping equipment, and digital monitoring are displacing discrete chemical procurement by large independent producers. Major Permian and DJ Basin operators are consolidating vendor relationships to capture volume discounts and simplify logistics coordination. This consolidation pattern is most visible among super-independent producers with multi-rig development programs in Texas and Colorado.
Global Fracking Fluids and Chemicals Market Segmentation
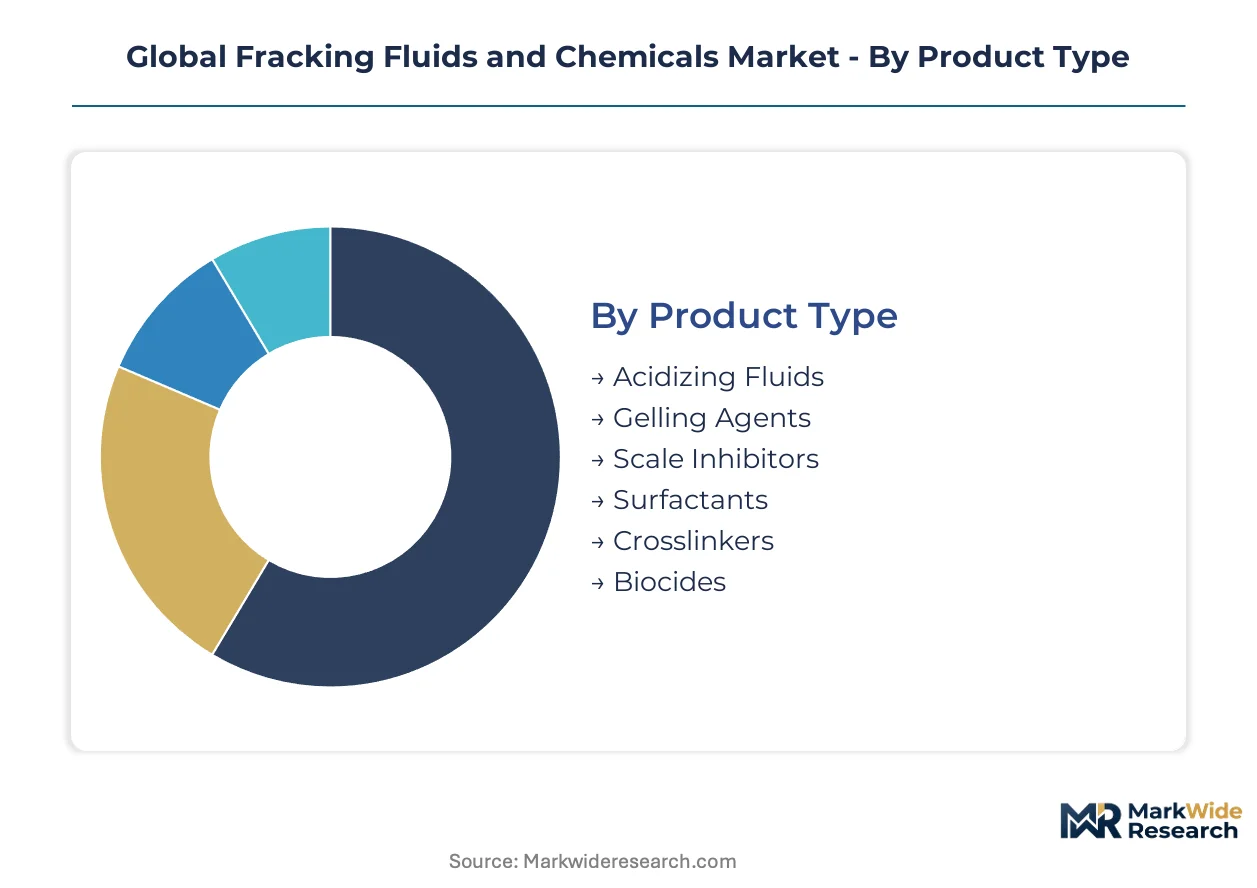
Segmentation in fracking fluids reveals where formulation complexity concentrates margin pools and where commoditization erodes supplier power. Understanding these fault lines enables targeted positioning across technology tiers and customer procurement sophistication levels.
Product Type:
Substitution pressure from bio-based alternatives and regulatory-driven reformulation targets gelling agents and biocides most aggressively, while scale inhibitors and surfactants face milder displacement threats due to performance-critical specifications.
- Gelling Agents:Guar gum derivatives and synthetic polymer viscosifiers form the backbone of crosslinked gel systems, with molecular weight distributions tailored to bottom-hole temperature conditions. Permian Basin operators consume the largest volumes as extended-reach laterals demand higher polymer loadings to suspend proppant over 15,000-foot distances.
- Biocides:Glutaraldehyde-based microbicides and quaternary ammonium compounds prevent sulfate-reducing bacteria proliferation in water-based fluids. REACH authorization restrictions in Europe are fragmenting supply chains, forcing Polish and Romanian shale developers to dual-source from North American and Asian suppliers.
- Crosslinkers:Borate and zirconium complexes activate gelling agents at controlled pH thresholds.
- Surfactants:Anionic and non-ionic formulations reduce surface tension for improved fluid recovery.
- Scale Inhibitors:Phosphonate and polymer chemistries prevent barium sulfate and calcium carbonate precipitation in production tubing.
- Acidizing Fluids:Hydrochloric acid blends with corrosion inhibitors dissolve formation damage near wellbore zones.
Gelling agents retain volume leadership; biocides hold the steepest expansion curve as regulatory reformulation drives specification turnover.
Technology:
Cost tier stratification separates high-volume slickwater deployments from premium gel and foam systems where chemistry complexity commands pricing power.
- Slickwater Fracturing:Low-viscosity water-based fluids with friction reducers dominate North American shale plays, enabling high-rate pumping through reduced horsepower requirements. Permian Basin operators have adopted hybrid polyacrylamide-polyacrylate friction reducers that cut surface equipment wear.
- Foam Fracturing:Nitrogen or carbon dioxide energized systems minimize liquid volumes for water-scarce formations. Australian Cooper Basin and Middle Eastern unconventional pilots deploy these systems to satisfy local environmental constraints and reduce produced water handling costs.
- Hydraulic Fracturing:Conventional high-pressure fluid injection remains the baseline category across most geographies.
- Gel Fracturing:Crosslinked polymer systems target formations requiring proppant suspension in complex fracture geometries.
- Carbon Dioxide Fracturing:Supercritical CO2 systems eliminate water entirely for water-sensitive formations.
- Nitrogen Fracturing:Gas-assisted delivery for underpressured reservoirs where liquid loading risks production impairment.
Slickwater fracturing captures the largest share of completion stage counts; foam fracturing is climbing the fastest as arid-region development accelerates.
Application:
Application maturity varies sharply, with shale gas and tight oil representing proven demand centers while geothermal energy presents nascent specification development challenges.
- Shale Gas Extraction:Multi-stage horizontal completions in organic-rich source rocks consume the highest chemical volumes per well, with fluid systems optimized for clay stabilization and proppant transport in low-permeability matrix. Marcellus and Haynesville operators drive consistent demand for standardized slickwater packages.
- Tight Oil Exploitation:Liquid-rich shale formations in the Bakken and Eagle Ford require tailored surfactant packages to maximize oil relative permeability and minimize formation damage from water blockage.
- Tight Gas Recovery:Sandstone and carbonate formations with sub-microdarcy permeability.
- Coalbed Methane Production:Shallow, low-pressure reservoirs requiring minimal fracture complexity.
- Enhanced Oil Recovery:Chemical flooding and conformance control in mature fields.
- Geothermal Energy:High-temperature stimulation for enhanced geothermal systems, with fluid stability requirements exceeding 200°C.
Shale gas extraction anchors current demand; tight oil exploitation is gaining share fastest as liquid-rich windows expand drilling inventories.
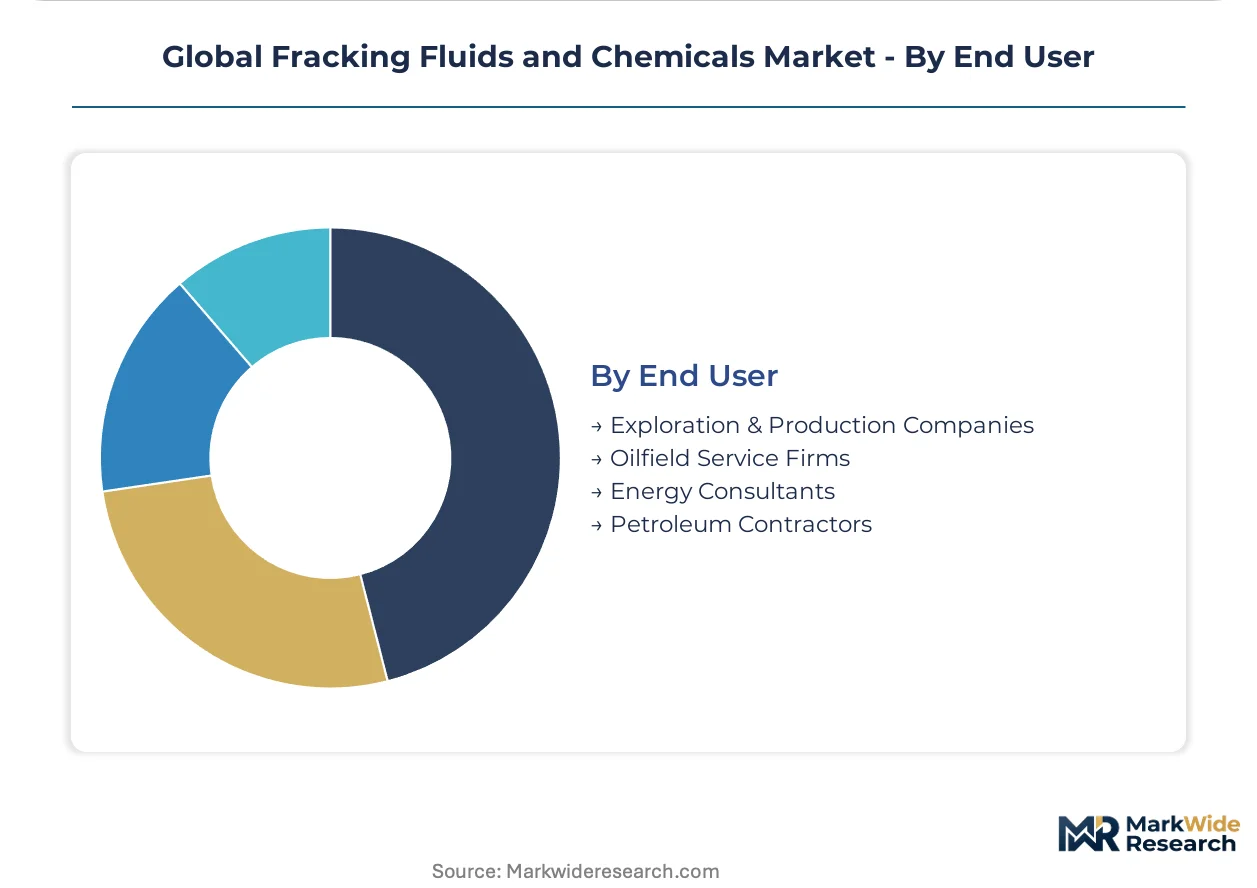
End User:
Customer type determines procurement sophistication, with integrated service firms bundling chemicals into performance contracts while independent producers maintain discrete supplier relationships.
- Oilfield Service Firms:Halliburton, Baker Hughes, and Schlumberger operate captive blending facilities and formulation laboratories, sourcing base chemicals at scale while differentiating through proprietary additive packages. These firms capture margin through integrated service contracts that bundle pumping equipment, chemicals, and real-time monitoring.
- Exploration & Production Companies:Super-independent producers in Texas and Colorado consolidate vendor relationships to capture volume discounts and simplify logistics coordination across multi-rig development programs.
- Petroleum Contractors:Regional completion specialists with project-based chemical procurement.
- Energy Consultants:Advisory firms influencing fluid selection through technical specification development.
Oilfield service firms retain volume leadership; exploration and production companies are expanding direct procurement fastest as in-house technical capabilities deepen.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in the United States demonstrate the lowest price elasticity as super-basin operators prioritize performance over cost, while Chinese shale developers remain acutely sensitive to chemical pricing amid capital discipline mandates. European procurement sits between these extremes, balancing REACH compliance costs against operational efficiency targets.
United States
Permian Basin operators in Texas and New Mexico consume the highest fracturing chemical volumes globally as lateral lengths exceed fifteen thousand feet. EPA underground injection control standards compel reformulation investments toward reduced-toxicity fluid systems. Houston hosts the densest concentration of formulation laboratories and captive blending facilities, where Halliburton and Baker Hughes operate integrated service hubs.
China
Sinopec and PetroChina are expanding shale gas development in the Sichuan Basin, driving demand for high-temperature stable friction reducers. MEE environmental standards restrict certain biocide chemistries in surface water protection zones. Chengdu and Chongqing anchor the domestic supply chain, with regional blenders sourcing base polymers from Yangtze River Delta petrochemical complexes.
Argentina
Vaca Muerta formation development in Neuquén province is attracting international operators deploying North American completion designs. The country's national hydrocarbons regulator enforces chemical disclosure requirements for unconventional operations. YPF and international joint ventures in the Neuquén industrial corridor are establishing localized blending capacity to reduce import dependency.
Saudi Arabia
Aramco is piloting foam fracturing systems in tight gas reservoirs to minimize liquid volumes in water-scarce regions. SFDA chemical registration pathways govern biocide and surfactant imports for oilfield applications. Dhahran and the Eastern Province host the kingdom's primary stimulation chemical storage and blending infrastructure.
Australia
Cooper Basin operators are adopting foam fracturing to satisfy environmental constraints on water consumption in arid regions. The country's national chemical regulator adminishes agricultural and industrial chemical standards affecting biocide approvals. Adelaide and Brisbane serve as distribution nodes for Asia-Pacific sourced friction reducers and gelling agents.
Global Fracking Fluids and Chemicals Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with Halliburton and Schlumberger commanding bundled service contracts while pure-play chemical suppliers compete on formulation differentiation. The structure rewards backward integration into polymer manufacturing and captive R&D infrastructure. Three archetypes dominate: vertically integrated service companies, commodity polymer suppliers, and specialty additive specialists. Consolidation pressure is driving M&A activity among mid-cap blenders, while technology licensing agreements proliferate between European chemical houses and North American service firms.
Among integrated service providers, Halliburton Company and Baker Hughes Company exemplify the bundled-offering archetype, combining pumping equipment with proprietary fluid systems. Dow Inc. and BASF SE occupy positions as large-scale polymer suppliers, anchoring supply relationships across multiple service tiers. Solvay S.A. and Kemira Oyj represent specialty chemical specialists with focused portfolios in high-performance additives. These groupings illustrate how competitive positioning stratifies between those controlling formulation intellectual property and those manufacturing base chemistries at scale.
| Leading Market Players |
|---|
| Weatherford International plc |
| Dow Inc. |
| Halliburton Company |
| Solvay S.A. |
| Ecolab Inc. |
| Schlumberger Limited |
| BASF SE |
| Kemira Oyj |
| Baker Hughes Company |
| Others |
Supply & Pricing Matrix
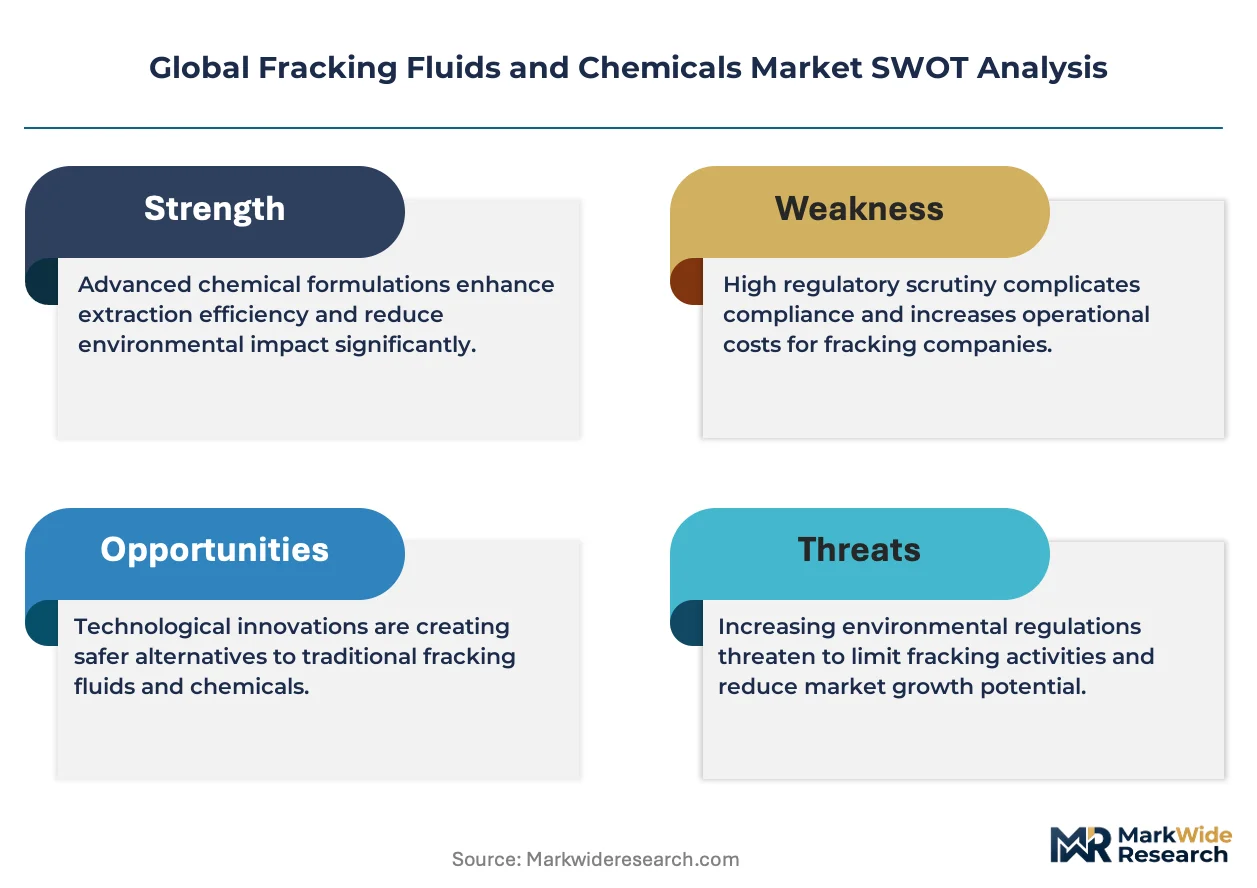
EPA underground injection control standards gate both chemical supplier qualification and price differentiation simultaneously, forcing reformulation investments that stratify pricing tiers between REACH-registered biocide packages and legacy formulations facing displacement pressure.
Pricing Analysis
Extended service contracts bundling real-time fluid monitoring with chemical supply drive lifetime value for integrated service providers. Three-tier pricing structure across premium, standard, and economy levels separates digital-enabled packages from commodity friction reducers and basic gel systems. Cost compression in commodity biocides intensifies because REACH authorization restrictions fragment European supply chains. Independent producers in Texas and Colorado demonstrate lowest price sensitivity, while Chinese shale developers remain most reactive to chemical pricing fluctuations.
Supply Chain Analysis
The United States and China anchor global production of gelling agents and friction reducer polymers, with India supplying guar gum derivatives tethered to agricultural commodity cycles. Base polymer production draws from Gulf Coast petrochemical complexes and Sichuan province manufacturing clusters. Single-source vulnerability concentrates in crosslinker manufacturing along the US Gulf Coast. Distribution runs through regional blending facilities co-located with major shale basins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment, where EPA disclosure requirements and REACH authorization pathways create switching costs that protect incumbent formulation libraries.
For Market Incumbents: Secure captive R&D infrastructure around high-temperature stable friction reducers and digital fluid monitoring integration. Expand backward integration into polymer manufacturing to offset guar gum price volatility. Defensive positioning requires preemptive REACH registration for biocide alternatives before authorization restrictions tighten. For New Entrants and Emerging Players: Differentiate on bio-based friction reducer formulations qualifying for EU Green Deal procurement preferences. Target Argentina Vaca Muerta development as the most penetrable geography, where North American completion designs create specification familiarity without entrenched supplier relationships. Go-to-market angle should emphasize localized blending capacity to reduce import dependency for Neuquén basin operators. For Investors and Strategic Acquirers: Carve-out targets emerge from integrated oilfield service companies seeking to monetize non-core chemical formulation assets. Long-term viability over the coming decade rests on regulatory compliance infrastructure rather than commodity scale. Acquisition focus should center on mid-cap blenders with captive REACH registrations. Signal to monitor: EPA acceleration of chemical composition reporting deadlines forcing IT infrastructure consolidation among legacy documentation systems.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Manufacturing | Halliburton and Dow control input costs through captive supply of gelling agents and friction reducers. |
| REACH-Compliant Biocide Registration | European suppliers capture cross-border share previously held by non-registered competitors in Polish shale projects. |
| Digital Fluid Monitoring Convergence | Baker Hughes pairs real-time pressure-temperature sensors with proprietary chemical packages for premium service tiers. |
| Localized Blending Capacity Buildout | YPF and international joint ventures in Neuquén reduce import dependency for Vaca Muerta development. |
| Hybrid Polymer Architecture Licensing | Specialist chemical houses license polyacrylamide-polyacrylate friction reducers to commodity suppliers facing margin compression. |
Research Methodology
The analysis maps gelling agents, biocides, crosslinkers, and friction reducers, each validated through formulation chemists, procurement leads at exploration and production companies, plant managers at regional blending facilities, and technical R&D directors at integrated service firms. Primary interview insights combined with secondary validation from EPA underground injection control filings, ECHA REACH registration databases, SEC 10-K disclosures, and customs trade data. Bottom-up chemical volume estimates triangulated against top-down shale completion activity metrics.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product chemistry tier, end-use application, technology type, and regional regulatory cluster. CAGRs derived from regression analysis of historical chemical intensity per completed lateral foot, incorporating inputs from lateral length extension trajectories and foam fracturing adoption curves in water-scarce regions.
Decision-makers should treat outputs as directional under assumptions of sustained super-basin development activity and stable regulatory disclosure timelines; material deviation in EPA enforcement intensity or guar gum harvest conditions would warrant model refresh. Recalibration cycles align with material shifts in lateral length trajectories and REACH authorization restriction schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Chad Oil and Gas Market
Oil & Gas
GCC Natural Gas Market
Oil & Gas
South and Central America Oil Country Tubular Goods (OCTG) Market
Oil & Gas
Southeast Asia Oil and Gas Upstream Market
Oil & Gas
Oil Storage Terminal Market
Oil & Gas
Proppant Market
Oil & Gas
SCADA Oil and Gas Market
Oil & Gas
Downhole Tools Market
Oil & Gas
Well Casing Market
Oil & Gas
Asia Pacific Upstream Oil and Gas Services Market
Oil & Gas
North Sea Oilfield Equipment Market
Oil & Gas
Connected Oil and Gas Market
Oil & Gas
Oil and Gas MIC Testing Market
Oil & Gas
Oil and Gas Infrastructure Market
Oil & Gas
Drilling and Completion Fluids Market
Oil & Gas
North America Directional Drilling Services Market