
 Solid Electrolyte Market | 2026-2036
Solid Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
Solid Electrolyte Market Analysis
The direct-to-cell-manufacturer channel is narrowing as solid electrolyte producers bypass legacy chemical distributors. Solid Power, Inc. leverages its partnership network with automotive OEMs to secure offtake agreements. QuantumScape Corp anchors its position through proprietary lithium-metal interface technology. Blue Solutions competes by sustaining production of polymer electrolyte cells for European bus fleets.
Solid electrolytes are ion-conductive materials, typically ceramic or sulfide compositions, that replace flammable liquid electrolytes in batteries while enabling lithium-metal anodes with energy densities exceeding 400 Wh per kilogram. Ceramic electrolytes dominate current pilot lines due to thermal stability above 200 degrees Celsius, though sulfide compositions are gaining traction for room-temperature conductivity. Polymer electrolytes occupy niche applications in thin-film medical devices where flexibility outweighs energy density. Composite electrolytes, blending ceramic fillers with polymer matrices, attract R&D investment as a bridge technology for mid-decade commercialization.
The US IRA domestic content credits, EU Battery Regulation carbon footprint rules, and China's GB standards for solid-state battery safety create a fragmented compliance landscape. EMA and REACH frameworks in Europe impose material disclosure requirements on sulfide-based chemistries that complicate cross-border supply chains. Stakeholders must monitor which regulatory jurisdiction certifies first-party validation protocols, as this will determine where initial gigafactory-scale deployments achieve operational permits.
Market Dynamics
Solid electrolyte manufacturers confront a supply-demand mismatch where lithium-metal anode compatibility requirements outpace ceramic and sulfide material yields. The transition from liquid to solid architectures compresses qualification timelines while expanding purity specifications.
Growth Catalysts
- MIIT Dual Carbon Mandates:China's battery safety GB standards now require thermal runaway containment above 200 degrees Celsius, forcing EV manufacturers toward ceramic electrolyte architectures.
- Bus Fleet Electrification:European municipal transport authorities specify polymer solid-state cells for depot-charging infrastructure, creating anchor demand for early production lines.
- Ulsan-Gwangju Cluster Concentration:South Korea's integrated battery manufacturing corridor enables co-located electrolyte synthesis and cell assembly, reducing logistics friction for sulfide compositions.
Market Restraints
- Lithium Sulfide Feedstock Volatility:Sulfide electrolyte production depends on refined lithium sulfide where spot pricing swings 40-60 percent quarterly, compressing margin visibility.
- Argon-Atmosphere Processing Bottlenecks:Sulfide compositions require oxygen-free manufacturing environments, limiting viable production geographies to regions with established inert gas infrastructure.
- REACH Disclosure Burden:ECHA's substance registration requirements for sulfide-based chemistries impose 18-24 month pre-market notification timelines, delaying EU commercialization.
Strategic Opportunities
- Medical Thin-Film Devices:Polymer electrolyte flexibility enables implantable cardiac monitors and drug delivery systems where conformal battery shapes outweigh energy density requirements.
- US IRA Domestic Content Credits:The Inflation Reduction Act's $35 per kilowatt-hour credit for North American battery production incentivizes localized solid electrolyte synthesis capacity.
- Composite Electrolyte Convergence:Ceramic-polymer hybrid formulations bridge the conductivity gap between sulfide and oxide systems, targeting mid-decade automotive qualification windows.
Industry Challenges
- Interfacial Engineering Talent Scarcity:Lithium-metal dendrite suppression requires specialized electrochemists familiar with solid-solid boundary mechanics, a skill set concentrated in fewer than twelve academic programs worldwide.
- Gigafactory Certification Timelines:First-party validation protocols for solid-state cell production remain undefined across NHTSA, ECE R100, and GB standards, freezing permit applications.
- Legacy Liquid Electrolyte Equipment Stranding:Existing electrode coating and formation assets require complete replacement for dry-process solid-state manufacturing, complicating brownfield expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solid Electrolyte Market |
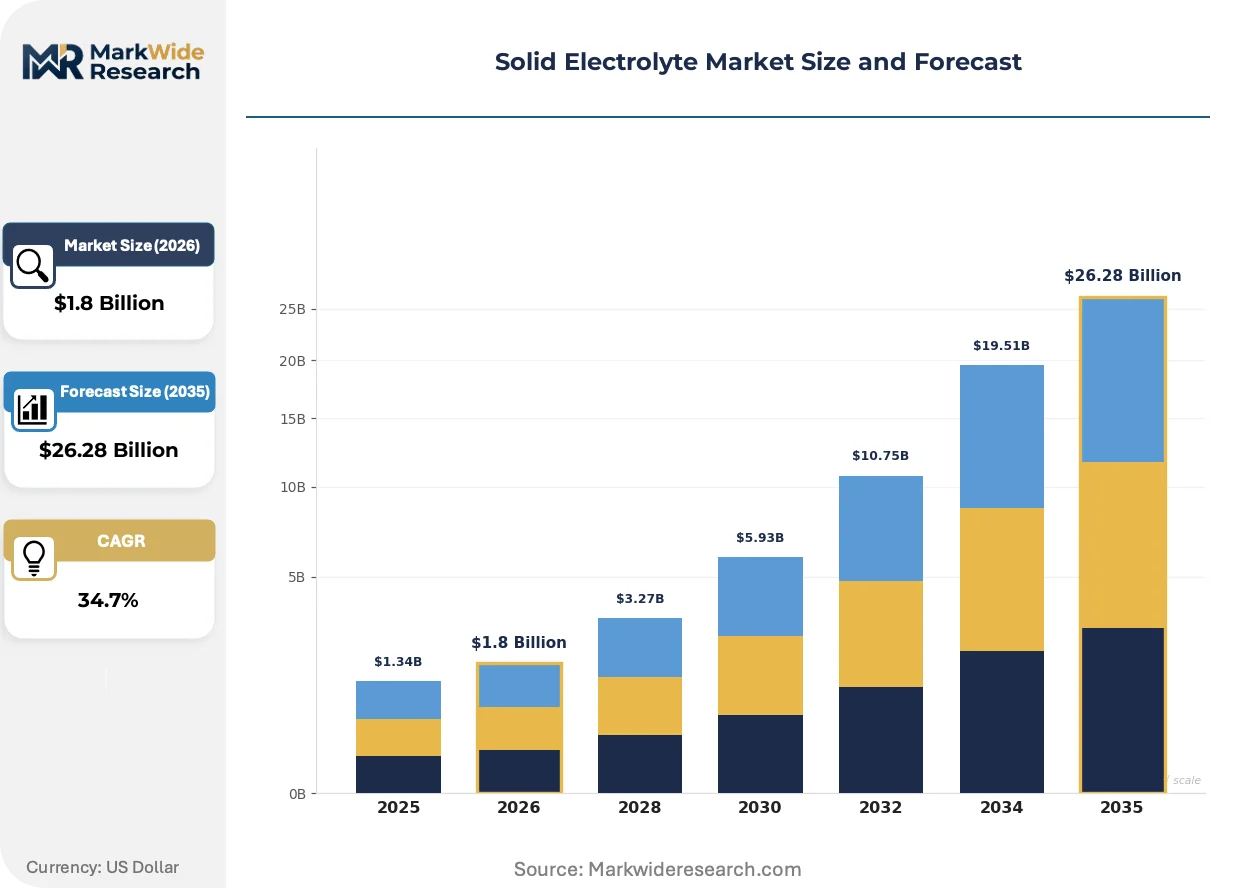
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $26.28 Billion |
| CAGR (2026 – 2036) | 34.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ceramic Electrolytes, Polymer Electrolytes, Composite Electrolytes, Glassy Electrolytes Application: Solid-State Batteries, Electric Vehicle Batteries, Portable Electronics, Grid Storage End User: Consumer Electronics, Automotive, Energy, Aerospace Technology: Thin Film Deposition, Sol-Gel Process, Screen Printing, Coating Techniques |
| Companies Covered | Solid Power, Inc., Blue Solutions, Ohara Inc., ProLogium Technology Co., Ltd., Ampcera Corp, Empower Materials, NEI Corporation, QuantumScape Corp, Ilika plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solid Electrolyte Market Emerging Trajectories
Manufacturing process virtualization and regulatory fragmentation are compressing development cycles while redrawing competitive boundaries. Material informatics and closed-loop synthesis control now determine yield economics.
Sulfide electrolyte compositions with lithium-argyrodite crystal structures are virtualizing the conductivity-performance tradeoff that previously favored liquid systems. Automotive cell manufacturers in South Korea and Japan are piloting these materials at 10-20 megawatt-hour annual scales. The technology is virtualizing traditional separator-electrolyte stack configurations into single-layer multifunctional components.
REACH Annex XVII restrictions on nickel and cobalt compounds are forcing electrolyte developers toward lithium-phosphorus-sulfur systems with reduced transition metal content. The regulation accelerates substitution away from layered oxide cathode pairings. European bus and commercial vehicle segments are responding fastest, with municipal tenders now specifying full material disclosure down to 0.1 percent weight thresholds.
Cell manufacturers are consolidating supplier relationships around electrolyte producers with captive lithium-metal processing capabilities. Direct offtake agreements are replacing spot chemical procurement for sulfide and oxide precursor materials. This concentration is most visible in South Korea, where Samsung SDI and LG Energy Solution have locked multi-year supply commitments with domestic ceramic powder specialists.
Solid Electrolyte Market Segmentation
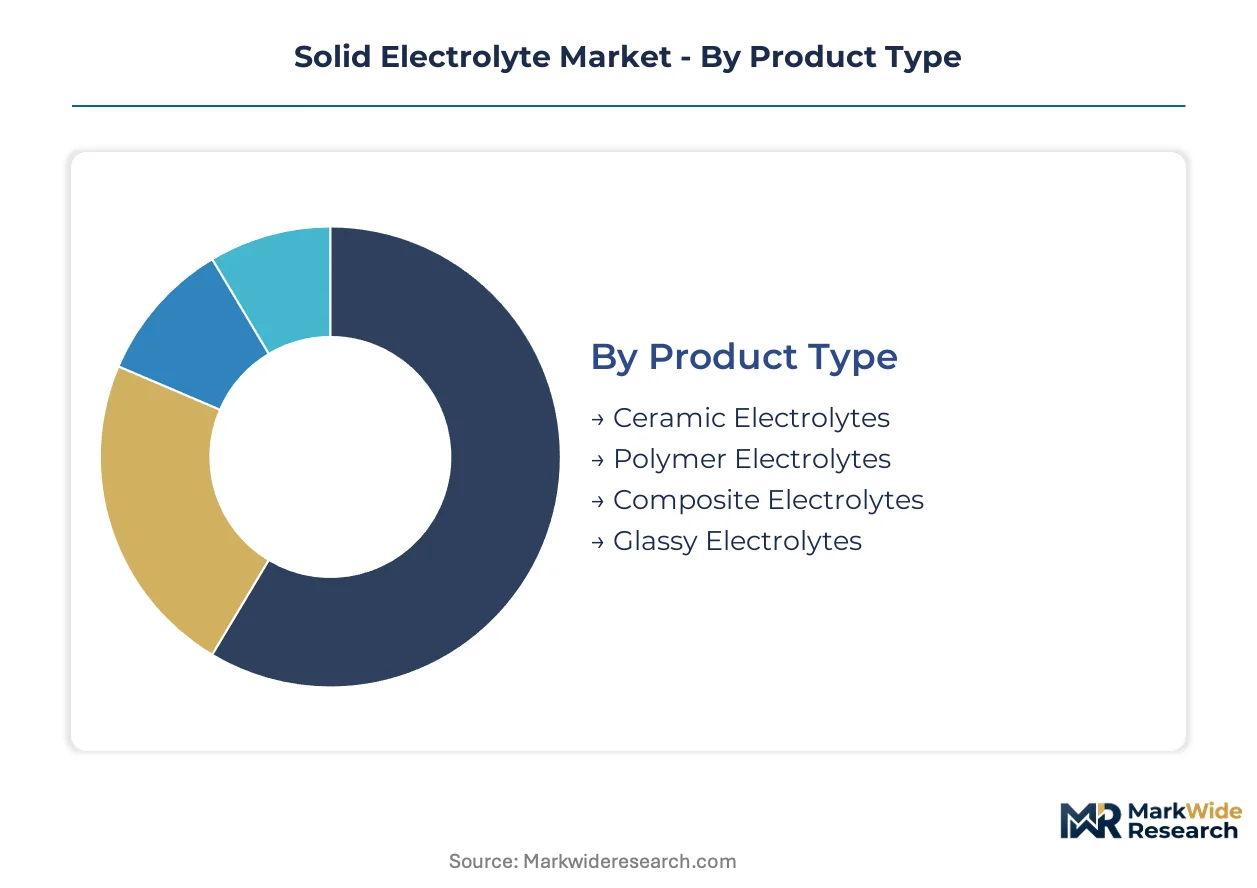
Solid electrolyte architectures diverge sharply across thermal stability, ionic conductivity, and manufacturing scalability requirements. Each segmentation axis reveals distinct competitive moats and qualification barriers that determine which material systems capture automotive versus medical versus stationary storage deployments.
Product Type:
The use-case spectrum spans from high-temperature automotive cells requiring ceramic stability to conformal medical devices where polymer flexibility dominates.
- Ceramic Electrolytes:Oxide-based compositions, primarily LLZO and LATP structures, deliver thermal stability above 200 degrees Celsius. Demand concentrates in South Korea's Ulsan-Gwangju battery corridor where Samsung SDI and LG Energy Solution operate pilot lines under MIIT-mandated safety specifications.
- Polymer Electrolytes:PEO-based matrices with lithium salt complexes operate at room temperature with mechanical flexibility. European municipal bus fleets anchor demand through Blue Solutions' depot-charging deployments, where cell conformability outweighs energy density targets.
- Composite Electrolytes:Ceramic-polymer hybrid formulations bridge conductivity gaps between sulfide and oxide systems.
- Glassy Electrolytes:Amorphous lithium-phosphorus-sulfur structures enable thin-film processing for specialized applications.
The dominant share belongs to Ceramic Electrolytes, while Composite Electrolytes are closing the gap fastest as mid-decade automotive qualification windows approach.
Application:
Cost tier differentiation separates premium automotive qualification from commodity grid storage economics.
- Solid-State Batteries:Next-generation cell architectures replacing liquid electrolyte systems entirely. Automotive OEM offtake agreements through Solid Power's partnership network drive volume commitments, though gigafactory certification timelines remain undefined across NHTSA and ECE R100 frameworks.
- Electric Vehicle Batteries:High-energy-density packs targeting 400 Wh per kilogram through lithium-metal anode integration. China's evolving GB standards for thermal runaway containment above 200 degrees Celsius force manufacturers toward ceramic architectures.
- Portable Electronics:Premium consumer devices where safety premiums justify solid-state cost structures.
- Grid Storage:Stationary applications where cycle life and fire safety offset lower energy density tolerance.
Electric Vehicle Batteries command the largest committed capacity, while Solid-State Batteries are expanding most quickly as pilot lines scale toward megawatt-hour annual output.
End User:
Customer type determines purity specifications, with aerospace and automotive imposing the strictest material qualification protocols.
- Automotive:Cell manufacturers consolidating supplier relationships around electrolyte producers with captive lithium-metal processing. Direct offtake agreements replace spot chemical procurement for sulfide and oxide precursors.
- Consumer Electronics:Thin-film medical devices and premium wearables where polymer electrolyte flexibility enables conformal battery shapes.
- Energy:Grid-scale storage developers prioritizing cycle stability over energy density.
- Aerospace:Satellite and defense applications with extreme temperature range requirements.
Automotive claims the dominant procurement volume, while Consumer Electronics offers the steepest expansion trajectory in implantable device segments.
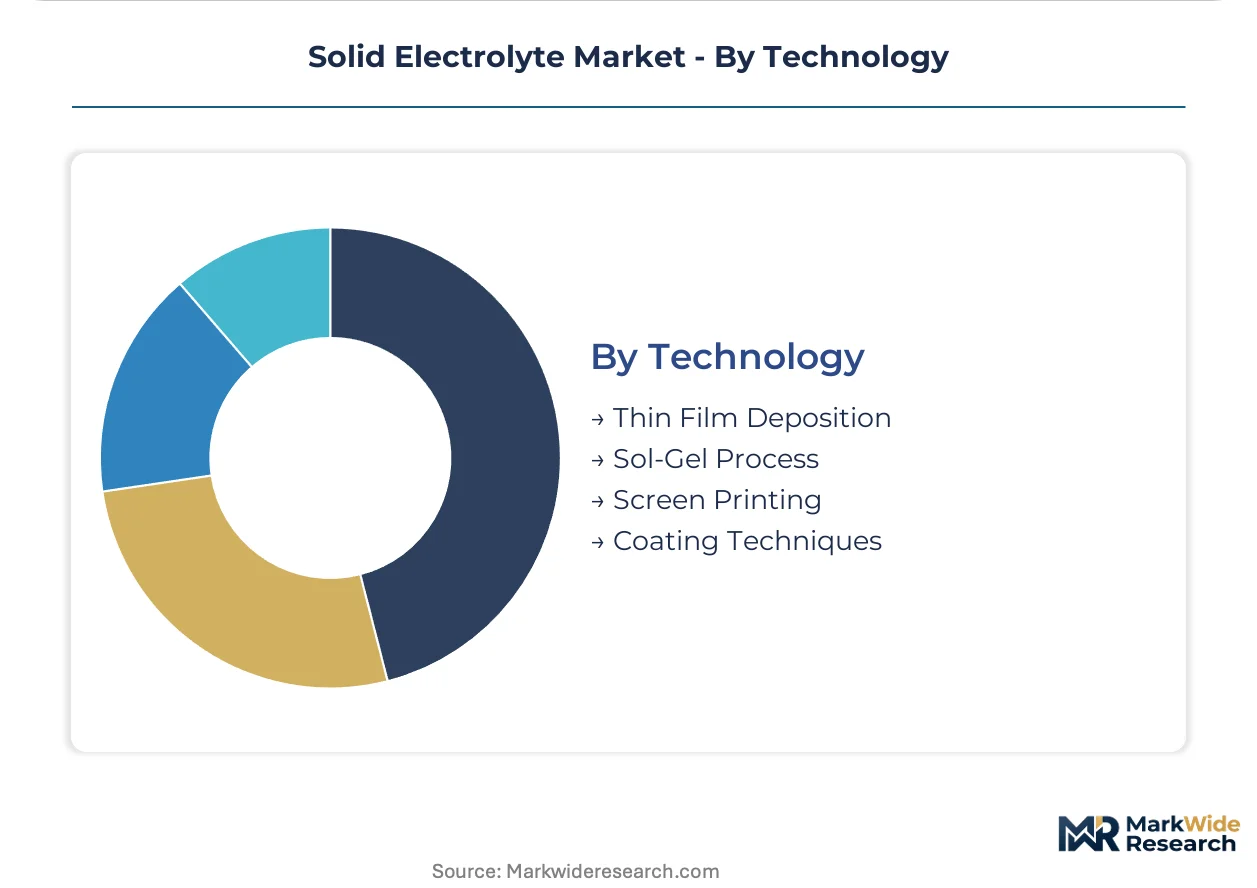
Technology:
Manufacturing maturity separates established coating methods from emerging deposition techniques requiring argon-atmosphere infrastructure.
- Thin Film Deposition:Physical vapor deposition and sputtering for sub-micron electrolyte layers. Medical device manufacturers leverage this precision for implantable cardiac monitors where conformal coverage outweighs throughput economics.
- Sol-Gel Process:Wet chemical synthesis enabling precise stoichiometric control of ceramic powders. South Korean ceramic specialists supply Samsung SDI and LG Energy Solution through co-located synthesis and cell assembly operations.
- Screen Printing:Thick-film deposition for patterned electrolyte geometries.
- Coating Techniques:Roll-to-roll processing for composite electrolyte sheet production.
Sol-Gel Process retains the dominant installed base, while Thin Film Deposition is gaining share fastest in medical and aerospace qualification pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in South Korea's Ulsan-Gwangju corridor exceeds that of European polymer specialists by a factor reflecting sulfide-ceramic yield premiums. China's MIIT-mandated safety standards compress qualification timelines for domestic ceramic producers. The United States leverages IRA domestic content credits to localize synthesis capacity away from established Asian supply nodes.
China
MIIT dual carbon goals and evolving GB standards for battery safety tighten material specifications for EV manufacturers. GB standards now require thermal runaway containment above 200 degrees Celsius, forcing ceramic electrolyte adoption. Yangtze River Delta clusters near Shanghai host pilot production lines for oxide-based compositions serving domestic automotive OEMs.
South Korea
Samsung SDI and LG Energy Solution anchor demand through multi-year offtake commitments with domestic ceramic powder specialists. The country's battery manufacturing corridor enables co-located electrolyte synthesis and cell assembly, reducing logistics friction for sulfide compositions. Ulsan-Gwangju concentration supports 10-20 megawatt-hour annual pilot scales under automotive qualification timelines.
United States
IRA domestic content credits at $35 per kilowatt-hour incentivize North American solid electrolyte synthesis capacity. NHTSA certification timelines for solid-state cell production remain undefined, freezing permit applications for gigafactory-scale deployments. Solid Power leverages partnership networks with automotive OEMs to secure offtake agreements ahead of regulatory clarity.
Japan
METI programs support lithium-argyrodite crystal structure development for room-temperature conductivity applications. JIS standards for solid-state battery interfaces remain in draft, delaying commercialization timelines relative to South Korean competitors. Kanto and Nagoya industrial zones concentrate thin-film deposition expertise for medical device applications.
Germany
REACH Annex XVII restrictions on nickel and cobalt compounds force electrolyte developers toward lithium-phosphorus-sulfur systems. ECHA substance registration requirements impose 18-24 month pre-market notification timelines for sulfide-based chemistries. Bavaria-based research consortia focus on composite electrolyte formulations bridging conductivity gaps between sulfide and oxide systems.
Solid Electrolyte Market Vendor Landscape
Automotive-anchored developers and materials-science specialists split the market along qualification-timeline and yield-optimization vectors. The competitive structure concentrates around players with captive lithium-metal processing capabilities and established inert-gas manufacturing infrastructure. Three archetypes dominate: sulfide-ceramic synthesis specialists, polymer-flexibility incumbents, and thin-film precision fabricators. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with direct offtake agreements replacing legacy chemical distribution channels.
Within the automotive-anchored tier, Solid Power, Inc. and QuantumScape Corp exemplify divergent interface-technology strategies. Blue Solutions occupies a distinct position among polymer-flexibility incumbents serving European municipal transport electrification. Ohara Inc. and ProLogium Technology Co., Ltd. represent Asian ceramic and composite formulation specialists with proximity to South Korean and Chinese cell manufacturing clusters. Ampcera Corp and NEI Corporation sit within the materials-science archetype focused on precursor purity and synthesis yield economics.
| Leading Market Players |
|---|
| Solid Power, Inc. |
| Blue Solutions |
| Ohara Inc. |
| ProLogium Technology Co., Ltd. |
| Ampcera Corp |
| Empower Materials |
| NEI Corporation |
| QuantumScape Corp |
| Ilika plc |
| Others |
Supply Flow & Price Mechanics
Lithium sulfide feedstock volatility determines both tiered pricing spreads and supply chain configuration across solid electrolyte manufacturing. Quarterly spot price swings of 40-60 percent compress margin visibility for sulfide compositions while reinforcing ceramic electrolyte premiums in automotive qualification pipelines.
Pricing Analysis
Configured-to-order pricing for automotive-grade ceramic electrolytes commands substantial premiums over standard polymer formulations for bus fleet applications. Pricing stratifies across automotive qualification tiers, medical device flexibility specifications, and grid storage economy grades, with certification level under MIIT GB standards serving as the primary differentiation driver. Cost compression in sulfide electrolyte production is intensifying because lithium sulfide spot market instability erodes contract margin predictability. Grid storage developers exhibit the highest price sensitivity, while automotive cell manufacturers prioritize thermal stability certifications over unit cost.
Supply Chain Analysis
Extended payment terms from South Korean battery manufacturers to domestic ceramic powder specialists are reshaping working capital requirements across the value chain. Geographic supply concentration centers on South Korea, China, and Japan, with the Ulsan-Gwangju corridor hosting co-located synthesis and cell assembly operations. Raw material dependencies draw from refined lithium sulfide, argon gas infrastructure, and high-purity lithium metal feedstocks. Single-source vulnerability in argon-atmosphere processing equipment creates structural risk for sulfide electrolyte scaling. Distribution runs through direct offtake agreements between electrolyte producers and automotive OEMs, bypassing legacy chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The scarcity of electrochemists trained in solid-solid interfacial engineering constrains expansion timelines for lithium-metal compatible production lines. This capability gap limits qualified personnel to fewer than twelve academic programs worldwide, creating competitive bottlenecks.
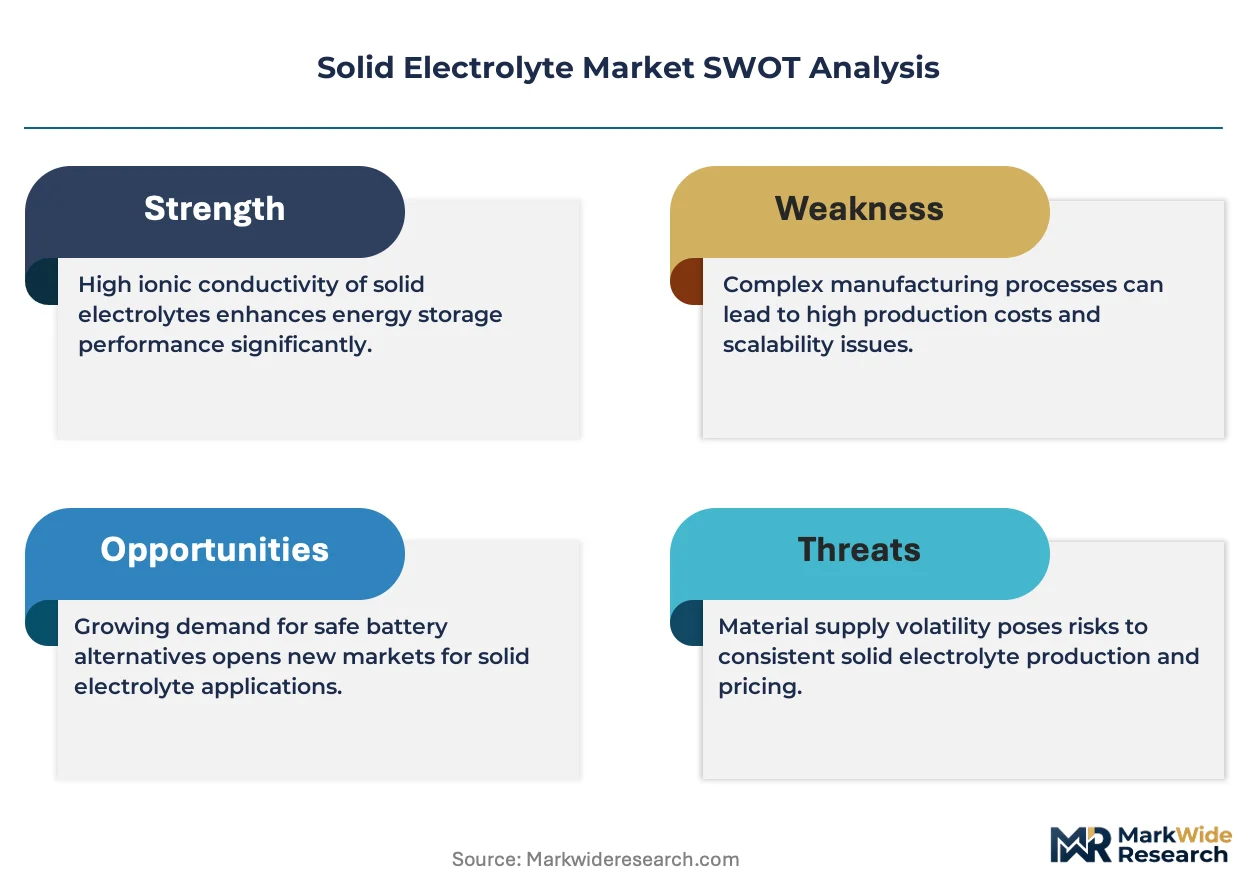
For Market Incumbents: Build captive lithium-metal processing capabilities as the primary defensive moat against emerging sulfide-ceramic synthesis specialists. Secure multi-year offtake agreements with South Korean and Chinese cell manufacturers before NHTSA certification timelines clarify. Invest in argon-atmosphere infrastructure in the Ulsan-Gwangju corridor to preempt logistics friction for sulfide compositions. For New Entrants and Emerging Players: North American solid electrolyte synthesis capacity represents the most penetrable white-space opportunity given IRA domestic content credit incentives. Target medical thin-film device segments where polymer electrolyte flexibility requirements lower barrier-to-entry versus automotive qualification. Pursue joint development agreements with European municipal bus fleet operators seeking depot-charging polymer cell alternatives. For Investors and Strategic Acquirers: First-party validation protocol certification by NHTSA, ECE R100, or MIIT reshapes the acquisition landscape toward producers with demonstrated regulatory engagement. Frame long-term viability around electrolyte producers with captive lithium-metal processing and established inert gas manufacturing infrastructure. Monitor which regulatory jurisdiction certifies initial gigafactory-scale operational permits as the signal for scalable deployment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Argon-Atmosphere Capacity Buildout | Sulfide electrolyte scaling requires oxygen-free infrastructure concentrated in South Korea and Japan. |
| Direct Automotive Offtake Agreements | Solid Power's partnership network demonstrates bypassing legacy chemical distributors secures volume commitments. |
| Composite Electrolyte R&D Convergence | Ceramic-polymer hybrid formulations target mid-decade automotive qualification windows between sulfide and oxide systems. |
| Captive Lithium-Metal Processing Integration | Cell manufacturers consolidate supplier relationships around electrolyte producers with in-house anode material capabilities. |
| Medical Thin-Film Deposition Partnership | PEO-based polymer electrolytes enable implantable cardiac monitors where conformal shapes outweigh energy density. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of SEC filings, customs and trade databases, MIIT GB standard publications, and ECHA REACH substance registrations. Primary interviews encompassed solid electrolyte R&D directors, automotive cell manufacturer procurement leads, argon gas infrastructure operators, and regulatory affairs specialists at ceramic powder producers. Bottom-up triangulation across pilot line capacity disclosures and top-down validation against EV battery deployment forecasts ensure analytical coherence.
Forecast inputs considered sulfide-ceramic yield differentials, automotive qualification timeline probabilities, and IRA domestic content credit utilization rates across the projection horizon. Segmentation dimensions modeled include electrolyte composition type, application tier from medical devices to automotive packs, end-user purity specifications, and regional manufacturing cluster concentration. CAGRs derive from capacity expansion announcements weighted against technical readiness levels for each material system.
Practitioners should monitor NHTSA certification protocol finalization, lithium sulfide spot price volatility bands, and MIIT GB standard enforcement intensity for early signals of forecast deviation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Batteries
Taiwan Battery Market
Batteries
Middle East and Africa SLI Battery Market
Batteries
Battery Maintainer Market
Batteries
Lithium-Fluorinated Graphite Batteries Market
Batteries
Water-Based Zinc-Ion Battery Market
Batteries
Wireless Power Bank Market
Batteries
Floor Scrubber Battery Market
Batteries
Stretchable Battery Market
Batteries
Asia-Pacific Battery Market
Batteries
Global Industrial Battery Market
Batteries
Grid-Scale Battery Market
Batteries
Mobile Battery Market
Batteries
Global Automotive Lead Acid Batteries Market
Batteries
Iron Salt Battery Market
Batteries
Global Electric Scooter Batteries Market
Batteries
Asia-Pacific Dual Carbon Battery Market