
 Australia Oil and Gas Market | 2026-2036
Australia Oil and Gas Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Oil and Gas Market Analysis
Software-defined production optimization is decoupling physical asset ownership from operational control in Australian upstream contracts. Woodside Energy Group Ltd leverages its Scarborough development to anchor long-term LNG offtake positions across Asian buyer portfolios. Santos Ltd specializes in Cooper Basin tight gas recovery, sustaining domestic supply commitments while competing for east coast pipeline capacity. INPEX Corp dominates Ichthys throughput volumes, extending its position as the largest single-train LNG facility in Australian history.
The Australia oil and gas sector encompasses crude oil, natural gas, LNG, and condensate extracted through offshore drilling, hydraulic fracturing, and conventional reservoir management, with hydrocarbons refined to fuels or liquefied for cryogenic marine transport to power generation and industrial end users. LNG production from the Type category commands premium margins due to Asian contract linkage to oil-indexed pricing, while Natural Gas for domestic Industrial Use faces structural cost pressure from renewable electricity substitution in alumina smelting and ammonia manufacturing. Exploration technology within the Technology dimension is concentrating in deepwater frontiers off Western Australia, whereas Distribution infrastructure remains mature with limited pipeline greenfield expansion outside Narrabri or Beetaloo development scenarios.
The National Offshore Petroleum Safety and Environmental Management Authority enforces facility integrity standards across Commonwealth waters, while the Australian Energy Market Operator coordinates gas scheduling and adequacy assessments for east coast consumers. The Clean Energy Regulator administers Safeguard Mechanism baselines that reshape investment economics for new liquefaction capacity. Stakeholders must weigh carbon credit procurement strategies against reservoir depletion timelines as European buyers harden emissions intensity clauses in term contracts.
Market Dynamics
The Safeguard Mechanism reforms are compressing emissions baselines for liquefaction facilities, forcing operators to integrate carbon capture or procure credits while Japanese and Korean capital continues expanding Queensland and Western Australia LNG export capacity.
Growth Catalysts
- Asian LNG Contract Linkage:Oil-indexed pricing in long-term offtake agreements with Japanese trading houses and Korean utilities underwrites capital commitments for new Western Australia trains.
- Cooper Basin Tight Gas Recovery:Advanced hydraulic fracturing techniques unlock stranded reserves, sustaining east coast domestic supply commitments despite pipeline capacity constraints.
- Narrabri and Beetaloo Development Scenarios:Greenfield pipeline expansion into New South Wales and Northern Territory basins diversifies supply routes beyond mature Queensland infrastructure.
Market Restraints
- Renewable Electricity Substitution:Alumina smelting and ammonia manufacturing sectors are switching to grid renewables, eroding industrial natural gas demand volumes.
- Deepwater Frontier Concentration:Exploration technology deployment clusters off Western Australia, leaving other offshore provinces undercapitalized and supply geographically concentrated.
- Safeguard Mechanism Baseline Tightening:The Clean Energy Regulator's progressively stricter emissions thresholds raise compliance costs for existing liquefaction capacity.
Strategic Opportunities
- Carbon Capture Integration:Reservoir depletion timelines create windows for retrofitting post-combustion capture at Pilbara and Carnarvon basin facilities before European emissions clauses harden.
- Software-Defined Production Optimization:Decoupling physical asset ownership from operational control opens contract structures for technology vendors in upstream joint ventures.
- East Coast Pipeline Capacity Competition:Santos and emerging Cooper Basin operators can secure firm transportation rights as domestic supply adequacy assessments intensify.
Industry Challenges
- Subsea Engineering Talent Scarcity:Deepwater frontier expansion outpaces Australian university pipeline output for subsea installation and integrity specialists.
- LNG Train Certification Timelines:National Offshore Petroleum Safety and Environmental Management Authority facility integrity approvals extend project schedules for Ichthys-scale developments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Oil and Gas Market |
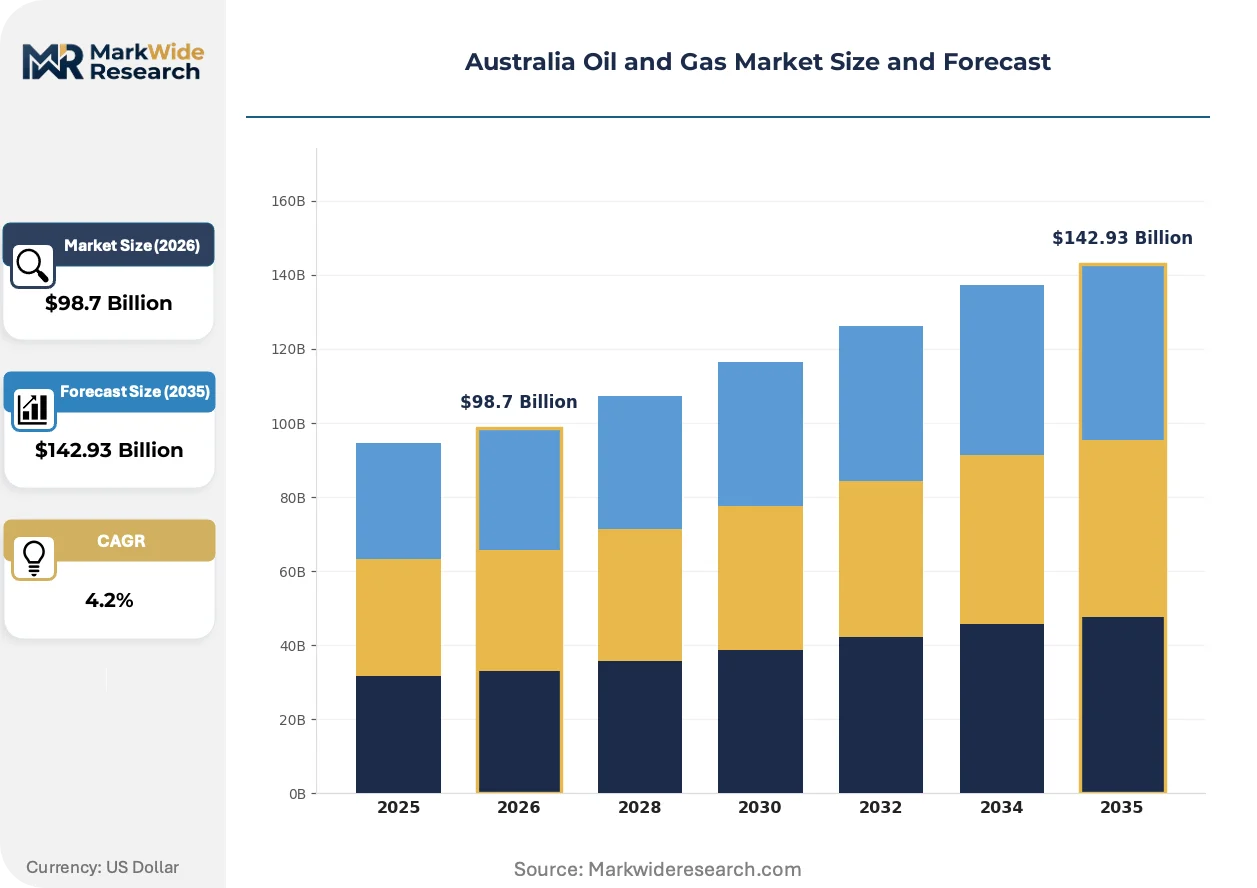
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $142.93 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Crude Oil, Natural Gas, LNG, Condensate Application: Power Generation, Industrial Use, Transportation, Residential Heating Technology: Exploration, Extraction, Refining, Distribution End User: Utilities, Manufacturers, government agencies, Commercial Enterprises |
| Companies Covered | Woodside Energy Group Ltd, Santos Ltd, Chevron Corporation, Shell PLC, Beach Energy Ltd, ExxonMobil Corporation, TotalEnergies SE, Origin Energy Ltd, INPEX Corp, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Oil and Gas Market Emerging Trajectories
Digital twins and autonomous subsea systems are compressing operational decision cycles across Australian offshore assets, while regulatory carbon accounting and buyer procurement patterns reshape contract economics.
Subsea robotics combined with AI-driven predictive maintenance is rewriting offshore inspection protocols. Woodside and INPEX are deploying autonomous underwater vehicles for riser integrity monitoring, compressing survey intervals from quarterly to continuous. This convergence is enabling smaller operational crews while extending facility life through preemptive intervention scheduling.
The Clean Energy Regulator's Safeguard Mechanism reforms are mandating facility-level emissions reporting with third-party verification. Liquefaction operators must now integrate real-time carbon intensity tracking into production accounting, with baseline exceedances triggering credit procurement obligations. Western Australia export trains face the steepest compliance ramps as European offtakers embed emissions clauses in term contract renegotiations.
Japanese and Korean buyers are unbundling long-term LNG offtake from destination restrictions, accepting portfolio flexibility in exchange for carbon intensity transparency. Trading houses now preference supply with certified capture integration or offset retirement documentation. This preference shift concentrates procurement leverage among Australian operators with verified abatement pathways, particularly in Pilbara developments with accessible geological storage formations.
Australia Oil and Gas Market Segmentation
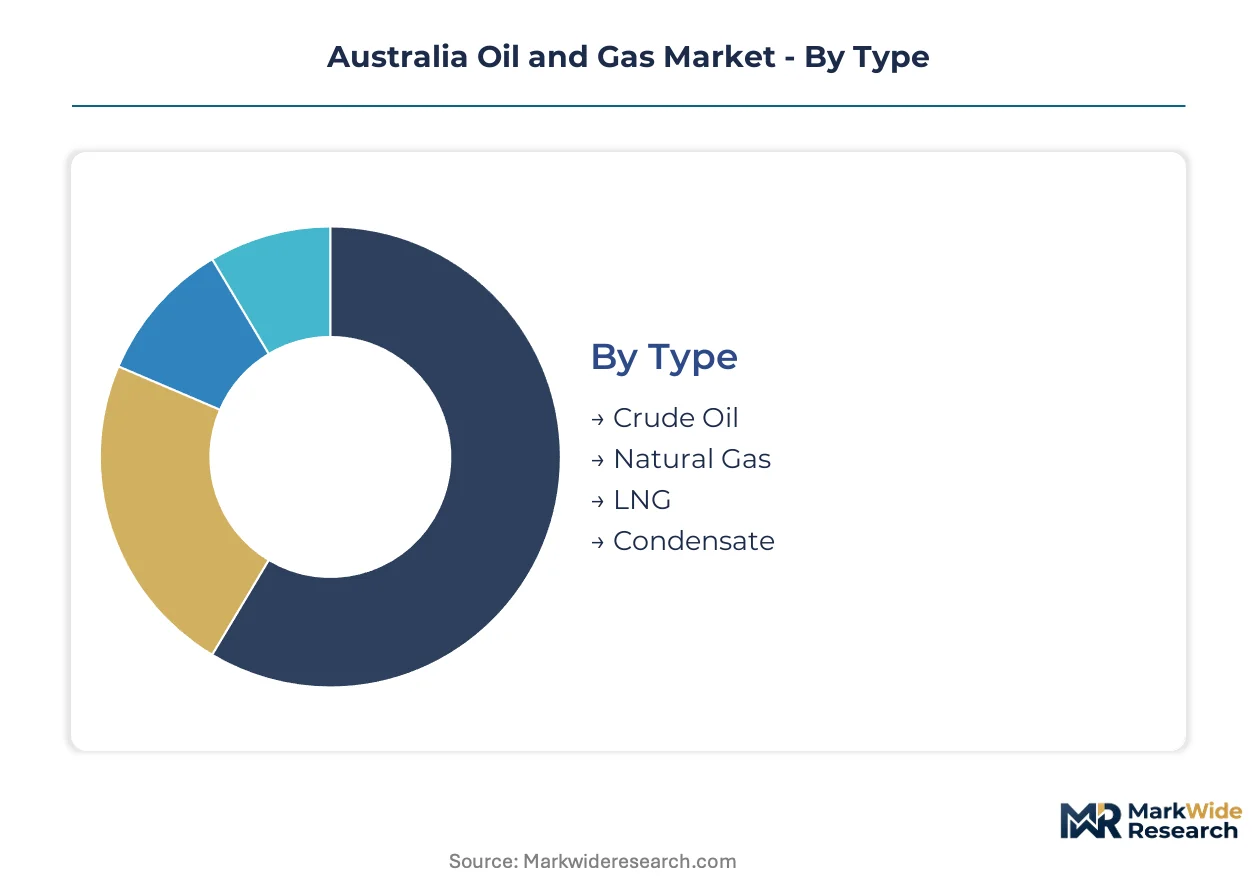
Segmentation in Australian hydrocarbons reveals how resource type, application intensity, and infrastructure maturity create divergent margin profiles across the value chain. Each dimension exposes distinct regulatory exposure and capital deployment patterns.
Type:
Specification and thermal content differentiate commodity pricing power and contract structures across Australian production.
- LNG:Cryogenic liquefaction of predominantly methane yields transportable supercooled cargo for Asian power utilities. Demand concentrates in Pilbara and Carnarvon basin export trains where Japanese trading houses anchor oil-indexed offtake positions. Carbon intensity clauses in European buyer contracts are reshaping procurement premiums.
- Natural Gas:Pipeline-delivered methane serves domestic grids and industrial consumers with lower processing overhead than liquefaction alternatives. East coast manufacturers in alumina and ammonia sectors are eroding volumes through renewable electricity substitution. Cooper Basin tight gas recovery sustains supply adequacy despite pipeline capacity constraints.
- Crude Oil:Liquid hydrocarbon mixtures refined into transport fuels and petrochemical feedstocks face declining domestic refinery throughput as import dependency rises.
- Condensate:Light liquid fractions separated from wet gas streams supply domestic refiners and Asian petrochemical complexes with naphtha-equivalent yields.
Mature deployment sits with Natural Gas pipeline infrastructure. Newer deployment is concentrated in LNG liquefaction capacity expansion.
Application:
End-use intensity and substitution vulnerability determine demand durability across Australian consumption sectors.
- Industrial Use:Process heat and chemical feedstock applications in alumina smelting, ammonia manufacturing, and metals processing command continuous offtake volumes. Western Australia's mining corridor anchors concentrated demand despite renewable penetration. Safeguard Mechanism baselines tighten cost structures for gas-reliant facilities.
- Power Generation:Gas turbine peaking capacity balances renewable intermittency in National Electricity Market jurisdictions. Queensland and South Australian utilities favor rapid-cycle gas plants over coal baseload retirement. Firming value capture depends on capacity market design outcomes.
- Transportation:Compressed natural gas for heavy fleet and LNG for marine bunkering remain niche applications against diesel dominance.
- Residential Heating:Reticulated gas networks in Melbourne and Sydney face electrification policy pressure and appliance switching incentives.
Volume concentration rests with Industrial Use. Steepest expansion trajectory appears in Power Generation firming applications.
Technology:
Capital intensity and operational risk profiles stratify across the production lifecycle from frontier exploration through terminal distribution.
- Extraction:Subsea completions and hydraulic fracturing unlock reserves in deepwater frontiers and tight formations. Western Australia's North West Shelf and Browse basins concentrate offshore deployment. Cooper Basin operators deploy advanced fracturing sequences for tight gas recovery.
- Exploration:Seismic imaging and wildcat drilling target undrilled provinces off Western Australia and in frontier basins. Capital allocation favors proven play extensions over greenfield frontier risk.
- Refining:Domestic conversion capacity at Kwinana and Lytton faces margin compression against Asian import competition.
- Distribution:Pipeline networks and LNG shipping infrastructure represent mature regulated assets with limited greenfield expansion outside Narrabri or Beetaloo scenarios.
Margin capture concentrates in Extraction. Technology differentiation is accelerating in Exploration digitalization.
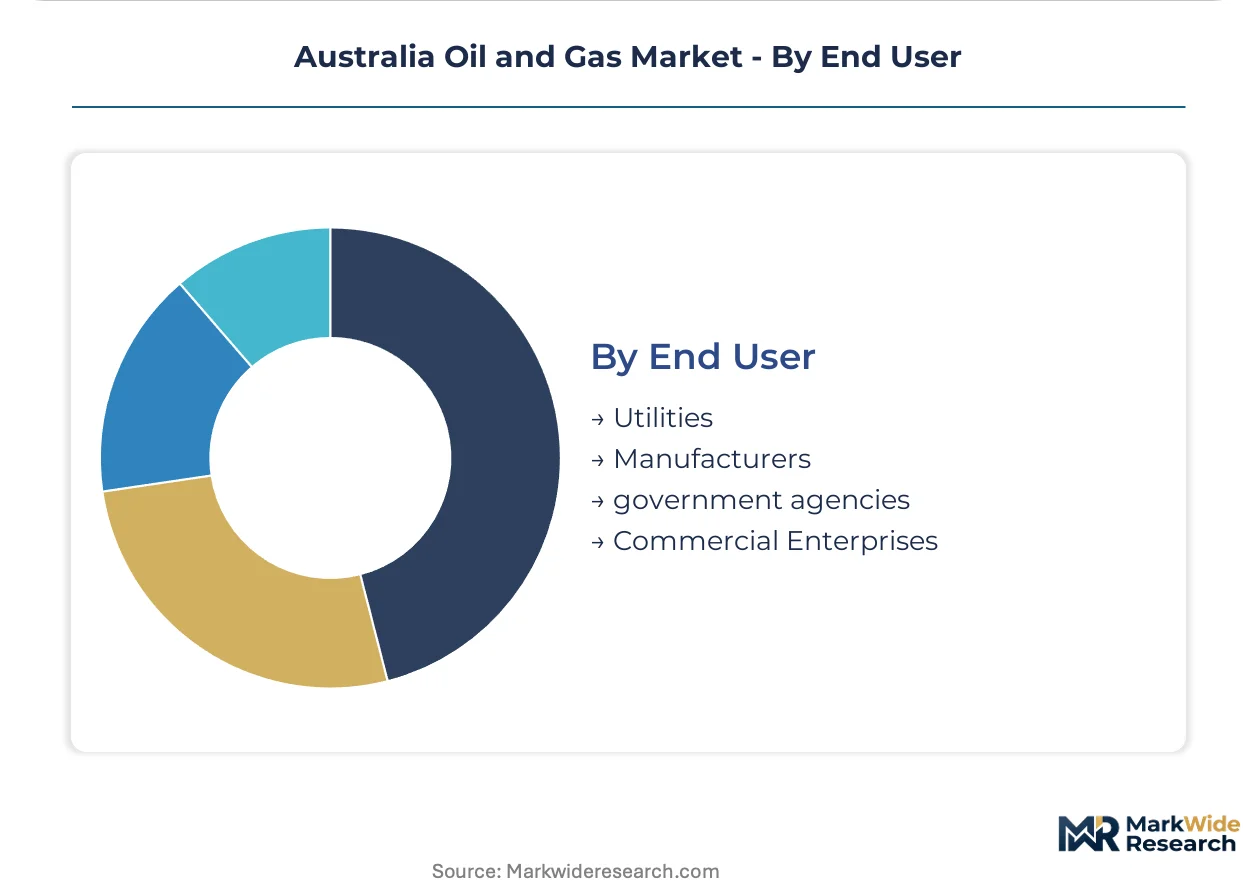
End User:
Procurement scale and contract duration separate price-taker spot buyers from term offtake negotiators.
- Utilities:State-owned and private power retailers procure gas for generation portfolios under medium-term supply agreements. AEMO scheduling coordination shapes delivery reliability requirements. Queensland and Western Australian government-owned entities retain dominant procurement positions.
- Manufacturers:Process industry facilities negotiate firm supply contracts with price hedging against volatile spot markets. Alumina and ammonia producers face renewable substitution pressure on contract renegotiation.
- Government Agencies:Strategic reserve management and emergency supply protocols create non-commercial offtake obligations.
- Commercial Enterprises:Smaller retail and service sector consumers face tariff structures that reflect pipeline transportation cost allocation.
Contract leverage concentrates with Utilities. Procurement complexity is rising fastest among Manufacturers navigating dual fuel transitions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Karratha industrial corridor anchors Australian hydrocarbon production, hosting liquefaction trains and offshore supply bases that feed Asian LNG demand. State-level regulatory variation and basin-specific geology fragment operational economics across the continent.
Western Australia
The Pilbara and Carnarvon basins concentrate offshore gas production feeding North West Shelf and Pluto LNG facilities. The state's Environmental Protection Authority enforces greenhouse gas emissions limits on new project approvals. Karratha and Dampier host the country's densest cluster of liquefaction infrastructure and subsea service yards.
Queensland
Coal seam gas fields in the Surat and Bowen basins supply Curtis Island LNG export terminals and domestic east coast markets. The Queensland government mandates petroleum royalty rates that influence tight gas investment thresholds. Gladstone's port and industrial zone channels the majority of the state's hydrocarbon export volume.
New South Wales
The Narrabri gas project represents the sole significant onshore production prospect in a state otherwise dependent on interstate pipeline supply. The Independent Planning Commission imposes strict groundwater monitoring conditions on coal seam gas development. Sydney's manufacturing corridor consumes pipeline gas for process heat despite electrification pressures.
Victoria
Declining Bass Strait reserves force the state into net importer status for natural gas. Energy Safe Victoria regulates pipeline integrity and retail market conduct. The Latrobe Valley's petrochemical and power generation complex maintains concentrated demand despite upstream depletion.
South Australia
The Cooper Basin sustains tight gas and conventional oil production through hydraulic fracturing and enhanced recovery techniques. The state's Department for Energy and Mining administers petroleum tenement frameworks that incentivize exploration drilling. Moomba's processing and pipeline hub anchors supply connectivity to eastern markets.
Australia Oil and Gas Market Vendor Landscape
Capital-heavy producers compete with asset-light trading houses for control of Australian hydrocarbon flows. The upstream segment consolidates around a handful of integrated operators with full-cycle capabilities from exploration through liquefaction. Two strategic archetypes dominate: basin-anchored developers with long-dated reserve positions, and portfolio traders optimizing offtake timing across multiple supply sources. Competitive intensity manifests through equity farm-in negotiations and pipeline capacity reservation battles.
Among Australian-domiciled operators, Woodside Energy Group Ltd exemplifies the integrated developer archetype with anchored positions in Western Australian deepwater developments. Santos Ltd occupies a position bridging domestic supply commitment and export market access through its Cooper Basin and Queensland assets. INPEX Corp represents the Japanese trading house model, leveraging Ichthys throughput to secure term offtake integration with Asian utility buyers.
| Leading Market Players |
|---|
| Woodside Energy Group Ltd |
| Santos Ltd |
| Chevron Corporation |
| Shell PLC |
| Beach Energy Ltd |
| ExxonMobil Corporation |
| TotalEnergies SE |
| Origin Energy Ltd |
| INPEX Corp |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed Japanese trading houses and Korean utilities anchor long-term offtake financing for Queensland and Western Australia liquefaction capacity, compressing spot price volatility while locking in oil-indexed contract structures that discipline marginal project economics.
Pricing Analysis
Throughput-linked pricing in long-term LNG offtake agreements anchors value capture for Australian liquefaction operators, with Japanese and Korean buyers indexing term contracts to JCC crude benchmarks. Price differentiation stems from carbon intensity certification tiers and destination flexibility clauses, with unbundled portfolio contracts commanding premiums over destination-restricted cargoes. Pricing pressure intensifies in domestic natural gas markets as alumina and ammonia manufacturers accelerate renewable electricity substitution, eroding industrial offtake volumes. Utilities and large manufacturers exhibit divergent sensitivity, with power generators least price-sensitive due to firming value capture while process manufacturers face acute margin compression from dual fuel transition costs.
Supply Chain Analysis
Specialized subsea engineering capacity rests on Norwegian fabrication yards, Singaporean installation contractors, and Australian heavy-industry manufacturing clusters concentrated around Karratha and Gladstone. Critical input dependencies include high-grade steel forgings for wellheads, cryogenic heat exchangers for liquefaction trains, and subsea umbilicals for deepwater completions. Single-source vulnerability concentrates in subsea installation vessel availability, with global fleet constraints extending project timelines for Ichthys-scale developments. Distribution runs through dedicated LNG shipping routes to Asian regasification terminals, supplemented by east coast pipeline networks coordinated by the Australian Energy Market Operator.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Australia oil and gas sector sits at a carbon-capture technology transition phase, with post-combustion capture systems displacing unabated liquefaction capacity as European buyers harden emissions intensity clauses in contract renegotiations.
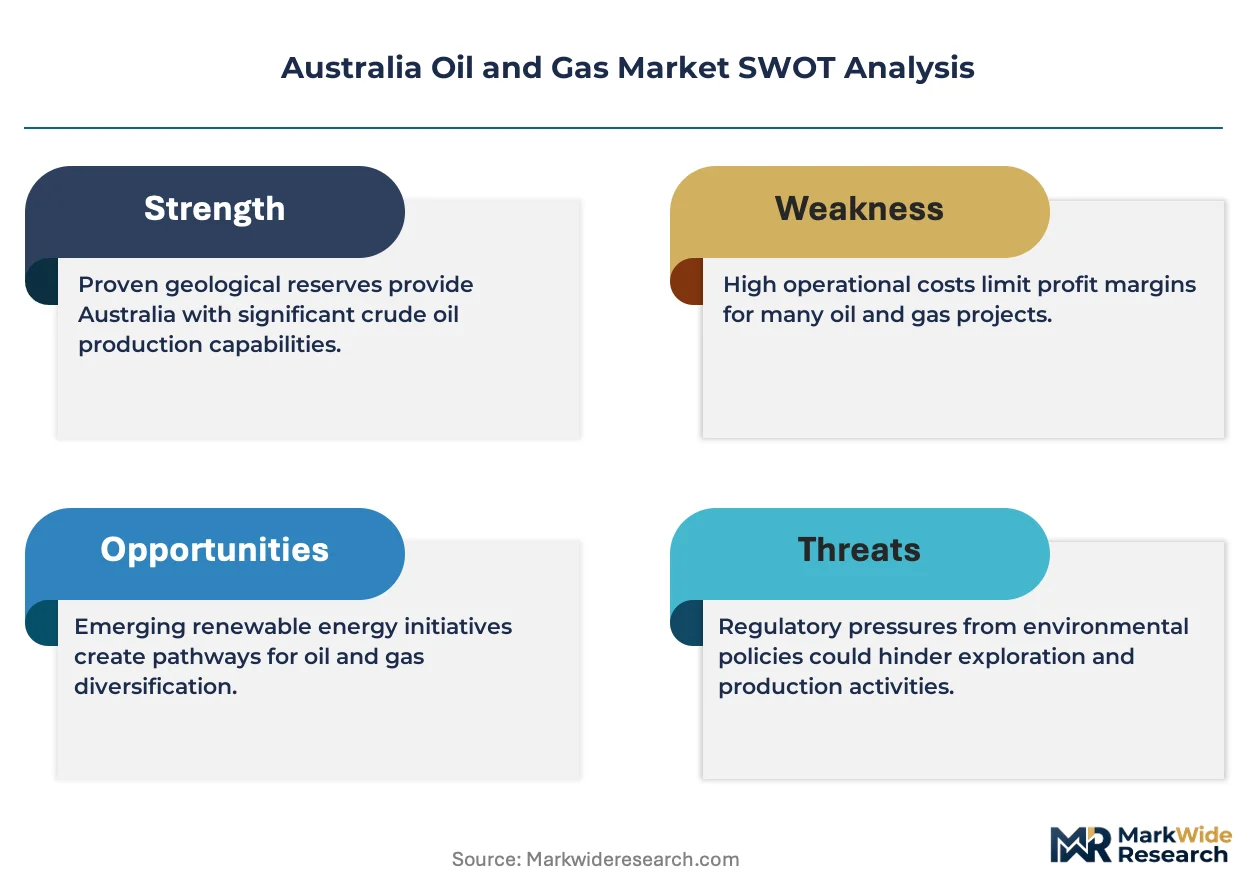
For Market Incumbents: Hedge legacy asset exposure by accelerating carbon capture retrofit timelines at Pilbara and Carnarvon basin facilities before Safeguard Mechanism baseline tightening triggers credit procurement obligations. Secure firm transportation rights on east coast pipelines as domestic supply adequacy assessments intensify competition for Cooper Basin offtake. Prioritize vertical integration into geological storage formations to capture carbon credit revenue streams and defend term contract positioning against emerging lower-carbon supply alternatives.
For New Entrants and Emerging Players: Direct-to-utility digital procurement platforms offer low-friction entry channels for certified lower-carbon gas volumes, bypassing incumbent trading house intermediation. Target the New South Wales manufacturing corridor where Narrabri development scenarios create first-mover pipeline access advantages ahead of mature Queensland infrastructure saturation. Pursue software-defined production optimization contracts that decouple operational control from physical asset ownership in upstream joint ventures.
For Investors and Strategic Acquirers: European buyer contract renegotiation waves are the leading indicator that carbon intensity certification will concentrate procurement leverage among verified abatement pathway operators within the next decade. Focus acquisition screening on Western Australian deepwater developers with accessible geological storage and existing Ichthys-scale facility throughput. Monitor Clean Energy Regulator baseline threshold announcements as the primary signal for credit procurement cost inflection and stranded asset risk timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Carbon Capture Retrofit Deployment | Post-combustion capture integration at Pluto LNG defends term contract positioning against European emissions clauses. |
| Long-term LNG Offtake Restructuring | Oil-indexed contract renegotiation with Korean utilities secures financing for Scarborough development train expansion. |
| East Coast Pipeline Capacity Reservation | Firm transportation rights on Moomba-to-Sydney corridor lock in domestic supply premium capture for Cooper Basin operators. |
| Software-Defined Production Optimization | Operational control decoupling from asset ownership opens technology vendor entry into Browse basin joint ventures. |
| Geological Storage Site Acquisition | Pilbara formation access enables carbon credit revenue stacking for liquefaction facilities facing Safeguard Mechanism compliance ramps. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, cross-referenced with primary interviews involving LNG trading desk heads, subsea engineering contractors, utility fuel procurement officers, and Clean Energy Regulator compliance leads. Australian Bureau of Statistics energy accounts, NOPSEMA facility integrity reports, AEMO gas market bulletins, and IEA country energy profiles supplied quantitative benchmarks. Bottom-up project-level capacity assessments and top-down macroeconomic demand modeling were reconciled through iterative triangulation.
Data-stream reconciliation across supply-side project pipelines and demand-side offtake contracting shaped the analytical framework, with segmentation modeled across fuel type, application intensity, technology maturity, and end-user procurement scale throughout the projection horizon. CAGRs were derived from facility commissioning timelines, reserve depletion curves, and contract rollover patterns. Forecast inputs incorporated Safeguard Mechanism baseline trajectory assumptions and Asian buyer carbon intensity clause adoption rates.
The model holds under sustained oil-indexed contract structures and gradual renewable substitution; deviation in accelerated European emissions border adjustments or abrupt east coast pipeline capacity constraints would shift volume and value outputs. Forecasts reflect documented assumptions about liquefaction train utilization rates and domestic manufacturing electrification pace. A small set of named triggers—Clean Energy Regulator baseline announcements, Ichthys-scale project approval timelines, and Japanese trading house portfolio rebalancing—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Iran Oil and Gas Exploration and Production Market
Oil & Gas
Norway Oilfield Equipment Market
Oil & Gas
Global Hydrate Inhibitors Market
Oil & Gas
Natural Gas Market
Oil & Gas
Rig-Less Intervention Service Market
Oil & Gas
Kuwait Oil and Gas Market
Oil & Gas
Oilfield Air Drilling Market
Oil & Gas
Brazil Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Fabrication Market
Oil & Gas
Kuwait Oil and Gas Upstream Market
Oil & Gas
Polycrystalline Diamond Compact (PDC) Drill Bit Market
Oil & Gas
Blowout Preventers (BOP) Market
Oil & Gas
Dry Natural Gas Market
Oil & Gas
United States Oil and Gas Separation Market
Oil & Gas
Coiled Tubing Services Market
Oil & Gas
Intelligent Well Completion Market