
 Laundry Dryer Market | 2026-2036
Laundry Dryer Market Size, Share, and Industry Trends Forecast 2026-2036
Laundry Dryer Market Analysis
Subscription-based equipment leasing and managed service contracts are reshaping competitive dynamics in the laundry dryer industry. Whirlpool leverages its North American service infrastructure to anchor long-term commercial contracts. Miele specializes in premium heat pump engineering for European residential markets. Samsung competes through smart connectivity platforms that extend recurring revenue beyond hardware sales.
A laundry dryer is an electromechanical appliance that removes moisture from textiles through heated air circulation, with drum capacities ranging from compact 3.5 kg units to industrial 100 kg systems and operating temperatures typically between 40°C and 80°C depending on fabric program. Its primary purpose spans residential convenience, commercial throughput optimization, and industrial textile finishing where controlled moisture removal protects material integrity. Heat pump technology now dominates margin pools in residential segments due to superior energy coefficients, while commercial end users gravitate toward stackable configurations that maximize floor space efficiency in urban laundromats and hospitality settings. Smart dryer adoption remains concentrated in premium residential tiers where connected diagnostics reduce service dispatch costs.
EU Ecodesign requirements and F-Gas Regulation constrain refrigerant choices and minimum efficiency thresholds for dryers sold across Europe. EPA Energy Star certification shapes product positioning in the United States by creating retail differentiation around verified consumption metrics. China's GB standards and MIIT efficiency labeling govern domestic manufacturing compliance and import access. Stakeholders must monitor how refrigerant phase-down schedules and building electrification codes interact with replacement cycle timing across installed bases.
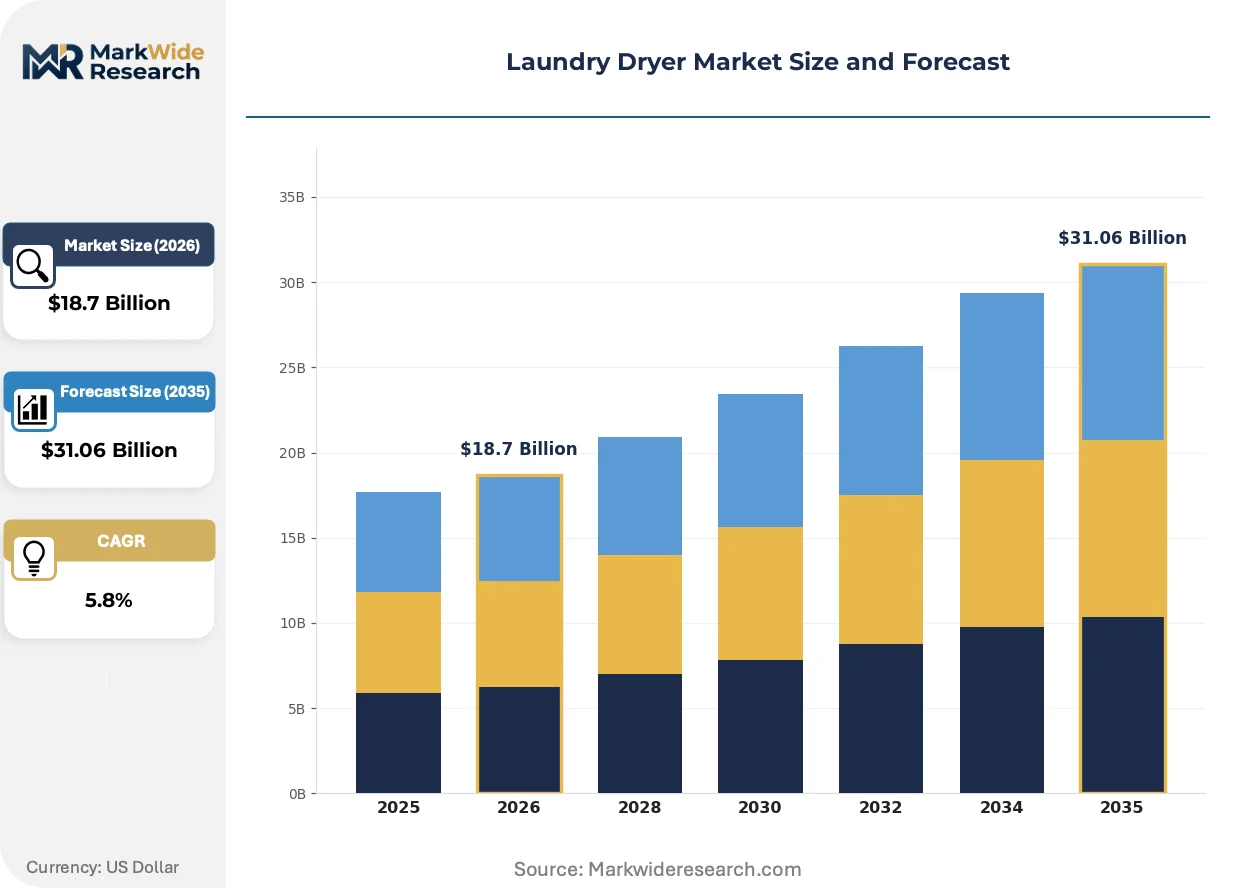
Market Dynamics
Heat pump technology mandates under EU Ecodesign regulations are compressing replacement cycles and forcing refrigerant transitions across European manufacturing footprints, while multi-family housing operators accelerate equipment leasing programs that restructure ownership economics.
Growth Catalysts
- EU Ecodesign Efficiency Mandates:Minimum energy performance standards for residential dryers are phasing out vented electric models, redirecting procurement toward heat pump systems with superior coefficient of performance ratings.
- Multi-family Housing Leasing Programs:Property management firms across rental portfolios are adopting subscription-based equipment models that bundle maintenance and replacement into predictable operating expenditures.
- Commercial Laundry Modernization:Aging industrial dryer fleets in hospitality and healthcare sectors are reaching end-of-life, triggering capital deployment toward stackable configurations that maximize throughput per square meter.
Market Restraints
- Copper and Steel Input Volatility:Drum fabrication and motor winding materials face commodity price swings that compress manufacturing margins and complicate long-term contract pricing.
- Refrigerant Supply Concentration:Heat pump dryer production depends on fluorinated gas supply chains concentrated among limited chemical producers, exposing assemblers to F-Gas Regulation quota constraints.
- Technical Limitation in Low-temperature Drying:Heat pump systems struggle to match the rapid cycle times of traditional vented dryers for heavy commercial loads, limiting penetration in time-sensitive applications.
Strategic Opportunities
- India Residential Electrification:Rising household appliance penetration in urbanizing tier-2 and tier-3 cities under BIS efficiency labeling creates first-mover positioning for heat pump variants adapted to voltage fluctuation conditions.
- Connected Diagnostics Convergence:Integration of IoT sensors with predictive maintenance algorithms enables service revenue streams that extend beyond hardware margins into recurring software subscriptions.
- Building Electrification Codes:Municipal gas hookup restrictions in new construction across California and New York jurisdictions mandate electric dryer specification, eliminating fossil-fuel competition in premium residential segments.
Industry Challenges
- Heat Pump Technician Shortage:Refrigeration cycle repair expertise remains scarce relative to conventional electric dryer service capacity, lengthening mean time to repair and elevating warranty costs.
- Certification Timeline Compression:EPA Energy Star verification and EU CE marking processes for novel refrigerant blends extend product launch windows, delaying revenue recognition against competitor cycles.
- Legacy Control System Integration:Smart dryer connectivity protocols must interface with existing building management systems in commercial installations, requiring customized middleware development per property.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laundry Dryer Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Condensing, Vented, Heat Pump, Gas End User: Residential, Commercial, Industrial, Institutional Technology: Smart Dryers, Conventional Dryers, Energy-Efficient Dryers, Stackable Dryers Installation Type: Built-In, Freestanding, Wall-Mounted, Portable |
| Companies Covered | Samsung, Whirlpool, LG, Miele, Electrolux, Maytag, Speed Queen, Bosch, GE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laundry Dryer Market Emerging Trajectories
Sensor-driven moisture detection and refrigerant chemistry advances are converging to redefine efficiency benchmarks, while procurement patterns shift toward performance-guaranteed service contracts that decouple capital ownership from drying capacity.
Variable-speed inverter compressors paired with multi-point humidity sensors are digitizing cycle optimization in residential heat pump dryers. Premium housing developers in Germany and the Netherlands are specifying these systems as standard fitments in new-build apartments. The technology is digitizing service dispatch by enabling remote diagnostics that predict component failure before tenant notification.
REACH restrictions on high-global-warming-potential refrigerants are compelling dryer manufacturers to qualify propane and isobutane alternatives with revised safety protocols. The F-Gas Regulation phase-down schedule is compressing R-134a availability for heat pump systems. Commercial laundries in France and Italy are responding by accelerating fleet replacement ahead of 2027 supply constraints.
Managed service contracts are displacing capital purchase models in multi-family housing and hospitality verticals. Equipment lessors assume responsibility for energy consumption, maintenance, and replacement timing, transferring operational risk from property owners. This pattern is most visible in German student housing and Dutch co-living developments where housing associations prioritize budget predictability over asset ownership.
Laundry Dryer Market Segmentation
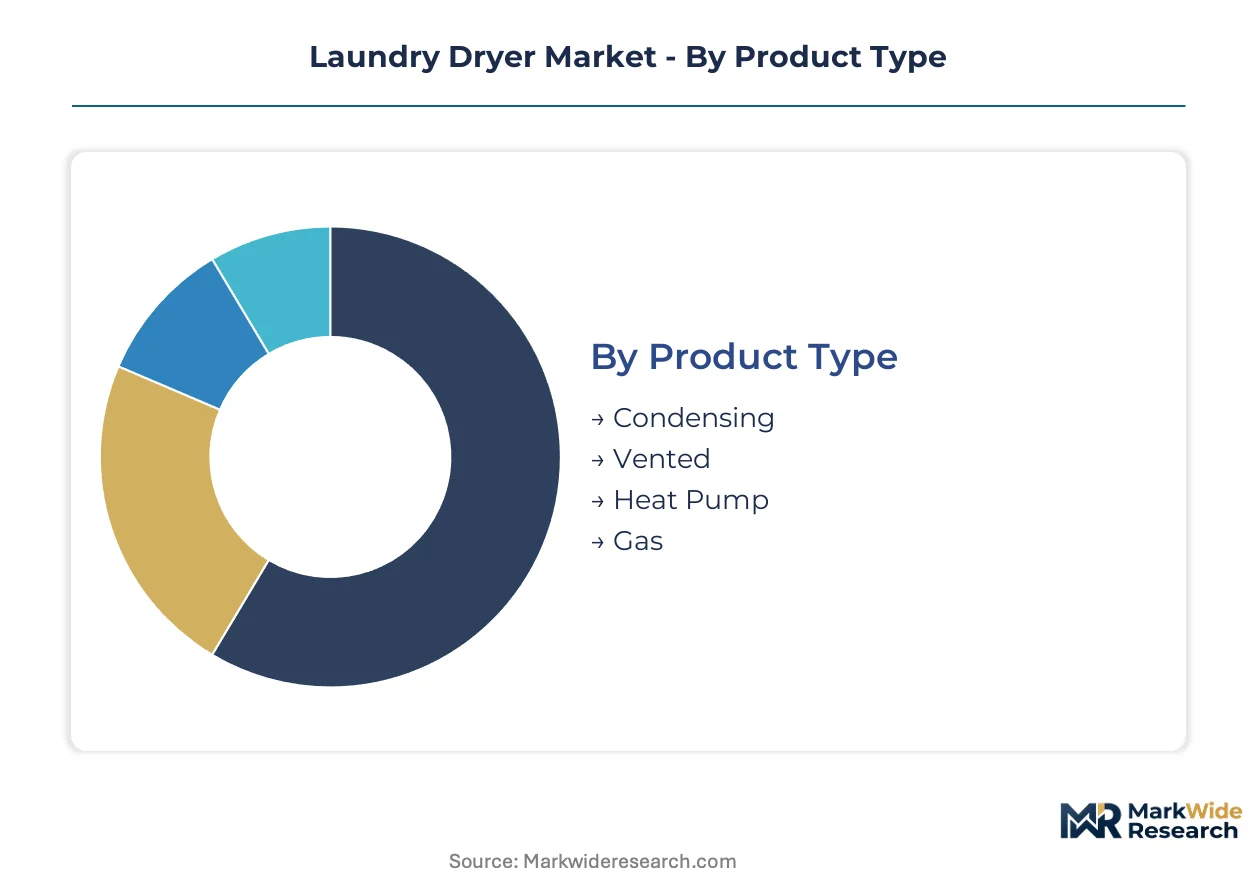
Dryer procurement cycles vary dramatically across segments. Residential replacements stretch 10-15 years while commercial hospitality fleets turn over every 7-9 years. Understanding these velocity differences shapes inventory planning and service revenue timing for manufacturers.
Product Type:
Heat pump systems compress replacement cycles in Europe while vented units retain longer lifecycles in markets without efficiency mandates. Gas dryers face electrification headwinds in new construction jurisdictions.
- Condensing:These units capture moisture in internal reservoirs rather than exhausting externally, enabling installation flexibility in apartments without venting infrastructure. Demand clusters in German and French multi-family housing where building codes restrict external penetrations. EU Ecodesign efficiency tiers are phasing out entry-level condensing models with poor coefficient of performance ratings.
- Vented:Traditional electric dryers expel moist air through ductwork, offering faster cycle times at lower capital cost. Penetration remains strongest in US suburban single-family housing where gas competition and venting accessibility persist. California and New York building electrification codes are eroding this segment's new-construction access.
- Heat Pump:Closed-loop refrigeration cycles achieve energy consumption reductions through condenser heat recovery. German housing associations specify these systems as standard in renovation programs. REACH refrigerant restrictions are forcing R-134a phase-outs and propane alternative qualifications.
- Gas:Natural gas combustion delivers rapid drying for heavy loads at lower operating cost per cycle. Commercial laundries in US states without electrification mandates continue specifying these units. Municipal gas hookup prohibitions in California and Massachusetts jurisdictions are constraining new placements.
Vented dryers dominate installed base across North America. Heat pump systems are where expansion concentrates in European regulatory environments.
End User:
Margin pools concentrate in commercial segments where throughput requirements justify premium pricing. Residential volume provides scale economies that fund R&D amortization across product lines.
- Residential:Single-family and multi-family households purchasing units through retail channels or developer specifications. German and Dutch new-build apartments increasingly bundle heat pump dryers as standard fitments. Smart connectivity adoption remains concentrated in premium housing tiers where remote diagnostics reduce service dispatch costs.
- Commercial:Laundromats, hospitality linen services, and healthcare textile operations optimizing throughput per square meter. Stackable configurations maximize floor space efficiency in urban laundromats across Tokyo and Seoul. Aging fleet replacement cycles in French and Italian hospitality sectors are accelerating procurement ahead of refrigerant supply constraints.
- Industrial:High-capacity continuous-batch systems processing 50-100 kg loads for textile finishing and rental linen operations. Demand concentrates in Turkey and Bangladesh garment manufacturing clusters where controlled moisture removal protects material integrity. Energy recovery systems command price premiums in carbon-intensive jurisdictions.
- Institutional:University housing, military facilities, and correctional institutions prioritizing durability and vandal resistance over efficiency optimization. Procurement runs through centralized purchasing cooperatives in US public university systems. Equipment leasing programs are displacing capital ownership in German student housing developments.
Residential segments dominate installed base. Commercial verticals are climbing the fastest as hospitality and healthcare modernization cycles converge.
Technology:
Smart functionality penetration correlates with housing value tiers and service infrastructure density. Energy efficiency certifications command retail price premiums in regulated markets.
- Smart Dryers:IoT-enabled units with predictive maintenance algorithms and cycle optimization through moisture sensing. Adoption concentrates in South Korean and US premium residential markets where connected appliance ecosystems extend recurring software revenue. Integration with utility demand-response programs creates tariff optimization opportunities.
- Conventional Dryers:Electromechanical timer-based systems without connectivity or sensor feedback. Volume persists in emerging market tier-2 cities and budget-conscious replacement cycles. India's BIS efficiency labeling is gradually constraining entry-level import access.
- Energy-Efficient Dryers:EPA Energy Star certified or EU A+++ rated systems with verified consumption metrics. Retail differentiation depends on third-party verification in US big-box channels. Chinese GB standards and MIIT labeling govern domestic manufacturing compliance.
- Stackable Dryers:Vertical configurations paired with matching washers for space-constrained installations. Hospitality procurement in Tokyo, Hong Kong, and Singapore prioritizes throughput per square meter. Customized middleware requirements for building management system integration extend sales cycles.
Conventional dryers dominate installed base. Smart connectivity is gaining share fastest in premium housing developments with dense service infrastructure.
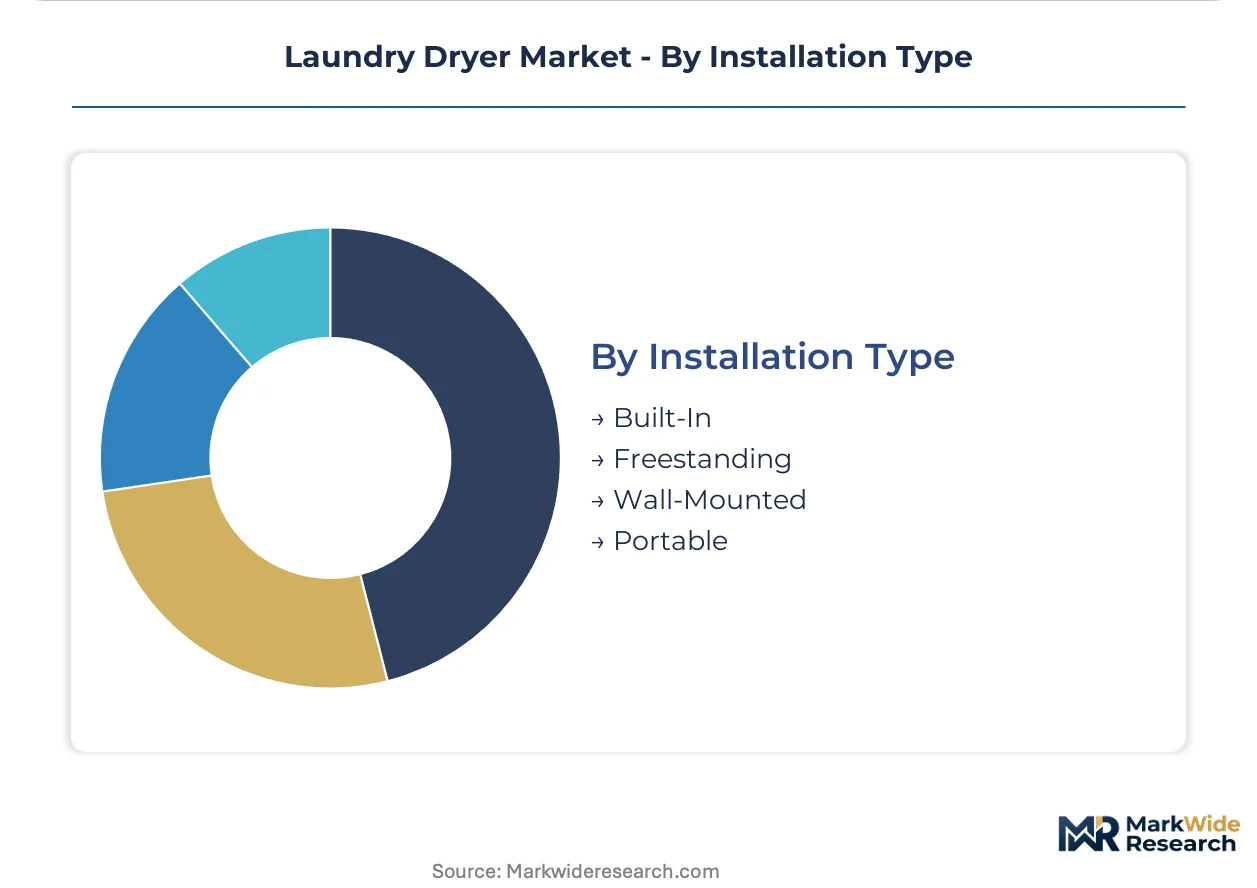
Installation Type:
Built-in specifications require earlier coordination with construction timelines. Portable and wall-mounted segments respond to rental market flexibility demands.
- Built-In:Custom cabinetry integration requiring rough-in coordination during construction phase. German and Dutch premium housing developers specify these configurations to maximize usable floor area. Lead times extend 8-12 weeks versus standard freestanding availability.
- Freestanding:Plug-and-play units requiring only electrical and venting connections. Volume concentration in US suburban replacement cycles and emerging market first-time appliance purchases. Big-box retail inventory depth supports immediate fulfillment.
- Wall-Mounted:Vertical mounting systems for extreme space constraints in micro-apartments and converted commercial buildings. Penetration visible in Tokyo and Seoul studio housing under 25 square meters. Structural load requirements limit retrofit applicability.
- Portable:Compact units with casters and temporary venting solutions for rental flexibility. Demand from US urban renters prohibited from permanent installations by lease terms. Capacity limitations restrict applicability to single-person households.
Freestanding configurations dominate installed base. Built-in specifications are expanding most quickly in European premium new-build segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import balances in laundry dryer equipment tilt toward manufacturing concentration in East Asia and Germany, with import dependency rising in markets lacking domestic assembly capacity. Trade flows track regulatory divergence, as efficiency mandates in Europe and North America reshape sourcing patterns for heat pump versus vented configurations.
Germany
Housing stock renovation programs and multi-family leasing expansion drive procurement of heat pump systems. The F-Gas Regulation and EU Ecodesign standards enforce refrigerant transitions and minimum efficiency thresholds. Commercial laundries in Berlin and Hamburg accelerate fleet modernization ahead of supply constraints.
United States
Building electrification codes in California and New York eliminate gas dryer access in new construction, redirecting demand toward electric configurations. EPA Energy Star certification shapes retail differentiation and utility rebate eligibility. Suburban replacement cycles in Texas and Florida sustain vented dryer volumes through big-box channels.
China
Domestic manufacturing scale supports export supply to emerging markets, while urban household penetration climbs in tier-2 and tier-3 cities. MIIT efficiency labeling and GB standards govern production compliance and import access. Yangtze River Delta clusters concentrate assembly capacity for heat pump compressor integration.
India
Residential electrification and appliance penetration in urbanizing secondary cities create first-mover positioning opportunities. BIS efficiency labeling gradually constrains entry-level import access and shapes domestic manufacturer compliance. Mumbai and Delhi-NCR housing developments pilot managed service contracts for multi-family installations.
Japan
Space-constrained urban housing sustains demand for compact and stackable configurations in Tokyo and Osaka. METI efficiency standards and JIS certification requirements shape product specifications for domestic and export markets. Smart connectivity integration advances in premium residential segments with dense service infrastructure.
Laundry Dryer Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream on refrigerant chemistry and compressor engineering. The vendor base organizes around three tiers: diversified appliance conglomerates with full-category portfolios, regional specialists with single-category depth, and contract manufacturers serving private-label retail. Consolidation pressure runs highest in heat pump technology, where refrigerant qualification costs and certification timelines favor scaled players. Competitive moves concentrate on vertical integration into compressor supply and strategic partnerships with property management platforms for leasing program participation.
Among diversified appliance conglomerates, Samsung Electronics Co., Ltd. and Whirlpool Corporation exemplify platform integrators with multi-category service infrastructure. Miele & Cie. KG occupies a position within the premium-tier specialist archetype, anchoring European heat pump engineering credibility. These three represent distinct strategic postures: scale-driven ecosystem integration, North American service network anchoring, and precision-engineered premium positioning.
| Leading Market Players |
|---|
| Samsung |
| Whirlpool |
| LG |
| Miele |
| Electrolux |
| Maytag |
| Speed Queen |
| Bosch |
| GE |
| Others |
Supply Flow & Price Mechanics
Compressor undercapacity in China's Yangtze River Delta is tightening supplier terms and accelerating cost pass-through negotiations for heat pump dryer assemblers. This utilization squeeze concentrates pricing power among refrigerant-qualified component vendors while forcing OEMs to absorb margin compression or renegotiate long-term service contracts.
Pricing Analysis
Industrial OEM buyers anchor the pricing structure through multi-year managed service contracts that bundle hardware, energy, and maintenance into predictable per-cycle fees. Pricing stratifies across premium heat pump systems with A+++ EU ratings, mid-tier condensing units for multi-family retrofit, and economy vented models for price-sensitive replacement cycles. Cost compression in the economy tier is intensifying because steel and copper volatility outpaces contract escalation clauses. Property management firms show highest price sensitivity due to budget predictability requirements, while hospitality operators prioritize throughput guarantees over unit economics.
Supply Chain Analysis
Contract manufacturing concentration sits with Foxconn, Midea, and Haier holding dominant assembly capacity across Ningbo, Suzhou, and Qingdao industrial clusters. Heat pump dryer production draws from Chinese compressor fabrication, German refrigerant chemistry, and South Korean inverter electronics. Single-source vulnerability in fluorinated gas supply exposes assemblers to F-Gas Regulation quota constraints. Distribution runs through big-box retail in North America, housing developer specifications in Germany and the Netherlands, and equipment lessor networks in multi-family verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Refrigeration cycle repair expertise has become the binding constraint as heat pump mandates expand, creating a technician scarcity that reshapes competitive advantage around service infrastructure depth rather than manufacturing scale alone.
For Market Incumbents: Insulate margin pools by backward integration into compressor supply and captive technician training academies. Lock in refrigerant allocation agreements ahead of F-Gas Regulation phase-down deadlines. Defend against emerging leasing platforms by embedding predictive maintenance algorithms that reduce mean time to repair below independent service competitors. For New Entrants and Emerging Players: Build out white-space positioning in India's tier-2 and tier-3 cities where BIS efficiency labeling is constraining import access for legacy players. Target voltage-adapted heat pump variants for residential electrification corridors. Pursue managed service contract pilots with Mumbai and Delhi-NCR housing developers as the go-to-market anchor. For Investors and Strategic Acquirers: Long-term, this sits as a service-arbitrage play because hardware commoditization redirects value capture toward recurring maintenance revenue and energy management software. Acquisition candidates should demonstrate dense regional technician networks or proprietary refrigerant handling certifications. Monitor commercial laundry fleet replacement announcements in France and Italy as the inflection signal for heat pump demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Program | Addresses F-Gas Regulation compliance gaps and reduces warranty cost exposure for heat pump deployments. |
| Refrigerant Supply Agreement | Secures propane and isobutane allocation ahead of R-134a phase-out deadlines under REACH restrictions. |
| Predictive Maintenance Platform | Converts hardware sales into recurring software revenue through IoT-enabled remote diagnostics integration. |
| Leasing Program Partnership | Captures multi-family housing procurement shifts toward subscription-based equipment models in German and Dutch markets. |
| Regional Assembly Footprint | Localizes production to evade import tariffs and align with India's BIS efficiency labeling requirements. |
Methodological Framework
Operator-level perspectives from multi-family housing procurement directors, commercial laundry fleet managers, HVAC service technicians, and refrigerant supply specialists anchored the qualitative base. Secondary validation drew from EU Ecodesign regulatory filings, EPA Energy Star certification databases, MIIT efficiency labeling records, and customs trade flow data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Scenario bracketing around refrigerant availability constraints, copper price volatility bands, and electrification code adoption timelines shaped the analytical framework. Segmentation dimensions modeled include product type, end-user vertical, technology tier, and installation configuration. CAGRs were derived from replacement cycle velocity differentials and regulatory mandate enforcement schedules. Forecast inputs incorporated housing stock renovation rates and commercial fleet aging profiles.
Stress conditions across refrigerant quota allocations, commodity input spikes, and technician wage inflation were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory enforcement timing and substitution elasticity. Quarterly review of F-Gas Regulation quota utilization rates and commercial laundry capital expenditure announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Electric Rice Cooker Market
Appliances
Oman Dishwashers Market
Appliances
Cordless Vacuum Cleaner Market
Appliances
North America Tumble Dryers Market
Appliances
Residential Vacuum Cleaners Market
Appliances
Consumer Appliances Market
Appliances
Residential Space Heater Market
Appliances
Japan Laundry Appliances Market
Appliances
Asia-Pacific Electric Rice Cooker Market
Appliances
Digital Showers Market
Appliances
Mexico Washing Machine Market
Appliances
Laundry Kiosk Market
Appliances
Europe Tumble Dryers Market
Appliances
France Household Side by Side Refrigerator Market
Appliances
Smart Microwave Oven Market
Appliances
United States Electronics and Appliance Stores Market