
 Under Counter Dishwasher Market | 2026-2036
Under Counter Dishwasher Market Size, Share, and Industry Trends Forecast 2026-2036
Under Counter Dishwasher Market Analytics
ENERGY STAR Version 8.0 is rebalancing the cost-of-entry calculus for under counter dishwasher manufacturers targeting North America. Whirlpool Corporation leverages its mass-production infrastructure to absorb compliance costs across high-volume residential lines. Miele & Cie. KG anchors its position through captive component manufacturing and extended-cycle durability testing. Hobart competes aggressively in commercial channels with field-service density and institutional relationships.
An under counter dishwasher is a compact dishwashing appliance engineered to fit beneath standard countertop surfaces, typically operating at noise levels below 50 decibels and cycle temperatures reaching 60–70°C for sanitization compliance. The unit serves residential kitchens and foodservice operations where floor space constraints prohibit freestanding or conveyor configurations. Built-in and smart product types command margin premiums as Wi-Fi-enabled diagnostics reduce service dispatch frequency. Energy-efficient and soil-sensor technologies attract commercial buyers facing utility cost pressures in high-cycle environments. Portable and drawer configurations occupy niche positions in rental housing and aging-in-place residential segments.
The EPA administers ENERGY STAR thresholds that dictate product eligibility for federal procurement and utility rebate programs across the United States. The EU Ecodesign Directive and F-Gas Regulation constrain refrigerant and energy performance for units sold in Europe, while CE marking mandates conformity assessment before market access. BIS certification in India and NMPA-adjacent quality frameworks in China add compliance layers for exporters. Stakeholders must monitor regulatory divergence between efficiency metrics and water-use limits as these standards increasingly determine competitive viability in priority export corridors.
Market Dynamics
ENERGY STAR Version 8.0 is compressing the viable supplier set in North America by tightening water-use thresholds and sanitization temperature requirements, forcing manufacturers to redesign heat-recovery systems and pump architectures.
Growth Catalysts
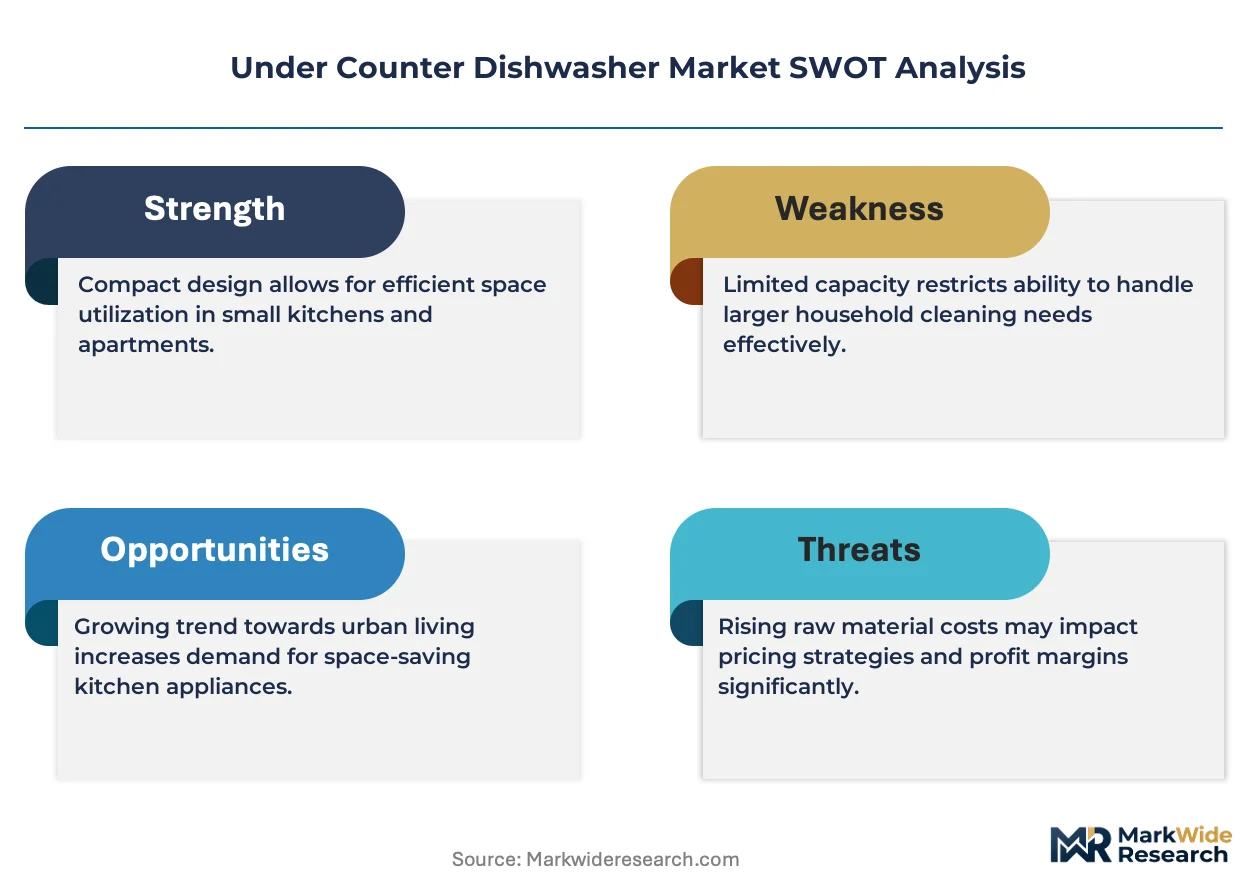
- Commercial kitchen replacement cycles:Aging equipment in United States foodservice operations drives systematic upgrades toward ENERGY STAR-certified units that qualify for utility rebate programs.
- REACH compliance in Europe:Restrictions on hazardous substances in electrical components push manufacturers toward stainless-steel interiors and lead-free solder formulations that extend product lifespans.
- Soil-sensor technology:Optical turbidity detection optimizes water and detergent dosing per load, reducing operating costs for high-cycle institutional users.
Market Restraints
- Stainless steel price volatility:Fluctuations in nickel and chromium input costs compress margins on premium compact units manufactured in Germany and Italy.
- Single-source pump motor suppliers:Concentrated sourcing of brushless DC motors from East Asian contract manufacturers creates vulnerability to logistics disruptions.
- Water hardness calibration limits:Fixed softener capacities in compact footprints reduce effectiveness in high-mineral regions without external pretreatment.
Strategic Opportunities
- India BIS certification pathway:Formal adoption of IS 302 standards for household electrical appliances opens access to urban middle-class replacement demand in Mumbai and Bangalore.
- Wi-Fi-enabled predictive maintenance:Integration of IoT diagnostics with commercial facility management platforms creates recurring revenue streams through subscription-based service alerts.
- Drawer configuration expansion:Dual-chamber designs serve aging-in-place residential segments and rental housing markets where space flexibility outweighs throughput requirements.
Industry Challenges
- Field service technician scarcity:Specialized training requirements for electronic control board diagnostics and refrigerant handling limit repair network density in secondary markets.
- CE marking conformity assessment delays:Third-party laboratory backlogs for electromagnetic compatibility testing extend product launch timelines by four to eight months.
- Legacy water inlet compatibility:Retrofit installations in older commercial buildings require adapter kits for non-standard plumbing configurations, complicating specification sales.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Under Counter Dishwasher Market |
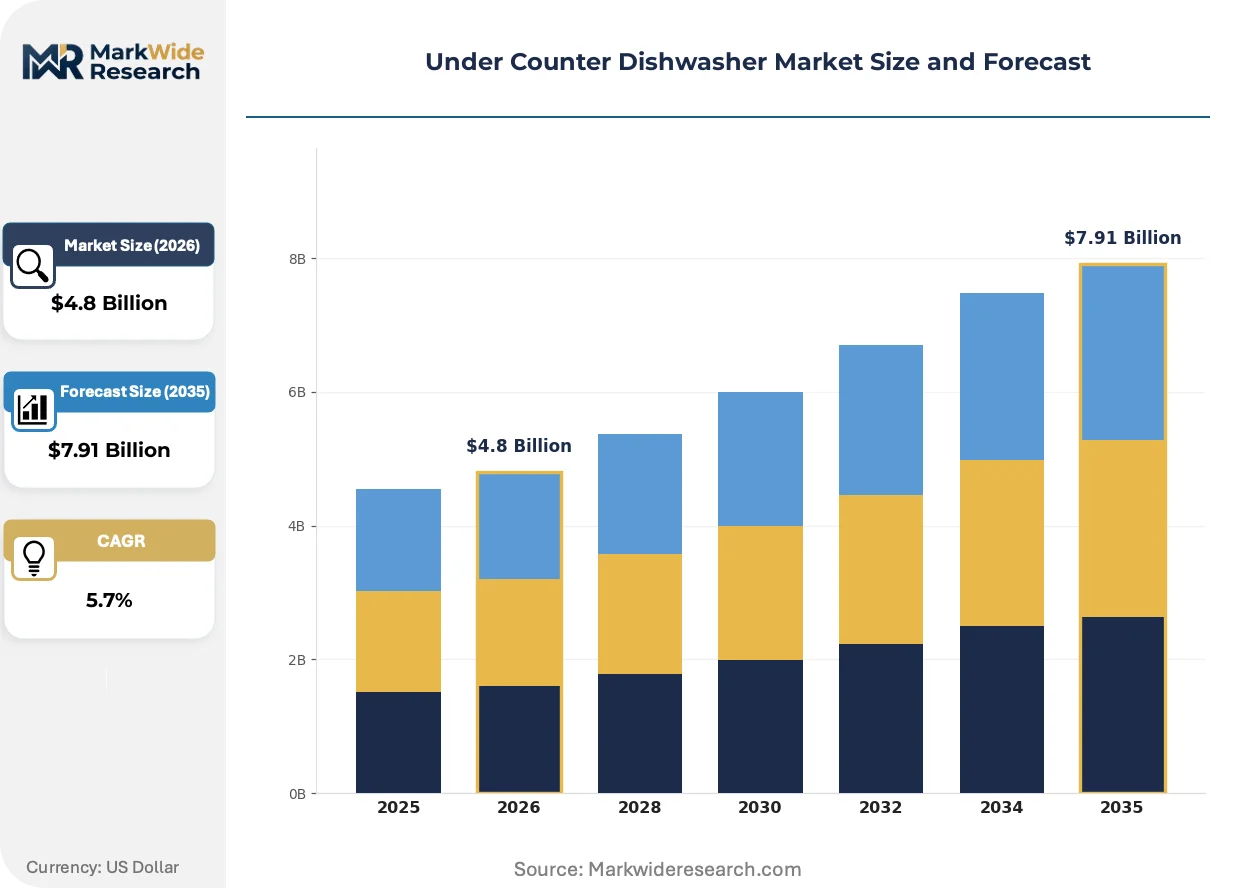
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Built-in, Portable, Drawer, Smart Technology: Energy-efficient, High-efficiency, Soil sensors, Wi-Fi-enabled End User: Household, Commercial Kitchens, Restaurants, Cafés Distribution Channel: Online Retail, Showrooms, Direct Sales, Appliance Dealers |
| Companies Covered | AB Electrolux, Whirlpool Corporation, BSH Hausgeräte GmbH, Haier Group Corporation, Jackson WWS, Winterhalter Gastronom GmbH, Miele & Cie. KG, Hobart, Meiko, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Under Counter Dishwasher Market Evolving Landscape
Heat-pump drying technology is rewriting the performance envelope for under counter units, extracting moisture at lower temperatures than conventional resistive elements. This shift is compressing the efficiency gap between compact residential models and larger conveyor systems.
Heat-pump condensation drying is rewriting energy economics by recovering waste heat from the wash cycle to pre-heat rinse water and dry dishes. High-end residential buyers in Germany and the United States are specifying these units despite 40-60% purchase premiums. The technology is rewriting competitive positioning by enabling sub-0.7 kWh per cycle performance that satisfies forthcoming EU Ecodesign thresholds without sacrificing stainless-steel interior durability.
EPA ENERGY STAR Version 8.0 is mandating maximum water consumption of 3.1 gallons per cycle for standard compact units, down from 3.5 gallons under Version 7.0. Manufacturers must redesign spray arm geometries and implement variable-speed pumps to maintain soil removal performance at reduced flow rates. Commercial operators in California and Texas face the steepest compliance pressure as state-level rebate programs align with federal procurement preferences.
Foodservice procurement teams are consolidating vendor relationships through multi-site equipment standardization contracts that bundle dishwashers with ice machines and refrigeration. Independent restaurant groups are displacing fragmented local dealer purchases with direct manufacturer agreements that include fixed five-year service pricing. This concentration is most visible in United States fast-casual chains expanding through franchise development agreements that mandate uniform kitchen specifications.
Under Counter Dishwasher Market Segmentation
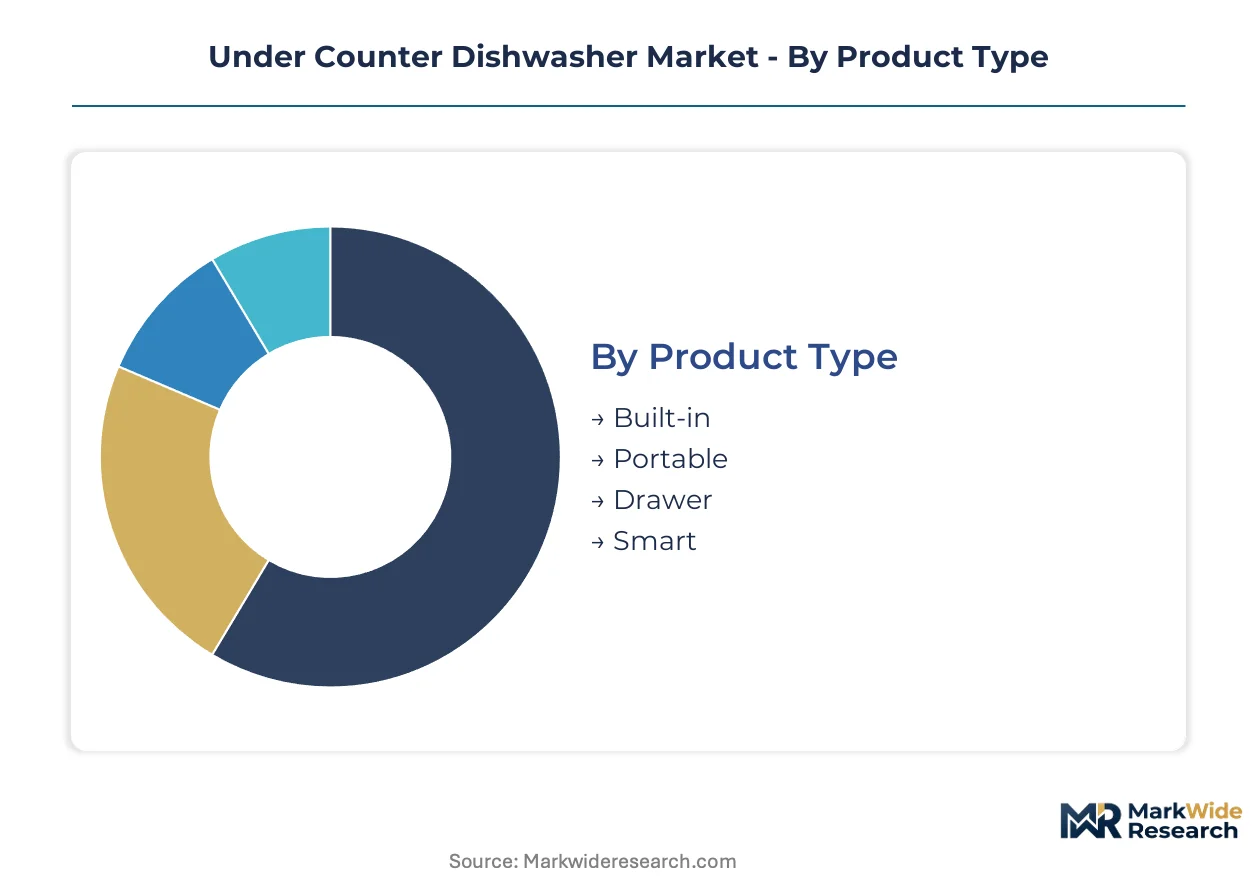
Under counter dishwasher purchasing decisions diverge sharply between residential replacement cycles and commercial procurement workflows. Segmentation reveals how specification complexity, certification requirements, and channel economics fragment addressable demand across price-performance tiers.
Product Type:
Buyers in this category separate by installation permanence and connectivity expectations rather than throughput capacity alone.
- Built-in:Permanent cabinet integration with standard 24-inch width specifications dominates new construction and full-kitchen renovation projects. Demand concentrates in Germany and the United States where ENERGY STAR and EU Ecodesign certification requirements drive specification toward heat-pump and variable-speed pump configurations.
- Smart:Wi-Fi-enabled units with predictive diagnostics and cycle optimization algorithms command margin premiums through subscription service attach rates. Commercial operators in California and Texas prioritize these models for multi-site fleet management and utility rebate qualification tracking.
- Portable:Freestanding units with caster mobility and temporary faucet connections serve rental housing markets where lease restrictions prohibit permanent modifications.
- Drawer:Dual-chamber independent operation configurations address aging-in-place residential segments and compact urban kitchens requiring flexible loading without bending.
Volume sits with built-in configurations; growth tilts toward smart connectivity as facility management platforms expand integration capabilities.
Technology:
Cost tier separates buyers here, with utility rebate eligibility and total cost of ownership calculations driving specification divergence between residential and commercial endpoints.
- Soil sensors:Optical turbidity detection systems adjust water volume, temperature, and detergent dosing in real-time based on load soiling levels. High-cycle institutional users in Texas and California specify these units to minimize per-cycle operating costs under escalating water rate structures.
- Energy-efficient:Heat-pump condensation drying and heat-recovery architectures achieve sub-0.7 kWh per cycle performance. German residential buyers absorb 40-60% purchase premiums to satisfy forthcoming EU Ecodesign thresholds without sacrificing stainless-steel interior durability.
- High-efficiency:Optimized spray arm geometries and variable-speed pumps maintain soil removal at reduced flow rates mandated by ENERGY STAR Version 8.0 water consumption limits.
- Wi-Fi-enabled:IoT diagnostic integration with commercial facility management platforms enables remote troubleshooting and automated service dispatch.
Energy-efficient technology captures the largest installed base; soil sensors are climbing the fastest as water cost pressures intensify across foodservice operations.
End User:
Application context determines specification rigor, with sanitization compliance requirements and cycle frequency creating distinct procurement workflows.
- Commercial Kitchens:Institutional foodservice operations in schools, hospitals, and corporate cafeterias require NSF/ANSI 3 sanitization compliance with 60-70°C final rinse temperatures. Replacement cycles in the United States accelerate as aging equipment faces ENERGY STAR Version 8.0 non-compliance.
- Restaurants:Independent and chain operators prioritize throughput speed and noise suppression below 50 decibels for front-of-house proximity installations. Fast-casual chains expanding through franchise development agreements increasingly mandate uniform specifications across multi-site portfolios.
- Household:Residential replacement demand concentrates in Germany and the United States where precision-engineered compact units serve high-end kitchen renovations.
- Cafés:Limited-service beverage-focused operations with moderate dishware volume prioritize compact footprints and rapid cycle completion over soil-sensor sophistication.
Commercial kitchens generate the highest unit volume; restaurants show the steepest expansion trajectory as multi-site standardization contracts consolidate vendor relationships.
Distribution Channel:
Customer type and purchase scale dictate channel selection, with procurement centralization trends reshaping traditional dealer networks.
- Direct Sales:Manufacturer-direct relationships with multi-site foodservice operators bundle equipment, installation, and fixed five-year service pricing. Fast-casual chains in the United States displace fragmented local dealer purchases through corporate procurement standardization.
- Appliance Dealers:Independent retail networks with field service technician density remain critical for residential replacement cycles and legacy building retrofit installations requiring adapter kits for non-standard plumbing.
- Online Retail:E-commerce platforms capture price-sensitive residential buyers comparing ENERGY STAR certification tiers and utility rebate eligibility documentation.
- Showrooms:Physical display environments support high-end residential specification in Germany where tactile evaluation of interior finish quality and noise dampening influences purchase decisions.
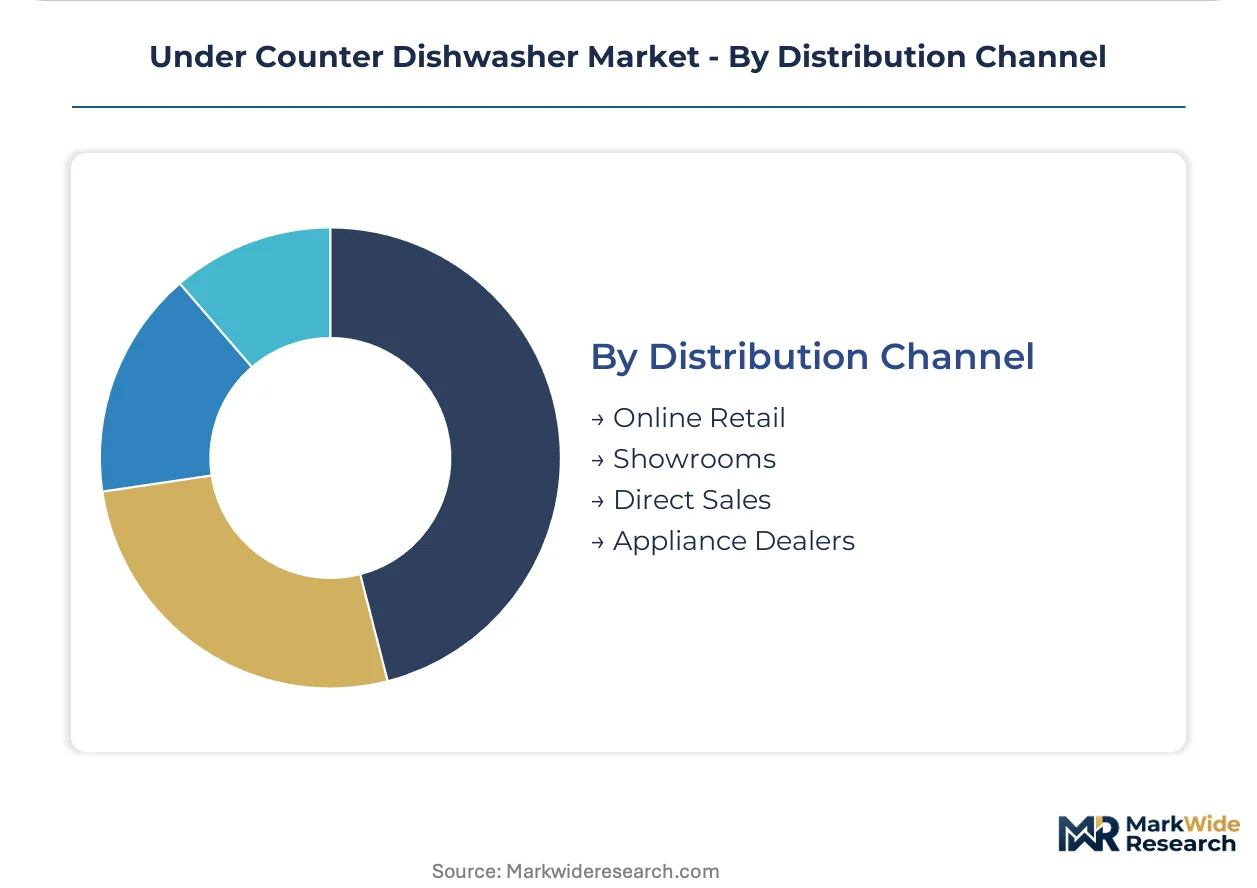
Appliance dealers maintain the deepest volume footprint; direct sales channels are gaining share fastest as procurement centralization accelerates across commercial operator consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise zones in Bavaria and Baden-Württemberg concentrate precision-engineered compact dishwasher manufacturing, drawing component suppliers into clustered supply networks. Special economic zones in China's Yangtze River Delta and Pearl River Delta attract contract manufacturers serving export markets with cost-optimized assemblies.
United States
Commercial kitchen replacement cycles accelerate as foodservice operators face ENERGY STAR Version 8.0 compliance deadlines. EPA-administered rebate programs in California and Texas steer procurement toward water-efficient configurations. Chicago and Dallas metropolitan areas concentrate multi-site restaurant chains consolidating vendor relationships through standardized equipment specifications.
Germany
High-end residential renovations drive demand for heat-pump-equipped units with stainless-steel interiors. EU Ecodesign Directive thresholds and REACH substance restrictions shape component sourcing decisions. Stuttgart and Munich industrial corridors host captive manufacturing operations for brushless DC pump motors and precision spray arm assemblies.
China
Urban middle-class apartment construction expands addressable demand for compact built-in configurations. NMPA-adjacent quality frameworks and GB standards compliance requirements filter export-oriented production. Shanghai and Shenzhen manufacturing clusters supply contract assembly for international brands while domestic brands penetrate tier-one city retail channels.
India
Mumbai and Bangalore urban households generate replacement demand as BIS IS 302 certification formalizes product safety benchmarks. Central Electricity Authority efficiency guidelines align with state-level utility rebate pilots in Maharashtra and Karnataka. Delhi-NCR and Hyderabad emerge as secondary demand centers for portable configurations serving rental housing markets.
Japan
Aging-in-place residential segments prioritize drawer configurations with reduced bending requirements. METI energy efficiency standards and JIS certification protocols maintain technical barriers for imported units. Osaka and Nagoya manufacturing bases supply domestic brands with heat-recovery pump technologies optimized for high-mineral water conditions.
Under Counter Dishwasher Market Competitive Landscape
United States producers anchor one tier; German specialists hold premium positioning through precision engineering. The supplier set compresses as ENERGY STAR Version 8.0 compliance costs eliminate marginal participants. Three archetypes dominate: mass-market manufacturers with captive component production, precision-engineered premium specialists, and commercial-channel service integrators. Competitive moves concentrate on backward integration into pump motor manufacturing and multi-site service contract bundling.
Among Germany-based precision manufacturers, Miele & Cie. KG and BSH Hausgeräte GmbH exemplify the premium-engineering archetype through extended-cycle durability architectures. Whirlpool Corporation represents scale-driven manufacturing with mass-production infrastructure absorbing regulatory compliance costs across high-volume lines. Hobart occupies a position within commercial-channel service integration, leveraging field-technician density and institutional procurement relationships.
| Leading Market Players |
|---|
| AB Electrolux |
| Whirlpool Corporation |
| BSH Hausgeräte GmbH |
| Haier Group Corporation |
| Jackson WWS |
| Winterhalter Gastronom GmbH |
| Miele & Cie. KG |
| Hobart |
| Meiko |
| Others |
Value Network & Pricing Analysis
ENERGY STAR Version 8.0 procurement mandates in the United States are forcing manufacturers to redesign heat-recovery systems and pump architectures, compressing margins on compact units and rewarding suppliers with captive component production.
Pricing Analysis
Short lead-time premiums dominate commercial procurement as multi-site foodservice operators face ENERGY STAR Version 8.0 compliance deadlines. Three-tier pricing structure across premium, standard, and economy levels separates heat-pump-equipped German units from mass-market Asian assemblies and basic portable configurations. Pricing pressure stems from nickel and chromium input cost volatility squeezing stainless-steel interior margins. Independent restaurant groups show highest price sensitivity; institutional buyers with utility rebate access absorb premium tiers.
Supply Chain Analysis
BIS domestic-content mandates for government procurement in India are reshaping sourcing decisions for exporters targeting Mumbai and Bangalore urban replacement cycles. Manufacturing concentrates in Germany, China, and Italy, with Stuttgart and Munich corridors hosting captive brushless DC pump motor production. Supply chains draw from East Asian contract manufacturers for precision spray arm assemblies and electronic control boards. Single-source pump motor concentration creates vulnerability to logistics disruptions. Distribution runs through direct manufacturer relationships with multi-site chains and independent appliance dealer networks with field-service density.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into pump motor manufacturing and heat-recovery system production defines competitive survival as ENERGY STAR compliance costs eliminate marginal participants.
For Market Incumbents: Acquire captive pump motor production capacity in Germany or China to secure supply continuity against East Asian logistics disruptions. Consolidate field-service technician networks in secondary United States markets where diagnostic training scarcity limits repair density. Defend against emerging smart-connectivity specialists by embedding IoT diagnostics into commercial fleet management platforms.
For New Entrants and Emerging Players: BIS IS 302 certification formalization in India opens a window for portable and drawer configuration penetration into Mumbai and Bangalore rental housing markets. Target aging-in-place residential segments in Japan with dual-chamber designs optimized for reduced bending requirements. Pursue direct-to-operator digital sales channels bypassing fragmented dealer networks.
For Investors and Strategic Acquirers: The window for entry favors precision-engineered compact specialists with heat-pump technology portfolios and established EU Ecodesign compliance pathways. Long-term viability rests on manufacturers controlling upstream heat-recovery component supply and downstream multi-site service contracts. Monitor ENERGY STAR Version 8.0 rebate program enrollment velocity as inflection indicator for commercial replacement cycle acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pump Motors | Captive brushless DC production insulates margins from East Asian logistics volatility. |
| Heat-Pump Technology Licensing | Sub-0.7 kWh cycle performance satisfies forthcoming EU Ecodesign thresholds without durability sacrifice. |
| Multi-Site Service Contract Bundling | Fixed five-year pricing locks in fast-casual chain procurement standardization. |
| IoT Diagnostic Platform Integration | Wi-Fi-enabled predictive maintenance reduces service dispatch frequency for California operators. |
| BIS Certification Pathway Investment | IS 302 compliance opens access to Maharashtra and Karnataka utility rebate pilots. |
Research Methodology
Document review covered EPA ENERGY STAR technical specifications, EU Ecodesign Directive implementing measures, and BIS appliance safety standards, complemented by interviews with commercial kitchen equipment procurement managers, foodservice facility directors, appliance dealer network operators, and aftermarket service technicians. Secondary sources included customs trade databases, SEC filings from listed manufacturers, and utility rebate program enrollment records. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across product type, technology tier, and end-user segmentation.
Segment-level outputs across built-in, smart, portable, and drawer configurations combined with technology adoption curves for soil-sensor and heat-pump architectures. CAGRs derived from regression analysis of replacement cycle timing, regulatory compliance deadlines, and rebate program budget trajectories. Forecast inputs incorporated stainless-steel price indices, brushless DC motor trade flows, and commercial construction permitting data for kitchen renovation pipelines.
The model assumes a particular technology adoption path; alternative pathways for heat-pump drying penetration would alter the outlook if resistive element cost compression accelerates. Forecasts reflect assumptions about ENERGY STAR Version 8.0 enforcement consistency and state-level rebate funding continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Small Appliances Market
Appliances
Asia Pacific Compact Dishwasher Market
Appliances
Saudi Arabia Dishwasher Market
Appliances
Refrigerator Repair Service Market
Appliances
North America Washing Machine Market
Appliances
Middle East and Africa Commercial Dishwashers Market
Appliances
United Kingdom Handheld Vacuum Cleaners Market
Appliances
Electric Fan Market
Appliances
APAC White Goods Market
Appliances
Bathroom Heaters Market
Appliances
Wall Oven Market
Appliances
Smart Massage Appliances Market
Appliances
Kuwait Dishwasher Market
Appliances
North America Personal Care Appliances Market
Appliances
UAE Dishwasher Market
Appliances
Europe Tumble Dryers Market