
 Japan Laundry Appliances Market | 2026-2036
Japan Laundry Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Laundry Appliances Market Foresight
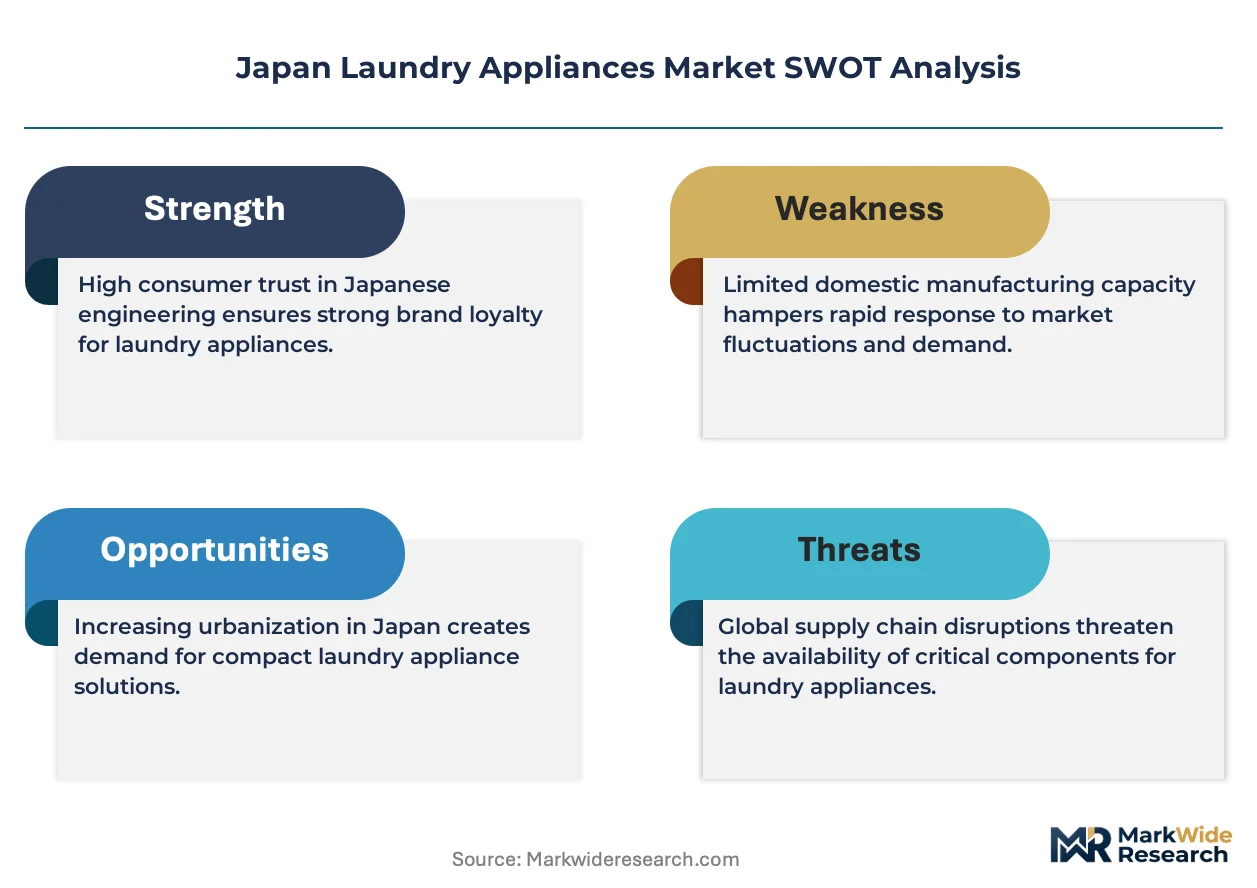
A capital-intensity divergence between domestic incumbents and multinational entrants is reorganizing competitive dynamics in Japan's laundry appliance sector. Panasonic Corporation leverages its vertically integrated compressor manufacturing to control heat pump dryer costs. Sharp Corporation sustains dominance in compact top-load designs tailored to Japanese housing dimensions. Samsung Electronics competes through premium smart-connected front-load positioning in urban retail channels.
Japan laundry appliances encompass electrically powered washing, drying, and combination units designed for textile cleaning with rated capacities typically spanning four to twelve kilograms and energy consumption metrics governed by METI's Top Runner program. The primary commercial purpose centers on automated fabric care for residential households, commercial laundromats, and industrial linen processing facilities. Washer-dryer combos command structural attention as Japan's shrinking living spaces elevate space-efficient designs, while heat pump technology captures margin pools through superior energy ratings. Smart technology integration represents the fastest-expanding dimension as IoT-enabled remote operation aligns with aging-population convenience needs.
METI enforces Top Runner energy-efficiency standards that mandate progressive reductions in power and water consumption, directly shaping product development roadmaps and factory certification requirements. JIS standards govern electrical safety and performance testing protocols, creating compliance barriers for uncertified imports. The PMDA maintains oversight of antimicrobial claims in washer drum coatings, constraining marketing language and additive formulations. Stakeholders must monitor evolving carbon-neutral building codes and their downstream implications for appliance replacement cycles in residential construction.
Market Dynamics
Heat pump dryer technology is compressing conventional condenser margins as METI's Top Runner standards harden energy-efficiency baselines and urban housing dimensions force compact-form-factor prioritization.
Growth Catalysts
- Top Runner Program:METI's escalating efficiency thresholds compel manufacturers to redesign thermal systems around heat pump architectures, accelerating replacement cycles in metropolitan housing stock.
- Urban Density:Tokyo and Osaka apartment configurations below fifty square meters elevate demand for washer-dryer combos with sub-sixty-centimeter widths, rewarding specialized compact engineering.
- Aging Demographics:IoT-enabled remote operation and automated detergent dosing address mobility constraints among Japan's sixty-five-plus households, expanding the addressable base for premium-connected units.
Market Restraints
- Copper and Rare Earth Volatility:Compressor motor laminations and permanent magnet materials expose cost structures to commodity swings, constraining margin predictability for heat pump dryer production.
- Import Certification Friction:JIS electrical safety testing and PMDA antimicrobial coating approvals create twelve-to-eighteen-month entry timelines for non-domestic manufacturers, protecting incumbent positioning.
- Space Constraints:Japanese residential floor plans limit separate washer-dryer installations, suppressing full-size front-load category expansion despite superior energy metrics.
Strategic Opportunities
- Commercial Laundromat Modernization:Coin-operated facility operators in Fukuoka and Sapporo seek heat pump retrofits to reduce utility exposure, opening B2B service contract models.
- Carbon-Neutral Building Codes:Tokyo Metropolitan Government's net-zero construction mandates for new residential towers embed high-efficiency appliance specifications, creating specification-driven demand.
- AI-Enabled Predictive Maintenance:Machine learning diagnostics converging with IoT sensor networks allow manufacturers to monetize subscription-based uptime guarantees for aging-unit households.
Industry Challenges
- Refrigerant Technician Scarcity:Heat pump dryer repair requires specialized handling of fluorinated gases under Japan's fluorocarbon emissions control law, limiting qualified service network expansion.
- Legacy System Integration:Smart appliance connectivity protocols must bridge proprietary home energy management systems deployed by regional utilities, complicating interoperability certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Laundry Appliances Market |
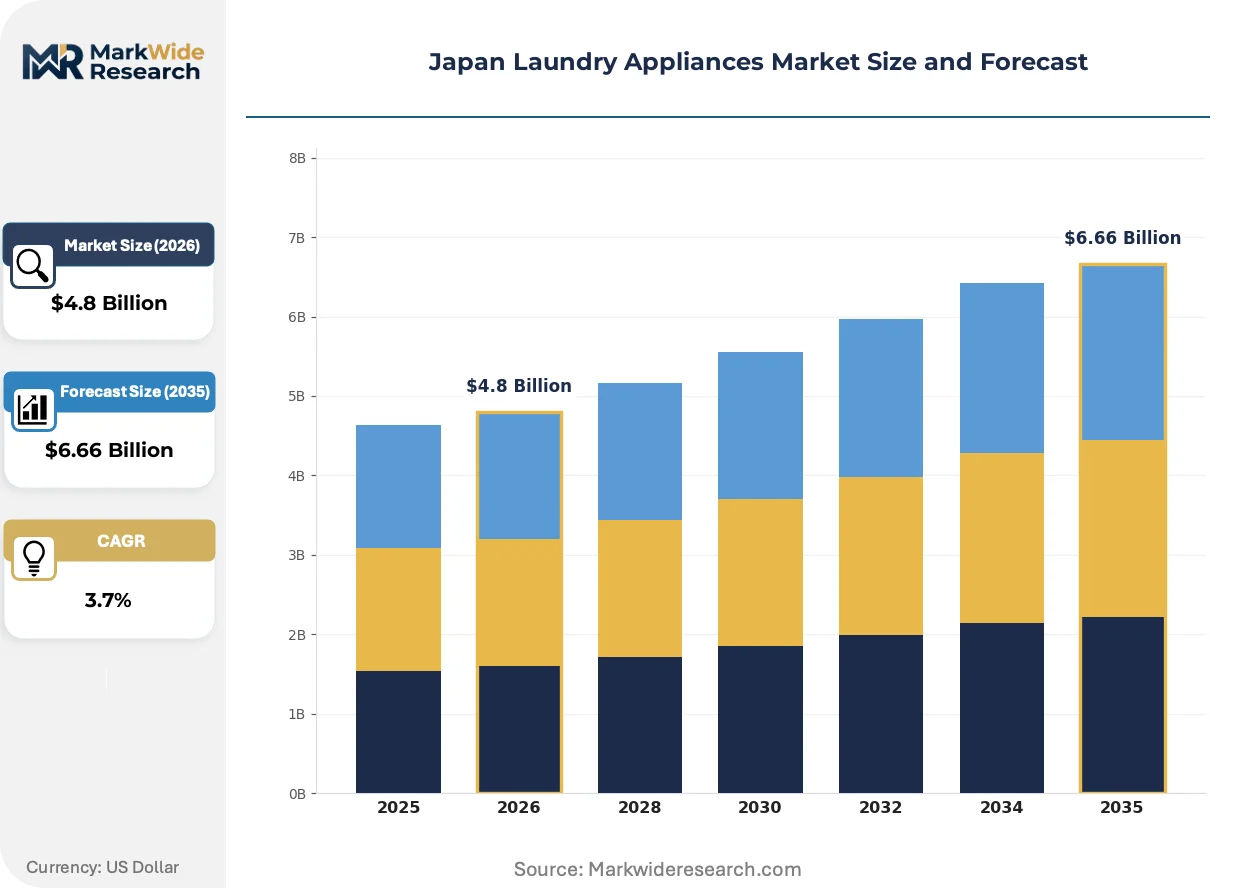
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Washing Machines, Dryers, Washer-Dryer Combos, Accessories End User: Residential, Commercial, Industrial, Ongoing Services Technology: Smart Technology, Heat Pump, Front Load, Top Load Distribution Channel: Online Retail, Department Stores, Appliance Specialized Stores, Others |
| Companies Covered | Sharp Corporation, Mitsubishi Electric Corporation, Panasonic Corporation, Samsung Electronics, LG Electronics Japan, Hitachi Global Life Solutions, Haier Japan (AQUA), Whirlpool Corporation, Toshiba Lifestyle Products & Services, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Laundry Appliances Market Shifts & Advancements
Product development trajectories center on thermal efficiency breakthroughs, connected service architectures, and form-factor miniaturization responding to immutable spatial constraints in Japanese residential construction.
Heat pump drying circuits are supplanting conventional electric-resistance heating elements in mid-tier and premium washer-dryer combos. Metropolitan apartment owners in Tokyo's twenty-three wards adopt these units at accelerating rates as electricity tariffs rise. The technology is compressing condenser-dryer market share and forcing condenser-focused manufacturers to retool production lines or exit the category entirely.
METI's 2024 revision to the Top Runner program tightens annual power consumption coefficients for washing and drying cycles by an additional eight percent. Manufacturers must redesign drum motors and inverter controls to maintain compliance eligibility. Compact washer-dryer combos face the steepest engineering burden given thermal load constraints in reduced footprints.
Subscription-based detergent and fabric care replenishment is displacing traditional retail purchasing for connected appliance households. Younger buyers in Osaka and Nagoya activate auto-replenishment algorithms that calibrate dosage to load weight and soil sensors. This shift locks in brand ecosystem loyalty and generates recurring revenue streams that hardware margins alone cannot match.
Japan Laundry Appliances Market Segmentation
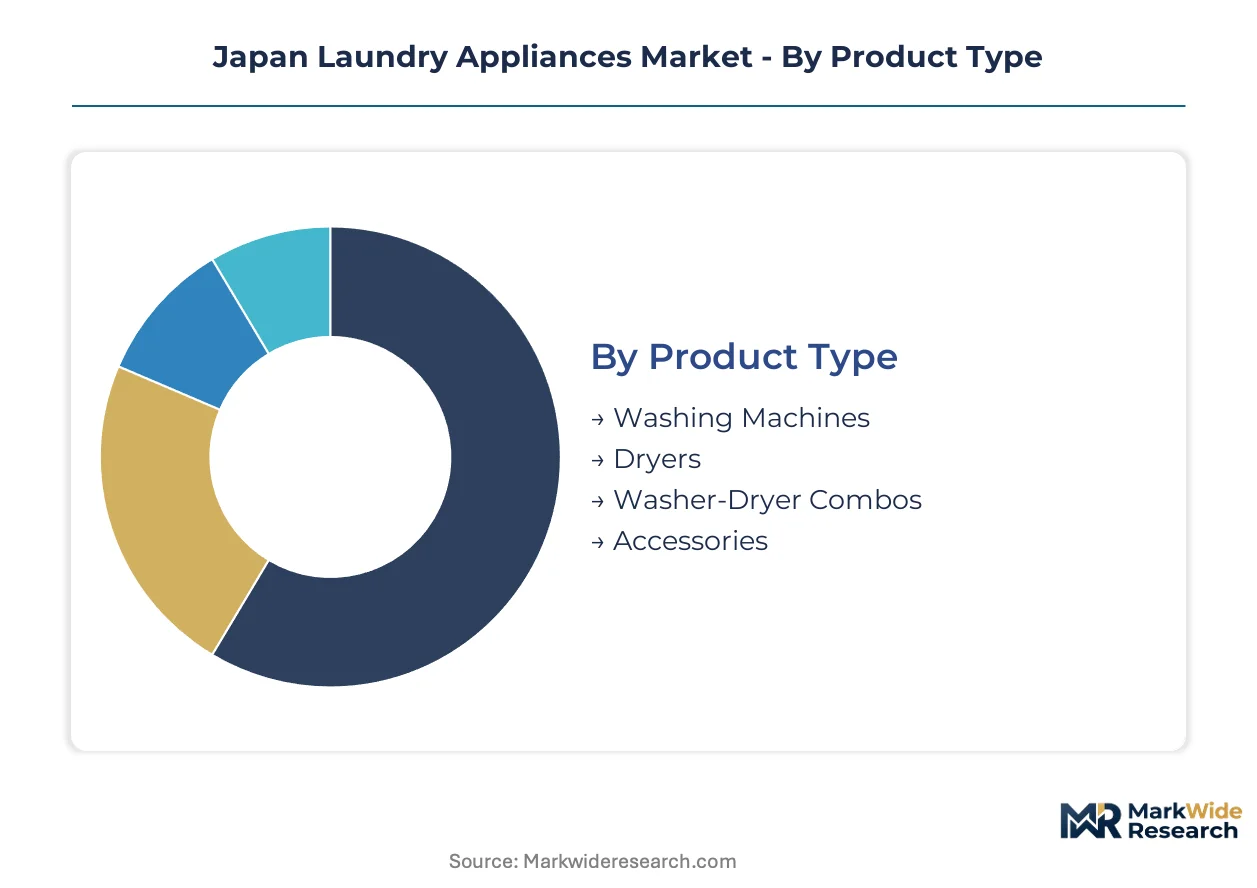
Segmentation in Japan's laundry appliance market reveals how METI regulations, urban housing constraints, and aging demographics fragment demand across incompatible product specifications. Manufacturers must optimize channel mix and pricing architecture separately for each segment cluster to capture replacement cycles and new household formation.
Product Type:
Channel mix varies sharply by product type, with washer-dryer combos and compact washing machines flowing through appliance specialized stores for installation support, while standalone dryers concentrate in department store home sections targeting suburban homeowners.
- Washing Machines:Freestanding and built-in units with capacities from four to twelve kilograms, employing either pulsator or drum mechanisms. Demand concentrates in Tokyo's twenty-three wards and Osaka's Kita ward, where replacement cycles accelerate under METI's tightening Top Runner efficiency thresholds.
- Dryers:Vented, condenser, and heat pump configurations with drying capacities typically half their paired washer ratings. Heat pump models are gaining share fastest in metropolitan condominiums as electricity tariffs rise and carbon-neutral building codes harden appliance specifications.
- Washer-Dryer Combos:Integrated single-unit designs with sub-sixty-centimeter widths engineered for Japanese apartment dimensions. Osaka and Nagoya apartment complexes under fifty square meters drive specification requirements for these space-constrained installations.
- Accessories:Detergent dispensers, stacking kits, and pedestal storage units. Online retail channels capture the bulk of this segment through subscription-based replenishment algorithms.
Washer-dryer combos dominate installed base in metropolitan corridors. Heat pump dryers are where expansion concentrates.
End User:
Cost tier stratification separates premium IoT-enabled residential units from price-sensitive commercial coin-op installations, with industrial linen processors occupying a distinct capital-equipment procurement layer.
- Residential:Single-family homes and apartment households purchasing units through retail channels with manufacturer warranty coverage. Aging demographics in Hokkaido and Kyushu expand demand for remote-operation features among sixty-five-plus households facing mobility constraints.
- Commercial:Coin-operated laundromats, apartment building shared facilities, and hospitality linen services. Fukuoka and Sapporo operators seek heat pump retrofits to reduce utility exposure and comply with municipal carbon reduction mandates.
- Industrial:Large-scale continuous-batch systems for hotels, hospitals, and uniform rental services. Procurement runs through direct manufacturer relationships with extended service contracts.
- Ongoing Services:Maintenance contracts, parts replacement, and detergent subscription programs. Subscription revenue is climbing the fastest as younger buyers in Kanto activate auto-replenishment algorithms.
Residential segments command the highest unit margins. Commercial services are where volume expansion concentrates.
Technology:
Application context dictates technology adoption, with smart connectivity prioritized for aging-in-place residential scenarios and heat pump engineering dominating new construction specifications under Tokyo's net-zero building codes.
- Smart Technology:IoT-enabled remote operation, soil sensors, and automated detergent dosing via smartphone applications. Kanto region households lead adoption as convenience features address caregiver shortages and elderly independent living preferences.
- Heat Pump:Closed-loop refrigerant systems achieving fifty percent energy reduction versus conventional electric resistance drying. METI's Top Runner program mandates this architecture for mid-tier and premium category compliance eligibility.
- Front Load:Horizontal-axis drum designs with superior water efficiency and gentler fabric handling. Space constraints in Japanese floor plans suppress category expansion despite superior energy metrics.
- Top Load:Vertical-axis pulsator mechanisms optimized for compact footprints and faster cycle completion. Sharp Corporation sustains engineering leadership in this segment tailored to Japanese housing dimensions.
Top load designs dominate legacy installed base. Heat pump technology is where specification-driven replacement concentrates.
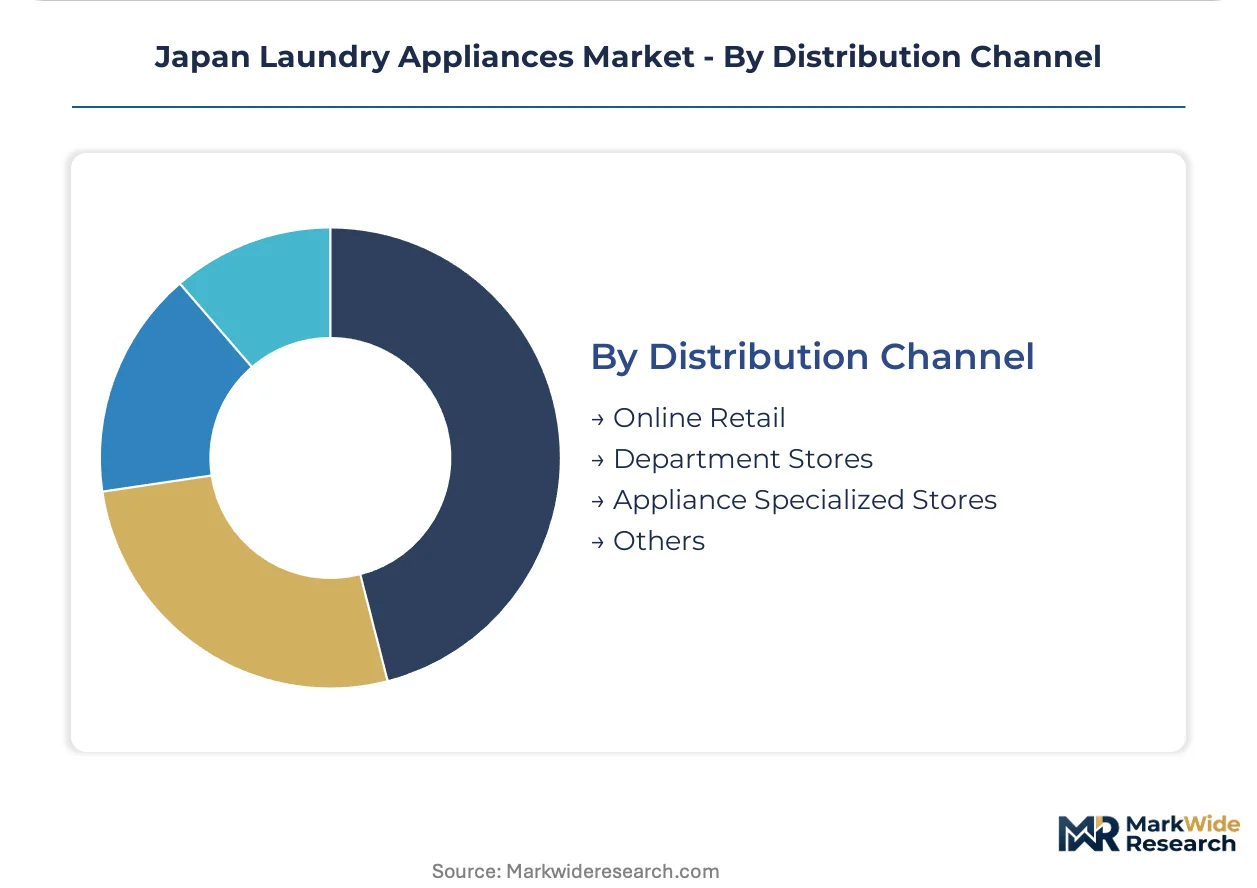
Distribution Channel:
Geography determines channel effectiveness, with appliance specialized stores anchoring metropolitan Tokyo and Osaka while online retail captures rural Hokkaido and Kyushu where physical store density is lowest.
- Online Retail:E-commerce platforms and manufacturer direct-to-consumer portals with subscription service integration. Younger demographics in Nagoya and Fukuoka activate auto-replenishment algorithms that lock in brand ecosystem loyalty.
- Department Stores:Flagship home appliance floors in Isetan, Takashimaya, and Mitsukoshi locations targeting premium front-load and heat pump purchases. Installation services and extended warranties differentiate this channel.
- Appliance Specialized Stores:Yamada Denki, Bic Camera, and regional chains providing in-person consultation and installation coordination. Kanto corridor stores capture the bulk of washer-dryer combo transactions requiring spatial measurement verification.
- Others:Builder direct specifications for new residential construction and commercial procurement through facility management contractors. Tokyo Metropolitan Government's net-zero mandates are expanding this channel fastest.
Appliance specialized stores dominate transaction volume. Online retail is where subscription-based recurring revenue concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Kanto commands premium pricing leverage against Kyushu's volume-driven discounting, reflecting divergent urban density and replacement cycle dynamics across Japanese regions.
Kanto/Tokyo
Tokyo's twenty-three wards and surrounding prefectures concentrate demand for sub-sixty-centimeter washer-dryer combos in micro-apartments under fifty square meters. METI's Top Runner program accelerates replacement cycles as efficiency thresholds tighten annually. Yokohama and Saitama apartment complexes drive specification requirements for heat pump-integrated units.
Kansai/Osaka
Osaka's Kita ward and Kyoto prefecture sustain robust demand for compact top-load designs optimized for traditional housing stock. The Osaka Prefecture municipal carbon reduction mandate shapes commercial laundromat retrofit decisions. Kobe port facilities anchor import logistics for multinational appliance brands entering western Japan.
Chubu/Nagoya
Nagoya's automotive industry concentration generates dual-income households prioritizing time-saving IoT-enabled appliances. Aichi prefecture building codes increasingly reference METI efficiency benchmarks for new residential construction. Toyota City and surrounding municipalities test smart grid integration for connected laundry systems.
Kyushu
Fukuoka's expanding young professional population drives entry-level washer-dryer combo volume despite lower per-unit margins. Municipal utilities in Saga and Kumamoto offer rebates for heat pump dryer adoption under regional decarbonization frameworks. Kitakyushu industrial zones host component suppliers for compressor manufacturing.
Hokkaido
Sapporo's severe winters elevate demand for rapid-dry heat pump systems in residential and commercial segments. Hokkaido prefectural energy efficiency programs subsidize appliance upgrades in aging rural housing stock. Asahikawa and Hakodate municipal governments specify high-efficiency units for public housing refurbishment.
Japan Laundry Appliances Market Competitive Landscape
Concentration sits with diversified electronics conglomerates possessing captive compressor manufacturing and established distribution through appliance specialized retail chains. Domestic incumbents leverage vertical integration into heat pump components against multinational entrants dependent on import certification timelines. Three strategic archetypes dominate: integrated electronics conglomerates with component manufacturing depth, specialized home appliance manufacturers with compact form-factor expertise, and Korean multinational electronics groups competing through smart connectivity positioning. Competitive dynamics center on backward integration into heat pump compressors and strategic partnerships with municipal utilities for smart grid integration.
Within the integrated conglomerate tier, Panasonic Corporation and Mitsubishi Electric Corporation exemplify archetypes combining captive supply of heat pump compressors with established METI certification pathways. Sharp Corporation occupies a distinct position as a specialized compact appliance manufacturer with deep roots in Japanese housing-optimized designs. Among multinational entrants, Samsung Electronics and LG Electronics Japan represent the smart connectivity competitive vector, navigating JIS safety testing and PMDA antimicrobial approval timelines to access metropolitan retail channels.
| Leading Market Players |
|---|
| Sharp Corporation |
| Mitsubishi Electric Corporation |
| Panasonic Corporation |
| Samsung Electronics |
| LG Electronics Japan |
| Hitachi Global Life Solutions |
| Haier Japan (AQUA) |
| Whirlpool Corporation |
| Toshiba Lifestyle Products & Services |
| Others |
Supply & Pricing Matrix
Twelve-to-eighteen-month JIS certification timelines compress pricing power for non-domestic manufacturers while rewarding Panasonic and Mitsubishi Electric with premium positioning through captive compressor supply. Inventory cycles for copper motor laminations and rare earth permanent magnets tie directly to yen-denominated commodity exposure, forcing tiered margin structures across heat pump and condenser dryer categories.
Pricing Analysis
The customization-premium spread separates standard washer-dryer combos from configured-to-order units with IoT integration and extended warranties. Three-tier pricing structure across premium, standard, and economy levels reflects METI Top Runner certification tiers and installation complexity. Cost compression in economy heat pump models is intensifying because Samsung and LG Electronics Japan absorb JIS testing overhead to gain metropolitan retail access. Commercial laundromat operators in Fukuoka and Sapporo exhibit highest price sensitivity, while Tokyo condominium associations purchasing builder-direct specifications show lowest sensitivity due to carbon-neutral mandate compliance requirements.
Supply Chain Analysis
Strategic stockpiling of compressor motors and inverter controls dominates inventory strategy as manufacturers buffer against copper and neodymium price volatility. Component manufacturing concentrates in Japan, South Korea, and China, with heat pump compressors drawing from Panasonic's domestic facilities and Mitsubishi Electric's Thai assembly plants. Supply chain risk centers on single-source vulnerability for specialized refrigerant handling equipment under Japan's fluorocarbon emissions control law. Distribution runs through appliance specialized stores for installation-heavy washer-dryer combos, while online retail captures detergent subscription replenishment and accessory sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's laundry appliance market is entering a cyclical recovery phase as METI's 2024 Top Runner revision forces replacement cycles in metropolitan housing stock built during the 2015-2020 efficiency standard window.
For Market Incumbents: Shield margin pools in heat pump dryer technology by deepening backward integration into compressor manufacturing and securing exclusive service technician training partnerships under fluorocarbon handling regulations. Panasonic and Mitsubishi Electric should lock in builder-direct channel access before Tokyo's net-zero construction mandates expand to Osaka and Nagoya prefectures, blocking multinational smart-connectivity positioning through proprietary home energy management system integration. For New Entrants and Emerging Players: PMDA antimicrobial coating fast-track approvals represent the critical path to metropolitan retail presence, with JIS electrical safety pre-certification in South Korean or Chinese testing labs compressing entry timelines. White-space targets concentrate in Hokkaido's aging rural housing stock and Kyushu's municipal rebate programs, where price sensitivity exceeds brand loyalty. A direct-to-consumer online model with subscription detergent bundling bypasses appliance specialized store channel control. For Investors and Strategic Acquirers: Long-term, this sits as a regulated replacement-cycle play because METI efficiency thresholds escalate predictably and Japanese housing stock ages in place rather than expanding. Acquisition targets should display captive heat pump component manufacturing or established PMDA/JIS certification pathways. The signal to watch is Tokyo Metropolitan Government's net-zero mandate expansion to commercial retrofit specifications, which would re-rate commercial laundromat service contract valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Heat Pump Compressor Backward Integration | Captive supply of inverter-controlled compressors locks in METI Top Runner compliance cost advantage against import-dependent competitors. |
| IoT Platform Utility Partnership | Smart grid integration with Tokyo Electric Power and Kansai Electric creates specification priority for connected washer-dryer combos in new construction. |
| Refrigerant Technician Certification Program | Proprietary service networks address fluorocarbon handling law constraints while generating recurring maintenance contract revenue. |
| Subscription Detergent Replenishment Launch | Auto-replenishment algorithms calibrated to soil sensors lock brand ecosystem loyalty among younger Osaka and Nagoya demographics. |
| Commercial Laundromat Heat Pump Retrofit | B2B service contracts in Fukuoka and Sapporo capture municipal carbon reduction mandate compliance spending. |
Research Methodology
A spread of perspectives from appliance manufacturing executives, METI certification specialists, appliance specialized store category managers, commercial laundromat operators, and residential construction procurement officers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through METI Top Runner program filings, JIS standard revision documentation, PMDA antimicrobial coating approval databases, and Tokyo Metropolitan Government building code amendments. Bottom-up unit shipment estimates triangulated against top-down household formation and replacement cycle models.
Segmentation dimensions modeled include product type, end user category, technology tier, and distribution channel across the projection horizon. CAGRs derived from regression analysis of historical efficiency standard adoption curves and housing construction permit data. Heat pump technology penetration rates and IoT connectivity adoption curves served as industry-specific forecast inputs, with sensitivity testing around electricity tariff trajectories and refrigerant technician supply constraints.
The analysis sits within stated boundaries; outcomes outside sustained METI enforcement intensity or accelerated net-zero building code adoption would require recalibration. Forecasts reflect assumptions regarding copper and rare earth price stability, JIS certification timeline consistency, and municipal utility rebate program continuity. Revision becomes warranted when heat pump dryer cost parity against condenser models crosses threshold penetration in economy-tier segments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
UAE Microwave Ovens Market
Appliances
Mini Washing Machine Market
Appliances
Built-In Large Cooking Appliance Market
Appliances
Middle East Portable Washing Machines Market
Appliances
Mexico Washing Machine Market
Appliances
Oman Dishwashers Market
Appliances
Japan Massage Equipment Market
Appliances
Asia Pacific Compact Dishwasher Market
Appliances
Under Counter Dishwasher Market
Appliances
France Household Side by Side Refrigerator Market
Appliances
Global Electric Water Heaters Market
Appliances
Personal Care Appliances Market
Appliances
Conveyor Dishwasher Market
Appliances
Hairdryer Market
Appliances
Consumer Appliances Market
Appliances
US Portable Washing Machines Market